
 Digital Breast Tomosynthesis (DBT) Equipment Market | 2026-2036
Digital Breast Tomosynthesis (DBT) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Breast Tomosynthesis (DBT) Equipment Market Outlook
China is fragmenting as domestic imaging manufacturers scale x-ray tube and detector module capacity to challenge incumbent DBT supply chains. Hologic, Inc sustains technology leadership through captive flat-panel detector production and dense patent positioning in tomosynthesis reconstruction algorithms. GE Healthcare anchors its installed base with service contracts that lock hospitals into multi-year imaging platform ecosystems. Siemens Healthineers differentiates through dual-energy tomosynthesis capabilities that integrate contrast-enhanced protocols into standard screening workflows.
Digital Breast Tomosynthesis equipment acquires multiple low-dose projection images across an arc of 15 to 50 degrees and reconstructs them into thin-slice three-dimensional volumes for breast lesion detection. The primary purpose is to reduce tissue overlap masking effects inherent in conventional two-dimensional mammography, thereby improving invasive cancer detection rates while maintaining comparable radiation dose. Full-Field 3D systems occupy the dominant revenue position due to their compatibility with high-volume screening programs and established reimbursement codes. Portable DBT represents the fastest-expanding segment as mobile breast screening units extend access to rural and underserved populations. AI-Enhanced technology commands premium pricing by automating lesion characterization and reducing radiologist reading time per examination.
The FDA enforces Mammography Quality Standards Act requirements that mandate equipment performance benchmarks and personnel certification, directly influencing DBT system upgrade timelines and facility compliance investments. EMA coordination with national health technology assessment bodies across France, Germany, and Italy determines whether DBT screening qualifies for public reimbursement, shaping manufacturer market access strategies. The EU MDR imposes stricter clinical evidence requirements on software-driven imaging modalities, extending certification timelines for AI-integrated tomosynthesis platforms. Stakeholders must monitor evolving radiologist workforce density and training pipeline capacity, as interpretation complexity and reading volume requirements constrain the scalable deployment of DBT screening programs regardless of equipment availability.
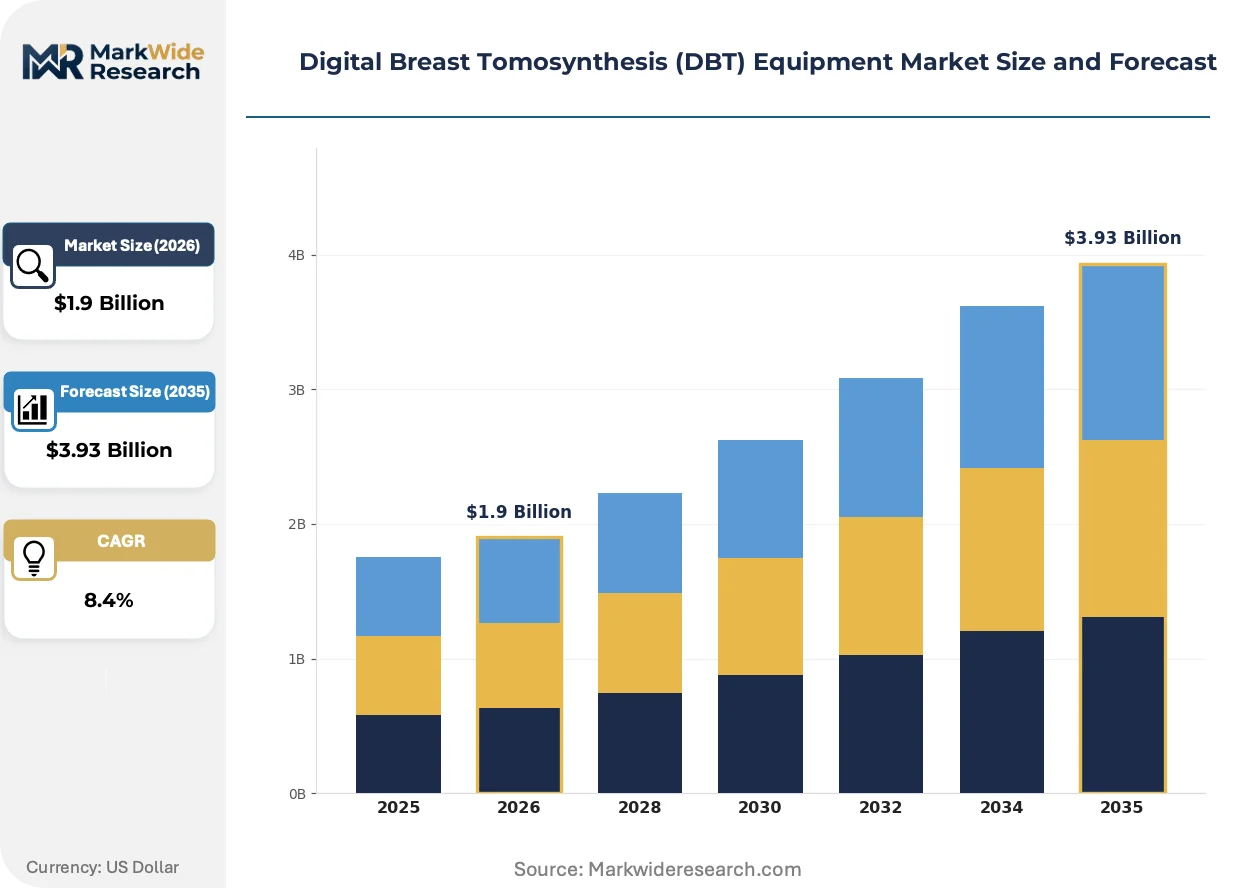
Market Dynamics
Reimbursement code activation for DBT screening procedures constitutes the dominant structural force reshaping equipment procurement cycles, as payor recognition converts capital expenditure into revenue-generating clinical utility.
Growth Catalysts
- Statutory health insurance coverage:Germany's G-BA assessment establishing DBT as standard-of-care for breast cancer screening creates predictable demand visibility for outpatient breast care networks.
- AI integration protocols:Automated lesion characterization algorithms reduce radiologist interpretation burden and enable higher throughput per installed system.
- Rural access mandates:Mobile screening unit deployment programs in underserved regions extend DBT penetration beyond hospital radiology departments.
Market Restraints
- X-ray tube supply concentration:Specialized rotating anode tube manufacturing concentrates among limited suppliers, creating procurement bottlenecks for system OEMs.
- EU MDR certification timelines:Stricter clinical evidence requirements for software-driven imaging modalities extend market authorization cycles for AI-enhanced platforms.
- Conventional 2D mammography installed base:Functional existing equipment with established maintenance infrastructure delays replacement decisions at cost-constrained facilities.
Strategic Opportunities
- Contrast-enhanced tomosynthesis protocols:Dual-energy imaging capabilities enable lesion vascularity assessment, expanding DBT from screening into diagnostic characterization workflows.
- India diagnostic imaging infrastructure:Central government health scheme expansion creates procurement channels for mid-range systems in tier-2 and tier-3 cities.
- Subscription-based software licensing:Recurring revenue models for reconstruction algorithm updates and AI module access decouple technology refresh from hardware replacement cycles.
Industry Challenges
- Radiologist workforce density constraints:Interpretation complexity and reading volume requirements limit scalable DBT program deployment regardless of equipment availability.
- Legacy PACS integration friction:Three-dimensional data volumes exceed storage and retrieval specifications of older picture archiving systems, requiring ancillary infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Breast Tomosynthesis (DBT) Equipment Market |
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Field 3D, Portable DBT, Digital Mammography, Contrast-Enhanced DBT End User: Hospitals, Diagnostic Imaging Centers, Research Institutions, Breast Clinics Technology: Tomosynthesis, Digital Detection, Advanced Imaging, AI-Enhanced Application: Screening, Diagnostic Tests, Clinical Studies, Treatment Monitoring |
| Companies Covered | Hologic, Inc, GE Healthcare, Siemens Healthineers, Fujifilm Holdings Corporation, Canon Medical Systems, Planmed Oy, PerkinElmer, Analogic Corporation, Internazionale Medico Scientifica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Breast Tomosynthesis (DBT) Equipment Market Strategic Shifts
Computational imaging advances and evolving payor frameworks are compressing the gap between diagnostic capability and economic accessibility, redefining how breast imaging technology delivers clinical value.
Photon-counting detector technology is hybridizing spectral sensitivity with standard tomosynthesis acquisition, enabling material decomposition within breast tissue without additional radiation exposure. Academic medical centers in the United States and university hospitals in Germany are piloting these systems for high-risk patient stratification. The convergence is compressing the traditional separation between screening and diagnostic imaging modalities into unified platform architectures.
The EU MDR's clinical evidence requirements for software-as-medical-device are forcing AI-integrated tomosynthesis vendors to generate prospective validation datasets across multiple European sites. Manufacturers must now maintain post-market surveillance infrastructure that tracks algorithm performance in routine clinical use. This regulatory burden disproportionately affects smaller imaging software developers lacking established quality management systems.
After-sales service unbundling is gaining traction as hospital procurement teams negotiate component-level maintenance contracts separate from original equipment manufacturer service agreements. Third-party imaging equipment servicers in the United States are capturing detector calibration and x-ray tube replacement business previously captive to GE Healthcare and Siemens Healthineers ecosystems. This disintermediation is most visible in mature DBT installed bases where technical training pipelines have produced independent service engineering capacity.
Digital Breast Tomosynthesis (DBT) Equipment Market Segmentation
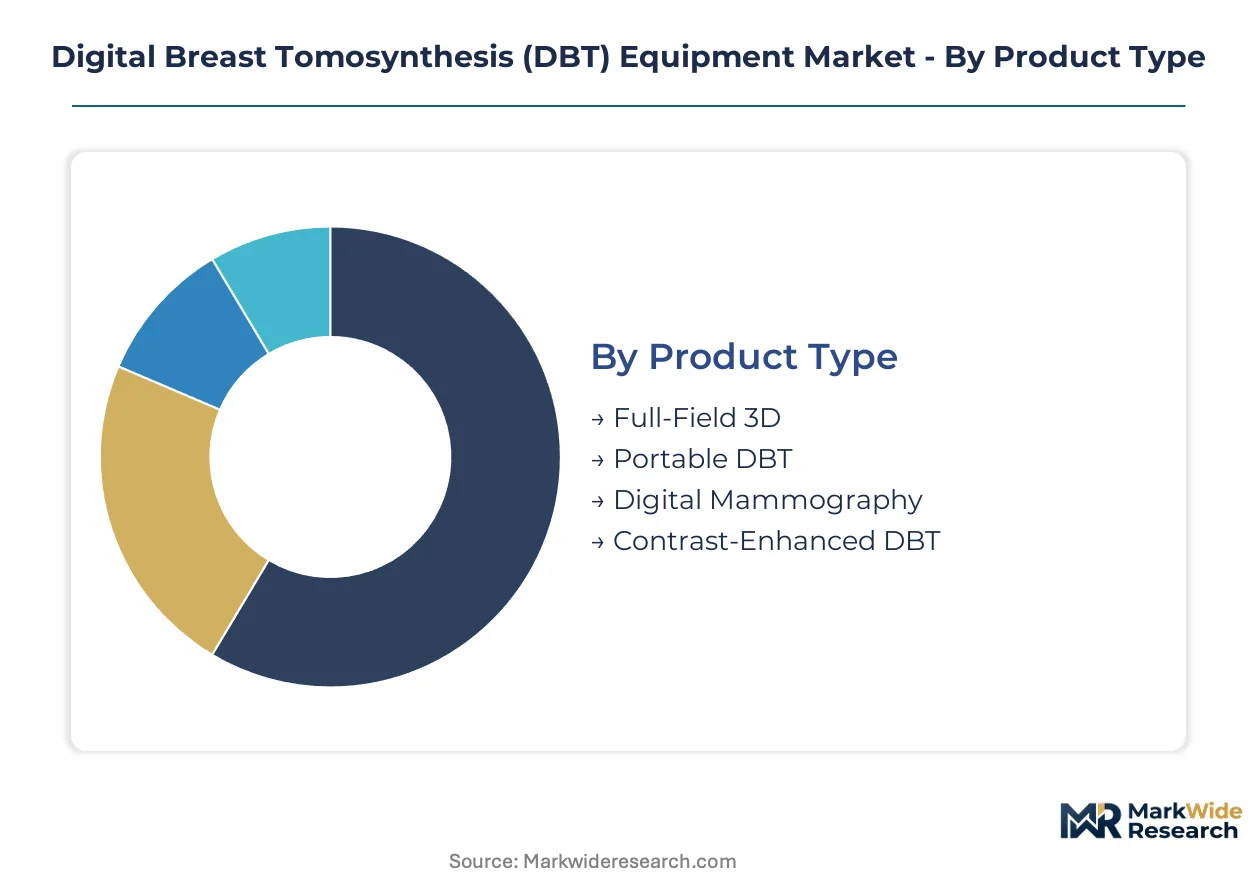
DBT equipment segmentation reveals how technical specifications, clinical settings, and software capabilities partition procurement decisions. Understanding these divisions exposes where pricing power concentrates and which system architectures face displacement pressure.
Product Type:
Cost tier differentiation separates systems by acquisition capital, throughput capacity, and reimbursement eligibility.
- Full-Field 3D:Stationary gantry systems acquire 15-50 degree arc projections with amorphous selenium or cesium iodide flat-panel detectors. Hospital radiology departments in Germany anchor demand as statutory health insurance reimbursement locks in standard-of-care status for high-volume screening programs.
- Portable DBT:Compact systems with battery-powered x-ray generators and carbon-fiber structural components enable mobile unit deployment. Rural access mandates in the United States drive fastest segment expansion as federally qualified health centers extend screening to underserved populations.
- Digital Mammography:Conventional 2D systems with digital receptors remain entrenched in cost-constrained facilities where functional equipment delays replacement cycles.
- Contrast-Enhanced DBT:Dual-energy acquisition protocols with iodinated contrast integration enable lesion vascularity assessment, expanding from screening into diagnostic characterization workflows.
Full-Field 3D holds installed capacity. Portable DBT is rotating up the share rankings.
End User:
Customer type determines procurement authority, service contract structure, and upgrade cycle frequency.
- Hospitals:Integrated health systems with centralized capital budgeting prioritize multi-modality platform ecosystems. GE Healthcare and Siemens Healthineers lock these accounts through long-term service agreements covering CT, MRI, and mammography infrastructure.
- Diagnostic Imaging Centers:Independent outpatient facilities concentrate DBT procurement in Germany's breast care networks where G-BA reimbursement creates predictable revenue visibility.
- Research Institutions:Academic medical centers pilot photon-counting detector technology and AI validation protocols, generating clinical evidence for regulatory submissions.
- Breast Clinics:Specialized single-modality facilities prioritize throughput optimization and radiologist workflow efficiency over platform breadth.
Hospitals command procurement volume. Diagnostic Imaging Centers are climbing the fastest in annual system placements.
Technology:
Maturity gradients separate established reconstruction methods from emerging software-driven capabilities.
- Tomosynthesis:Established filtered back-projection and iterative reconstruction algorithms process arc-acquired projections into thin-slice volumes. Hologic's dense patent positioning in reconstruction mathematics sustains technology leadership.
- Digital Detection:Amorphous silicon TFT arrays with cesium iodide scintillation layers dominate detector architecture, though photon-counting cadmium-zinc-telluride sensors are gaining traction in premium installations.
- Advanced Imaging:Spectral decomposition and dual-energy acquisition extend tissue characterization without additional radiation exposure.
- AI-Enhanced:Deep learning algorithms automate lesion detection, density assessment, and triage prioritization. EU MDR clinical evidence requirements extend certification timelines for these software-as-medical-device platforms.
Tomosynthesis holds installed capacity. AI-Enhanced is rotating up the share rankings.
Application:
Volume distribution across clinical use cases determines system utilization rates and revenue per examination.
- Screening:Asymptomatic population imaging drives highest examination volume and reimbursement code dependency. FDA Mammography Quality Standards Act compliance mandates shape equipment replacement timelines.
- Diagnostic Tests:Symptomatic patient workup and callback evaluation commands premium pricing per study but lower annual throughput.
- Clinical Studies:Trial imaging generates episodic demand tied to pharmaceutical and device study protocols.
- Treatment Monitoring:Neoadjuvant therapy response assessment creates recurring demand in oncology service lines.
Screening holds installed capacity. Diagnostic Tests are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's Mammography Quality Standards Act enforcement infrastructure underwrites United States market primacy, while Germany's statutory health insurance reimbursement architecture anchors European equipment absorption. China's domestic x-ray tube manufacturing capacity expansion reshapes supply chain geography across Asia-Pacific procurement channels.
United States
Hospital radiology departments anchor equipment procurement as screening protocols shift toward three-dimensional imaging. The FDA refines mammography quality standards that shape replacement cycles and software upgrade requirements. Academic medical centers in Boston and the Research Triangle pilot photon-counting detector systems for high-risk patient stratification.
Germany
Outpatient breast care networks concentrate demand visibility following G-BA assessment establishing DBT as standard-of-care. Statutory health insurance reimbursement activation creates predictable procurement cycles for diagnostic imaging centers. The Rhine-Ruhr and Bavarian medical technology clusters host university hospitals validating AI-integrated reconstruction algorithms.
China
Domestic manufacturers scale x-ray tube and detector module capacity to challenge incumbent supply chains. The national pharmaceutical regulator tightens clinical evidence requirements for software-driven imaging modalities under revised medical device regulations. Shanghai and Shenzhen imaging equipment production zones attract venture financing for flat-panel detector assembly lines.
India
Central government health scheme expansion creates procurement channels for mid-range systems in tier-2 and tier-3 cities. The national pharmaceutical regulator extends certification timelines for AI-enhanced platforms under strengthened software-as-medical-device frameworks. Maharashtra and Karnataka diagnostic imaging infrastructure clusters absorb mobile screening unit deployments.
Japan
Prefectural health authorities integrate DBT into standardized breast cancer screening protocols for asymptomatic populations. The national pharmaceutical regulator coordinates with health technology assessment bodies on reimbursement eligibility criteria. Tokyo and Osaka metropolitan medical centers concentrate installed base expansion for contrast-enhanced diagnostic characterization workflows.
Digital Breast Tomosynthesis (DBT) Equipment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in detector architecture and reconstruction algorithm supply. The vendor base concentrates among imaging conglomerates with multi-modality service ecosystems and independent breast imaging specialists with focused modality depth. Three archetypes dominate: captive detector manufacturers with dense patent positioning, diversified health technology conglomerates with long-term service lock-in, and regional equipment specialists with price-competitive standard configurations. Competitive moves center on multi-year service contract bundling and AI module subscription licensing.
Within the diversified health technology tier, GE Healthcare and Siemens Healthineers exemplify platform integrators leveraging multi-modality service ecosystems. Hologic, Inc. occupies a distinct position as a captive flat-panel detector producer with concentrated patent positioning in tomosynthesis reconstruction mathematics. Fujifilm Holdings Corporation represents the diversified imaging conglomerate archetype with cross-modal technology transfer capabilities.
| Leading Market Players |
|---|
| Hologic, Inc |
| GE Healthcare |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Canon Medical Systems |
| Planmed Oy |
| PerkinElmer |
| Analogic Corporation |
| Internazionale Medico Scientifica |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific air freight corridors linking Shanghai Pudong to Frankfurt and Chicago O'Hare transmit cost volatility from specialized x-ray tube foundries directly into DBT system landed costs, compressing margins for mid-tier OEMs while amplifying price differentiation between premium detector-integrated platforms and standard-configuration alternatives.
Pricing Analysis
Volume-discount tiering structures separate procurement negotiations for hospital health systems purchasing five-plus units annually from independent breast clinics acquiring single systems. Three-tier pricing stratifies across premium AI-integrated platforms with photon-counting detectors, standard full-field 3D configurations with amorphous selenium panels, and economy portable units for mobile screening deployment. Cost compression in the standard tier intensifies because Chinese domestic manufacturers are scaling flat-panel detector assembly capacity. Hospital purchasing committees exhibit highest price sensitivity, while academic medical centers prioritize technology access over unit economics.
Supply Chain Analysis
Export-control regimes limiting dual-use semiconductor manufacturing equipment constrain photon-counting detector substrate flows from Germany and Japan into Chinese assembly plants. Specialized rotating anode x-ray tube production concentrates in Germany, Japan, and the United States, with amorphous selenium and cesium iodide scintillator materials drawing from South Korean and Belgian chemical processors. Single-source vulnerability characterizes high-voltage generator modules sourced from Austrian and Swiss suppliers. Distribution runs through authorized dealer networks for hospital systems and direct OEM contracts for government health scheme procurement in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities now outpace hardware revenue expansion as AI module subscriptions and reconstruction algorithm licensing generate recurring income streams independent of capital equipment replacement cycles.
For Market Incumbents: Harden service contract renewal rates by embedding detector calibration and x-ray tube replacement into multi-year agreements that resist third-party disintermediation. Deepen backward integration into flat-panel detector substrates to offset supply concentration risk from South Korean chemical processors. Prioritize certification investment for EU MDR software-as-medical-device pathways ahead of smaller AI developers lacking quality management infrastructure.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 and tier-3 diagnostic imaging centers where central government health scheme expansion creates procurement channels underserved by incumbent service networks. Target portable DBT configurations for federally qualified health center mobile screening programs in rural United States markets. Pursue component-level maintenance contracts as an entry vector, leveraging technical training pipeline graduates to undercut OEM service pricing.
For Investors and Strategic Acquirers: Independent breast imaging specialists with concentrated modality depth and established G-BA reimbursement track records in Germany present consolidation targets as platform integrators seek focused technology assets. Long-term viability hinges on AI algorithm validation infrastructure capable of generating prospective clinical evidence across multiple European sites under EU MDR surveillance requirements. Monitor radiologist workforce density constraints as the inflection indicator—interpretation complexity bottlenecks will cap scalable DBT program deployment regardless of equipment availability, shifting value capture toward workflow automation software.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Module Subscription Licensing | Recurring revenue decouples technology refresh from hardware replacement cycles. |
| Photon-Counting Detector Integration | Spectral sensitivity enables material decomposition without additional radiation exposure. |
| EU MDR Software Certification | Post-market surveillance infrastructure requirements disproportionately burden smaller developers. |
| Mobile Screening Unit Deployment | Federally qualified health centers extend DBT access to rural and underserved United States populations. |
| Third-Party Service Contract Capture | Independent servicers capture detector calibration business from OEM captive agreements. |
Study Parameters
Operator-level perspectives from hospital purchasing committee chairs, biomedical engineering directors, breast imaging radiologists, GPO contracts managers, and outpatient clinic administrators anchored the qualitative base. Secondary validation drew from FDA 510(k) premarket notification databases, EMA medical device registration filings, German G-BA health technology assessment reports, CMS Medicare reimbursement code databases, and hospital procurement contract aggregators. Bottom-up equipment shipment modeling triangulated against top-down healthcare expenditure allocation estimates across the analysis window.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated reimbursement adoption pathways throughout the forecast period. Segmentation dimensions modeled included product type tier, end-user facility scale, technology maturity gradient, and application clinical purpose. CAGRs were derived from installed base expansion rates weighted by replacement cycle timing and software upgrade attach rates. Forecast inputs incorporated radiologist workforce density projections and statutory health insurance coverage activation timelines.
Stress conditions across reimbursement code activation delays, x-ray tube supply disruptions, and EU MDR certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding screening protocol transition speed and AI algorithm regulatory acceptance. Material shifts in statutory health insurance coverage determination or radiologist training pipeline capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Electroretinography Market
Medical Imaging
Specialty PACS Market
Medical Imaging
Germany Magnetic Resonance Imaging Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
Spectroscopy Intravascular Imaging System Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Global Portable Magnetic Resonance Imaging Market
Medical Imaging
South America Mammography Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
Global Ultrasound Imaging Devices Market