
 Neuromodulation Market | 2026-2036
Neuromodulation Market Size, Share, and Industry Trends Forecast 2026-2036
Neuromodulation Market Intelligence
The shift toward closed-loop, adaptive neuromodulation systems is redrawing the therapeutic landscape for efficacy and patient outcomes. Medtronic leverages its extensive research and development in deep brain stimulation to maintain a significant market presence. Boston Scientific Corporation differentiates through its focus on spinal cord stimulation technologies for pain management, while Abbott competes with a diverse portfolio that addresses multiple therapy areas, including Parkinson's disease and chronic pain.
Neuromodulation involves the alteration of nerve activity through targeted delivery of electrical or chemical agents directly to a specific area of the nervous system. These systems typically consist of an implantable pulse generator, electrodes, and a patient programmer, enabling precise modulation of neural circuits. Spinal Cord Stimulators represent a dominant product category, driven by their established application in chronic pain management. Therapies for epilepsy and Parkinson's disease are also significant, supported by expanding clinical evidence and growing physician acceptance.
Market access is governed by stringent regulatory approvals from bodies like the US FDA and through CE marking under Europe's Medical Device Regulation (MDR). These frameworks mandate rigorous clinical trials to prove safety and efficacy, setting a high barrier to entry. In China, NMPA approval is essential for market entry. Stakeholders must now navigate the increasing complexity of securing reimbursement approvals from payers alongside these demanding regulatory hurdles.
Market Dynamics
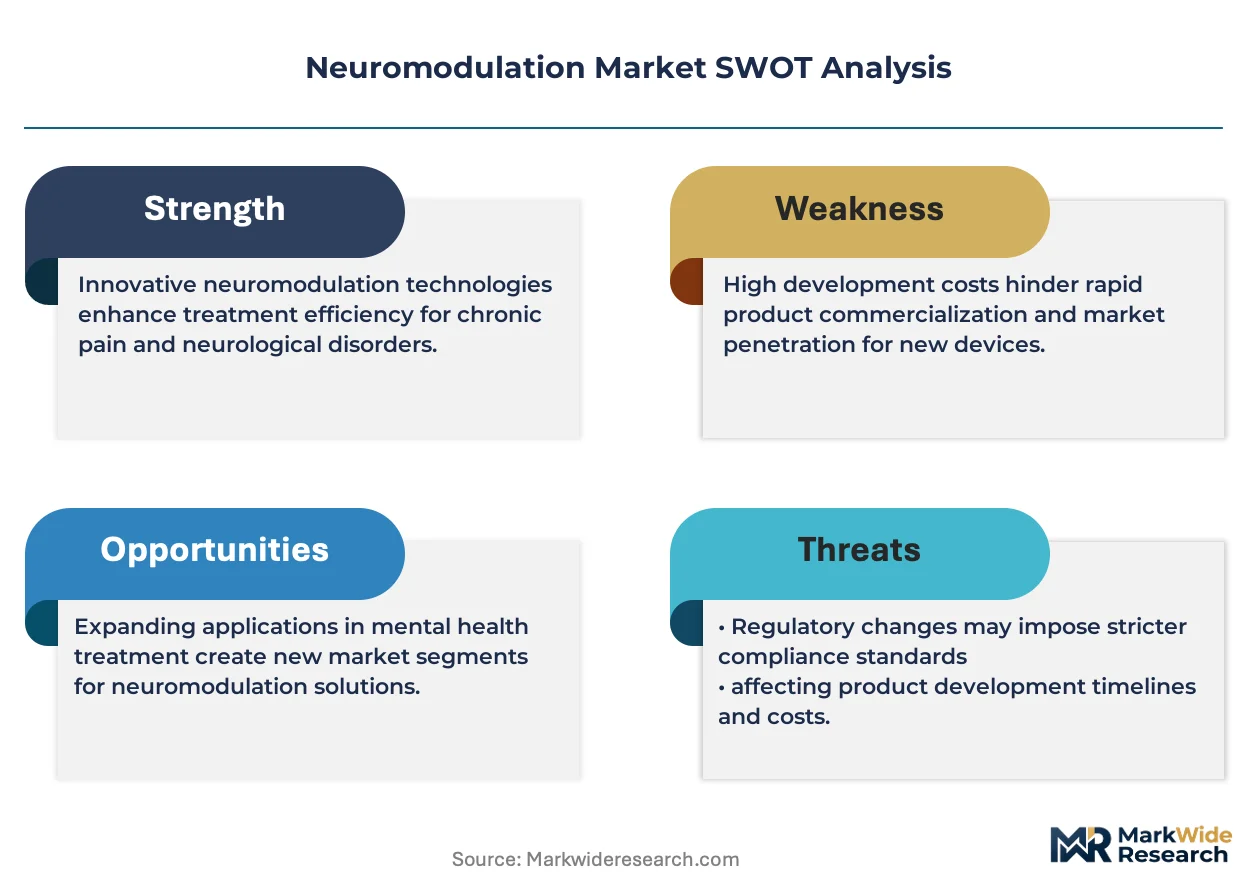
The convergence of advanced microelectronics with personalized medicine is the central force shaping the neuromodulation market. This evolution drives a fundamental shift from static, open-loop stimulation for symptom management toward adaptive, closed-loop systems that provide real-time therapeutic adjustments based on patient-specific neural feedback.
Growth Catalysts
- Expanding Clinical Applications:Growing clinical evidence for therapies treating epilepsy and Parkinson's disease is broadening physician acceptance and securing more favorable reimbursement decisions from payers in the United States and Germany.
- Device Miniaturization:Continuous innovation in implantable pulse generator (IPG) and electrode design is leading to smaller, less invasive devices, which improves patient comfort and reduces surgical recovery times.
- Chronic Disease Prevalence:The increasing global incidence of chronic pain, particularly neuropathic and back pain, creates a sustained demand for effective, long-term, non-pharmacological treatment alternatives to opioid-based therapies.
Market Restraints
- High Treatment Costs:The significant upfront cost of neuromodulation systems and associated surgical procedures, combined with inconsistent reimbursement frameworks outside of established markets, creates a substantial barrier to patient access.
- Stringent Regulatory Hurdles:The rigorous and lengthy clinical trial processes mandated by regulatory bodies like the US FDA and under Europe's Medical Device Regulation (MDR) set a high barrier to entry and slow the pace of innovation.
- Device-Related Complications:Potential risks such as lead migration, hardware failure, or infection, along with the necessity for periodic battery replacement surgeries, can deter both patients and referring physicians from choosing implantable therapies.
Strategic Opportunities
- Emerging Psychiatric Indications:Developing therapies for treatment-resistant depression and obsessive-compulsive disorder (OCD) represents a significant growth vector, supported by early but promising clinical data.
- Untapped Geographic Markets:Expansion into markets with aging populations and rising healthcare spending, such as Japan and South Korea, offers substantial opportunity for spinal cord stimulation and deep brain stimulation technologies.
- AI-Powered Closed-Loop Systems:Integrating artificial intelligence and machine learning algorithms into devices to predict and preempt symptoms before they occur offers a pathway to superior therapeutic outcomes beyond current adaptive systems.
Industry Challenges
- Specialized Physician Shortage:A scarcity of neurosurgeons and pain specialists trained in the implantation and long-term management of complex neuromodulation systems creates an execution bottleneck, limiting procedure volumes.
- Divergent Regulatory Pathways:Navigating disparate and complex approval processes, such as those governed by the NMPA in China versus the FDA in the United States, demands significant resources and extends product launch timelines.
- Data Interoperability:Achieving seamless and secure integration between implantable devices, patient programmers, and hospital electronic health record (EHR) systems remains a persistent technical and logistical challenge for providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuromodulation Market |
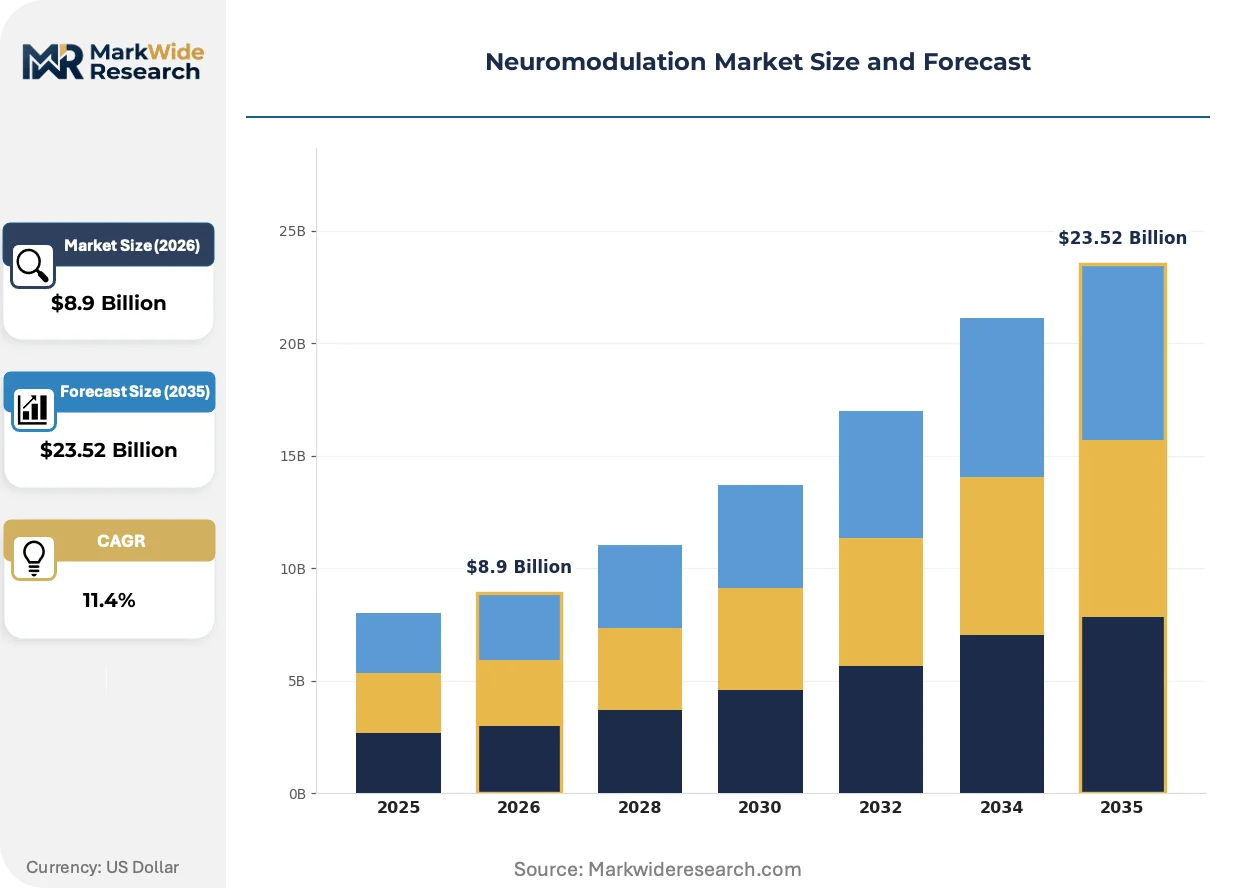
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $23.52 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinal Cord Stimulators, Deep Brain Stimulators, Vagus Nerve Stimulators, Transcranial Magnetic Stimulators Therapy Area: Pain Management, Epilepsy, Depression, Parkinson's Disease End User: Hospitals, Neurology Clinics, Rehabilitation Centers, Homecare Settings Application: Chronic Pain, Mood Disorders, Movement Disorders, Sleep Disorders |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, LivaNova PLC, Nevro Corp, NeuroPace, Axonics Modulation Technologies, Saluda Medical, Biotronik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuromodulation Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive pivot toward non-pharmacological, data-driven interventions. This movement prioritizes creating more precise, personalized, and less invasive therapies, moving beyond the limitations of one-size-fits-all electrical stimulation protocols and enhancing patient-specific outcomes.
Implantable pulse generators (IPGs) provide the controlled electrical stimulation central to neuromodulation therapy. Patients requiring long-term, discrete treatment for conditions like chronic pain or movement disorders are the primary adopters. This core technology is miniaturizing the entire device footprint, which enables implantation in a wider variety of anatomical locations and significantly reduces surgical invasiveness.
Europe's Medical Device Regulation (MDR) has intensified scrutiny on high-risk implantable devices. This framework mandates more extensive clinical data and robust post-market surveillance to prove safety and performance throughout the device lifecycle. The regulation affects all manufacturers selling into the European Union, forcing reinvestment in clinical trials and quality management systems to obtain and maintain CE marking for their products.
A notable behavioral shift is occurring from a purely physician-directed selection process toward a more patient-centric model. In this new dynamic, factors like a device's impact on lifestyle, its ease of use, and the patient's ability to access their own therapy data are becoming critical decision criteria. This trend is most visible in the United States, where patients with chronic pain or Parkinson's disease are increasingly active participants in choosing their treatment pathway.
Neuromodulation Market Segmentation
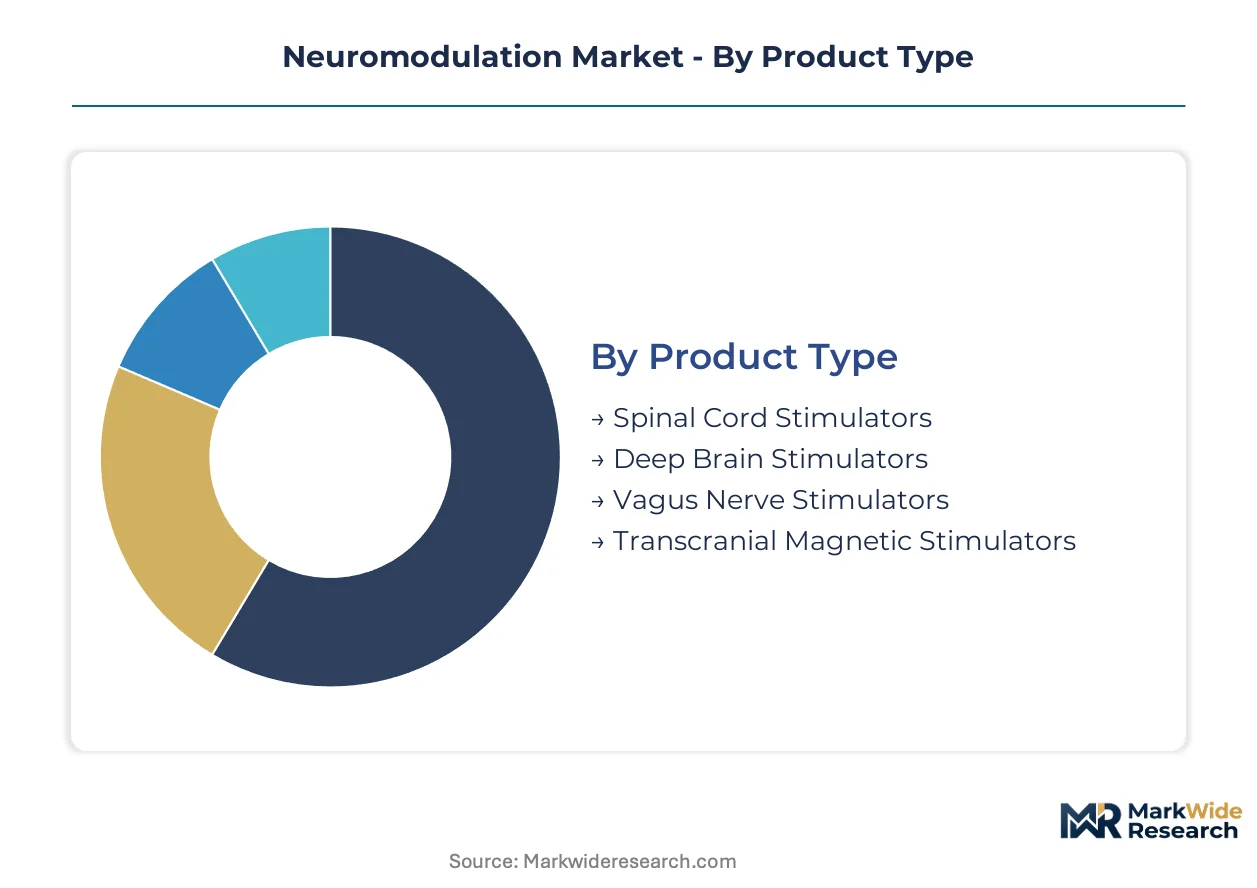
The neuromodulation market exhibits diverse therapeutic approaches and device technologies, necessitating granular segmentation to understand specific demand patterns. Analyzing these distinct segments reveals the underlying forces driving innovation and adoption across varied clinical settings. This detailed breakdown highlights key areas of investment and strategic focus for market participants.
Product Type:
Margin pools within the product type segment often concentrate around complex, implantable devices requiring specialized surgical expertise and extensive post-operative care.
- Spinal Cord Stimulators:These devices deliver low-voltage electrical current to the spinal cord, interrupting pain signals before they reach the brain. Demand concentrates in chronic neuropathic and intractable back pain management, driven by the need for non-opioid alternatives in the United States and Germany.
- Deep Brain Stimulators:Implanted electrodes target specific brain areas, delivering electrical impulses to regulate abnormal brain activity. The demand for these systems is strong in Parkinson's disease and essential tremor treatment, supported by expanding clinical evidence and physician acceptance in developed economies.
- Vagus Nerve Stimulators:These devices provide intermittent electrical pulses to the vagus nerve, primarily used for epilepsy and treatment-resistant depression.
- Transcranial Magnetic Stimulators:Non-invasive devices use magnetic fields to stimulate nerve cells in the brain, offering therapy for major depressive disorder and obsessive-compulsive disorder.
Spinal Cord Stimulators hold installed capacity due to their established application. Deep Brain Stimulators are rotating up the share rankings with expanding indications and technological advancements.
Therapy Area:
The application landscape for neuromodulation therapies spans a wide range of neurological and psychiatric conditions, defining specific patient populations and treatment protocols.
- Pain Management:This area encompasses the use of neuromodulation for chronic, intractable pain, including neuropathic pain and failed back surgery syndrome. Demand is high in the United States and Europe, driven by the opioid crisis and the search for durable, non-pharmacological solutions.
- Parkinson's Disease:Neuromodulation, particularly deep brain stimulation, offers significant symptom control for motor fluctuations and dyskinesia in advanced Parkinson's disease. Clinical guidelines in countries like France and Japan increasingly support its use for eligible patients.
- Epilepsy:Therapies like vagus nerve stimulation and responsive neurostimulation reduce seizure frequency in patients with drug-resistant epilepsy.
- Depression:Neuromodulation techniques, including transcranial magnetic stimulation and vagus nerve stimulation, target treatment-resistant depression cases.
The fastest expansion is observed in Parkinson's Disease treatments, while Pain Management maintains a substantial base of treated patients.
End User:
The end-user segment determines the infrastructure requirements and care delivery models for neuromodulation therapies, influencing device distribution and patient access.
- Hospitals:These facilities serve as primary sites for implantable neuromodulation device surgeries, including deep brain and spinal cord stimulators. Hospitals in major urban centers across the United States and Germany manage the initial patient workup and complex post-operative care.
- Neurology Clinics:Specialists within these clinics manage patient selection, programming, and long-term follow-up for neuromodulation devices. These clinics in countries like Canada and Australia provide ongoing patient support and therapy adjustments.
- Rehabilitation Centers:These centers integrate neuromodulation therapies into comprehensive rehabilitation programs for neurological conditions and chronic pain.
- Homecare Settings:Patients utilize external neuromodulation devices and patient programmers in homecare, enabling self-management and remote monitoring capabilities.
High-volume procedures predominantly occur within Hospitals, with Homecare Settings representing a growing point-of-care option for ongoing management.
Application:
The specific medical application dictates the targeted neural pathways and the precise parameters required for effective neuromodulation, tailoring treatment to patient needs.
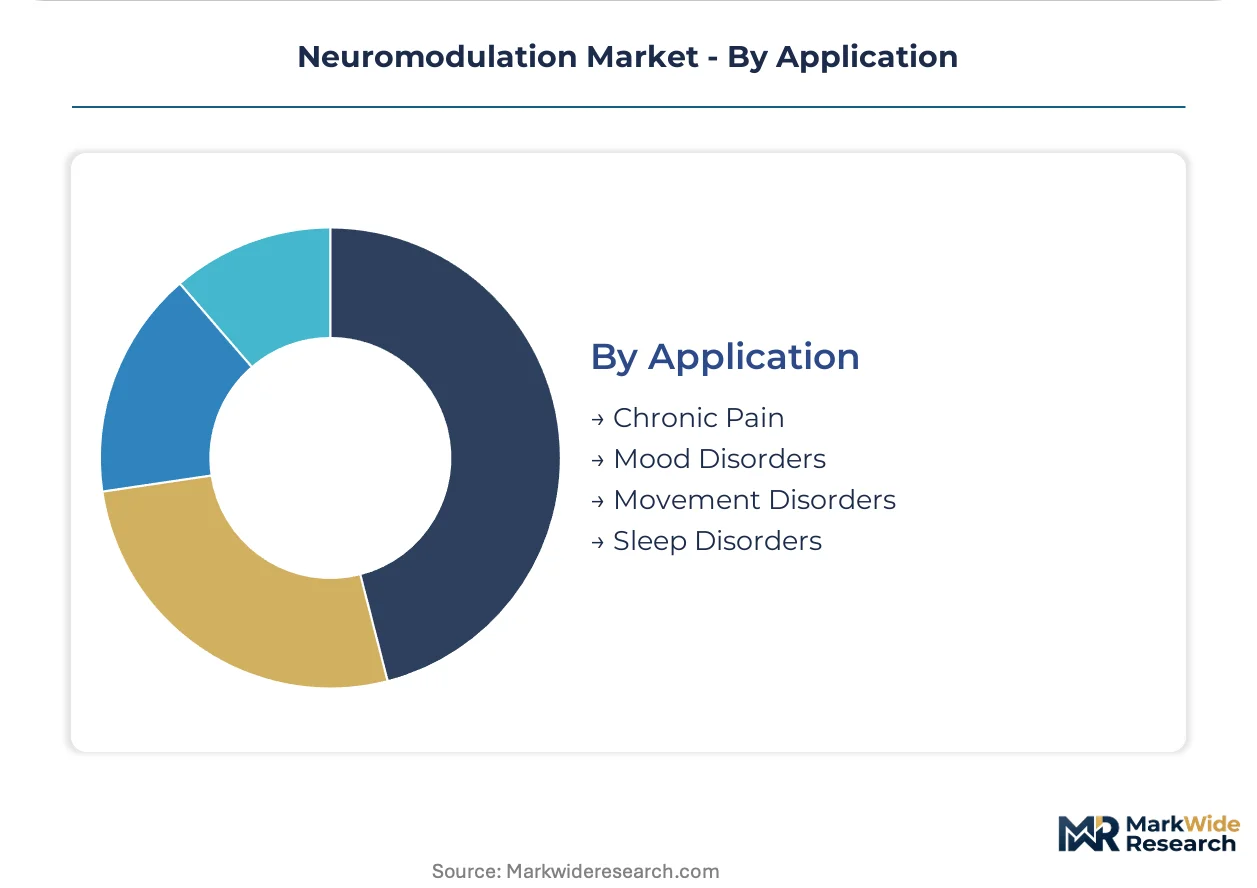
- Chronic Pain:This application involves using neuromodulation to alleviate persistent pain conditions, such as neuropathic pain, radicular pain, and complex regional pain syndrome. Patient demand is particularly high in regions with aging populations and high incidences of musculoskeletal disorders, like Japan and Italy.
- Movement Disorders:Neuromodulation addresses conditions characterized by involuntary or impaired movements, including Parkinson's disease, essential tremor, and dystonia. The application focuses on restoring motor function and reducing disabling symptoms, especially in technologically advanced healthcare systems.
- Mood Disorders:This application targets conditions like major depressive disorder and obsessive-compulsive disorder, utilizing neuromodulation to modulate brain circuits associated with mood regulation.
- Sleep Disorders:Emerging applications explore neuromodulation for conditions such as insomnia and sleep apnea, aiming to regulate neural activity involved in sleep patterns.
Chronic Pain drives the largest patient volume, while Sleep Disorders show significant potential for future expansion as research progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neuromodulation technology development and manufacturing capabilities are concentrating in a few key global hubs. These regions benefit from advanced healthcare infrastructure, significant R&D investment, and established regulatory pathways. This concentration influences global market dynamics.
United States
The United States exhibits robust demand for neuromodulation, driven by its sophisticated healthcare infrastructure and established reimbursement frameworks. US FDA approvals ensure high device safety and efficacy standards. Innovation clusters in Boston and California's Silicon Valley foster significant neurotech research and development.
Germany
Germany shows strong demand for neuromodulation devices, supported by growing physician acceptance for Parkinson's disease and epilepsy treatments. CE marking under Europe's Medical Device Regulation (MDR) is essential for market entry. Medical technology clusters in Bavaria and Baden-Württemberg develop and manufacture high-precision implantable devices.
Japan
Japan presents significant opportunities due to its rapidly aging population and increasing prevalence of movement disorders. PMDA approval is a crucial regulatory hurdle for neuromodulation devices. Medical device ecosystems in Tokyo and Osaka actively engage in clinical research and product localization efforts.
China
China's neuromodulation market is expanding, fueled by rising healthcare spending and a growing patient pool for chronic conditions. NMPA approval is a prerequisite for any neuromodulation device to gain market access. Shanghai and Beijing are developing as important hubs for neurotech research, manufacturing, and clinical application.
France
France exhibits steady demand for neuromodulation, particularly for deep brain stimulation in Parkinson's disease, supported by national clinical guidelines. The ANSM regulates medical devices, ensuring compliance with Europe's Medical Device Regulation (MDR). Specialized neurology clinics and research institutions in Paris and Lyon contribute to advanced therapy adoption.
Neuromodulation Market Key Industry Players
Concentration sits with diversified medical device giants that command significant market share through extensive product portfolios. The market exhibits a tiered structure, with established global players alongside agile specialized neurotech innovators. These larger entities often pursue portfolio diversification and geographic expansion to maintain their competitive positioning. Smaller firms frequently focus on technological specialization and strategic partnerships to gain market traction.
Within the tier of established global medical technology providers, Medtronic represents a leader in deep brain stimulation, leveraging its extensive R&D capabilities. Boston Scientific Corporation occupies a significant position through its focus on spinal cord stimulation technologies for pain management. Abbott, a diversified healthcare company, exemplifies broad portfolio coverage across multiple therapy areas, including Parkinson's disease and chronic pain. These companies anchor the market with their long-standing presence and wide-ranging product offerings. Their strategic focus often involves continuous innovation within their core competencies and careful navigation of complex regulatory environments globally.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| LivaNova PLC |
| Nevro Corp |
| NeuroPace |
| Axonics Modulation Technologies |
| Saluda Medical |
| Biotronik |
| Others |
Cost & Logistics Intelligence
The shift from traditional pharmacological pain management to advanced neuromodulation devices reconfigures both the manufacturing footprint and the value-based pricing models across healthcare systems. This dynamic influences component sourcing and patient access.
Pricing Analysis
Europe's Medical Device Regulation (MDR) dictates the pricing tier structure for implantable neuromodulation devices, emphasizing value-based pricing tied to clinical outcomes. Price differentiation stems from device complexity and the level of post-sales support, including patient programming and follow-up. Pricing softness reflects increasing competition in established segments like spinal cord stimulators. Hospitals, facing budget constraints, exhibit higher price sensitivity compared to specialized neurology clinics focused on advanced, complex cases.
Supply Chain Analysis
Inbound logistics costs, particularly for high-precision microelectronics from East Asia, affect the final cost of neuromodulation systems. Supply concentrations are evident in Germany, the United States, and Japan for advanced manufacturing, relying on specialized microprocessors and biocompatible materials. Single-source vulnerability for rare-earth magnets represents a structural risk. Distribution runs through a direct sales force to hospitals and specialized clinics, often bundled with training and technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neuromodulation market faces a significant bottleneck from the limited availability of specialized neurosurgeons and pain specialists. This scarcity of trained personnel constrains procedure volumes and treatment adoption across regions.
For Market Incumbents: Shield existing market share by investing in next-generation closed-loop systems that offer superior patient outcomes, countering the threat from agile neurotech startups. Pursue strategic acquisitions of smaller firms specializing in non-invasive neuromodulation to broaden portfolio coverage. Control key intellectual property for miniaturized implantable pulse generators (IPGs) through continuous R&D.
For New Entrants and Emerging Players: Remote patient monitoring and programming services represent a service-layer gap where incumbents under-serve, offering a clear entry point. Target the treatment-resistant depression segment in untapped geographic markets like South Korea, leveraging non-invasive transcranial magnetic stimulation. Differentiate through user-friendly patient programmers and integrated data analytics for personalized therapy adjustments.
For Investors and Strategic Acquirers: The market sits at an early-growth phase that favors specialized neurotech innovators with validated clinical data. Long-term viability remains strong, driven by aging populations and the shift towards non-pharmacological therapies. Identify acquisition targets offering AI-powered closed-loop systems or novel bioelectronic medicine platforms. The signal to watch is expanding reimbursement coverage for emerging psychiatric indications.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Facilitates market access into the European Union for advanced neuromodulation devices. |
| Hospital System Partnership | Secures preferred provider status and streamlines patient access for implantable therapies. |
| Software Companion Development | Enhances device functionality and patient engagement through personalized therapy management. |
| Reimbursement Strategy | Ensures financial coverage for high-cost neuromodulation treatments, improving patient affordability. |
| Clinical Trial Advancement | Validates new indications for neuromodulation, broadening therapeutic applications for patients. |
Research Approach
The analysis maps neuromodulation sub-sectors, including spinal cord and deep brain stimulation, each validated through primary interviews with neurosurgeons, pain specialists, and hospital administrators. This integrates insights from device engineers and regulatory affairs leads. Secondary validation draws from FDA filings, CE marking documentation, and peer-reviewed clinical trial databases. Bottom-up data aggregation and top-down market sizing ensure robust triangulation.
Outputs were cross-referenced against external industry reports and historical market performance benchmarks to ensure consistency over the projection horizon. The analytical framework models segmentation across product type, therapy area, end-user, and application. Compound annual growth rates (CAGRs) derive from projected adoption rates and technological advancement curves, with key inputs including chronic disease prevalence and regulatory approval timelines.
Forecasts assume regulatory continuity in US FDA and Europe's MDR regimes; material policy shifts would require re-modeling. These projections reflect current market dynamics and technological trajectories, with device-related complications or reimbursement instability as specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intradermal Injections Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Heart Failure POC and LOC Devices Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Ventilator Accessories Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Versatile Cryosurgical Devices Market
Medical Devices
Global Otoscopes Market
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
Portable Medical Electronic Products Market
Medical Devices
Annuloplasty Rings Market