
 Ventilator Accessories Market | 2026-2036
Ventilator Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Ventilator Accessories Market Outlook
Silicone elastomer is recalibrating cost structures across ventilator tubing and mask seals as manufacturers substitute it for traditional PVC in reusable accessory lines. Medtronic leverages its polymer science capabilities to anchor premium tubing portfolios in North American health systems. ResMed competes through specialized humidifier chamber designs that integrate with its proprietary ventilator platforms. Fisher & Paykel Healthcare dominates breathing mask interfaces through sustained R&D investment in nasal cushion geometries.
Ventilator accessories encompass the disposable and semi-durable components that interface between mechanical ventilators and patients, including circuits rated for specific pressure differentials, filtration media with defined bacterial retention efficiencies, and humidification modules maintaining targeted airway moisture levels. These components serve to maintain sterile gas pathways, reduce ventilator-associated pneumonia risk, and enable precise parameter control across invasive and non-invasive ventilation modes. Filters and breathing masks capture the deepest margin pools due to high replacement frequency and direct patient-contact classification, while hybrid technology configurations are gaining fastest as manufacturers blend pneumatic reliability with electronic feedback in modern critical care settings. Manual technology persists in emergency transport segments where power independence remains non-negotiable.
FDA 510(k) clearance pathways and ISO 18562 biocompatibility standards govern material selection and patient-contact safety for accessories distributed in the United States, while the EU MDR and REACH chemical restrictions shape formulation choices for European market access. The EPA regulates volatile organic compound emissions from adhesive and coating processes used in tubing assembly operations. Stakeholders must monitor how evolving sterilization validation requirements across multiple jurisdictions will reshape manufacturing location decisions and supply chain configurations for disposable accessory lines.
Market Dynamics
The FDA's tightening sterilization validation requirements for reusable ventilator accessories are compressing product lifecycles and accelerating manufacturer migration toward single-use disposable architectures across North American supply chains.
Growth Catalysts
- Critical care infrastructure expansion:Government-funded ICU capacity programs in India are accelerating procurement of ventilator circuits and humidification systems through centralized hospital procurement frameworks.
- ISO 18562 biocompatibility standards:Harmonized material safety requirements are streamlining cross-border regulatory submissions and reducing time-to-market for silicone-based tubing innovations.
- Silicone elastomer substitution:Manufacturers are replacing PVC in reusable accessory lines to meet evolving chemical safety thresholds while maintaining pressure differential ratings.
Market Restraints
- Petrochemical feedstock volatility:Polymer resin costs for tubing and mask components fluctuate with crude oil indices, compressing margin stability for mid-tier manufacturers.
- Single-use waste compliance:EU MDR chemical restrictions and REACH substance limitations are constraining formulation choices for disposable accessory lines entering European distribution channels.
- Reusable sterilization complexity:Heat-sensitive electronic sensors embedded in modern humidification chambers degrade under standard autoclave cycles, limiting refurbishment economics.
Strategic Opportunities
- Home ventilation expansion:Non-invasive ventilation interfaces for sleep apnea and COPD management are penetrating residential care settings previously served only by acute facilities.
- Electronic-pneumatic convergence:Integration of flow sensors and pressure transducers into disposable circuits enables real-time parameter feedback without reusable capital equipment.
- Emergency transport segments:Manual technology configurations retain demand in ambulance and military field deployments where power independence remains non-negotiable.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists capable of balancing biocompatibility, sterilization resilience, and extrusion processability command premium compensation in medical device labor markets.
- 510(k) submission timelines:FDA clearance pathways for novel humidification chamber geometries extend development cycles, delaying revenue recognition for R&D-intensive portfolios.
- Legacy ventilator interoperability:Proprietary connector standards across installed equipment bases fragment addressable markets for universal-fit accessory designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventilator Accessories Market |
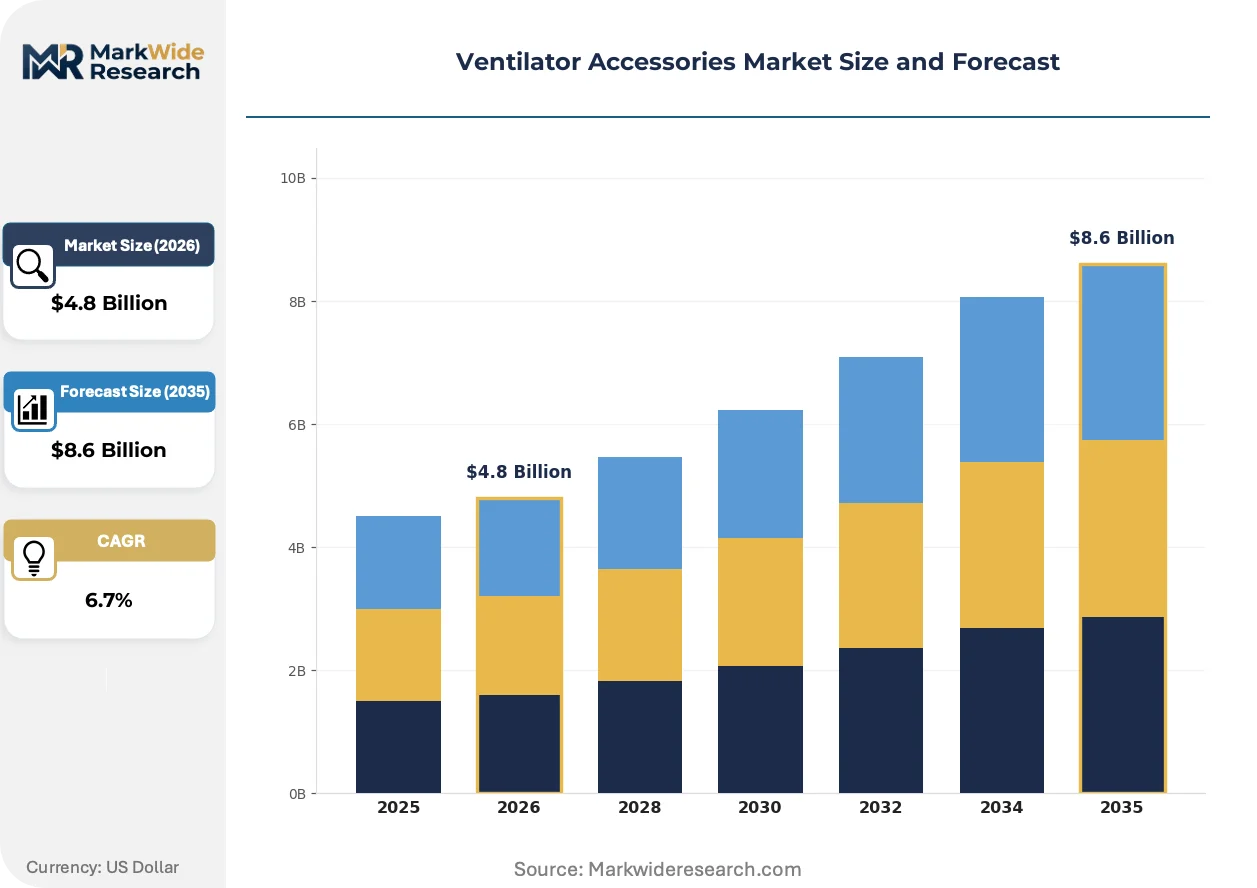
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filters, Tubing, Humidifiers, Breathing Masks Technology: Manual, Electric, Pneumatic, Hybrid End User: Hospitals, Homecare, Emergency Services, Clinics Application: Critical Care, Anesthesia, Postoperative Care, Transport |
| Companies Covered | Medtronic, Koninklijke Philips N.V., ResMed, GE Healthcare, Drägerwerk AG & Co. KGaA, Hamilton Medical, Smiths Group plc, Fisher & Paykel Healthcare, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventilator Accessories Market Strategic Shifts
Active materials and embedded sensing architectures are redefining the functional boundary between disposable circuits and capital equipment, compressing replacement economics while elevating clinical precision.
Silicone elastomer formulations are expanding into high-pressure tubing and mask seal applications where thermoplastic alternatives fail under cyclic loading. Academic medical centers in the United States are piloting these materials in extended-use protocols. The technology is expanding into premium positioning strategies that justify per-unit cost premiums against commodity PVC supply chains.
EU MDR technical documentation requirements are forcing manufacturers to reconstruct clinical evidence packages for legacy breathing mask interfaces previously cleared under withdrawn directives. Notified body capacity constraints are extending conformity assessment timelines. Small-to-mid tier suppliers are consolidating or exiting the European market entirely, concentrating distribution among polymer-integrated multinationals.
Hospital procurement departments are unbundling after-sales service contracts from capital ventilator purchases, creating standalone accessory sourcing frameworks. Group purchasing organizations are aggregating demand across health system networks, compressing distributor margins. This concentration is most visible in India, where government tender mechanisms specify multi-year circuit and filter supply agreements alongside initial equipment awards.
Ventilator Accessories Market Segmentation
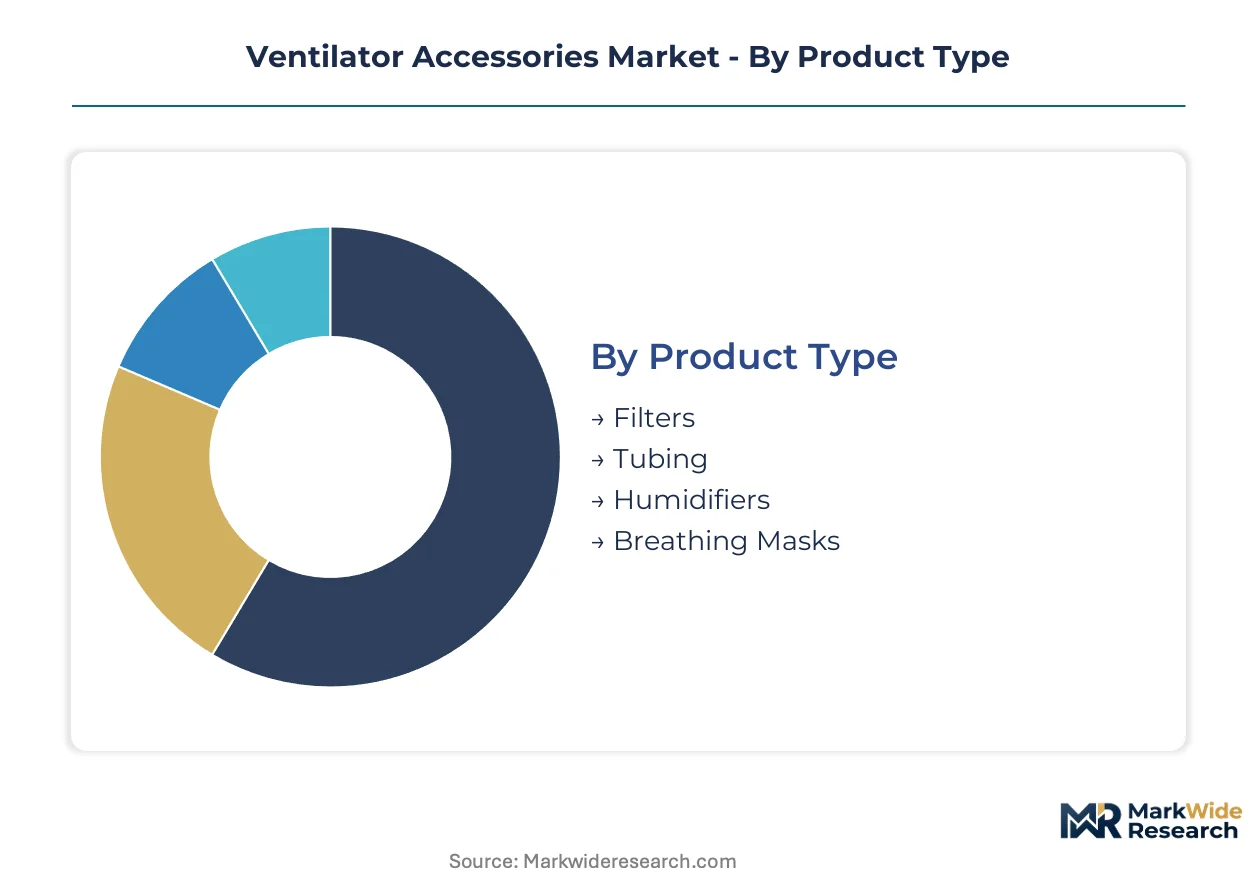
Ventilator accessories segment across four functional dimensions that shape procurement patterns and margin structures. Product type and technology classifications determine sterilization protocols and replacement economics, while end-user and application splits govern volume concentration and regulatory exposure.
Product Type:
Procurement departments weight replacement frequency against infection control liability when allocating spend across accessory categories.
- Filters:Bacterial and viral filtration media with defined particle retention efficiencies, typically rated at 99.97% for 0.3 micron aerosols. Demand concentrates in Indian government ICU expansion programs where bulk filter procurement accompanies ventilator tenders under centralized hospital frameworks. These components command premium positioning due to direct patient-contact classification and single-use disposal mandates.
- Breathing Masks:Nasal and oronasal interfaces incorporating silicone cushion geometries for pressure distribution and seal integrity. Homecare settings in the United States drive volume for non-invasive ventilation masks as COPD management shifts toward residential care. Mask replacement cycles accelerate with silicone elastomer substitution replacing legacy PVC formulations.
- Tubing:Corrugated circuits rated for pressure differentials and gas flow dynamics, manufactured from silicone or thermoplastic elastomers.
- Humidifiers:Chambers maintaining targeted airway moisture levels through heated or passive water exchange mechanisms.
Volume sits with Breathing Masks; growth tilts toward Filters.
Technology:
Power dependence and electronic integration define deployment contexts across acute, transport, and residential environments.
- Hybrid:Configurations blending pneumatic reliability with embedded flow sensors and pressure transducers for real-time parameter feedback. Critical care units in academic medical centers favor these systems for invasive ventilation modes requiring precise tidal volume control. Electronic-pneumatic convergence commands per-unit premiums against commodity pneumatic alternatives.
- Manual:Power-independent bellows and bag-valve-mask assemblies for emergency scenarios. Ambulance services and military field deployments in India retain demand where electrical supply uncertainty precludes electric alternatives. These configurations persist despite limited revenue per unit due to regulatory requirements for backup ventilation capability.
- Electric:Motor-driven flow generation with integrated battery systems for portable operation.
- Pneumatic:Gas-powered mechanisms leveraging wall supply or cylinder sources without electronic components.
Revenue concentrates in Hybrid configurations; Manual technology retains defensive procurement positions.
End User:
Facility type determines sterilization infrastructure, staff training levels, and reimbursement pathways for accessory procurement.
- Hospitals:Acute care institutions with centralized sterile processing departments and ICU capacity expansion programs. Indian government-funded critical care infrastructure drives concentrated circuit and humidification system procurement through multi-year supply agreements. FDA sterilization validation tightening accelerates single-use migration in these settings.
- Homecare:Residential settings for sleep apnea and COPD management with simplified interfaces and reduced technical support. United States Medicare reimbursement pathways shape volume for non-invasive mask and tubing replacements in patient homes. Silicone elastomer durability supports extended-use protocols outside acute monitoring environments.
- Emergency Services:Pre-hospital and transport contexts requiring power-independent backup systems.
- Clinics:Outpatient facilities with limited sterilization infrastructure favoring disposable architectures.
Procurement scale favors Hospitals; expansion rates climb fastest in Homecare.
Application:
Clinical scenario dictates pressure requirements, monitoring intensity, and accessory replacement protocols.
- Critical Care:Invasive ventilation for respiratory failure with high-acuity monitoring and sterile circuit requirements. Academic medical centers in the United States pilot silicone elastomer tubing in extended-use protocols to reduce replacement frequency. ISO 18562 biocompatibility standards govern material selection for prolonged patient contact durations.
- Transport:Inter-facility and pre-hospital transfer scenarios requiring compact, durable configurations. Military and ambulance deployments in India specify lightweight circuits with manual backup capability for power-independent operation. Vibration resistance and connector standardization dominate procurement specifications.
- Anesthesia:Operating room ventilation with scavenging systems and volatile anesthetic compatibility.
- Postoperative Care:Recovery unit ventilation with intermediate monitoring and weaning protocols.
Technology investment intensity peaks in Critical Care; Transport applications sustain manual technology demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian government-funded critical care infrastructure programs concentrate procurement demand for ventilator circuits and humidification systems through centralized hospital frameworks, while FDA sterilization tightening and EU MDR compliance reshape manufacturing footprints across North American and European supply chains.
United States
Academic medical centers pilot silicone elastomer tubing in extended-use protocols to reduce replacement frequency and infection control liability. FDA 510(k) clearance pathways and ISO 18562 biocompatibility standards govern material selection for patient-contact safety. Minneapolis and Boston anchor polymer science R&D clusters where manufacturers balance sterilization resilience with extrusion processability.
India
Government tender mechanisms specify multi-year circuit and filter supply agreements alongside initial ventilator equipment awards through centralized procurement frameworks. CDSCO medical device regulations and PLI scheme incentives shape domestic manufacturing investment decisions. Delhi-NCR and Maharashtra concentrate critical care infrastructure expansion with ICU capacity programs accelerating humidification system deployment.
Germany
Industrial clusters in Baden-Württemberg and Bavaria host precision polymer processing operations serving breathing mask interface production. EU MDR technical documentation requirements and REACH chemical restrictions constrain formulation choices for disposable accessory lines entering European distribution. Notified body capacity constraints extend conformity assessment timelines for legacy product recertification.
Japan
Homecare settings drive volume for non-invasive ventilation masks as COPD management shifts toward residential care under reimbursement pathway evolution. PMDA medical device regulations and METI industrial policy coordinate domestic manufacturing quality standards. Osaka and Nagoya clusters specialize in nasal cushion geometries and silicone seal durability testing.
Australia
TGA medical device regulations align with ISO 18562 standards to streamline cross-border regulatory submissions for silicone-based tubing innovations. Sydney and Melbourne concentrate respiratory device distribution networks serving Asia-Pacific export markets. Domestic procurement patterns favor hybrid technology configurations blending pneumatic reliability with electronic feedback for critical care applications.
Ventilator Accessories Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers balance reusable and disposable architectures amid regulatory tightening. The vendor base concentrates among polymer-integrated multinationals with captive material science capabilities and mid-tier specialists facing consolidation pressure from EU MDR compliance costs. Two strategic archetypes prevail: diversified medical device conglomerates leveraging vertical integration advantages, and focused respiratory specialists competing through proprietary platform integration. M&A activity and capacity expansion in silicone elastomer processing represent the dominant competitive moves reshaping supply configurations.
Within the diversified conglomerate tier, Medtronic and Koninklijke Philips N.V. exemplify polymer science integration across tubing and mask portfolios. ResMed occupies a position among platform-integrated specialists, while Fisher & Paykel Healthcare anchors the focused respiratory device archetype with sustained R&D positioning in nasal interface geometries. These entities represent contrasting strategic postures: scale-driven material backward integration versus specialized platform ecosystem control.
| Leading Market Players |
|---|
| Medtronic |
| Koninklijke Philips N.V. |
| ResMed |
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Hamilton Medical |
| Smiths Group plc |
| Fisher & Paykel Healthcare |
| Getinge AB |
| Others |
Value Chain & Pricing Dynamics
Silicone elastomer resin costs cascade through three-tier pricing structures across premium, standard, and economy levels as manufacturers in Germany and Japan balance biocompatibility certification investments against commodity PVC alternatives. Indian government tender mechanisms compress margins on bulk circuit and filter procurement while elevating price premiums for ISO 18562-validated silicone tubing in North American academic medical centers.
Pricing Analysis
Volume concentrates in economy-grade PVC circuits for Indian hospital tenders where per-unit margins compress under centralized procurement frameworks, while premium silicone elastomer formulations capture margin pools in North American critical care settings through ISO 18562 certification premiums. Price differentiation hinges on biocompatibility validation tier and sterilization resilience specifications, with FDA 510(k) clearance pathways adding regulatory cost layers that commodity suppliers avoid. Pricing pressure stems from petrochemical feedstock volatility in polymer resin markets, squeezing mid-tier manufacturers lacking backward integration into raw material supply. Group purchasing organizations exhibit highest price sensitivity in hospital segment aggregation, whereas homecare reimbursement pathways in the United States sustain premium positioning for durable silicone mask interfaces.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing hubs to North American distribution centers elevates landed costs for silicone tubing and humidification chambers, incentivizing regional production footprints in Germany and the United States. Supply concentrates in China for polymer resin feedstocks, India for molded circuit components, and Germany for precision breathing mask interfaces. Raw material dependencies center on medical-grade silicone elastomers, thermoplastic polyurethane for flexible connectors, and filtration media with defined bacterial retention specifications. Single-source vulnerability in medical-grade silicone supply from concentrated chemical processing clusters poses structural risk for manufacturers lacking dual-sourcing arrangements. Distribution runs through group purchasing organization contracts in hospital segments and durable medical equipment channels for homecare settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ventilator accessories market functions as a vertical-integration race where polymer science capabilities and captive silicone elastomer processing determine margin defense against regulatory tightening and procurement concentration.
For Market Incumbents: Deploy backward integration into medical-grade silicone elastomer compounding to insulate margin structures from petrochemical volatility and secure supply continuity under FDA sterilization validation tightening. Consolidate distribution relationships with Indian government procurement frameworks through multi-year circuit and filter supply agreements that lock out fragmented competitors. Counter proprietary ventilator platform fragmentation by developing universal-fit connector architectures compatible with legacy installed bases. For New Entrants and Emerging Players: Enter via emergency transport segments in India and Southeast Asia where manual technology configurations retain defensive demand and regulatory barriers remain lower than electronic-pneumatic hybrid systems. Target homecare mask replacement markets in Japan and Australia where reimbursement pathway evolution sustains premium positioning for silicone durability innovations. Pursue white-label manufacturing partnerships with polymer-integrated multinationals lacking specialized nasal cushion geometries rather than competing on capital-intensive R&D. For Investors and Strategic Acquirers: EU MDR notified body capacity constraints extending conformity assessment timelines is the leading indicator that small-to-mid tier suppliers will accelerate exit or consolidation, creating acquisition opportunities for polymer-integrated platforms with technical documentation resources. Long-term viability over the coming decade hinges on positioning within silicone elastomer formulation capabilities and regulatory compliance infrastructure rather than commodity circuit manufacturing. Monitor CDSCO domestic manufacturing incentive announcements under India's PLI scheme as the signal for supply chain relocation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Elastomer Capacity Expansion | Backward integration into medical-grade compounding secures margin defense against petrochemical volatility. |
| FDA 510(k) Submission Acceleration | Novel humidification chamber geometries command premium positioning in academic medical center procurement. |
| Indian Government Tender Participation | Multi-year circuit supply agreements lock in volume concentration from ICU expansion programs. |
| EU MDR Technical Documentation Investment | Notified body capacity constraints favor prepared manufacturers in legacy product recertification. |
| Homecare Distribution Partnership | Medicare reimbursement pathways in the United States sustain recurring mask replacement revenue. |
Study Parameters
Independent corroboration across hospital procurement databases, GPO contract filings, and FDA 510(k) clearance records underwrites the qualitative findings in this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and polymer formulation specialists supplied operational context on sterilization validation requirements and silicone substitution trends. Secondary validation drew from customs trade data for polymer resin imports, CDSCO medical device registration filings, and ISO 18562 biocompatibility testing documentation. Bottom-up segment sizing triangulated against top-down market aggregation from equipment installation bases and replacement frequency assumptions.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in segment-level projections. The analytical framework models product type, technology configuration, end-user facility category, and application scenario as core segmentation dimensions, with regional regulatory cluster and procurement mechanism type as cross-cutting variables. CAGRs derive from installed base growth, replacement cycle compression or extension, and mix shift toward premium silicone formulations. Forecast inputs incorporate ICU capacity expansion timelines from government budget allocations and evolving FDA sterilization validation guidance.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt petrochemical price shocks, notified body capacity bottlenecks in EU MDR recertification, or sudden shifts in Indian government procurement centralization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Therapeutic Respiratory Devices Market
Medical Devices
Vaginal Specula Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
Surgical Robotic Services Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Global Medical Implants Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
Global Medical Dynamometer Market
Medical Devices
Laser BPH Devices Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Consumer Grade EEG Device Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Medical Devices Clinical Trials Market