
 Electroencephalography (EEG) Amplifier System Market | 2026-2036
Electroencephalography (EEG) Amplifier System Market Size, Share, and Industry Trends Forecast 2026-2036
Electroencephalography (EEG) Amplifier System Market Insights
Multi-source procurement among tier-one hospitals is consolidating around vendors with validated supply chains and regulatory track records. Nihon Kohden Corporation anchors its position through deep vertical integration in analog front-end manufacturing. Cadwell Industries, Inc. differentiates via specialized software-based amplifier platforms for intraoperative monitoring. Brain Products GmbH competes in the research segment with modular architectures that support dense-array configurations.
An electroencephalography amplifier system is an electronic instrument that detects, filters, and amplifies microvolt-level brain electrical signals, typically achieving input-referred noise below 0.5 µV RMS and common-mode rejection exceeding 100 dB to enable accurate neural recording. Its primary purpose is to translate cortical electrical activity into digitized waveforms for clinical diagnosis of epilepsy, sleep disorders, and traumatic brain injury, as well as for neuroscientific research. Wireless and portable product types are capturing expanded share as ambulatory monitoring protocols migrate beyond hospital walls, while software-based technology is displacing legacy analog architectures in research settings where real-time signal processing and cloud integration command premium positioning. The brain-machine interface application remains nascent but draws disproportionate R&D investment from defense and consumer neurotechnology funders.
FDA 510(k) clearance and EU MDR conformity assessment govern commercial access in the United States and Europe, respectively, with both frameworks demanding rigorous electromagnetic compatibility and patient electrical safety validation. Japan's PMDA and China's NMPA impose additional clinical evidence requirements that extend registration timelines for foreign manufacturers. Stakeholders must monitor evolving harmonization between IEC 60601-1 third edition amendments and emerging cybersecurity standards for networked neurophysiology equipment.
Market Dynamics
Wireless amplifier architectures are compressing the traditional hospital-centric deployment model for EEG systems, enabling ambulatory monitoring protocols that extend neural recording beyond clinical walls into home and mobile environments.
Growth Catalysts
- FDA 510(k) clearance streamlining:The FDA's premarket notification pathway for Class II medical devices accelerates commercial entry for wireless EEG amplifiers, reducing time-to-market for manufacturers with established electromagnetic compatibility validation.
- Epilepsy center expansion:Academic medical centers in Germany, Japan, and the United States are procuring dense-array systems for surgical planning, creating concentrated demand for high-channel-count amplifier platforms.
- Cloud-native signal processing:Real-time telemetry and remote diagnostic capabilities embedded in software-based architectures enable continuous monitoring revenue models that hardware-centric systems cannot match.
Market Restraints
- Analog front-end component concentration:Specialized low-noise operational amplifiers and precision resistors concentrate supply among Japanese and German component manufacturers, exposing OEMs to allocation risk.
- EU MDR clinical evidence requirements:The European Union's Medical Device Regulation demands expanded clinical validation for active implantable accessories, extending conformity assessment timelines for wireless amplifier systems.
- Substitute neural monitoring modalities:Magnetoencephalography and functional near-infrared spectroscopy capture research funding that might otherwise flow to high-density EEG amplifier development.
Strategic Opportunities
- Brain-machine interface defense contracts:DARPA and allied defense research agencies in the United States and United Kingdom are funding non-invasive neural control systems, creating premium procurement channels for ruggedized wireless amplifiers.
- Home sleep monitoring deregulation:Japan's PMDA pathway simplification for home-use polysomnography equipment enables direct-to-consumer distribution models previously restricted to clinical settings.
- AI-integrated diagnostic workflows:Convergence between edge-computing amplifiers and FDA-cleared seizure detection algorithms creates integrated platform opportunities that command pricing premiums over standalone hardware.
Industry Challenges
- Biomedical signal processing expertise scarcity:The intersection of analog circuit design, neurophysiology, and embedded systems engineering concentrates qualified personnel among a handful of university programs and incumbent manufacturers.
- Legacy EMR integration complexity:Hospital information systems from dominant health IT vendors require proprietary interfacing modules that extend deployment timelines and inflate professional services costs for amplifier installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electroencephalography (EEG) Amplifier System Market |
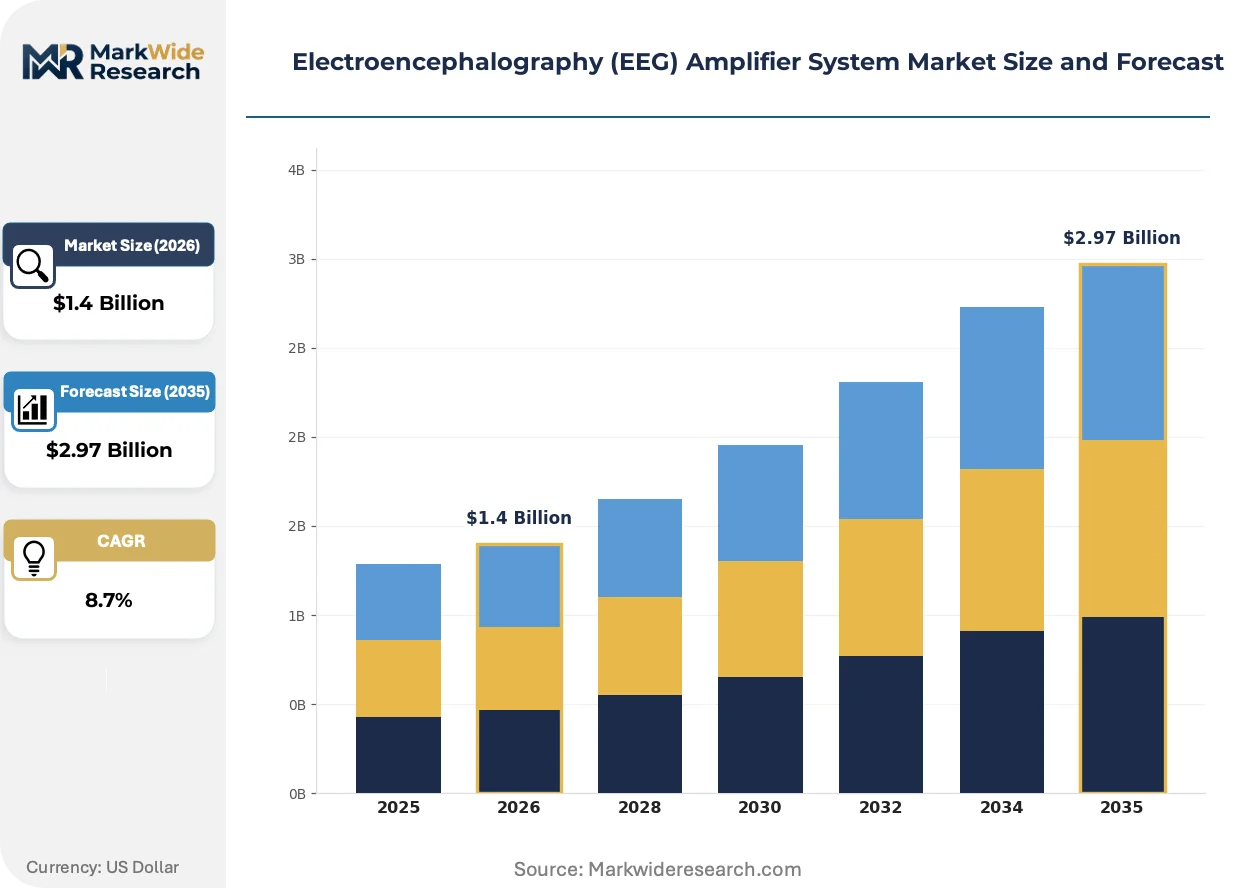
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wireless, Modular, Stationary Technology: Analog, Digital, Hybrid, Software-Based End User: Research Institutes, Hospitals, Clinics, Laboratories Application: Sleep Studies, Neurological Disorders, Cognitive Research, Brain-Machine Interface |
| Companies Covered | Natus Medical, Inc., Nihon Kohden Corporation, Cadwell Industries, Inc., Compumedics Limited, NeuroWave Systems Inc., Medtronic, Elekta AB, EB Neuro S.p.A., Brain Products GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electroencephalography (EEG) Amplifier System Market Trends and Innovations
Dry-electrode and capacitive coupling technologies are eliminating conductive gel dependencies, while regulatory frameworks coalesce around cybersecurity mandates for networked neurophysiology equipment.
Active dry-electrode arrays with integrated impedance buffering are rewriting the economics of high-density EEG deployment. Research institutions and clinical trial operators are adopting these systems for longitudinal studies where gel application disrupts protocol adherence. The technology is compressing per-session preparation time from thirty minutes to under five, enabling study designs with frequent repeated measurements that gel-based systems cannot support.
The EU MDR's Annex I requirements for electromagnetic compatibility and software lifecycle processes are tightening conformity assessment scope for networked amplifier systems. Manufacturers must now demonstrate systematic cybersecurity risk management across the entire signal chain, from electrode to cloud storage. European notified bodies are prioritizing assessment resources toward active devices with wireless connectivity, creating queue advantages for manufacturers with pre-validated quality management systems.
Subscription-based access models for amplifier hardware and analysis software are displacing capital purchase arrangements in academic research settings. Core facilities at major universities are unbundling equipment ownership from data processing services, shifting budget line items from grant-funded equipment to operational expenditures. This reconfiguration is most visible in the United States, where NIH funding mechanisms increasingly favor shared instrumentation grants over individual laboratory acquisitions.
Electroencephalography (EEG) Amplifier System Market Segmentation
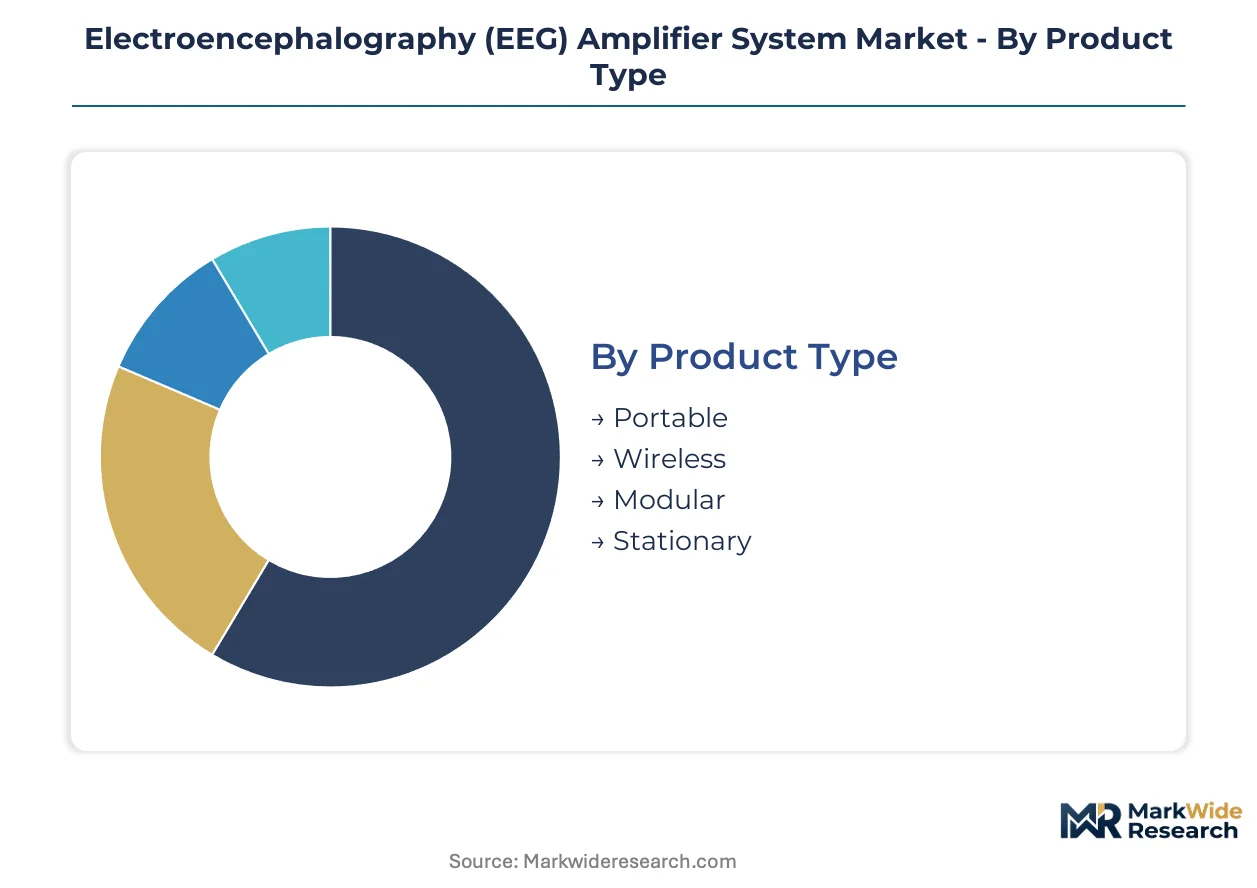
Segmentation in the EEG amplifier market reflects divergent technical requirements between clinical diagnostics and neuroscientific research. Procurement patterns split sharply between institutions demanding validated, regulatory-cleared systems and research operators prioritizing configurability over certification.
Product Type:
Standalone amplifier units dominate hospital procurement, while embedded modules integrate into multi-modal monitoring platforms for surgical suites.
- Portable:Battery-powered units with 16-32 channel configurations enable bedside screening in emergency departments and intensive care settings. Demand concentrates in academic medical centers across Germany and the United States where rapid deployment for seizure monitoring commands premium pricing.
- Wireless:Bluetooth and proprietary radio-frequency architectures eliminate tethering constraints for ambulatory epilepsy monitoring. Japan's PMDA pathway simplification for home-use equipment accelerates adoption beyond traditional clinical boundaries.
- Modular:Expandable chassis systems support 64-256 channel configurations through stackable amplifier blocks. Research institutes at Max Planck Society facilities and MIT deploy these for dense-array cognitive studies.
- Stationary:Rack-mounted systems with isolated power supplies serve dedicated EEG suites requiring maximum channel density and signal integrity.
Stationary systems lead volumes today; wireless configurations are gaining share fastest.
Technology:
Cost tiers separate legacy analog architectures from digitally-native platforms commanding research premiums.
- Analog:Discrete transistor front-ends with hardware filtering remain prevalent in price-sensitive clinical installations. Hospitals in India and Brazil specify these for routine epilepsy diagnostics where electromagnetic environments permit simpler shielding.
- Digital:Oversampling converters with FPGA-based real-time processing enable software-defined bandwidth selection. Sleep medicine clinics in the United States adopt these for polysomnography workflows requiring flexible filter configurations.
- Hybrid:Combined analog preamplification with digital back-end processing balances noise performance against computational flexibility. European neurology clinics favor these for intraoperative monitoring where latency constraints prohibit pure software architectures.
- Software-Based:Direct digitization at the electrode with cloud-native signal processing commands highest research pricing. DARPA-funded brain-machine interface programs specify these for neural decoding applications.
Hybrid platforms dominate current procurement; software-based architectures show the steepest expansion trajectory.
End User:
Customer type determines certification requirements, with clinical operators demanding FDA 510(k) or EU MDR clearance and research buyers accepting CE-IVD or self-certified laboratory equipment.
- Research Institutes:Universities and dedicated neuroscience centers prioritize channel density and open-source software compatibility over regulatory validation. The Allen Institute and similar facilities drive demand for 256+ channel systems with programmable gain stages.
- Hospitals:Tertiary care centers require integrated EMR connectivity and validated seizure detection algorithms. Germany's university hospitals anchor European demand for high-end surgical planning systems.
- Clinics:Outpatient neurology practices specify 16-32 channel systems for routine diagnostic workups. Independent epilepsy centers in the United States represent concentrated procurement for ambulatory monitoring services.
- Laboratories:Pharmaceutical and contract research organizations deploy preclinical systems for compound safety screening in toxicology studies.
Hospitals lead volumes today; research institutes are expanding procurement most rapidly.
Application:
Application maturity spans decades-established sleep medicine to emergent brain-machine interface development with divergent regulatory pathways.
- Sleep Studies:Polysomnography amplifiers integrate respiratory and cardiac channels alongside EEG for comprehensive sleep disorder diagnosis. Home sleep testing deregulation in Japan creates new distribution channels beyond hospital-based sleep centers.
- Neurological Disorders:Epilepsy monitoring units require prolonged recording capability with video synchronization. Level 3 and 4 epilepsy centers in the United States specify these for pre-surgical evaluation protocols.
- Cognitive Research:Event-related potential systems with millisecond-precision triggering support psychology and linguistics experiments. European Research Council funding sustains demand at institutions like the Donders Institute.
- Brain-Machine Interface:High-channel-count systems with real-time decoding algorithms enable prosthetic control and neural feedback applications. Defense research agencies in the United States and United Kingdom fund development despite limited commercial deployment.
Neurological disorder diagnostics lead volumes today; brain-machine interface applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States, Germany, and Japan concentrate procurement of high-channel-count EEG amplifier systems for epilepsy surgical planning and neuroscientific research, with regulatory pathways in each jurisdiction shaping vendor market access timelines.
United States
Level 3 and 4 epilepsy centers at Johns Hopkins, Mayo Clinic, and Cleveland Clinic drive demand for dense-array systems exceeding 128 channels. FDA 510(k) clearance pathways for Class II medical devices accelerate commercial entry for wireless amplifier platforms with validated electromagnetic compatibility. Research institutes at MIT and Stanford anchor procurement of software-based architectures for brain-machine interface development funded by DARPA.
Germany
University hospitals in Berlin, Munich, and Heidelberg specify integrated systems for intraoperative monitoring and pre-surgical epilepsy evaluation. EU MDR conformity assessment requirements for active implantable accessories extend registration timelines for wireless amplifier systems. The Max Planck Society facilities and Donders Institute in the Netherlands sustain cross-border demand for modular research-grade platforms.
Japan
PMDA pathway simplification for home-use polysomnography equipment enables direct-to-consumer distribution models previously restricted to clinical settings. Academic medical centers at the University of Tokyo and Kyoto University anchor demand for high-end surgical planning systems. Osaka-based neurology clinics are expanding ambulatory monitoring services with portable 16-32 channel configurations.
United Kingdom
Defense research agencies fund non-invasive neural control systems, creating premium procurement channels for ruggedized wireless amplifiers. NHS England's specialized commissioning for epilepsy services concentrates high-end system procurement at Great Ormond Street Hospital and the National Hospital for Neurology and Neurosurgery. Research councils sustain demand at the MRC Cognition and Brain Sciences Unit in Cambridge.
China
NMPA clinical evidence requirements extend registration timelines for foreign manufacturers seeking market access. Tier-3 hospitals in Beijing, Shanghai, and Guangzhou are expanding neurology department capacity with 32-64 channel systems for routine diagnostic workups. Domestic manufacturers are capturing share in price-sensitive provincial markets with analog-front-end platforms.
Electroencephalography (EEG) Amplifier System Market Competitive Landscape
Global majors compete with regional champions across regulatory certification depth and research-grade customization capability. Market structure tilts toward consolidation among vendors with validated FDA and EU MDR track records, while specialized research operators occupy profitable niches. Three archetypes dominate: vertically integrated Japanese electronics conglomerates, German precision instrumentation specialists, and U.S.-based neurotechnology platform developers. Competitive moves center on strategic partnerships with academic medical centers and technology licensing for dry-electrode architectures.
Among Japanese-based manufacturers, Nihon Kohden Corporation exemplifies the vertically integrated archetype with captive analog front-end manufacturing. German specialists Brain Products GmbH and EB Neuro S.p.A. occupy positions within the research-grade modular segment, while U.S.-based Natus Medical, Inc. and Cadwell Industries, Inc. represent the clinical-validation-focused tier with established FDA clearance portfolios.
| Leading Market Players |
|---|
| Natus Medical, Inc. |
| Nihon Kohden Corporation |
| Cadwell Industries, Inc. |
| Compumedics Limited |
| NeuroWave Systems Inc. |
| Medtronic |
| Elekta AB |
| EB Neuro S.p.A. |
| Brain Products GmbH |
| Others |
Pricing and Supply Chain Analysis
Software-based amplifier architectures with cloud-native signal processing are compressing hardware margins while concentrating procurement power among vendors with validated FDA and EU MDR track records. This technological shift simultaneously elevates R&D amortization costs and rewards manufacturers with captive analog front-end production in Japan and Germany.
Pricing Analysis
Input-cost pass-through from specialized low-noise operational amplifiers and precision resistors concentrates pricing power among Japanese and German component manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared surgical planning systems from research-grade modular platforms and price-sensitive clinical installations in emerging markets. Cost compression in the standard tier is intensifying because domestic manufacturers in China are capturing provincial markets with analog-front-end alternatives. Research institutes exhibit the lowest price sensitivity due to grant-funded procurement, while outpatient neurology clinics in the United States face acute budget constraints for ambulatory monitoring equipment.
Supply Chain Analysis
Workforce availability for biomedical signal processing engineering concentrates manufacturing and R&D activities in Germany, Japan, and the United States. Supply chains draw from Japanese precision resistor foundries, German analog semiconductor fabricators, and Taiwanese FPGA suppliers. Single-source vulnerability in specialized low-noise operational amplifiers exposes OEMs to allocation risk during demand surges. Distribution runs through hospital purchasing committees and academic core facility managers, with GPO contracts dominating tertiary care procurement in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR conformity assessment timelines extend registration costs for foreign manufacturers while Japan's PMDA pathway simplification accelerates home-use equipment commercialization at lower regulatory burden.
For Market Incumbents: Deepen backward integration into analog front-end manufacturing to offset component allocation risk from Japanese suppliers. Fortify FDA 510(k) clearance portfolios against emerging software-based competitors by accelerating electromagnetic compatibility validation for wireless architectures. Prioritize hospital system partnerships that embed amplifiers into integrated EMR workflows, creating switching costs for replacement vendors. For New Entrants and Emerging Players: Capture the home sleep monitoring segment in Japan where PMDA deregulation enables direct-to-consumer distribution previously restricted to clinical settings. Exploit underpenetrated ambulatory epilepsy monitoring services at independent neurology clinics in the United States that lack capital for dense-array surgical planning systems. Lead with dry-electrode technology to compress per-session preparation time and differentiate from gel-dependent incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among research-grade modular specialists with dense-array capabilities but limited clinical certification depth. Long-term viability hinges on convergence toward AI-integrated diagnostic workflows that command pricing premiums over standalone hardware. Monitor FDA clearance velocity for seizure detection algorithms as the inflection indicator for platform-level consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Reduces time-to-market for wireless amplifiers with validated electromagnetic compatibility at Johns Hopkins and Mayo Clinic procurement channels. |
| EU MDR Conformity Assessment Investment | Extends market access timelines but creates queue advantages for manufacturers with pre-validated quality management systems in Germany. |
| Hospital System Partnership Development | Embeds amplifiers into Epic and Cerner EMR workflows, inflating professional services costs for competitor replacement at U.S. tertiary centers. |
| Dry-Electrode Technology Licensing | Rewrites economics of high-density EEG deployment for longitudinal studies at Max Planck Society and MIT research facilities. |
| Cloud-Native Signal Processing Integration | Enables continuous monitoring revenue models that hardware-centric systems cannot match in sleep medicine clinics. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and China, with primary inputs from each market cluster. The research combines structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at amplifier manufacturers with secondary validation from FDA 510(k) filings, EU MDR notified body databases, PMDA approval records, and hospital procurement databases. Bottom-up channel checks triangulate against top-down macroeconomic and healthcare expenditure models.
Granularity-level modeling operates at the intersection of product type, technology architecture, end-user institution, and application with regional regulatory cluster differentiation. The analytical framework projects volume and value outputs across the modeling period by segmenting standalone, portable, wireless, modular, and stationary configurations against analog, digital, hybrid, and software-based technology tiers. CAGRs derive from weighted average of historical procurement patterns and forward-looking adoption curves for ambulatory monitoring and brain-machine interface applications.
Regulatory pathway delays, component allocation disruptions, and substitute neural monitoring modality funding shifts are the dominant revision risks to forecast assumptions. Material deviation in FDA clearance velocity, EU MDR notified body queue depth, or DARPA brain-machine interface contract awards warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Organ Preservation Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
Global Smart Biopsy Devices Market
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
Balloon Valvuloplasty Device Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Syringeless Injector Market
Medical Devices
Depression Devices Market
Medical Devices
Global Electroceuticals Market
Medical Devices
Powered Mattress System Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
Skull Deformity Implants Market
Medical Devices
Global Micro Guide Catheters Market