
 Wearable Bioelectronic Skin Patches Market | 2026-2036
Wearable Bioelectronic Skin Patches Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Bioelectronic Skin Patches Market Analytics
Post-surgery monitoring is recalibrating the addressable opportunity for wearable bioelectronic skin patches as hospitals seek ambulatory alternatives to inpatient recovery. Medtronic plc anchors this shift through its established cardiac monitoring infrastructure and hospital channel relationships. Dexcom Inc. dominates continuous glucose monitoring with proprietary biosensor architectures that sustain premium positioning among diabetes patients and endocrinology practices.
Wearable bioelectronic skin patches constitute ultrathin, flexible substrates integrating biosensors, microfluidic channels, and wireless transceivers for transdermal physiological signal acquisition and therapeutic delivery. These devices typically incorporate biocompatible polymers such as polyimide or polydimethylsiloxane with conductive traces of silver nanowires or graphene, fabricated through roll-to-roll processing or microelectromechanical systems lithography to achieve conformal skin contact and sustained wearability over 7–14 days. Monitoring patches command the largest current revenue pool due to established reimbursement for cardiac arrhythmia detection and diabetes management, while smart patches represent the fastest-expanding category as artificial intelligence-enabled edge analytics compress diagnostic latency and enable predictive intervention workflows. Therapeutic patches leveraging electrical stimulation compete in pain management and neuromodulation segments where regulatory pathways remain more fragmented.
FDA breakthrough device designation and ISO 13485 quality management standards shape product development timelines and market access thresholds for patch manufacturers seeking US commercialization. The EU Medical Device Regulation and CE marking requirements impose additional clinical evidence burdens on biosensor patch developers targeting European healthcare systems. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic algorithms and anticipate how pre-certification frameworks for software components may reshape competitive entry barriers.
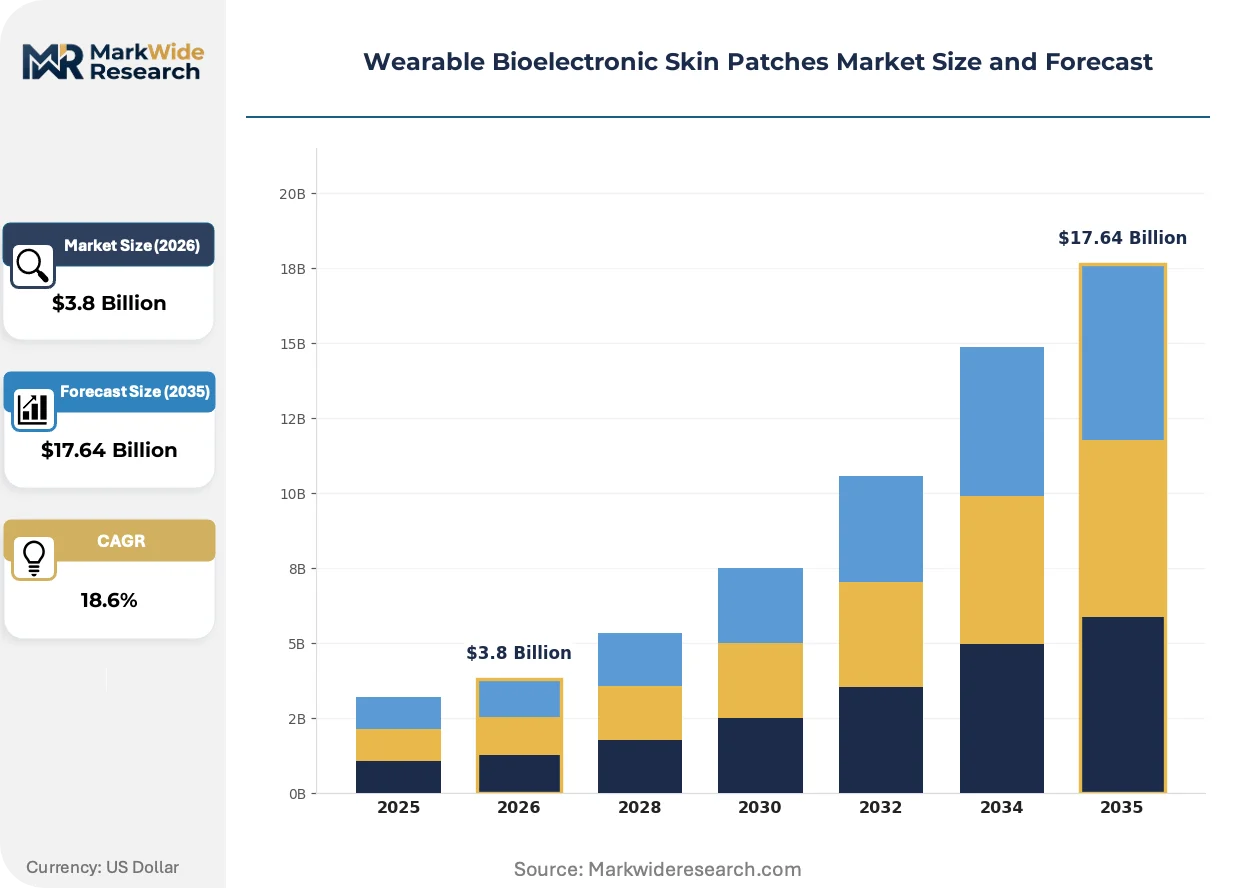
Market Dynamics
The convergence of artificial intelligence-enabled edge analytics with conformal biosensor substrates is compressing diagnostic latency from days to hours, fundamentally altering how healthcare systems allocate monitoring capacity across inpatient and ambulatory settings.
Growth Catalysts
- Medicare reimbursement expansion:Remote patient monitoring codes in the United States now cover continuous cardiac and glucose surveillance, accelerating hospital procurement cycles for patch-based alternatives to telemetry beds.
- FDA breakthrough device designation:This pathway compresses premarket review timelines for novel biosensor patches targeting unmet clinical needs in arrhythmia detection and post-surgical recovery monitoring.
- Silver nanowire-graphene hybrid conductors:These materials enable stretchable circuitry maintaining signal fidelity through 30% skin deformation, unlocking 14-day wear durations for chronic disease management applications.
Market Restraints
- Biocompatible polymer supply concentration:Polydimethylsiloxane precursor manufacturing clusters in Germany and Japan create vulnerability to petrochemical feedstock volatility and logistics disruptions.
- EU Medical Device Regulation clinical evidence burdens:MDR requirements for post-market surveillance and notified body recertification extend European commercialization timelines by 18-24 months relative to FDA pathways.
- Adhesive dermatitis incidence:Extended wear protocols confront skin irritation rates of 15-20% in melanin-rich populations, limiting addressable demographics for 7-day continuous monitoring patches.
Strategic Opportunities
- Post-acute care transition protocols:United States hospital systems seeking to reduce readmission penalties are embedding patch-based monitoring into discharge workflows for cardiac and orthopedic surgery patients.
- Neuromodulation therapeutic patches:Electrical stimulation devices for migraine and chronic pain target pharmacy benefit managers with drug-sparing value propositions outside established device reimbursement frameworks.
- ISO 13485 pre-certification frameworks:Anticipated FDA guidance on software-as-medical-device quality management systems will advantage developers with integrated hardware-software validation capabilities.
Industry Challenges
- Microelectromechanical systems lithography talent scarcity:Roll-to-roll fabrication engineers with biocompatible substrate experience command 40% wage premiums, constraining manufacturing scale-up for mid-tier developers.
- Wireless transceiver integration complexity:Bluetooth Low Energy and emerging ultra-wideband protocols demand RF engineering capabilities rarely co-located with biosensor chemistry expertise in incumbent device firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Bioelectronic Skin Patches Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Patches, Diagnostic Patches, Monitoring Patches, Smart Patches Application: Chronic Disease Management, Fitness Tracking, Post-Surgery Monitoring, Real-Time Health Monitoring Technology: Electrical Stimulation, Biosensors, Wireless Communication, Microfluidics End User: Healthcare Providers, Fitness Enthusiasts, Research Institutions, Home Users |
| Companies Covered | 3M, Koninklijke Philips, GE Healthcare, MC10, iRhythm Technologies, Inc., Insulet Corporation, Epicore Biosystems, Inc., Medtronic plc, Dexcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Bioelectronic Skin Patches Market Evolving Landscape
Artificial intelligence inference at the patch edge is eliminating cloud-dependent latency, enabling real-time arrhythmia classification and predictive hypoglycemia alerts that shift clinical workflow from reactive to preemptive intervention models.
Graphene-silver nanowire composite electrodes are consolidating electrochemical and impedance sensing modalities onto single conformal substrates, replacing discrete sensor arrays with unified architectures. Cardiology departments in United States academic medical centers are piloting these unified patches for simultaneous ECG-electrolyte monitoring, compressing device procurement from multiple vendors to single-source contracts. This consolidation is eroding the historical separation between cardiac monitoring and metabolic surveillance business lines.
The FDA's evolving guidance on predetermined change control plans for machine learning-enabled devices is creating regulatory infrastructure for algorithm updates without full premarket resubmission. Patch developers can now deploy predictive model improvements through software versioning protocols rather than hardware recalls. Diabetes management platforms with continuous glucose monitoring integration are the earliest adopters, leveraging this pathway to compress glucose prediction algorithm iteration cycles from quarters to weeks.
Hospital procurement committees are unbundling device acquisition from data analytics subscriptions, forcing patch manufacturers to price hardware and software components separately. This disintermediation of bundled offerings pressures margin structures previously protected by multi-year platform lock-in contracts. Cardiac monitoring patch vendors face the most acute margin compression in United States integrated delivery networks, where procurement officers now benchmark hardware costs against Asian contract manufacturers while negotiating analytics fees with specialized software vendors.
Wearable Bioelectronic Skin Patches Market Segmentation
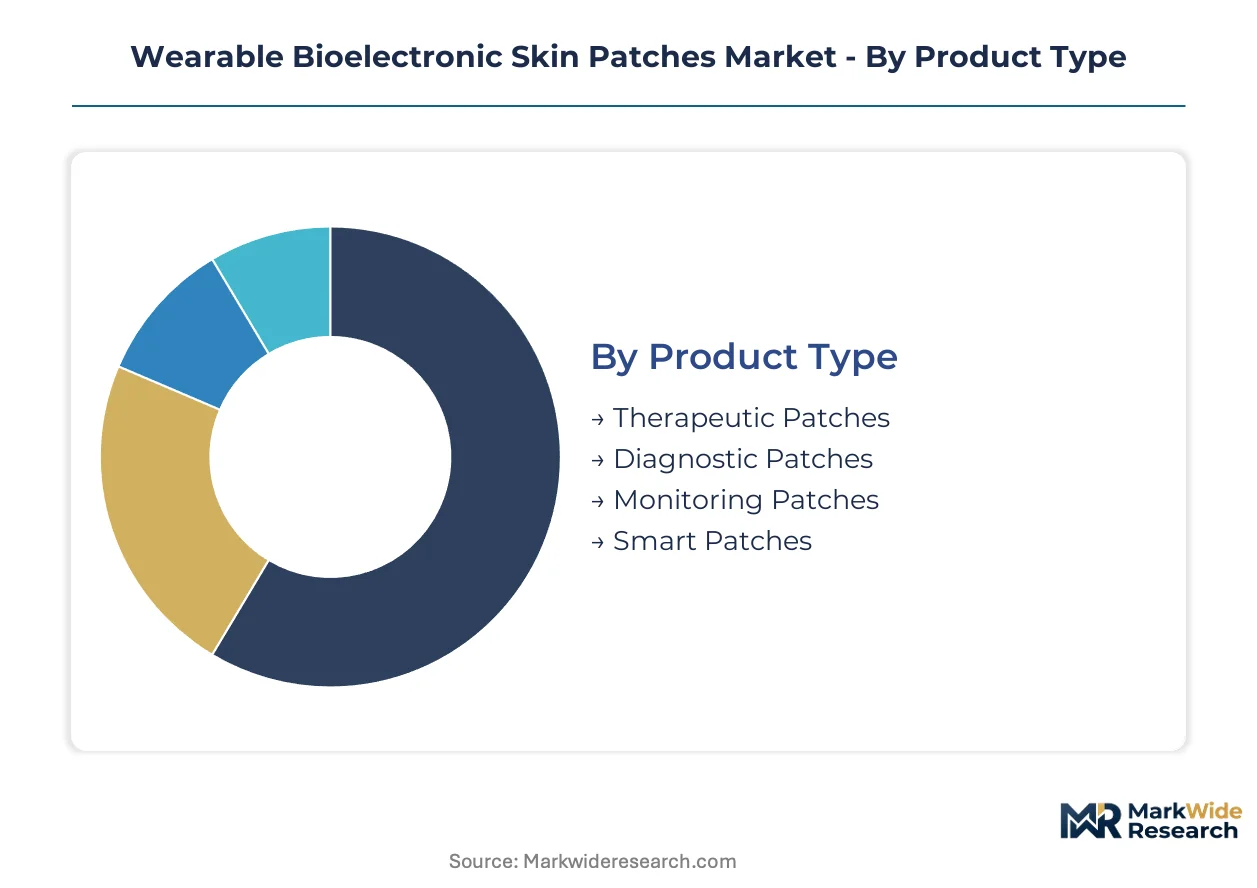
Wearable bioelectronic skin patches fragment across four orthogonal dimensions that determine pricing architecture, regulatory pathway, and channel strategy. Product type and application segments exhibit the strongest divergence in margin structure and reimbursement eligibility.
Product Type:
Volume concentration clusters in established monitoring formats, while premium capture shifts toward AI-integrated smart patches with predictive analytics subscriptions.
- Monitoring Patches:These devices integrate polyimide substrates with silver nanowire conductive traces for continuous cardiac and glucose surveillance. United States hospital systems drive procurement through Medicare reimbursement codes for remote patient monitoring, with 14-day wear protocols now standard for ambulatory arrhythmia detection.
- Smart Patches:Edge-deployed machine learning algorithms enable real-time classification of physiological signals without cloud latency. Academic medical centers in the United States pilot these for predictive hypoglycemia alerts and post-surgical complication detection, compressing diagnostic workflows from reactive to preemptive models.
- Therapeutic Patches:Electrical stimulation devices target migraine and chronic pain through transdermal neuromodulation.
- Diagnostic Patches:Single-use biosensor formats deliver point-of-care electrolyte and metabolite quantification.
Mature deployment sits with monitoring patches. Newer deployment is concentrated in smart patches.
Application:
Reimbursement eligibility separates clinical applications from consumer wellness, with chronic disease management commanding hardware premiums and data analytics subscriptions.
- Chronic Disease Management:Diabetes and cardiovascular conditions sustain the largest addressable patient populations. United States endocrinology practices and cardiology departments procure continuous glucose and cardiac monitoring patches through established durable medical equipment channels, with Medicare coverage eliminating out-of-pocket barriers for Medicare Advantage enrollees.
- Post-Surgery Monitoring:Hospital discharge protocols embed patch-based surveillance to reduce readmission penalties under CMS quality programs. United States integrated delivery networks negotiate enterprise contracts covering cardiac and orthopedic surgery cohorts, replacing telemetry bed days with ambulatory recovery pathways.
- Real-Time Health Monitoring:Acute care settings deploy these for rapid physiological assessment.
- Fitness Tracking:Consumer wellness applications lack reimbursement and compete on hardware cost alone.
Established volume flows through chronic disease management. Post-surgery monitoring is expanding most quickly as hospitals recalibrate inpatient capacity.
Technology:
Material science differentiation determines signal fidelity, wear duration, and manufacturing yield.
- Biosensors:Electrochemical and impedance sensing modalities leverage graphene-silver nanowire composites for unified substrate architectures. United States academic medical centers consolidate procurement around these multi-analyte formats, replacing discrete sensor arrays from multiple vendors with single-source contracts for simultaneous ECG-electrolyte monitoring.
- Wireless Communication:Bluetooth Low Energy dominates current deployments, though ultra-wideband protocols are emerging for spatial positioning applications in post-surgical recovery tracking.
- Microfluidics:Sweat and interstitial fluid sampling channels enable non-invasive metabolite quantification.
- Electrical Stimulation:Therapeutic delivery through conformal electrodes targets pain management segments outside established device reimbursement frameworks.
Production maturity centers on biosensor integration. Wireless communication protocols are gaining share fastest as latency requirements tighten for predictive intervention workflows.
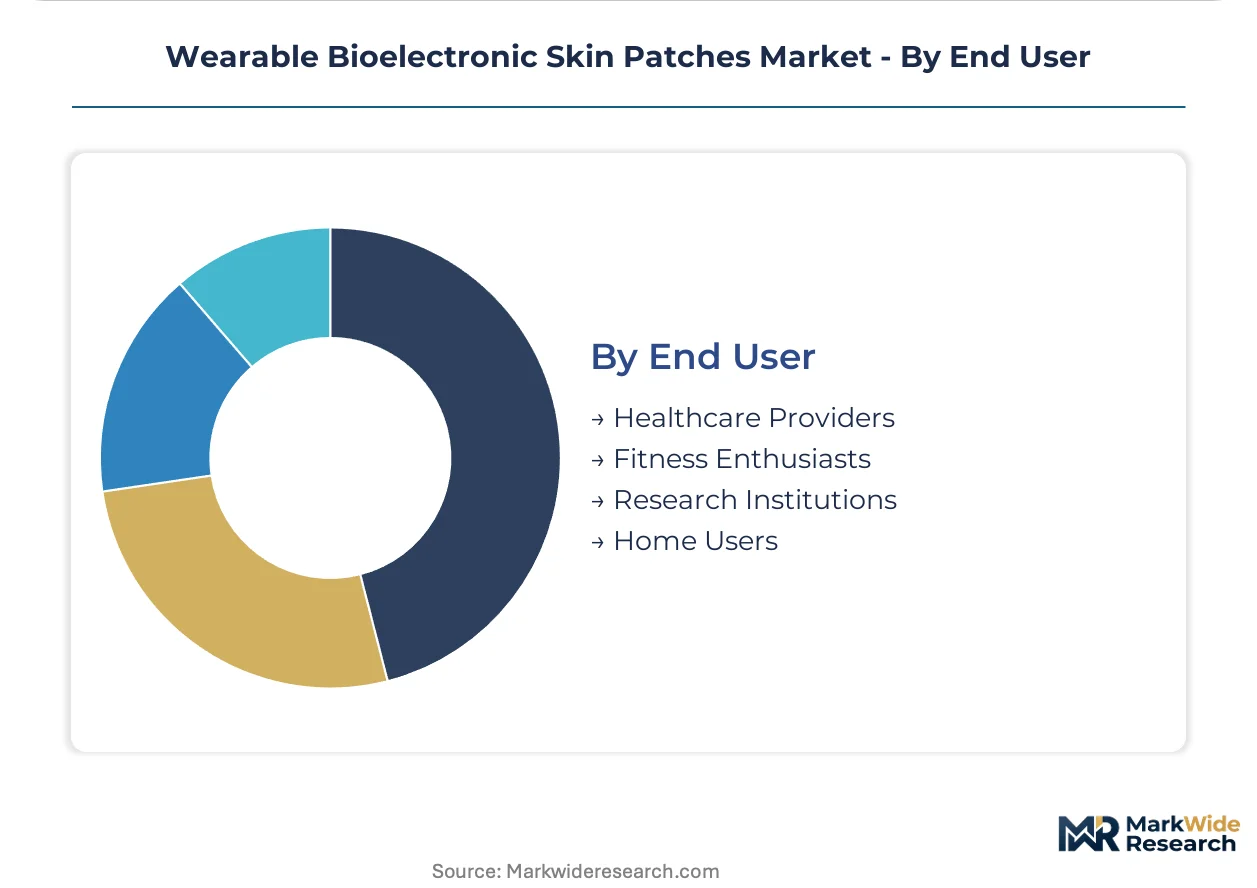
End User:
Procurement authority and reimbursement access create divergent pricing tolerances across user categories.
- Healthcare Providers:Hospitals and physician practices negotiate enterprise pricing for cardiac and glucose monitoring patches. United States integrated delivery networks unbundle hardware from analytics subscriptions, benchmarking device costs against Asian contract manufacturers while separately negotiating software fees with specialized vendors.
- Home Users:Diabetes patients drive direct-to-consumer purchases where insurance coverage gaps exist, particularly in high-deductible health plans.
- Research Institutions:Clinical trial sponsors procure custom patch configurations for decentralized study protocols.
- Fitness Enthusiasts:Price-sensitive consumers prioritize hardware cost over clinical-grade accuracy.
Revenue concentration rests with healthcare providers. Home user deployment is climbing the fastest as Medicare reimbursement expands remote patient monitoring eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Suzhou concentrate roll-to-roll fabrication capacity for biocompatible polymers and stretchable conductors. These zones attract medical device multinationals seeking proximity to graphene precursor suppliers and MEMS lithography foundries. Tax incentives for high-value manufacturing anchor regional production gravity.
United States
Medicare reimbursement expansion for remote patient monitoring codes drives hospital procurement of cardiac and glucose surveillance patches. FDA breakthrough device designation compresses premarket review timelines for novel biosensor formats targeting unmet arrhythmia detection needs. Greater Boston and San Diego host dense clusters of patch developers leveraging proximity to academic medical centers for clinical validation partnerships.
Germany
Polydimethylsiloxane precursor manufacturing clusters in the Rhine-Ruhr region supply biocompatible substrates to European device makers. EU Medical Device Regulation clinical evidence requirements extend commercialization timelines but create quality barriers protecting incumbent positions. Baden-Württemberg's precision engineering ecosystem supports MEMS lithography talent pools for microfluidic channel fabrication.
China
NMPA streamlined review pathways for innovative medical devices accelerate domestic patch developer market access. Yangtze River Delta integration zones combine graphene nanowire production with roll-to-roll processing infrastructure for cost-competitive substrate manufacturing. Shanghai and Suzhou medical device parks host joint ventures between local fabricators and multinational biosensor technology licensors.
Japan
PMDA Sakigake designation system provides prioritized consultation for breakthrough wearable diagnostics targeting aging population chronic disease management. METI funding for flexible electronics commercialization supports domestic development of 14-day wear duration patches. Kansai region chemical manufacturers supply high-purity polymer precursors to device makers across East Asian supply chains.
South Korea
MFDS fast-track approval for software-enabled medical devices accommodates AI-integrated patch formats with edge analytics capabilities. Seoul Capital Area semiconductor foundries offer MEMS lithography services previously concentrated in Japanese and German facilities. Government-backed bio-health clusters in Daejeon-Sejong region bridge biosensor chemistry expertise with wireless communication engineering talent.
Wearable Bioelectronic Skin Patches Market Competitive Landscape
Top-tier vendors anchor hospital procurement channels and Medicare reimbursement pathways, while mid-tier specialists compete on materials innovation and manufacturing scale. The vendor base stratifies across integrated device conglomerates with cardiac monitoring infrastructure, pure-play biosensor developers with proprietary substrate architectures, and contract manufacturers serving white-label patch programs. Two dominant competitive moves define positioning: backward integration into biocompatible polymer precursor production to secure supply continuity, and strategic partnerships with AI software vendors to embed predictive analytics at the patch edge.
Among diversified medical technology conglomerates, 3M, Koninklijke Philips, and GE Healthcare occupy positions spanning materials science through hospital system distribution. These entities exemplify integrated archetypes controlling multiple value chain nodes from conductive substrate fabrication to enterprise procurement relationships. Their scale advantages concentrate in United States integrated delivery network contracting and European hospital group purchasing organization negotiations, where bundled hardware-analytics offerings historically protected margin structures now facing unbundling pressure.
| Leading Market Players |
|---|
| 3M |
| Koninklijke Philips |
| GE Healthcare |
| MC10 |
| iRhythm Technologies, Inc. |
| Insulet Corporation |
| Epicore Biosystems, Inc. |
| Medtronic plc |
| Dexcom Inc. |
| Others |
Value Network & Pricing Analysis
Roll-to-roll fabrication of graphene-silver nanowire composites is consolidating manufacturing economics around 14-day wear-duration substrates while concentrating production capacity in East Asian Special Economic Zones. This process transition simultaneously compresses unit costs for biosensor patches and creates supply dependencies on petrochemical feedstock corridors linking German polydimethylsiloxane precursor clusters to Chinese roll-to-roll foundries.
Pricing Analysis
Short lead-time premiums of 15-25% apply to FDA breakthrough-designated patches where hospital procurement committees face readmission penalty deadlines, while spot inventory discounts emerge for standard cardiac monitoring formats with 90-day replenishment cycles. Three-tier pricing structure across premium AI-integrated smart patches, standard glucose monitoring formats, and economy wellness trackers reflects certification-grade differentiation and analytics bundling. Cost compression in the standard tier is intensifying because procurement officers benchmark hardware against Asian contract manufacturers. Home users in high-deductible health plans exhibit highest price sensitivity; academic medical centers with enterprise contracts show lowest.
Supply Chain Analysis
Domestic-content mandates in China's NMPA streamlined review pathways are reshaping sourcing toward Yangtze River Delta integration zones, displacing historical reliance on German and Japanese polymer precursor imports. Manufacturing concentrates in China, Germany, and Japan for biocompatible substrates, with South Korean MEMS lithography foundries gaining share for microfluidic channel fabrication. Raw material dependencies center on graphene nanowires, polydimethylsiloxane precursors, and silver nanowire conductive traces. Single-source vulnerability sits with Rhine-Ruhr polydimethylsiloxane clusters exposed to petrochemical volatility. Distribution runs through hospital group purchasing organizations in the United States and integrated delivery network procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over biocompatible polymer precursor production and AI software validation capabilities determines margin defense. Players are pursuing backward integration into graphene-silver nanowire composite manufacturing to secure 14-day wear-duration substrate supply.
For Market Incumbents: Hedge against unbundling pressure by captive production of biosensor substrates and acquisition of edge-analytics software vendors. Medtronic plc and Dexcom Inc. face procurement committee demands to separate hardware from analytics pricing. Channel control through exclusive hospital system partnerships remains the critical defensive lever. For New Entrants and Emerging Players: Begin with post-surgical monitoring white space where CMS readmission penalties create urgent demand and reimbursement pathways are expanding fastest. Neuromodulation therapeutic patches for migraine management offer pharmacy benefit manager entry angles outside established device reimbursement frameworks. Direct contracting with United States integrated delivery networks bypasses incumbent GPO lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified medical technology conglomerates seeking AI-enabled patch platforms. Long-term viability hinges on FDA pre-certification for software-as-medical-device quality management systems. Acquisition target archetype: mid-tier developers with ISO 13485 certification and graphene-silver nanowire substrate IP. The signal to watch is FDA guidance on predetermined change control plans for machine learning-enabled devices.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compresses premarket review timelines for novel arrhythmia detection patches targeting unmet clinical needs. |
| CE Marking Pathway under EU MDR | Extends European commercialization timelines but creates quality barriers protecting incumbent positions. |
| Hospital System Partnership | Locks in enterprise procurement for cardiac and orthopedic surgery discharge monitoring protocols. |
| Software Companion Development | Enables real-time edge analytics for predictive hypoglycemia alerts without cloud latency. |
| Reimbursement Strategy | Secures Medicare remote patient monitoring codes eliminating out-of-pocket barriers for enrollees. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, Medicare reimbursement code expansions, and hospital procurement contract values anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at patch developers. Secondary validation drew from FDA filings, CMS Medicare data, hospital procurement databases, and ISO 13485 certification records. Bottom-up patch shipment estimates triangulated against top-down chronic disease prevalence models.
Input-output matrices mapped biosensor substrate production volumes to end-use demand across chronic disease management, post-surgical monitoring, and wellness applications over the projection horizon. Segmentation dimensions modeled include product type, application, technology, and end user with geographic regulatory cluster overlays. CAGRs were derived from logistic diffusion curves fitted to reimbursement expansion trajectories and hospital adoption rates. Forecast inputs incorporated Medicare remote patient monitoring code utilization trends and FDA breakthrough device designation approval velocities.
Regulatory guidance shifts, adhesive dermatitis incidence variability across patient populations, and biocompatible polymer supply disruptions are the dominant revision risks to shipment and value forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Ligament Augmentation Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Digital Slit Lamp Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Hip Kits Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Sinus Implants Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Smart Bassinet Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market