
 US Magnetic Resonance Angiography Market | 2026-2036
US Magnetic Resonance Angiography Market Size, Share, and Industry Trends Forecast 2026-2036
US Magnetic Resonance Angiography Market Intelligence
ACR MRI accreditation is unwinding the competitive landscape, filtering out imaging centers lacking sufficient case volumes or technologist training. GE Healthcare sustains formidable installed-base leverage through its predictive service contracts and helium conservation systems. Siemens Healthineers differentiates via its compressed sensing acceleration protocols that slash neurovascular scan times. Philips Healthcare anchors its position through integrated cardiovascular informatics that pipe MRA data directly into cath lab planning workflows.
Magnetic resonance angiography employs non-contrast and gadolinium-enhanced pulse sequences to visualize arterial and venous structures without ionizing radiation, typically operating at 1.5 tesla or 3 tesla field strengths with spatial resolution below one millimeter for vessel lumen assessment. Its primary purpose centers on detecting stenosis, aneurysms, and vascular malformations across cerebral, renal, and peripheral territories where catheter angiography carries procedural risk. High-field MRI systems command the dominant revenue share due to their superior signal-to-noise ratios and parallel imaging capabilities, though wide bore configurations are gaining traction among bariatric and claustrophobic patient populations. Neurovascular imaging generates the densest procedure volumes, while coronary artery evaluation represents the fastest-expanding application segment as free-breathing cardiac MRA protocols mature.
FDA 510(k) pathways and ACR technical standards govern scanner safety, image quality benchmarks, and contrast agent labeling, directly shaping capital procurement criteria for hospital radiology departments and outpatient imaging centers. CMS reimbursement coding under the physician fee schedule and hospital outpatient prospective payment system determines whether facilities can recover MRA procedure costs, influencing upgrade cycles and site-of-service decisions. Stakeholders must monitor how FDA guidance on artificial intelligence-enabled image reconstruction interacts with evolving ACR appropriateness criteria, as these will determine which platform investments retain clinical and economic viability.
Market Dynamics
Compressed sensing acceleration and AI-enabled image reconstruction are compressing scan times while elevating throughput expectations for hospital radiology departments. These technical advances are reshaping capital procurement criteria and service line economics across integrated delivery networks.
Growth Catalysts
- ACR Accreditation Mandates:The American College of Radiology's quality benchmarks are filtering out low-volume imaging centers, concentrating procedure flow toward accredited hospital systems with dedicated neurovascular and cardiovascular service lines.
- Helium Conservation Systems:Closed-cycle magnet cooling technologies are extending MRI platform lifecycles and reducing operational downtime, enabling facilities to defer replacement capital while maintaining imaging capacity.
- Integrated Cardiovascular Informatics:Direct data piping from MRA suites into cath lab planning workflows is eliminating manual transfer steps and accelerating interventional decision-making across Northeast and California hospital networks.
Market Restraints
- Gadolinium Supply Concentration:Contrast agent manufacturing concentrates among a handful of pharmaceutical suppliers, exposing imaging centers to price volatility and periodic shortage risk.
- High-Field Magnet Capital Intensity:3 tesla platforms require substantial infrastructure investment including shielded suites and cryogenic support systems, limiting deployment to well-capitalized health systems.
- Claustrophobia-Driven Procedure Loss:Traditional bore configurations exclude 10-15% of referred patients, forcing facilities to maintain dual-platform inventories or accept volume leakage.
Strategic Opportunities
- Wide-Bore Platform Expansion:70-centimeter bore configurations are penetrating bariatric and pediatric segments previously excluded from MRA protocols, opening procedure volume in Texas and Florida health systems.
- Free-Breathing Coronary MRA:Cardiac gating advances are displacing CT angiography for coronary evaluation in renal-impaired populations, creating a fastest-expanding application segment.
- AI-Enabled Reconstruction Pathways:FDA guidance on machine learning-based image enhancement is compressing 510(k) review timelines for algorithm-augmented sequences.
Industry Challenges
- MR Technologist Training Bottlenecks:Specialized certification for neurovascular and cardiac MRA protocols exceeds standard radiologic technology curricula, constraining scanner utilization rates.
- Legacy PACS Integration Friction:New acquisition platforms require middleware development to communicate with decade-old picture archiving systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Magnetic Resonance Angiography Market |
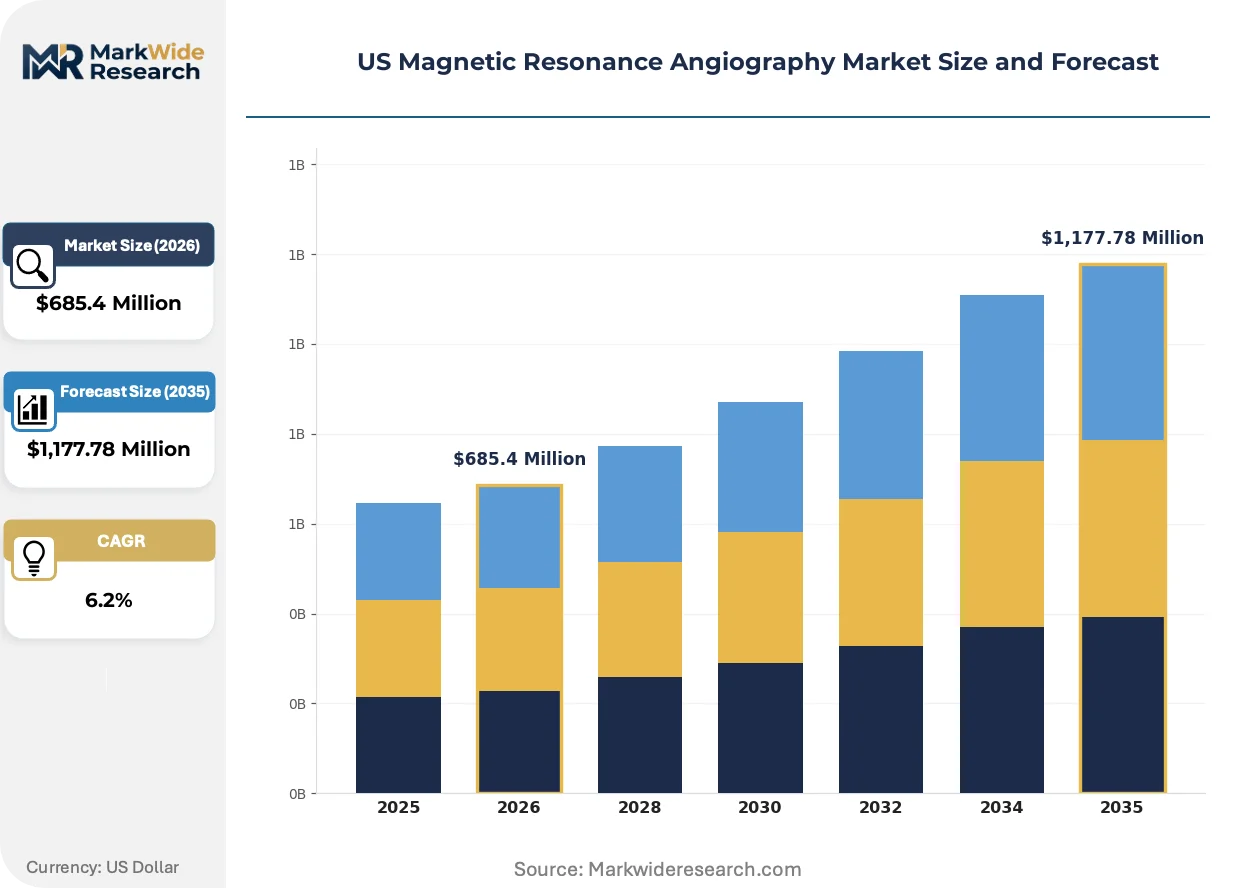
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI Systems, Open MRI Systems, Wide Bore MRI Systems, High-Field MRI Systems Application: Neurovascular Imaging, Peripheral Vascular Imaging, Coronary Artery Evaluation, Renal Artery Assessment End User: Diagnostic Centers, Ambulatory Surgical Centers, Specialized Clinics, Academic Research Institutes Deployment: Hospital-Based, Freestanding Imaging Centers, Mobile Imaging Units, Cardiac Care Facilities |
| Companies Covered | Canon Medical Systems, Hitachi Medical Corporation, GE Healthcare, Aurora Imaging Technology, Toshiba Corporation, Siemens Healthineers, Fujifilm Healthcare, United Imaging Healthcare, Philips Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Magnetic Resonance Angiography Market Strategic Shifts & Innovations
Non-contrast MRA sequences and accelerated acquisition protocols are displacing traditional gadolinium-enhanced workflows across cerebral and renal vascular imaging. These technical shifts are compressing examination durations while addressing contrast safety concerns in renal-impaired populations.
Compressed sensing reconstruction is fragmenting the traditional trade-off between spatial resolution and scan duration. Research institutes and academic medical centers are piloting these algorithms for neurovascular screening protocols, enabling sub-minute acquisitions that previously required ten-minute sequences. The technology is fragmenting service line economics by allowing hospitals to double daily scanner throughput without capital expansion.
FDA 510(k) review timelines for AI-enabled image reconstruction are compressing under new guidance documents issued for machine learning-based medical devices. The agency's streamlined pathway is accelerating commercial rollout for algorithm-augmented MRA sequences. Hospital procurement committees in California and Massachusetts are prioritizing platforms with cleared AI modules in current upgrade cycles.
After-sales service contracts are unbundling from equipment leases as health systems seek operational flexibility. Independent service organizations are capturing preventive maintenance volumes previously held by original equipment manufacturers. This disintermediation is most visible in the Northeast, where integrated delivery networks are consolidating vendor relationships across multi-site imaging footprints.
US Magnetic Resonance Angiography Market Segmentation
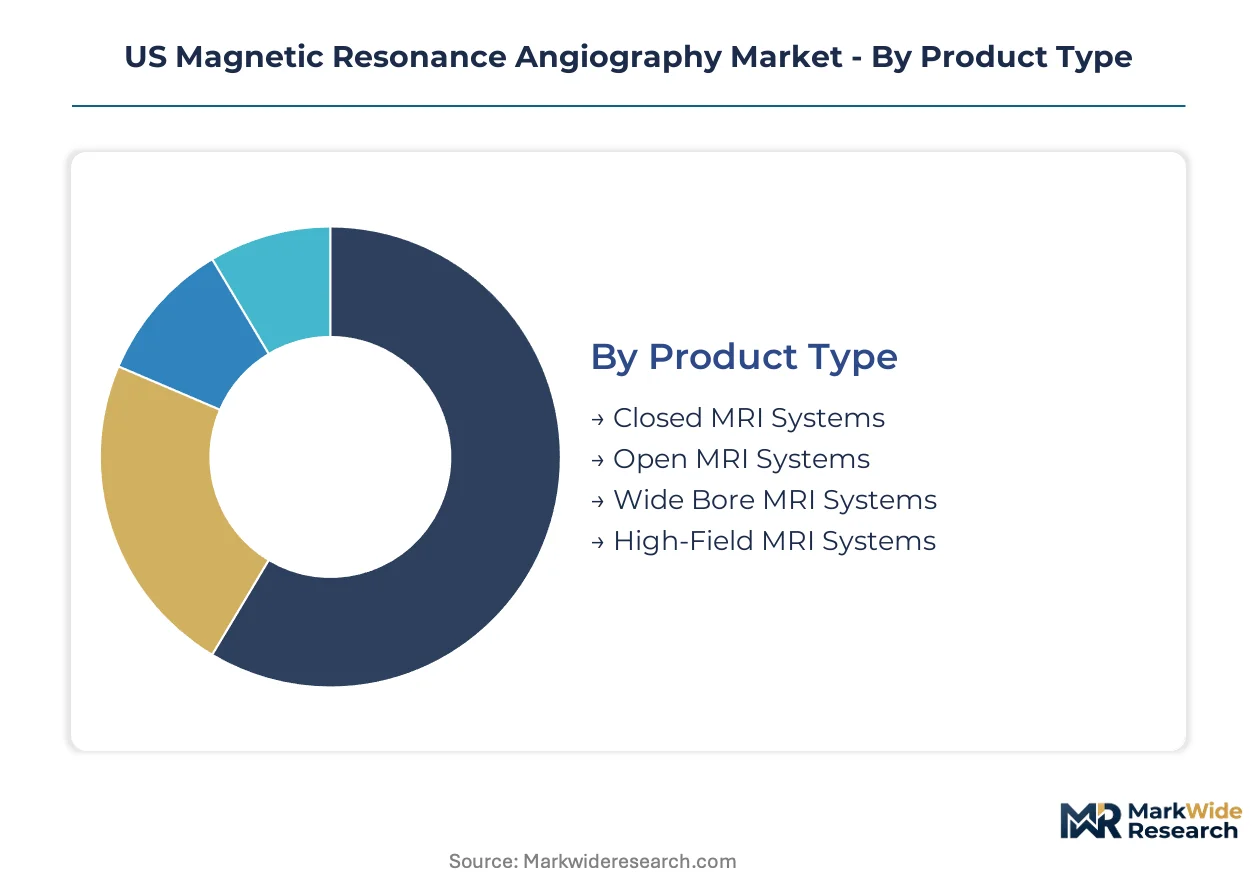
MRA platform segmentation reveals how FDA technical standards and ACR accreditation criteria fragment procurement decisions across care settings. Equipment specifications and site-of-service economics determine which configurations penetrate specific patient populations and clinical workflows.
Product Type:
FDA 510(k) clearance pathways differentiate platforms by field strength and bore configuration, directly shaping shielding requirements and helium conservation system specifications.
- Closed MRI Systems:Conventional bore designs operate at 1.5 tesla with full cryogenic enclosures. Northeast hospital systems deploy these for high-throughput neurovascular screening where patient tolerance permits.
- Open MRI Systems:Vertical field geometries eliminate the enclosed tunnel structure entirely. Texas and Florida health systems prioritize these for bariatric and pediatric segments where claustrophobia rates exceed national averages.
- Wide Bore MRI Systems:70-centimeter apertures balance signal performance with patient accessibility.
- High-Field MRI Systems:3 tesla platforms deliver superior signal-to-noise ratios for sub-millimeter vessel resolution.
High-field systems handle the majority of throughput; wide bore configurations are expanding most quickly on share.
Application:
Clinical utility varies sharply by vascular territory, with CMS reimbursement coding creating divergent economic returns across procedure types.
- Neurovascular Imaging:Cerebral MRA protocols detect aneurysms and arteriovenous malformations without catheter risks. Academic medical centers in Massachusetts and California concentrate procedure volume for stroke network referrals.
- Peripheral Vascular Imaging:Lower extremity runoff sequences evaluate arterial insufficiency in diabetic populations. Hospital-based deployments across the Midwest prioritize these for wound care service line integration.
- Coronary Artery Evaluation:Free-breathing cardiac gating advances are displacing CT angiography in renal-impaired patients.
- Renal Artery Assessment:Non-contrast sequences address gadolinium retention concerns in chronic kidney disease.
Neurovascular imaging dominates procedure counts; coronary artery evaluation is climbing the fastest on share.
End User:
Capital intensity and technologist certification requirements stratify MRA accessibility across provider types.
- Diagnostic Centers:High-volume outpatient facilities concentrate elective vascular screening. California imaging chains leverage compressed sensing protocols to maximize daily scanner utilization.
- Ambulatory Surgical Centers:Limited service settings focus on pre-operative planning for peripheral vascular interventions.
- Specialized Clinics:Vascular surgery and cardiology practices embed MRA for procedural planning.
- Academic Research Institutes:NIH-funded centers pilot accelerated acquisition algorithms and AI reconstruction techniques.
Diagnostic centers process the largest procedure volumes; academic research institutes are gaining share fastest through grant-funded platform upgrades.
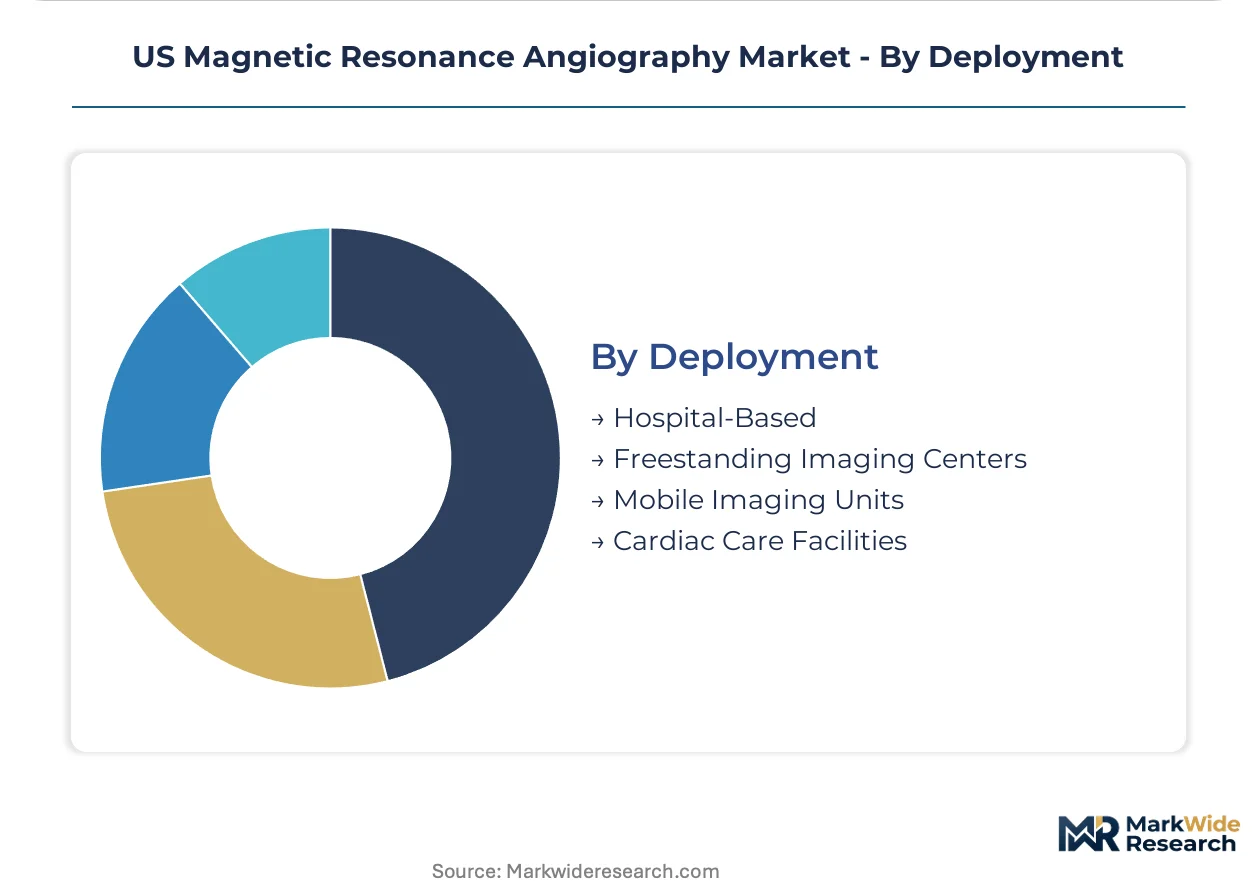
Deployment:
Site-of-service economics and integrated care network strategies determine physical placement of MRA capacity.
- Hospital-Based:Inpatient and emergency department access drives capital allocation. Northeast health systems embed MRA suites within comprehensive stroke centers for door-to-needle workflow integration.
- Freestanding Imaging Centers:Independent facilities compete on convenience and pricing for elective procedures.
- Mobile Imaging Units:Trailer-mounted 1.5 tesla systems extend reach to rural markets.
- Cardiac Care Facilities:Dedicated cardiovascular institutes co-locate MRA with catheterization laboratories.
Hospital-based deployments anchor installed capacity; cardiac care facilities are expanding most rapidly on share through service line consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and academic medical centers drive MRA capital procurement across distinct US sub-regions, with integrated cardiovascular service lines and stroke network certifications concentrating demand in specific metropolitan clusters.
Northeast Corridor
Comprehensive stroke center certifications and NIH-funded research institutes generate concentrated demand for high-field MRI platforms. Massachusetts General Hospital and New York-Presbyterian anchor neurovascular imaging volumes that justify 3 tesla upgrades. FDA 510(k) clearance timelines for AI-enabled reconstruction modules accelerate procurement cycles in Boston and Manhattan hospital networks.
California
Integrated delivery networks and outpatient imaging chains compete on compressed sensing throughput for elective vascular screening. Kaiser Permanente and Stanford Health Care deploy wide-bore configurations for bariatric populations. State-level seismic building codes extend MRI suite construction timelines, favoring mobile unit deployments in Central Valley markets.
Texas
Bariatric surgery volumes and pediatric specialty demand pull open MRI configurations into Dallas and Houston health systems. Texas Medical Center institutions pilot non-contrast renal artery protocols for chronic kidney disease populations. CMS hospital outpatient prospective payment system adjustments influence whether ASCs or hospital-based sites capture peripheral vascular procedures.
Florida
Snowbird demographics and Medicare Advantage penetration concentrate elective MRA screening in South Florida imaging chains. Tampa and Orlando health systems balance claustrophobia accommodation with throughput targets through mixed-platform inventories. State certificate-of-need regulations constrain freestanding imaging center expansion in saturated urban counties.
Midwest
Rural hospital networks and mobile imaging vendors extend MRA access beyond tertiary centers in Illinois and Ohio. Cleveland Clinic and Northwestern Memorial anchor academic research volumes for coronary MRA protocol development. Department of Transportation medical certification requirements for commercial drivers generate steady peripheral vascular imaging demand.
US Magnetic Resonance Angiography Market Key Industry Players
Player mix skews toward diversified medical technology conglomerates with installed-base leverage across imaging modalities. Siemens Healthineers, GE Healthcare, and Philips Healthcare anchor the premium tier through integrated cardiovascular informatics and predictive service contracts. Three strategic archetypes dominate: full-platform vendors with cath lab integration capabilities, mid-tier specialists in wide-bore configurations, and emerging challengers with AI-augmented reconstruction. Competitive moves center on unbundling after-sales service contracts and compressing 510(k) review timelines for algorithm-enhanced sequences.
Among diversified imaging conglomerates, GE Healthcare, Siemens Healthineers, and Philips Healthcare exemplify the integrated-platform archetype. These corporations occupy positions where predictive maintenance contracts and helium conservation systems extend customer retention. Canon Medical Systems and Fujifilm Healthcare represent the mid-tier specialist vector, while United Imaging Healthcare anchors the emerging challenger position with grant-funded academic research institute deployments.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Hitachi Medical Corporation |
| GE Healthcare |
| Aurora Imaging Technology |
| Toshiba Corporation |
| Siemens Healthineers |
| Fujifilm Healthcare |
| United Imaging Healthcare |
| Philips Healthcare |
| Others |
Cost & Logistics Intelligence
Helium recovery infrastructure at 3 tesla manufacturing plants creates scale thresholds that compress supplier margins while elevating price floors for hospital buyers. FDA 510(k) clearance cycles and ACR accreditation requirements lock in multi-year service contracts that bundle hardware, software, and cryogenic support into indivisible cost structures.
Pricing Analysis
Cost-plus contracts with helium indexation dominate MRA platform procurement, tying capital lease payments to spot market volatility in cryogenic gas supply. Three-tier pricing structure across premium, standard, and economy levels separates 3 tesla integrated cardiovascular suites from 1.5 tesla standalone scanners and refurbished wide-bore configurations. Pricing pressure stems from independent service organizations unbundling preventive maintenance from OEM leases, forcing original manufacturers to compress margin on long-term support agreements. Price sensitivity concentrates among freestanding imaging centers in saturated urban markets, while academic medical centers prioritize throughput optimization over unit cost.
Supply Chain Analysis
Inventory lead times for superconducting wire and helium conservation systems extend platform delivery windows beyond standard medical equipment procurement cycles. Manufacturing concentration centers on Germany, Japan, and the United States for magnet winding and cryogenic assembly, with China supplying RF coil subassemblies and gradient amplifier components. Raw material dependencies include niobium-titanium superconducting filament, liquid helium for magnet cooling, and rare-earth elements for gradient coil fabrication. Single-source vulnerability concentrates in helium liquefaction capacity, where domestic production constraints expose buyers to supply interruption. Distribution runs through direct OEM sales teams for hospital systems and regional distributors for outpatient imaging chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among integrated delivery networks in the Northeast and California has shifted procurement leverage toward multi-site health systems capable of dictating platform specifications and service terms across cardiovascular service lines.
For Market Incumbents: Shield installed-base revenue by embedding predictive maintenance algorithms and helium conservation retrofits that extend platform lifecycles beyond standard replacement cycles. Deepen vertical integration into cryogenic service operations to capture maintenance volumes threatened by independent service organizations. Prioritize FDA 510(k) submissions for AI-enabled reconstruction modules that compress review timelines and accelerate upgrade conversions. For New Entrants and Emerging Players: FDA breakthrough device designation for free-breathing coronary MRA sequences offers a regulatory fast-track into the fastest-expanding application segment. Target academic research institutes in Massachusetts and California where NIH grant funding supports pilot deployments of accelerated acquisition protocols. Pursue hospital-at-home and mobile imaging partnerships that bypass capital-intensive fixed-suite competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wide-bore platform specialists with established pediatric and bariatric reimbursement pathways over pure-play AI reconstruction vendors. Long-term viability rests on capturing service line integration contracts that pipe MRA data directly into cath lab planning workflows. Monitor FDA guidance publication velocity on machine learning-based medical devices as an inflection indicator for algorithm-augmented sequence commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI Reconstruction | Accelerated clearance timelines compress competitive windows for algorithm-augmented neurovascular sequences. |
| Helium Conservation System Retrofit | Closed-cycle cooling extends magnet lifecycles and defers replacement capital for hospital radiology departments. |
| Hospital System Partnership for Stroke Network | Comprehensive stroke center certification concentrates procedure flow toward accredited platforms with door-to-needle integration. |
| Wide-Bore Platform Launch for Bariatric Segment | 70-centimeter apertures capture pediatric and claustrophobic populations excluded from conventional bore configurations. |
| Independent Service Organization Acquisition | Vertical integration into preventive maintenance captures recurring revenue streams threatened by third-party disintermediation. |
Research Approach
The analysis maps high-field MRI platforms, wide-bore configurations, open MRI systems, and AI-enabled reconstruction modules, each validated through radiology department heads, biomedical engineering directors, GPO contracts managers, and MRI technologist supervisors. Primary interviews with hospital purchasing committees and outpatient imaging center operators combined with secondary validation against FDA 510(k) databases, CMS Medicare cost reports, ACR accreditation records, and hospital procurement databases. Bottom-up platform shipment tracking and top-down health system capital expenditure analysis provided triangulation checks.
Consistency checks validated volume and value outputs against external benchmarks including installed base estimates from major health system annual reports and replacement cycle assumptions from academic medical center capital planning disclosures. The analytical framework modeled field strength tiers, bore configurations, application segments spanning neurovascular through coronary evaluation, and deployment settings across hospital-based and freestanding sites. CAGRs derived from procedure volume growth assumptions tied to stroke network expansion and cardiac MRA protocol maturation, cross-referenced against helium supply constraints and technologist training pipeline limitations.
Underlying assumptions cover ACR accreditation penetration rates, FDA review timeline compression for AI-enabled devices, and helium market price stability, with deviation risk concentrated in gadolinium supply disruptions and CMS reimbursement coding adjustments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
Gallium-68 Market
Medical Imaging
United States Mammography Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
AI Radiology Worklist Orchestration Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Dental Imaging Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Interventional X - Ray Systems Market
Medical Imaging
Panoramic and Cephalometric Radiography Systems Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market