
 Asia-Pacific Neurology Monitoring Market | 2026-2036
Asia-Pacific Neurology Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Neurology Monitoring Market Outlook
Disposable silver-silver chloride electrodes are pivoting toward conductive polymer alternatives that cut per-procedure costs and reduce skin irritation in long-term ICU monitoring. Medtronic PLC leverages its neurosurgical implant portfolio to anchor recurring revenue streams from intracranial monitoring accessories. Nihon Kohden Corporation dominates Japan's hospital channel through dense technical service networks and JIS-certified manufacturing. Siemens Healthineers competes on imaging-neurology integration, bundling EEG with MRI and CT workflows.
Neurology monitoring encompasses the continuous or intermittent acquisition, processing, and display of electrical, hemodynamic, and structural data from the central and peripheral nervous systems, typically sampling EEG signals at 256–1024 Hz with 16–64 channel configurations for clinical-grade spatial resolution. Its primary purpose is to enable real-time detection of seizure activity, ischemic progression, and consciousness-level changes in acute and chronic care settings. EEG Devices occupy the largest installed base across Asia-Pacific tertiary hospitals, though AI Algorithms within the Technology dimension represent the fastest-expanding margin pool as software-as-a-service contracts replace capital-heavy hardware sales. Home Care under End User shows structural momentum in Australia and South Korea, where remote epilepsy monitoring reimbursement codes have activated new procurement channels.
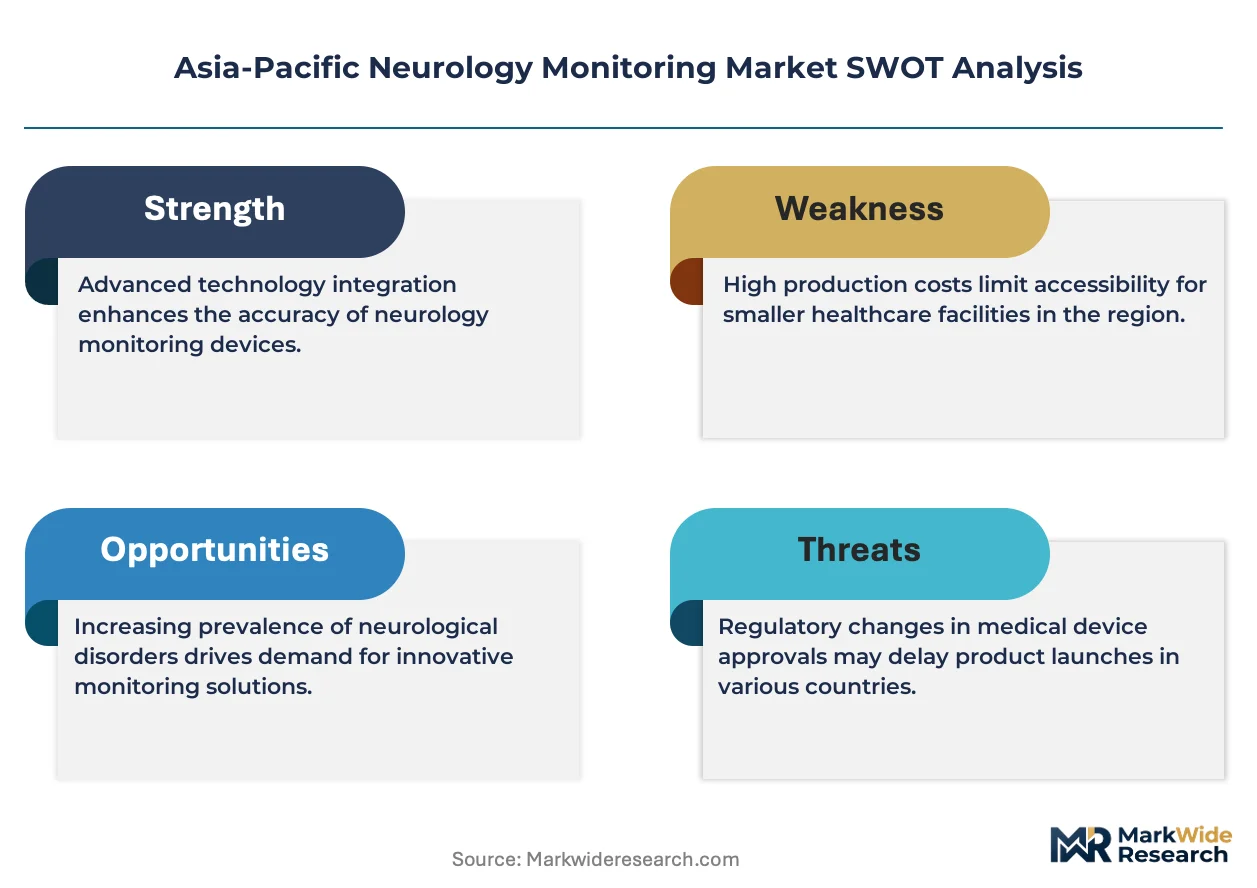
Japan's PMDA and Australia's TGA enforce divergent software-as-medical-device frameworks that fragment AI algorithm deployment timelines across the region. China's NMPA maintains stricter clinical evidence requirements for cloud-integrated neurology platforms, creating compliance moats for domestic manufacturers with established trial networks. Stakeholders must track harmonization negotiations between ASEAN medical device directives and individual national pharmacovigilance reporting standards, as alignment would unlock cross-border tele-neurology service scalability.
Market Dynamics
Hospital consolidation across China and Japan is compressing vendor negotiation cycles while accelerating procurement of integrated neurology platforms that bundle hardware, software, and technical service contracts into multi-year agreements.
Growth Catalysts
- Japan's PMDA streamlined AI device pathways:Accelerated approval timelines for machine-learning diagnostic algorithms reduce time-to-market for neurology software developers targeting tertiary hospitals.
- China's hospital upgrade mandates:Government-funded neurocritical care unit expansions in provincial centers drive bulk purchasing of continuous EEG and intracranial pressure monitoring systems.
- Aging demographics:South Korea and Australia's expanding elderly populations amplify demand for long-term epilepsy monitoring and stroke surveillance infrastructure.
Market Restraints
- Conductive polymer electrode supply concentration:Raw material dependency on specialized polymer suppliers in Japan and South Korea creates input cost volatility for disposable electrode manufacturers.
- China's NMPA cloud-integration requirements:Stricter clinical evidence standards for cloud-connected neurology platforms extend compliance timelines and favor domestic trial networks.
- Technical limitation in signal artifact rejection:ICU environmental interference with EEG acquisition necessitates costly hardware upgrades or proprietary filtering software.
Strategic Opportunities
- Remote epilepsy monitoring in Australia:Reimbursement code activation for home-based EEG surveillance opens new procurement channels outside traditional hospital capital budgets.
- AI-EEG and imaging convergence:Integration of machine-learning seizure detection with MRI and CT workflows creates bundled service offerings for integrated delivery networks.
- South Korea's digital health incentives:Government subsidies for telemedicine infrastructure reduce patient acquisition costs for remote neurology monitoring providers.
Industry Challenges
- Neurophysiology technologist shortage:Limited training pipeline for ICU EEG interpretation creates bottlenecks in monitoring program expansion across tertiary centers.
- Legacy EMR integration complexity:Proprietary data formats from established EEG vendors require expensive middleware development for health system interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Neurology Monitoring Market |
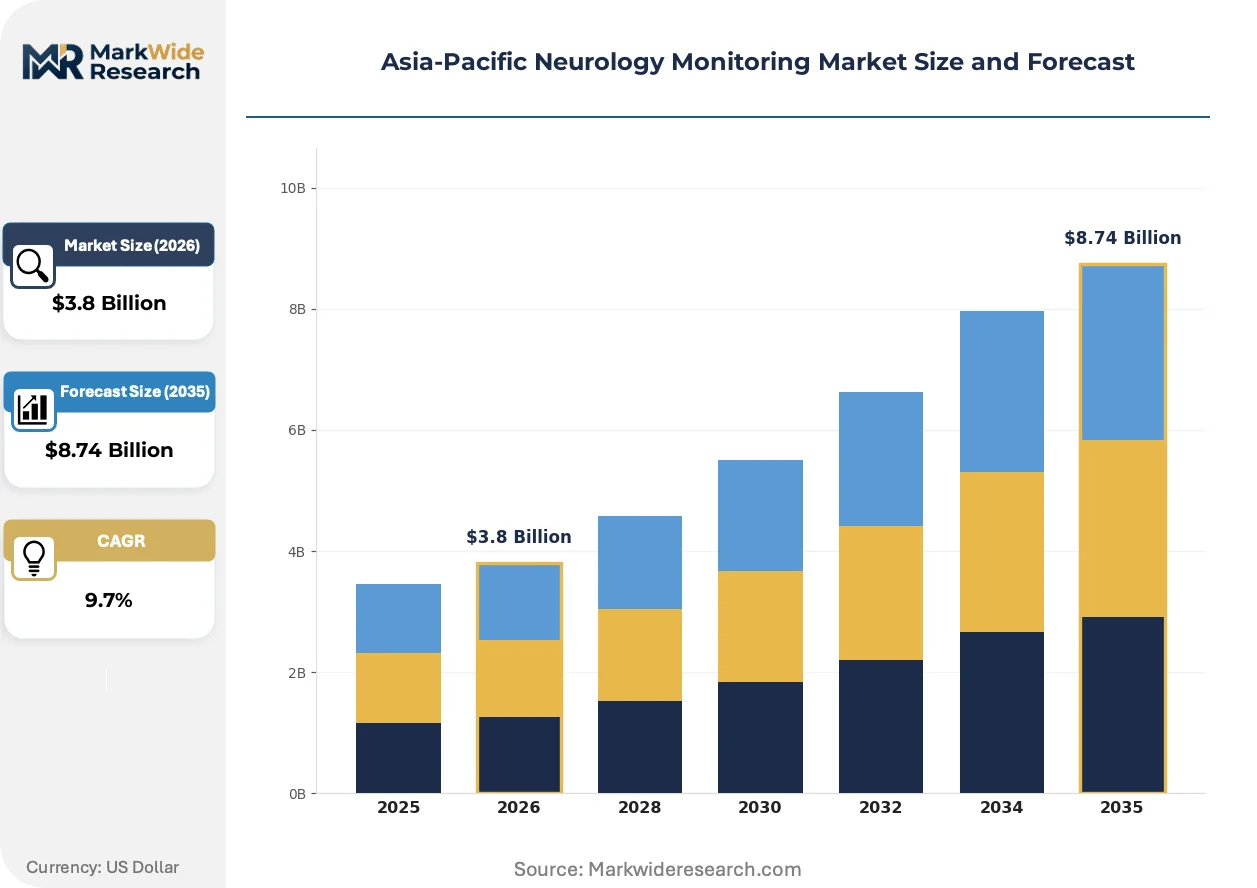
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EEG Devices, Electromyography, Neurostimulators, Imaging Systems End User: Hospitals, Diagnostic Centers, Research Institutes, Home Care Technology: Wireless Monitoring, Portable Devices, Cloud Integration, AI Algorithms Application: Epilepsy Monitoring, Sleep Studies, Pain Management, Cognitive Assessment |
| Companies Covered | Compumedics Limited, Medtronic PLC, Siemens Healthineers, General Electric Company, Nihon Kohden Corporation, Masimo Corporation, Koninklijke Philips N V, Dragerwerk Ag & Co Kgaa, Natus Medical Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Neurology Monitoring Market Strategic Shifts
Software-as-a-service contracts are displacing capital-heavy hardware sales across Asia-Pacific neurology monitoring, with vendors restructuring revenue models around per-patient monitoring fees rather than upfront device purchases.
Conductive polymer electrodes are rewriting cost structures in long-term ICU monitoring. These alternatives to traditional silver-silver chloride designs cut per-procedure expenses while reducing skin irritation in extended applications. Japanese and Australian tertiary hospitals are adopting them at accelerated rates for neurocritical care units. This shift is compressing margins for conventional electrode suppliers while opening recurring revenue streams for polymer formulation specialists.
PMDA's software-as-medical-device framework is fragmenting AI algorithm deployment timelines across the region. The regulation creates divergent compliance pathways between Japan and Australia's TGA standards, forcing developers to maintain parallel regulatory submissions. Neurology software vendors targeting multi-country hospital systems face extended product launch cycles and duplicated clinical trial investments.
Hospital procurement committees are consolidating vendor relationships around integrated platform providers. Standalone EEG device manufacturers face exclusion from preferred supplier lists as Chinese and Japanese health systems prioritize bundled contracts covering hardware, AI analytics, and technical service networks. This concentration is most visible in China's provincial hospital upgrades, where single-source agreements now dominate neurocritical care unit outfitting.
Asia-Pacific Neurology Monitoring Market Segmentation
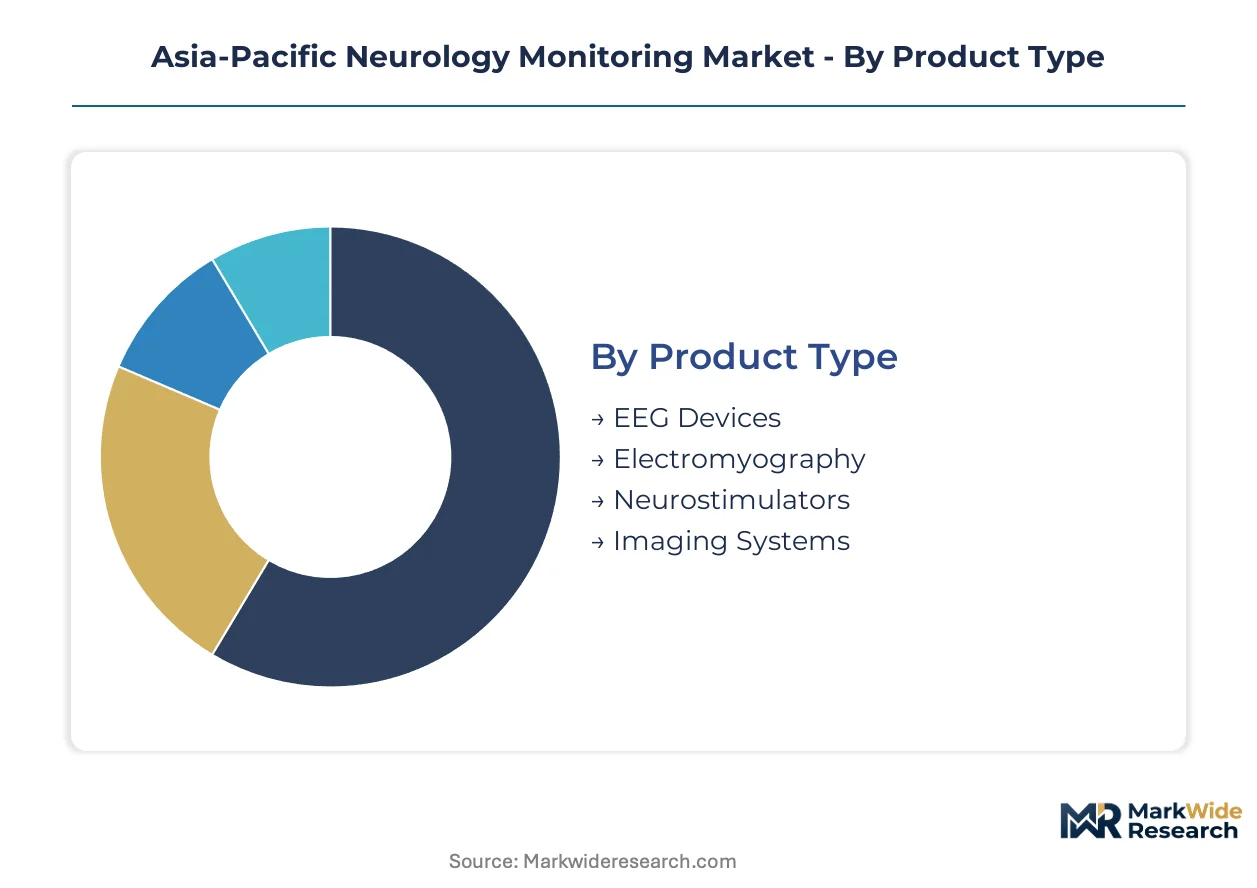
Segmentation in neurology monitoring reveals distinct procurement patterns across hardware, software, and service layers. Upgrade cycles vary dramatically: EEG devices face 7-10 year replacement timelines, while AI algorithm subscriptions refresh annually.
Product Type:
Replacement cycles and technology refresh rates differ sharply across product categories, with capital-intensive systems demanding longer depreciation schedules than disposable accessories.
- EEG Devices:These systems sample electrical activity at 256-1024 Hz through 16-64 channel configurations. China's provincial hospital upgrades drive bulk installations of continuous monitoring platforms in neurocritical care units.
- Electromyography:Peripheral nerve signal acquisition systems measure muscle response to neural stimulation. Diagnostic centers in Japan and South Korea prioritize portable EMG units for outpatient neurology clinics.
- Neurostimulators:Implantable pulse generators for deep brain and spinal cord applications.
- Imaging Systems:MRI and CT modalities with neurology-specific acquisition protocols.
Volume placements concentrate in EEG Devices; the faster expansion belongs to Neurostimulators.
End User:
Customer type determines contract structure, with hospitals favoring capital purchases and home care segments driving subscription-based revenue models.
- Hospitals:Tertiary centers across China and Japan deploy integrated platforms bundling hardware, software, and technical service contracts into multi-year agreements. Neurocritical care unit expansions in provincial Chinese hospitals anchor regional demand.
- Diagnostic Centers:Outpatient facilities prioritize throughput-optimized devices with rapid patient turnaround. Australia's private neurology clinics are expanding EEG capacity for sleep study referrals.
- Research Institutes:Academic medical centers with clinical trial mandates.
- Home Care:Remote monitoring deployments activated by Australia's reimbursement codes for epilepsy surveillance.
Procurement value concentrates in Hospitals; the steepest expansion trajectory belongs to Home Care.
Technology:
Technology layers stack from physical connectivity through analytical intelligence, with software components capturing expanding margin pools.
- Wireless Monitoring:Bluetooth and proprietary radio protocols eliminate tethered patient connections. Japanese tertiary hospitals adopt wireless EEG for ICU mobility, reducing artifact from cable strain.
- AI Algorithms:Machine-learning seizure detection and automated waveform classification. PMDA's streamlined approval pathways accelerate deployment across Japan's hospital networks.
- Portable Devices:Battery-powered acquisition systems for ambulatory and field deployment.
- Cloud Integration:Centralized data storage with remote access capabilities.
Installed base concentrates in Portable Devices; the fastest revenue climb belongs to AI Algorithms.
Application:
Clinical use case determines device specification, with epilepsy and sleep applications driving distinct hardware configurations and reimbursement pathways.
- Epilepsy Monitoring:Continuous or intermittent EEG surveillance for seizure detection and localization. Australia's activated reimbursement codes for home-based monitoring open procurement channels outside hospital capital budgets.
- Sleep Studies:Polysomnography and home sleep apnea testing with neurology-specific montages. South Korea's aging demographics amplify demand for sleep disorder diagnosis in diagnostic centers.
- Pain Management:Neurostimulation programming and spinal cord monitoring.
- Cognitive Assessment:EEG-based brain function evaluation for dementia and trauma.
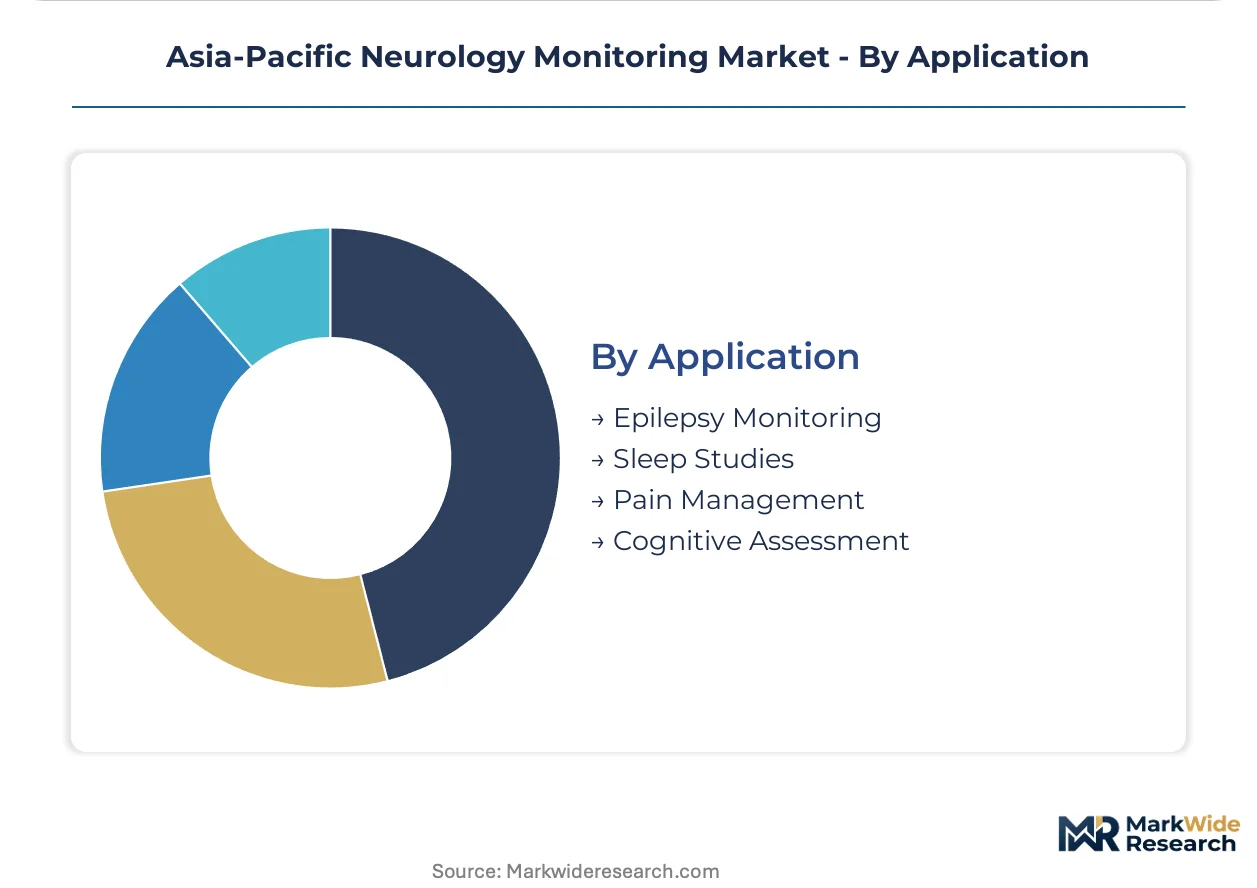
Procedure volume concentrates in Epilepsy Monitoring; the most rapid share gain belongs to Sleep Studies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the dominant share of regional procurement volume through government-funded neurocritical care expansions. Japan and South Korea anchor technology adoption curves, while Australia activates alternative reimbursement channels for home-based monitoring.
China
Provincial hospital upgrades drive bulk installations of continuous EEG and intracranial pressure systems. NMPA maintains stricter clinical evidence requirements for cloud-integrated platforms, favoring domestic manufacturers with established trial networks. Shanghai and Beijing medical centers concentrate procurement of integrated neurology platforms.
Japan
Aging demographics amplify demand for long-term epilepsy monitoring and stroke surveillance infrastructure. PMDA has streamlined approval pathways for AI-enabled diagnostic devices, accelerating technology diffusion across tertiary hospitals. Tokyo and Osaka anchor dense technical service networks supporting JIS-certified manufacturing.
South Korea
Government subsidies for telemedicine infrastructure reduce patient acquisition costs for remote neurology monitoring providers. MFDS regulates software-as-medical-device frameworks alongside hardware safety standards. Seoul Capital Area hospitals deploy wireless EEG systems for ICU mobility applications.
Australia
Remote epilepsy monitoring reimbursement codes have activated new procurement channels outside traditional hospital capital budgets. TGA enforces divergent software-as-medical-device frameworks that fragment AI algorithm deployment timelines. New South Wales and Victoria lead home care segment expansion for sleep study referrals.
India
Diagnostic center expansion in tier-2 cities drives portable EMG unit demand for outpatient neurology clinics. CDSCO regulates neurostimulation and implantable monitoring devices through centralized approval processes. Maharashtra and Karnataka concentrate private neurology clinic infrastructure investment.
Asia-Pacific Neurology Monitoring Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers capturing preferred supplier status in consolidated procurement channels. The market structures around three tiers: multinational conglomerates with imaging-neurology integration capabilities, dedicated neurology device specialists with dense service networks, and regional manufacturers competing on electrode disposables and accessories. Dominant competitive moves include bundling hardware-software-service contracts into multi-year agreements and restructuring revenue models around per-patient monitoring fees rather than capital sales.
Within the multinational conglomerate tier, Medtronic PLC and Siemens Healthineers exemplify platform integration strategies. Nihon Kohden Corporation anchors the dedicated specialist archetype with Japan-focused technical service density. These three occupy positions across the hardware-software-service spectrum without overlapping segment specialization.
| Leading Market Players |
|---|
| Compumedics Limited |
| Medtronic PLC |
| Siemens Healthineers |
| General Electric Company |
| Nihon Kohden Corporation |
| Masimo Corporation |
| Koninklijke Philips N V |
| Dragerwerk Ag & Co Kgaa |
| Natus Medical Inc |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed hospital procurement networks in China and family-owned electrode specialists in Japan anchor supply behavior while enforcing pricing discipline through multi-year technical service contracts and JIS-certified manufacturing standards.
Pricing Analysis
Volume placements concentrate in hardware while margin expansion belongs to software subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform providers from standalone device manufacturers and disposable accessory suppliers. Cost compression in economy-tier electrodes is intensifying because conductive polymer formulations are displacing silver-silver chloride designs. Diagnostic centers in Australia and South Korea exhibit highest price sensitivity, whereas neurocritical care units in Chinese provincial hospitals prioritize bundled service reliability over per-unit costs.
Supply Chain Analysis
Single-source vulnerability sits with specialized polymer suppliers in Japan and South Korea for conductive electrode formulations. Manufacturing concentrates in Japan, China, and South Korea for EEG hardware assembly, with raw material dependencies spanning silver chloride compounds, medical-grade polymers, and precision analog-to-digital converters. Supply chain risk centers on regulatory restriction as China's NMPA cloud-integration requirements fragment cross-border platform deployment. Distribution runs through hospital procurement committees and group purchasing organizations with consolidated vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized neurophysiology technologist capacity constraints prop pricing power for vendors with embedded training and technical service networks.
For Market Incumbents: Cement preferred supplier status by deepening technical service density in China's provincial hospital networks and securing JIS certification maintenance for polymer electrode manufacturing. Emerging AI-native software vendors threaten hardware-centric revenue streams, making backward integration into algorithm development a critical defensive lever.
For New Entrants and Emerging Players: PMDA's streamlined AI device pathways in Japan opens a window for seizure-detection software specialists to penetrate tertiary hospital procurement channels ahead of TGA harmonization. Australia's activated home-care reimbursement codes represent the most penetrable geography, with direct-to-neurologist SaaS sales offering lower customer acquisition friction than hospital capital committees.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap electrode manufacturers with polymer formulation IP in Japan and South Korea facing margin compression from conductive polymer displacement. Watch for MFDS telemedicine subsidy renewal decisions as an inflection indicator for remote monitoring infrastructure valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Regulatory Submission | PMDA's streamlined pathways accelerate machine-learning seizure detection deployment across Japan's tertiary hospitals. |
| Hospital System Partnership | Integrated platform bundling secures multi-year procurement contracts in China's provincial neurocritical care expansions. |
| Reimbursement Strategy Development | Australia's home-based EEG surveillance codes unlock patient-funded subscription revenue outside capital budgets. |
| Software Companion Development | Cloud-integrated analytics address NMPA clinical evidence requirements while differentiating from hardware-only vendors. |
| Backward Integration into Polymer Manufacturing | In-house conductive formulation production insulates margin pressure from Japanese and South Korean raw material suppliers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across neurocritical care unit directors, biomedical engineering procurement leads, GPO contracts managers, and EEG technologist training program administrators. Hospital procurement databases, PMDA device approval registries, NMPA clinical trial disclosure filings, and provincial health system budget appropriations documents provided segmentation baselines. Bottom-up installation counts triangulated against top-down health system expenditure estimates.
Data-stream reconciliation across hardware shipment records, software subscription bookings, and service contract values generated volume and value outputs. Segmentation dimensions spanned product type, end user archetype, technology layer, and application with regional regulatory cluster overlays. CAGRs derived from installed base replacement cycles, reimbursement code activation timelines, and AI algorithm adoption curves. Forecast inputs incorporated neurocritical care bed expansion targets and conductive polymer electrode conversion rates.
Caveats apply where PMDA-TGA harmonization delays or NMPA cloud-integration enforcement shifts could materially shift the outlook. Forecasts reflect assumptions about hospital consolidation trajectories, technologist training pipeline expansion, and polymer formulation cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Narcolepsy Treatment Market
Neurology
Cognitive Neuroscience Market
Neurology
Arachnoiditis Market
Neurology
Global Neuromarketing Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
Global Sciatica Treatment Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Transcranial Doppler Market
Neurology
Status Epilepticus Treatment Market
Neurology
Netherlands Neurology Devices Market
Neurology
Japan Neurology Devices Market
Neurology
Tourette Syndrome Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Arachnoiditis Treatment Market
Neurology
Global MRI Guided Neurosurgical Ablation Market
Neurology
United Kingdom Neurology Devices Market