
 Central Nervous System Lymphoma Treatment Market | 2026-2036
Central Nervous System Lymphoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Central Nervous System Lymphoma Treatment Market Outlook
The capital-intensity divergence between large-cap biopharmaceutical platforms and emerging neuro-oncology specialists is bifurcating competitive dynamics in CNS lymphoma therapeutics. Roche leverages its established diagnostics-to-therapeutics infrastructure to sustain leadership in CD20-directed combination protocols. AbbVie anchors its position through deep expertise in B-cell pathway modulation, while Kazia Therapeutics competes as a focused developer of blood-brain barrier penetrant agents.
Central nervous system lymphoma treatment encompasses multimodal therapeutic interventions targeting malignant lymphoid cell infiltration of the brain, leptomeninges, spinal cord, or vitreoretinal compartment, with methotrexate-based high-dose regimens remaining the pharmacologic backbone due to superior CNS penetration kinetics. Its primary purpose centers on achieving durable remission in an aggressive malignancy where the blood-brain barrier limits conventional systemic agent efficacy. Targeted therapy segments are attracting disproportionate R&D allocation as Bruton tyrosine kinase and PI3K inhibitors demonstrate intracranial activity, while stem cell transplant maintains structural importance as consolidation for eligible patients despite transplant-related mortality constraints. First-line treatment stages command the deepest clinical investment, though second-line protocols are expanding as relapsed disease biology becomes better characterized through molecular profiling.
FDA oncology center of excellence standards, EMA orphan drug designations, and NMPA priority review pathways collectively shape trial design, approval velocity, and post-market surveillance obligations for CNS lymphoma developers. REACH compliance and ISO 14155 clinical investigation standards further govern manufacturing quality and trial conduct for agents targeting this indication. Stakeholders must monitor emerging biomarker-defined subpopulations and evolving payer evidence requirements for blood-brain barrier penetration claims.
Market Dynamics
Blood-brain barrier penetration technology is restructuring competitive advantage in CNS lymphoma therapeutics, as developers race to demonstrate intracranial pharmacokinetic superiority over conventional high-dose methotrexate protocols that have dominated first-line care for two decades.
Growth Catalysts
- FDA Accelerated Approval Pathways:The oncology center of excellence fast-track designation compresses development timelines for rare CNS malignancies, incentivizing sponsors to pursue breakthrough therapy status for blood-brain barrier penetrant candidates.
- Molecular Profiling Infrastructure:Academic medical centers are deploying next-generation sequencing panels to stratify primary CNS lymphoma by MYD88 and CD79B mutation status, enabling biomarker-driven patient selection for targeted enrollment.
- Specialty Oncology Center Expansion:Dedicated neuro-oncology units in the United States are consolidating referral networks and standardizing methotrexate-based induction protocols across multi-site consortia.
Market Restraints
- Stem Cell Transplant Mortality Constraints:Transplant-related mortality rates limit consolidation therapy eligibility to patients under 70 with adequate organ function, structurally capping addressable patient volume for curative-intent regimens.
- High-Dose Methotrexate Nephrotoxicity:Renal clearance requirements and mandatory hydration protocols create capacity bottlenecks at infusion centers, restricting throughput during induction cycles.
- Blood-Brain Barrier Pharmacokinetic Failure:Systemic rituximab demonstrates negligible cerebrospinal fluid penetration, forcing reliance on intrathecal delivery or combination high-dose protocols with inferior tolerability profiles.
Strategic Opportunities
- Bruton Tyrosine Kinase Inhibitor Expansion:Ibrutinib and zanubrutinib are demonstrating intracranial activity in relapsed settings, creating a pathway for chemo-sparing maintenance protocols in molecularly selected subpopulations.
- EMA Orphan Drug Incentives:European market access benefits from ten-year exclusivity provisions and protocol assistance programs that reduce regulatory development costs for rare CNS indications.
- PI3K-AKT Pathway Convergence:Dual inhibition strategies combining BTK and PI3K blockade are entering early-phase trials, potentially addressing chemoresistance mechanisms in relapsed disease.
Industry Challenges
- Neuro-Oncology Trial Design Complexity:Response assessment in CNS lymphoma requires modified response criteria accounting for pseudoprogression and steroid effects, complicating endpoint standardization across investigative sites.
- Pharmacovigilance for Blood-Brain Barrier Agents:CNS penetration intensifies neurotoxicity signal detection requirements, mandating specialized safety monitoring infrastructure that smaller developers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Nervous System Lymphoma Treatment Market |
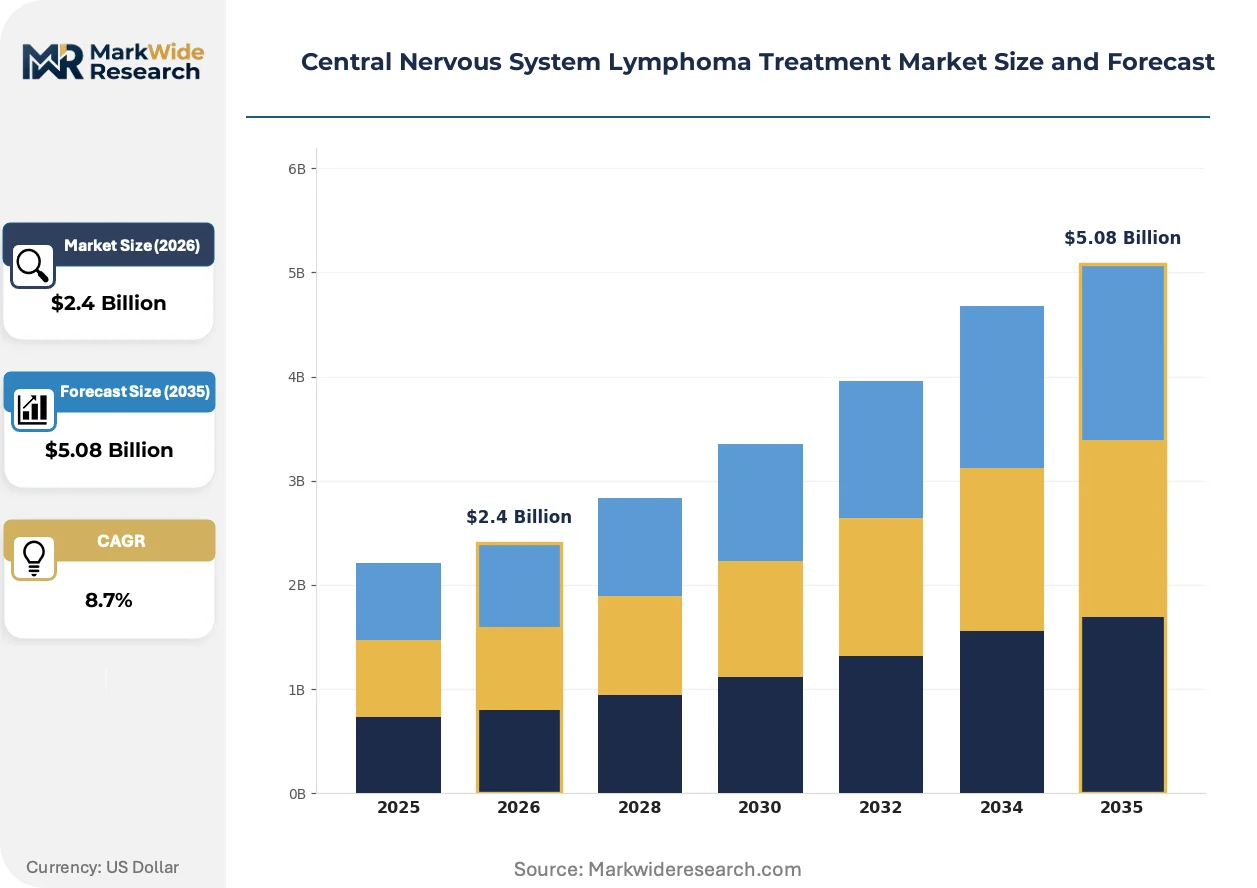
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Stem Cell Transplant, Targeted Therapy End User: Hospitals, Clinics, Research Institutions, Home Care Delivery Mode: Intravenous, Oral, Intra-arterial, Subcutaneous Treatment Stage: First-Line, Second-Line, Maintenance, Palliative |
| Companies Covered | AstraZeneca, Gilead Sciences, Roche, AbbVie, Amgen, Novartis, Incyte Corporation, Kazia Therapeutics, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Nervous System Lymphoma Treatment Market Strategic Shifts
Concentrated R&D investment is pivoting toward targeted agents with demonstrated intracranial activity, displacing incremental optimization of cytotoxic backbone regimens that have plateaued in efficacy.
Chimeric antigen receptor T-cell engineering is decomposing the traditional transplant-consolidation paradigm for relapsed CNS lymphoma. Academic centers in the United States are piloting CD19-directed constructs with modified conditioning protocols to enhance CNS trafficking. This cellular platform is compressing the addressable market for autologous stem cell transplant in second-line settings.
REACH compliance and EMA MDR requirements are intensifying manufacturing quality obligations for blood-brain barrier penetrant drug-device combinations. Sponsors must demonstrate endotoxin control and leachables validation for intrathecal delivery systems. European notified bodies are extending review timelines for novel CNS delivery mechanisms, compressing competitive windows for first movers.
Site-of-care migration is accelerating as high-dose methotrexate administration shifts from inpatient to ambulatory infusion centers with specialized pharmacy capabilities. United States payers are deploying prior authorization requirements that favor network consolidation around accredited neuro-oncology hubs. This channel concentration is marginalizing community oncology practices lacking 24-hour methotrexate clearance monitoring infrastructure.
Central Nervous System Lymphoma Treatment Market Segmentation
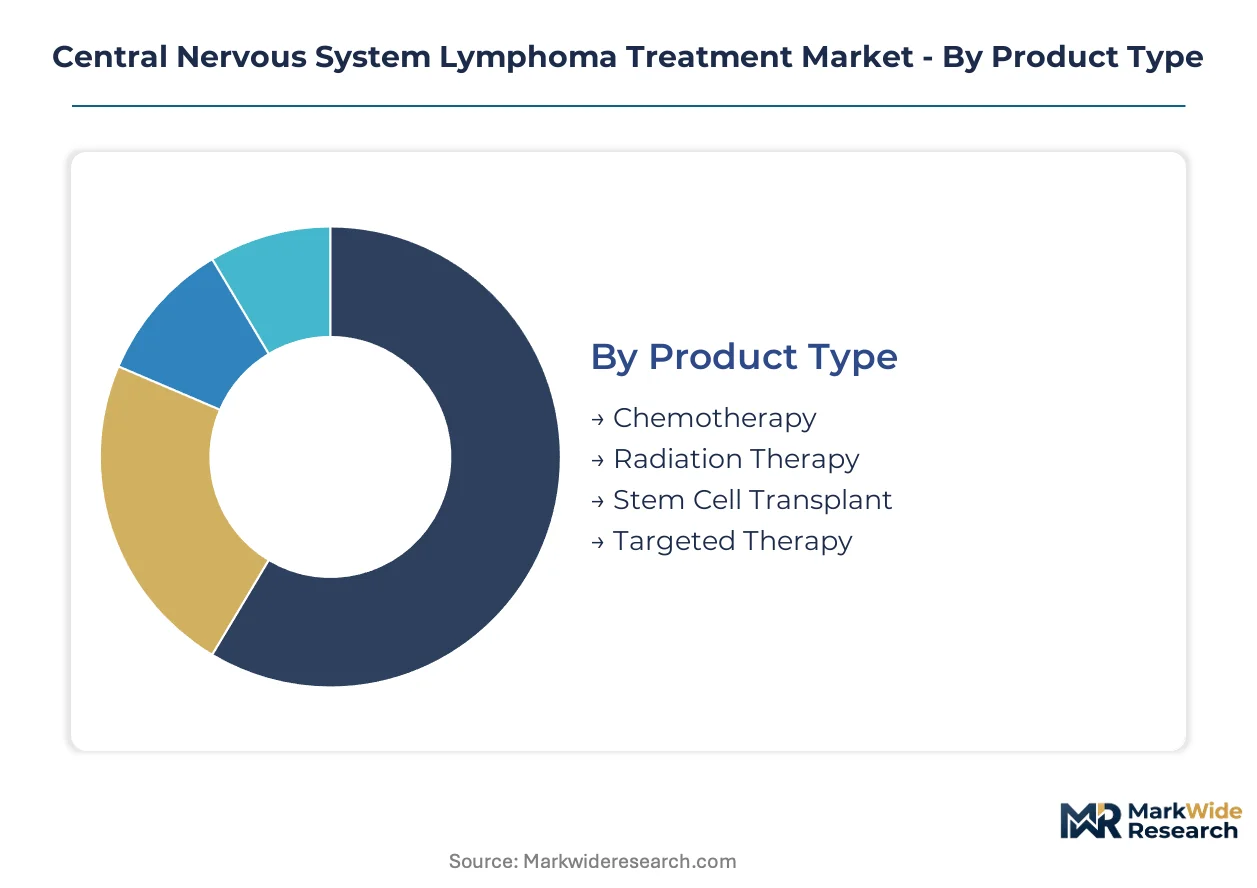
Segmentation in CNS lymphoma therapeutics reveals divergent channel economics and clinical workflows across treatment modalities. Each dimension—product type, end user, delivery mode, and treatment stage—carries distinct reimbursement logic and site-of-care requirements that shape commercial strategy.
Product Type:
Channel concentration varies sharply across therapeutic modalities, with high-complexity interventions anchoring to academic medical centers while simpler regimens diffuse into community networks.
- Chemotherapy:Methotrexate-based high-dose protocols remain the pharmacologic backbone, requiring specialized infusion centers with 24-hour leucovorin rescue capability. Demand concentrates at NCI-designated cancer centers in the United States where referral networks for primary CNS lymphoma are most developed, though nephrotoxicity monitoring creates capacity constraints.
- Targeted Therapy:Bruton tyrosine kinase inhibitors and PI3K pathway modulators are gaining traction through specialty pharmacy distribution channels. Academic consortia are driving adoption of ibrutinib and zanubrutinib in relapsed molecularly-selected subpopulations, with intracranial pharmacokinetic data supporting payer coverage decisions.
- Radiation Therapy:Whole-brain and involved-field protocols deploy through hospital-based radiation oncology departments with stereotactic capability.
- Stem Cell Transplant:Autologous consolidation therapy is restricted to transplant-eligible patients under 70 with adequate organ function, limiting addressable volume.
By volume, chemotherapy leads. By growth pace, targeted therapy is expanding most quickly.
End User:
Site-of-care economics are restructuring patient flow, with payers deploying prior authorization requirements that favor accredited neuro-oncology hubs over generalist settings.
- Hospitals:Inpatient and outpatient hospital units handle complex induction protocols requiring intensive monitoring. Major academic medical centers in Boston, Houston, and New York anchor referral networks for high-dose methotrexate administration, with 24-hour pharmacy and nephrology support mandatory for safe delivery.
- Clinics:Ambulatory infusion centers with specialized pharmacy capabilities are capturing stable maintenance therapy and oral targeted agent management. United States payers are consolidating networks around accredited neuro-oncology hubs, marginalizing community practices lacking blood-brain barrier penetration expertise.
- Research Institutions:Early-phase trial sites drive access to CAR-T constructs and novel delivery mechanisms.
- Home Care:Oral kinase inhibitors and supportive care medications shift to home administration with remote monitoring.
By patient volume, hospitals dominate. By channel expansion rate, clinics are gaining share fastest.
Delivery Mode:
Pharmacokinetic requirements and blood-brain barrier penetration dictate route selection, with intravenous maintaining structural importance despite oral convenience advantages.
- Intravenous:High-dose methotrexate and rituximab require IV administration with specialized hydration protocols. Infusion center capacity bottlenecks at major cancer centers restrict throughput during induction cycles, creating wait times that compress competitive windows for novel agents.
- Oral:BTK inhibitors and corticosteroid tapers enable outpatient management with improved patient convenience. Prescription fulfillment runs through specialty pharmacy networks with prior authorization requirements that favor formulary placement at large payers.
- Intra-arterial:Blood-brain barrier disruption techniques remain experimental, deployed at select academic centers.
- Subcutaneous:Limited current application in CNS lymphoma, though under investigation for maintenance regimens.
By treatment episodes, intravenous leads. By development pipeline activity, oral formulations are climbing the fastest.
Treatment Stage:
Clinical investment depth and reimbursement intensity vary across the care continuum, with first-line protocols commanding the deepest R&D allocation.
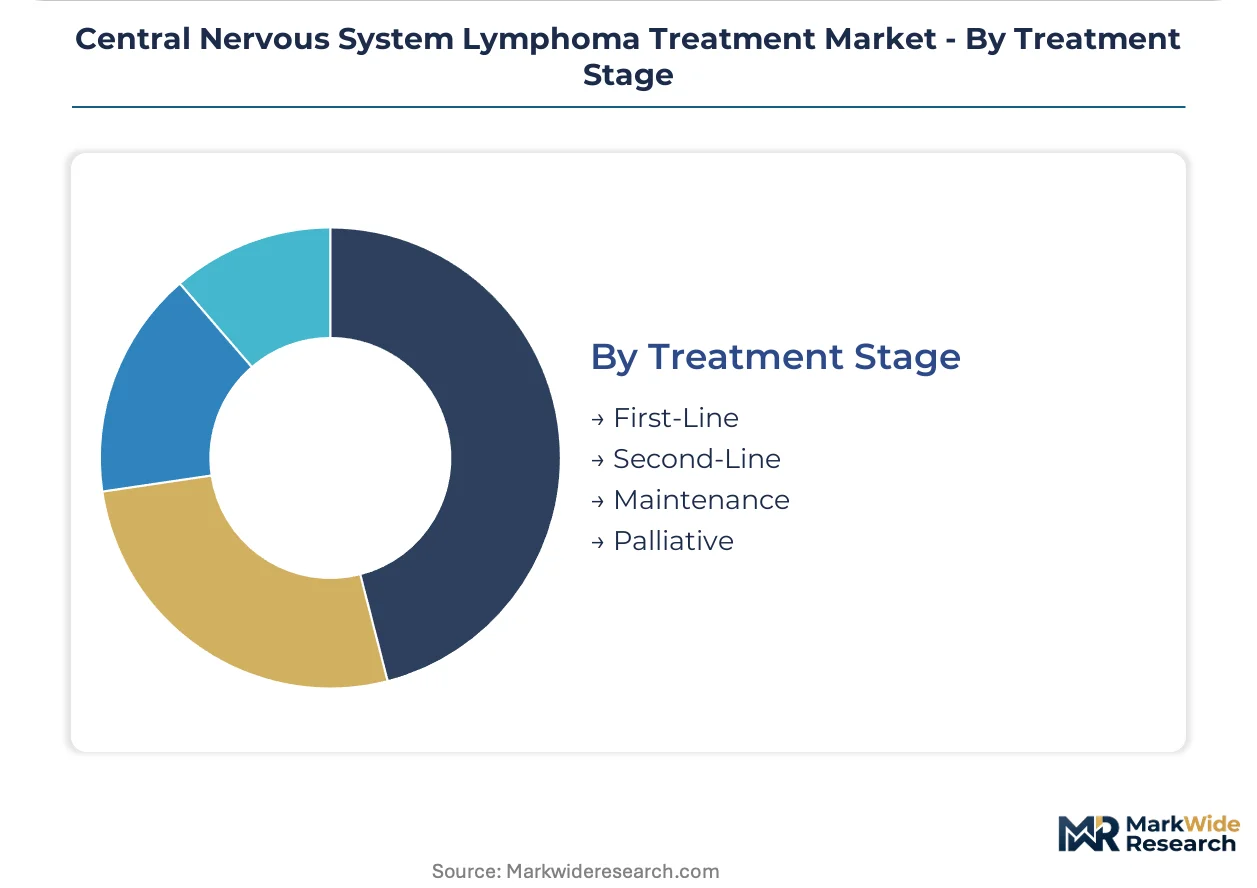
- First-Line:Methotrexate-based induction with or without rituximab anchors curative-intent therapy. FDA accelerated approval pathways are compressing timelines for blood-brain barrier penetrant candidates entering this setting, with breakthrough therapy status incentivizing sponsor investment.
- Second-Line:Relapsed disease biology is becoming better characterized through molecular profiling, enabling biomarker-driven enrollment for targeted agents. Academic centers are piloting CD19-directed CAR-T constructs to displace autologous transplant consolidation.
- Maintenance:Chemo-sparing protocols with BTK inhibitors are under investigation for molecularly-selected subpopulations.
- Palliative:Focused radiation and corticosteroids address symptomatic progression in transplant-ineligible patients.
By clinical trial count, first-line leads. By pipeline innovation intensity, second-line protocols show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity in CNS lymphoma therapeutics diverges sharply by geography. United States payers prioritize intracranial pharmacokinetic data for coverage decisions, while European systems emphasize transplant-eligibility criteria that constrain addressable volumes. Emerging markets exhibit price sensitivity that favors methotrexate-generic protocols over novel targeted agents.
United States
FDA accelerated approval pathways and breakthrough therapy designations compress development timelines for blood-brain barrier penetrant candidates. The oncology center of excellence fast-track mechanism incentivizes sponsors to generate intracranial response data early. Major academic medical centers in Boston, Houston, and New York anchor referral networks for high-dose methotrexate administration with 24-hour pharmacy support.
Germany
EMA orphan drug designation provides ten-year market exclusivity and protocol assistance that reduce regulatory costs for rare CNS indications. The country's statutory health insurance system reimburses autologous stem cell transplant consolidation for eligible patients under 70. Heidelberg and Berlin-based university hospitals lead European enrollment in CD19-directed CAR-T constructs for relapsed disease.
Japan
PMDA priority review pathways and sakigake designation accelerate access for innovative neuro-oncology agents with demonstrated CNS penetration. The aging demographic expands the transplant-ineligible population, intensifying demand for chemo-sparing maintenance protocols. Tokyo and Osaka academic centers pioneer biomarker-driven patient stratification using MYD88 and CD79B mutation profiling.
United Kingdom
NICE technology appraisals require cost-effectiveness evidence that favors methotrexate-rituximab combinations over premium-priced targeted agents in first-line settings. The NHS England specialized commissioning framework concentrates CNS lymphoma care at designated neuro-oncology centers. London and Manchester academic networks standardize response assessment protocols accounting for pseudoprogression and steroid effects.
China
NMPA priority review pathways and conditional approval mechanisms are shortening timelines for blood-brain barrier penetrant agents in rare malignancies. Domestic developers are advancing PI3K-AKT pathway inhibitors through investigator-initiated trials at Beijing and Shanghai cancer centers. Reimbursement negotiations for innovative oncology drugs increasingly reference intracranial pharmacokinetic benchmarks.
Central Nervous System Lymphoma Treatment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in CNS lymphoma therapeutics. Large-cap biopharmaceutical platforms sustain dominance through diagnostics-to-therapeutics infrastructure and established CD20-directed combination protocols. Emerging neuro-oncology specialists compete on blood-brain barrier penetration expertise and accelerated development timelines. Consolidation pressures favor players with integrated manufacturing quality systems capable of REACH compliance and EMA MDR validation for novel delivery mechanisms.
Among large-cap diversified developers, Roche, AbbVie, and Novartis occupy positions defined by B-cell pathway modulation depth and neuro-oncology clinical infrastructure. Roche exemplifies the diagnostics-anchored archetype with established CNS lymphoma biomarker platforms. AbbVie represents expertise in targeted combination design. Novartis anchors the cellular therapy vector through CAR-T development capabilities. Kazia Therapeutics sits within the focused-developer tier competing on blood-brain barrier penetrant specialization. These archetypes reflect divergent capital intensity requirements and regulatory risk tolerance across the competitive spectrum.
| Leading Market Players |
|---|
| AstraZeneca |
| Gilead Sciences |
| Roche |
| AbbVie |
| Amgen |
| Novartis |
| Incyte Corporation |
| Kazia Therapeutics |
| Bristol-Myers Squibb |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for blood-brain barrier penetrant active pharmaceutical ingredients concentrate pricing power with specialized CDMOs in Switzerland and Germany, while infusion center capacity constraints in the United States create bottlenecks that elevate site-of-care premiums for high-dose methotrexate administration.
Pricing Analysis
After-sales revenue from leucovorin rescue protocols and extended nephrotoxicity monitoring contracts drives lifetime value per patient episode. The market operates on a hybrid pricing structure combining per-cycle chemotherapy reimbursement with bundled payments for transplant-eligible pathways. Price differentiation hinges on blood-brain barrier penetration certification and academic medical center accreditation tier. Cost compression in first-line methotrexate protocols is intensifying because of generic substitution pressure. Community oncology practices exhibit highest price sensitivity, while NCI-designated cancer centers command premium reimbursement through outcome-based contracting.
Supply Chain Analysis
Inbound logistics costs for temperature-controlled methotrexate vials have climbed on constrained container availability from Basel to Newark trade lanes. Manufacturing concentrates in Switzerland, Germany, and the United States for sterile injectable formulations. Raw material dependencies include pharmaceutical-grade methotrexate API, rituximab biosimilar feedstock, and specialized blood-brain barrier penetration excipients. Single-source vulnerability for BTK inhibitor intermediates sourced from Japanese chemical suppliers poses structural risk. Distribution runs through specialty pharmacy networks with cold-chain validation for hospital-based infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Central Nervous System Lymphoma Treatment Market represents high-growth disruption as FDA accelerated approval pathways compress development timelines for blood-brain barrier penetrant candidates, creating first-mover advantages that reshape competitive economics.
For Market Incumbents: Compound diagnostics-to-therapeutics infrastructure advantages by integrating CD20 biomarker platforms with next-generation BTK inhibitor combination protocols. Deepen backward integration into blood-brain barrier penetration formulation capabilities to defend against emerging neuro-oncology specialists. Lock in capacity at NCI-designated cancer centers through exclusive leucovorin rescue service contracts. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-tracks provide regulatory acceleration for focused developers lacking legacy oncology infrastructure. Target second-line relapsed settings where molecular profiling infrastructure remains underdeveloped and payer evidence requirements for intracranial pharmacokinetic data are still forming. Lead with biomarker-driven patient stratification capabilities to differentiate from methotrexate-generic protocols. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap biopharmaceutical parents seeking to divest non-core neuro-oncology assets with blood-brain barrier penetration expertise. Long-term viability centers on demonstrated intracranial response rates and regulatory exclusivity duration. Watch for EMA orphan drug designation announcements as inflection indicators for European market access positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerated FDA pathways compress timelines for blood-brain barrier penetrant candidates entering first-line protocols. |
| Regulatory Approval Pathway | EMA orphan drug designation secures ten-year exclusivity and protocol assistance for rare CNS indications. |
| Manufacturing Scale-Up | REACH-compliant sterile injectable capacity expansion anchors supply security for high-dose methotrexate backbones. |
| Pipeline Diversification | PI3K-AKT pathway convergence strategies address chemoresistance mechanisms in molecularly-selected relapsed subpopulations. |
| Licensing Agreement | CD19-directed CAR-T construct partnerships compress addressable market for autologous stem cell transplant consolidation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA oncology center of excellence guidance documents, EMA orphan drug designation databases, and ClinicalTrials.gov CNS lymphoma protocol registrations. Interviews with drug development executives, regulatory affairs leads, formulary directors at major United States payers, and hospital procurement managers at NCI-designated cancer centers inform qualitative assessments. Secondary validation draws from SEC 10-K oncology segment disclosures, CMS Medicare reimbursement data, and hospital procurement database analytics. Bottom-up patient-flow modeling triangulates against top-down market sizing across treatment stages.
Segmentation dimensions modeled span product type, end user, delivery mode, and treatment line, with geographic regulatory clusters and biomarker-defined patient populations as cross-cutting variables. CAGRs derive from epidemiological incidence projections, treatment penetration curves, and pricing trajectory assumptions across the analysis window. Forecast inputs incorporate transplant-eligibility demographics, blood-brain barrier penetration approval velocity, and site-of-care migration patterns toward ambulatory infusion centers.
Decision-makers should treat outputs as directional under stable regulatory approval timelines and consistent payer coverage policies for blood-brain barrier penetrant agents; material deviation would warrant model refresh. Accelerated approval withdrawals, stem cell transplant mortality threshold shifts, or biosimilar rituximab entry could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Global Neuromarketing Market
Neurology
Status Epilepticus Treatment Market
Neurology
Mexico Neurology Devices Market
Neurology
Chile Neurology Devices Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
Neurological Biomarkers Market
Neurology
Arachnoiditis Treatment Market
Neurology
Nerve Repair Market
Neurology
Hepatic Encephalopathy Market
Neurology
Neurology Software Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Frontotemporal Disorders Treatment Market
Neurology
Neurocutaneous Disorders Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
North America Traumatic Brain Injuries Assessment Market