
 China Neurology Devices Market | 2026-2036
China Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Neurology Devices Market Outlook
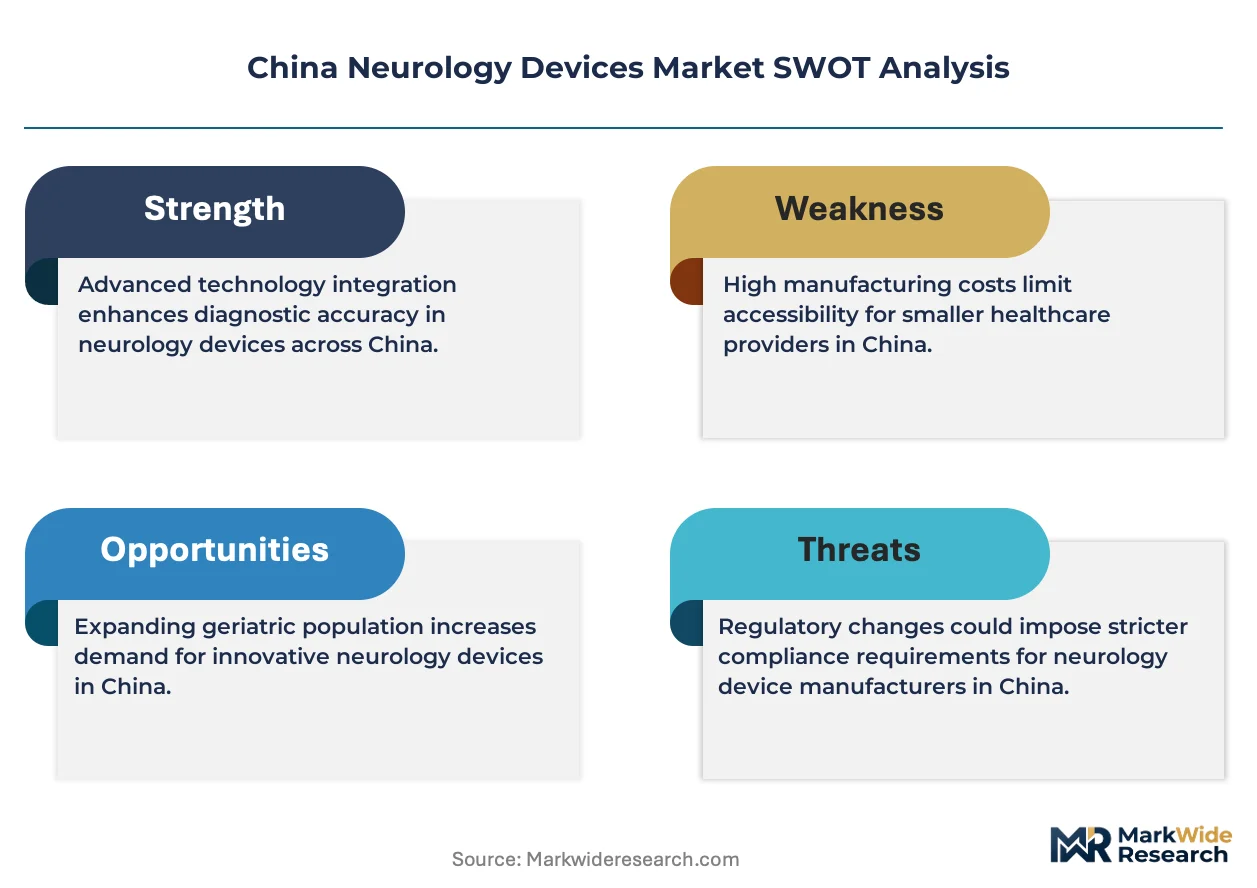
NMPA's innovation approval channel is expanding eligibility for breakthrough neurology devices, raising compliance costs for entrants while rewarding established manufacturers with faster market access. Medtronic PLC leverages its deep neurostimulation portfolio to sustain premium positioning across China's hospital procurement networks. Stryker Corporation anchors its presence through specialized cranial and neurovascular instruments tailored to Chinese surgical protocols. Abbott Laboratories differentiates via integrated neuromodulation systems that compete directly with domestic challengers in pain management segments.
Neurology devices encompass instruments, implants, and diagnostic systems engineered to monitor, treat, or modulate nervous system function, typically incorporating biocompatible materials, precision electronics, and signal-processing algorithms operating at microvolt sensitivity thresholds. These systems serve clinical purposes spanning intraoperative navigation, chronic disease management, and neural pathway mapping. Neurostimulation devices dominate current revenue pools given their implantable nature and recurring replacement cycles, while neuroimaging systems built on magnetic resonance imaging technology represent the fastest-expanding category as hospitals upgrade to higher-field-strength platforms. EEG devices occupy a mature, price-competitive tier where Mindray Medical International and Lepu Medical Technology press multinational margins through localized manufacturing and service networks.
NMPA's GB standards for active implantable medical devices, alongside MIIT's dual carbon goals pressuring manufacturing energy efficiency, collectively reshape product design requirements and facility certification timelines for neurology device producers. The country's national pharmaceutical regulator maintains stringent clinical evidence demands for novel neurostimulation indications, filtering out undercapitalized applicants. Stakeholders must monitor NMPA's evolving technical review guidelines and provincial centralized procurement shifts to anticipate margin compression or access expansion across China's fragmented hospital tier system.
Market Dynamics
NMPA's accelerated review pathways for innovative medical devices are compressing product development timelines while simultaneously elevating clinical evidence requirements, forcing manufacturers to restructure regulatory affairs capabilities and local partnership strategies.
Growth Catalysts
- Neuroimaging infrastructure expansion:Tier-one hospitals in Beijing, Shanghai, and Guangzhou are installing higher-field-strength MRI platforms to manage stroke and neurodegenerative patient volumes.
- NMPA innovation approval channel:Breakthrough device designation eligibility is expanding, rewarding established manufacturers with faster market access for novel neurostimulation systems.
- Dual carbon goals compliance:MIIT's manufacturing energy efficiency mandates are accelerating facility upgrades that favor producers with capital for green certification.
Market Restraints
- Clinical evidence intensity:NMPA's stringent data demands for novel neurostimulation indications filter out undercapitalized applicants before technical review completion.
- Input material concentration:Biocompatible polymers and precision electronics for implantable devices rely on concentrated supplier bases in coastal manufacturing zones.
- Reimbursement fragmentation:Provincial centralized procurement shifts create pricing unpredictability across China's hospital tier system.
Strategic Opportunities
- Tier-two city penetration:Neurosurgery department density in Chengdu, Wuhan, and Xi'an remains below saturation thresholds for advanced navigation systems.
- Home-based neurostimulation monitoring:Remote patient management platforms are creating new service revenue streams beyond device implantation.
- GB standards harmonization:Active implantable medical device technical guidelines are converging toward international benchmarks, simplifying multinational product adaptation.
Industry Challenges
- Signal processing specialization:Microvolt-sensitivity algorithm development requires scarce expertise at the intersection of neuroscience and electrical engineering.
- Legacy system integration:New neuroimaging platforms must interface with hospital information systems that vary widely across provincial networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Neurology Devices Market |
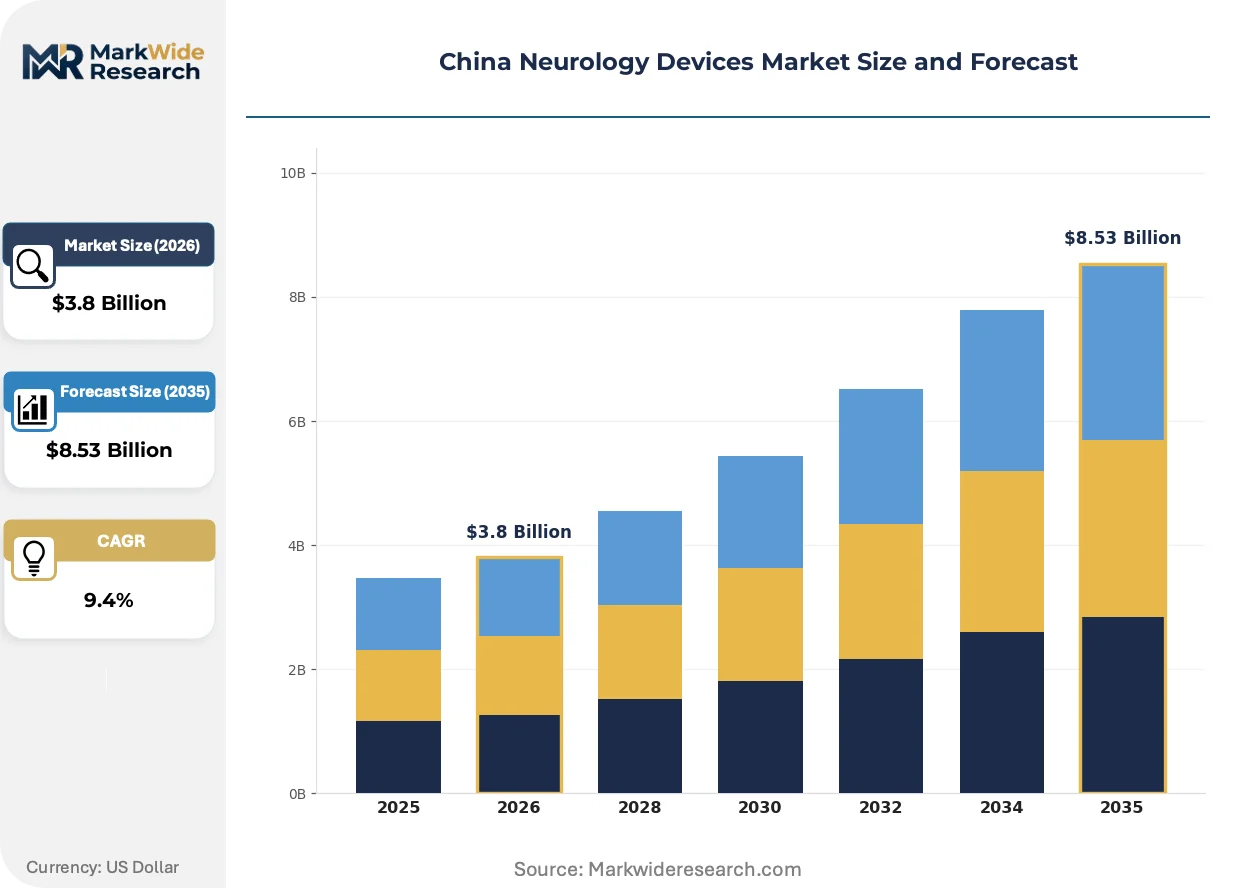
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulation Devices, EEG Devices, Neuroimaging Systems, Cranial Stimulation Devices Technology: Magnetic Resonance Imaging, Electroencephalography, Functional MRI, Computed Tomography End User: Hospitals, Neurology Clinics, Rehabilitative Centers, Research Institutions Application: Chronic Pain Management, Epilepsy Treatment, Stroke Rehabilitation, Neurodegenerative Disorders |
| Companies Covered | Medtronic PLC, Stryker Corporation, Boston Scientific Corporation, Abbott Laboratories, Johnson and Johnson, MicroPort Scientific, B. Braun Melsungen AG, Mindray Medical International, Lepu Medical Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Neurology Devices Market Strategic Shifts
Neurology device development is pivoting toward integrated diagnostic-therapeutic platforms that compress the gap between neural signal detection and intervention, with software-defined functionality displacing hardware-centric architectures.
High-field MRI technology is rewriting competitive positioning in neuroimaging procurement. Beijing and Shanghai tertiary hospitals are adopting 7-tesla platforms for submillimeter resolution in functional brain mapping. This capability is compressing the diagnostic timeline for neurodegenerative conditions and forcing equipment vendors to restructure service contracts around uptime guarantees rather than hardware margins.
NMPA's evolving GB standards for active implantable medical devices are tightening electromagnetic compatibility and biostability testing protocols. Domestic manufacturers face extended facility certification timelines while multinationals with established quality management systems capture early-mover advantage. The neurostimulation segment is responding by consolidating clinical affairs teams in Shanghai regulatory consulting clusters.
Hospital procurement committees are unbundling after-sales service from device pricing, creating transparent cost structures for maintenance and algorithm updates. Neuroimaging vendors in Guangzhou are piloting subscription-based software licensing for image reconstruction modules. This behavior is most visible in tier-one cities where neurosurgery department budgets face centralized procurement audit scrutiny.
China Neurology Devices Market Segmentation
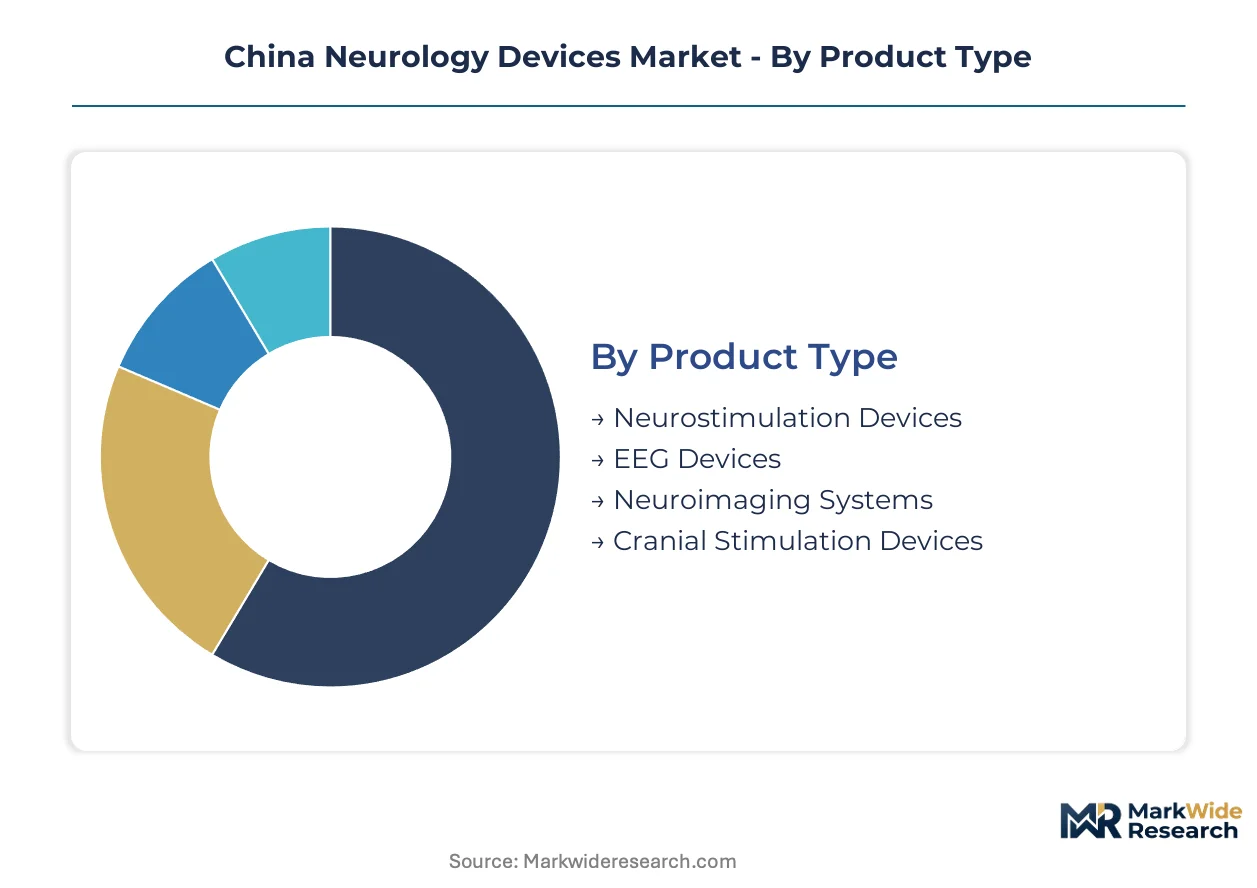
Neurology device procurement in China follows distinct technical and economic logics across product categories, with reimbursement eligibility and hospital tier capacity determining adoption velocity. Manufacturers must align portfolio development with NMPA approval pathways and provincial procurement priorities.
Product Type:
Hospital procurement committees weight replacement cycles and service revenue potential differently across implantable versus capital equipment categories.
- Neurostimulation Devices:Implantable pulse generators and leads utilizing biocompatible polymers and microelectrode arrays deliver chronic electrical modulation for movement disorders and pain. Beijing and Shanghai tertiary hospitals drive demand through deep brain stimulation programs for Parkinson's disease, with replacement surgeries generating recurring revenue streams.
- Neuroimaging Systems:MRI and CT platforms with specialized neurological coils enable structural and functional brain mapping at submillimeter resolution. Guangzhou hospital networks are upgrading to 7-tesla field strengths for neurodegenerative diagnostics, compressing equipment replacement timelines from seven to five years.
- EEG Devices:Surface and intracranial electrode systems with microvolt-sensitivity amplifiers capture cortical electrical activity for seizure localization and sleep studies.
- Cranial Stimulation Devices:Non-invasive transcranial magnetic and direct current stimulation units target depression and stroke rehabilitation in outpatient settings.
Neurostimulation devices lead volumes today; neuroimaging systems are gaining share fastest.
Technology:
Capital allocation across imaging modalities reflects diagnostic specificity requirements and facility infrastructure constraints.
- Magnetic Resonance Imaging:Superconducting magnet systems with gradient coil arrays generate high-contrast soft tissue visualization without ionizing radiation. Tier-one hospitals in Beijing prioritize 3-tesla and 7-tesla platforms for functional neurosurgical planning, while tier-two cities standardize on 1.5-tesla workhorses.
- Electroencephalography:Amplifier chains with 24-256 channel configurations and active electrode technology enable long-term epilepsy monitoring and intraoperative mapping. Chengdu neurology clinics are expanding ambulatory EEG services for rural patient catchment, driving portable system demand.
- Functional MRI:Blood-oxygen-level-dependent contrast sequences map neural activation patterns for preoperative eloquent cortex localization.
- Computed Tomography:Multi-detector arrays with submillimeter slice thickness deliver rapid stroke triage and hemorrhage detection in emergency settings.
MRI technology commands the largest installed base; functional MRI applications are expanding most quickly.
End User:
Facility type determines reimbursement coding, patient volume thresholds, and technical service requirements.
- Hospitals:Tertiary medical centers with neurosurgery departments house comprehensive diagnostic-therapeutic platforms and interventional suites. Shanghai public hospital procurement networks concentrate demand for integrated neuromodulation systems, with centralized tendering compressing vendor margins.
- Neurology Clinics:Specialized outpatient facilities focus on diagnostic workup and chronic disease monitoring with lower capital intensity. Wuhan private clinic chains are deploying telemedicine-linked EEG for remote interpretation, creating distributed demand for cloud-connected devices.
- Rehabilitative Centers:Post-acute facilities emphasize non-invasive stimulation and physical therapy integration for stroke recovery.
- Research Institutions:Academic medical centers and neuroscience institutes operate experimental platforms for clinical trial endpoints and biomarker discovery.
Hospitals dominate current procurement; neurology clinics are scaling fastest.
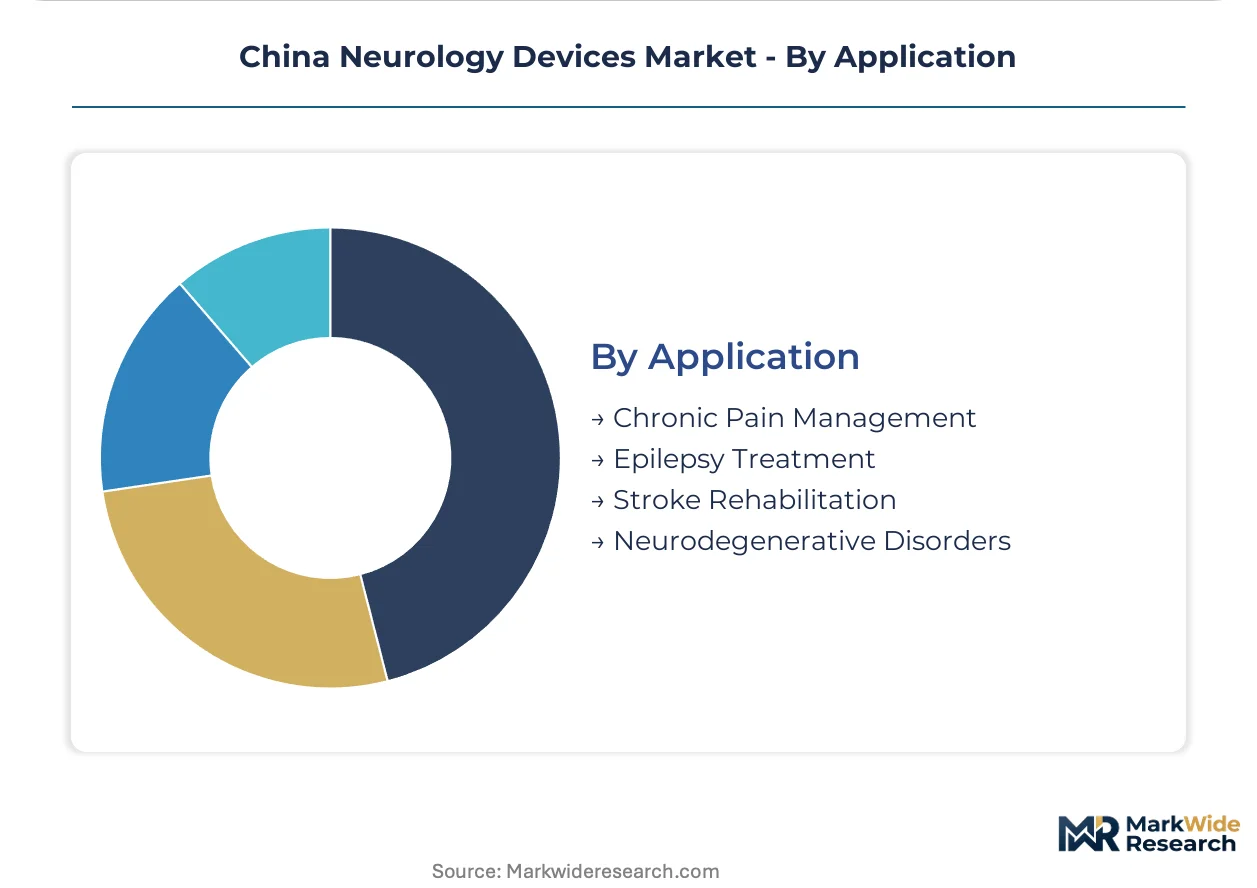
Application:
Clinical indication drives device specification, with chronic conditions requiring implantable solutions versus acute events favoring diagnostic platforms.
- Chronic Pain Management:Spinal cord and peripheral nerve stimulation systems with rechargeable pulse generators address failed back surgery syndrome and complex regional pain. Guangdong provincial reimbursement expansion for neuropathic pain indications is accelerating patient access to implantable therapies.
- Epilepsy Treatment:Responsive neurostimulation and vagus nerve stimulation devices provide adjunctive therapy for drug-resistant seizures. Xi'an epilepsy centers are adopting stereo-EEG-guided laser ablation combined with chronic stimulation, integrating device categories.
- Stroke Rehabilitation:Non-invasive brain stimulation and robotic exoskeletons target motor recovery in subacute and chronic phases.
- Neurodegenerative Disorders:Deep brain stimulation for Parkinson's disease and emerging applications for Alzheimer's represent premium implantable segments.
Chronic pain management leads procedure volumes; neurodegenerative applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurosurgical talent clusters in Beijing, Shanghai, and Guangzhou anchor procurement demand for advanced neurology devices. Provincial reimbursement policies and hospital tier density create divergent adoption timelines across China's urban hierarchy.
Beijing-Tianjin-Hebei
Tertiary hospitals in Beijing house the highest density of deep brain stimulation programs for movement disorders. NMPA's innovation approval channel processes neurostimulation device applications through regulatory consulting clusters in the capital. Tianjin's manufacturing zones supply precision electronics for implantable pulse generators to domestic producers.
Yangtze River Delta
Shanghai's neurosurgery departments drive demand for integrated neuromodulation systems through centralized public hospital tendering. MIIT's dual carbon goals pressuring energy efficiency are accelerating green facility certifications among device producers in Suzhou and Hangzhou. The region's medical device industrial parks concentrate EEG amplifier manufacturing for export markets.
Pearl River Delta
Guangzhou hospital networks are upgrading to 7-tesla MRI platforms for neurodegenerative diagnostics, compressing equipment replacement cycles. Guangdong provincial reimbursement expansion for neuropathic pain indications accelerates patient access to spinal cord stimulation therapies. Shenzhen's electronics ecosystem supplies microelectrode arrays and signal processing components to neurostimulation device assemblers.
Sichuan-Chongqing
Chengdu's neurology clinics are expanding ambulatory EEG services for rural patient catchment, driving portable system demand. NMPA's GB standards for active implantable devices require extended facility certification timelines for local manufacturers. Chongqing's medical device industrial corridor hosts assembly operations for cranial navigation instruments serving western China hospital networks.
China Neurology Devices Market Competitive Environment
The competitive structure tilts toward multinational incumbents with established neurostimulation portfolios and domestic challengers pressing on price-sensitive diagnostic segments. Three archetypes dominate: premium-tier implantable system providers, mid-market imaging equipment specialists, and localized service-intensive EEG manufacturers. Consolidation pressure operates through strategic partnerships for regulatory navigation and capacity expansion in tier-two city service networks.
Among multinational neuromodulation providers, Medtronic PLC and Abbott Laboratories occupy positions exemplifying premium-tier implantable system strategies, while Stryker Corporation represents the integrated surgical instruments archetype. Domestic challengers Mindray Medical International and Lepu Medical Technology exemplify the localized manufacturing and service network model pressuring margins in mature diagnostic categories.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker Corporation |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Johnson and Johnson |
| MicroPort Scientific |
| B. Braun Melsungen AG |
| Mindray Medical International |
| Lepu Medical Technology |
| Others |
Value Chain & Pricing Dynamics
MIIT's dual carbon goals for manufacturing energy efficiency gate qualified supply access and premium-tier pricing power for neurology device producers in China. NMPA's GB standards for active implantable devices extend facility certification timelines, compressing margins for domestic manufacturers while multinationals with established quality systems capture pricing premiums through faster market entry.
Pricing Analysis
Hospital procurement committees are unbundling after-sales service from device pricing, creating transparent cost structures for maintenance and algorithm updates. Three-tier pricing structure across premium, standard, and economy levels separates multinational implantable systems from mid-market imaging equipment and domestic EEG manufacturers. Pricing pressure stems from provincial centralized procurement shifts, with tier-two hospitals exhibiting highest price sensitivity and Beijing-Shanghai tertiary centers least sensitive due to neurosurgery department budgets and reimbursement coverage.
Supply Chain Analysis
Direct-to-hospital channels handle tier-one tertiary demand while distributor networks serve tier-two city expansion. Biocompatible polymers and precision microelectronics for implantable devices draw from concentrated supplier bases in China's coastal manufacturing zones, with Japan and Germany providing specialized components. Single-source vulnerability runs through Shenzhen's microelectrode array ecosystem and Suzhou's precision electronics clusters. Distribution runs through provincial GPOs and hospital procurement networks with divergent technical service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's neurology device market operates as a geographic-arbitrage play where NMPA's accelerated review timelines reward established manufacturers with faster market access versus the extended regulatory pathways in the United States and European Union.
For Market Incumbents: Anchor defensive positioning through backward integration into precision electronics manufacturing and exclusive hospital system partnerships in Beijing and Shanghai. Consolidate clinical affairs capabilities in Shanghai regulatory consulting clusters to filter emerging domestic challengers. Deepen service revenue streams via remote patient monitoring platforms that extend beyond device implantation cycles. For New Entrants and Emerging Players: Cloud-connected EEG platforms for neurology clinic chains represent the most penetrable white-space target, with Wuhan and Chengdu private clinic networks scaling fastest. Target tier-two city ambulatory diagnostic services where neurosurgery department density remains below saturation thresholds. Pursue telemedicine-linked go-to-market angles that leverage remote interpretation partnerships with rural hospital networks. For Investors and Strategic Acquirers: Roll-up economics work for domestic EEG and portable diagnostic specialists because provincial procurement fragmentation prevents scale concentration. Five-to-ten year viability hinges on NMPA innovation approval channel access and tier-two city service network density. Monitor GB standards harmonization progress toward international benchmarks as the primary inflection signal for multinational acquisition appetite.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Innovation Approval Channel Access | Breakthrough device designation compresses time-to-market for novel neurostimulation systems against standard review timelines. |
| Hospital System Partnership | Exclusive service contracts with Beijing and Shanghai tertiary centers lock out competitors through integrated neuromodulation system deployments. |
| Software Companion Development | Remote patient management platforms create recurring revenue beyond implantation through algorithm update subscriptions. |
| Reimbursement Strategy | Provincial coverage expansion for neuropathic pain indications accelerates patient access to spinal cord stimulation therapies. |
| Geographic Manufacturing Footprint | Suzhou and Hangzhou green facility certifications satisfy MIIT dual carbon mandates while positioning for tier-two city procurement. |
Study Parameters
Multiple input streams — hospital procurement database analysis, NMPA regulatory filing review, and neurosurgery department capacity surveys — were reconciled through bottom-up and top-down triangulation. Primary interviews with hospital purchasing committee members, biomedical engineers at tertiary centers, GPO contracts managers, and regulatory affairs consultants were validated against secondary sources including NMPA approval databases, provincial tender announcements, and MIIT facility certification records.
Historical neurostimulation and neuroimaging shipment data were cross-referenced against panel input from equipment vendors and service providers across the projection horizon. Segmentation modeling incorporated product type, technology modality, end-user facility tier, and clinical application dimensions. CAGRs were derived from installed base growth rates, replacement cycle compression, and reimbursement expansion trajectories, with neuroimaging field-strength upgrade demand and home-based monitoring platform adoption serving as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA technical guideline revisions and provincial centralized procurement policy shifts. Outputs reflect documented assumptions around regulatory approval timelines, reimbursement coding expansions, and hospital capital expenditure priorities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Ulnar Nerve Treatment Market
Neurology
Neurology Digital Therapeutics Market
Neurology
Brain Ischemia Market
Neurology
Global Neurology Clinical Trials Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
US Optic Neuritis Market
Neurology
Acute Repetitive Seizures Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Grand Mal Seizure Treatment Market
Neurology
Brain Aneurysm Treatment Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Global Narcolepsy Therapeutics Market
Neurology
Coma Diagnosis and Treatment Market
Neurology
Bell Palsy Treatment Market
Neurology
Occipital Nerve Block Treatment Market