
 Hydrocephalus Market | 2026-2036
Hydrocephalus Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocephalus Market Outlook
The global pool of fellowship-trained pediatric neurosurgeons is collapsing, constraining surgical capacity for ventriculoperitoneal shunt placements in underserved regions. Medtronic leverages its integrated neuroscience portfolio to sustain dominance in programmable valve systems across North American academic medical centers. Christoph Miethke GmbH & Co. KG anchors European market presence through precision-engineered gravitational shunt technologies. B. Braun SE competes on manufacturing scale, supplying cost-optimized shunt assemblies to hospital systems in Asia-Pacific markets.
Hydrocephalus denotes pathological cerebrospinal fluid accumulation within the ventricular system, managed through implanted diversion devices typically constructed from silicone elastomer with radiopaque markers and pressure-regulating valve mechanisms. The primary commercial purpose centers on preventing intracranial pressure elevation, neurological damage, and mortality across congenital, acquired, and normal-pressure patient populations. Shunt systems occupy the largest revenue pool given recurring replacement cycles and complication-driven revision surgeries, while endoscopic devices represent the fastest-growing segment as third ventriculostomy adoption expands in pediatric cases. Diagnostic imaging modalities command premium pricing in preoperative planning and postoperative monitoring workflows, with hospitals constituting the dominant end-user channel due to requisite neurosurgical infrastructure.
FDA 510(k) clearance pathways govern valve and catheter introductions in the United States, while EU MDR technical documentation requirements extend conformity assessment timelines for European market access. Japan's PMDA enforces stringent biocompatibility and durability testing protocols that filter lower-capability manufacturers from Asia's second-largest neurosurgical device market. Stakeholders must monitor evolving reimbursement thresholds for remote monitoring-enabled shunt systems as payers reassess value-based coverage criteria for chronic CSF management interventions.
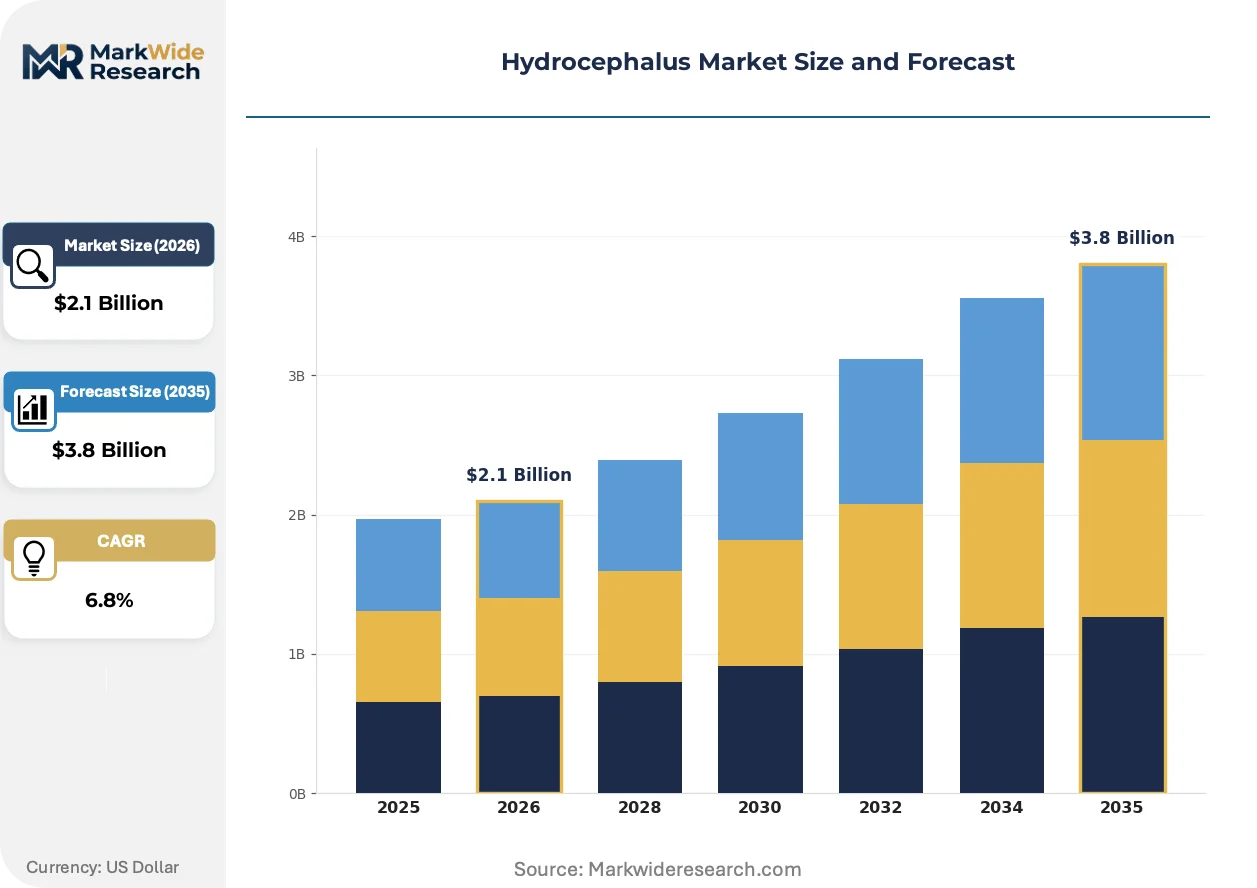
Market Dynamics
Programmable shunt valve technology is compressing revision surgery rates while EU MDR conformity timelines extend commercialization cycles for new entrants, creating asymmetric pressure on capital allocation across the competitive landscape.
Growth Catalysts
- Japan PMDA biocompatibility protocols:Stringent durability testing filters lower-capability manufacturers from Asia's second-largest neurosurgical device market, concentrating premium demand among validated suppliers.
- Pediatric tertiary hospitals:Fellowship-trained neurosurgical departments in academic medical centers drive adoption of advanced CSF management systems with integrated pressure monitoring capabilities.
- Silicone elastomer with radiopaque markers:Material innovations enabling precise catheter placement visualization are reducing operative time and postoperative imaging requirements.
Market Restraints
- FDA 510(k) notification backlog:Premarket clearance pathways for valve and catheter introductions create extended timelines between development completion and revenue recognition.
- Platinum-cured silicone supply concentration:Medical-grade elastomer sourcing depends on a narrow supplier base in Germany and the United States, exposing manufacturers to input volatility.
- Endoscopic third ventriculostomy substitution:Minimally invasive cerebrospinal fluid diversion without implanted hardware threatens long-term shunt system volume in congenital pediatric cases.
Strategic Opportunities
- Remote monitoring-enabled shunt systems:Wireless intracranial pressure telemetry creates value-based reimbursement opportunities as United States payers reassess chronic CSF management coverage criteria.
- Gravitational valve technology convergence:Integration of body-position-responsive flow regulation with programmable pressure settings addresses overdrainage complications in ambulatory patients.
- India neurosurgical infrastructure expansion:Underpenetrated tertiary hospital development in metropolitan corridors creates channel entry points for cost-optimized shunt assemblies.
Industry Challenges
- Fellowship-trained pediatric neurosurgeon scarcity:Collapsing global specialist pipeline constrains surgical capacity for ventriculoperitoneal shunt placements in underserved regions.
- EU MDR technical documentation burden:Extended conformity assessment timelines for European market access compress working capital efficiency during product launch phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocephalus Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shunts, Endoscopic Devices, Diagnostic Imaging, Catheters Therapy Area: Pediatric Neurosurgery, Adult Neurology, Emergency Care, Rehabilitation End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Clinics, Research Institutions Delivery Mode: Invasive Procedures, Non-invasive Techniques, Outpatient Services, Remote Monitoring |
| Companies Covered | Sophysa, Johnson & Johnson, Medtronic, Christoph Miethke GmbH & Co. KG, Natus Medical, Integra LifeSciences, Spiegelberg GmbH & Co. KG, Tokibo Co., Ltd., B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocephalus Market Strategic Shifts
Wireless telemetry integration is redefining postoperative monitoring protocols while regulatory convergence pressures manufacturers to harmonize quality systems across multiple jurisdictions simultaneously.
Smart shunt systems incorporating intracranial pressure sensors with Bluetooth Low Energy transmission are supplanting passive mechanical valves in pediatric neurosurgery departments. Academic medical centers in the United States and Germany are piloting these devices for ambulatory pressure trending. The technology is compressing emergency department utilization for suspected shunt malfunction while creating new data infrastructure requirements.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for European market access. Notified bodies now demand expanded clinical evidence for legacy device recertifications. Small and mid-cap manufacturers are responding through strategic partnerships with contract research organizations to share regulatory burden.
Hospital procurement committees are consolidating vendor relationships for CSF management devices around integrated supply agreements. Single-source contracts bundling shunt hardware, endoscopic instruments, and imaging accessories are displacing product-specific purchasing in United States health systems. This concentration is most visible in California and Texas integrated delivery networks where neurosurgical service line consolidation has accelerated.
Hydrocephalus Market Segmentation
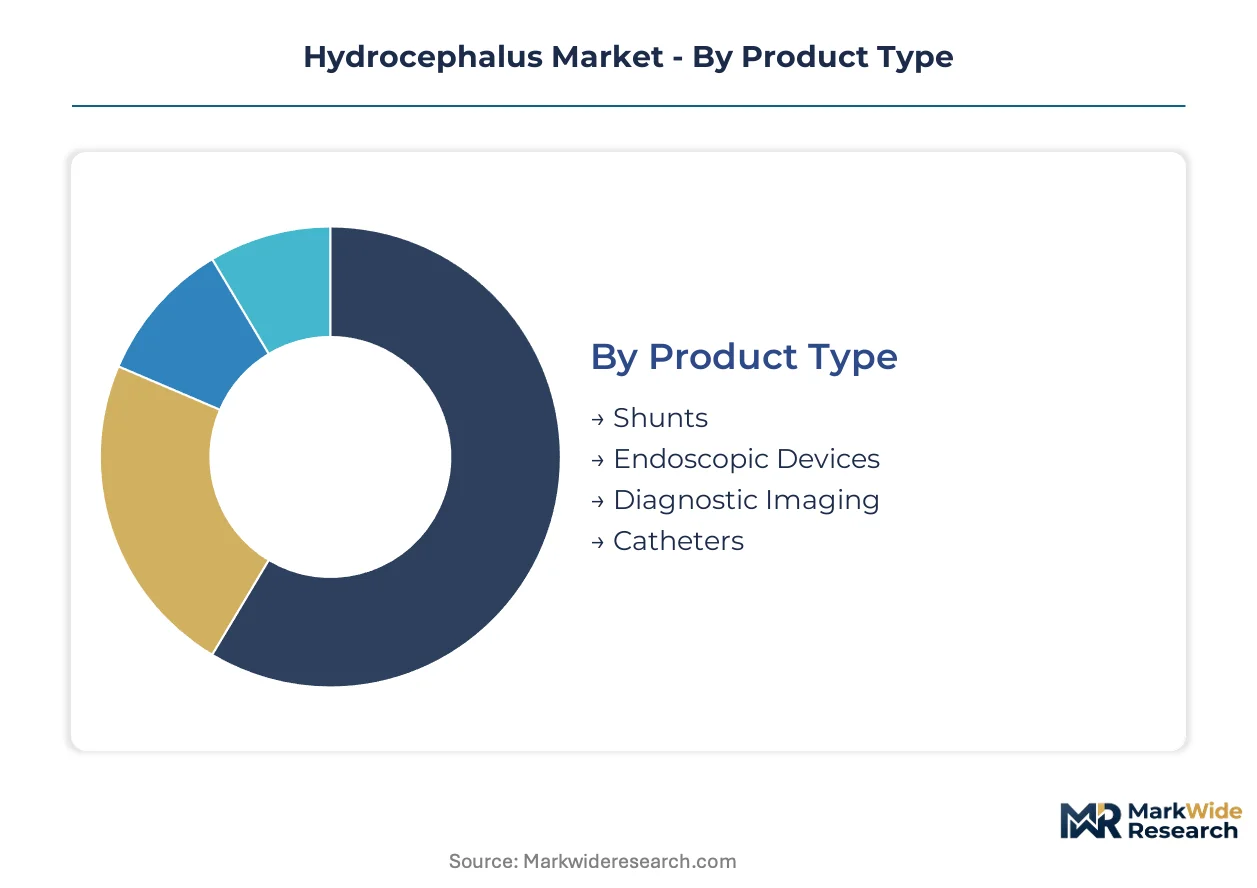
Product heterogeneity in hydrocephalus management creates divergent substitution pressures across segments, with implantable hardware facing erosion from endoscopic alternatives while diagnostic modalities expand into chronic monitoring workflows. Understanding segment-level competitive dynamics reveals where capital allocation concentrates and which technologies face imminent displacement.
Product Type:
Endoscopic third ventriculostomy exerts the strongest substitution pressure on implanted shunt systems, compressing volume in congenital pediatric cases while driving complementary demand for intraoperative navigation tools.
- Shunts:Silicone elastomer diversion systems with pressure-regulating valves and radiopaque catheter markers constitute the revenue foundation. United States academic medical centers concentrate demand for programmable valves with integrated pressure monitoring, though revision surgery rates and complication-driven replacements sustain recurring revenue pools despite endoscopic substitution threats.
- Endoscopic Devices:Minimally invasive cerebrospinal fluid diversion instruments including neuroendoscopes, ventricular catheters, and third ventriculostomy tools are expanding fastest in pediatric tertiary hospitals. Germany and Japan lead adoption where fellowship-trained specialists cluster, with body-position-responsive flow regulation now converging with programmable settings to address overdrainage in ambulatory patients.
- Diagnostic Imaging:Preoperative planning and postoperative monitoring modalities command premium pricing in hospital workflows.
- Catheters:Silicone-based ventricular and peritoneal drainage components with radiopaque visualization markers reduce operative time.
Shunt systems anchor the volume base while endoscopic devices gain share at the steepest rate.
Therapy Area:
Cost tier stratification separates emergency interventions from chronic management, with reimbursement intensity highest in pediatric neurosurgery and lowest in rehabilitation settings.
- Pediatric Neurosurgery:Congenital and early-onset hydrocephalus management drives adoption of advanced programmable valve systems with wireless telemetry. United States tertiary hospitals concentrate surgical volume where FDA 510(k) cleared devices compete on integrated pressure monitoring capabilities, though collapsing fellowship-trained specialist pipelines constrain capacity expansion.
- Adult Neurology:Normal-pressure and acquired hydrocephalus in aging populations creates demand for gravitational valve technologies that respond to body position changes. Japanese PMDA biocompatibility protocols filter lower-capability manufacturers, concentrating premium supply among validated German and United States suppliers.
- Emergency Care:Acute intracranial pressure elevation interventions require rapid-deployment external ventricular drainage systems.
- Rehabilitation:Post-surgical monitoring and long-term patient management creates secondary demand for diagnostic follow-up.
Pediatric neurosurgery commands the premium tier while adult neurology expands most quickly as aging demographics shift case mix.
End User:
Customer type determines procurement sophistication, with hospital systems leveraging integrated supply agreements against fragmented ambulatory purchasing.
- Hospitals:Tertiary academic medical centers with fellowship-trained neurosurgical departments dominate CSF management device procurement, consolidating vendor relationships around single-source contracts bundling shunt hardware, endoscopic instruments, and imaging accessories. California and Texas integrated delivery networks exhibit the most pronounced concentration.
- Ambulatory Surgical Centers:Cost-optimized shunt assemblies and streamlined diagnostic protocols serve lower-acuity cases.
- Rehabilitation Clinics:Postoperative monitoring and patient follow-up create demand for non-invasive assessment tools.
- Research Institutions:Clinical trial infrastructure and device development partnerships drive early-stage technology validation.
Hospitals capture the dominant revenue share while ambulatory surgical centers climb the fastest as case migration accelerates.
Delivery Mode:
Supply concentration in platinum-cured silicone sourcing from Germany and United States manufacturers shapes which delivery modalities achieve cost scalability.
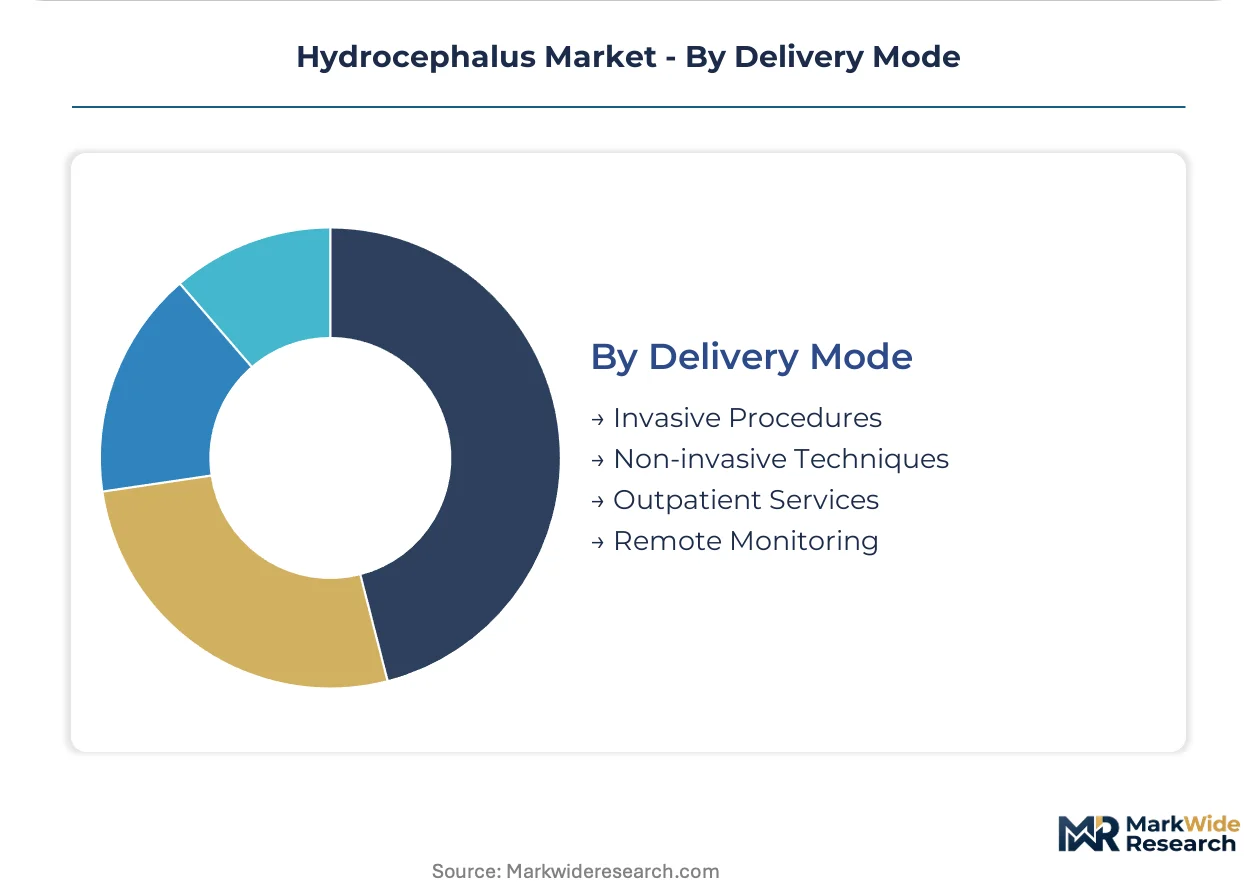
- Invasive Procedures:Ventriculoperitoneal shunt placement and endoscopic third ventriculostomy constitute the procedural foundation, with EU MDR conformity assessment timelines extending commercialization cycles for new valve and catheter introductions. Notified body demands for expanded clinical evidence compress working capital efficiency during launch phases.
- Non-invasive Techniques:Diagnostic imaging and external pressure monitoring reduce hardware dependency.
- Outpatient Services:Postoperative surveillance and routine shunt pressure adjustments shift volume from inpatient settings.
- Remote Monitoring:Wireless intracranial pressure telemetry with Bluetooth Low Energy transmission is supplanting passive mechanical valves in pilot programs. United States payers are reassessing value-based coverage criteria for chronic CSF management as ambulatory pressure trending compresses emergency department utilization.
Invasive procedures sustain the volume foundation while remote monitoring achieves the steepest expansion trajectory as reimbursement frameworks adapt.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways anchor commercialization timelines in the United States, while EU MDR conformity assessments and Japan PMDA biocompatibility protocols filter market access across the three dominant geographies.
United States
Academic medical centers in California and Texas concentrate demand for programmable valve systems with wireless telemetry capabilities. FDA 510(k) clearance pathways govern valve and catheter introductions, creating extended timelines between development completion and revenue recognition. Pediatric neurosurgery departments in tertiary hospitals drive adoption of advanced CSF management systems.
Germany
Precision-engineered gravitational shunt technologies command premium positioning in European markets. EU MDR technical documentation requirements extend conformity assessment timelines, compressing working capital efficiency during product launch phases. Industrial clusters in Baden-Württemberg and Bavaria host specialized manufacturers supplying radiopaque catheter assemblies.
Japan
PMDA enforces stringent biocompatibility and durability testing protocols that filter lower-capability manufacturers from Asia's second-largest neurosurgical device market. Fellowship-trained pediatric neurosurgeons cluster in Tokyo and Osaka metropolitan corridors. Gravitational valve technologies for adult normal-pressure hydrocephalus management expand fastest in aging demographic segments.
India
Underpenetrated tertiary hospital development in Maharashtra and Karnataka metropolitan corridors creates channel entry points for cost-optimized shunt assemblies. CDSCO medical device regulations govern import and manufacturing compliance for silicone elastomer components. Domestic procurement committees increasingly consolidate vendor relationships around integrated supply agreements.
United Kingdom
NHS England reimbursement frameworks for chronic CSF management devices shape demand concentration in London and Southeast academic medical centers. MHRA post-Brexit regulatory alignment with EU MDR extends conformity assessment burdens for new market entrants. Pediatric neurosurgery departments in Manchester and Birmingham drive adoption of endoscopic third ventriculostomy instruments.
Hydrocephalus Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the hydrocephalus device landscape. The vendor base concentrates around three strategic tiers: integrated neuroscience portfolios sustaining dominance in programmable valve systems, precision-engineered specialists anchoring European gravitational technologies, and scale-driven manufacturers supplying cost-optimized assemblies to emerging markets. Competitive dynamics center on M&A activity consolidating hospital procurement relationships and strategic partnerships sharing regulatory burden for EU MDR compliance.
Within the integrated portfolio tier, Medtronic and Johnson & Johnson occupy positions representing technology leadership through comprehensive neuroscience divisions. Christoph Miethke GmbH & Co. KG exemplifies the European precision-engineering archetype, while B. Braun SE anchors scale-driven manufacturing capabilities serving Asia-Pacific cost optimization requirements.
| Leading Market Players |
|---|
| Sophysa |
| Johnson & Johnson |
| Medtronic |
| Christoph Miethke GmbH & Co. KG |
| Natus Medical |
| Integra LifeSciences |
| Spiegelberg GmbH & Co. KG |
| Tokibo Co., Ltd. |
| B. Braun SE |
| Others |
Value Chain & Pricing Dynamics
Endoscopic third ventriculostomy substitution for congenital pediatric cases simultaneously redistributes procurement volume toward navigation instruments and compresses shunt hardware pricing power in tertiary hospital systems. This demand migration concentrates premium pricing in intraoperative imaging while standard shunt assemblies face cost optimization pressures across Asia-Pacific procurement committees.
Pricing Analysis
United States academic medical centers command 40-60% premiums over India metropolitan hospital systems for programmable valve systems with equivalent pressure regulation specifications. Three-tier pricing structure across premium, standard, and economy levels segments by FDA 510(k) clearance tier and integrated telemetry capability. Cost compression in economy-tier shunt assemblies is intensifying because B. Braun SE and domestic Indian manufacturers scale silicone elastomer production for CDSCO-compliant devices. Pediatric neurosurgery departments exhibit lowest price sensitivity given outcome-critical procurement mandates, while rehabilitation clinics and ambulatory surgical centers demonstrate highest sensitivity to per-unit hardware costs.
Supply Chain Analysis
Platinum-cured silicone precursor manufacturing concentrates in Baden-Württemberg industrial clusters and select United States chemical processing corridors, creating single-source vulnerability for medical-grade elastomer specifications. Raw material dependencies center on silicone monomers, radiopaque barium sulfate fillers, and titanium valve housing alloys sourced from Germany, Japan, and China. Tariff exposure on Chinese-sourced titanium components threatens margin stability for European valve assemblers. Distribution runs through hospital procurement committees consolidating vendor relationships around integrated supply agreements bundling shunt hardware with endoscopic instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
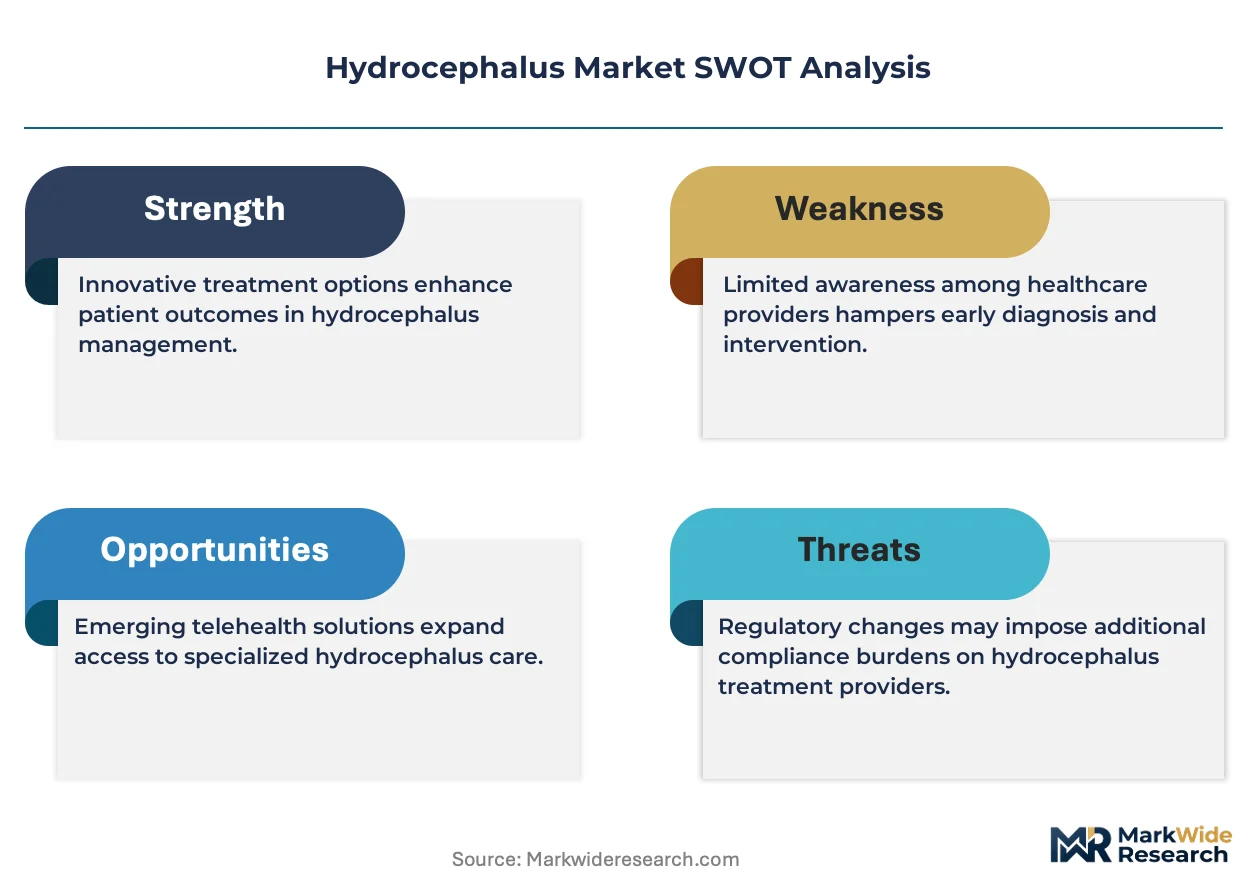
Market fragmentation creates entry niches as wireless telemetry integration splits demand between established programmable valve incumbents and sensor-technology specialists. Fellowship-trained neurosurgeon scarcity constrains surgical capacity, opening service-model opportunities alongside hardware supply.
For Market Incumbents: Shield programmable valve market position by deepening backward integration into silicone elastomer compounding and securing exclusive hospital system partnerships in California and Texas integrated delivery networks. Invest in FDA 510(k) clearance for next-generation Bluetooth Low Energy pressure telemetry before EU MDR recertification burdens compress competitor working capital. Channel control through single-source contracts bundling imaging accessories represents the critical defensive lever against gravitational valve technology convergence. For New Entrants and Emerging Players: FDA Breakthrough Device Designation fast-track for wireless intracranial pressure monitoring systems opens regulatory pathway acceleration against entrenched mechanical valve portfolios. Target India metropolitan tertiary hospital development in Maharashtra and Karnataka corridors with CDSCO-compliant cost-optimized shunt assemblies. Go-to-market angle should emphasize remote monitoring value-based reimbursement readiness as United States payers reassess chronic CSF management coverage criteria. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European precision valve specialists facing EU MDR technical documentation cost escalation. Long-term viability over the intermediate investment horizon rests on gravitational technology convergence and ambulatory pressure telemetry adoption curves. Acquisition target archetype: mid-cap German or Japanese manufacturers with validated PMDA biocompatibility protocols and underexploited Asia-Pacific distribution. Signal to watch: CMS reimbursement code establishment for remote monitoring-enabled shunt systems as inflection indicator for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Partnership | Shared regulatory burden with contract research organizations accelerates conformity assessment timelines for valve recertifications. |
| Wireless Telemetry FDA Submission | Bluetooth Low Energy pressure monitoring secures 510(k) clearance ahead of reimbursement code establishment by CMS. |
| India Manufacturing Footprint Expansion | Domestic silicone elastomer compounding for CDSCO compliance reduces tariff exposure and procurement committee cost barriers. |
| Gravitational-Programmable Valve Convergence | Body-position-responsive flow regulation integration addresses overdrainage complications in ambulatory normal-pressure hydrocephalus patients. |
| Hospital System Integrated Supply Agreement | Single-source contracts bundling shunt hardware with endoscopic instruments lock out competitor access in California and Texas IDNs. |
Study Parameters
A standing panel of pediatric neurosurgeons, hospital procurement committee directors, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) clearance databases, PMDA biocompatibility filing records, CMS Medicare reimbursement data, and EU MDR notified body conformity assessment timelines. Bottom-up demand modeling for shunt replacement cycles and revision surgery rates triangulated against top-down neurosurgical device market estimates.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include product type hierarchy, therapy area stratification, end-user procurement sophistication, and delivery mode technology readiness. CAGRs derived from surgical volume projections, replacement cycle frequencies, and pricing tier migration patterns. Industry-specific forecast inputs incorporated fellowship-trained specialist pipeline collapse rates and remote monitoring reimbursement policy evolution.
Decision-makers should treat outputs as directional under assumptions of stable FDA 510(k) clearance timelines and sustained United States payer value-based coverage expansion; material deviation in EU MDR notified body capacity or Japan PMDA biocompaticity protocol stringency would warrant model refresh. Practitioners should keep alternative scenarios live as endoscopic third ventriculostomy substitution rates and wireless telemetry clinical evidence accumulation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Optic Neuropathy Management Market
Neurology
Netherlands Neurology Devices Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Mexico Neurology Devices Market
Neurology
CNS Treatment and Therapy Market
Neurology
Brain Ischemia Market
Neurology
Chiari Malformation Treatment Market
Neurology
United Kingdom Neurology Devices Market
Neurology
Parkinsons Disease Therapeutics Market
Neurology
Europe Neurology Monitoring Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Acute Repetitive Seizures Market
Neurology
South Korea Neurology Devices Market
Neurology
India Neurology Devices Market
Neurology
Vocal Cord Paralysis Market