
 Vocal Cord Paralysis Market | 2026-2036
Vocal Cord Paralysis Market Size, Share, and Industry Trends Forecast 2026-2036
Vocal Cord Paralysis Market Outlook
Hospital procurement channels for laryngeal implants is rewriting competitive access rules across the Vocal Cord Paralysis Market. Medtronic leverages its entrenched ENT sales infrastructure to sustain preferential contracting with integrated delivery networks. Boston Scientific Corporation competes through specialized reimbursement navigation support that anchors its position in academic medical centers.
Vocal cord paralysis denotes the immobilization of one or both vocal folds due to recurrent laryngeal nerve injury, idiopathic neuropathy, or iatrogenic trauma during thyroid or cardiac surgery, resulting in impaired glottal closure and compromised airway protection during deglutition. The condition demands intervention to restore phonatory efficiency, pulmonary aspiration prevention, or both, depending on whether the impairment is unilateral or bilateral. Injectable therapies occupy the most mature margin pool within product type segmentation, while surgical procedures—particularly thyroplasty and arytenoid adduction—represent the fastest-growing revenue category as patients seek durable structural correction over temporary chemodenervation. Among end users, rehabilitation centers are expanding their share of post-surgical voice therapy protocols, though hospitals retain dominant billing capture for the highest-acuity interventions.
The FDA regulates laryngeal implants as Class II or Class III medical devices under 510(k) and PMA pathways, with breakthrough device designation increasingly shaping premarket strategy for novel bioresorbable injectables. The Centers for Medicare & Medicaid Services controls reimbursement thresholds that directly determine site-of-service economics for thyroplasty and medialization laryngoplasty procedures. Stakeholders must monitor whether CMS will extend transitional pass-through payment status to next-generation implantable laryngeal prostheses as outpatient procedural volume shifts accelerate.
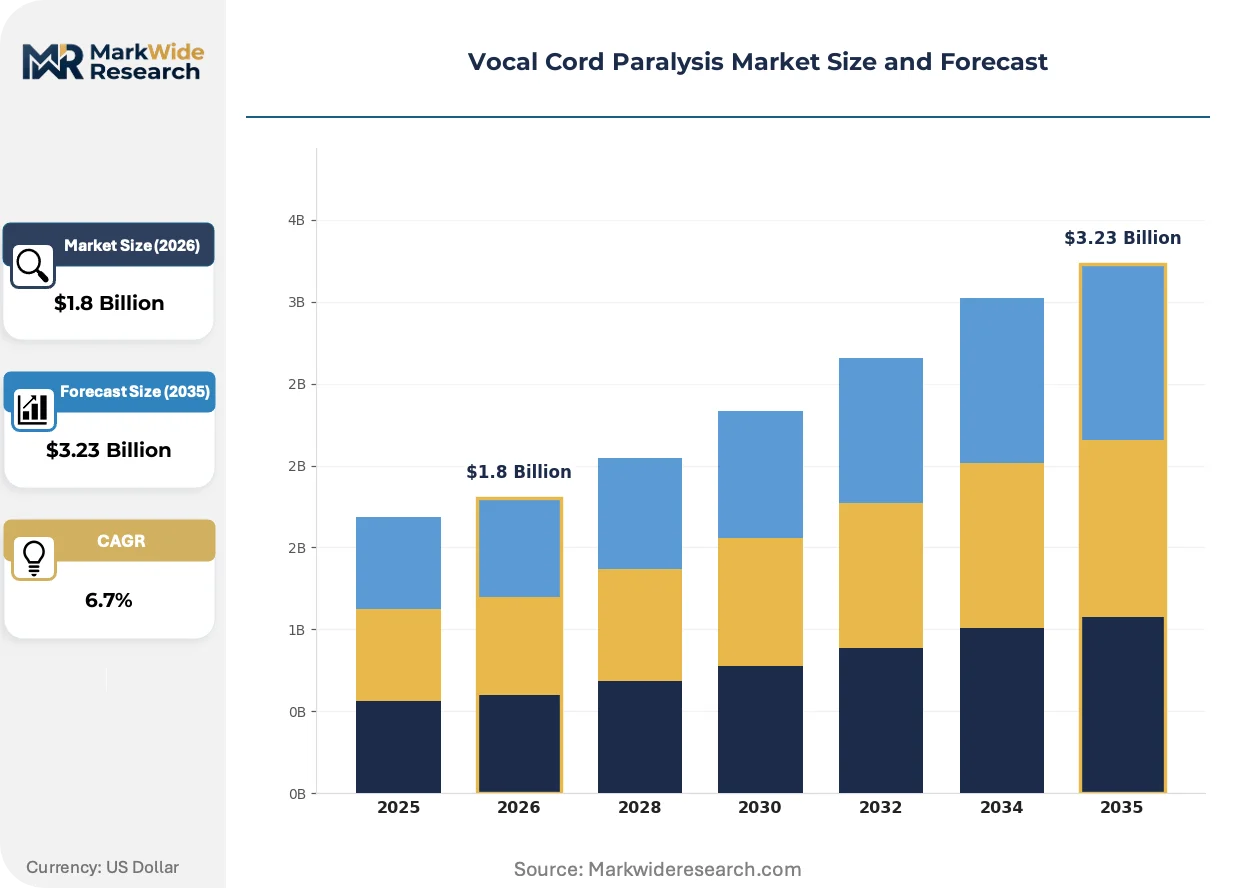
Market Dynamics
Hospital procurement consolidation is concentrating purchasing power for laryngeal implants into fewer integrated delivery networks, forcing device manufacturers to restructure contracting strategies around bundled procedural episodes rather than standalone product sales.
Growth Catalysts
- Breakthrough Device Designation:The FDA's accelerated pathway for novel laryngeal implants compresses time-to-market for bioresorbable injectables, incentivizing R&D investment in durable structural solutions.
- Tertiary Referral Center Expansion:Academic medical centers in the United States are building dedicated laryngology service lines to capture complex airway reconstruction cases.
- Medialization Laryngoplasty:Patient preference for permanent vocal fold medialization over temporary chemodenervation is shifting procedure mix toward implant-based interventions.
Market Restraints
- Silicone Implant Cost Volatility:Raw material price fluctuations for medical-grade silicone directly compress margins on thyroplasty implants.
- Single-Country Supply Concentration:Domestic manufacturing of laryngeal prostheses clusters heavily in the United States, exposing buyers to localized disruption risks.
- CMS Reimbursement Compression:Medicare's site-neutral payment policies create friction against outpatient procedural migration for laryngeal interventions.
Strategic Opportunities
- Underpenetrated Ambulatory Surgery Centers:United States-based ASCs remain underserved for select medialization procedures, creating white space for site-of-service expansion.
- Regenerative Injectable Convergence:Cross-pollination between tissue engineering and laryngeal surgery opens pathways for autologous cell-based vocal fold augmentation.
- Telehealth-Enabled Voice Therapy:Post-surgical rehabilitation protocols are integrating remote monitoring platforms to extend care continuity beyond traditional clinic visits.
Industry Challenges
- Laryngology Fellowship Pipeline:The limited number of accredited fellowship programs constrains specialist supply for complex airway reconstruction.
- Implant-Device Integration Complexity:Legacy electronic health record systems in United States hospitals resist seamless incorporation of implant tracking for laryngeal prostheses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vocal Cord Paralysis Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Therapies, Surgical Procedures, Voice Therapy, Medical Devices End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Treatment Method: Botulinum Toxin, Phonosurgery, Thyroplasty, Speech Therapy Severity Level: Mild, Moderate, Severe, Progressive |
| Companies Covered | Teleflex Incorporated, Smiths Group, Stryker, Siemens Healthineers AG, Boston Scientific Corporation, Karl Storz SE & Co. KG, Medtronic, Intuitive Surgical Inc., Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vocal Cord Paralysis Market Strategic Shifts
Bioresorbable materials and digital surgical planning are compressing the traditional boundary between temporary and permanent interventions in vocal cord paralysis treatment, forcing incumbents to recalibrate product portfolio architecture.
Injectable calcium hydroxylapatite microspheres are collapsing the distinction between office-based temporary augmentation and operating-room structural medialization. United States-based otolaryngology practices are adopting these materials for intermediate-duration phonatory restoration. The technology is collapsing revenue segmentation between injectable and implantable product categories.
CMS site-neutral payment reforms are redistributing procedural economics across ambulatory settings. The policy compresses reimbursement premiums historically attached to hospital-based thyroplasty. United States academic medical centers are responding by unbundling voice therapy from surgical episodes.
Voice outcome measurement tools are reshaping procurement criteria for laryngeal implants. United States otolaryngology departments now require objective acoustic and aerodynamic data as contract preconditions. The shift privileges manufacturers with validated post-market surveillance infrastructure over commodity suppliers.
Vocal Cord Paralysis Market Segmentation
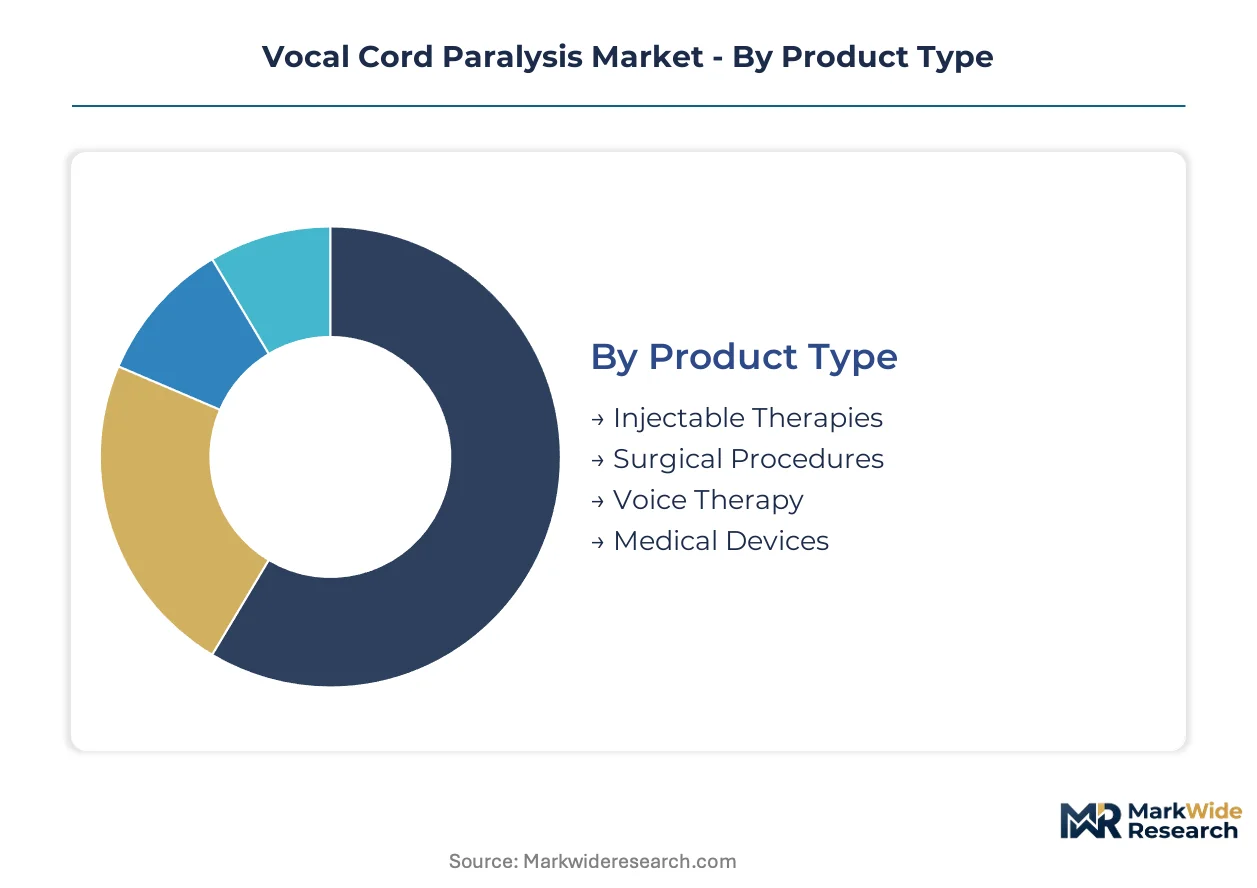
Segmentation in the Vocal Cord Paralysis Market reveals divergent margin profiles across intervention types. Injectable therapies command repeat-purchase revenue streams while surgical procedures capture durable structural correction premiums.
Product Type:
Cycle times vary dramatically across product categories, with injectable therapies turning over quarterly versus surgical implants delivering multi-year revenue recognition.
- Injectable Therapies:Calcium hydroxylapatite microspheres and collagen-based formulations enable office-based vocal fold augmentation. United States otolaryngology practices favor these for intermediate-duration phonatory restoration, balancing convenience against durability trade-offs.
- Surgical Procedures:Thyroplasty and arytenoid adduction demand operating-room infrastructure and specialized laryngology fellowship training. Academic medical centers in the United States concentrate the highest procedural volumes for these permanent structural interventions.
- Voice Therapy:Post-surgical rehabilitation protocols integrate acoustic biofeedback and telehealth monitoring platforms.
- Medical Devices:Implantable laryngeal prostheses require PMA or 510(k) FDA clearance pathways.
Injectable therapies anchor the volume base while surgical procedures gain share at the steepest rate.
End User:
Cost tiers stratify sharply across care settings, with hospital-based surgical episodes commanding premium reimbursement against lower-intensity clinic and home-based alternatives.
- Hospitals:Tertiary referral centers dominate billing capture for high-acuity thyroplasty and bilateral vocal fold reconstruction. CMS site-neutral payment reforms are compressing historical reimbursement premiums attached to inpatient laryngeal surgery.
- Clinics:Office-based practices concentrate injectable augmentation volume and initial diagnostic laryngoscopy. United States-based otolaryngology clinics are expanding in-office procedural capacity to capture site-of-service economics.
- Rehabilitation Centers:Post-surgical voice therapy protocols are expanding their share of care continuity.
- Home Care:Telehealth-enabled platforms extend remote monitoring for post-operative voice outcomes.
Hospitals retain the highest revenue per episode while clinics expand visit volume most aggressively.
Treatment Method:
Application logic separates temporary neuromodulation from permanent structural correction, with patient selection criteria driving distinct site-of-service requirements.
- Botulinum Toxin:Chemodenervation targets spasmodic dysphonia and select unilateral vocal fold paralysis cases requiring temporary medialization. United States-based laryngology practices administer these injections in office settings with minimal anesthesia support.
- Phonosurgery:Microflap techniques and laser excision address concurrent benign vocal fold lesions. Academic medical centers with dedicated voice centers capture complex phonosurgical cases requiring intraoperative laryngeal electromyography.
- Thyroplasty:Medialization laryngoplasty with silicone or Gore-Tex implants delivers permanent glottal closure.
- Speech Therapy:Behavioral intervention targets compensatory phonatory strategies and pulmonary aspiration prevention.
Thyroplasty carries the highest procedural reimbursement while phonosurgical volume climbs fastest among academic referral networks.
Severity Level:
Customer type stratification maps directly to intervention intensity, with progressive and severe cases demanding multidisciplinary airway reconstruction versus mild presentations managed conservatively.
- Mild:Unilateral vocal fold paresis with preserved phonatory compensation responds to voice therapy and watchful observation. United States-based otolaryngology practices triage these cases to clinic-based management pathways.
- Moderate:Impaired glottal closure with aspiration risk drives injectable augmentation demand. Rehabilitation centers in the United States are expanding their role in post-intervention voice therapy for this severity tier.
- Severe:Complete immobility demands surgical medialization or laryngeal framework reconstruction.
- Progressive:Neuromuscular etiologies such as amyotrophic lateral sclerosis require iterative intervention escalation.
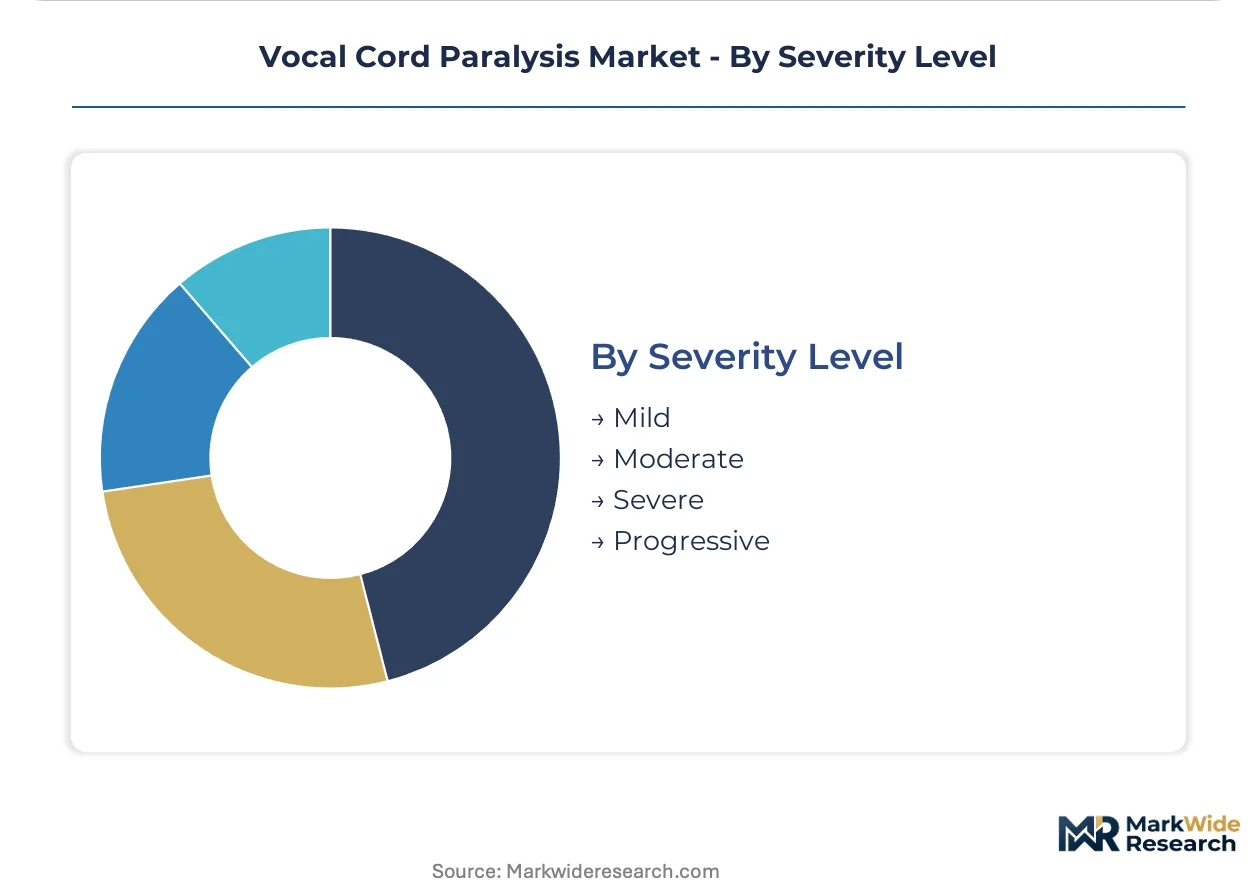
Moderate severity generates the highest case volume while progressive presentations drive the most complex multidisciplinary resource allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulatory pathways anchor the United States as the dominant geography, with Medicare reimbursement thresholds shaping procedural economics across hospital networks and ambulatory settings.
United States
Tertiary referral centers in Boston, New York, and Los Angeles concentrate the highest laryngology procedural volumes. CMS site-neutral payment reforms compress reimbursement premiums historically attached to hospital-based thyroplasty. The Southeast corridor from Atlanta to Miami expands ambulatory surgery center capacity for medialization procedures.
Germany
Academic medical centers in Munich and Heidelberg drive adoption of advanced phonosurgical techniques. EMA medical device regulations under MDR framework govern laryngeal implant market access timelines. The Baden-Württemberg cluster anchors precision manufacturing supply chains for medical-grade silicone components.
Japan
Aging demographics elevate demand for aspiration prevention interventions in Tokyo and Osaka metropolitan areas. PMDA breakthrough designation pathways accelerate review timelines for novel bioresorbable injectables. The Nagoya medical device corridor concentrates domestic manufacturing of laryngeal prostheses.
United Kingdom
NHS England specialized commissioning frameworks concentrate complex airway reconstruction in London and Manchester tertiary centers. MHRA post-Brexit regulatory autonomy reshapes conformity assessment routes for implantable devices. The Cambridge-Oxford-London golden triangle anchors voice outcome research and clinical validation studies.
India
Rising thyroid surgery volumes in Delhi-NCR and Mumbai generate iatrogenic recurrent laryngeal nerve injury cases requiring intervention. CDSCO medical device rules govern import licensing for foreign-manufactured laryngeal implants. The Bengaluru medical technology cluster incubates domestic manufacturing capabilities for cost-sensitive implant segments.
Vocal Cord Paralysis Market Competitive Environment
Diversified surgical conglomerates and specialized ENT device manufacturers split the market into distinct capability tiers. The vendor base concentrates around established hospital contracting relationships rather than technology differentiation alone. Three archetypes dominate: integrated surgical platforms with broad ENT portfolios, laryngology-focused specialists with deep reimbursement expertise, and emerging players leveraging breakthrough designation pathways. Competitive intensity manifests through bundled procedural contracting and site-of-service expansion into ambulatory settings.
Among diversified surgical platform providers, Medtronic and Stryker occupy positions anchored by entrenched hospital procurement relationships and broad service line integration. Boston Scientific Corporation exemplifies the reimbursement-navigation specialist archetype, with academic medical center concentration reflecting its strategic positioning. Karl Storz SE & Co. KG represents the visualization-technology pathway into laryngeal intervention workflows.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Smiths Group |
| Stryker |
| Siemens Healthineers AG |
| Boston Scientific Corporation |
| Karl Storz SE & Co. KG |
| Medtronic |
| Intuitive Surgical Inc. |
| Olympus Corporation |
| Others |
Value Chain & Pricing Dynamics
Medical-grade silicone production clusters in the United States and Germany concentrate upstream supply for laryngeal implants, anchoring margin pools in premium thyroplasty devices while cost-sensitive injectables compete on volume economics.
Pricing Analysis
United States-based thyroplasty implants command price premiums over European and Asian equivalents due to FDA PMA pathway costs and specialized laryngology training requirements. Three-tier pricing structure across premium silicone implants, standard Gore-Tex medialization devices, and economy calcium hydroxylapatite injectables reflects certification grade and durability differentiation. Pricing pressure stems from CMS site-neutral payment reforms compressing hospital reimbursement premiums. Ambulatory surgery centers exhibit highest price sensitivity while academic medical centers prioritize outcome validation over unit cost.
Supply Chain Analysis
Teleflex Incorporated and Smiths Group hold contract-manufacturing capacity for implantable laryngeal prostheses, with production concentrated in the United States, Germany, and Japan. Raw material dependencies center on medical-grade silicone elastomers, bioresorbable polymer precursors, and precision-machined titanium components. Single-source vulnerability runs through specialized silicone formulation suppliers serving PMA-cleared device tiers. Distribution runs through integrated delivery network procurement channels and direct hospital contracting with GPO intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vocal Cord Paralysis Market rewards service-attach models where post-surgical voice therapy protocols and remote monitoring platforms expand recurring revenue faster than hardware implant sales alone.
For Market Incumbents: Entrench hospital system relationships through bundled procedural contracting that combines thyroplasty implants with voice therapy service lines. Deepen backward integration into medical-grade silicone compounding to defend against raw material cost volatility threatening implant margins. Prioritize FDA breakthrough device designation navigation support as emerging bioresorbable entrants threaten commoditization of permanent medialization devices.
For New Entrants and Emerging Players: Build out ambulatory surgery center partnerships in the United States Southeast corridor where site-of-service economics favor lower-cost medialization procedures. Target underpenetrated calcium hydroxylapatite injectable segments in office-based laryngology practices seeking intermediate-duration phonatory restoration. Deploy telehealth-enabled voice therapy platforms as differentiated go-to-market anchors that extend care continuity beyond implant placement.
For Investors and Strategic Acquirers: Capital is best deployed toward laryngology-focused specialists with deep CMS reimbursement expertise and established academic medical center concentration. Long-term viability hinges on portfolio breadth spanning temporary injectables through permanent implants with companion digital monitoring layers. Monitor FDA breakthrough device designation grants to bioresorbable injectable developers as inflection signals for structural medialization displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Device Designation Navigation | FDA accelerated pathways compress time-to-market for novel bioresorbable laryngeal implants. |
| Hospital System Partnership | Integrated delivery network contracting secures preferential access to high-acuity thyroplasty volumes. |
| Reimbursement Strategy | CMS site-neutral payment expertise determines ambulatory surgery center expansion viability. |
| Software Companion Development | Voice outcome measurement tools reshape procurement criteria toward validated post-market surveillance. |
| Backward Integration into Silicone Compounding | Captive supply of medical-grade elastomers defends margins against raw material price volatility. |
Study Parameters
The analysis maps injectable therapies, surgical procedures, voice therapy protocols, and implantable medical devices, each validated through laryngology fellowship directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Primary fieldwork combined with secondary validation from FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, hospital procurement records, and accredited fellowship program directories. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Assumptions held fixed include FDA regulatory pathway timelines, CMS site-neutral payment policy trajectories, and laryngology fellowship program graduation rates. Variable assumptions encompass bioresorbable material adoption curves, ambulatory surgery center procedural migration velocity, and telehealth reimbursement permanence. Segmentation dimensions modeled span product type, end user, treatment method, severity level, and geographic referral center density. CAGRs derived from logistic diffusion curves fitted to historical procedural adoption patterns with elasticity adjustments for reimbursement threshold effects.
Sensitivities concentrate around FDA breakthrough device designation grant velocity, CMS outpatient procedural payment parity implementation timing, and medical-grade silicone supply disruption scenarios. Forecasts reflect documented assumptions regarding specialist workforce expansion and patient preference shifts toward durable structural correction. Quarterly review of FDA PMA submission volumes, CMS proposed rulemaking dockets, and academic medical center service line announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Chronic Brain Damage Management Market
Neurology
Mild Cognitive Impairment Market
Neurology
Traumatic Brain Injuries Assessment Market
Neurology
Arachnoiditis Market
Neurology
Sweden Neurology Devices Market
Neurology
Neuroendocrine Carcinoma Market
Neurology
AIDS Related Primary CNS Lymphoma Market
Neurology
Europe Pediatric Neurology Device Market
Neurology
North America Neurology Devices Market
Neurology
CNS Lymphoma Market
Neurology
Parkinsons Disease Therapeutics Market
Neurology
Chile Neurology Devices Market
Neurology
US Optic Neuritis Market
Neurology
Mild Traumatic Brain Injury Treatment Market
Neurology
Optic Neuritis Treatment Market
Neurology
Lewy Body Dementia Treatment Market