
 Movement Disorder Market | 2026-2036
Movement Disorder Market Size, Share, and Industry Trends Forecast 2026-2036
Movement Disorder Market Outlook
Deep-brain stimulation programming services is reconfiguring margin pools away from hardware implantation toward recurring clinical optimization. Medtronic Plc leverages its installed base of neurostimulators to sustain high-margin follow-on revenue streams. AbbVie Inc. anchors its position through dopamine agonist portfolios that dominate oral pharmacotherapy for Parkinson's disease. Neurocrine Biosciences, Inc. differentiates via VMAT2 inhibitors that compete in the expanding tardive dyskinesia segment.
Movement disorders encompass pathological conditions—Parkinson's disease, essential tremor, dystonia, and Huntington's disease—characterized by impaired voluntary or involuntary motor control resulting from basal ganglia circuit dysfunction, with diagnosis relying on standardized rating scales such as the Unified Parkinson's Disease Rating Scale and objective kinematic gait analysis. Pharmacological interventions command the largest revenue share, though surgical approaches including deep-brain stimulation and focused ultrasound ablation are capturing faster growth as device efficacy data accumulates. Non-pharmacological therapies such as physiotherapy and speech pathology represent mature, lower-margin segments where reimbursement constraints limit expansion.
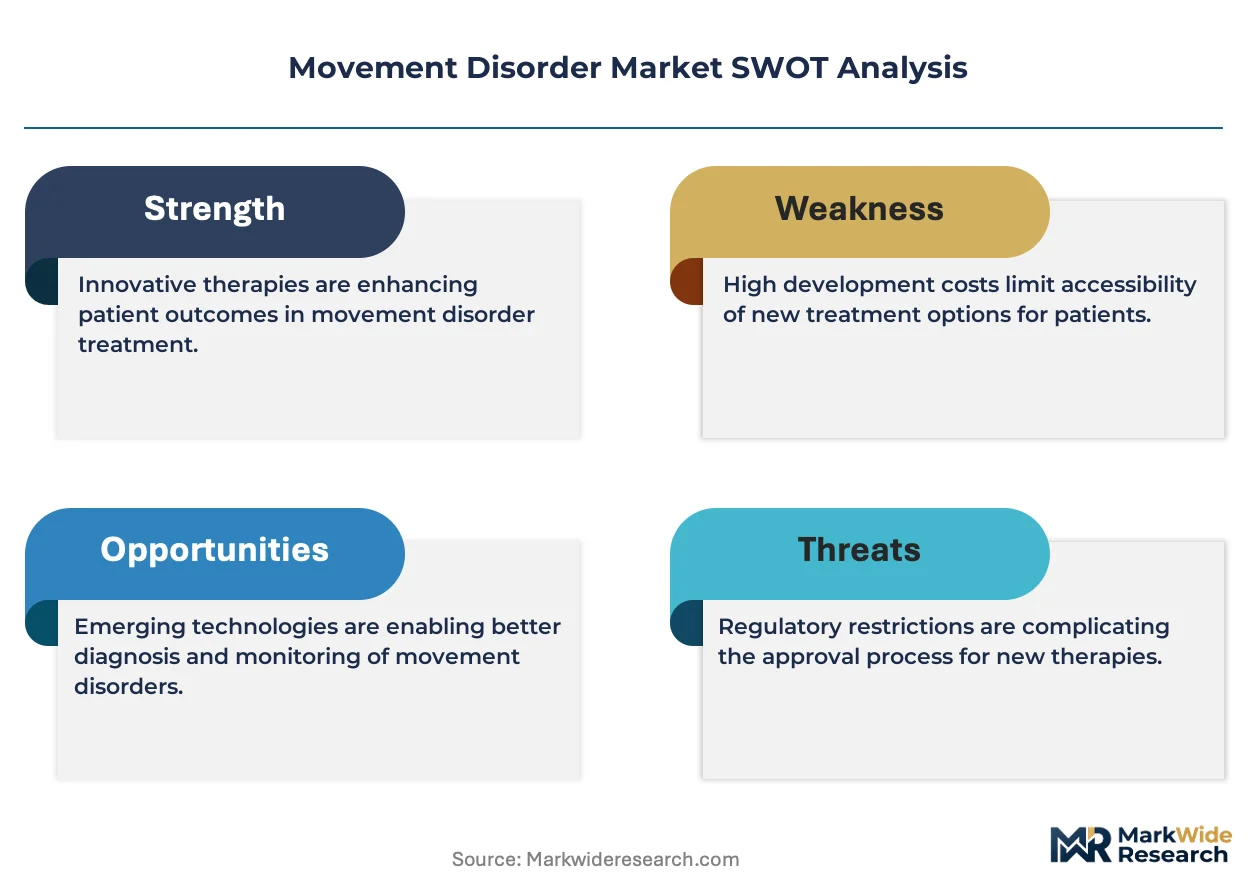
The FDA's breakthrough device pathway and EU MDR conformity requirements shape product development timelines and market access costs for device manufacturers, while the EMA and national health technology assessment bodies influence pricing and reimbursement for novel pharmacological entrants. The analysis indicates that stakeholders must monitor evolving CMS coverage determinations for closed-loop adaptive stimulation systems and prepare for parallel regulatory submissions across multiple jurisdictions to secure timely commercialization.
Market Dynamics
Deep-brain stimulation programming services are reconfiguring margin pools away from one-time hardware implantation toward recurring clinical optimization, forcing device manufacturers to build software capabilities and service infrastructure that sustain long-term revenue capture.
Growth Catalysts
- FDA Breakthrough Device Pathway:Accelerated review timelines for closed-loop adaptive neurostimulators compress commercialization cycles and reduce capital-at-risk for developers targeting treatment-resistant Parkinson's disease populations.
- Germany's specialized movement disorder centers:Hospital-based neurology departments in Bavaria and North Rhine-Westphalia are expanding device-assisted therapy suites, creating concentrated demand clusters for advanced surgical interventions.
- Closed-loop sensing technology:Real-time biomarker feedback systems enable automated stimulation adjustment, reducing patient programming burden while improving motor symptom control fidelity.
Market Restraints
- EU MDR conformity assessment costs:Enhanced clinical evidence requirements for implantable neurostimulators extend certification timelines and inflate regulatory expenditure for mid-tier manufacturers without legacy device portfolios.
- Titanium electrode supply concentration:Precision-machined lead components depend on a limited supplier base in Switzerland and Germany, exposing device makers to input cost volatility and single-source risk.
- Focused ultrasound ablation efficacy ceiling:Non-invasive lesioning techniques demonstrate durability limitations for bilateral interventions, constraining addressable patient populations in essential tremor segments.
Strategic Opportunities
- Japan's aging demographic bulge:The PMDA's streamlined approval track for devices with prior FDA clearance enables rapid market entry into the world's oldest population, where Parkinson's disease prevalence concentrates.
- Remote programming platforms:Telemedicine-integrated stimulation adjustment protocols expand rural patient access while reducing clinical visit frequency, unlocking reimbursement innovation through CMS remote therapeutic monitoring codes.
- VMAT2 inhibitor line extensions:Tardive dyskinesia indications for Huntington's disease chorea represent adjacent therapeutic spaces with limited competitive density and favorable payer dynamics.
Industry Challenges
- Neurostimulator programming expertise scarcity:Movement disorder centers face recruitment bottlenecks for fellowship-trained programmers capable of optimizing complex multi-contact electrode configurations.
- Legacy device upgrade pathway complexity:Battery replacement surgeries for non-rechargeable implantable pulse generators require careful patient selection to minimize hardware explant rates and preserve brand loyalty.
- Cross-jurisdiction reimbursement harmonization:Parallel submissions to CMS, NICE, and Japan's Chuikyo demand divergent health economic evidence packages, fragmenting commercial strategy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Movement Disorder Market |
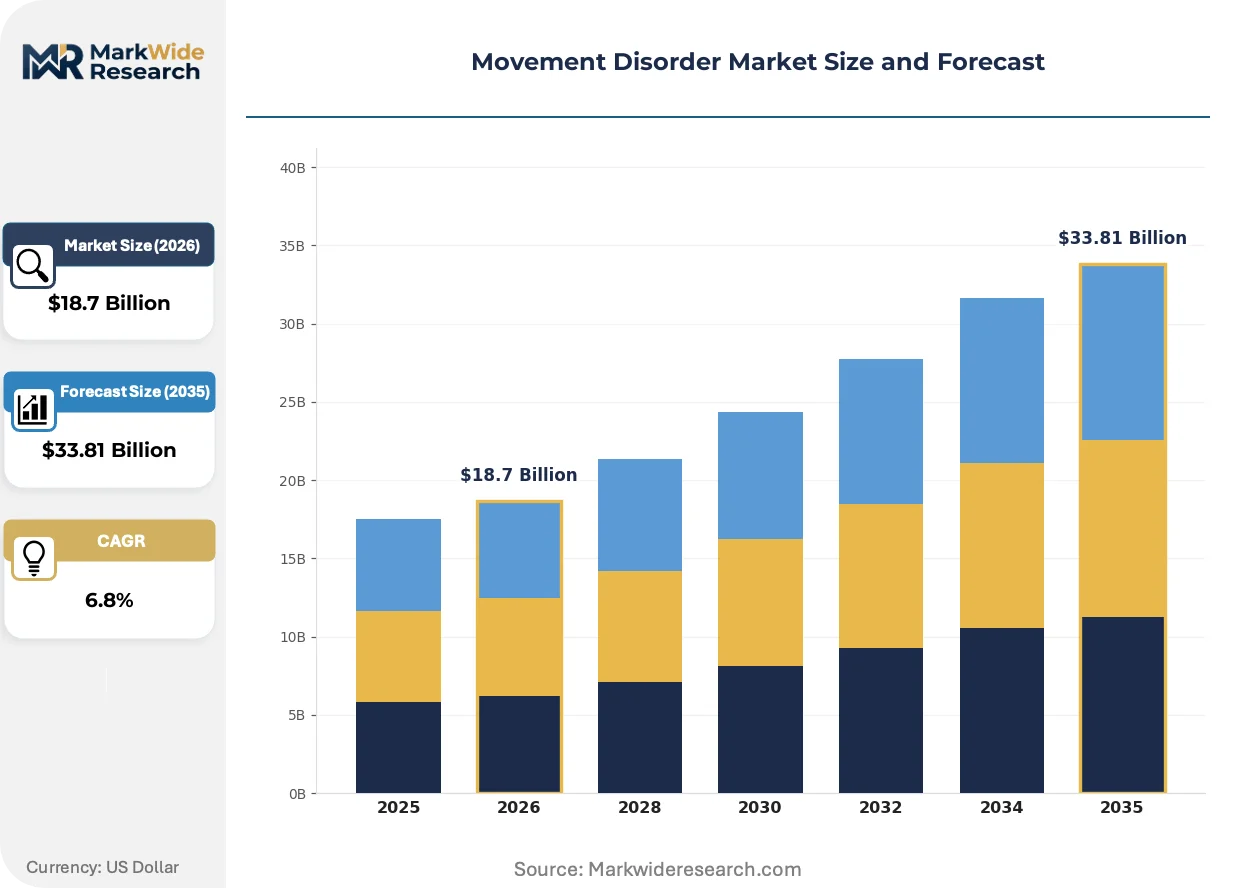
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Devices, Therapies, Procedures End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Treatment Approach: Pharmacological, Non-Pharmacological, Surgical, Integrative Symptom Type: Tremors, Rigidity, Bradykinesia, Dystonia |
| Companies Covered | Boston Scientific Corporation, AbbVie Inc., Medtronic Plc, Teva Pharmaceutical Industries Ltd., Novartis AG, Neurocrine Biosciences, Inc., F. Hoffmann-La Roche Ltd, GlaxoSmithKline Plc, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Movement Disorder Market Strategic Shifts
Artificial intelligence is penetrating movement disorder diagnostics and therapy optimization, compressing the gap between raw neural signal acquisition and clinically actionable intervention protocols across hospital and ambulatory settings.
Directional lead technology with independent current steering is digitizing the spatial precision of deep-brain stimulation, enabling patient-specific field shaping that minimizes off-target effects. Academic medical centers in the United States and Germany are adopting these systems at replacement-cycle pace, converting hardware upgrades into software-defined programming flexibility that reduces revision surgery rates.
The EMA's evolving health technology assessment framework for neuromodulation devices is tightening evidentiary standards for comparative effectiveness against optimized medical therapy. Manufacturers must now generate randomized trial data against active control arms rather than placebo, extending development timelines but elevating reimbursement security for products demonstrating sustained motor benefit.
Hospital procurement committees are consolidating vendor relationships for movement disorder device portfolios, favoring suppliers offering integrated ecosystems spanning implantable hardware, programming software, and remote monitoring infrastructure. This concentration dynamic is most visible in United States academic medical centers, where single-source contracts reduce supply chain complexity but compress price negotiation leverage for individual product lines.
Movement Disorder Market Segmentation
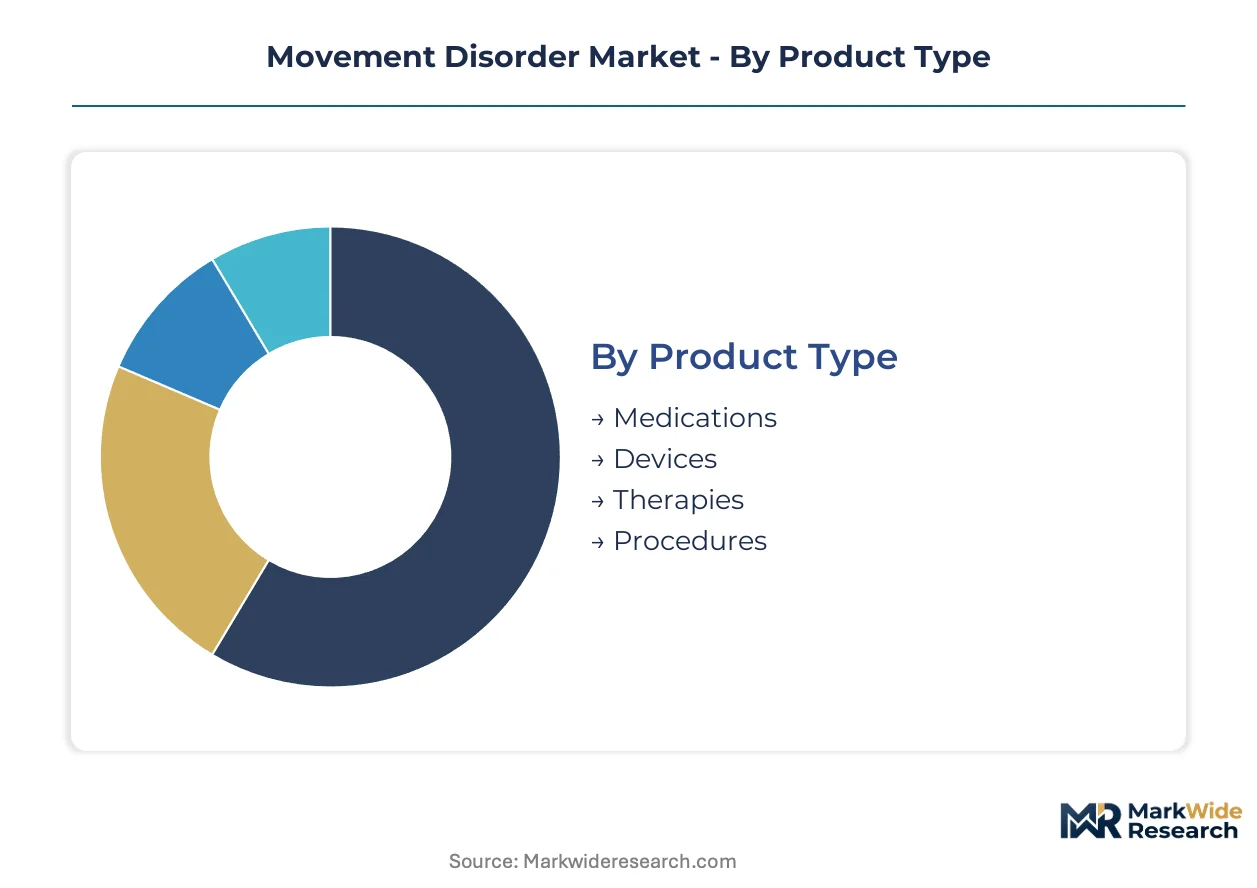
Movement disorder therapeutics fragment across intervention modalities, care settings, and symptom targets. Each segmentation dimension carries distinct reimbursement codes, regulatory pathways, and margin structures that shape portfolio allocation decisions.
Product Type:
Cost tier differentiation separates one-time capital equipment from recurring consumable revenue streams across the product spectrum.
- Medications:Oral and injectable formulations span dopamine agonists, levodopa combinations, and VMAT2 inhibitors. Oral pharmacotherapy dominates prescription volumes in Germany and Japan, where centralized formularies negotiate price-volume agreements for Parkinson's disease maintenance therapy.
- Devices:Implantable pulse generators, directional leads, and external programming systems constitute the hardware layer. Deep-brain stimulation systems concentrate demand in United States academic medical centers and German specialized movement disorder centers, where surgical volume thresholds justify capital investment.
- Therapies:Physiotherapy, occupational therapy, and speech-language pathology represent labor-intensive service delivery. Rehabilitation protocols face reimbursement compression under CMS bundled payment models, constraining margin expansion despite clinical guideline recommendations.
- Procedures:Surgical interventions include deep-brain stimulation implantation, focused ultrasound ablation, and intrathecal pump placement. Procedure volumes correlate with fellowship-trained neurosurgeon density in metropolitan hospital clusters.
Medications hold installed capacity. Devices is rotating up the share rankings.
End User:
Application setting determines acuity tolerance, regulatory oversight intensity, and capital equipment requirements.
- Hospitals:Tertiary care centers house comprehensive movement disorder programs integrating neurology, neurosurgery, and rehabilitation services. United States hospital systems in Boston, Cleveland, and San Francisco anchor device implantation volumes through designated Centers of Excellence status.
- Clinics:Outpatient neurology practices manage stable patients on optimized medication regimens. German Parkinson's disease networks in Bavaria concentrate specialist consultations, reducing emergency department utilization through proactive symptom management.
- Home Care:Remote monitoring platforms and caregiver-administered therapies extend treatment continuity beyond facility walls. Japan's community-based long-term care insurance supports home nursing for advanced Parkinson's disease, preserving hospital capacity for acute interventions.
- Rehabilitation Centers:Dedicated facilities deliver intensive therapy protocols for post-surgical recovery and functional maintenance. Post-DBS programming and gait training concentrate in United States inpatient rehabilitation facilities with neuroplasticity-specialized staff.
Hospitals hold installed capacity. Home Care is rotating up the share rankings.
Treatment Approach:
Maturity gradients separate established pharmacological standards from emerging surgical modalities with evolving evidence bases.
- Pharmacological:Dopaminergic replacement and adjunctive agents constitute first-line intervention for idiopathic Parkinson's disease. Oral levodopa combinations retain dominant prescription share despite motor complication profiles that drive surgical candidacy assessments.
- Non-Pharmacological:Exercise-based interventions, speech therapy, and cognitive training address functional limitations without systemic side effect burdens. German statutory health insurance funds reimburse physiotherapy for Parkinson's disease under disease management program contracts.
- Surgical:Deep-brain stimulation and ablative techniques target medication-refractory tremor and motor fluctuations. FDA breakthrough device designations for closed-loop adaptive systems are compressing evidence generation timelines for next-generation neurostimulators.
- Integrative:Multimodal protocols combining pharmacological, procedural, and rehabilitative elements coordinate care across specialties. Academic medical centers in the United States are piloting bundled payment models for integrated Parkinson's disease management.
Pharmacological holds installed capacity. Surgical is rotating up the share rankings.
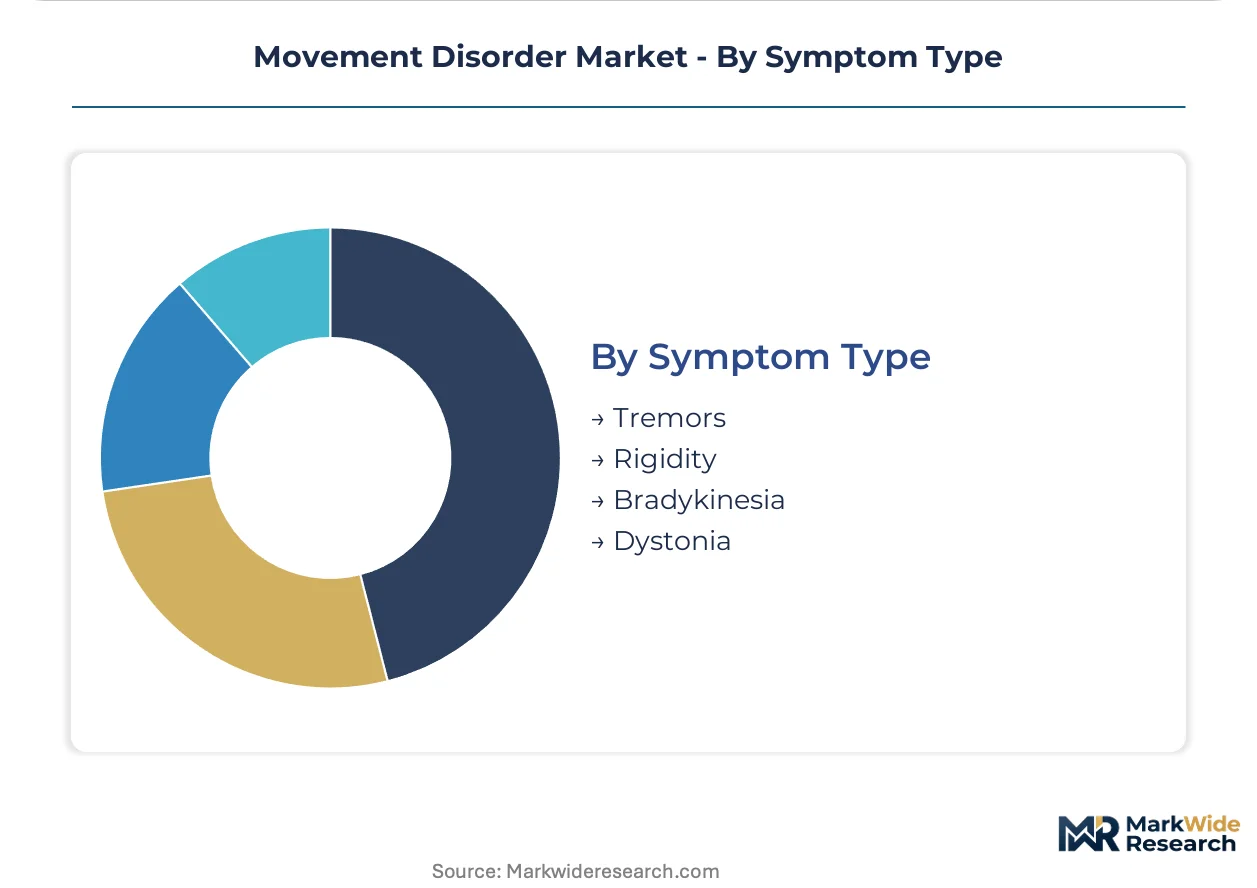
Symptom Type:
Customer type targeting aligns therapeutic development with unmet need severity and measurable outcome endpoints.
- Tremors:Rhythmic oscillatory movements in essential tremor and Parkinson's disease respond variably to pharmacological and surgical intervention. Focused ultrasound thalamotomy concentrates demand in United States and Japanese essential tremor populations seeking non-invasive alternatives.
- Rigidity:Increased muscle tone and resistance to movement characterize advanced Parkinson's disease and progressive supranuclear palsy. Dopaminergic therapy provides partial relief; deep-brain stimulation of the subthalamic nucleus addresses rigidity-dominant phenotypes in surgical candidates.
- Bradykinesia:Slowness of movement initiation and execution impairs activities of daily living across parkinsonian syndromes. Levodopa-responsive bradykinesia defines the therapeutic window for oral pharmacotherapy optimization.
- Dystonia:Sustained involuntary muscle contractions produce abnormal postures in cervical, cranial, and generalized distributions. Botulinum toxin injections dominate focal dystonia management; deep-brain stimulation addresses generalized and segmental forms refractory to chemodenervation.
Tremors holds installed capacity. Dystonia is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States prioritizes device-assisted surgical interventions while Germany and Japan concentrate pharmacotherapy optimization within centralized care networks.
United States
Academic medical centers in Boston, Cleveland, and San Francisco anchor deep-brain stimulation implantation volumes through designated Centers of Excellence status. FDA breakthrough device designations for closed-loop adaptive neurostimulators compress commercialization timelines for treatment-resistant Parkinson's disease populations. Hospital procurement committees in these metropolitan clusters favor integrated vendor ecosystems spanning hardware, software, and remote monitoring infrastructure.
Germany
Specialized movement disorder centers in Bavaria and North Rhine-Westphalia expand device-assisted therapy suites, creating concentrated demand clusters for advanced surgical interventions. EMA health technology assessment frameworks tighten evidentiary standards for neuromodulation devices, requiring randomized trial data against active control arms. Statutory health insurance funds negotiate price-volume agreements for Parkinson's disease maintenance therapy through disease management program contracts.
Japan
The PMDA's streamlined approval track for devices with prior FDA clearance enables rapid market entry into the world's oldest population, where Parkinson's disease prevalence concentrates. Community-based long-term care insurance supports home nursing for advanced cases, preserving hospital capacity for acute interventions. Kanto and Kansai regions house the majority of fellowship-trained movement disorder specialists capable of complex neurostimulator programming.
United Kingdom
NICE technology appraisals influence pricing and reimbursement for novel pharmacological entrants targeting tardive dyskinesia and Huntington's disease chorea. London and Southeast England concentrate tertiary neurology services, though regional variation in deep-brain stimulation access persists. NHS England's specialized commissioning framework consolidates complex movement disorder procedures into designated provider networks.
Switzerland
Precision-machined titanium electrode components for neurostimulator leads originate from concentrated supplier bases in the Basel and Zurich regions, exposing device makers to input cost volatility. Swissmedic maintains stringent conformity assessment requirements for implantable neuromodulation systems. Academic hospitals in Geneva and Lausanne participate in multinational clinical trials for next-generation directional lead technology.
Movement Disorder Market Competitive Environment
Capability concentration sits with device manufacturers possessing integrated hardware-software-service ecosystems; scale advantage sits with diversified pharmaceutical portfolios commanding formulary placement. The market structures around three tiers: implantable neurostimulator specialists, dopaminergic therapy incumbents, and emerging VMAT2 inhibitor developers. Strategic moves center on M&A to capture programming service capabilities and geographic expansion into Japan's aging demographic bulge.
Among diversified medical technology conglomerates, Medtronic Plc and Boston Scientific Corporation occupy positions anchoring the implantable device segment, while AbbVie Inc. exemplifies the pharmaceutical archetype through dopamine agonist portfolio dominance. Neurocrine Biosciences, Inc. represents the emerging biopharmaceutical tier focused on movement disorder sub-segments with limited competitive density. These three entities collectively illustrate the market's tripartite competitive structure: hardware-software integration, small-molecule maintenance therapy, and targeted specialty pharmacology.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| AbbVie Inc. |
| Medtronic Plc |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Neurocrine Biosciences, Inc. |
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline Plc |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Titanium electrode supply concentration in Switzerland and Germany exposes device manufacturers to input cost volatility that compresses margin spreads between premium directional lead systems and standard electrode configurations while forcing procurement committees toward multi-year supply agreements.
Pricing Analysis
Long-term offtake contracts dominate procurement for implantable pulse generators and directional leads, with hospital systems in the United States and Germany negotiating bundled pricing across hardware, software licenses, and programming service subscriptions. Price differentiation rests on FDA breakthrough device designation status and rechargeable versus non-rechargeable battery technology tiers. Pricing pressure stems from CMS bundled payment models that compress reimbursement for device implantation procedures. Academic medical centers demonstrate lowest price sensitivity due to Centers of Excellence status requirements, while community hospitals face acute budget constraints.
Supply Chain Analysis
Extended payment terms from Swiss and German precision-machining suppliers strain working capital for mid-tier device manufacturers lacking legacy volume commitments. Titanium feedstock and platinum-iridium electrode contacts draw from concentrated metallurgical processing in Switzerland, Germany, and the United States. Single-source vulnerability pervades directional lead fabrication, where FDA master file cross-referencing locks buyers into established supplier relationships. Distribution runs through hospital procurement committees and specialized movement disorder center networks rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement committee consolidation in United States academic medical centers, where single-source vendor contracts for integrated device-service ecosystems compress price negotiation leverage for individual manufacturers.
For Market Incumbents: Build programming service moats through remote monitoring platform integration and fellowship-trained clinician network capture. Defensive consolidation should prioritize backward integration into titanium electrode supply through captive Swiss machining partnerships. Threat from closed-loop adaptive neurostimulator entrants demands accelerated FDA submission timelines for next-generation directional lead systems. For New Entrants and Emerging Players: Pursue Japan's PMDA streamlined approval track for devices with prior FDA clearance, exploiting the aging demographic bulge and limited local programming expertise. White-space targets include tardive dyskinesia VMAT2 inhibitor line extensions and rural telemedicine-integrated stimulation adjustment protocols. Go-to-market angle should emphasize CMS remote therapeutic monitoring code reimbursement innovation. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors hardware-software-service integrators over pure-play device manufacturers. Long-term viability favors platforms with installed base conversion potential and recurring revenue capture through programming optimization services. Acquisition target archetype: mid-tier neuromodulation developers with directional lead IP and remote monitoring software assets. Signal to watch is CMS coverage determination timing for closed-loop adaptive stimulation systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review timelines compress commercialization cycles for closed-loop adaptive neurostimulators targeting treatment-resistant Parkinson's disease. |
| Hospital System Partnership | Single-source contracts with United States academic medical centers secure implantation volume through designated Centers of Excellence status. |
| Software Companion Development | AI-integrated programming platforms differentiate hardware offerings while capturing high-margin recurring optimization revenue streams. |
| Reimbursement Strategy | CMS remote therapeutic monitoring code alignment unlocks rural patient access and reduces clinical visit frequency for device programming. |
| CE Marking Pathway | EU MDR conformity assessment completion enables German specialized movement disorder center market entry despite tightened evidentiary standards. |
Study Parameters
A spread of perspectives from neurostimulator programming specialists, hospital procurement managers, biomedical engineers, and payer access specialists converged on the working assumptions through structured primary interviews validated against FDA 510(k) filings, EMA health technology assessment documentation, CMS Medicare coverage determinations, and hospital GPO contract databases. Bottom-up demand modeling across device implantation volumes triangulated with top-down pharmaceutical prescription audit data.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation dimensions spanning intervention modality, care setting acuity, symptom target, and regional regulatory cluster. CAGRs derived from weighted average of historical procedure volume trajectories and pharmacotherapy adoption curves, incorporating PMDA approval timeline assumptions for Japan market entry and EU MDR certification cost inflation for mid-tier manufacturers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by closed-loop adaptive neurostimulator developers or VMAT2 inhibitor line extension specialists would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Nerve Repair Market
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
Global Sciatica Treatment Market
Neurology
Lewy Body Dementia Treatment Market
Neurology
Chiari Malformation Treatment Market
Neurology
Global Neuromarketing Market
Neurology
Multiple Sclerosis Treatment Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Labyrinthitis Market
Neurology
White Matter Injury Treatment Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Interventional Neurology Market
Neurology
Italy Neurology Devices Market
Neurology
Optic Neuritis Treatment Market
Neurology
Mild Cognitive Impairment Market