
 Neuroendoscopy Devices Market | 2026-2036
Neuroendoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neuroendoscopy Devices Market Analysis
The EU Medical Device Regulation is broadening compliance requirements for neuroendoscopy manufacturers selling into European healthcare systems. Karl Storz leverages its optical engineering heritage to dominate rigid endoscope supply across German university hospitals. Medtronic sustains R&D intensity in robotic-assisted platforms for cranial access procedures. Stryker anchors its position through channel control of integrated operating room ecosystems in North American neurosurgical centers.
Neuroendoscopy devices are rigid or flexible fiber-optic instruments with working channels of 2–6 mm diameter, designed for visualization and intervention within the ventricular system and skull base through small cranial openings or natural orifices. These instruments enable biopsy, tumor resection, and cerebrospinal fluid diversion while minimizing parenchymal disruption. Rigid endoscopes capture the largest revenue pool due to their optical clarity and durability in high-volume tumor resection workflows, while robotic assistance represents the fastest-expanding technology segment as hospitals seek to standardize precision in intracranial navigation. Flexible endoscopes occupy a narrower but strategically important niche in transsphenoidal and ventricular approaches where line-of-sight constraints limit rigid instrument utility.
FDA 510(k) clearance pathways and the EU MDR conformity assessment process shape product development timelines and commercial access for neuroendoscopy systems in their respective markets. ISO 13485 quality management standards and IEC 60601 electrical safety requirements further constrain design choices for manufacturers targeting multi-regional distribution. Stakeholders must monitor how Japan's PMDA and China's NMPA evolve their review criteria for robotic-assisted surgical devices, as alignment across these frameworks will determine which manufacturers can scale platforms across the three largest neurosurgical equipment markets without redundant clinical validation investments.
Market Dynamics
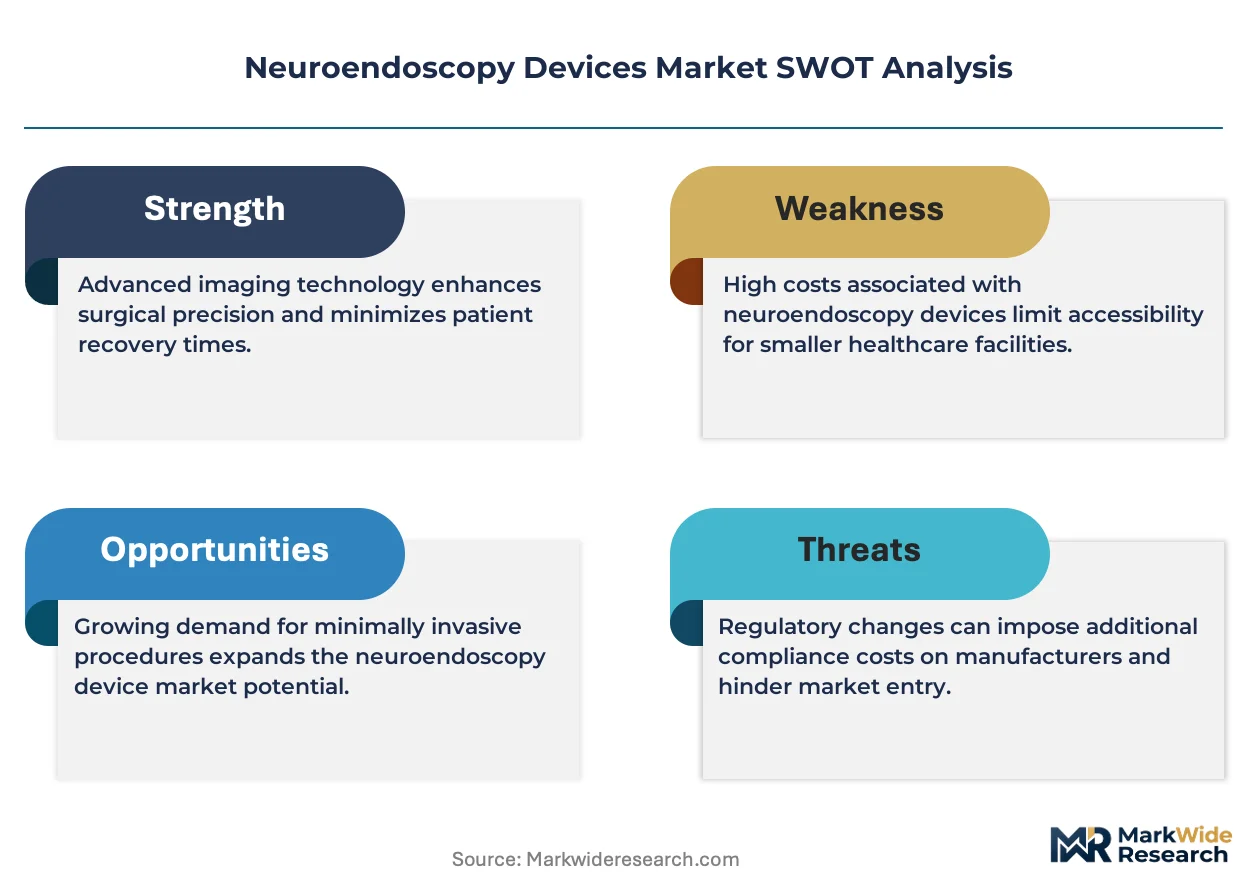
Reimbursement migration toward value-based surgical bundles is compressing capital equipment replacement cycles and forcing manufacturers to embed outcome guarantees into device contracts, fundamentally altering how hospitals evaluate total cost of ownership for neuroendoscopy platforms.
Growth Catalysts
- Medicare bundled payment expansion:The Centers for Medicare and Medicaid Services is extending episode-based reimbursement for cranial procedures, incentivizing hospitals to adopt minimally invasive techniques that reduce length of stay and readmission penalties.
- 4K imaging sensor maturation:CMOS sensor manufacturers have achieved cost parity with CCD technology, enabling native 4K resolution in rigid neuroendoscopes without the thermal management burden that previously constrained optical performance.
- German university hospital consolidation:The merger of Charité Berlin and Munich University Hospital networks has created procurement pools exceeding 50 neurosurgical suites, concentrating demand for standardized instrument platforms.
Market Restraints
- Iridium optical fiber cost volatility:The specialized fiber bundles comprising rigid endoscope light channels derive 60% of raw material cost from iridium-doped glass, subject to Russian and South African supply concentration.
- EU MDR clinical evidence requirements:The expanded mandate for post-market clinical follow-up data on Class IIb neurosurgical devices has extended conformity assessment timelines by 14-18 months for manufacturers without legacy device portfolios.
- Robotic-assisted open surgery competition:Platforms such as ROSA Brain and Neuromate are capturing cranial biopsy volume that previously flowed to pure endoscopic approaches, particularly in frameless stereotaxy applications.
Strategic Opportunities
- Japan's PMDA fast-track pathway:The Sakigake designation for breakthrough medical devices offers priority review and conditional early approval for robotic neuroendoscopy platforms, compressing time-to-market by 12-24 months versus standard review.
- Flexible endoscope ventriculostomy:Third ventriculostomy and septostomy procedures remain underpenetrated by flexible instruments in the United States, where rigid endoscopes still dominate despite anatomical advantages of steerable optics.
- India's PLI scheme for medical devices:The Production Linked Incentive program offers 5% reimbursement on incremental sales for domestic manufacturing of high-value neurosurgical equipment, attracting contract manufacturers serving European OEMs.
Industry Challenges
- Neuroendoscopic fellowship pipeline constraints:The Society of Neurological Surgeons reports fewer than 40 accredited minimally invasive cranial fellowship positions annually in the United States, creating a bottleneck for safe adoption of advanced instrumentation.
- ISO 13485:2016 transition audits:Manufacturers with certificates expiring in 2024-2025 face compressed audit availability and heightened scrutiny of software lifecycle processes for camera control units and robotic navigation modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuroendoscopy Devices Market |
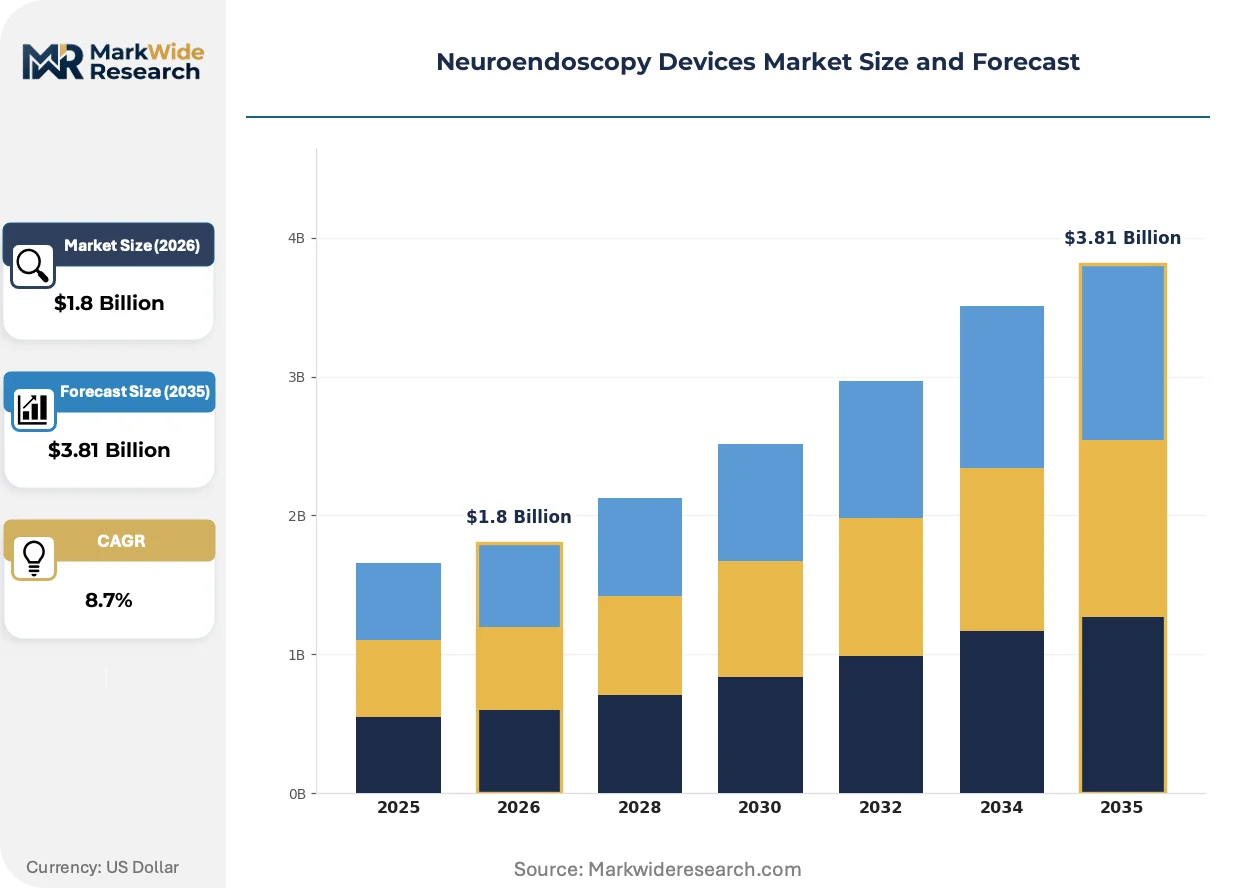
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Endoscopes, Flexible Endoscopes, Accessories, Light Sources Application: Intracranial Surgery, Tumor Resection, Biopsy, Ventricular Drainage End User: Hospitals, Ambulatory Surgical Centers, Neuro Clinics, Research Institutions Technology: Optical Systems, Robotic Assistance, Minimally Invasive Techniques, Imaging Integration |
| Companies Covered | Medtronic, Ackermann Instrumente GmbH, Karl Storz, Clarus Medical LLC, adeor medical AG, B. Braun SE, Stryker, Richard Wolf GmbH, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuroendoscopy Devices Market Emerging Trajectories
Digital integration is dissolving the boundary between visualization hardware and surgical navigation software, creating platform ecosystems where instrument vendors must compete on data interoperability rather than optical specifications alone.
Single-use sterile sheaths for rigid neuroendoscopes are consolidating the reprocessing economics of high-volume tumor centers. German and Japanese hospitals are adopting these disposable barriers to eliminate autoclave turnaround delays in busy operating schedules. The technology is consolidating vendor relationships around suppliers capable of guaranteeing sheath-to-scope optical alignment tolerances below 50 microns.
The EU Medical Device Regulation's Unique Device Identification mandate is forcing neuroendoscopy manufacturers to embed RFID or datamatrix tracking in every rigid and flexible instrument by 2026. German notified bodies are interpreting this as requiring lot-level traceability for optical components sourced from sub-suppliers. Karl Storz and Richard Wolf have responded by verticalizing fiber bundle production to maintain certificate continuity.
Hospital procurement committees are unbundling service contracts from capital purchases, separating preventive maintenance from software update subscriptions and training packages. North American academic medical centers are leading this disaggregation, using third-party clinical engineering departments to manage multi-vendor endoscope fleets. The shift is most pronounced in California and Massachusetts, where health system consolidation has created centralized biomedical equipment management functions.
Neuroendoscopy Devices Market Segmentation
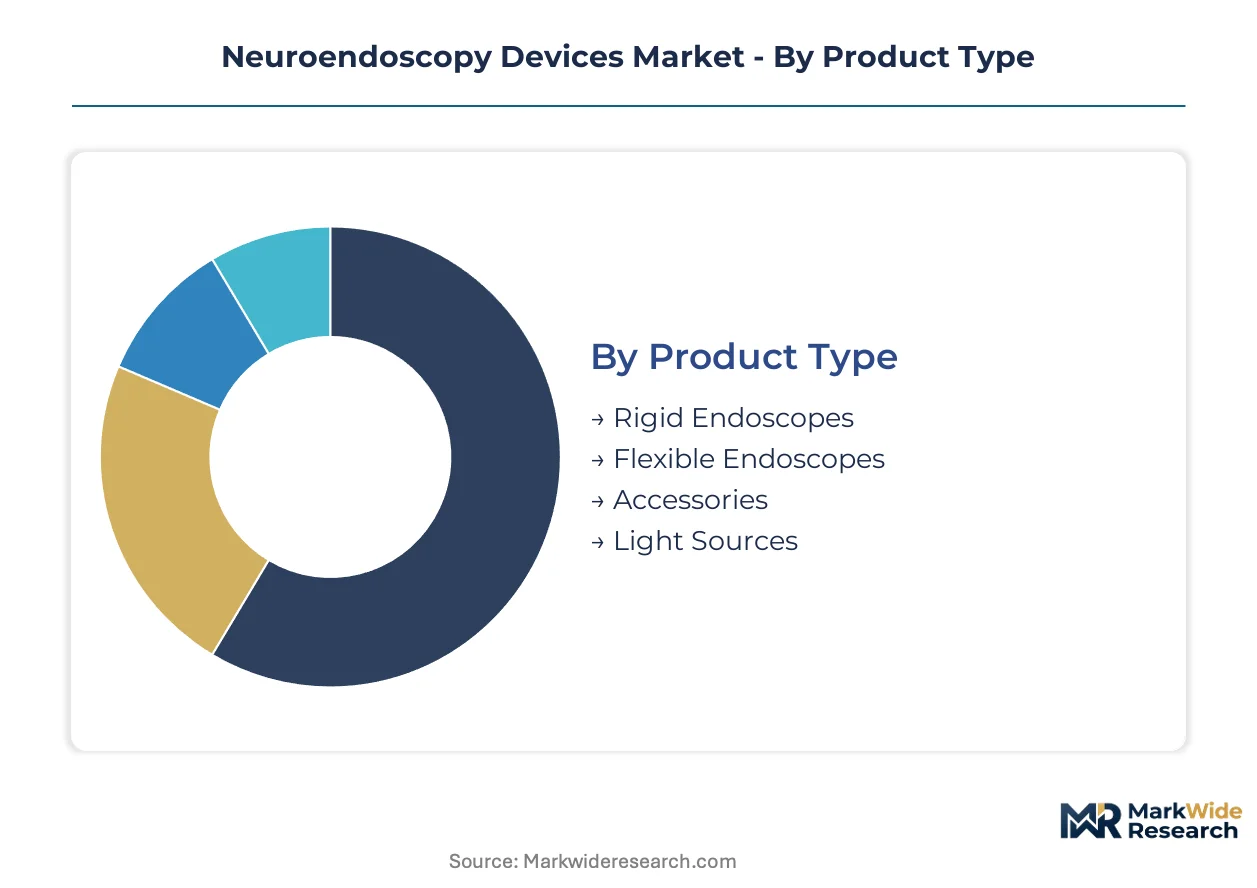
Neuroendoscopy procurement patterns diverge sharply across product categories, with hospital capital committees applying distinct replacement cycles to visualization hardware versus consumable accessories. Understanding these segment-specific upgrade rhythms illuminates where manufacturers can capture recurring revenue versus episodic capital sales.
Product Type:
Replacement cycles for visualization equipment stretch 7-10 years, while accessory turnover occurs within 12-18 months, creating divergent revenue predictability across this category.
- Rigid Endoscopes:These instruments employ rod-lens optical chains encased in stainless steel shafts of 2.8-4.0 mm diameter, delivering superior light transmission and image fidelity for tumor resection workflows. German university hospitals and North American academic medical centers concentrate demand for premium 4K-compatible rigid systems as they modernize operating room infrastructure under value-based reimbursement contracts.
- Flexible Endoscopes:Fiber-optic bundles with active steering mechanisms enable navigation through curved anatomical pathways such as the nasal cavity and ventricular system. Adoption is accelerating in Japan and select US tertiary centers where transsphenoidal pituitary surgery volumes justify the higher per-procedure cost against rigid alternatives.
- Accessories:Biopsy forceps, irrigation cannulas, and electrode probes represent high-velocity consumables with recurring purchase obligations tied to procedure volume.
- Light Sources:LED and xenon illumination systems power optical visualization, with LED configurations displacing legacy xenon in new installations due to thermal efficiency advantages.
Volume placements concentrate in Rigid Endoscopes; the faster expansion belongs to Flexible Endoscopes.
Application:
Procedure reimbursement differentials across cranial interventions shape capital allocation toward specific surgical workflows, with tumor-related interventions commanding premium equipment investment.
- Intracranial Surgery:Ventricular endoscopy and cyst fenestration utilize rigid instrumentation through burr hole access, with procedure volumes scaling alongside pediatric hydrocephalus referral networks in the United States and Germany.
- Tumor Resection:Endoscopic endonasal approaches to skull base neoplasms demand integrated visualization-navigation platforms with sub-millimeter registration accuracy. Japanese neurosurgical departments lead adoption of robotic-assisted enhancement for these procedures under PMDA fast-track approvals.
- Biopsy:Frameless stereotactic guidance combined with endoscopic visualization enables tissue sampling from deep brain structures with reduced morbidity versus open approaches.
- Ventricular Drainage:Third ventriculostomy and shunt placement represent high-volume interventions where flexible endoscope advantages remain underexploited in US community hospital settings.
Procedure economics favor Tumor Resection for capital intensity; Ventricular Drainage offers the steepest expansion trajectory as flexible technology penetrates community practice.
End User:
Capital deployment authority and clinical volume thresholds determine which facility types justify comprehensive neuroendoscopy platform investment versus targeted instrument procurement.
- Hospitals:Tertiary and quaternary centers with dedicated neurosurgical suites drive demand for integrated operating room ecosystems combining endoscopy with navigation and intraoperative imaging. Consolidated health systems in California and Massachusetts leverage centralized procurement to standardize across multiple campuses.
- Ambulatory Surgical Centers:Limited cranial procedure volumes constrain standalone ASC investment, though select multi-specialty centers in Germany perform outpatient ventriculostomy with streamlined rigid instrumentation.
- Neuro Clinics:Specialized cranial-focused facilities concentrate diagnostic endoscopy and minor interventions, particularly in Japan's urban metropolitan corridors.
- Research Institutions:Preclinical and cadaveric training programs sustain demand for demonstration equipment and educational instrument sets.
Installed base concentrates in Hospitals; Neuro Clinics are gaining share fastest as subspecialization fragments cranial care delivery.
Technology:
Technology stack decisions increasingly bundle hardware with software and service components, shifting vendor selection criteria from optical specifications toward platform interoperability.
- Optical Systems:Native 4K CMOS sensors with improved dynamic range now match legacy CCD performance without thermal degradation, enabling sustained high-resolution visualization during lengthy tumor resections.
- Robotic Assistance:Motorized instrument holders and navigation-integrated positioning systems standardize trajectory precision for deep brain access. PMDA Sakigake designation in Japan accelerates regulatory pathways for breakthrough robotic platforms.
- Minimally Invasive Techniques:Endoscopic corridor surgery through natural orifices and keyhole craniotomies reduces parenchymal disruption and length of stay, aligning with Medicare bundled payment incentives.
- Imaging Integration:Real-time overlay of preoperative MRI and CT onto endoscopic video feeds demands DICOM-compliant connectivity and sub-second latency processing.
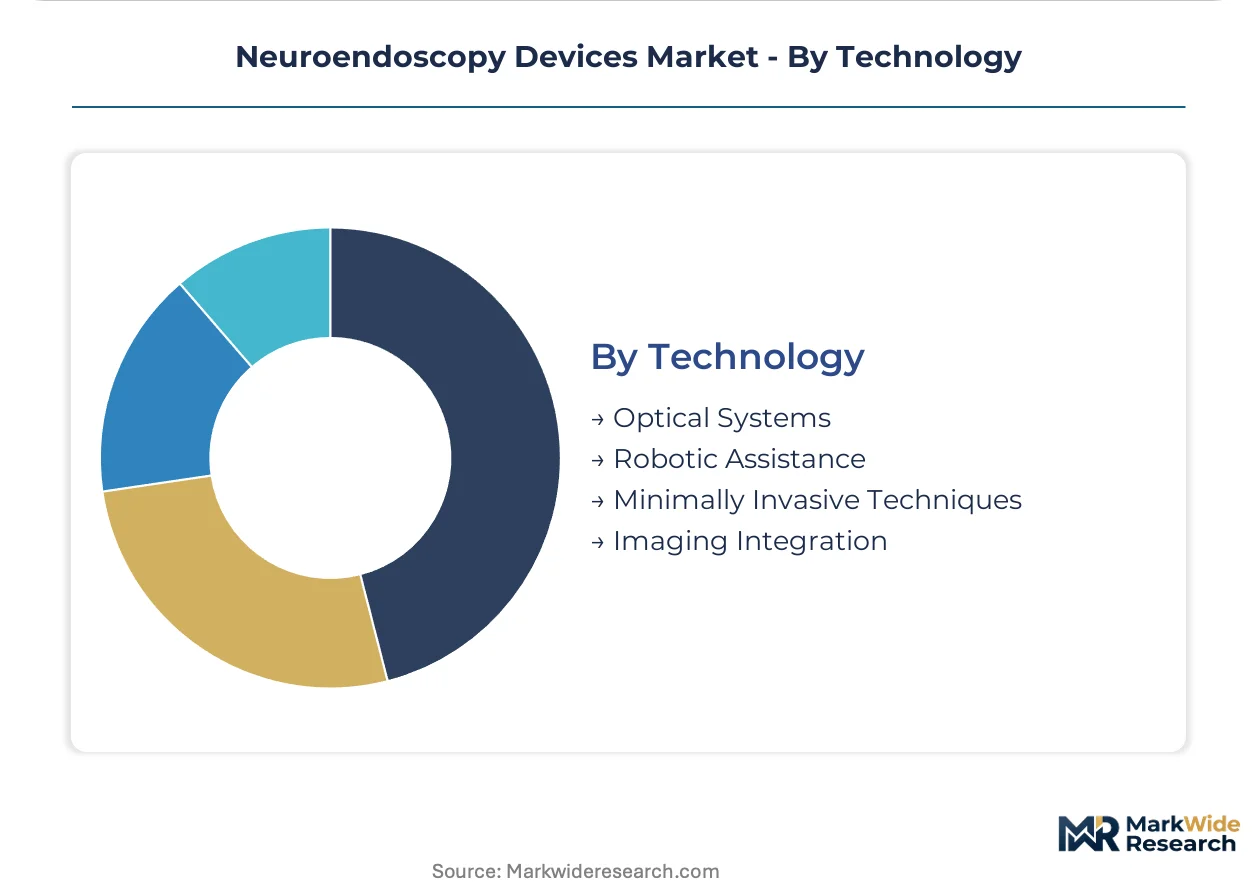
Deployment concentrates in Optical Systems; Robotic Assistance climbs the fastest as precision requirements intensify for skull base approaches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates optical component fabrication while the United States absorbs the highest-value integrated systems. Japan's PMDA fast-track pathway accelerates robotic platform approvals. India's PLI scheme attracts contract manufacturers serving European OEMs.
United States
Medicare bundled payment expansion for cranial procedures drives hospital investment in minimally invasive platforms. FDA 510(k) clearance pathways shape product development timelines for manufacturers targeting multi-regional distribution. California and Massachusetts health systems leverage centralized procurement to standardize neuroendoscopy fleets across consolidated campuses.
Germany
University hospital consolidation creates procurement pools exceeding 50 neurosurgical suites, concentrating demand for standardized instrument platforms. EU MDR conformity assessment extends timelines for Class IIb device approvals, favoring manufacturers with legacy portfolios. Karl Storz leverages optical engineering heritage across Charité Berlin and Munich networks.
Japan
PMDA Sakigake designation offers priority review for breakthrough robotic neuroendoscopy platforms, compressing time-to-market by 12-24 months. METI funding supports domestic CMOS sensor development for 4K visualization systems. Tokyo and Osaka metropolitan corridors host specialized neuro clinics driving flexible endoscope adoption.
India
CDSCO regulatory alignment with international standards enables faster market entry for multinational manufacturers. PLI scheme reimbursement on incremental sales attracts contract manufacturers serving European OEMs. Maharashtra and Karnataka medical device clusters expand domestic production capacity for high-value neurosurgical equipment.
China
NMPA evolving review criteria for robotic-assisted surgical devices determines scalable platform deployment across the neurosurgical equipment market. Domestic CMOS sensor manufacturers achieve cost parity with legacy CCD technology. Shanghai and Beijing hospital networks drive demand for integrated visualization-navigation platforms.
Neuroendoscopy Devices Market Vendor Landscape
The competitive structure tilts toward diversified medical technology conglomerates with optical engineering depth. German and US-based players anchor premium rigid endoscope supply, while Japanese manufacturers concentrate on flexible instrument innovation. Strategic archetypes include integrated operating room ecosystem vendors, specialized optical component suppliers, and robotic navigation platform developers. M&A activity targets navigation software capabilities, while capacity expansion focuses on CMOS sensor verticalization.
Among diversified conglomerates, Medtronic and Stryker represent the ecosystem-integration archetype, bundling visualization hardware with navigation software and service contracts. Karl Storz exemplifies the optical-specialist tier, leveraging German precision manufacturing heritage across university hospital networks. Olympus Corporation anchors the flexible endoscope segment, drawing on Japanese fiber-optic engineering for transsphenoidal and ventricular applications.
| Leading Market Players |
|---|
| Medtronic |
| Ackermann Instrumente GmbH |
| Karl Storz |
| Clarus Medical LLC |
| adeor medical AG |
| B. Braun SE |
| Stryker |
| Richard Wolf GmbH |
| Olympus Corporation |
| Others |
Supply Flow & Price Mechanics
Performance-grade bifurcation between 4K-native CMOS systems and legacy CCD configurations manifests in divergent pricing power and supply chain architectures across German university hospitals and North American academic centers. Premium tiers command sustained margins through captive fiber bundle production, while standard-tier manufacturers absorb iridium cost volatility from concentrated Russian and South African glass suppliers.
Pricing Analysis
Margin tightening in standard-tier rigid endoscopes reflects iridium-doped glass cost volatility and compressed replacement cycles under Medicare bundled payment contracts. Three-tier pricing structure across premium 4K-integrated, standard HD-compatible, and economy legacy systems stratifies by optical resolution and robotic navigation compatibility. Cost-down pressure on flexible endoscope lines accelerates as Japanese manufacturers achieve CMOS cost parity. Community hospital procurement committees exhibit highest price sensitivity, while German Charité network consolidated purchasing pools prioritize outcome guarantees over unit economics.
Supply Chain Analysis
ISO 13485:2016 certification gating and EU MDR Unique Device Identification mandates constrain supplier qualification to German optical component fabricators, Japanese CMOS sensor foundries, and South Korean LED illumination specialists. Rigid endoscope production draws from iridium-doped glass fiber bundles, stainless steel precision shafts, and sapphire lens elements. Single-source vulnerability concentrates in Russian-sourced specialty glass precursors. Distribution runs through hospital procurement committees, GPO contracts, and direct university hospital network agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessment timeline extensions and iridium supply concentration are forcing subscale manufacturers toward exit or acquisition, consolidating vendor relationships around optical engineering heritage and legacy device portfolios.
For Market Incumbents: Acquire navigation software capabilities to defend integrated platform positioning against robotic-assisted open surgery competition from ROSA Brain and Neuromate systems. Backward integration into CMOS sensor design secures supply continuity as Japanese METI funding accelerates domestic foundry capacity. Channel control through multi-year service contract bundling protects replacement cycle revenue against third-party clinical engineering disaggregation in California and Massachusetts health systems.
For New Entrants and Emerging Players: US community hospital ventricular drainage segments remain underserved by flexible endoscope penetration despite anatomical advantages over rigid instrumentation. India's PLI scheme manufacturing clusters offer contract production entry points serving European OEM cost-down requirements. Reimbursement strategy alignment with Medicare bundled payment episode definitions accelerates hospital adoption committee access.
For Investors and Strategic Acquirers: Re-rating potential sits with optical-specialist tier manufacturers possessing ISO 13485:2016 certificate continuity and verticalized fiber bundle production given EU MDR lot-level traceability enforcement. Long-term viability favors assets with German university hospital network installed bases and PMDA Sakigake pathway regulatory momentum. The signal to watch is NMPA robotic-assisted device review criteria alignment across the three largest neurosurgical equipment markets.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market clinical follow-up data requirements extend conformity assessment timelines for Class IIb devices. |
| Hospital System Partnership | Charité Berlin and Munich network procurement pools exceed 50 neurosurgical suites, concentrating standardization demand. |
| Software Companion Development | DICOM-compliant connectivity with sub-second latency processing enables real-time MRI overlay for skull base approaches. |
| Reimbursement Strategy | Medicare bundled payment expansion for cranial procedures incentivizes minimally invasive technique adoption. |
| Backward Integration | Captive fiber bundle production maintains certificate continuity under EU MDR lot-level traceability mandates. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance timelines, EU MDR conformity assessment durations, and PMDA Sakigake approval compressions anchored the trend analysis, supplemented by interviews with neurosurgical department heads, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers. Secondary validation drew from FDA filings, EMA notified body guidance documents, CMS Medicare reimbursement bulletins, and ISO 13485 registrar audit disclosures. Bottom-up procedure volume modeling and top-down capital equipment spend estimates were triangulated against manufacturer revenue disclosures.
Input-output matrices mapped rigid endoscope, flexible endoscope, and robotic-assisted platform deployment across technology stack, application workflow, and end-user facility tier dimensions throughout the forecast period. CAGRs were derived from installed base replacement cycle analysis and procedure volume elasticity to reimbursement regime shifts. Forecast inputs incorporated iridium price trajectory scenarios and fellowship pipeline accreditation rates from the Society of Neurological Surgeons.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA robotic device review criteria evolution and iridium supply chain reconfiguration. Model assumptions reflect documented regulatory pathway timelines and notified body audit capacity constraints. A model refresh is warranted upon material change in EU MDR clinical evidence interpretation or Medicare bundled payment procedure code expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
High Intensity Focused Ultrasound (HIFU) Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
Hearing Aids Market
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Global Microscopy Device Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Global Robotic Endoscopy Devices Market