
 Pre-Filled Hemostasis Agents Market | 2026-2036
Pre-Filled Hemostasis Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Filled Hemostasis Agents Market Analytics
European gelatin and collagen producers is recalibrating output schedules to align with surgical demand rebounds across Western Europe. BD sustains broad manufacturing scale across multiple delivery formats including pre-filled syringes. Ethicon leverages Johnson & Johnson's surgical channel depth to anchor hospital procurement contracts in North America. Baxter International competes through recombinant factor specialization and blood management integration.
Pre-filled hemostasis agents comprise sterile, ready-to-use biological or synthetic formulations—typically gelatin sponges, collagen matrices, or thrombin solutions—engineered to accelerate clot formation at surgical sites without reconstitution delays. These agents reduce operative blood loss and eliminate compounding errors in time-critical procedures. Thrombin-based products and recombinant factors capture premium positioning due to faster onset profiles and lower immunogenicity risk. Gelatin-based agents occupy volume-driven segments in orthopedic and trauma applications where cost sensitivity shapes tender outcomes. Pre-filled syringes and spray applicators are gaining preference over manual preparation as surgical workflows standardize on single-use formats.
FDA biologics sterility requirements and EU MDR technical documentation mandates are extending development timelines and raising compliance costs for new entrants. ISO 13485 quality management and CE marking under the EU AI Act's broader healthcare device scrutiny further tighten market access conditions. Stakeholders must monitor regulatory divergence between FDA and EMA hemostat classification pathways to optimize multi-territory launch sequencing.
Market Dynamics
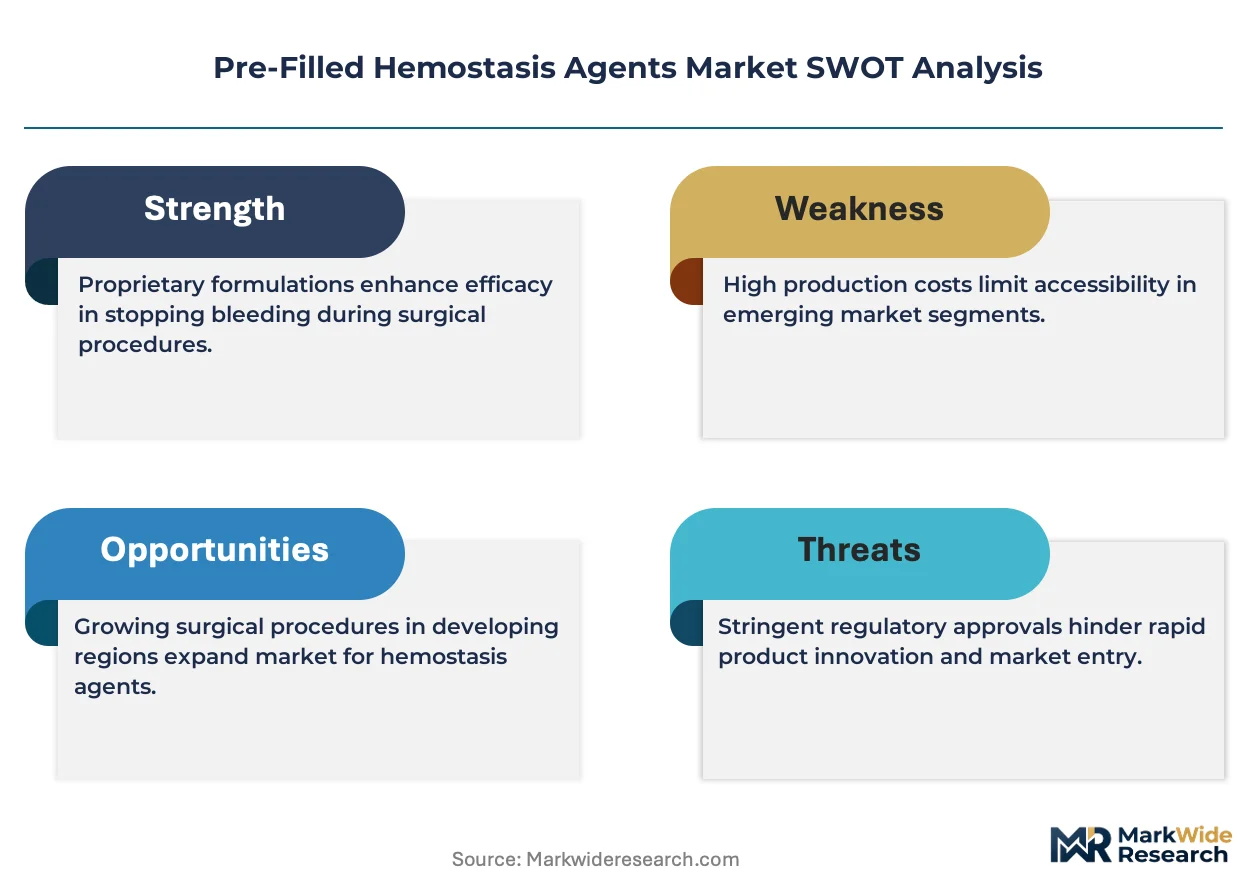
FDA biologics sterility updates and EU MDR technical documentation mandates are compressing product development timelines while elevating compliance investment thresholds for pre-filled hemostasis agent manufacturers.
Growth Catalysts
- Cardiovascular surgical volume:Rising coronary artery bypass graft and valve replacement procedures in United States hospital systems are expanding addressable demand for rapid-acting thrombin formulations.
- EU MDR framework:Tightened pre-market scrutiny under Medical Device Regulation is accelerating consolidation toward established manufacturers with robust quality management systems and clinical data packages.
- Recombinant thrombin technology:Advances in recombinant protein production are reducing immunogenicity risks and enabling broader adoption in pediatric and repeat-surgery patient populations.
Market Restraints
- Raw material concentration:Pharmaceutical-grade gelatin supply concentrates in European processing facilities, exposing manufacturers to regional production disruptions and input cost volatility.
- Regulatory friction:Divergent FDA and EMA classification pathways for hemostatic biologics force redundant clinical studies and dual-track submission strategies that extend time-to-market.
- Autologous blood salvage:Cell saver technology and intraoperative blood recovery systems substitute for topical hemostasis in high-volume bleeding procedures, capping penetration in cardiac surgery suites.
Strategic Opportunities
- Ambulatory surgical centers:United States outpatient facility expansion creates demand for single-use, pre-filled formats that eliminate pharmacy compounding and reduce staffing requirements.
- Japan reimbursement tailwind:Ministry of Health, Labour and Welfare premium pricing for innovative hemostatic devices incentivizes local clinical trials and regulatory submissions for novel delivery mechanisms.
- Spray applicator convergence:Integration of fibrin sealants with laparoscopic delivery systems is unifying hemostasis and tissue adhesion functions in minimally invasive procedures.
Industry Challenges
- ISO 13485 certification timelines:Extended audit backlogs and notified body capacity constraints are delaying quality management system approvals for new market entrants.
- Biologics sterility validation:FDA requirements for terminal sterilization of protein-based formulations without activity degradation demand specialized equipment investments and process development expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Filled Hemostasis Agents Market |
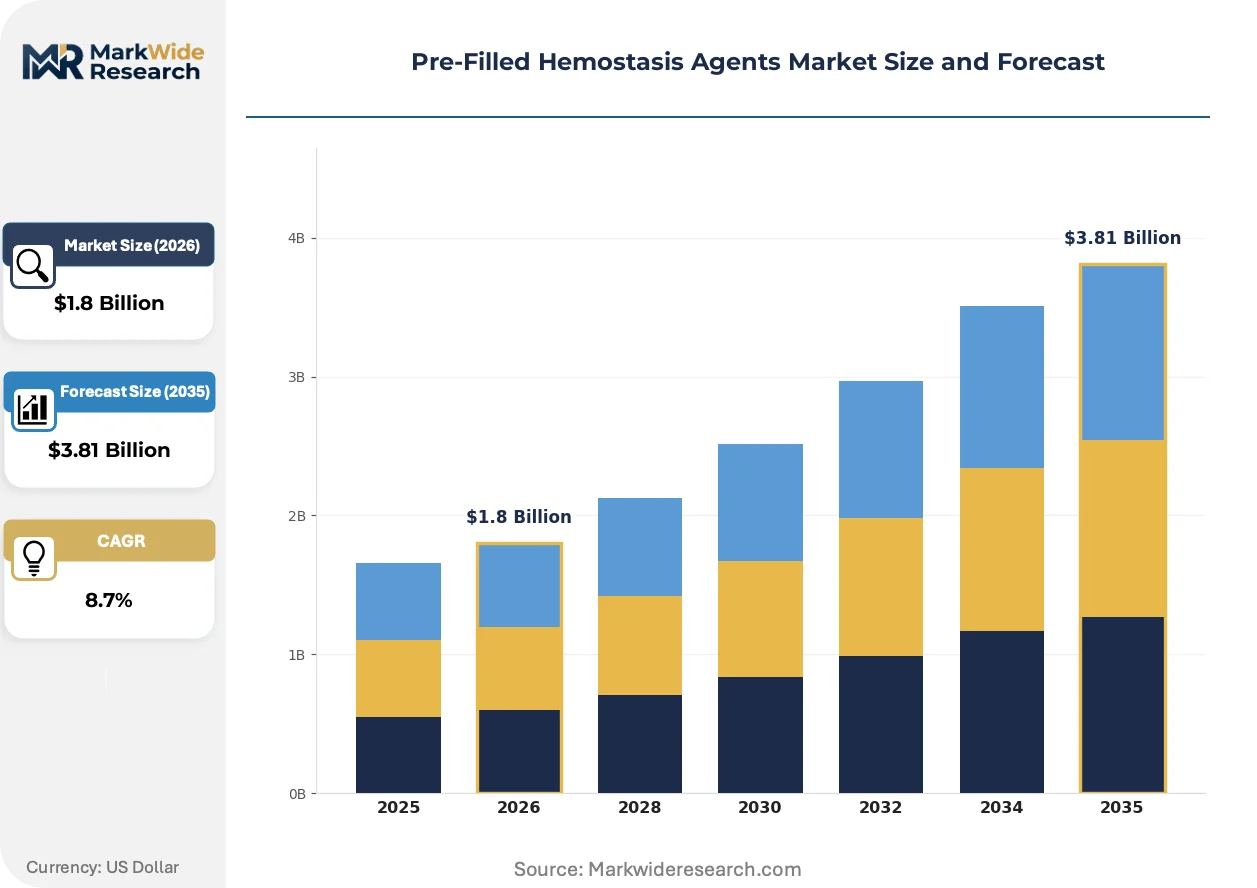
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin-Based Agents, Collagen Matrix, Recombinant Factors, Thrombin-Based Products Application: Minimally Invasive Surgery, Orthopedic Surgery, Cardiovascular Procedures, Trauma Management Delivery Mode: Injectable, Topical, Spray Applicators, Pre-Filled Syringes End User: Hospitals, Surgical Centers, Emergency Departments, Outpatient Clinics |
| Companies Covered | BD (Becton, Dickinson and Company), Medtronic Plc., Ethicon (Johnson & Johnson), Smith & Nephew, Integra Life Sciences Corporation, Pfizer Inc., Teleflex Incorporated, B. Braun SE, Baxter International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Filled Hemostasis Agents Market Evolving Landscape
Pre-filled hemostasis agent development is converging on workflow integration and point-of-care readiness, with manufacturers prioritizing formats that eliminate preparation variability and compress operating room turnover times.
Flowable gelatin-thrombin composites are unifying mechanical compression and enzymatic clotting in a single applicator, eliminating the need for sequential product deployment. Orthopedic trauma teams in Level I trauma centers are adopting these hybrid formats for complex fracture repairs. The technology is compressing the traditional two-step hemostasis protocol into a single intervention, reducing operative time and product waste.
EU MDR Article 10 technical documentation requirements are mandating expanded clinical evidence and post-market surveillance systems for hemostatic devices. Manufacturers must now maintain systematic literature reviews and PMCF study protocols across their product portfolios. Class III device categories face the steepest compliance burden, with several firms withdrawing legacy gelatin sponge products rather than funding retrospective clinical evaluations.
Hospital purchasing cooperatives are consolidating supplier contracts and demanding standardized formularies across multi-facility networks. Group purchasing organizations in the United States are displacing individual hospital procurement autonomy with centralized hemostasis agent selection. This concentration is most visible in integrated delivery networks spanning multiple states, where clinical preference is yielding to supply chain efficiency metrics.
Pre-Filled Hemostasis Agents Market Segmentation
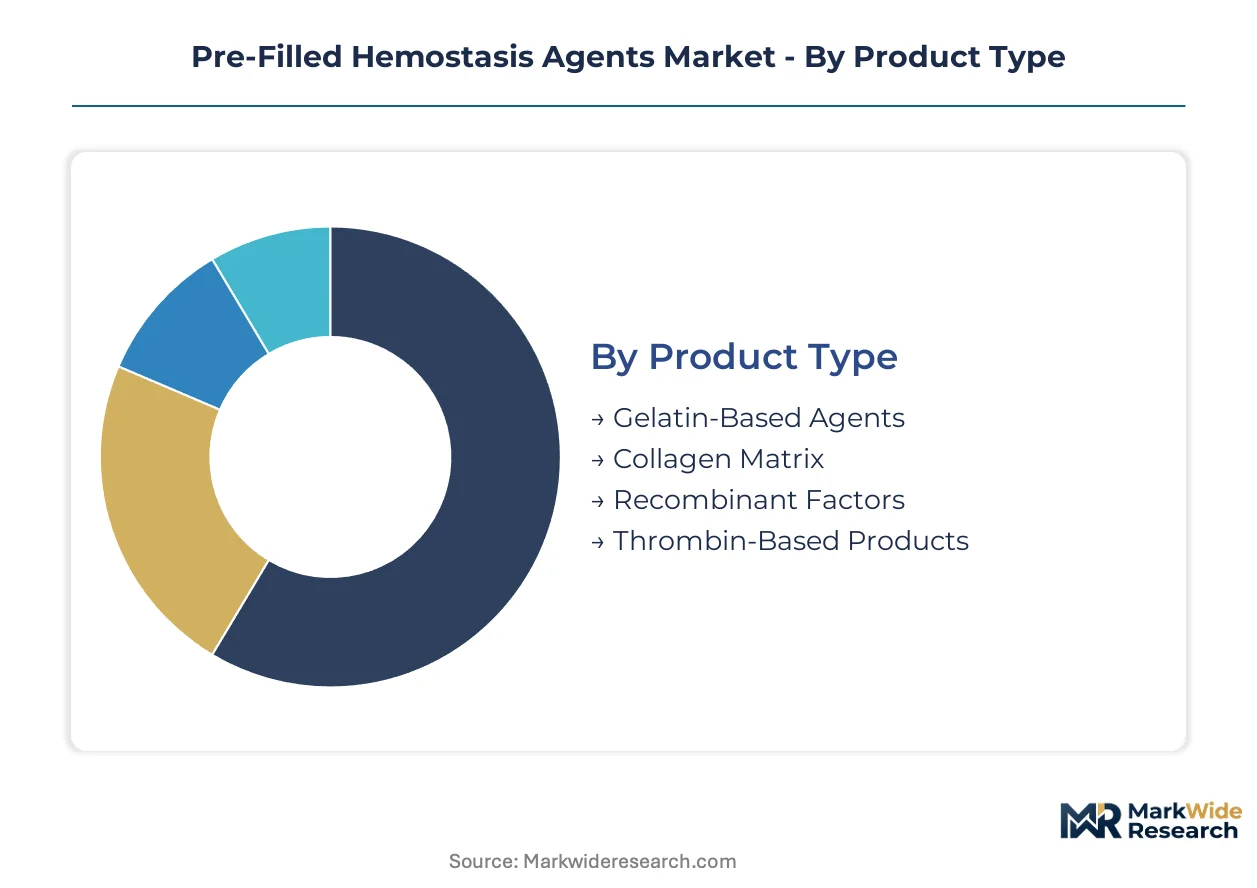
Pre-filled hemostasis agents fragment across four distinct dimensions, each governing procurement logic and margin structure differently. Product composition determines sterility validation burden and reimbursement tier. Delivery format shapes workflow integration and hospital formulary positioning.
Product Type:
Supply concentration in pharmaceutical-grade gelatin processing creates tiered input cost exposure across biological hemostat categories.
- Thrombin-Based Products:Enzymatic formulations derived from bovine or human plasma sources accelerate fibrin conversion at wound sites. United States cardiovascular surgical suites concentrate demand for rapid-on thrombin formats where blood loss reduction justifies premium procurement.
- Recombinant Factors:Genetically engineered thrombin and fibrinogen variants eliminate viral transmission risk and immunogenicity concerns. Pediatric and repeat-surgery populations in German hospital systems are expanding addressable demand for these synthetic alternatives.
- Gelatin-Based Agents:Absorbable sponges and granules provide mechanical hemostasis through platelet activation and scaffold formation.
- Collagen Matrix:Bovine or porcine-derived matrices deliver rapid clotting through contact activation of the intrinsic pathway.
Thrombin-based formulations absorb the bulk of installed capacity; recombinant factors are expanding most quickly.
Application:
Procedure volume trajectories and bleeding risk profiles segment demand intensity across surgical specialties.
- Cardiovascular Procedures:Coronary artery bypass grafting and valve replacement operations generate concentrated demand for rapid-acting hemostasis. United States integrated delivery networks standardize on pre-filled thrombin syringes to compress cardiopulmonary bypass duration.
- Orthopedic Surgery:Joint replacement and spinal fusion procedures require sustained hemostasis across large tissue surfaces. German trauma centers favor flowable gelatin composites for complex fracture repairs where bone bleeding complicates visualization.
- Minimally Invasive Surgery:Laparoscopic and robotic procedures demand specialized applicator formats for confined anatomical spaces.
- Trauma Management:Emergency bleeding control in Level I trauma centers prioritizes speed of deployment over cost optimization.
Cardiovascular applications command the steepest pricing; minimally invasive surgery is climbing the fastest.
Delivery Mode:
Point-of-care preparation burden and sterility assurance requirements differentiate format adoption across facility types.
- Pre-Filled Syringes:Sterile, single-use thrombin and gelatin syringes eliminate pharmacy compounding delays. United States ambulatory surgical centers prioritize these formats to reduce staffing overhead and turnover times.
- Spray Applicators:Pressurized or pump-driven systems distribute hemostatic agents across irregular tissue surfaces. Japanese Ministry of Health, Labour and Welfare reimbursement incentives accelerate adoption of integrated spray-laparoscopy systems.
- Injectable:Direct parenteral administration of liquid hemostats for deep tissue or inaccessible bleeding sites.
- Topical:Sponges, powders, and films applied manually to superficial or exposed wound beds.
Pre-filled syringes absorb the bulk of installed capacity; spray applicators are gaining share fastest.
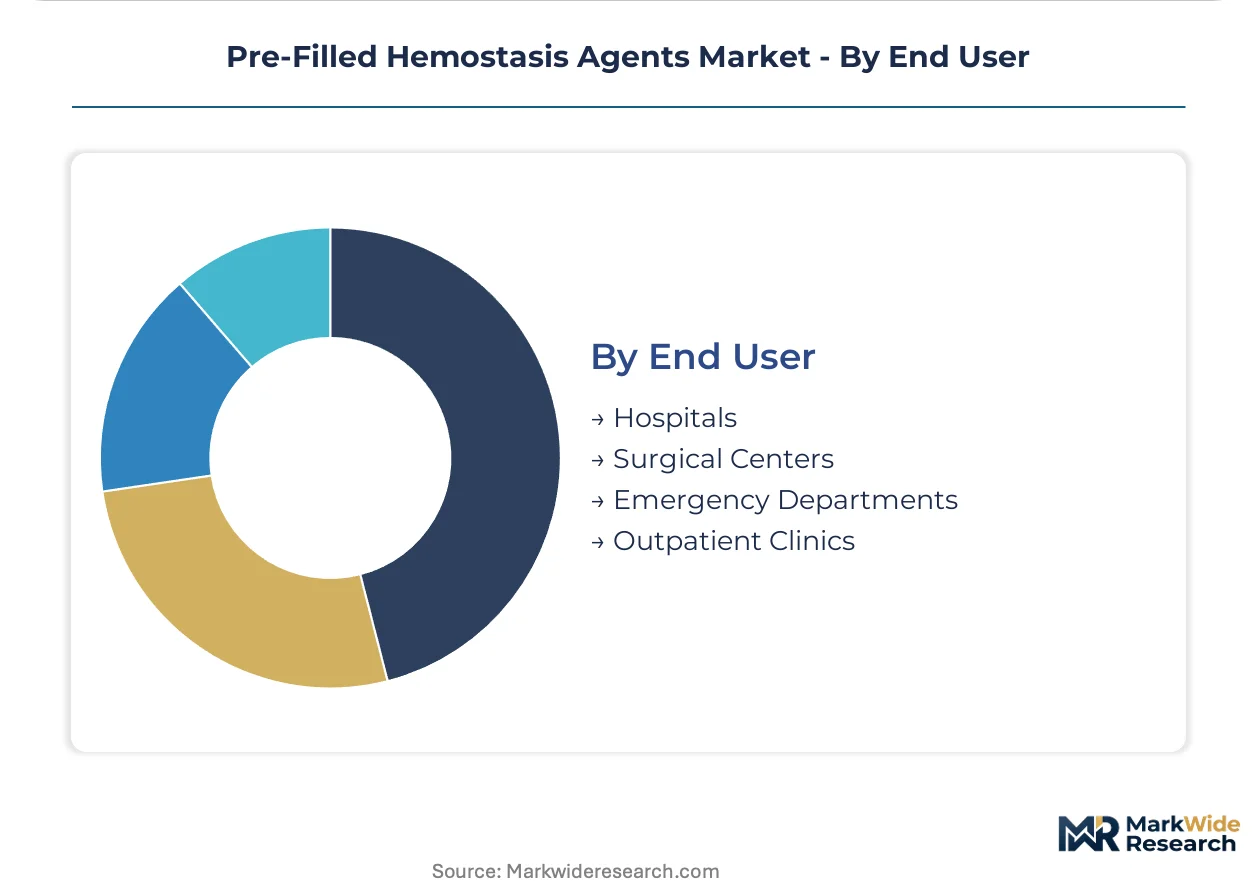
End User:
Purchasing autonomy and formulary control intensity vary sharply across facility categories, reshaping vendor contracting strategies.
- Hospitals:Academic medical centers and community hospitals with centralized pharmacy operations negotiate multi-year hemostat contracts. United States group purchasing organizations consolidate demand across integrated delivery networks spanning multiple states.
- Surgical Centers:Outpatient facilities with limited pharmacy infrastructure favor single-use formats that eliminate compounding. German day-surgery clinics are expanding procurement of pre-filled gelatin syringes for arthroscopic procedures.
- Emergency Departments:Trauma bays require immediate availability of multiple hemostat formats for uncontrolled bleeding scenarios.
- Outpatient Clinics:Minor procedure suites with intermittent surgical volume prioritize low-unit-cost topical formats.
Hospitals absorb the bulk of installed capacity; surgical centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade gelatin processing concentrates in European facilities, creating supply chain dependencies that shape regional procurement strategies and sterilization compliance investments across manufacturing hubs.
United States
Cardiovascular surgical suites in Cleveland Clinic and Mayo Clinic networks standardize on pre-filled thrombin syringes to compress cardiopulmonary bypass duration. FDA biologics sterility requirements mandate terminal sterilization validation for protein-based formulations without activity degradation. Boston's medical device corridor hosts contract manufacturers specializing in recombinant thrombin production for pediatric applications.
Germany
Trauma centers in Berlin and Munich favor flowable gelatin composites for complex fracture repairs where bone bleeding complicates visualization. EU MDR technical documentation mandates force manufacturers to maintain systematic literature reviews and PMCF study protocols. The Baden-Württemberg industrial cluster integrates surgical instrument fabrication with hemostat applicator assembly for laparoscopic systems.
Japan
Ministry of Health, Labour and Welfare premium pricing for innovative hemostatic devices accelerates adoption of integrated spray-laparoscopy systems in Tokyo and Osaka hospitals. PMDA streamlined review pathways for combination products reduce regulatory friction for novel delivery mechanisms. The Kobe biomedical innovation zone anchors translational research partnerships between device manufacturers and university surgical departments.
United Kingdom
NHS England procurement frameworks consolidate hemostat purchasing across integrated care systems, displacing individual hospital formulary autonomy. MHRA post-Brexit regulatory divergence from EU MDR creates parallel submission requirements for biologic-device combinations. The Cambridge-Oxford-London golden triangle concentrates early-stage hemostasis agent development within academic spinout companies.
India
CDSCO accelerated approval pathways for orphan surgical devices expand access to recombinant thrombin in Delhi and Mumbai tertiary centers. Government medical device parks in Andhra Pradesh and Telangana offer tax incentives for hemostat manufacturing localization. Hyderabad's pharmaceutical corridor attracts contract sterilization providers serving domestic and export markets.
Pre-Filled Hemostasis Agents Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and hospital procurement channel depth, producing a tiered structure where scale-driven conglomerates anchor premium pricing while specialized manufacturers capture niche indications. Three archetypes dominate: diversified medical technology conglomerates with surgical channel integration, biologics-focused specialists leveraging recombinant protein platforms, and regional contract manufacturers serving price-sensitive tender markets. Consolidation accelerates through M&A targeting sterile fill-finish capacity, while portfolio diversification into adjacent wound closure categories defends margin position.
Within the diversified conglomerate tier, BD, Ethicon, and Baxter International exemplify scale-driven positioning. BD sustains broad manufacturing scale across multiple delivery formats including pre-filled syringes. Ethicon leverages Johnson & Johnson's surgical channel depth to anchor hospital procurement contracts. Baxter International competes through recombinant factor specialization and blood management integration.
| Leading Market Players |
|---|
| BD (Becton, Dickinson and Company) |
| Medtronic Plc. |
| Ethicon (Johnson & Johnson) |
| Smith & Nephew |
| Integra Life Sciences Corporation |
| Pfizer Inc. |
| Teleflex Incorporated |
| B. Braun SE |
| Baxter International Inc. |
| Others |
Value Network & Pricing Analysis
EU MDR Article 10 technical documentation mandates gate qualified supply access and premium-tier pricing authorization for pre-filled hemostasis agent manufacturers. Compliance investment thresholds stratify vendor tiers, with sterilization-validated producers commanding formulary placement against unbundled competitors lacking PMCF infrastructure.
Pricing Analysis
Warranty and post-market surveillance bundling separate premium thrombin formulations from unbundled gelatin sponge alternatives in hospital procurement. Three-tier pricing structure across premium, standard, and economy levels reflects sterilization validation burden and clinical evidence depth. Cost compression in economy-tier gelatin products intensifies as group purchasing organizations consolidate contract awards. Ambulatory surgical centers exhibit highest price sensitivity, while cardiovascular surgical suites absorb premium thrombin pricing without volume attrition.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for temperature-controlled hemostat logistics. Pharmaceutical-grade gelatin processing concentrates in European facilities, with recombinant thrombin production anchored in Boston's medical device corridor. Single-source vulnerability in bovine-derived collagen supply chains from Ireland and France exposes manufacturers to livestock disease containment protocols. Distribution runs through hospital service centers and surgical center direct-to-site models, with GPO intermediaries consolidating demand aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating toward manufacturers with validated sterilization infrastructure and EU MDR compliance capabilities. Extended notified body audit backlogs are forcing capital-constrained entrants toward contract manufacturing arrangements or exit.
For Market Incumbents: Hedge against autologous blood salvage substitution by deepening recombinant factor portfolios and acquiring sterile fill-finish capacity in low-cost manufacturing zones. Prioritize backward integration into pharmaceutical-grade gelatin processing to insulate margin position from European input volatility. Anchor hospital procurement contracts through integrated delivery network partnerships that displace competitor formulary access.
For New Entrants and Emerging Players: CDSCO accelerated approval pathways in India open a window for orphan surgical device positioning in Delhi and Mumbai tertiary centers. Target ambulatory surgical center spray applicator demand in the United States where pharmacy infrastructure constraints favor single-use formats. Pursue reimbursement strategy partnerships with Japanese Ministry of Health, Labour and Welfare to capture premium pricing for novel delivery mechanisms.
For Investors and Strategic Acquirers: Withdrawal of legacy gelatin sponge products from EU MDR compliance burden is the leading indicator that sterilization-validated manufacturing assets are acquiring scarcity premium. Five-to-ten year viability favors contract manufacturers with ISO 13485 certification and notified body relationships over pure-play developers. Monitor PMDA streamlined review pathway utilization rates as inflection signal for Japanese market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Systematic literature review infrastructure secures Class III device market access against withdrawal-prone competitors. |
| Recombinant Thrombin Capacity Expansion | Genetically engineered production platforms reduce immunogenicity risk for pediatric and repeat-surgery populations. |
| Spray Applicator Laparoscopy Integration | Minimally invasive procedure convergence unifies hemostasis and tissue adhesion in single delivery systems. |
| Group Purchasing Organization Partnership | Integrated delivery network formulary anchoring displaces individual hospital procurement autonomy. |
| Japanese Reimbursement Strategy Development | Ministry of Health, Labour and Welfare premium pricing accelerates novel mechanism adoption in Tokyo and Osaka. |
Research Methodology
Multi-period observation of surgical volume trajectories, regulatory submission timelines, and GPO contract award patterns anchored the trend analysis, supplemented by interviews with hospital procurement managers, biomedical engineers, regulatory affairs specialists, and GPO contracts directors. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up demand modeling across delivery formats and applications triangulated against top-down market sizing from manufacturer capacity disclosures.
Segment-weighting approaches distributed value across product type, application, delivery mode, and end user dimensions throughout the forecast period. CAGRs were derived from surgical procedure growth rates, reimbursement trajectory assumptions, and technology substitution elasticity estimates. Recombinant factor adoption curves and EU MDR compliance cost pass-through rates informed scenario-specific trajectory adjustments.
The model assumes a particular technology adoption path for flowable gelatin-thrombin composites; alternative pathways for autologous blood salvage advancement would alter the outlook for topical hemostasis penetration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Portable Ultrasonic Skin Scrubber Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
Powered Wheelchair Market
Medical Devices
Nasal Implant Market
Medical Devices
Wireless Handheld Ultrasound Devices Market
Medical Devices
Global Enteral Feeding Tubes Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Global Wearable Injector Devices Market
Medical Devices
Implantable Port Devices Market