
 Global Cerebrospinal Fluid Drainage Catheter Market | 2026-2036
Global Cerebrospinal Fluid Drainage Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cerebrospinal Fluid Drainage Catheter Market Intelligence
Demand from specialized neurosurgery centers is rotating away from general trauma care units, which require less sophisticated monitoring devices. Medtronic leverages its extensive distribution network to serve high-volume hospital settings. Integra LifeSciences Corporation specializes in regenerative technologies, including advanced CSF management systems. B. Braun SE competes on the basis of its broad portfolio of neurosurgical products and established presence in European markets.
A cerebrospinal fluid drainage catheter is a sterile, flexible tube designed for placement within the cerebral ventricles or lumbar subarachnoid space. These devices, often made from biocompatible silicone and sometimes impregnated with antibiotics, facilitate the drainage of excess CSF to manage intracranial pressure. Within product types, external ventricular drains remain a standard for acute care, while programmable valves represent a higher-margin segment. Hydrocephalus management constitutes the largest application, with postoperative CSF drainage showing consistent demand.
Market access is governed by stringent regulatory approvals from bodies like the FDA in the United States and the EMA in Europe under its Medical Device Regulation (MDR). In China, the NMPA's requirements for clinical data and device registration influence product launch timelines and development costs. Device manufacturers must navigate these evolving regulatory landscapes while investing in clinical evidence to support claims of improved safety and efficacy.
Market Dynamics
The market's central dynamic is the rotation of demand toward specialized neurosurgery centers, which prioritizes clinical outcomes over unit cost. This shift elevates the importance of infection-resistant materials and advanced valve technologies, concentrating market value within higher-specification product segments.
Growth Catalysts
- Antibiotic-Impregnated Catheters:The development of catheters impregnated with antibiotics directly addresses the critical risk of hospital-acquired infections, improving patient safety and supporting adoption in high-acuity neurosurgical applications.
- Specialized Neurosurgery Centers:Demand is concentrating within high-volume neurosurgery centers in countries like the United States and Germany, which standardizes the use of advanced CSF management systems for complex cases.
- Hydrocephalus Management:The rising incidence of hydrocephalus, particularly in aging populations, provides a consistent and growing procedural volume that underpins stable market expansion for drainage catheters.
Market Restraints
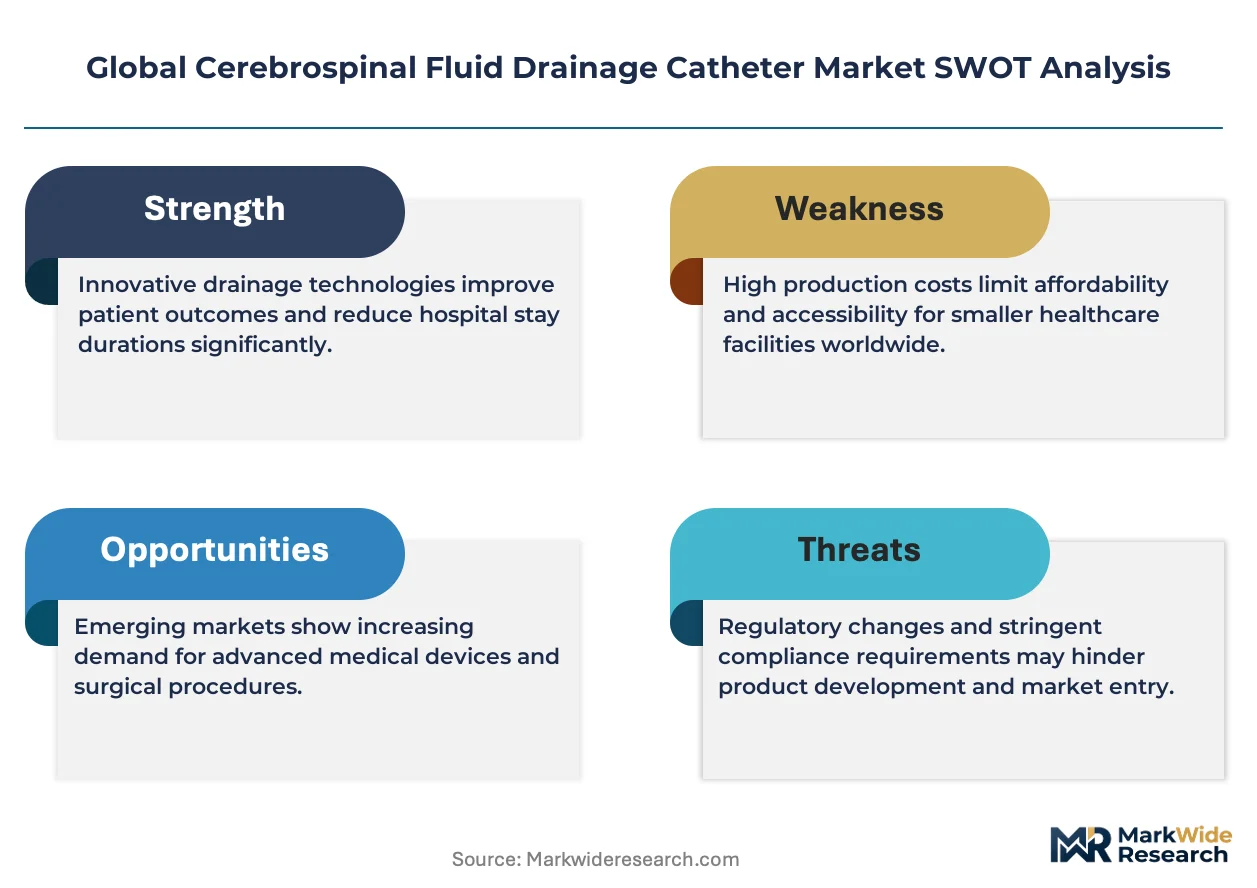
- Stringent Regulatory Approvals:Gaining clearance from bodies like the FDA and complying with Europe's MDR involves extensive clinical data and significant investment, creating high barriers for new device manufacturers.
- Risk of Catheter-Related Complications:Despite material improvements, the persistent risk of infection, blockage, and malfunction remains a significant clinical concern that can limit device longevity and necessitate revision surgeries.
- Substitution by Endoscopic Procedures:For certain types of obstructive hydrocephalus, minimally invasive neuroendoscopic techniques, such as endoscopic third ventriculostomy (ETV), can serve as an alternative to shunt placement, potentially reducing catheter demand.
Strategic Opportunities
- Expansion in China:As the NMPA refines its device registration pathways, a substantial opportunity exists for manufacturers to address the large, underserved patient population for hydrocephalus management.
- Smart Catheter Development:Integrating sensors for real-time intracranial pressure monitoring directly into drainage catheters presents an opportunity to create higher-value, data-driven devices that improve patient management.
- Postoperative Drainage Applications:The consistent demand for temporary CSF drainage following neuro-oncology and complex spinal surgeries represents a stable, adjacent application segment beyond chronic hydrocephalus treatment.
Industry Challenges
- MDR Compliance Burden:The European Union's Medical Device Regulation (MDR) requires manufacturers to produce more extensive clinical evidence for both new and existing devices, increasing compliance costs and resource allocation demands.
- Specialized Neurosurgeon Training:The effective placement and long-term management of advanced devices, particularly programmable valves, depend on specialized surgical expertise, which can be a bottleneck to adoption in less developed healthcare systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cerebrospinal Fluid Drainage Catheter Market |
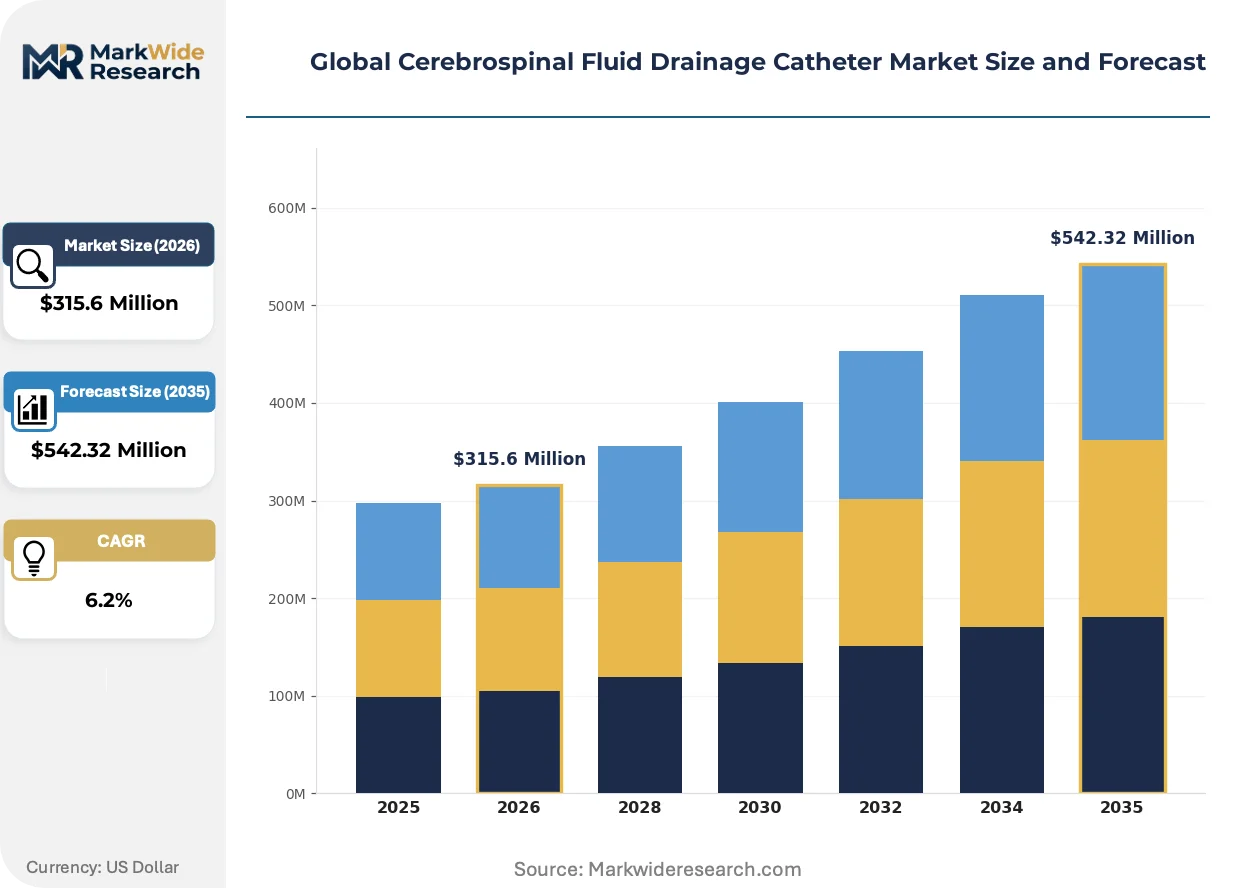
| Market Size in 2026 | $315.6 Million |
| Market Size in 2035 | $542.32 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventricular Catheters, Lumbar Drain Catheters, External Ventricular Drains, Programmable Valves Application: Hydrocephalus Management, Intracranial Pressure Monitoring, Postoperative CSF Drainage, Subarachnoid Hemorrhage Treatment End User: Neurosurgery Centers, Neurology Clinics, Trauma Care Units, Specialized Diagnostic Labs Deployment: Hospital Settings, Specialty Care Facilities, Ambulatory Surgical Centers, Critical Care Units |
| Companies Covered | Integra LifeSciences Corporation, Spiegelberg GmbH & Co. KG, Medtronic, Sophysa, Natus Medical Incorporated, Johnson & Johnson Services, Stryker, Möller Medical GmbH, B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cerebrospinal Fluid Drainage Catheter Market Strategic Shifts & Innovations
Material science advancements and the push for smarter device integration are fundamentally altering cerebrospinal fluid management. Innovations are focused on reducing complication rates and providing clinicians with more control over treatment, moving beyond simple fluid drainage to active pressure management.
Antibiotic-impregnated silicone is a key material innovation designed to reduce the risk of device-related infections. Specialized neurosurgery centers are rapidly adopting these advanced catheters for both acute and chronic hydrocephalus management. This adoption is bifurcating the market into a premium segment focused on superior infection control and a standard segment for less critical, short-duration applications.
Europe's Medical Device Regulation (MDR) is imposing more rigorous requirements for clinical evidence and post-market surveillance. This regulation increases the burden of proof for safety and efficacy, raising development costs and extending timelines for market entry. The external ventricular drain segment, a mature product category, is particularly affected, forcing manufacturers to generate new clinical data for re-certification.
A clear shift in purchasing is occurring, with specialized neurosurgery centers consolidating their buying power around systems offering superior clinical outcomes. This trend displaces procurement from general hospital units, which often prioritize lower-cost, less sophisticated devices. This consolidation is most visible in the United States and Germany, where high-volume neurological institutes influence technology adoption standards for the broader market.
Global Cerebrospinal Fluid Drainage Catheter Market Segmentation
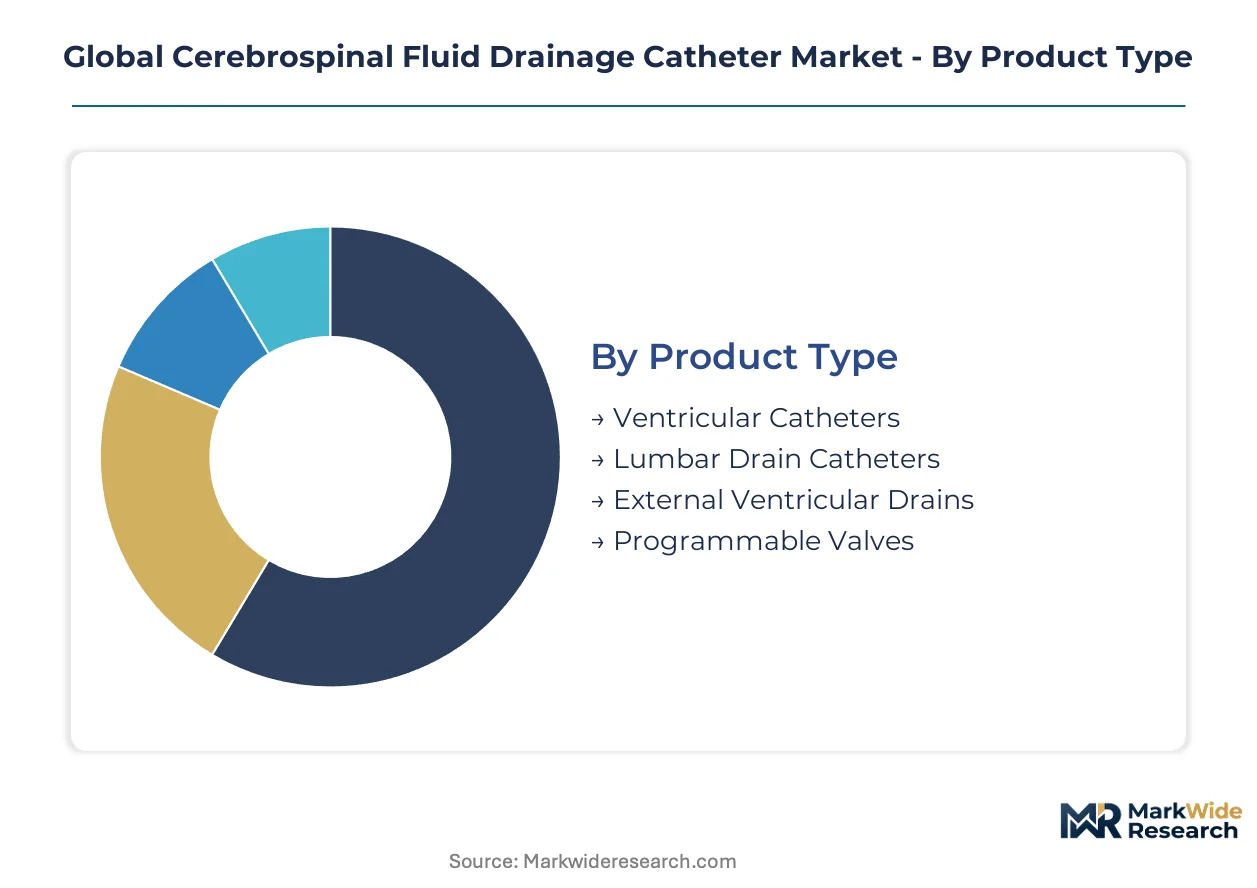
The global cerebrospinal fluid drainage catheter market's segmentation reveals distinct demand patterns and technological priorities. Understanding these segments is crucial for manufacturers to align product development with clinical needs and for healthcare providers to optimize patient outcomes. Each category highlights specific areas of innovation and market concentration.
Product Type:
The product type segment faces substitution pressure from alternative procedures, particularly for less complex cases.
- External Ventricular Drains:These sterile, flexible tubes are a standard for acute management of intracranial pressure, facilitating temporary CSF drainage. Demand concentrates in specialized neurosurgery centers for emergency interventions, driven by their immediate efficacy in critical care settings.
- Programmable Valves:These advanced devices allow non-invasive adjustment of CSF drainage pressure post-implantation, enhancing patient-specific hydrocephalus management. Their higher cost and complexity are justified by improved long-term outcomes and reduced revision surgeries in leading neurological institutes.
- Ventricular Catheters:These catheters are typically implanted into the cerebral ventricles for both temporary and permanent CSF diversion, often as components of shunt systems.
- Lumbar Drain Catheters:Placed in the lumbar subarachnoid space, these devices manage CSF pressure in specific conditions, including postoperative leak management and subarachnoid hemorrhage.
External Ventricular Drains retain volume leadership for acute interventions; Programmable Valves hold the steepest expansion curve in chronic hydrocephalus management.
Application:
The application landscape defines specific clinical needs, with each segment reflecting distinct patient populations and procedural requirements.
- Hydrocephalus Management:This application represents the largest segment, addressing the buildup of CSF in the brain through permanent or temporary drainage systems. Its consistent growth is underpinned by the rising incidence of hydrocephalus, especially in aging demographics in countries like the United States and Germany.
- Postoperative CSF Drainage:This segment involves temporary drainage of CSF following neuro-oncology procedures and complex spinal surgeries to prevent complications. Demand remains stable in high-volume surgical centers, prioritizing infection-resistant catheters for patient safety.
- Intracranial Pressure Monitoring:This application involves devices that measure and manage pressure within the skull, often used in conjunction with drainage to guide treatment decisions in critical care.
- Subarachnoid Hemorrhage Treatment:CSF drainage catheters are utilized in managing complications from subarachnoid hemorrhage, helping to reduce intracranial pressure and prevent hydrocephalus.
Hydrocephalus Management drives the largest procedural volumes; Postoperative CSF Drainage shows consistent demand, expanding steadily.
End User:
The end user segment highlights the evolving procurement preferences and clinical capabilities across different healthcare facility types.
- Neurosurgery Centers:These specialized facilities are the primary consumers of advanced CSF drainage catheters, prioritizing devices that offer superior clinical outcomes and infection resistance. Their concentration in regions like the United States and Germany dictates technology adoption standards.
- Neurology Clinics:These clinics often manage the long-term care of patients with shunts and require follow-up and adjustment services for programmable valves. Their demand centers on devices supporting chronic management and patient quality of life.
- Trauma Care Units:These units primarily require temporary CSF drainage solutions for acute head injuries, often favoring standard, readily available external ventricular drains for immediate intervention.
- Specialized Diagnostic Labs:These labs support the diagnostic process for conditions requiring CSF analysis, indirectly influencing the demand for drainage procedures but not direct catheter users.
Neurosurgery Centers command the highest value purchases; Neurology Clinics are gaining share as long-term management improves.
Deployment:
The deployment segment categorizes where these devices are utilized, reflecting the varying patient acuity and infrastructure capabilities of different settings.
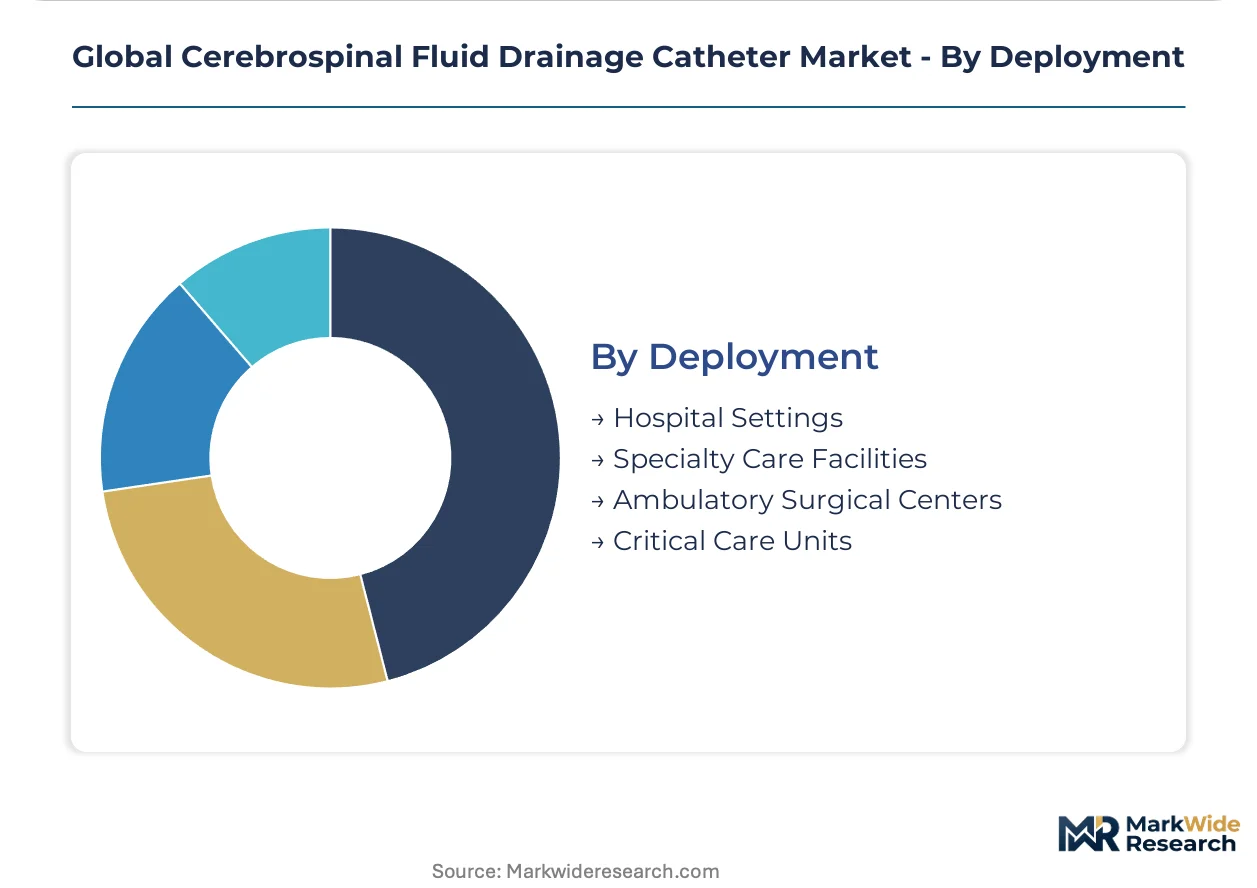
- Hospital Settings:General hospital environments, encompassing various departments, represent a broad deployment area for CSF drainage catheters, particularly for acute and postoperative care. High-volume hospitals integrate these devices across neurosurgery and critical care units.
- Critical Care Units:These specialized units within hospitals focus on acutely ill patients requiring intensive monitoring and immediate intervention for intracranial pressure management. Demand here emphasizes reliable, high-performance external drainage systems for rapid response.
- Specialty Care Facilities:These facilities cater to specific neurological conditions, often requiring advanced CSF management systems for chronic conditions, including rehabilitation and long-term care.
- Ambulatory Surgical Centers:These centers perform less complex, outpatient procedures; their use of CSF drainage catheters is limited, primarily for minor interventions or temporary management before transfer.
Hospital Settings remain the largest deployment channel; Specialty Care Facilities represents the fastest-growing trajectory for long-term patient management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global cerebrospinal fluid drainage catheter market sees significant demand originating from established healthcare systems, with advanced medical device technology flowing towards specialized neurosurgery centers. These regions prioritize clinical outcomes and infection control, influencing product development and market access strategies.
United States
Demand for advanced CSF drainage catheters in the United States stems from a high incidence of hydrocephalus and a concentration of leading neurosurgery centers. The FDA's stringent regulatory approval process ensures device safety and efficacy, influencing product launch timelines. Major medical technology corridors like Boston and the Bay Area drive innovation and adoption of high-specification devices.
Germany
Germany represents a strong market for cerebrospinal fluid drainage catheters, driven by an aging population and a well-developed healthcare infrastructure. Compliance with the EMA's Medical Device Regulation (MDR) is critical for market entry and sustained presence. Specialized neurological institutes in cities like Munich and Berlin are key adoption hubs for advanced CSF management systems.
China
China offers a substantial growth opportunity for cerebrospinal fluid drainage catheters due to its large, underserved patient population and expanding healthcare access. The NMPA's evolving device registration pathways influence product development and local manufacturing partnerships. Medical device industrial parks in Shanghai and Suzhou are becoming centers for both production and market penetration.
Japan
Japan's market for CSF drainage catheters is characterized by an aging demographic and a strong emphasis on high-quality medical devices. The PMDA's regulatory framework ensures rigorous evaluation of new technologies, supporting patient safety. Research and development clusters in Tokyo and Kyoto focus on integrating advanced sensor technologies into neurosurgical devices.
Global Cerebrospinal Fluid Drainage Catheter Market Key Industry Players
Player mix skews toward large, diversified medical technology companies alongside specialized neurosurgical device manufacturers. The market exhibits a tiered structure, with established global players dominating the premium segment through extensive distribution. Strategic archetypes include comprehensive solution providers, specialized innovators focusing on niche applications, and regional manufacturers. Portfolio diversification and technology licensing are dominant competitive moves.
Among global medical technology leaders, Medtronic and Johnson & Johnson Services represent diversified players offering a broad range of medical devices, including neurosurgical solutions. These corporations leverage vast R&D resources and global distribution networks. B. Braun SE, a European medical device conglomerate, occupies a strong position, particularly within European markets, through its broad neurosurgical product portfolio and established presence.
| Leading Market Players |
|---|
| Integra LifeSciences Corporation |
| Spiegelberg GmbH & Co. KG |
| Medtronic |
| Sophysa |
| Natus Medical Incorporated |
| Johnson & Johnson Services |
| Stryker |
| Möller Medical GmbH |
| B. Braun SE |
| Others |
Cost & Logistics Intelligence
Volume-based purchasing contracts, common in high-volume hospital settings, lock in both supply access and offer buyers greater price visibility for standard cerebrospinal fluid drainage catheters.
Pricing Analysis
The technology-generation pricing gap differentiates advanced programmable valves from traditional external ventricular drains. Value-based pricing dominates the premium segment, driven by superior clinical outcomes and reduced revision surgeries. Price differentiation stems from advanced material properties like antibiotic impregnation and stringent regulatory certifications such as FDA and EMA approvals. Pricing softness affects the standard EVD segment, as general trauma care units prioritize unit cost. Specialized neurosurgery centers exhibit lower price sensitivity for high-specification devices.
Supply Chain Analysis
The United States and Germany anchor the production of high-value components for advanced cerebrospinal fluid management systems. Supply chains draw from specialized manufacturers of biocompatible silicone, advanced valve mechanisms, and antibiotic compounds. Single-source vulnerability for highly specialized components represents a structural risk, particularly for programmable valves. Distribution runs through direct sales forces and specialized medical device distributors, serving neurosurgery centers and critical care units globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market for cerebrospinal fluid drainage catheters faces ongoing substitution defense, primarily from minimally invasive neuroendoscopic techniques like endoscopic third ventriculostomy.
For Market Incumbents:
Compound existing distribution network strengths by offering comprehensive training programs for advanced programmable valves in emerging markets. Invest further in clinical evidence generation to demonstrate superior long-term outcomes of antibiotic-impregnated catheters, countering persistent infection risks. Leverage extensive R&D resources to develop integrated smart catheter solutions, providing active pressure management. This strategy defends against new entrants focusing on niche technology advancements.
For New Entrants and Emerging Players:
A certification fast-track for innovative material science presents a significant opportunity to access specific regional markets. Target the underserved patient population in China by focusing on NMPA-compliant, cost-effective solutions for hydrocephalus management. Develop data-driven devices with integrated sensors for real-time intracranial pressure monitoring, offering a distinct go-to-market angle. This approach allows penetration into higher-value segments by addressing unmet clinical needs.
For Investors and Strategic Acquirers:
Capital is best deployed toward specialized innovators focusing on advanced valve technologies and smart catheter development. Long-term viability hinges on companies capable of navigating stringent regulatory landscapes and demonstrating superior patient outcomes. Acquisition targets should possess strong intellectual property in infection-resistant materials or integrated monitoring capabilities. The signal to watch is the increasing adoption rate of smart catheter prototypes in leading neurosurgery centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Evidence Investment | Reinforces product claims under MDR, improving market access and clinician confidence. |
| Antibiotic-Impregnated Catheter Expansion | Reduces infection rates, enhancing patient safety and driving adoption in high-acuity settings. |
| Smart Catheter Development | Integrates real-time monitoring, creating higher-value devices for precision patient management. |
| China Market Entry Strategy | Addresses a large, underserved patient population, unlocking substantial growth potential. |
| Specialized Neurosurgery Center Partnerships | Secures preferred vendor status and influences technology adoption standards across the market. |
Research Approach
Operator-level perspectives from neurosurgery center directors, hospital procurement leads, regulatory affairs specialists, and R&D engineers anchored the qualitative base of this analysis. Primary interviews were triangulated with extensive secondary research, drawing from FDA filings, EMA submissions, clinical trial databases, and industry reports. This combined approach ensured both bottom-up market insights and top-down validation of market trends.
Sensitivity analysis framed the analytical framework, modeling the cerebrospinal fluid drainage catheter market across the projection horizon. Segmentation dimensions included product type, application, end user, deployment, and regional regulatory landscapes, each modeled independently. Compound annual growth rates were derived from historical data analysis and projected market drivers, with neurosurgical procedure volumes and hydrocephalus incidence serving as key forecast inputs.
Underlying assumptions cover regulatory stability, technological progression, and healthcare infrastructure development, with deviation risk concentrated in unforeseen policy shifts or rapid alternative technology adoption. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Venturi Mask Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Kirschner Wires Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Global Automated External Defibrillators Market