
 Chip-On-The-Tip Endoscopes Market | 2026-2036
Chip-On-The-Tip Endoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Chip-On-The-Tip Endoscopes Market Outlook
Asset-light leasing models for high-definition endoscope systems is tilting competitive dynamics toward manufacturers with captive financing arms. Olympus Corporation leverages its established hospital relationships across Japan to sustain recurring revenue streams from service contracts. Karl Storz SE & Co. KG anchors its position through in-house optical component production that controls quality and reduces supplier dependency. Fujifilm Holdings Corporation differentiates by integrating digital imaging platforms with proprietary image-processing algorithms.
Chip-on-the-tip endoscopes integrate a miniaturized CMOS or CCD image sensor directly at the distal tip of the insertion tube, eliminating fiber-optic relay lenses and enabling native high-definition video transmission through digital signal processing. These devices serve primarily to provide real-time visualization of mucosal surfaces and operative fields during diagnostic and interventional procedures across gastroenterology, pulmonology, and urology. Flexible endoscopes capture expanding procedure volumes in outpatient settings where patient throughput and turnaround efficiency determine capital allocation. Digital imaging technology leads investment intensity as manufacturers compete on resolution, color fidelity, and AI-compatible data formats. Video endoscopes command premium positioning in surgical centers where 4K and 3D visualization integrate with operating room navigation systems.
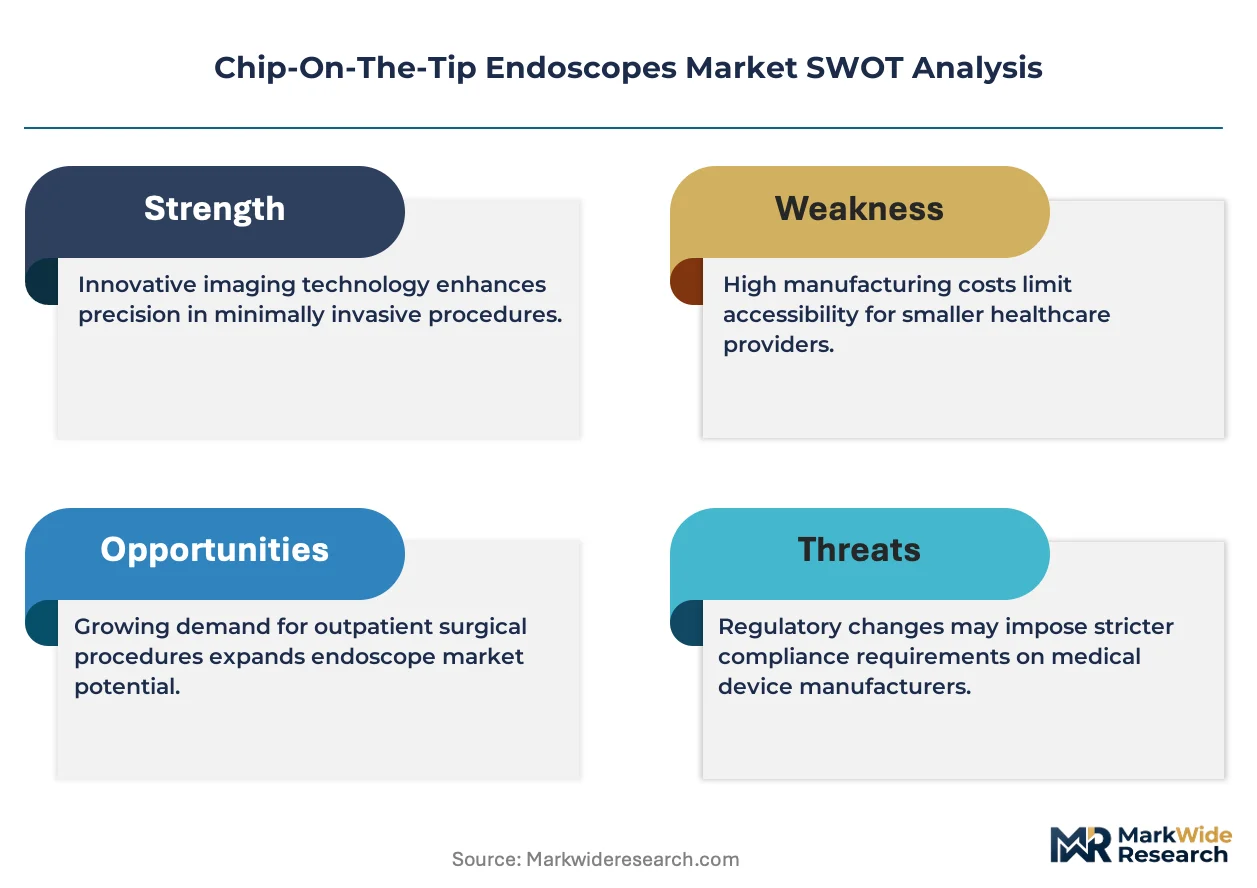
The FDA enforces reprocessing validation requirements under 510(k) clearance pathways that elevate barriers for new flexible endoscope entrants. The EU Medical Device Regulation mandates clinical evidence and post-market surveillance that extend certification timelines for chip-on-the-tip systems sold in Germany, France, and Italy. Japan's Ministry of Health, Labour and Welfare maintains stringent pharmaceutical and medical device approval standards that domestic incumbents navigate with established regulatory affairs infrastructure. Stakeholders must monitor how reimbursement shifts toward value-based frameworks reshape procurement criteria for capital-intensive visualization equipment.
Market Dynamics
The FDA's updated reprocessing guidelines for flexible endoscopes are compressing product lifecycles and forcing manufacturers toward disposable architectures. This regulatory pressure intersects with CMOS sensor miniaturization to restructure competitive advantage around infection control credentials rather than optical performance alone.
Growth Catalysts
- Outpatient Procedure Volume:Ambulatory surgical centers in the United States are expanding gastroenterology throughput, creating installed base demand for video endoscopes with rapid turnaround capabilities.
- EU MDR Clinical Evidence Requirements:The European Union Medical Device Regulation mandates post-market surveillance systems that favor established manufacturers with regulatory affairs infrastructure, consolidating procurement toward certified suppliers.
- CMOS Sensor Cost Curves:Semiconductor fabrication scale economies are reducing image sensor unit costs, enabling high-definition chip-on-the-tip architectures at price points accessible to mid-tier hospitals.
Market Restraints
- Optical Component Supply Concentration:Precision lens grinding capabilities cluster in German and Japanese manufacturing bases, creating single-source vulnerability for distal tip objective assemblies.
- Reprocessing Validation Burden:FDA 510(k) clearance pathways require exhaustive sterilization efficacy documentation that extends development timelines for flexible endoscope entrants.
- Capital Equipment Replacement Cycles:Hospital capital expenditure compression following pandemic-era balance sheet stress is elongating endoscope system refresh intervals from five to seven years.
Strategic Opportunities
- Semi-Disposable Architecture:Insertion tube and distal tip designs with limited-use lifespans bypass reprocessing liability while capturing recurring revenue from consumable components.
- Artificial Intelligence Integration:Real-time polyp detection algorithms from digital imaging platforms command premium positioning in screening colonoscopy workflows.
- Japan Domestic Production:METI industrial policy supports medical device manufacturing clusters in Tokyo and Osaka, creating regulatory pathway advantages for locally produced chip-on-the-tip systems.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Miniaturized electromechanical design expertise for distal tip integration concentrates among semiconductor and medical device crossover specialists.
- Legacy System Interoperability:Hospital video processors and light source units require backward compatibility engineering that fragments R&D allocation across multiple connector standards.
- ISO 13485 Certification Timelines:Quality management system audits for medical device manufacturing extend supplier qualification periods, constraining component sourcing flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip-On-The-Tip Endoscopes Market |
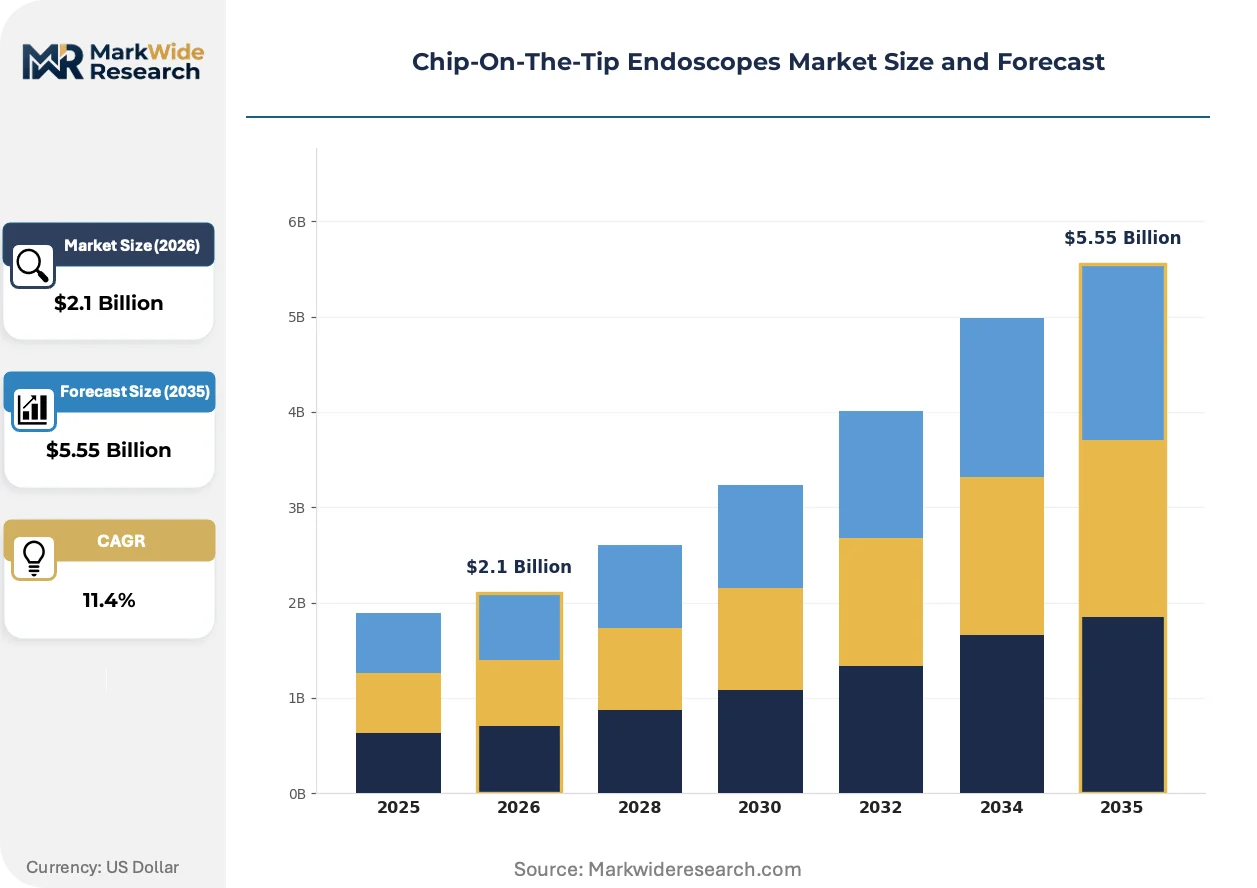
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Endoscopes, Flexible Endoscopes, Rigid Endoscopes, Video Endoscopes Technology: Digital Imaging, Optical Fiber, Miniaturized Sensors, Video Capture End User: Hospitals, Outpatient Clinics, Research Laboratories, Surgical Centers Application: Gastroenterology, Pulmonology, Urology, ENT Procedures |
| Companies Covered | Olympus Corporation, Karl Storz SE & Co. KG, Fujifilm Holdings Corporation, Boston Scientific Corporation, Medtronic plc, Stryker Corporation, HOYA Corporation, Richard Wolf GmbH, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip-On-The-Tip Endoscopes Market Strategic Shifts
Digital signal processing architectures are collapsing the traditional separation between image acquisition and visualization hardware, enabling software-defined endoscopy platforms that upgrade through firmware rather than capital replacement.
Single-use distal tip assemblies are collapsing the economic logic of reusable endoscope reprocessing, as hospital infection control departments absorb liability costs that now exceed per-procedure disposable premiums. Outpatient surgical centers in the United States are adopting these architectures fastest, where patient throughput economics prioritize turnaround speed over capital asset utilization. The structural consequence is compressing manufacturer business models toward consumable revenue streams and away from installed base service contracts.
The EU Medical Device Regulation's clinical evidence requirements are extending certification timelines for chip-on-the-tip systems sold in Germany, France, and Italy. Manufacturers must now submit post-market surveillance data and risk management documentation that previously sufficed with predicate device equivalence. High-definition flexible endoscopes with novel sensor configurations face the steepest compliance burden, pushing some suppliers toward incremental modifications of cleared architectures rather than breakthrough innovations.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, forcing manufacturers to compete on discrete maintenance pricing rather than bundled lifetime cost proposals. This behavioral shift is most visible in Japanese university hospitals, where centralized purchasing consortia negotiate service level agreements separately from device acquisition. The disaggregation is compressing manufacturer margin structures and accelerating third-party independent service organization entry into preventive maintenance workflows.
Chip-On-The-Tip Endoscopes Market Segmentation
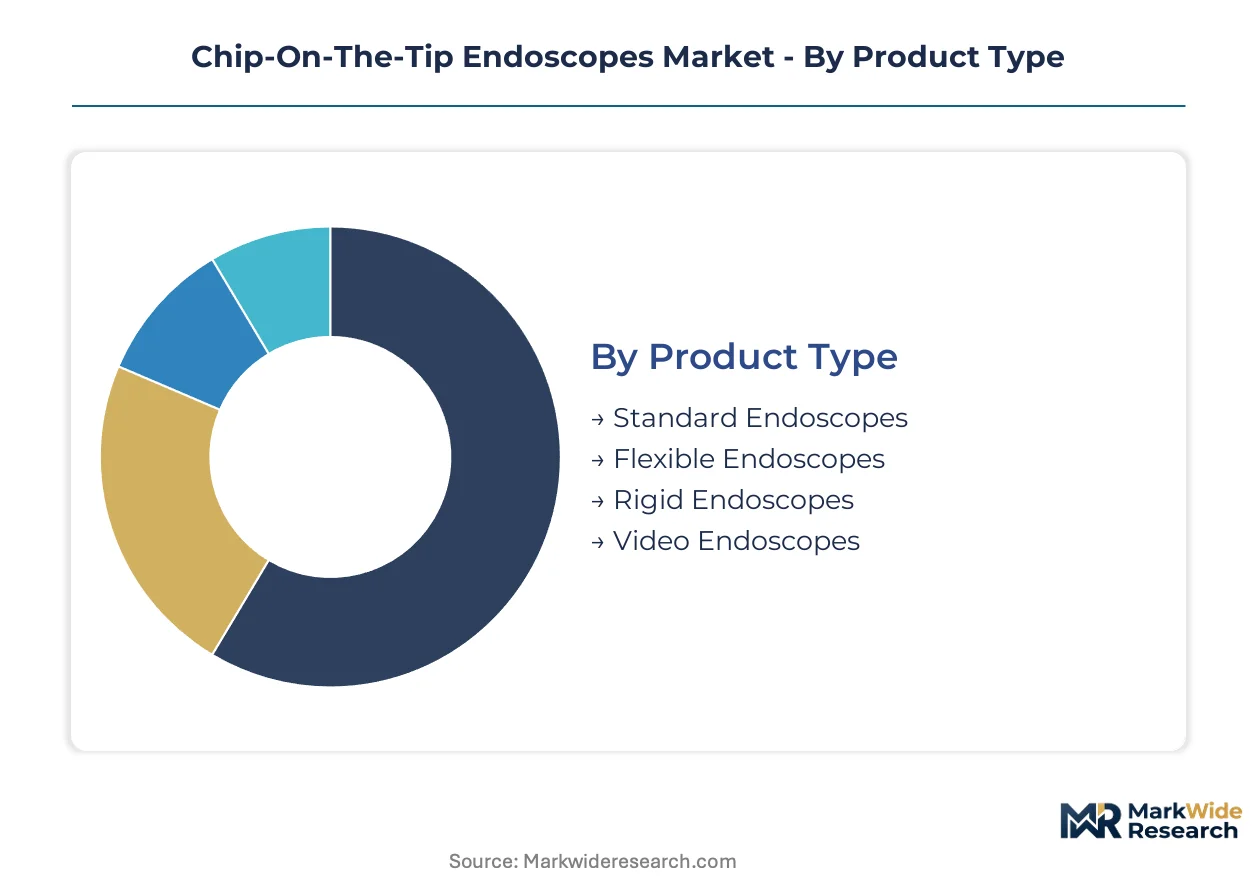
Chip-on-the-tip architectures fragment across procedure requirements, capital intensity thresholds, and sterilization protocols. Manufacturers configure sensor placement, insertion tube flexibility, and imaging pipelines to match distinct clinical workflows and purchasing authority structures.
Product Type:
Use-case spectrum spans diagnostic screening through interventional surgery, with flexibility and video capability determining site-of-service placement.
- Flexible Endoscopes:Articulating insertion tubes with distal-tip CMOS sensors enable real-time mucosal navigation through tortuous anatomical paths. Demand concentrates in United States ambulatory surgical centers where gastroenterology throughput economics prioritize rapid patient turnaround.
- Video Endoscopes:Native digital signal transmission eliminates fiber-optic degradation, supporting 4K resolution and AI-compatible data formats. Procurement in Japanese university hospitals favors these systems for integration with operating room navigation platforms.
- Standard Endoscopes:Conventional fiber-optic relay designs serving cost-constrained facilities with established reprocessing infrastructure.
- Rigid Endoscopes:Stainless steel insertion tubes for arthroscopy and laparoscopy where anatomical access permits straight-line instrument paths.
Established volume favors flexible designs; emerging adoption favors video architectures with software-upgrade pathways.
Technology:
Cost tier stratification separates premium digital platforms from legacy optical systems, with semiconductor integration driving performance differentiation.
- Digital Imaging:Software-defined pipelines enable post-processing algorithms and firmware-based feature expansion without hardware replacement. Hospital procurement in Germany is expanding for systems supporting real-time polyp detection workflows.
- Miniaturized Sensors:Sub-millimeter CMOS and CCD packages at the distal tip eliminate relay lens complexity and reduce cross-sectional profile. Manufacturing scale economies from consumer electronics are compressing unit costs for mid-tier hospital access.
- Optical Fiber:Coherent fiber bundles for budget-sensitive installations where image quality requirements permit analog transmission limitations.
- Video Capture:Integrated recording and documentation systems for litigation protection and quality assurance auditing in United States surgical centers.
Capital allocation concentrates on digital imaging; miniaturized sensors are climbing the fastest as semiconductor fabrication matures.
End User:
Customer type determines purchasing authority structure, with centralized consortia negotiating differently than departmental capital committees.
- Hospitals:Integrated delivery networks with infection control departments absorbing reprocessing liability costs. German hospital systems are expanding chip-on-the-tip adoption for minimally invasive gastroenterology procedures.
- Surgical Centers:Focused-service facilities where per-procedure economics favor disposable distal-tip architectures over capital-intensive reusable systems.
- Outpatient Clinics:Lower-acuity settings with constrained capital budgets and reliance on manufacturer leasing programs.
- Research Laboratories:Preclinical and translational imaging requiring customizable sensor configurations and non-standard wavelength sensitivity.
Procurement volume concentrates in hospitals; steepest expansion trajectory sits with surgical centers adopting semi-disposable models.
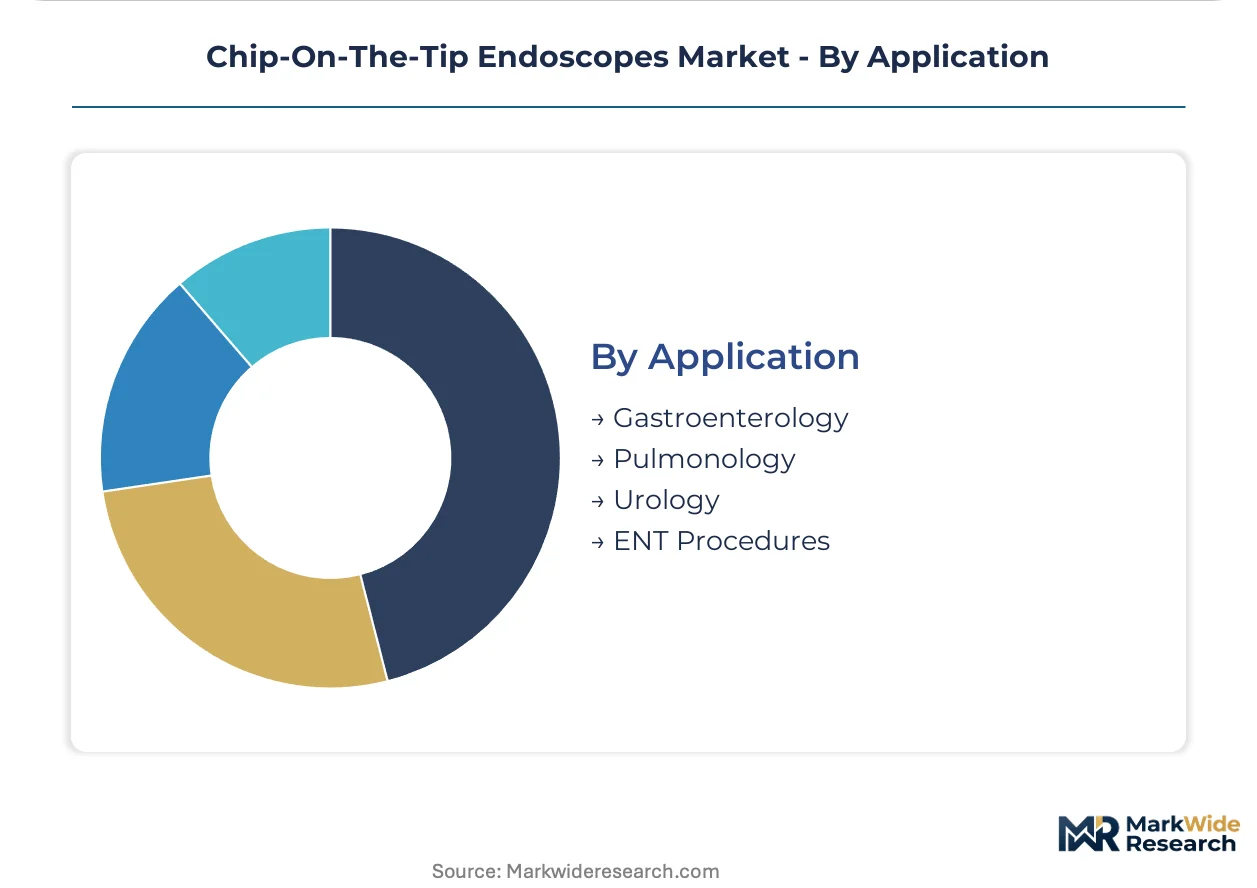
Application:
Procedure-specific anatomical constraints and reimbursement frameworks reshape sensor specification requirements across specialties.
- Gastroenterology:Colonoscopy and upper GI screening drives the largest procedure volumes, with Japan's Ministry of Health, Labour and Welfare reimbursement policies influencing technology adoption timelines.
- Pulmonology:Bronchoscopy applications require smaller working channels and integrated suction capability for airway navigation.
- Urology:Cystoscopy and ureteroscopy demand waterproof distal-tip sealing and compatibility with lithotripsy energy delivery.
- ENT Procedures:Sinonasal and laryngeal access requires acute angulation ranges and compact control body ergonomics.
Procedure volume concentrates in gastroenterology; pulmonology is gaining share fastest with lung cancer screening program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing clusters in Japan and Germany, while the United States remains a net importer of high-definition chip-on-the-tip systems. Domestic production capacity in these three markets shapes competitive positioning for manufacturers seeking regulatory pathway advantages.
United States
Ambulatory surgical centers in Texas and Florida are expanding gastroenterology throughput, driving installed base demand for rapid-turnaround video endoscopes. FDA 510(k) clearance pathways enforce reprocessing validation requirements that elevate barriers for new flexible endoscope entrants. Minneapolis and Boston anchor medical device engineering clusters where third-party independent service organizations are entering preventive maintenance workflows.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia are expanding adoption of chip-on-the-tip devices for minimally invasive gastroenterology procedures. EU Medical Device Regulation mandates clinical evidence and post-market surveillance that extend certification timelines for systems sold across Germany, France, and Italy. Precision lens grinding capabilities concentrate in Stuttgart and Jena, creating single-source vulnerability for distal tip objective assemblies.
Japan
Centralized purchasing consortia in Tokyo and Osaka are unbundling after-sales service contracts from capital equipment purchases. Ministry of Health, Labour and Welfare maintains stringent pharmaceutical and medical device approval standards that domestic incumbents navigate with established regulatory affairs infrastructure. METI industrial policy supports manufacturing clusters in Tokyo and Osaka, creating regulatory pathway advantages for locally produced chip-on-the-tip systems.
China
Domestic hospital procurement departments in Shanghai and Beijing are prioritizing cost-competitive digital imaging platforms for screening colonoscopy workflows. NMPA approval standards for Class III medical devices require extensive clinical trials that favor joint ventures with established multinational manufacturers. Yangtze River Delta manufacturing bases are scaling CMOS sensor packaging capabilities for mid-tier hospital price points.
South Korea
Seoul Capital Area university hospitals are integrating 4K visualization systems with operating room navigation platforms. MFDS maintains harmonized standards with FDA and PMDA that streamline approval pathways for manufacturers with prior US or Japan clearances. Busan-Ulsan industrial corridors host precision electromechanical component suppliers serving distal tip assembly integration.
Chip-On-The-Tip Endoscopes Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream of final assembly, supplying miniaturized sensors and optical subassemblies to finished device manufacturers. Market structure tilts toward consolidated procurement authority as hospital systems and surgical center chains centralize purchasing decisions. Three archetypes dominate: diversified medical technology conglomerates with captive financing arms, specialized endoscope manufacturers with in-house optical production, and semiconductor crossover suppliers leveraging consumer electronics scale economies. Competitive moves concentrate on semi-disposable architecture development and artificial intelligence integration for real-time diagnostic assistance.
Among Japanese and German diversified manufacturers, Olympus Corporation and Karl Storz SE & Co. KG exemplify platform integrators with established hospital relationships and service contract infrastructures. Fujifilm Holdings Corporation occupies a position bridging optical component production and digital imaging platform integration. These three entities represent the archetype of manufacturers navigating regulatory complexity through dedicated regulatory affairs infrastructure and localized production clustering.
| Leading Market Players |
|---|
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Fujifilm Holdings Corporation |
| Boston Scientific Corporation |
| Medtronic plc |
| Stryker Corporation |
| HOYA Corporation |
| Richard Wolf GmbH |
| CONMED Corporation |
| Others |
Value Chain & Pricing Dynamics
Stuttgart and Jena's precision lens grinding clusters concentrate distal tip objective assembly capacity, feeding downstream pricing power to German and Japanese manufacturers who control critical optical component supply. CMOS sensor fabrication scale economies from Yangtze River Delta packaging facilities are compressing unit costs for mid-tier hospital systems, yet single-source vulnerability in electromechanical distal tip integration preserves premium capture at the system level.
Pricing Analysis
Hospital procurement departments anchor a three-tier pricing structure across premium, standard, and economy levels, with 4K video endoscopes commanding significant premiums over fiber-optic alternatives based on FDA 510(k) clearance tier and integrated AI compatibility. Price differentiation hinges on certification grade and after-sales service bundling, with Japanese university hospitals showing least sensitivity due to centralized consortia negotiating power. Pricing pressure stems from outpatient surgical centers in Texas and Florida prioritizing per-procedure disposable economics over capital-intensive reusable systems, compressing margins on traditional installed-base service contracts.
Supply Chain Analysis
CMOS wafer fabrication feeds from Taiwan and South Korea, while precision optical glass and electromechanical distal tip components draw from Germany and Japan, creating geographic concentration across three manufacturing clusters. Raw material dependencies include semiconductor-grade silicon, specialty optical polymers, and biocompatible sterilization-resistant alloys. Single-source vulnerability in sub-millimeter sensor packaging creates supply chain risk, as ISO 13485 certification timelines extend supplier qualification periods. Distribution runs through hospital GPO contracts and surgical center leasing programs, with third-party independent service organizations fragmenting aftermarket service revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Miniaturized electromechanical design expertise for distal tip integration concentrates among a narrow pool of semiconductor and medical device crossover specialists, creating acquisition scarcity and R&D bidding wars for qualified biomedical engineering talent.
For Market Incumbents: Pre-empt semi-disposable architecture commoditization by accelerating firmware-defined platform development that locks hospital customers into recurring software upgrade revenue streams. Backward integration into CMOS sensor packaging through Yangtze River Delta joint ventures reduces exposure to Taiwan supply concentration. Defensive patent filings around real-time polyp detection algorithms create barriers against AI-native entrants threatening premium video endoscope positioning. For New Entrants and Emerging Players: Chinese provincial hospital systems outside Shanghai and Beijing present the most penetrable geography, where NMPA joint venture requirements favor partnerships with established multinationals seeking local manufacturing footprint. Target cost-competitive digital imaging platforms for screening colonoscopy workflows in mid-tier facilities bypassing Olympus and Fujifilm service contract incumbency. Go-to-market through domestic CMOS packaging partnerships in Yangtze River Delta industrial corridors accelerates price point accessibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor crossover suppliers with consumer electronics scale economies and medical device regulatory affairs infrastructure. Long-term viability hinges on AI integration capabilities and disposable architecture transition timing. Acquisition targets showing ISO 13485 certification progress and FDA 510(k) predicate device strategies merit priority evaluation. Monitor MFDS and PMDA approval pathway harmonization as inflection signal for Korean and Japanese market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Semi-Disposable Architecture Development | Bypasses FDA reprocessing liability while capturing recurring consumable revenue from outpatient surgical centers. |
| AI Polyp Detection Algorithm Integration | Commands premium positioning in Japanese screening colonoscopy workflows with Ministry reimbursement alignment. |
| CMOS Sensor Packaging Partnership | Reduces unit costs through Yangtze River Delta manufacturing scale economies for mid-tier hospital access. |
| EU MDR Post-Market Surveillance Investment | Extends certification timelines that consolidate procurement toward established manufacturers with regulatory infrastructure. |
| Third-Party Service Organization Entry | Fragments manufacturer margin structures in Japanese university hospitals with unbundled maintenance pricing. |
Study Parameters
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists anchors the qualitative findings, while secondary validation draws from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up installed base modeling triangulates against top-down procedure volume estimates from gastroenterology and pulmonology screening program data.
Calibration against historical replacement cycle patterns and capital expenditure survey data from integrated delivery networks shapes the analytical framework across the analysis window. Segmentation dimensions include product architecture flexibility, sensor technology tier, end-user purchasing authority structure, and application-specific reimbursement pathway. CAGRs derive from procedure volume elasticity modeling and semiconductor cost curve projections, with forecast inputs incorporating outpatient surgical center expansion rates and EU MDR certification timeline extensions.
Practitioners should monitor FDA reprocessing guideline revisions, CMOS sensor supply concentration shifts, and value-based reimbursement framework adoption for early signals of forecast deviation. Cross-checking against hospital capital expenditure survey benchmarks and GPO contract renewal patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
China Arthroscopy Market
Endoscopy
Endotherapy Devices Market
Endoscopy
Global Veterinary Endoscopy Market
Endoscopy
Global Neuroendoscopy Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
India Endoscopy Devices Market
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
Nasopharyngoscope Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Japan Endoscopy Devices Market