
 Asia-Pacific Ultrasound Devices Market | 2026-2036
Asia-Pacific Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ultrasound Devices Market Outlook
Point-of-care diagnostics is pivoting toward portable and handheld platforms across Asia-Pacific emergency departments and rural clinics. GE Healthcare leverages its installed base in tertiary hospitals to extend service contracts into secondary facilities. Mindray Medical International Ltd anchors its competitive position through cost-engineered cart-based systems tailored for public hospital budgets in China and Southeast Asia. Samsung Healthcare differentiates via semiconductor-derived image-processing chipsets that reduce hardware footprint without sacrificing resolution.
Ultrasound devices generate acoustic images through piezoelectric crystal transducers operating at frequencies between 2 and 18 megahertz, with beamforming algorithms reconstructing real-time anatomical visualizations for non-invasive diagnostic and interventional guidance. Diagnostic ultrasound systems occupy the largest revenue pool due to obstetric and abdominal screening volumes, while portable ultrasound is expanding fastest as battery density and wireless probe miniaturization enable bedside and ambulance deployment. High-intensity focused ultrasound represents a concentrated margin segment where therapeutic ablation applications command premium pricing against traditional surgical modalities.
Japan's PMDA and Australia's TGA enforce stringent electromagnetic compatibility and biological safety standards that shape product development timelines for manufacturers seeking market access. China's NMPA accelerates review pathways for domestically manufactured Class II devices under its medical device innovation program, redirecting R&D investment toward local regulatory compliance. South Korea's MFDS adoption of harmonized IEC 60601-2-37 standards reduces testing duplication but raises baseline technical requirements for new entrants. Stakeholders must monitor how India's CDSCO alignment with International Medical Device Regulators Forum guidelines reshapes import certification burdens for multinational suppliers.
Market Dynamics
Hospital procurement departments across Asia-Pacific are consolidating vendor relationships under long-term managed service agreements rather than discrete equipment purchases. This structural shift compresses capital expenditure cycles while extending supplier lock-in through embedded software subscriptions and remote maintenance protocols.
Growth Catalysts
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import dependency for transducer assemblies and cart-based chassis. Local production certificates accelerate hospital procurement approvals in tier-two cities.
- Point-of-care emergency deployment:Ambulance services and rural clinics adopt battery-powered handheld units for trauma triage. Wireless probe miniaturization enables bedside imaging without dedicated radiology infrastructure.
- China's NMPA innovation pathway:Streamlined Class II device reviews compress regulatory timelines for domestically engineered systems. Manufacturers redirect R&D investment toward local compliance rather than dual-track certification.
Market Restraints
- Piezoelectric crystal supply concentration:Specialty ceramic substrate production clusters in Japan and South Korea expose manufacturers to single-source risk during geopolitical trade friction.
- Japan PMDA electromagnetic compatibility testing:Stringent shielding requirements for clinical environments extend product development timelines by 8-14 months for new market entrants.
- Computed tomography substitution in abdominal diagnostics:CT resolution advantages in oncology staging displace mid-range ultrasound systems in tertiary hospital radiology departments.
Strategic Opportunities
- Vietnam's underpenetrated provincial hospital network:Government health infrastructure spending targets 600 district-level facilities by 2030. Cart-based systems with simplified operator interfaces capture first-mover positioning.
- High-intensity focused ultrasound therapeutic ablation:Non-invasive tumor treatment applications command premium pricing against surgical resection. Urology and gynecology departments in South Korea and Australia pilot reimbursement pathways.
- AI-assisted image interpretation convergence:Deep learning algorithms embedded at the chipset level reduce operator training requirements. Semiconductor-software partnerships create differentiated positioning for equipment vendors.
Industry Challenges
- Sonographer training pipeline gaps:Specialized certification programs in Indonesia and Philippines produce insufficient qualified operators for expanded rural deployment targets.
- Legacy PACS integration complexity:Hospital information system heterogeneity across China's provincial networks demands customized middleware development for seamless image archiving.
- IP licensing for beamforming algorithms:Patent thickets held by US and European research institutions complicate independent software development for regional equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ultrasound Devices Market |
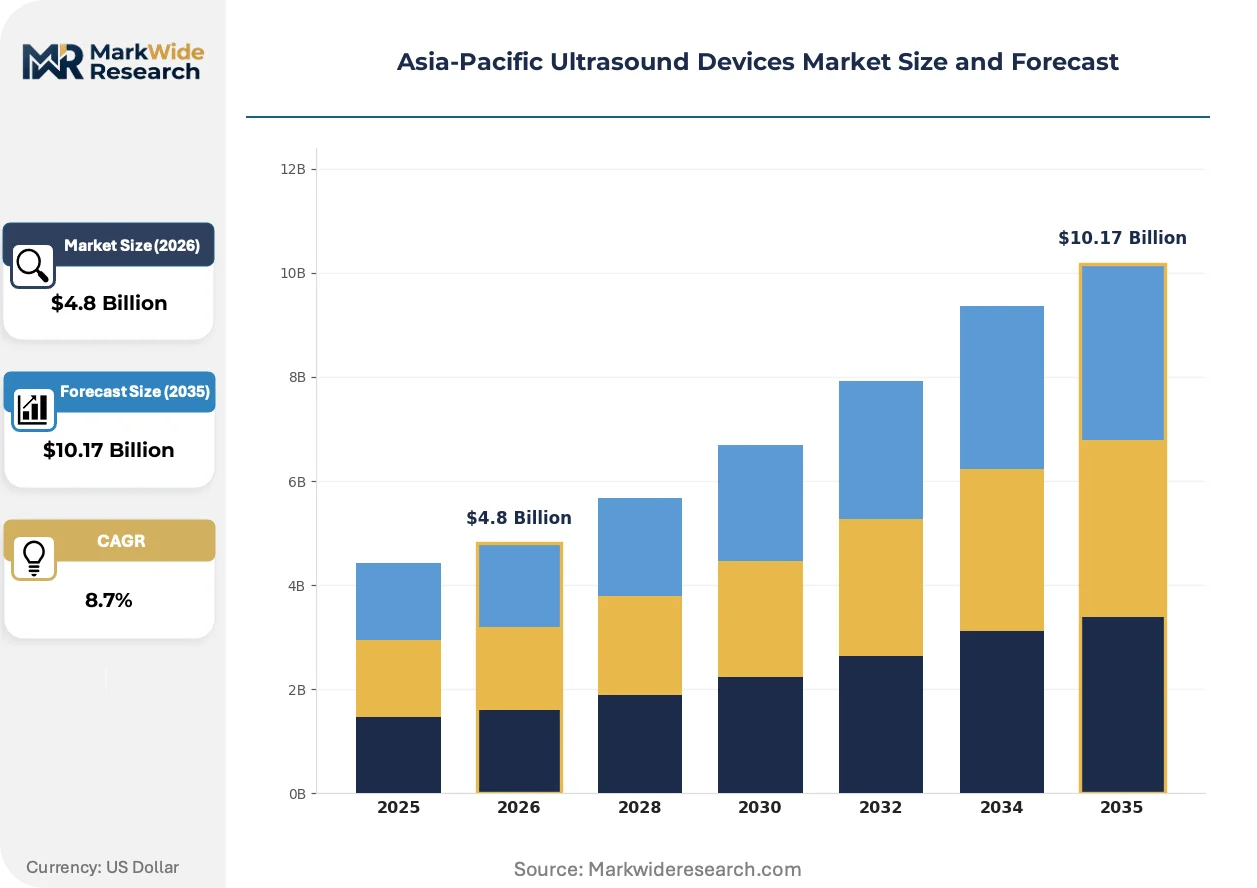
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound, Therapeutic Ultrasound, Portable Ultrasound, 3D/4D Ultrasound Technology: Piezoelectric, Ultrasound Contrast Agent, Doppler Ultrasound, High-Intensity Focused Ultrasound End User: Hospitals, Diagnostic Centers, Research Laboratories, Home Care Application: Obstetrics, Cardiology, Urology, Musculoskeletal |
| Companies Covered | GE Healthcare, Koninklijke Philips NV, Canon Medical Systems Corporation, Siemens Healthineers AG, Mindray Medical International Ltd, FUJIFILM Holdings Corp, Samsung Healthcare, Esaote SpA, Hitachi Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ultrasound Devices Market Strategic Shifts
Semiconductor miniaturization and edge-computing architectures are compressing hardware footprints while expanding diagnostic capability at the point of care. Three interconnected developments are restructuring competitive positioning across the Asia-Pacific equipment base.
Wireless probe technology is decentralizing ultrasound deployment from centralized radiology departments to bedside and ambulance environments. Emergency physicians in Australian and Japanese trauma centers adopt palm-sized transducers for rapid hemodynamic assessment. This hardware migration collapses the traditional distinction between diagnostic imaging and physical examination, enabling real-time clinical decision-making without patient transport.
China's NMPA medical device innovation program accelerates review pathways for domestically manufactured Class II systems. The policy redirects multinational R&D investment toward local regulatory compliance rather than dual-track certification strategies. Domestic manufacturers in Shenzhen and Suzhou leverage streamlined timelines to introduce cost-optimized cart-based platforms targeting public hospital procurement budgets.
Service unbundling separates hardware ownership from software-enabled diagnostic support. Public hospital consortia in India and Thailand negotiate subscription-based image analysis and remote quality assurance rather than bundled capital purchases. This financing rotation shifts vendor revenue toward recurring software fees while reducing upfront budget barriers for facility expansion.
Asia-Pacific Ultrasound Devices Market Segmentation
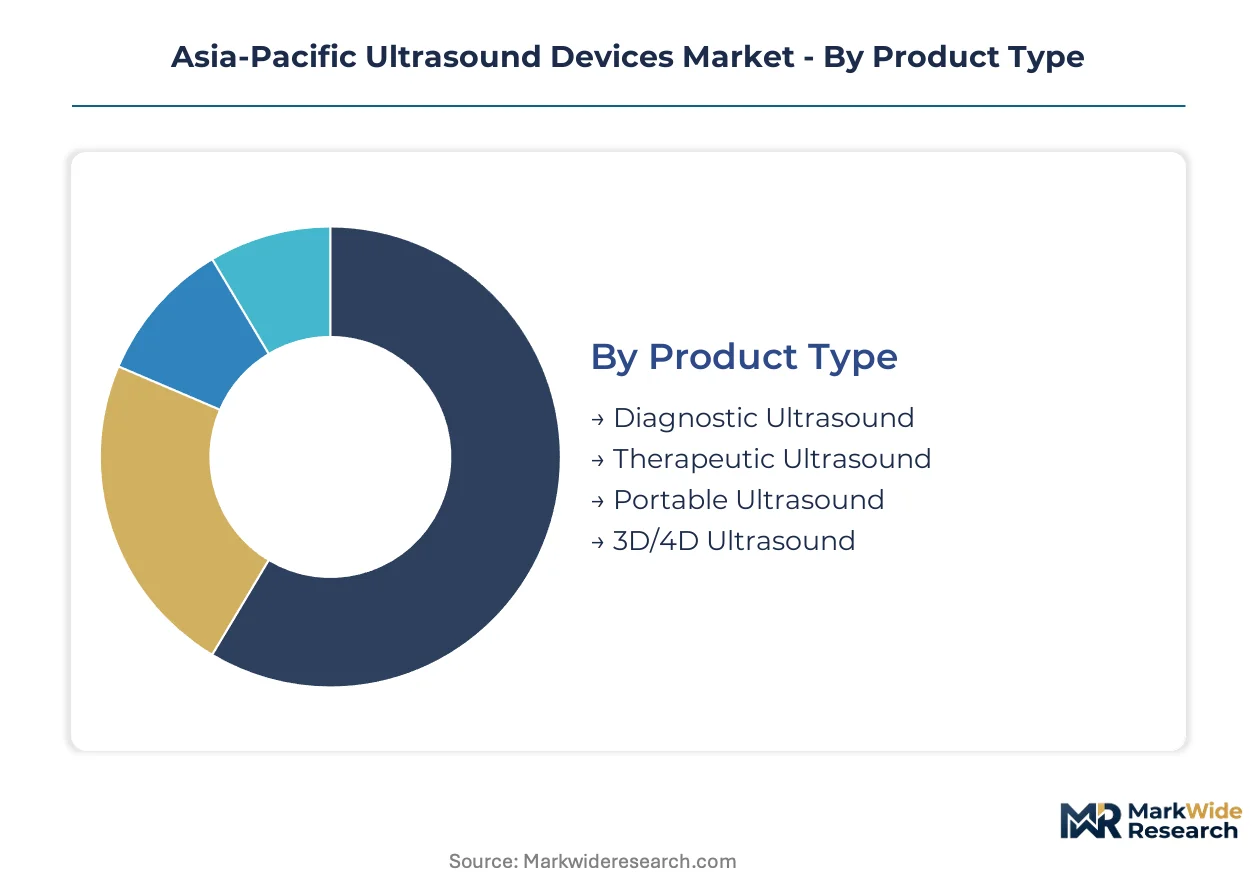
Ultrasound device manufacturers in Asia-Pacific configure product portfolios around distinct operational environments, from tertiary hospital radiology suites to ambulance-deployed emergency units. Each segment demands specialized transducer frequencies, software architectures, and regulatory compliance pathways that reshape vendor R&D allocation and pricing models.
Product Type:
Standardization dominates cart-based diagnostic platforms while customization concentrates in portable and therapeutic systems engineered for specific clinical workflows.
- Diagnostic Ultrasound:Cart-based systems integrate multi-frequency transducer arrays with beamforming processors for abdominal, cardiac, and obstetric imaging. Hospital procurement departments in China's tier-two cities prioritize these platforms as healthcare infrastructure decentralizes from urban centers.
- Portable Ultrasound:Battery-powered handheld units with wireless probe miniaturization enable bedside and ambulance deployment without dedicated radiology infrastructure. Emergency physicians in Australian trauma centers adopt palm-sized transducers for rapid hemodynamic assessment, collapsing the traditional distinction between diagnostic imaging and physical examination.
- Therapeutic Ultrasound:Focused acoustic energy delivery systems for tissue ablation and physiotherapy applications command specialized operator certification.
- 3D/4D Ultrasound:Real-time volumetric rendering systems with semiconductor-derived image-processing chipsets reduce hardware footprint for obstetric visualization.
Leading the category by volume: Diagnostic Ultrasound. Expanding most quickly: Portable Ultrasound.
Technology:
Cost tiers separate mature piezoelectric platforms from premium high-intensity focused systems and emerging contrast-enhanced modalities.
- High-Intensity Focused Ultrasound:Concentrated acoustic energy deposition enables non-invasive tumor ablation in urology and gynecology applications. South Korean and Australian departments pilot reimbursement pathways for this therapeutic alternative to surgical resection, commanding premium pricing against traditional modalities.
- Piezoelectric:Ceramic crystal transducers operating between 2 and 18 megahertz generate acoustic images through beamforming algorithms. Production concentration in Japan and South Korea exposes manufacturers to single-source supply risk during trade friction.
- Doppler Ultrasound:Frequency-shift detection systems for vascular flow assessment integrate into cardiology and emergency medicine workflows.
- Ultrasound Contrast Agent:Microbubble-enhanced imaging agents improve lesion characterization in liver and renal diagnostics.
Highest margin capture: High-Intensity Focused Ultrasound. Broadest installed base: Piezoelectric.
End User:
Customer type stratification reflects capital intensity gradients from institutional procurement to individual practitioner acquisition.
- Hospitals:Radiology departments and point-of-care units across Asia-Pacific consolidate vendor relationships under long-term managed service agreements rather than discrete equipment purchases. India's PLI scheme for medical devices accelerates domestic manufacturing capacity, reducing import dependency for transducer assemblies.
- Diagnostic Centers:Specialized imaging facilities concentrate high-throughput obstetric and abdominal screening volumes in urban corridors.
- Home Care:Simplified operator interfaces target monitoring applications for chronic condition management.
- Research Laboratories:Preclinical imaging systems with specialized transducer configurations support pharmaceutical development workflows.
Dominant procurement volume: Hospitals. Fastest customer segment expansion: Diagnostic Centers.
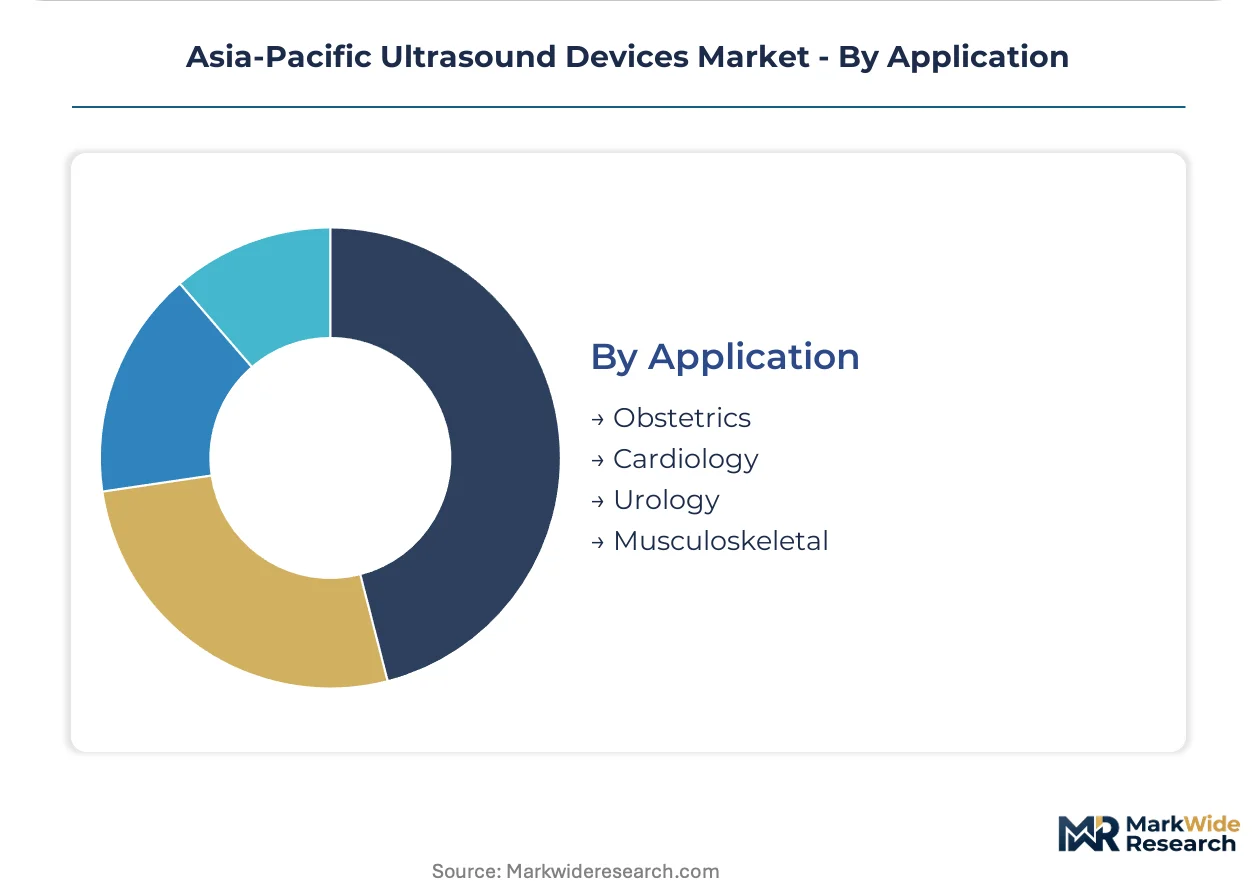
Application:
Volume concentration in obstetric screening contrasts with margin concentration in interventional cardiology and therapeutic urology.
- Obstetrics:Fetal biometry and anomaly screening generate the largest procedure volumes across Asia-Pacific healthcare systems. Public hospital budgets in China and Southeast Asia drive demand for cost-engineered cart-based systems from domestic manufacturers in Shenzhen and Suzhou.
- Cardiology:Echocardiography systems with specialized phased-array transducers command premium positioning for structural heart assessment.
- Urology:High-intensity focused ultrasound applications for prostate and renal tumor ablation pilot reimbursement pathways in South Korea and Australia.
- Musculoskeletal:Portable systems enable guided injection and tendon assessment in sports medicine and rheumatology practices.
Steepest procedure volume: Obstetrics. Premium pricing trajectory: Cardiology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan and South Korea concentrate piezoelectric crystal production, while China and India absorb the bulk of device consumption across decentralized hospital networks. This production-consumption divide shapes procurement patterns and regulatory compliance investments throughout the region.
China
Tier-two cities drive procurement volumes as healthcare infrastructure decentralizes from Beijing and Shanghai. NMPA accelerates Class II device reviews for domestically manufactured systems, compressing regulatory timelines. Shenzhen and Suzhou manufacturers introduce cost-optimized cart-based platforms targeting public hospital budgets.
Japan
Tertiary hospital radiology departments sustain demand for premium diagnostic systems with advanced beamforming capabilities. PMDA enforces stringent electromagnetic compatibility standards that extend product development timelines by 8-14 months for new entrants. Tokyo and Osaka medical device clusters concentrate specialty ceramic substrate production for transducer assemblies.
India
PLI scheme incentives reduce import dependency for transducer assemblies and cart-based chassis, accelerating domestic manufacturing capacity. CDSCO alignment with International Medical Device Regulators Forum guidelines reshapes import certification burdens for multinational suppliers. Tier-two city hospitals leverage local production certificates to expedite procurement approvals.
South Korea
Urology and gynecology departments pilot reimbursement pathways for high-intensity focused ultrasound therapeutic ablation applications. MFDS adoption of harmonized IEC 60601-2-37 standards reduces testing duplication while raising baseline technical requirements. Seoul-based medical technology clusters concentrate semiconductor-derived image-processing chipset development.
Australia
Emergency trauma centers adopt palm-sized wireless transducers for rapid hemodynamic assessment in ambulance and bedside environments. TGA biological safety standards shape product development timelines for manufacturers seeking market access. Sydney and Melbourne hospital networks consolidate vendor relationships under long-term managed service agreements.
Asia-Pacific Ultrasound Devices Market Competitive Environment
Top-tier vendors anchor premium diagnostic imaging, while mid-tier specialists compete on cost-engineered platforms for public hospital procurement. The vendor base stratifies across three archetypes: diversified conglomerates with semiconductor heritage, pure-play medical device manufacturers, and emerging domestic champions leveraging regulatory fast-tracks. Competitive moves concentrate on strategic partnerships for AI-assisted image interpretation and geographic expansion through managed service agreements.
Among diversified technology conglomerates, GE Healthcare and Samsung Healthcare exemplify archetypes leveraging installed base advantages and semiconductor-derived capabilities respectively. Mindray Medical International Ltd occupies a position representing cost-engineered specialists targeting public hospital budgets. These three anchors illustrate how competitive positioning diverges across premium-tier service contracts, mid-tier volume plays, and technology-differentiated hardware architectures.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Siemens Healthineers AG |
| Mindray Medical International Ltd |
| FUJIFILM Holdings Corp |
| Samsung Healthcare |
| Esaote SpA |
| Hitachi Ltd |
| Others |
Value Chain & Pricing Dynamics
Specialty ceramic substrate indices for piezoelectric crystals cascade through three pricing tiers across the Asia-Pacific ultrasound device market, with procurement officers in China's tier-two public hospitals capturing cost advantages from India's PLI-scheme production certificates while tertiary facilities in Japan absorb PMDA compliance premiums.
Pricing Analysis
Margin tightening in mid-range cart-based systems reflects China's NMPA innovation pathway compressing domestic manufacturer cost structures. A three-tier pricing structure across premium, standard, and economy levels separates GE Healthcare service-contract bundling from Mindray's public-hospital volume plays and Shenzhen manufacturers' bare-hardware positioning. Pricing pressure intensifies in portable segments as wireless probe miniaturization commoditizes hardware differentiation. Diagnostic centers in Southeast Asia exhibit highest price sensitivity; South Korean urology departments piloting HIFU reimbursement show lowest.
Supply Chain Analysis
India's PLI scheme domestic-content mandates reshape sourcing patterns for transducer assemblies and cart-based chassis, accelerating local production certificates. Piezoelectric crystal supply concentrates in Japan and South Korea, with semiconductor-derived image-processing chipsets anchoring in Seoul technology clusters. Specialty ceramic substrate production draws from Tokyo-Osaka medical device corridors. Single-source vulnerability persists in high-frequency transducer arrays. Distribution runs through hospital procurement consortia negotiating managed service agreements rather than discrete equipment purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
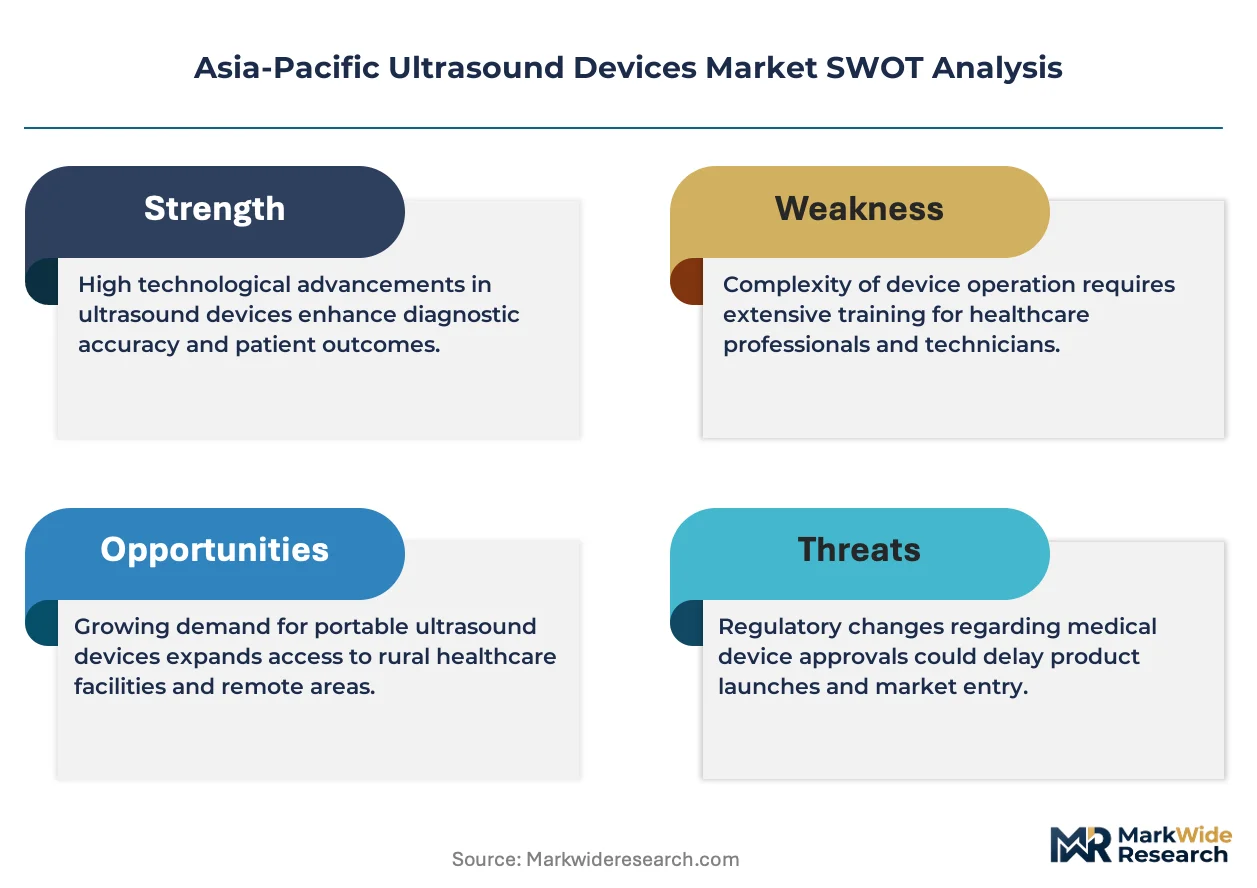
The Asia-Pacific ultrasound device market operates as a cost-of-compliance story where Japan's PMDA electromagnetic compatibility testing creates an 8-14 month barrier-to-entry moat for compliant incumbents against undercapitalized challengers.
For Market Incumbents: Acquire AI-assisted image interpretation capabilities through semiconductor-software partnerships to defend against CT substitution in abdominal diagnostics. Deepen backward integration into piezoelectric crystal supply through captive sourcing arrangements in South Korea. Lock in hospital procurement consortia via embedded remote maintenance protocols and subscription-based quality assurance. For New Entrants and Emerging Players: Enter via Vietnam's underpenetrated provincial hospital network where government infrastructure spending targets 600 district-level facilities. Target cart-based systems with simplified operator interfaces for first-mover positioning. Pursue software-unbundled financing models that reduce upfront capital barriers for public hospital expansion. For Investors and Strategic Acquirers: The window for entry favors domestic Chinese manufacturers with NMPA fast-track clearance and cost-engineered platforms for tier-two city procurement. Long-term viability hinges on regulatory compliance assets rather than hardware differentiation alone. Watch CDSCO alignment with IMDRF guidelines as the signal for India's import certification burden inflection.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class II Fast-Track Submission | Compresses regulatory timelines for Shenzhen and Suzhou manufacturers targeting public hospital budgets. |
| Semiconductor-Software Partnership | Samsung Healthcare leverages chipset-derived image processing to reduce hardware footprint without resolution sacrifice. |
| Hospital System Managed Service Agreement | GE Healthcare extends tertiary hospital service contracts into secondary facilities across Australian networks. |
| PLI Scheme Domestic Manufacturing Certificate | Mindray and multinational suppliers accelerate tier-two city procurement approvals through local production. |
| HIFU Reimbursement Pathway Development | South Korean urology departments pilot premium pricing for non-invasive tumor ablation against surgical resection. |
Study Parameters
Document review covered NMPA device registration filings, PMDA electromagnetic compatibility standards, and GPO procurement databases, complemented by interviews with hospital purchasing committee directors, biomedical engineers, and radiology department heads across China, Japan, India, and Australia. Secondary validation drew from MFDS harmonization guidelines, CDSCO import certification records, and Asia-Pacific medical device trade flow data. Bottom-up equipment shipment analysis triangulated against top-down healthcare infrastructure spending forecasts.
Market size and growth trajectory outputs reflect segment-level modeling across diagnostic, portable, therapeutic, and 3D/4D product categories, disaggregated by piezoelectric, HIFU, Doppler, and contrast-enhanced technology tiers. End-user segmentation captured hospital, diagnostic center, home care, and research laboratory procurement patterns. Application-level splits across obstetrics, cardiology, urology, and musculoskeletal imaging informed volume assumptions. CAGRs derived from regression analysis against healthcare infrastructure investment, regulatory pathway velocity, and substitution elasticity parameters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical trade friction affecting Japan-South Korea ceramic substrate flows and NMPA policy shifts redirecting domestic manufacturer R&D investment. Reimbursement pathway adoption for HIFU therapeutic applications in South Korea and Australia introduces additional scenario dispersion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Active Implantable Devices Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Medical Machine Battery Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Bariatric Beds Market
Medical Devices
Global Foley Catheters Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Intubation Accessories Market
Medical Devices
Breast Pump Flange Market
Medical Devices
South Africa Aesthetic Devices Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
Middle East and Africa Biomedical Sensors Market