
 Mobile Accelerator Market | 2026-2036
Mobile Accelerator Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Accelerator Market Intelligence
Platform licensing revenue from integrated hardware and software solutions is reshaping the market's value chain, shifting focus from pure component sales. Qualcomm Technologies leverages its extensive patent portfolio in mobile processing and connectivity for consumer electronics brands. Telefonaktiebolaget LM Ericsson specializes in network-side acceleration to support telecommunications providers. Akamai Technologies differentiates by focusing on content delivery network (CDN) based acceleration for mobile applications.
A mobile accelerator is a specialized hardware component or software function designed to offload intensive computational tasks from a device's central processing unit. These accelerators, often measured in Trillions of Operations Per Second (TOPS), handle specific workloads to improve performance and power efficiency. Application-Specific Integrated Circuits (ASICs) offer high efficiency for dedicated tasks like image processing. Machine learning applications are driving significant investment in specialized Neural Processing Units, a fast-growing technology segment.
Regulations from bodies like the US Federal Communications Commission (FCC) govern radio frequency emissions for integrated mobile devices. The EU's General Data Protection Regulation (GDPR) influences how on-device AI accelerators process personal data. In China, Ministry of Industry and Information Technology (MIIT) standards dictate network compatibility and performance requirements. Stakeholder success will depend on navigating the strategic choice between deploying acceleration capabilities on-device versus at the network edge.
Market Dynamics
The strategic decision between deploying acceleration on-device versus at the network edge defines the market's competitive structure. The global rollout of 5G infrastructure provides the low-latency connectivity that makes network-side acceleration a viable alternative to powerful on-device Neural Processing Units.
Growth Catalysts
- Machine Learning on Mobile:The expansion of AI-powered features in smartphones, from computational photography to real-time translation, requires dedicated hardware like NPUs to ensure performance without draining battery life.
- 5G Network Deployment:Widespread 5G availability reduces latency, enabling cloud-based and network-edge acceleration models that complement on-device hardware for applications like augmented reality and cloud gaming.
- China's Semiconductor Policy:Government support for the domestic semiconductor industry in China, including subsidies and favorable policies, stimulates local design and manufacturing of mobile accelerator ASICs for its vast electronics sector.
Market Restraints
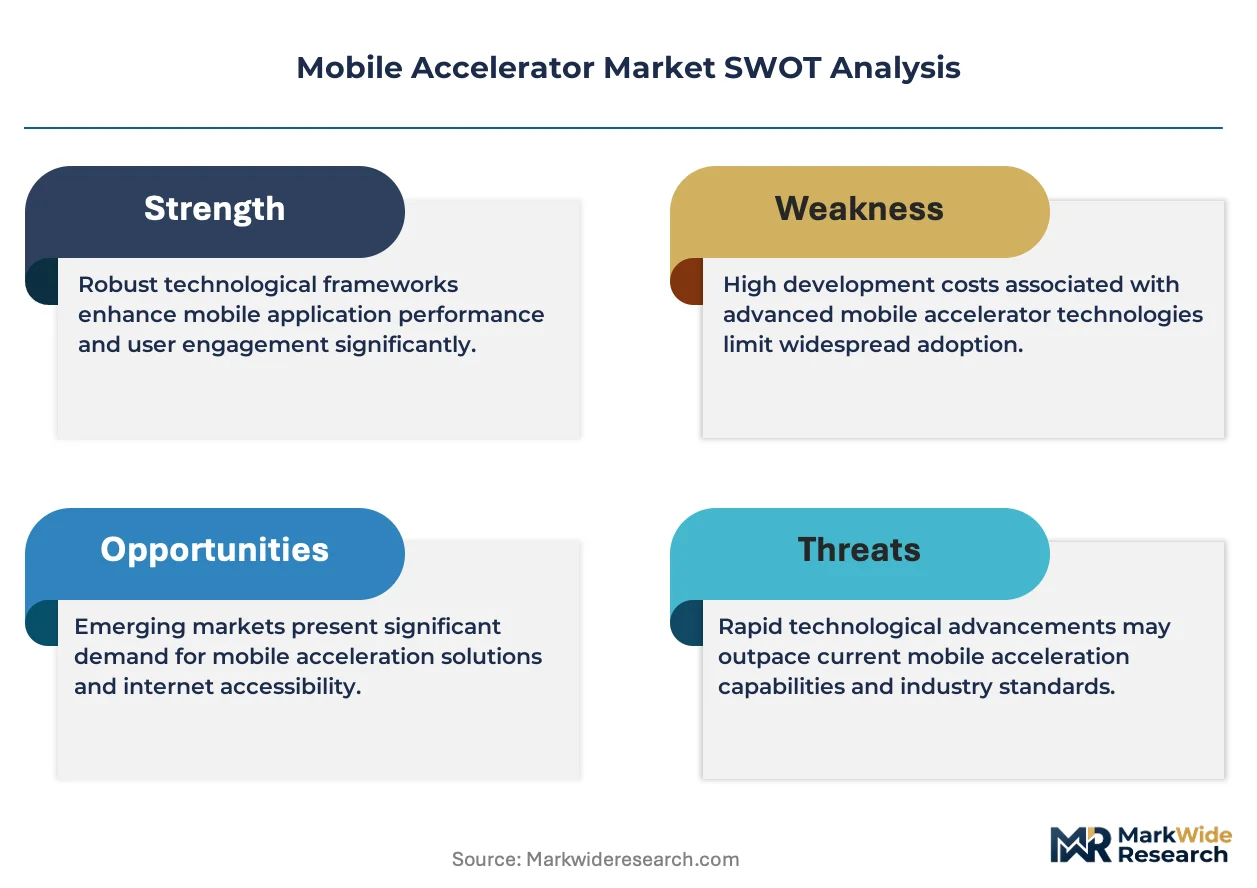
- High ASIC Development Costs:The non-recurring engineering costs and long design cycles for custom Application-Specific Integrated Circuits present a significant financial barrier for smaller device manufacturers and startups.
- Thermal and Power Constraints:Increasing the computational power of on-device accelerators generates substantial heat, creating thermal management challenges that can throttle performance in compact mobile form factors.
- CPU/GPU Generalization:Advances in general-purpose CPU and GPU architectures allow them to handle a wider range of moderately intensive tasks, reducing the need for specialized accelerators in mid-range devices.
Strategic Opportunities
- Automotive Infotainment Systems:Integrating mobile accelerators into in-vehicle infotainment and telematics systems offers a new high-volume market beyond consumer smartphones, driven by demand for responsive user interfaces and connected services.
- On-Device Security Processing:The convergence of AI and cybersecurity creates an opportunity for accelerators dedicated to real-time threat detection and biometric authentication, addressing privacy concerns governed by regulations like GDPR.
- Cost-Optimized Solutions for India:Developing power-efficient and cost-optimized accelerator IP for the high-volume, mid-range smartphone segment in India presents a significant opportunity for component and licensing vendors.
Industry Challenges
- Hardware-Software Co-Design Talent:A scarcity of engineers skilled in both hardware accelerator architecture and the software development kits needed to utilize them creates a bottleneck in product development and ecosystem support.
- API and Software Fragmentation:The lack of a universal software abstraction layer across different accelerator hardware complicates application development, limiting the portability of accelerated apps and increasing developer workload.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Accelerator Market |
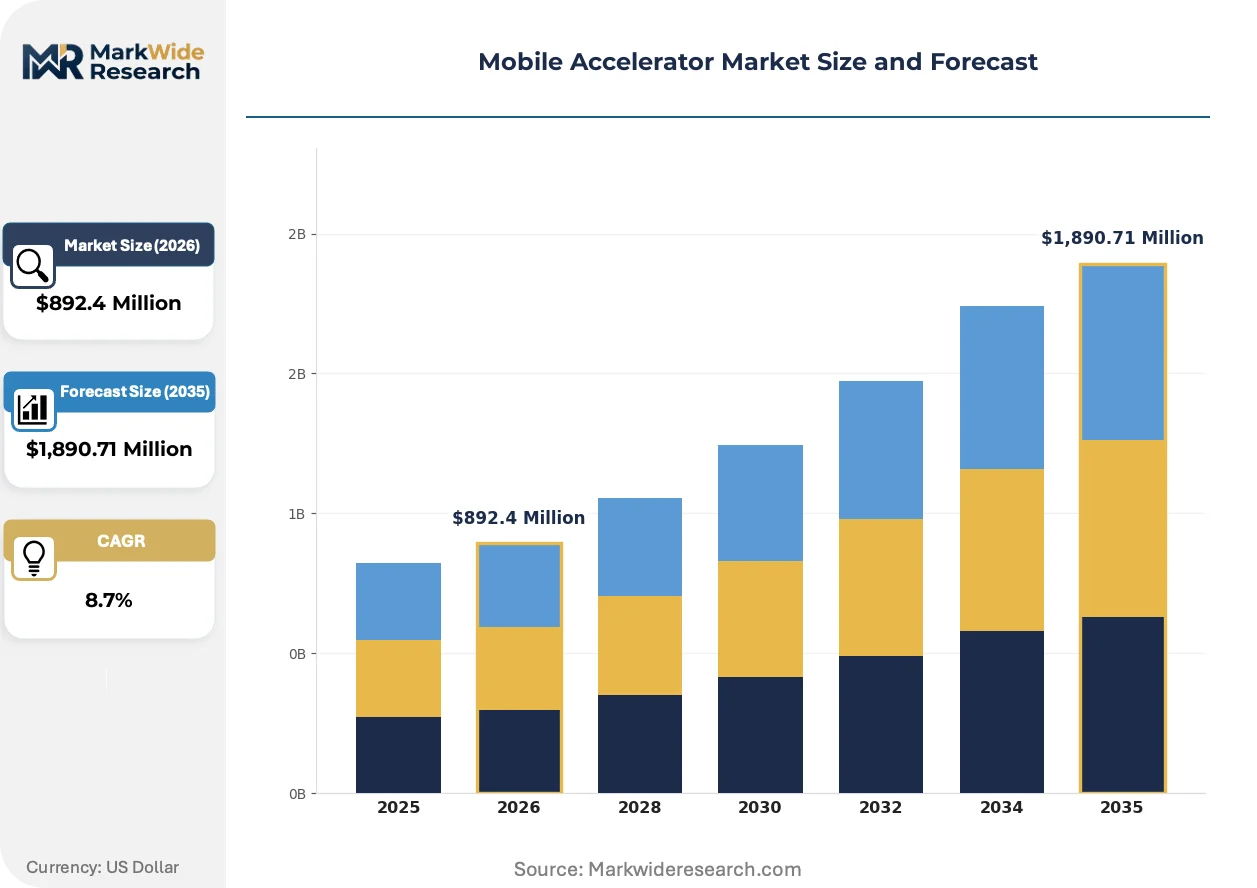
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,890.71 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphics Accelerators, Network Accelerators, Storage Accelerators, DSP Accelerators, ASIC Accelerators Technology: FPGA, GPU, ASIC, DSP, Neural Processing Units Application: Augmented Reality, Edge Computing, Image Processing, Machine Learning, Virtual Reality End User Industry: Telecommunications Providers, Consumer Electronics Brands, Semiconductor Manufacturers, Software Developers, Automotive Tier-1 Suppliers |
| Companies Covered | Akamai Technologies, Qualcomm Technologies, Telefonaktiebolaget LM Ericsson, Huawei Technologies, F5 Networks, Flash Networks, Equinix, Cloudflare, Juniper Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Accelerator Market Strategic Shifts & Innovations
A fundamental shift from prioritizing raw computational throughput toward optimizing performance-per-watt is underway. This focus on power efficiency and specialized function is driving innovation in both hardware architecture and software deployment models for mobile devices.
Heterogeneous computing integrates multiple specialized processing units, like NPUs and DSPs, onto a single System-on-Chip to handle diverse tasks efficiently. Smartphone manufacturers are rapidly adopting this approach across premium and mid-tier devices to support complex AI and imaging workloads. This integration is collapsing the distinction between the CPU and dedicated accelerators, creating a unified, power-efficient processing fabric.
The forthcoming EU AI Act proposes risk-based classifications for artificial intelligence systems, including those embedded in consumer devices. This regulation incentivizes on-device processing for personal data to align with privacy-by-design principles and reduce compliance burdens. Mobile accelerator designs are consequently prioritizing features that support auditable, secure, and private AI computations directly on the handset.
Value capture is shifting from the sale of discrete accelerator components to the licensing of integrated hardware and software platforms. This model provides device OEMs with a complete solution stack including drivers, libraries, and development tools, displacing traditional component-level procurement. The trend is most prominent in the competitive smartphone market where software optimization is critical for differentiation.
Mobile Accelerator Market Segmentation
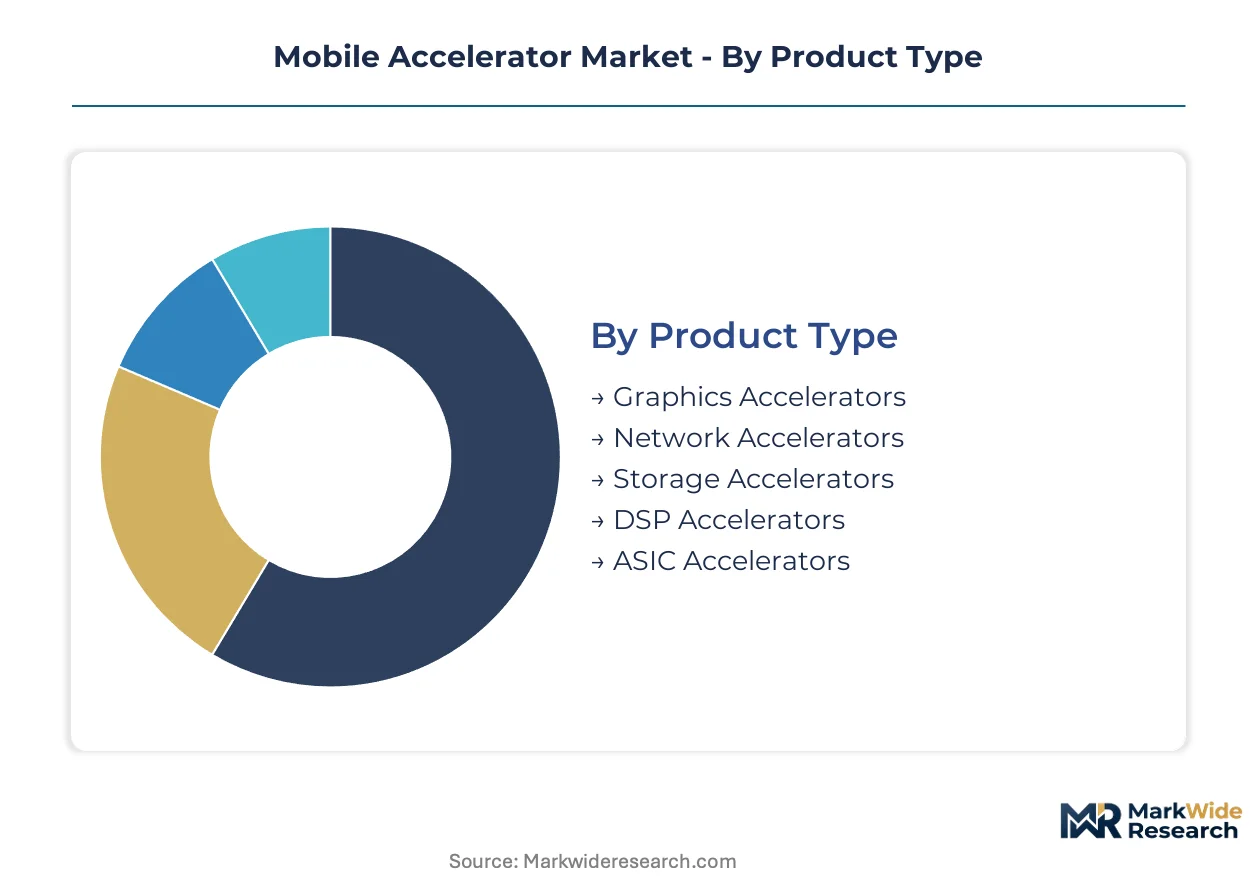
The mobile accelerator market is segmented by various dimensions, revealing the evolving technological landscape and diverse application requirements. This structural breakdown clarifies where innovation is occurring and how value is being created across the industry. Understanding these segments highlights the varied demands from different end-user sectors and technological preferences.
Product Type:
Product types exhibit varying development cycles, with some requiring extensive design phases while others offer quicker deployment.
- ASIC Accelerators:Application-Specific Integrated Circuits offer maximum efficiency for dedicated tasks, often requiring long design cycles and high non-recurring engineering costs. Demand concentrates in China's consumer electronics sector, driven by government support for domestic semiconductor manufacturing.
- Network Accelerators:These components improve data throughput and reduce latency in communication infrastructure, crucial for advanced connectivity. Telecommunications providers heavily invest in network accelerators to support 5G deployment, enabling low-latency applications at the network edge.
- Graphics Accelerators:Specialized hardware enhances visual rendering and display capabilities for mobile devices.
- DSP Accelerators:Digital Signal Processors efficiently handle audio and video processing tasks.
- Storage Accelerators:These improve data access speeds and efficiency for on-device storage systems.
ASIC Accelerators anchor the volume base while Network Accelerators gain share at the steepest rate.
Technology:
Technology segments span a wide range of development costs, influencing their adoption rates across different device tiers.
- Neural Processing Units:Specialized processors optimized for machine learning workloads deliver high performance-per-watt for AI-powered features. Demand concentrates across premium and mid-tier smartphones, driven by the expansion of AI applications like computational photography.
- ASIC:Custom-designed integrated circuits provide the highest performance and energy efficiency for specific, high-volume tasks. Consumer electronics brands integrate ASICs to differentiate their flagship devices, particularly for image processing and security features.
- FPGA:Field-Programmable Gate Arrays offer flexibility for prototyping and specialized, lower-volume applications.
- GPU:Graphics Processing Units offer parallel processing capabilities for a wide range of computational tasks.
- DSP:Digital Signal Processors efficiently manage audio and video processing in mobile devices.
Neural Processing Units are expanding most quickly, reflecting widespread investment in on-device AI capabilities.
Application:
Application segments represent varying volume demands, from niche specialized uses to widespread consumer functionalities.
- Machine Learning:This segment leverages mobile accelerators for real-time AI inference, enabling features like voice assistants and predictive text. Demand concentrates across all smartphone tiers, driven by the push for more intelligent and personalized user experiences.
- Image Processing:Accelerators enhance computational photography, enabling advanced features such as portrait mode and low-light optimization directly on mobile devices. Consumer electronics brands prioritize image processing capabilities for camera differentiation.
- Augmented Reality:This application uses accelerators for real-time overlay of digital information onto the physical world.
- Edge Computing:Accelerators deployed at the network edge reduce latency for data processing closer to the user.
- Virtual Reality:This segment utilizes mobile accelerators to render immersive digital environments with low latency.
Machine Learning and Image Processing applications are leading the adoption wave for mobile accelerator technologies.
End User Industry:
End user industries exhibit distinct procurement patterns and technology requirements based on their customer bases.
- Consumer Electronics Brands:These companies integrate mobile accelerators into smartphones, tablets, and wearables to enhance performance and differentiate products. Demand for accelerators is intense in markets like China, where large manufacturers compete on AI features.
- Automotive Tier-1 Suppliers:This segment integrates mobile accelerators into infotainment and telematics systems for advanced in-vehicle experiences. The opportunity for these suppliers is significant as demand for responsive user interfaces and connected services grows.
- Telecommunications Providers:These entities deploy network-side accelerators to support 5G infrastructure and edge computing services.
- Semiconductor Manufacturers:These companies design and produce the specialized hardware components for mobile acceleration.
- Software Developers:This group creates the applications and frameworks that leverage mobile accelerator capabilities.
Consumer Electronics Brands and Automotive Tier-1 Suppliers are driving innovation in mobile accelerator integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The mobile accelerator market exhibits varying demand elasticity across regions, with premium device segments in developed economies prioritizing performance. Conversely, emerging markets often seek cost-optimized solutions for high-volume mid-range devices. This regional differentiation influences product development and market entry strategies.
China
Demand for mobile accelerators in China stems from its extensive consumer electronics manufacturing base. The Ministry of Industry and Information Technology (MIIT) standards dictate network compatibility. Shenzhen's electronics manufacturing hub drives local design and production of ASICs. Government support for the semiconductor industry stimulates domestic innovation.
United States
United States demand for mobile accelerators centers on advanced machine learning applications and high-performance computing. Regulations from the US Federal Communications Commission (FCC) govern radio frequency emissions. Silicon Valley remains a key hub for NPU development and software ecosystem innovation. Tech giants drive significant investment in AI acceleration.
India
India represents a significant opportunity for cost-optimized and power-efficient mobile accelerator solutions in the mid-range smartphone segment. The government's Production Linked Incentive (PLI) scheme encourages domestic electronics manufacturing. Bengaluru's tech ecosystem fosters local development of AI software. High volume demand for affordable devices shapes accelerator IP requirements.
Germany
Germany's market for mobile accelerators benefits from strong automotive industry integration and advanced industrial applications. The EU AI Act proposes risk-based classifications for AI systems, influencing on-device processing. Munich's automotive and electronics clusters focus on integrating accelerators into infotainment systems. Research in edge computing further drives specialized hardware demand.
South Korea
South Korea exhibits strong demand for mobile accelerators driven by its leading smartphone manufacturers and 5G infrastructure. Regulatory bodies ensure high standards for mobile device performance and network integration. Seoul's technology firms actively develop advanced NPUs and image processing ASICs. Innovation in display technology and AI features fuels accelerator adoption.
Mobile Accelerator Market Key Industry Players
Capability concentration sits with specialized hardware and software developers; scale advantage sits with integrated device manufacturers and network operators. The market exhibits a tiered structure, from pure component providers to comprehensive platform licensors offering full solution stacks. Strategic archetypes include intellectual property powerhouses, network infrastructure specialists, and content delivery innovators. Companies engage in technology licensing, strategic partnerships, and targeted M&A to expand their ecosystem influence and secure market share.
Within the intellectual property powerhouse archetype, Qualcomm Technologies anchors the mobile processing and connectivity segment for consumer electronics brands, leveraging its extensive patent portfolio. Telefonaktiebolaget LM Ericsson represents the network-side acceleration specialists, supporting telecommunications providers with robust infrastructure solutions for 5G deployment. Akamai Technologies occupies a unique position as a content delivery network-based accelerator provider, optimizing mobile application performance and user experience for global users. These entities exemplify the diverse approaches to value creation in the mobile accelerator market.
| Leading Market Players |
|---|
| Akamai Technologies |
| Qualcomm Technologies |
| Telefonaktiebolaget LM Ericsson |
| Huawei Technologies |
| F5 Networks |
| Flash Networks |
| Equinix |
| Cloudflare |
| Juniper Networks |
| Others |
Cost & Logistics Intelligence
Asian semiconductor logistics routes face cost dynamics directly influencing both supply concentration and downstream price differentiation for mobile accelerators. Demand for advanced packaging and high-performance components drives specific pricing tiers across the market.
Pricing Analysis
Platform licensing revenue from integrated hardware and software solutions drives lifetime value for mobile accelerator providers. Pricing models increasingly adopt a hybrid approach, combining upfront licensing fees with recurring royalties based on device volume or feature activation. Price differentiation stems from performance-per-watt metrics and the depth of software ecosystem support offered to OEMs. Pricing pressure stems from the rapid commoditization of mid-range components, particularly in high-volume markets. Consumer electronics brands in emerging markets exhibit the highest price sensitivity for accelerator IP.
Supply Chain Analysis
High-purity silicon wafers and specialized chemicals form the foundational upstream feedstock for mobile accelerator production. Geographic supply concentration centers on Taiwan, South Korea, and China, which host the majority of advanced semiconductor fabrication facilities. Geopolitical trade restrictions present a structural supply chain risk, impacting the availability and cost of critical components. The distribution model primarily runs through direct sales channels to large consumer electronics brands and telecommunications equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile accelerator market presents a service-attach opportunity, with platform licensing revenue expanding faster than discrete hardware component sales.
For Market Incumbents: Insulate core IP through continuous investment in advanced process technology and hardware-software co-design talent. Develop comprehensive solution stacks that integrate seamlessly with OEM platforms to counter competitive threats from generalized CPU/GPU advancements. Reinforce existing patent portfolios in key areas like Neural Processing Units and 5G connectivity to maintain a defensive moat against emerging entrants. Leverage established relationships with consumer electronics brands to offer bundled IP and support services.
For New Entrants and Emerging Players: Pursue niche application segments with high growth potential and lower incumbent saturation. Automotive infotainment systems and on-device security processing represent penetrable white-space targets. Develop cost-optimized accelerator IP specifically for the high-volume, mid-range smartphone segment in India. A go-to-market angle focused on flexible licensing models and rapid integration support for smaller OEMs can secure initial market share.
For Investors and Strategic Acquirers: The EU AI Act proposes risk-based classifications, reshaping the acquisition landscape for AI-enabled hardware. Long-term viability extends over a 5-10 year window, favoring companies with robust IP in power-efficient AI processing and secure on-device computation. Acquisition targets should prioritize firms specializing in Neural Processing Unit architectures or hardware-software co-design for specific vertical applications. The signal to watch is the adoption rate of privacy-by-design features in new mobile devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop specialized NPU architectures | Enhances on-device AI performance for advanced mobile applications. |
| Form strategic partnerships with telecom providers | Accelerates 5G edge computing deployments and network-side acceleration. |
| Invest in hardware-software co-design talent | Addresses the scarcity of engineers capable of optimizing accelerator utilization. |
| Expand into automotive infotainment systems | Captures a new high-volume market beyond traditional consumer electronics. |
| Offer flexible IP licensing models | Attracts mid-tier device manufacturers seeking cost-effective acceleration solutions. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, technology patents, and industry whitepapers. Primary interviews engaged CTOs, hardware architects, product managers from consumer electronics brands, and telecom network planners. This approach ensured a balanced perspective across the value chain, triangulating insights from both bottom-up market observations and top-down strategic analyses.
Forecast inputs considered include technology adoption curves, 5G deployment rates, and regional economic development across the analysis window. The quantitative model segmented the market by product type, technology, application, end-user industry, and geographic market maturity. Compound annual growth rates were derived by projecting demand drivers such as smartphone unit shipments and AI model complexity growth.
Macroeconomic conditions sit as an overlay; deviation in global semiconductor supply or consumer spending would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological progression. Cross-checking against national statistical reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Industrial Ethernet Market
Network Technology
GCC Set-Top Box Market
Network Technology
Global Network Probe Market
Network Technology
Intelligent Network Management Market
Network Technology
Europe SD-WAN Market
Network Technology
ISP Management Systems Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
5G CPE Device Market
Network Technology
Global Wireless Router Market
Network Technology
WAN Optimization Controllers Market
Network Technology
Dark Fiber Market
Network Technology
Mobile Hotspot Router Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
Network Devices Market
Network Technology
Digital Repeater Market