
 Digital Repeater Market | 2026-2036
Digital Repeater Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Repeater Market Outlook
Multi-source component procurement is repositioning supply chain economics for digital repeater manufacturers. Motorola Solutions, Inc. leverages its public safety specialization to anchor government contracts across North America. Texas Instruments Incorporated sustains semiconductor supply advantages through in-house fabrication of RF signal processing chips. Remotek Corporation competes on compact form-factor designs for distributed antenna systems.
A digital repeater is an electronic device that receives, amplifies, and retransmits radio frequency signals within specific frequency bands, typically operating at power levels between 20 milliwatts and 20 watts depending on application requirements. It extends coverage of wireless networks in environments where direct base station signals prove insufficient, such as underground transit systems, large commercial buildings, and remote industrial sites. Wireless technology variants command structural priority due to 5G network densification requirements, while optical repeaters occupy premium margin tiers for fiber-backhaul integration. Public safety applications represent the fastest-expanding segment as first-responder agencies mandate interoperable communications across jurisdictions.
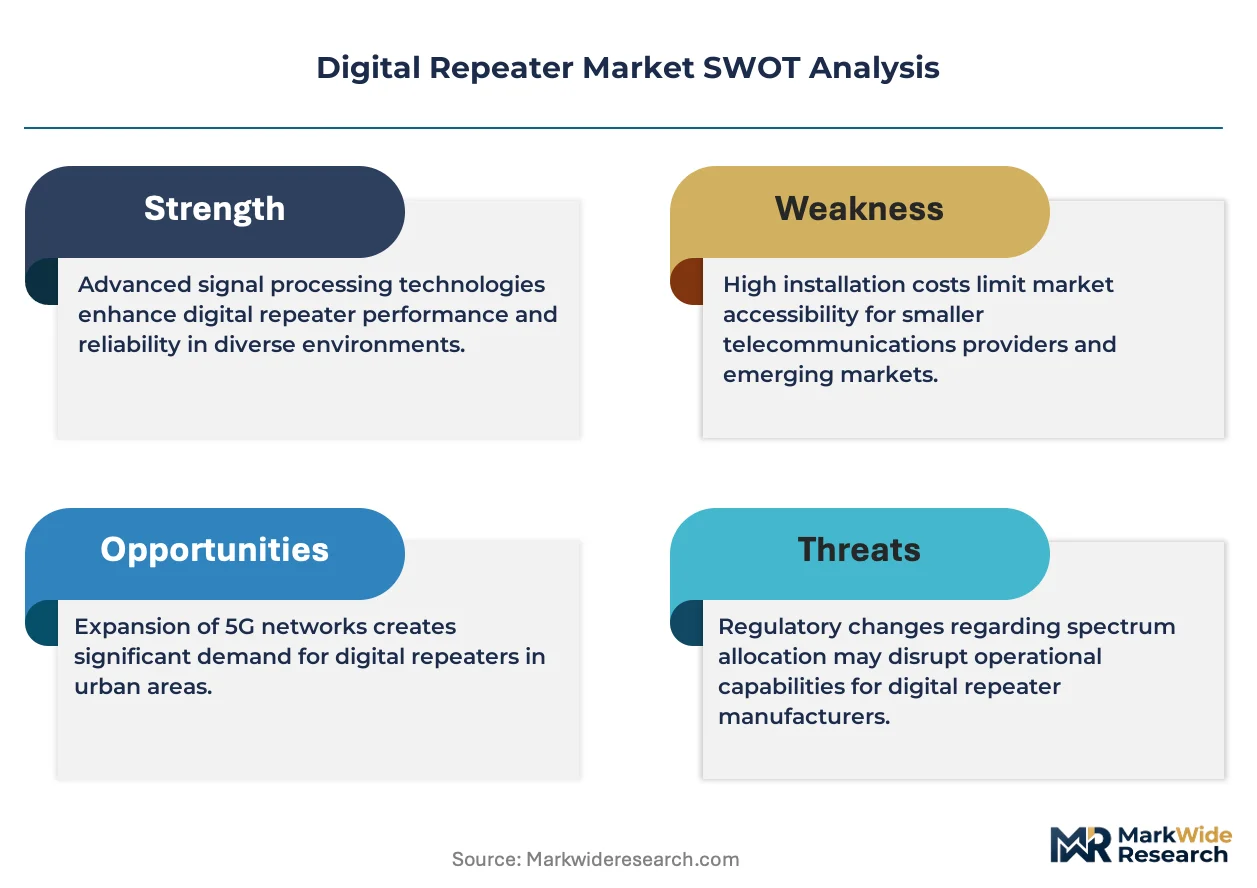
The Federal Communications Commission enforces Part 90 and Part 27 rules governing signal boosters and repeater emissions in the United States, directly shaping product certification timelines and market access conditions. European manufacturers must satisfy CE marking under the Radio Equipment Directive alongside ETSI harmonized standards for electromagnetic compatibility. India's Wireless Planning and Coordination Wing imposes type-approval requirements that delay entry for unlicensed spectrum devices. Stakeholders must monitor evolving spectrum reallocation decisions and prioritize modular hardware architectures that adapt to shifting regulatory band plans.
Market Dynamics
5G network densification is compressing deployment timelines for digital repeater infrastructure, forcing manufacturers to accelerate modular hardware development while navigating fragmented spectrum allocation regimes across multiple jurisdictions.
Growth Catalysts
- India's Smart City Mission:Municipal infrastructure projects mandate ubiquitous indoor coverage for IoT sensors and emergency services, creating sustained procurement pipelines for distributed antenna systems.
- CE marking under RED:Harmonized electromagnetic compatibility standards streamline cross-border equipment certification, reducing time-to-market for European manufacturers.
- Public safety interoperability mandates:First-responder agencies require cross-jurisdictional radio coverage, driving replacement cycles for legacy analog repeater networks.
Market Restraints
- GaN and GaAs substrate costs:Power amplifier semiconductors face price volatility due to concentrated mining and refining operations in specific extraction geographies.
- FCC Part 90 certification timelines:Signal booster approval processes extend 12-18 months, freezing product launches for unlicensed spectrum variants.
- Small cell substitution:Carrier-grade femtocell and picocell deployments cannibalize low-power repeater demand in enterprise environments.
Strategic Opportunities
- Sub-6 GHz 5G mid-band expansion:C-band and 3.5 GHz allocations create white space for software-defined repeaters with field-programmable frequency agility.
- Railway tunnel coverage gaps:Underground transit authorities in Germany and Japan issue dedicated tenders for ruggedized optical-fiber backhaul repeaters.
- India's PLI scheme for telecom equipment:Production-linked incentives reduce landed cost disadvantages for domestic manufacturing of RF components.
Industry Challenges
- RF engineering talent scarcity:Specialized microwave design expertise concentrates in defense-aerospace clusters, limiting hiring pipelines for commercial repeater developers.
- Legacy analog integration:Hybrid network architectures require backward-compatible signaling protocols, complicating firmware architecture and testing matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Repeater Market |
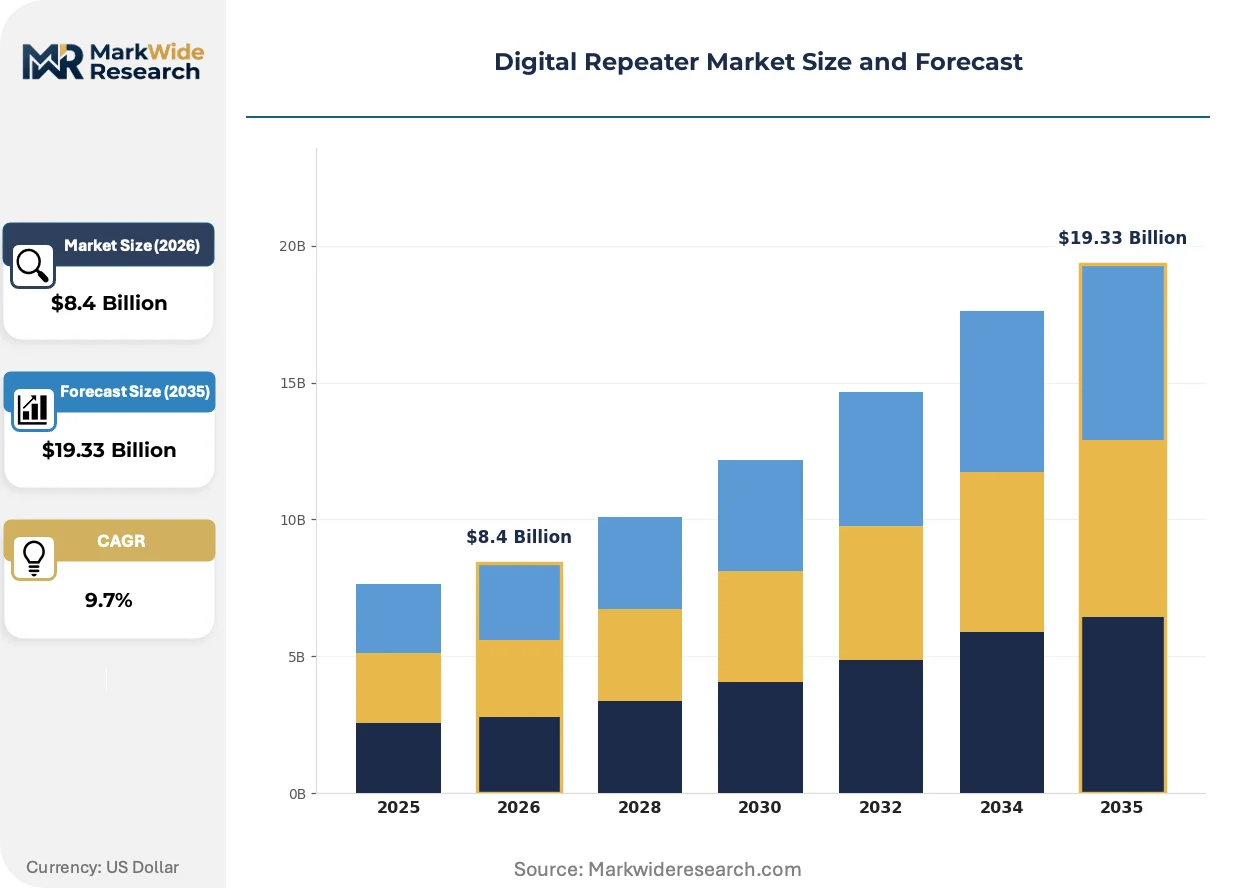
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Analog, Digital, Optical, Wireless Application: Telecommunications, Broadcasting, Public Safety, Industrial Automation End User: Telecom Operators, Government Agencies, Enterprises, Utilities Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Remotek Corporation, Cellcom Telecommunications, Inc., Motorola Solutions, Inc., Cellular Specialties, Inc., Puget Sound Instrument Company, Inc., Texas Instruments Incorporated, Westell, Inc., BearCom Group, Inc., Coiler Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Repeater Market Strategic Shifts
Software-defined radio architectures are displacing fixed-frequency hardware, enabling field-reconfigurable repeaters that adapt to spectrum reallocation without hardware swaps. This shift compresses product lifecycles while expanding addressable deployment scenarios.
Open RAN interface standards are expanding into digital repeater design, allowing multi-vendor interoperability between baseband units and remote radio heads. Telecom operators in South Korea and Finland mandate O-RAN compliance in 5G infrastructure tenders, pressuring proprietary hardware vendors to publish interface specifications or cede procurement decisions.
The FCC's revised Part 27 rules governing signal boosters now mandate automatic gain control and network protection features, elevating compliance costs for entry-level equipment. Manufacturers serving the United States must redesign RF front-ends to incorporate real-time interference detection, shifting competitive advantage toward firms with integrated semiconductor capabilities.
Enterprise buyers now specify outcome-based coverage guarantees rather than equipment-centric procurement, transferring performance risk to system integrators. Mining and oil-gas operators in Australia and Canada contract for "dead-zone elimination" service levels, compelling repeater vendors to bundle installation, optimization, and maintenance into multi-year agreements.
Digital Repeater Market Segmentation
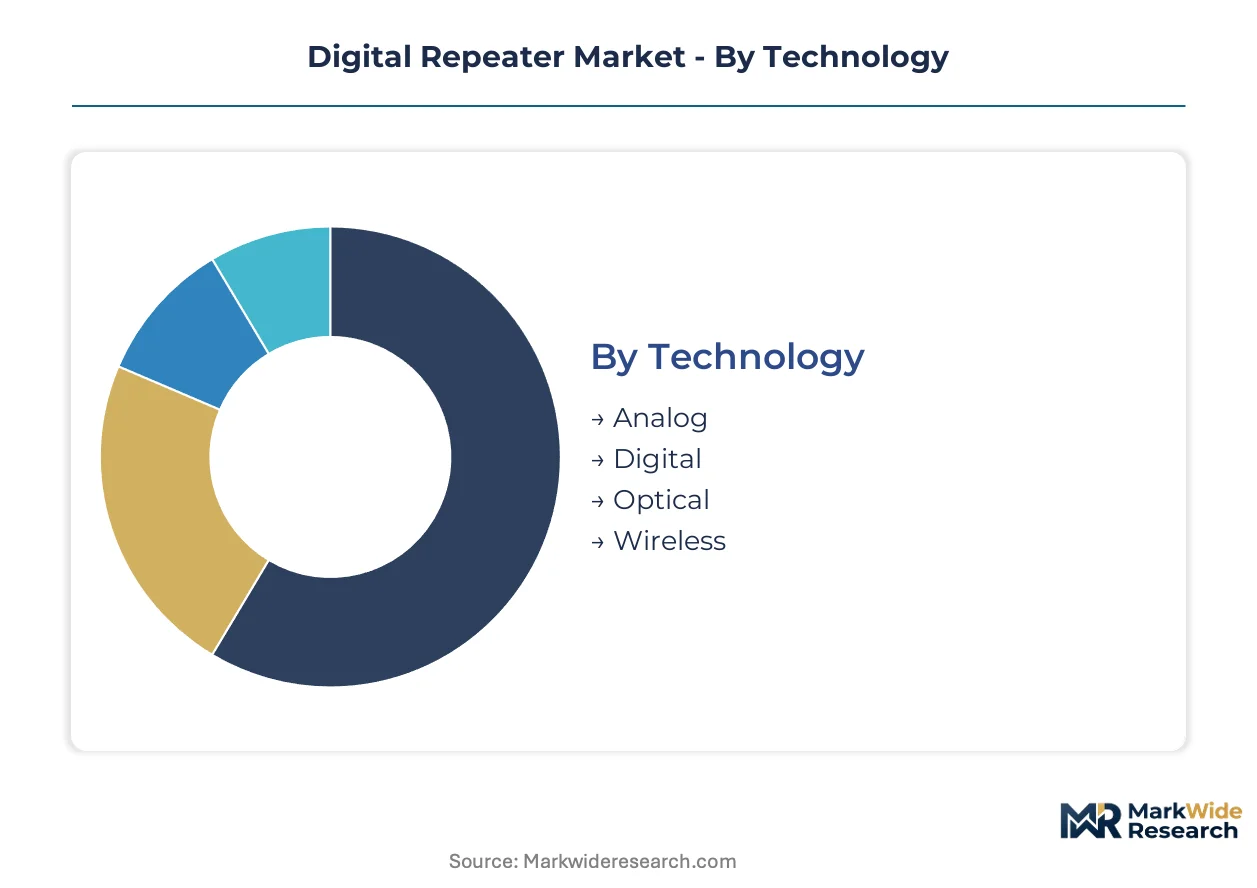
Digital repeater procurement varies sharply by deployment context, with spectrum allocation rules and infrastructure age dicting upgrade cycles across each segment category. Manufacturers must align product roadmaps to distinct certification timelines and performance specifications governing each technology variant and end-use environment.
Technology:
Replacement cycles for repeater hardware accelerate where 5G densification mandates field-reconfigurable architectures, compressing obsolescence windows for fixed-frequency legacy systems.
- Wireless:Field-programmable radio heads operate across sub-6 GHz and mmWave allocations without hardware swaps. India's smart city infrastructure tenders specify wireless repeaters for municipal IoT backhaul, with TRAI spectrum harmonization reducing multi-band equipment costs.
- Optical:Fiber-fed remote units deliver sub-microsecond latency for railway tunnel coverage in Germany and Japan. Underground transit authorities issue dedicated procurement frameworks for ruggedized optical repeaters with redundant backhaul paths.
- Digital:Software-defined baseband processing enables dynamic spectrum sharing across fragmented national allocations.
- Analog:Legacy FM and UHF architectures persist in rural public safety networks with extended replacement timelines.
Wireless sits at the top of the volume ranking, with Optical climbing the fastest.
Application:
Margin structures diverge by application based on certification burden and interoperability mandates, with public safety commanding premium pricing for hardened equipment.
- Public Safety:First-responder agencies mandate cross-jurisdictional interoperability under FCC Part 90 rules, driving replacement of analog networks. Municipal procurement in the United States prioritizes automatic gain control and interference detection features.
- Telecommunications:Carrier-grade distributed antenna systems address indoor coverage gaps for 5G mid-band deployments. South Korean operators require O-RAN compliance in infrastructure tenders, pressuring proprietary hardware vendors.
- Broadcasting:Terrestrial television transmitters and radio relay stations maintain coverage in remote terrain.
- Industrial Automation:Mining and oil-gas operators in Australia contract for dead-zone elimination service levels with bundled maintenance.
Telecommunications dominates shipment volumes, while Public Safety shows the steepest expansion trajectory.
End User:
Procurement authority concentrates differently across end-user types, with government contracts favoring established defense-aerospace suppliers and enterprise buyers demanding outcome-based coverage guarantees.
- Telecom Operators:Tier-1 carriers in India and South Korea drive volume through 5G small cell densification programs. Network equipment procurement follows centralized vendor qualification processes with multi-year framework agreements.
- Government Agencies:Federal and state emergency management authorities specify interoperable communications under hardened environmental standards. FCC certification timelines extend 12-18 months for signal booster approvals.
- Enterprises:Commercial building owners and campus operators purchase through system integrators with performance-based contracts.
- Utilities:Power grid operators deploy repeaters for SCADA and smart meter backhaul in remote substations.
Telecom Operators anchor volume demand, with Government Agencies expanding most quickly.
Deployment:
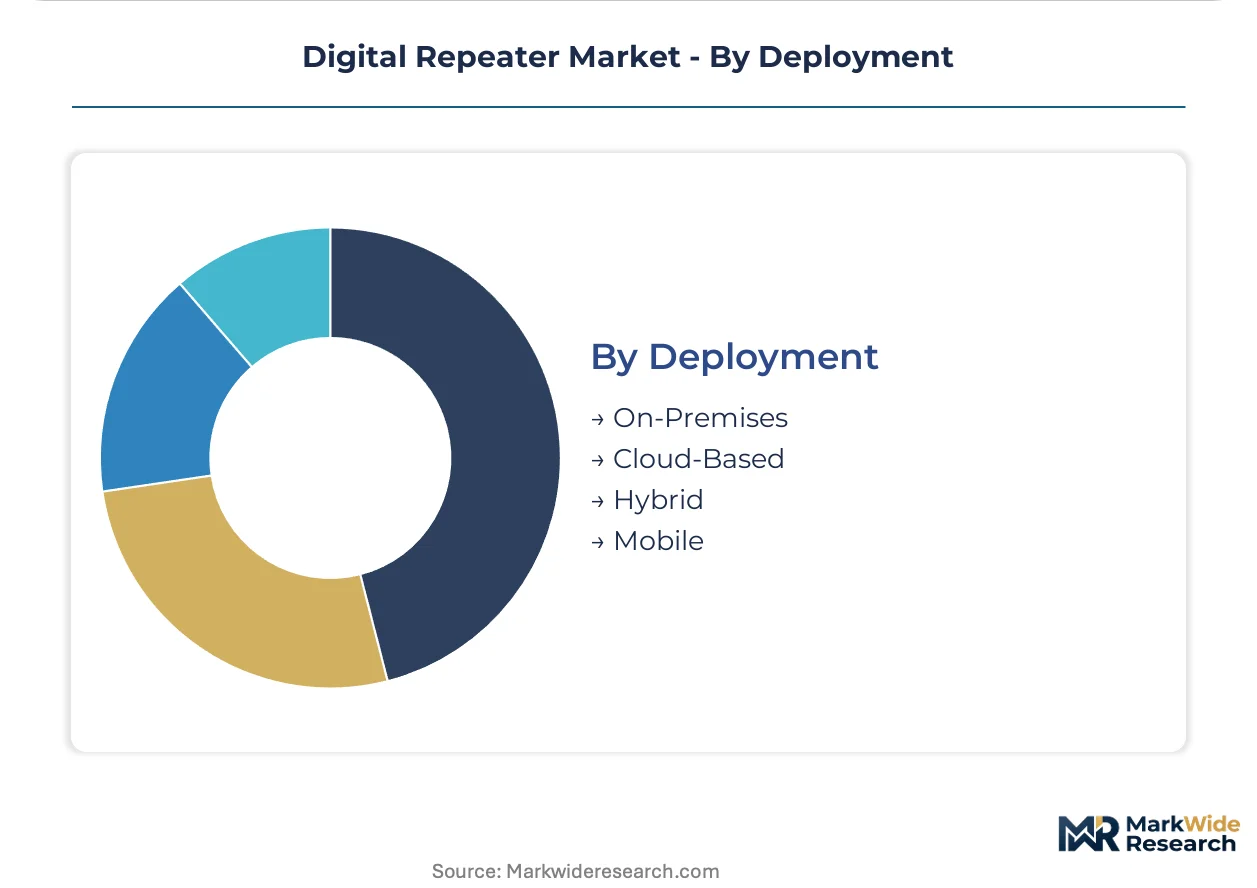
Cloud-managed architectures are displacing on-premises control systems, enabling centralized optimization across distributed repeater fleets while reducing field engineering requirements.
- On-Premises:Local baseband units maintain deterministic latency for time-sensitive industrial control applications. Manufacturing facilities in Germany specify on-premises repeaters with deterministic Ethernet backhaul for robotic coordination.
- Hybrid:Edge-processing nodes combine local RF handling with cloud-based analytics for predictive maintenance. Finnish telecom operators mandate hybrid architectures in 5G infrastructure tenders.
- Cloud-Based:Fully virtualized repeater management enables rapid reconfiguration across multi-site enterprise deployments.
- Mobile:Vehicle-mounted and portable repeaters support temporary coverage for emergency response and events.
On-Premises retains the largest installed base, with Hybrid gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart city infrastructure clusters in India anchor procurement volume for distributed antenna systems, while regulatory divergence across North America, Europe, and Asia-Pacific fragments certification timelines for digital repeater manufacturers.
United States
Federal emergency management agencies mandate interoperable public safety communications across state jurisdictions, driving replacement cycles for legacy analog repeater networks. FCC Part 90 certification timelines extend 12-18 months for signal booster approvals, freezing product launches for unlicensed spectrum variants. Dallas-Fort Worth metroplex hosts concentrated defense-aerospace RF engineering talent pools that commercial repeater developers compete to access.
Germany
Underground transit authorities in Berlin and Munich issue dedicated tenders for ruggedized optical-fiber backhaul repeaters with redundant path architectures. CE marking under the Radio Equipment Directive streamlines cross-border equipment certification, reducing time-to-market for European manufacturers. Bavaria's industrial automation corridor demands deterministic-latency on-premises repeaters for robotic coordination in manufacturing facilities.
India
Municipal infrastructure projects under the Smart City Mission mandate ubiquitous indoor coverage for IoT sensors and emergency services, creating sustained procurement pipelines. TRAI spectrum harmonization reduces multi-band equipment costs for wireless repeater deployments. Bengaluru and Hyderabad clusters concentrate domestic RF component manufacturing benefiting from PLI scheme production-linked incentives.
South Korea
Tier-1 carriers drive volume through 5G small cell densification programs with centralized vendor qualification processes. Operators mandate O-RAN compliance in infrastructure tenders, pressuring proprietary hardware vendors to publish interface specifications. Seoul Capital Area anchors network equipment procurement through multi-year framework agreements with technology-agnostic specifications.
Japan
Underground transit authorities in Tokyo and Osaka procure ruggedized optical repeaters for railway tunnel coverage with sub-microsecond latency requirements. METI industrial standards shape electromagnetic compatibility testing protocols for commercial equipment. Nagoya-Chubu manufacturing clusters supply precision RF components to repeater assembly operations serving Asia-Pacific export markets.
Digital Repeater Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-defined architectures and open-interface compliance. The vendor base stratifies across three maturity tiers: defense-aerospace heritage suppliers, semiconductor-integrated hardware specialists, and regional system integrators. Two dominant competitive moves define current positioning: backward integration into captive RF semiconductor supply, and strategic partnerships with telecom operators for outcome-based coverage contracts.
Among North American defense-aerospace heritage suppliers, Motorola Solutions, Inc. and Texas Instruments Incorporated exemplify contrasting archetypes—one representing public safety specialization for government contracts, the other semiconductor-integrated hardware with in-house fabrication capabilities. Remotek Corporation occupies a position within the compact form-factor specialist tier. These three anchors illustrate how geographic clustering around federal procurement hubs, semiconductor foundry corridors, and distributed antenna system integration centers shapes competitive positioning without requiring uniform strategic responses.
| Leading Market Players |
|---|
| Remotek Corporation |
| Cellcom Telecommunications, Inc. |
| Motorola Solutions, Inc. |
| Cellular Specialties, Inc. |
| Puget Sound Instrument Company, Inc. |
| Texas Instruments Incorporated |
| Westell, Inc. |
| BearCom Group, Inc. |
| Coiler Corporation |
| Others |
Value Chain & Pricing Dynamics
RF engineering talent scarcity in Dallas-Fort Worth and Bengaluru clusters widens labor-cost differentials between defense-aerospace heritage suppliers and emerging software-defined specialists, compressing margin spreads at the economy tier while premium pricing holds firm for hardened public safety equipment.
Pricing Analysis
Input-cost pass-through from GaN and GaAs substrate volatility flows unevenly across equipment tiers. Three-tier pricing structure across premium, standard, and economy levels separates FCC Part 90-certified public safety units from enterprise DAS hardware and unlicensed consumer boosters. Pricing pressure stems from small cell substitution in enterprise environments, forcing repeater vendors toward bundled service contracts. Government agencies show lowest price sensitivity due to interoperability mandates, while commercial building owners drive hardest bargain through system integrator channels.
Supply Chain Analysis
Workforce availability constraints in Taiwan, South Korea, and the United States limit RF semiconductor fabrication capacity for power amplifier components. Manufacturing draws from concentrated gallium nitride substrate suppliers, precision RF filter foundries, and fiber-optic transceiver assembly operations. Single-source vulnerability in GaN wafer supply from specific extraction geographies threatens component availability. Distribution runs through tier-1 carrier procurement frameworks, regional system integrators, and government contracting vehicles with extended qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital repeater market has shifted toward a late-cycle quality story as first-responder agencies mandate automatic gain control and interference detection features that only premium-tier suppliers can deliver.
For Market Incumbents: Deepen captive RF semiconductor supply through backward integration into GaN fabrication or strategic foundry partnerships to offset substrate cost volatility. Fortify position in FCC Part 90 certification pipelines where 12-18 month approval timelines freeze out unqualified competitors. Prioritize modular hardware architectures that adapt to spectrum reallocation without hardware swaps. For New Entrants and Emerging Players: Launch via outcome-based coverage contracts for mining and oil-gas operators in Australia and Canada who specify dead-zone elimination service levels rather than equipment procurement. Target India's PLI scheme beneficiaries with domestic RF component manufacturing partnerships. Pursue O-RAN compliance as a table-stakes entry credential for South Korean carrier tenders. For Investors and Strategic Acquirers: Defense-aerospace conglomerates with public safety portfolios are the most active acquirers in this space, seeking software-defined radio capabilities to complement legacy hardware franchises. Over a multi-year horizon, viability hinges on spectrum agility and open-interface compliance rather than fixed-frequency heritage. Watch for FCC Part 27 rule revisions as the inflection signal that elevates compliance costs and consolidates vendor tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Fabrication | Captive wafer supply insulates margins from concentrated mining geographies in substrate markets. |
| O-RAN Interface Certification | Multi-vendor interoperability unlocks South Korean and Finnish carrier procurement frameworks. |
| Outcome-Based Coverage Contracts | Performance-risk transfer to integrators captures enterprise buyers seeking dead-zone elimination guarantees. |
| Modular Hardware Architecture Development | Field-programmable frequency agility adapts to TRAI and FCC spectrum reallocation without redesign. |
| PLI Scheme Manufacturing Localization | Domestic RF component production in Bengaluru and Hyderabad clusters reduces landed cost disadvantages. |
Study Parameters
Bottom-up telecom operator and government agency procurement modeling reconciled against top-down RF component supply tracking forms the analytical core. Primary interviews with network equipment procurement managers, public safety communications directors, and DAS system integrators combined with secondary validation from FCC equipment authorization databases, ETSI harmonized standards filings, and TRAI spectrum allocation notices. Top-down triangulation cross-checks shipment data against carrier capex disclosures and municipal infrastructure tender awards.
Historical trendline analysis of replacement cycles across analog-to-digital migration periods informs projection frameworks. Segmentation dimensions span technology variant, application vertical, deployment architecture, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to 5G densification timelines and smart city infrastructure spend patterns. Industry-specific inputs include spectrum reallocation schedules, PLI scheme disbursement trajectories, and public safety interoperability mandate implementation phases.
Several conditions sit outside the modeled scope, including abrupt spectrum reallocation decisions, trade restriction escalations affecting GaN substrate flows, and carrier pivot toward standalone small cell architectures. Forecasts reflect documented assumptions about regulatory continuity and infrastructure investment commitment. Material deviation in FCC rulemaking timelines, PLI scheme renewal terms, or O-RAN standardization velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Gigabit Wi-Fi Access Points Market
Network Technology
WAN Optimization Controllers Market
Network Technology
Dark Fiber Market
Network Technology
Lit Fiber Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Global Routing Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Enterprise Network Equipment Market
Network Technology
Global Wi-Fi Range Extender Market
Network Technology
Global LWAN Market
Network Technology
Global Network Monitoring Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Malaysia Wireless Router Market
Network Technology
Data Center Switches Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Global Self-Organizing Network Market