
 Europe SD-WAN Market | 2026-2036
Europe SD-WAN Market Size, Share, and Industry Trends Forecast 2026-2036
Europe SD-WAN Market Insights
The EU Green Deal is realigning enterprise network priorities toward energy-efficient infrastructure across European operations. Cisco Systems leverages its security-integrated portfolio to dominate the managed services layer. Deutsche Telekom anchors its position through captive fiber assets and sovereign cloud partnerships. Nokia Corporation competes on 5G transport convergence with its packet core expertise.
SD-WAN is a software-defined networking architecture that abstracts WAN transport intelligence from proprietary hardware into centralized controllers, enabling policy-based path selection across MPLS, broadband, LTE, and 5G links with sub-50 millisecond failover. Its primary commercial purpose is to reduce branch connectivity costs while maintaining application performance SLAs for cloud workloads. Managed service deployments lead the European market as enterprises outsource operational complexity to telecom providers. Multi-cloud deployment models are expanding fastest as organizations distribute workloads across AWS, Azure, and sovereign European cloud instances. DIY installations remain margin-constrained due to scarce in-house networking talent.
GDPR and the NIS2 Directive shape European SD-WAN procurement by mandating encryption standards, data residency controls, and incident reporting capabilities that vendors must embed at the controller level. ETSI NFV standards further constrain supplier options by certifying interoperability between virtual network functions. The EU AI Act introduces additional audit requirements for automated traffic management decisions. Stakeholders must monitor regulatory divergence between EU harmonized standards and emerging national cybersecurity certifications in France, Germany, and Italy.
Market Dynamics
European financial institutions are accelerating branch modernization mandates under NIS2 Directive compliance deadlines, forcing incumbent MPLS architectures toward encrypted, cloud-native alternatives with sovereign data controls.
Growth Catalysts
- NIS2 Directive:The EU cybersecurity framework mandates encrypted WAN transport and incident reporting capabilities, compelling enterprise procurement of security-integrated SD-WAN controllers.
- Cloud-first banking:Financial services firms in Frankfurt and London require sub-50 millisecond failover to maintain trading application SLAs across distributed AWS and Azure workloads.
- 5G transport convergence:Packet core virtualization is electrifying interest in unified SD-WAN and mobile edge deployments for industrial automation use cases.
Market Restraints
- Scarce networking talent:DIY installations face margin compression as enterprises lack in-house engineers capable of controller-level policy orchestration.
- Fiber asset concentration:Deutsche Telekom's captive infrastructure in Germany limits price competition for managed service alternatives.
- ETSI NFV certification delays:Virtual network function interoperability testing extends vendor qualification timelines by 6-12 months.
Strategic Opportunities
- France cybersecurity certification:ANSSI's national scheme creates first-mover advantage for vendors achieving sovereign cloud partnership status.
- AI traffic management:The EU AI Act's audit requirements for automated path selection decisions favor vendors with embedded explainability features.
- Italy industrial corridor:Northern manufacturing clusters remain underpenetrated for 5G-enabled SD-WAN despite automotive supplier demand concentration.
Industry Challenges
- GDPR controller configuration:Data residency controls require geographic segmentation of policy engines, complicating multi-tenant managed service architectures.
- Legacy MPLS contract structures:Enterprises face early termination penalties that delay cloud migration timelines and compress vendor negotiation leverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe SD-WAN Market |
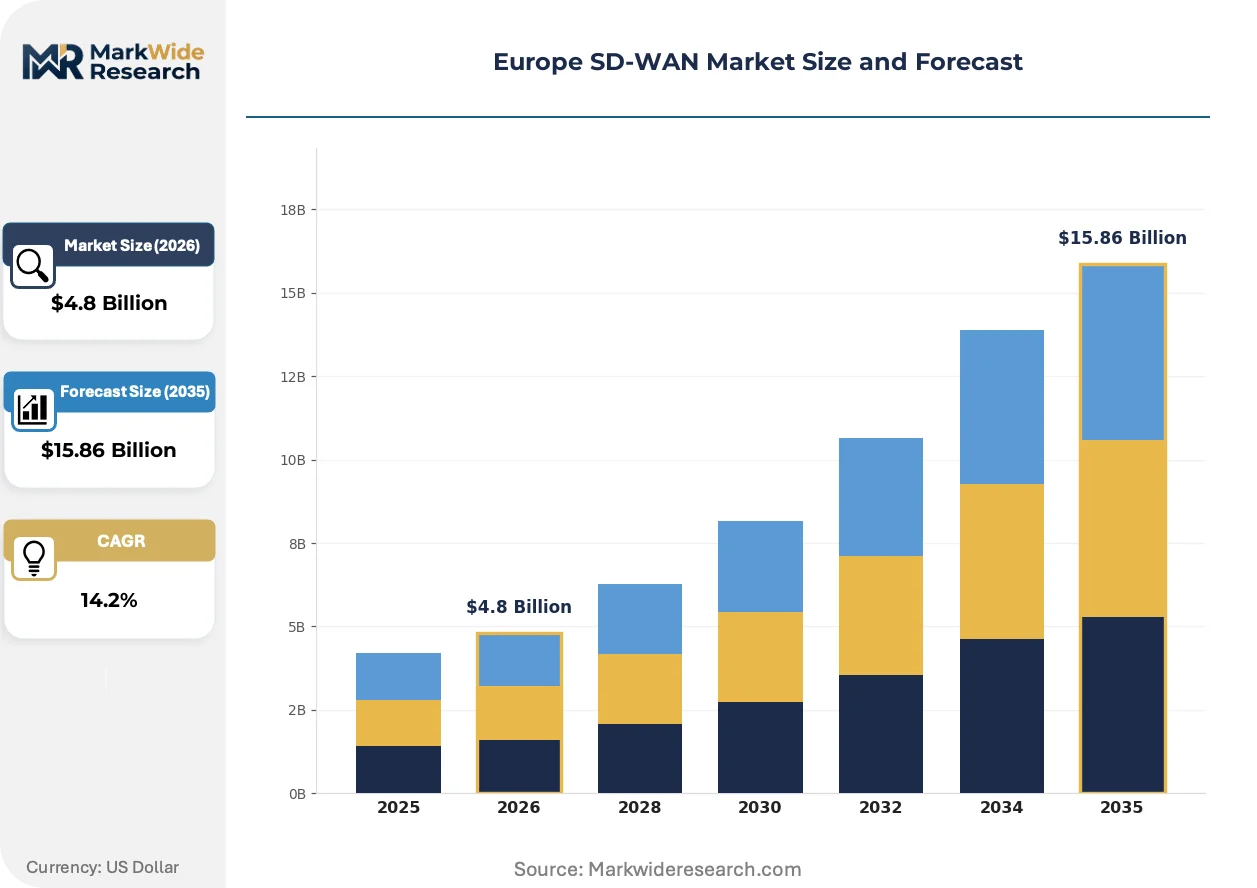
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed, Hybrid, Hosted, DIY Deployment Model: Public Cloud, Private Cloud, On-Premises, Multi-Cloud End User: Enterprises, SMBs, Government, Service Providers Technology: MPLS, LTE, Broadband, 5G |
| Companies Covered | BT Group PLC, Vodafone Group PLC, Virgin Media Business Limited, Exponential-e Ltd., Gamma Communications PLC, Cisco Systems, Inc., Nokia Corporation, Palo Alto Networks, Deutsche Telekom AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe SD-WAN Market Trends and Innovations
SD-WAN architectures are converging with zero-trust security frameworks and sovereign cloud requirements, reshaping how European enterprises evaluate vendor portfolios beyond pure connectivity metrics.
Secure Access Service Edge is electrifying branch security architectures by collapsing SD-WAN, firewall, and zero-trust network access into unified policy controllers. German automotive suppliers are piloting these converged stacks for supplier extranet connectivity. The technology is compressing procurement cycles as CISOs consolidate vendor relationships under single-platform RFPs.
The EU AI Act introduces mandatory documentation requirements for automated traffic management decisions that affect application performance. Vendors must embed algorithmic audit trails at the controller level to satisfy compliance officers. Financial services procurement teams in London and Paris are prioritizing explainable path selection features in vendor evaluations.
Outcome-based connectivity contracts are displacing traditional port-speed pricing in European managed service agreements. Enterprises in the Netherlands and Belgium now demand application-level SLA guarantees with penalty clauses for cloud workload latency violations. This shift favors telecom providers with end-to-end visibility across fiber, 5G, and broadband transport layers.
Europe SD-WAN Market Segmentation
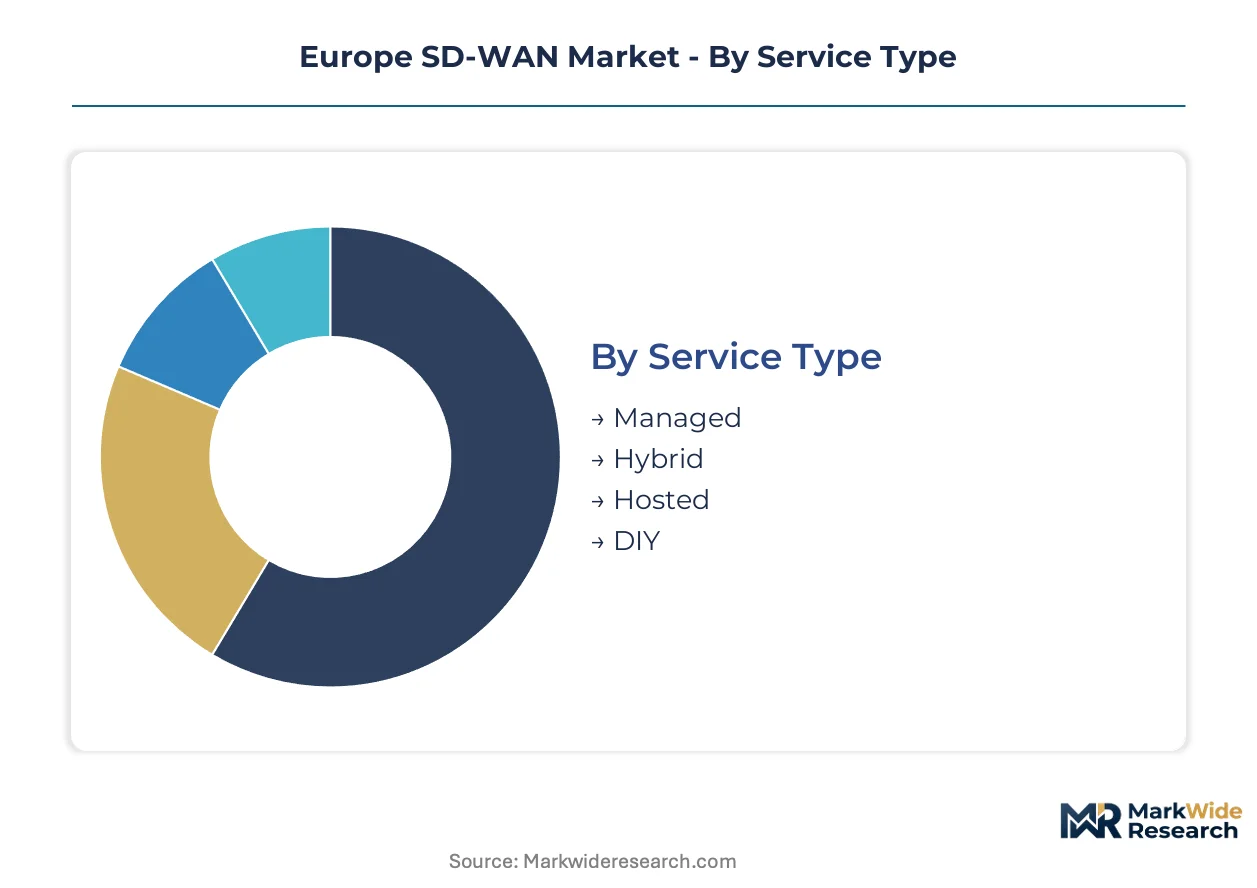
European SD-WAN procurement patterns diverge sharply between cost-optimized connectivity and premium managed service tiers. Deployment choices reflect regulatory pressure from the NIS2 Directive and GDPR data residency mandates.
Service Type:
Managed services dominate premium procurement while DIY deployments concentrate in cost-constrained segments.
- Managed:Telecom providers operate controller infrastructure, policy orchestration, and security updates under multi-year SLAs. Frankfurt and London financial institutions favor this model to satisfy NIS2 incident reporting requirements without internal engineering overhead.
- Hybrid:Enterprises retain policy control while outsourcing transport management, splitting operational burden between internal security teams and provider fiber assets. German automotive suppliers pilot this for supplier extranet segmentation.
- Hosted:Controller software runs on sovereign cloud instances with enterprise-managed policies.
- DIY:Self-operated deployments face scarce networking talent constraints across European labor markets.
Mature deployment sits with Managed. Newer deployment is concentrated in Hybrid.
Deployment Model:
Cloud-native architectures are displacing premises-bound controllers as multi-cloud workload distribution accelerates.
- Multi-Cloud:Policy engines orchestrate traffic across AWS, Azure, and sovereign European cloud instances with geographic segmentation for GDPR compliance. Dutch and Belgian enterprises lead adoption under outcome-based connectivity contracts with application-level SLA guarantees.
- Public Cloud:Controller instances run on hyperscaler infrastructure with shared-tenant economics.
- Private Cloud:Dedicated virtual infrastructure serves single-tenant security requirements in French and German regulated industries.
- On-Premises:Physical controller appliances persist in legacy MPLS transition scenarios with early termination penalty constraints.
Volume leadership sits with Public Cloud. Steepest expansion trajectory belongs to Multi-Cloud.
End User:
Procurement sophistication varies from sovereign cloud mandates in government to price-sensitive SMB self-service.
- Enterprises:Multi-site organizations with 50-plus locations demand encrypted WAN transport, zero-trust integration, and automated failover below 50 milliseconds for trading applications.
- Government:National cybersecurity certifications in France, Germany, and Italy constrain vendor qualification to sovereign partnership status.
- Service Providers:Telecom operators white-label SD-WAN platforms for downstream resale.
- SMBs:Small and mid-sized businesses prioritize plug-and-play deployment with minimal policy customization.
Compliance complexity peaks with Government. Fastest uptake is occurring in Enterprises.
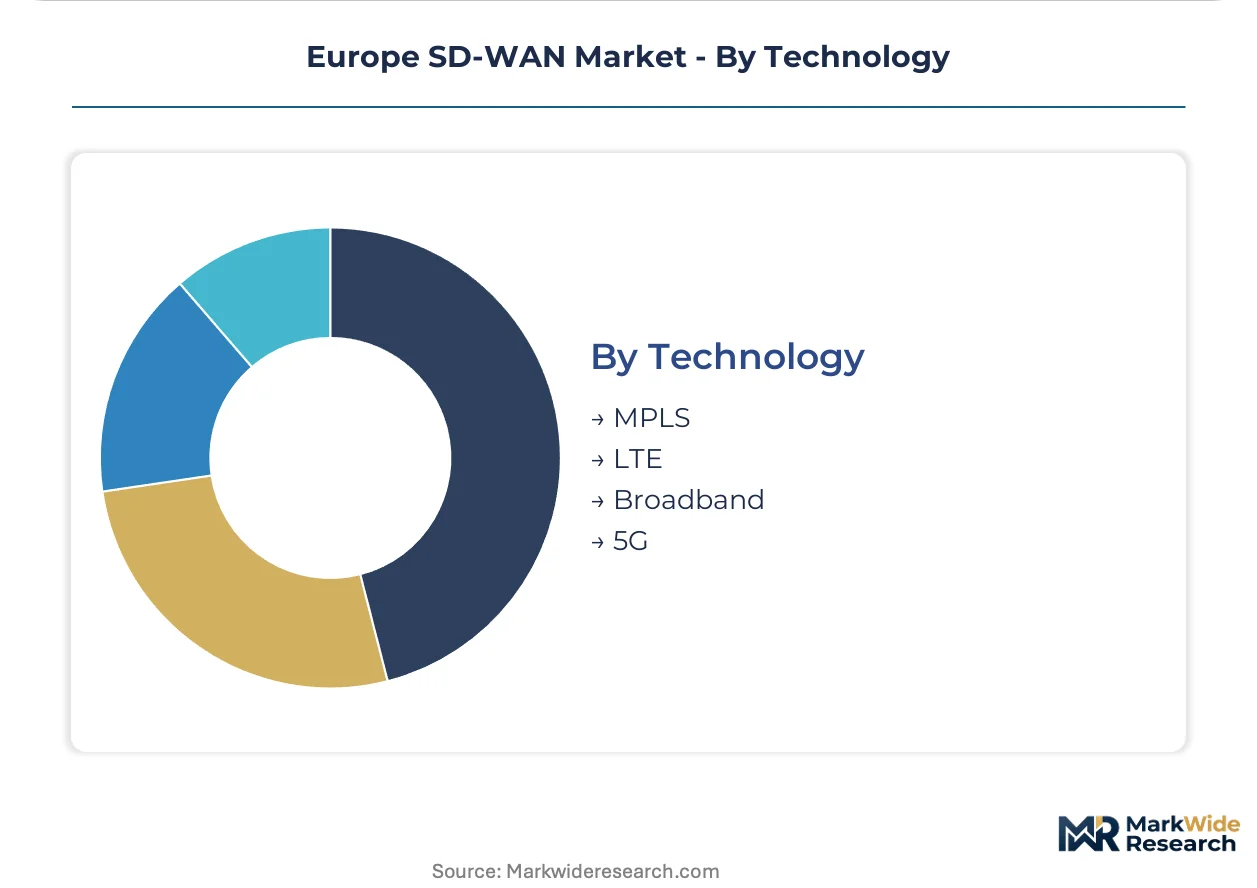
Technology:
Transport diversity enables path selection intelligence while 5G convergence reshapes industrial edge deployment.
- 5G:Packet core virtualization unifies mobile edge and SD-WAN policy controllers for industrial automation use cases. Northern Italian manufacturing corridors remain underpenetrated despite automotive supplier demand concentration.
- Broadband:Cost-optimized internet transport dominates branch backup and price-sensitive primary connectivity.
- MPLS:Legacy private circuits persist in financial services under contract structures with early termination penalties.
- LTE:Cellular failover provides continuity for remote sites beyond fiber reach.
Declining share sits with MPLS. Gaining share fastest is 5G.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's financial district generates concentrated demand for sub-50 millisecond failover connectivity as trading firms modernize branch infrastructure. The EU NIS2 Directive and GDPR data residency mandates reshape procurement priorities across continental networks. Sovereign cloud partnerships and national cybersecurity certifications now determine vendor qualification in regulated industries.
Germany
Automotive suppliers in Baden-Württemberg and Bavaria pilot 5G-enabled SD-WAN for industrial automation, demanding unified mobile edge policy controllers. The BSI (Federal Office for Information Security) enforces strict encryption standards for critical infrastructure operators. Deutsche Telekom's captive fiber assets in North Rhine-Westphalia limit price competition for managed service alternatives.
United Kingdom
London trading floors require encrypted WAN transport with automated failover below 50 milliseconds for distributed AWS and Azure workloads. The UK National Cyber Security Centre mandates incident reporting capabilities that favor security-integrated controller platforms. BT Group and Virgin Media Business compete for financial services contracts across the City and Canary Wharf clusters.
France
Paris-based banking consortiums prioritize explainable path selection features to satisfy EU AI Act audit requirements for automated traffic management. ANSSI's national cybersecurity certification scheme creates first-mover advantage for vendors achieving sovereign cloud partnership status. Île-de-France enterprises concentrate procurement of hosted controller instances with geographic policy segmentation.
Netherlands
Amsterdam and Rotterdam enterprises lead adoption of outcome-based connectivity contracts with application-level SLA guarantees and penalty clauses. The Dutch Authority for Digital Infrastructure enforces GDPR-compliant data residency controls across multi-tenant managed service architectures. Randstad logistics hubs drive demand for broadband-5G hybrid transport with intelligent path selection.
Italy
Northern manufacturing corridors in Lombardy and Piedmont remain underpenetrated for 5G-enabled SD-WAN despite automotive supplier demand concentration. Italy's national cybersecurity agency certifies vendors for critical infrastructure protection under EU harmonized standards. Milan-based system integrators bridge sovereign cloud partnerships for mid-market industrial automation deployments.
Europe SD-WAN Market Competitive Landscape
Premium-margin players sit above commodity-margin players across security integration and sovereign cloud certification dimensions. The European SD-WAN market structures around three tiers: telecom operators with captive fiber assets, security-integrated technology vendors, and regional managed service specialists. Strategic archetypes include converged SASE platform providers, sovereign cloud partnership holders, and industrial 5G transport convergents. Dominant competitive moves center on national cybersecurity certification acquisition and outcome-based SLA contract structuring.
Within the telecom operator tier, Deutsche Telekom AG and BT Group PLC exemplify captive infrastructure strategies that constrain price competition in core markets. Cisco Systems, Inc. occupies a position representing security-integrated portfolio consolidation across managed services layers. Nokia Corporation anchors the 5G transport convergence archetype through packet core virtualization expertise.
| Leading Market Players |
|---|
| BT Group PLC |
| Vodafone Group PLC |
| Virgin Media Business Limited |
| Exponential-e Ltd. |
| Gamma Communications PLC |
| Cisco Systems, Inc. |
| Nokia Corporation |
| Palo Alto Networks |
| Deutsche Telekom AG |
| Others |
Pricing and Supply Chain Analysis
Managed-to-DIY deployment divergence splits the European SD-WAN market into premium SLA tiers and cost-optimized commodity segments, with each tier demanding distinct controller hardware sourcing and sovereign cloud partnership configurations. This bifurcation concentrates pricing power with telecom operators holding captive fiber assets while compressing margins for self-operated installations facing scarce networking talent.
Pricing Analysis
Outcome-based connectivity contracts anchor pricing to application-level SLA guarantees rather than port-speed metrics, with Dutch and Belgian enterprises demanding penalty clauses for cloud workload latency violations. Three-tier pricing structure across premium managed services, hybrid deployments, and economy DIY segments reflects certification grade and sovereign cloud partnership status. Pricing pressure stems from Deutsche Telekom's fiber concentration in Germany limiting competitive alternatives. SMBs exhibit highest price sensitivity, while Frankfurt financial institutions prioritize sub-50 millisecond failover reliability over cost.
Supply Chain Analysis
ETSI NFV certification and national cybersecurity schemes in France, Germany, and Italy gate vendor qualification, extending procurement timelines by 6-12 months. Controller hardware production centers on Taiwan, South Korea, and USA, with software development anchored in USA and India. Semiconductor components for packet core virtualization and encryption modules draw from concentrated Asian foundries. Single-source vulnerability sits with proprietary ASIC suppliers for high-throughput edge devices. Distribution runs through telecom operator direct channels and systems integrator partnerships serving mid-market verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce in-house networking talent across European labor markets constrains DIY deployment capacity, propping managed service pricing premiums as enterprises outsource operational complexity to certified providers.
For Market Incumbents: Deploy sovereign cloud partnership acquisition as the primary defensive lever against emerging SASE platform competitors. Capture ANSSI certification in France and BSI approval in Germany before NIS2 Directive deadlines tighten qualification windows. Consolidate security-integrated controller portfolios to counter Palo Alto Networks' converged platform threat in financial services procurement.
For New Entrants and Emerging Players: Capture northern Italian manufacturing corridors in Lombardy and Piedmont, where 5G-enabled SD-WAN penetration lags automotive supplier demand concentration. Target hosted controller deployments for mid-market German automotive suppliers seeking supplier extranet segmentation without full managed service overhead. Lead with industrial automation use cases requiring unified mobile edge policy controllers.
For Investors and Strategic Acquirers: Exit pathways concentrate in telecom operator tuck-ins and security vendor platform consolidation, with sovereign cloud partnership holders commanding premium multiples. Long-term viability favors vendors embedding explainable AI traffic management features ahead of EU AI Act audit requirement maturation. Watch ANSSI certification queue depth as inflection signal for French market access competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership Acquisition | ANSSI and BSI certifications unlock regulated industry procurement in France and Germany. |
| SASE Platform Integration | Cisco's security-integrated portfolio consolidation responds to CISO vendor rationalization mandates. |
| 5G Transport Convergence | Nokia's packet core virtualization expertise addresses industrial automation edge deployment demand. |
| Outcome-Based Contract Structuring | Application-level SLA guarantees with penalty clauses displace port-speed pricing in Dutch and Belgian markets. |
| Explainable AI Traffic Management | Algorithmic audit trails at controller level satisfy EU AI Act compliance for London and Paris financial services. |
Research Methodology
Multi-period observation of managed service contract structures, NIS2 Directive implementation timelines, and sovereign cloud partnership formations anchored the trend analysis, supplemented by interviews with European network architects, telecom procurement officers, CISOs at financial institutions, and industrial automation engineers. Secondary validation drew from ETSI NFV certification databases, ANSSI and BSI security approval registers, hyperscaler capex disclosures, and EU regulatory filing repositories. Bottom-up deployment model sizing triangulated against top-down telecom operator revenue segment reporting.
Input-output matrices modeled traffic volumes across MPLS, broadband, LTE, and 5G transport layers against controller instance counts segmented by deployment model, service type, end-user category, and national regulatory cluster. CAGRs were derived from elasticity-calibrated growth functions applied across the projection horizon. Industry-specific forecast inputs incorporated NIS2 Directive compliance deadline phasing and EU AI Act audit requirement rollout patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ETSI NFV certification delays, sovereign cloud partnership exclusivity terms, and 5G spectrum auction timing. Forecasts reflect documented assumptions regarding regulatory harmonization and talent scarcity persistence. A model refresh is warranted upon material change in NIS2 enforcement intensity or ANSSI certification queue processing rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
MENA Wireless Routers Market
Network Technology
Zero-Touch Provisioning Market
Network Technology
Cloud Gateway Module Market
Network Technology
CPE Router Market
Network Technology
US Private 5G Network Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
Global Active Network Management Market
Network Technology
Gigabit Passive Optical Network (GPON) Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Network Packet Broker Market
Network Technology
Network Performance Monitoring Market
Network Technology
WAN Optimization Controllers Market
Network Technology
Industrial Wireline Networking Market
Network Technology
Converged Cable Access Platform (CCAP) Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Ethernet Backhaul Equipment Market