
 Global Active Network Management Market | 2026-2036
Global Active Network Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Active Network Management Market Intelligence
A shift from outsourced grid analytics toward in-house software development is hardening among major utilities seeking control over real-time network orchestration. Siemens leverages deep manufacturing scale in digital substation hardware to anchor European utility relationships. ABB competes through specialized consulting services that bridge legacy SCADA investments with cloud-native architectures. General Electric sustains technology leadership in phasor measurement unit integration for North American transmission operators.
Active network management comprises software-defined control systems that monitor, predict, and autonomously reconfigure electricity distribution networks using sub-second telemetry from distributed sensors and smart meters. These platforms execute voltage regulation, fault isolation, and load balancing across meshed topologies with renewable penetration exceeding fifty percent. Software offerings capture the dominant margin pool as utilities prioritize algorithmic forecasting over incremental hardware spend. Distributed energy resource management systems represent the fastest-expanding technology segment, while supervisory control and data acquisition installations remain mature but essential infrastructure across legacy grids.
FERC Order 2222 in the United States mandates distribution utilities to accommodate aggregated distributed energy resources in wholesale markets, directly stimulating platform procurement. The EU Green Deal and Germany's Energy Industry Act impose connection priority for renewables, forcing grid operators to deploy dynamic hosting capacity algorithms. Australia's energy market operator requires visibility standards for inverter-connected resources under updated grid codes. Stakeholders must weigh regulatory compliance timelines against the technical debt of retrofitting legacy SCADA networks with API-native control layers.
Market Dynamics
Utilities face mounting pressure to orchestrate bidirectional power flows from distributed solar and wind assets, forcing a fundamental rearchitecture of control systems from centralized SCADA to algorithmic, cloud-native platforms.
Growth Catalysts
- FERC Order 2222:The US mandate requires distribution utilities to integrate aggregated distributed energy resources into wholesale markets, compelling procurement of dynamic hosting capacity software.
- Germany's Energy Industry Act:Statutory renewable connection obligations force distribution system operators to deploy autonomous voltage regulation and fault isolation systems.
- Sub-second telemetry:Smart meter and sensor density improvements enable real-time network reconfiguration that was technically impossible under legacy polling intervals.
Market Restraints
- SCADA retrofit costs:Legacy infrastructure in mature European grids requires expensive API-native control layer overlays before active management platforms can function.
- Silicon supply concentration:Phasor measurement unit and digital substation hardware production clusters in East Asian foundries, exposing procurement timelines to geopolitical friction.
- Cybersecurity certification delays:IEC 62351 compliance timelines for critical infrastructure software extend vendor qualification periods by twelve to eighteen months.
Strategic Opportunities
- Australia's inverter visibility standards:Updated grid codes from the national energy market operator create immediate demand for distributed energy resource management systems.
- Algorithmic forecasting convergence:Machine learning-based load prediction is merging with autonomous switching to create unified control platforms that displace siloed vendor stacks.
- India's renewable-rich states:Rajasthan and Gujarat distribution companies lack legacy SCADA density, enabling greenfield deployment of cloud-native architectures without technical debt.
Industry Challenges
- Power systems engineering talent scarcity:Utilities compete with technology vendors for specialists capable of integrating legacy protection relays with containerized software deployments.
- Multi-vendor interoperability testing:Proprietary communication protocols from incumbent automation suppliers force costly custom integration work for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Active Network Management Market |
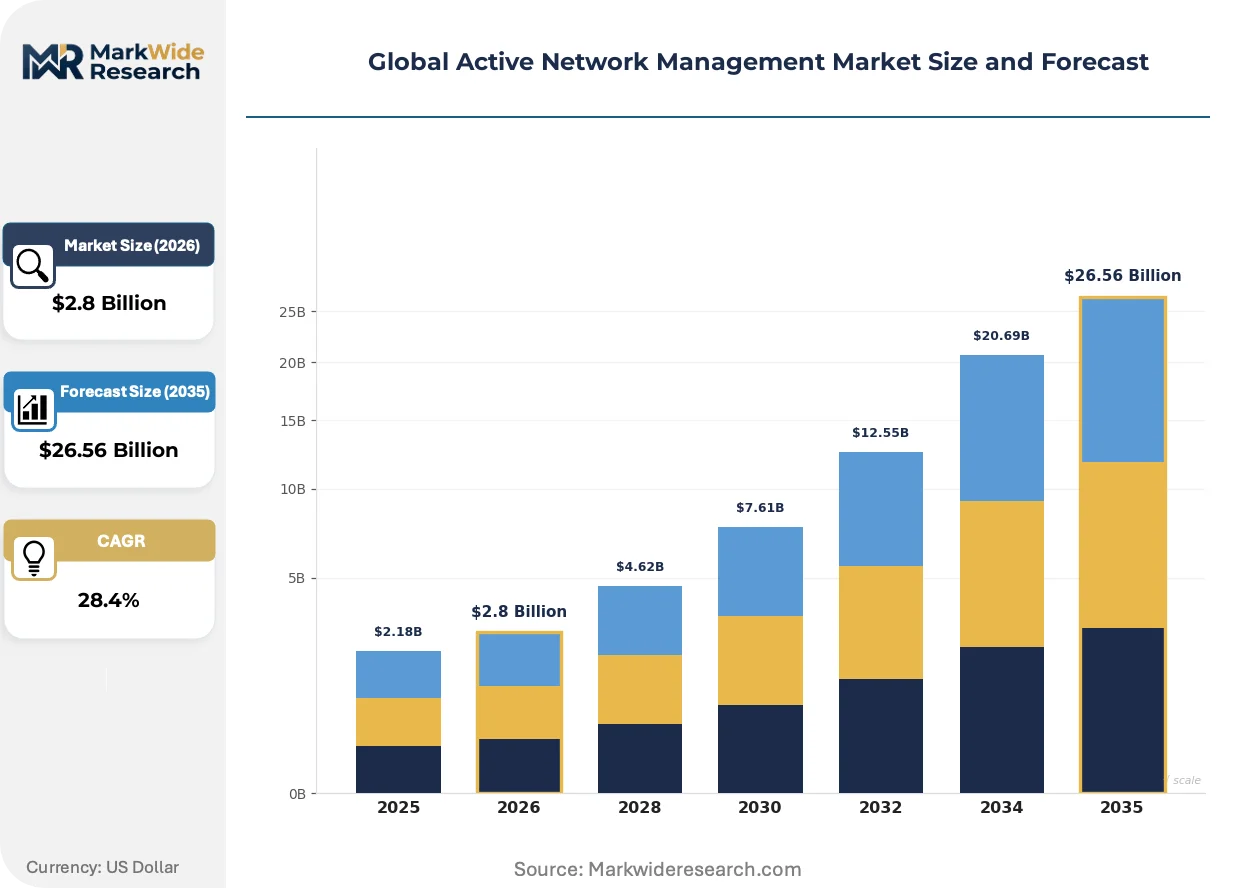
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.56 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Offering: Hardware, Software, Services, Consulting Application: Load Balancing, Voltage Regulation, Fault Detection, Demand Response, Energy Storage Integration End User: Utilities, Renewable Energy Providers, Telecom Operators, Data Centers, Commercial Enterprises Technology: Phasor Measurement Units, Advanced Metering Infrastructure, Supervisory Control and Data Acquisition, Distributed Energy Resource Management Systems |
| Companies Covered | Siemens, ABB, General Electric, Schneider Electric, Cisco Systems, IBM, Oracle, Itron, Landis+Gyr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Active Network Management Market Strategic Shifts & Innovations
Software-defined control architectures are compressing the traditional hardware-software boundary in grid automation, with algorithmic platforms capturing investment flows that previously flowed to substation equipment.
Cloud-native distributed energy resource management systems are overtaking on-premise SCADA extensions for new utility deployments. European distribution system operators in Germany and the Netherlands are migrating voltage optimization and fault location algorithms to containerized edge-to-cloud stacks. This shift is compressing hardware procurement cycles while expanding recurring software revenue pools for control platform vendors.
The EU Green Deal's grid modernization mandates are accelerating algorithmic hosting capacity assessments as standard connection practice. Distribution operators must now demonstrate dynamic capacity headroom before approving renewable interconnection requests. German network operators are responding by deploying physics-informed neural networks that predict thermal and voltage constraints across meshed low-voltage circuits.
Subscription-based control software licensing is displacing perpetual hardware-software bundles in utility procurement. North American municipal and cooperative utilities are unbundling automation software from switchgear contracts, selecting best-of-breed algorithm vendors independently of primary equipment suppliers. This pattern is most visible in California and Texas, where competitive retail markets pressure operational cost structures.
Global Active Network Management Market Segmentation
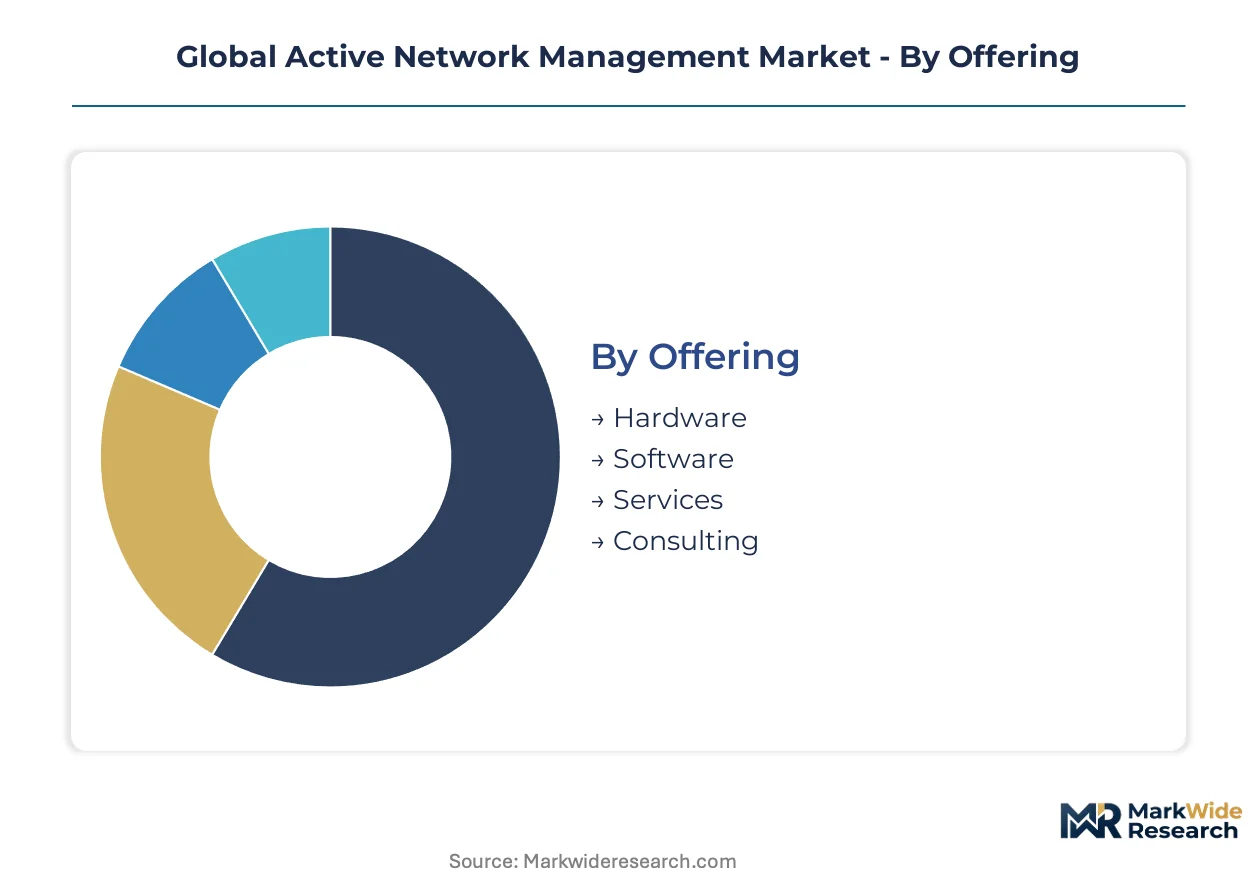
Active network management platforms fragment across four distinct axes that shape procurement patterns and vendor positioning. Each segmentation layer reveals divergent margin structures, integration complexity, and regulatory exposure that determine competitive outcomes.
Offering:
Standardization dominates hardware and consulting while software and services fragment into bespoke configurations.
- Software:Algorithmic platforms execute voltage regulation, fault isolation, and load balancing through sub-second telemetry from distributed sensors. German distribution system operators under the Energy Industry Act prioritize autonomous hosting capacity algorithms over incremental hardware spend.
- Services:Implementation, integration, and ongoing operational support bridge legacy SCADA investments with cloud-native architectures. North American municipal utilities unbundle software procurement from switchgear contracts, creating standalone services demand.
- Hardware:Phasor measurement units, digital substation equipment, and edge computing nodes provide physical telemetry infrastructure.
- Consulting:Specialized engineering advisory guides utilities through multi-vendor interoperability testing and cybersecurity certification.
Leading the category by volume: Software. Growing fastest: Services.
Application:
Mission-critical functions command premium pricing while operational optimization applications compete on cost efficiency.
- Voltage Regulation:Autonomous tap-changer control and reactive power management stabilize meshed low-voltage circuits with renewable penetration exceeding fifty percent. Australian grid codes mandate visibility standards that accelerate voltage optimization deployment.
- Fault Detection:Sub-second isolation algorithms minimize outage duration through predictive relay coordination. FERC Order 2222 in the United States drives wholesale market integration requirements that stress fault response speed.
- Load Balancing:Real-time power flow orchestration across bidirectional distribution networks.
- Demand Response:Aggregated distributed energy resource dispatch for grid stability services.
- Energy Storage Integration:Battery management system coordination with network reconfiguration protocols.
Highest margin concentration: Fault Detection. Steepest expansion trajectory: Voltage Regulation.
End User:
Regulated utilities anchor procurement volume while competitive retail markets drive software unbundling.
- Utilities:Distribution and transmission operators deploy end-to-end active management platforms under statutory renewable connection obligations. Germany's distribution system operators face mandatory dynamic hosting capacity demonstrations before approving interconnection requests.
- Renewable Energy Providers:Solar and wind asset operators require visibility into network constraints affecting generation dispatch. Rajasthan and Gujarat distribution companies in India enable greenfield cloud-native deployment without legacy SCADA technical debt.
- Telecom Operators:Backup power and microgrid management for network infrastructure resilience.
- Data Centers:On-site generation integration with grid-interactive load flexibility.
- Commercial Enterprises:C&I facilities pursuing behind-the-meter optimization and demand charge management.
Procurement scale leader: Utilities. Fastest-growing demand: Renewable Energy Providers.
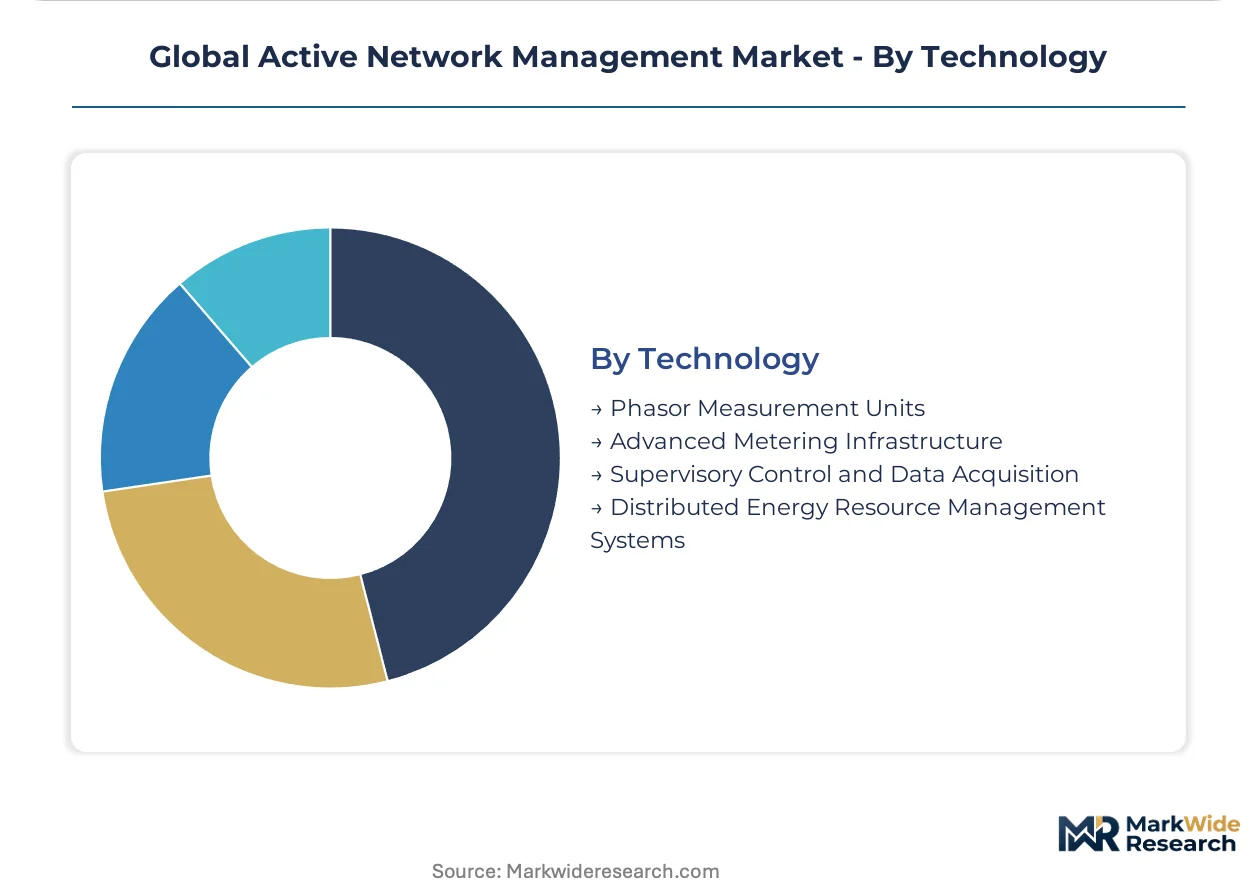
Technology:
Mature infrastructure layers coexist with emerging software-defined architectures in hybrid deployment patterns.
- Distributed Energy Resource Management Systems:Cloud-native platforms aggregate inverter-connected resources for autonomous dispatch and market participation. Australia's updated grid codes from the national energy market operator create immediate procurement stimulus.
- Supervisory Control and Data Acquisition:Legacy centralized control systems remain essential infrastructure requiring API-native overlays for active management functionality. European grid operators face expensive retrofit cycles before algorithmic platforms achieve full capability.
- Phasor Measurement Units:Synchrophasor telemetry enables wide-area stability monitoring across transmission networks.
- Advanced Metering Infrastructure:Smart meter density improvements provide sub-second telemetry foundations for real-time network reconfiguration.
Deployment maturity leader: Supervisory Control and Data Acquisition. Gaining share fastest: Distributed Energy Resource Management Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German distribution system operators anchor procurement volume under statutory renewable connection obligations, while the United States and Australia accelerate deployment through wholesale market mandates and grid code updates. Indian states with sparse legacy infrastructure present greenfield opportunities for cloud-native architectures.
Germany
FERC Order 2222 analogs in the EU Green Deal framework force dynamic hosting capacity demonstrations before renewable interconnection approvals. The Energy Industry Act imposes statutory obligations on distribution system operators to deploy autonomous voltage regulation systems. North Rhine-Westphalia and Bavaria host the densest concentrations of meshed low-voltage circuit deployments with physics-informed neural networks predicting thermal constraints.
United States
FERC Order 2222 mandates distribution utilities to integrate aggregated distributed energy resources into wholesale markets, compelling dynamic hosting capacity software procurement. The Federal Energy Regulatory Commission's directive directly stimulates platform adoption across municipal and cooperative utilities. California and Texas utilities unbundle automation software from switchgear contracts, selecting independent algorithm vendors under competitive retail market pressure.
Australia
The national energy market operator's updated grid codes mandate visibility standards for inverter-connected resources, creating immediate distributed energy resource management system demand. Sub-second telemetry requirements from smart meter density improvements enable real-time network reconfiguration previously impossible under legacy polling intervals. Victoria and New South Wales distribution networks deploy voltage optimization algorithms to manage bidirectional power flows from rooftop solar penetration exceeding fifty percent in some zones.
India
Rajasthan and Gujarat distribution companies lack legacy SCADA density, enabling greenfield cloud-native deployment without technical debt from retrofit cycles. The Ministry of Power's renewable-rich state programs prioritize algorithmic forecasting over incremental hardware spend. Ahmedabad and Jaipur industrial corridors attract autonomous network management pilots for solar-wind hybrid parks requiring meshed topology control.
United Kingdom
Ofgem's network price control mechanisms incentivize distribution system operators to demonstrate cost-efficient renewable integration through software-defined control architectures. The regulator's RIIO-ED2 framework rewards operators deploying predictive hosting capacity assessments for distributed generation connections. Scottish distribution networks advance wide-area stability monitoring across transmission interfaces with high wind penetration from North Sea developments.
Global Active Network Management Market Key Industry Players
Strategic partnerships dominate the current landscape as industrial automation conglomerates ally with cloud-native software specialists to bridge legacy SCADA investments with API-native control layers. The vendor base stratifies across three tiers: diversified industrial technology groups with digital substation hardware scale, specialized grid software pure-plays, and IT infrastructure vendors extending into operational technology domains. Two archetypes command disproportionate influence: manufacturing-anchored platforms leveraging deep utility relationships, and consulting-heavy integrators managing multi-vendor interoperability complexity. Competitive intensity concentrates on M&A activity targeting machine learning forecasting capabilities and geographic expansion into renewable-rich emerging markets.
Among diversified industrial technology groups, Siemens, ABB, and General Electric occupy distinct positioning vectors within the competitive structure. Siemens leverages deep manufacturing scale in digital substation hardware to anchor European utility relationships. ABB competes through specialized consulting services that bridge legacy SCADA investments with cloud-native architectures. General Electric sustains technology leadership in phasor measurement unit integration for North American transmission operators, representing the manufacturing-anchored platform archetype with embedded hardware-software bundling advantages.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| General Electric |
| Schneider Electric |
| Cisco Systems |
| IBM |
| Oracle |
| Itron |
| Landis+Gyr |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up software specialists have consolidated fragmented grid analytics vendors, tightening pricing discipline while concentrating procurement leverage over digital substation hardware suppliers across Germany and the United States.
Pricing Analysis
Volume concentrates in perpetual hardware-software bundles while margins migrate toward recurring SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels separates utilities with IEC 62351 certification requirements from municipal operators prioritizing cost efficiency. Pricing pressure stems from unbundling trends in California and Texas competitive retail markets. Renewable energy providers exhibit highest price sensitivity, whereas transmission operators under FERC mandates demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from European utilities mandate multi-supplier qualification for phasor measurement units and edge computing nodes. Production clusters in Taiwan, South Korea, and Germany supply semiconductor components and digital substation equipment. Raw material dependencies include silicon wafers, rare earth magnets, and copper busbars. Single-source vulnerability concentrates in East Asian foundry capacity. Distribution runs through authorized system integrators and direct OEM relationships with major utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from IEC 62351 certification timelines and SCADA retrofit technical debt will force weaker software vendors into strategic exits or acquisition.
For Market Incumbents: Deepen manufacturing scale in digital substation hardware to anchor utility relationships against cloud-native software pure-plays. Prioritize backward integration into phasor measurement unit production to reduce East Asian foundry exposure. Invest in containerized edge-to-cloud certification pipelines to compress eighteen-month vendor qualification periods.
For New Entrants and Emerging Players: Physics-informed neural networks for thermal constraint prediction offer a technology-first wedge into German distribution system operator procurement under Energy Industry Act obligations. Target Rajasthan and Gujarat greenfield deployments lacking legacy SCADA technical debt. Pursue direct utility partnerships bypassing incumbent system integrator channels.
For Investors and Strategic Acquirers: Distressed-cycle entries favor machine learning forecasting specialists in Australia facing inverter visibility mandate procurement acceleration. Long-term viability centers on algorithmic platform vendors with recurring revenue foundations and utility-owned software development reversals as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies voltage regulation and fault detection algorithms under single vendor relationship for German utilities. |
| Acquisition of Specialist Firm | Machine learning forecasting capabilities compress procurement cycles for Australian grid operators. |
| Geographic Expansion | Greenfield cloud-native deployment in Indian renewable-rich states bypasses European retrofit costs. |
| Strategic Partnership | Industrial automation conglomerates ally with cloud-native software vendors bridging SCADA legacy investments. |
| Product Launch | Containerized edge-to-cloud stacks capture recurring software revenue from unbundled procurement trends. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with utility planning officers, distribution system operators, grid automation engineers, and software procurement leads. EIA data, FERC filings, IEA reports, and EU Green Deal implementation documents provided validation. Bottom-up project pipeline analysis triangulated against top-down utility capex surveys.
Granularity-level modeling deployed technology segments at component level, application functions at system architecture level, and end-user categories at procurement authority level across the analysis window. CAGRs derived from algorithmic adoption curves weighted by regulatory mandate implementation timelines. Forecast inputs incorporated smart meter density trajectories and renewable interconnection queue data.
Several conditions sit outside the modeled scope, including cybersecurity incident impacts on vendor qualification timelines and geopolitical disruptions to East Asian semiconductor supply. Forecasts reflect documented assumptions about regulatory compliance deadlines and utility capital allocation priorities. A model refresh is warranted upon material change in FERC Order 2222 implementation pace or EU Green Deal grid modernization funding levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
SP Routing and Ethernet Switching Market
Network Technology
Enterprise Routers Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Radio Modem Market
Network Technology
Network Management Solutions Market
Network Technology
Network Telemetry Market
Network Technology
Sand Lane Systems Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Data Center Switches Market
Network Technology
Cloud Managed Access Points Market
Network Technology
North America Enterprise WLAN Market
Network Technology
Lit Fiber Market
Network Technology
Global Internet Transit Market
Network Technology
IT Connector Market