
 Home Wi-Fi Router and Extender Market | 2026-2036
Home Wi-Fi Router and Extender Market Size, Share, and Industry Trends Forecast 2026-2036
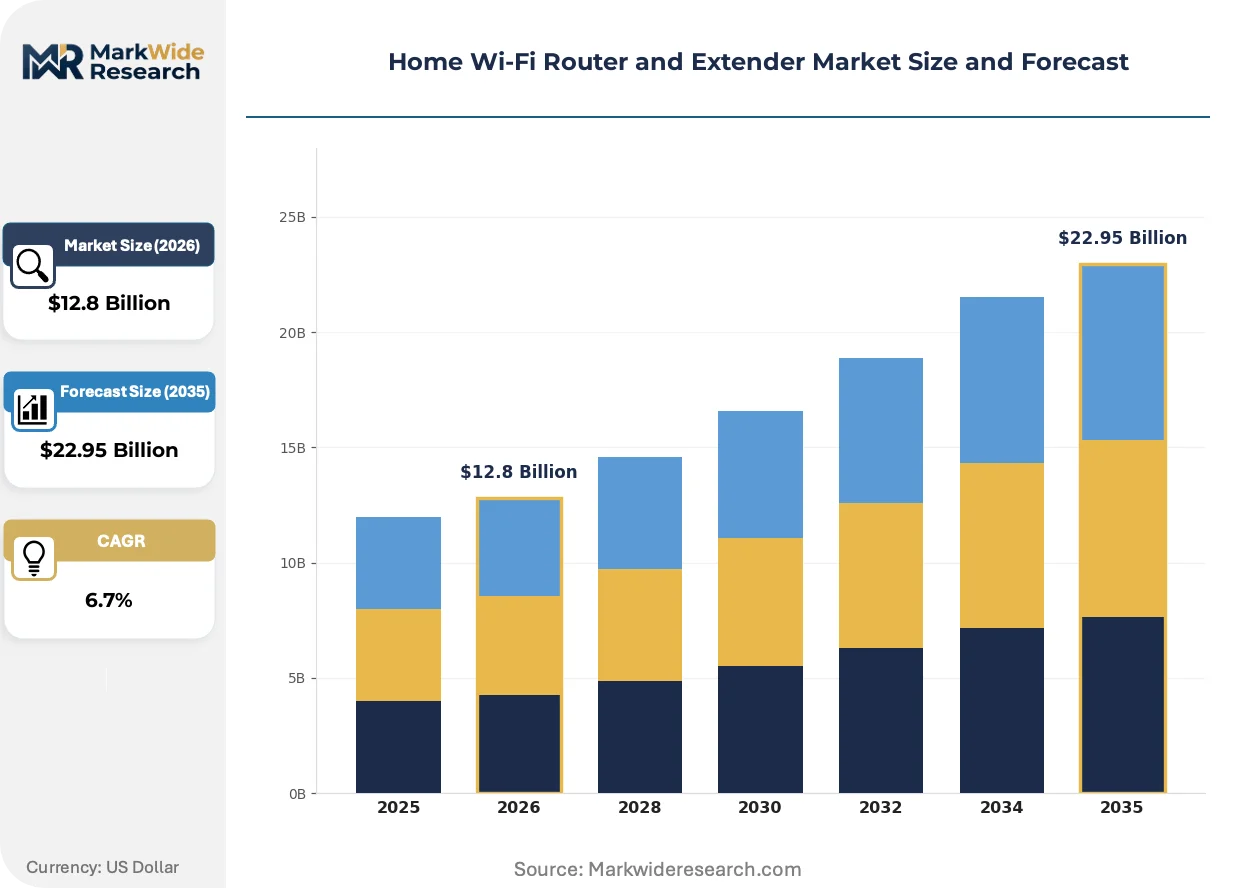
Home Wi-Fi Router and Extender Market Outlook
Multi-dwelling residential deployment is expanding as the dominant end-use vector for home Wi-Fi infrastructure. TP-Link leverages its manufacturing scale to dominate entry-level and mid-tier price bands across Asia-Pacific and European markets. Netgear sustains premium positioning through specialized mesh systems targeting bandwidth-intensive households. D-Link competes aggressively on channel control, maintaining broad retail distribution across North American and Latin American markets.
Home Wi-Fi routers and extenders are radio-frequency networking devices that distribute internet connectivity across residential and small-office environments, typically operating on 2.4 GHz and 5 GHz bands with newer Wi-Fi 6 models adding 6 GHz support. These devices employ beamforming and MU-MIMO technologies to direct signals toward connected endpoints, reducing interference in dense device environments. Dual Band and Tri Band product types capture the majority of current revenue as mature segments with established supply chains, while Wi-Fi 6 hardware represents the fastest-growing category as consumers replace aging 802.11ac equipment. Mesh Networking technology commands premium pricing and superior margins compared to traditional router-extender pairings, particularly among residential end users seeking seamless whole-home coverage.
The FCC governs spectrum allocation and device certification for Wi-Fi equipment in the United States, with recent 6 GHz band openings enabling Wi-Fi 6E product lines that manufacturers must validate for compliance. ETSI and national regulators across Germany, France, and Italy enforce harmonized radio equipment standards through CE marking requirements that shape product development timelines for vendors targeting European distribution. China's MIIT administers type approval and radio transmission standards that influence hardware designs for domestic and export markets. Stakeholders must monitor spectrum policy shifts and interoperability certification timelines as determinants of product roadmaps and geographic launch sequencing.
Market Dynamics
Wi-Fi 6E spectrum liberalization across the United States, United Kingdom, and South Korea is compressing hardware replacement cycles and forcing incumbent vendors to accelerate certification timelines for tri-band equipment.
Growth Catalysts
- Smart home device density:Residential IoT endpoints per household in China and Germany now exceed 15 units, saturating legacy 802.11ac capacity and forcing infrastructure upgrades.
- FCC 6 GHz allocation:The United States regulator opened 1200 MHz of contiguous spectrum, enabling 160 MHz channel bonding that reduces congestion in apartment-dense environments.
- Mesh protocol maturation:IEEE 802.11k/v/r standards adoption eliminates handoff latency, making multi-node systems viable for bandwidth-intensive households.
Market Restraints
- Semiconductor supply concentration:Wi-Fi 6E radio front-end modules depend on gallium arsenide foundries concentrated in Taiwan, exposing vendors to single-source risk.
- CE marking timeline variability:ETSI harmonized standards interpretation diverges between Germany and Italy, fragmenting European launch sequencing.
- Copper and substrate cost volatility:PCB laminate prices fluctuate with epoxy resin feedstock markets, compressing mid-tier hardware margins.
Strategic Opportunities
- Rural broadband subsidy programs:United States BEAD infrastructure grants prioritize last-mile connectivity, creating pull-through demand for CPE equipment in underserved counties.
- AI-driven RF optimization:Machine learning-based channel selection algorithms converge with cloud-managed platforms, enabling subscription revenue attachment to hardware sales.
- India smart city mandates:Municipal Wi-Fi deployments under the Digital India program require residential-grade extenders for public hotspot backhaul.
Industry Challenges
- Interoperability certification backlog:Wi-Fi Alliance 6E certification queue times extend to 14 weeks, delaying product launches past retail seasonal windows.
- Firmware security maintenance burden:CVE disclosure velocity for embedded Linux stacks forces vendors to sustain engineering resources for end-of-life hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Wi-Fi Router and Extender Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Band, Dual Band, Tri Band, Wi-Fi 6 Technology: Beamforming, MU-MIMO, Mesh Networking, WPA3 End User: Residential, Small Office, Large Office, Educational Institutions Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | D-Link, Zyxel, TP-Link, MikroTik, Tenda, Netgear, Asus, Ubiquiti, Linksys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Wi-Fi Router and Extender Market Strategic Shifts
Active antenna systems and cloud-native management platforms are rewriting how residential networks self-optimize, shifting value capture from hardware margins to recurring software revenue.
Wi-Fi 7 (802.11be) is rewriting performance expectations for residential networking. The standard introduces 320 MHz channel widths and 4K-QAM modulation, doubling theoretical throughput versus Wi-Fi 6E. Early chipset sampling from Qualcomm and MediaTek indicates 2025 availability for premium tier products. This is rewriting competitive positioning by forcing vendors to bifurcate roadmaps between cost-optimized Wi-Fi 6E volume plays and Wi-Fi 7 flagships.
Ofcom's 2023 decision to mirror FCC 6 GHz rules is rewriting European product planning. The United Kingdom regulator's framework enables full-power indoor and low-power outdoor operation, harmonizing with United States certification templates. Vendors targeting both markets now consolidate testing protocols, reducing duplicate engineering spend. Germany and France are expected to follow this template, compressing regional fragmentation.
Subscription-based network management is rewriting how consumers acquire Wi-Fi infrastructure. Eero, Netgear, and TP-Link now bundle advanced parental controls and security scanning into monthly fees. Retail channel partners capture recurring commissions, shifting their preference toward vendors with mature SaaS stacks. This pattern concentrates in the United States and United Kingdom, where credit-card-enabled app stores streamline billing.
Home Wi-Fi Router and Extender Market Segmentation
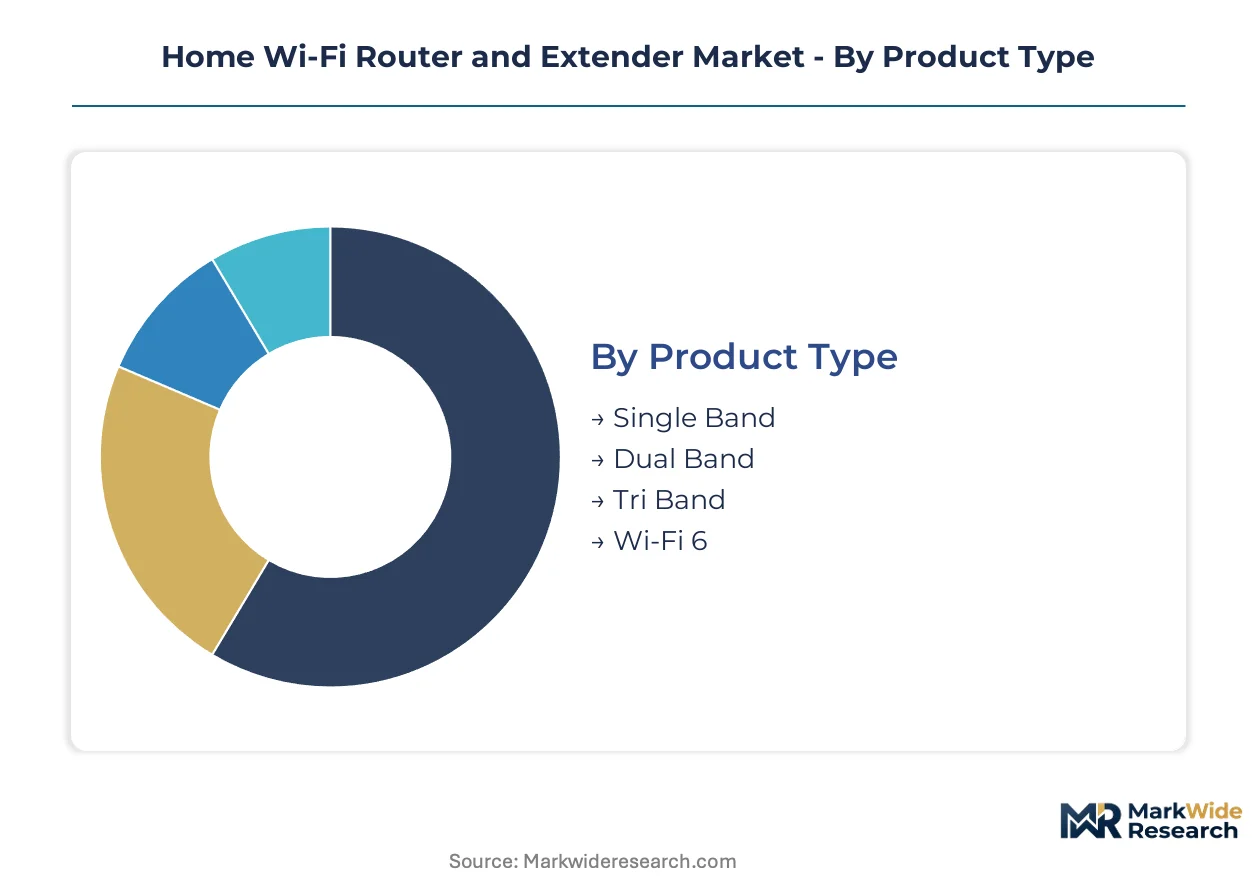
Wi-Fi hardware segmentation reveals how technical specifications, deployment environments, and procurement pathways fragment demand across radically different value profiles. Manufacturers must align R&D investment and channel strategy to the specific performance thresholds and purchasing behaviors governing each segment cluster.
Product Type:
Radio frequency architecture and spectrum utilization define the core hardware differentiation axis in residential networking equipment.
- Single Band:Legacy 2.4 GHz-only hardware persists in price-sensitive developing markets and IoT gateway applications where throughput requirements remain minimal. Demand concentrates in rural India and Southeast Asian provinces where fiber backhaul remains limited and cost constraints dominate procurement decisions.
- Dual Band:Simultaneous 2.4 GHz and 5 GHz operation captures the volume core of replacement cycles across suburban United States and European households. FCC 6 GHz liberalization is compressing the premium positioning of this segment as consumers migrate toward tri-band alternatives for congested environments.
- Tri Band:Dedicated backhaul channels eliminate throughput degradation in multi-node deployments, commanding premium pricing in bandwidth-intensive households with 500+ Mbps service tiers.
- Wi-Fi 6:OFDMA and 1024-QAM modulation deliver fourfold capacity improvement over 802.11ac predecessors, representing the steepest expansion trajectory as service providers mandate compatible CPE for gigabit service activation.
Dual Band leads on scale; Wi-Fi 6 leads on momentum.
Technology:
Signal optimization protocols and security standards determine competitive differentiation beyond raw throughput specifications.
- Beamforming:Phase-array antenna steering concentrates RF energy toward client devices rather than broadcasting omnidirectionally, extending effective range in multi-story residential layouts.
- MU-MIMO:Multi-user multiple-input multiple-output enables simultaneous downstream transmission to multiple clients, eliminating sequential queuing latency in device-dense households where endpoint counts exceed fifteen units.
- Mesh Networking:Self-organizing node topologies with IEEE 802.11k/v/r fast roaming eliminate dead zones in sprawling or architecturally complex homes, gaining share fastest among premium residential deployments seeking seamless whole-property coverage.
- WPA3:Simultaneous Authentication of Equals and forward secrecy protocols address KRACK vulnerability exposure in legacy WPA2 deployments, now mandatory for Wi-Fi Alliance certification and enterprise procurement compliance.
MU-MIMO dominates volume penetration; Mesh Networking commands margin expansion.
End User:
Deployment scale and performance tolerance create distinct hardware specification requirements across residential and commercial environments.
- Residential:Aesthetic form factors and mobile app management prioritize consumer usability over administrative granularity, with mesh systems capturing premium positioning in bandwidth-intensive households.
- Small Office:Guest network isolation and basic traffic prioritization satisfy ten-to-fifty endpoint environments without dedicated IT staffing, representing stable replacement demand tied to broadband service upgrades.
- Large Office:Centralized management platforms and captive portal authentication integrate with existing enterprise infrastructure, requiring vendor relationships with channel partners capable of post-deployment support.
- Educational Institutions:Density-optimized access points with schedule-based policy enforcement address thousand-plus student populations, with E-Rate funding eligibility shaping procurement vendor selection in United States public school districts.
Residential dominates unit volume; Educational Institutions drive specification complexity.
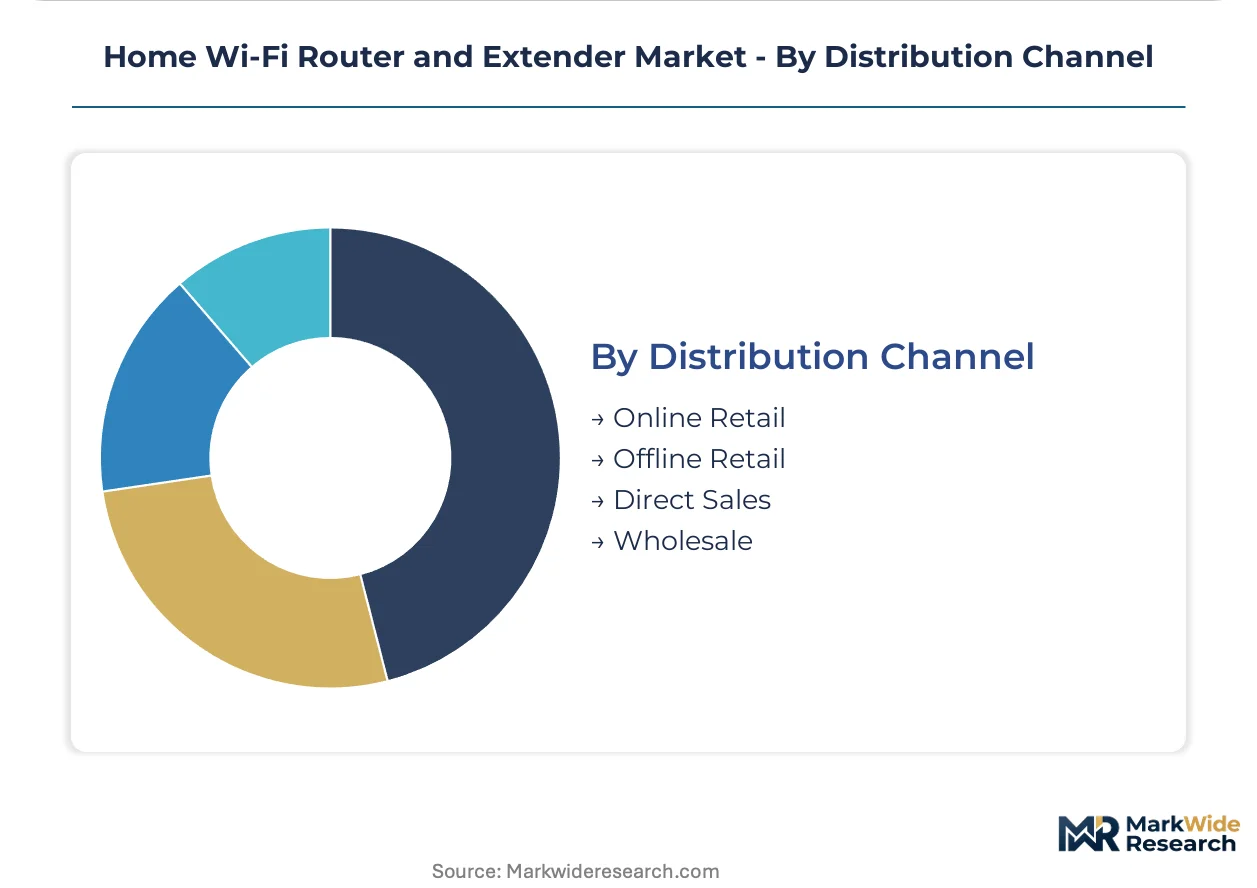
Distribution Channel:
Customer acquisition cost and service attachment potential vary dramatically across physical and digital procurement pathways.
- Online Retail:Algorithmic discovery and comparison shopping engines concentrate price competition, with subscription service attachment emerging as the primary margin recovery mechanism for vendors.
- Offline Retail:Big-box electronics and home improvement channels provide tactile evaluation and same-day availability, maintaining relevance for urgent replacement scenarios and less technically confident purchasers.
- Direct Sales:Manufacturer-controlled storefronts enable full margin capture and first-party data accumulation, though traffic acquisition costs challenge profitability without complementary service revenue.
- Wholesale:ISP and MSP bulk procurement agreements lock in multi-year CPE supply relationships, with technical integration requirements and volume commitments creating substantial vendor switching costs.
Online Retail leads on growth velocity; Wholesale anchors revenue predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as vendors relocate production to jurisdictions with streamlined certification pathways and lower compliance costs. The United States, China, Germany, United Kingdom, and India collectively concentrate both demand generation and hardware assembly capacity.
United States
FCC 6 GHz spectrum liberalization and BEAD rural broadband subsidies are accelerating CPE procurement across underserved counties. The regulator opened 1200 MHz of contiguous spectrum, enabling Wi-Fi 6E tri-band hardware deployment. Silicon Valley and Austin host cloud-managed networking startups that are commercializing AI-driven RF optimization platforms.
China
Apartment-dense urban environments in Shanghai and Shenzhen are driving mesh networking adoption at scale. MIIT type-approval standards influence hardware designs for both domestic consumption and export markets. Shenzhen's electronics manufacturing corridor anchors global production of Wi-Fi radio front-end modules and PCB assemblies.
Germany
Residential IoT endpoint density exceeding fifteen units per household is saturating legacy 802.11ac capacity and forcing infrastructure upgrades. ETSI harmonized standards and CE marking requirements shape product development timelines for vendors targeting European distribution. Munich and Stuttgart industrial clusters specialize in industrial-grade networking equipment with residential crossover applications.
United Kingdom
Ofcom's 2023 decision to mirror FCC 6 GHz rules is compressing regional certification fragmentation. The regulator's framework enables full-power indoor and low-power outdoor operation, harmonizing with United States testing protocols. London's fintech corridor generates concentrated demand for low-latency home office networking solutions.
India
Digital India smart city mandates and municipal Wi-Fi deployments require residential-grade extenders for public hotspot backhaul. TRAI broadband penetration targets are expanding addressable households beyond tier-one metros. Bangalore and Hyderabad technology corridors concentrate software development talent for cloud-managed networking platforms.
Home Wi-Fi Router and Extender Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors seek to defray certification costs and accelerate geographic expansion. The vendor base fragments across three tiers: scale-driven Asian manufacturers, premium-positioned specialized mesh providers, and channel-agnostic networking generalists. Two archetypes command attention: vertically integrated fabricators with captive semiconductor sourcing, and software-centric platforms monetizing subscription revenue attachment. M&A activity and technology licensing agreements represent the dominant competitive moves as firms consolidate testing capabilities and secure patent portfolios.
Among Asia-Pacific-based manufacturers, TP-Link and D-Link exemplify the scale-driven archetype, leveraging manufacturing concentration to dominate entry-level and mid-tier price bands. Netgear occupies a position within the premium-tier vector, representing specialized mesh system providers targeting bandwidth-intensive households. These three anchors illustrate how geographic origin and corporate structure correlate with strategic positioning across hardware-centric versus software-centric revenue models.
| Leading Market Players |
|---|
| D-Link |
| Zyxel |
| TP-Link |
| MikroTik |
| Tenda |
| Netgear |
| Asus |
| Ubiquiti |
| Linksys |
| Others |
Value Chain & Pricing Dynamics
Epoxy resin feedstock price volatility cascades through PCB laminate costs into tiered hardware margins, compressing mid-tier vendor profitability while premium mesh systems absorb input fluctuations through subscription revenue buffers. This cost transmission mechanism stratifies competitive positioning across manufacturing footprints and certification jurisdictions.
Pricing Analysis
Distributor margin layers absorb 15-25 point spreads between factory gate and retail shelf, with wholesale ISP procurement commanding steepest volume discounts. Three-tier pricing structure across premium, standard, and economy levels separates Wi-Fi 7 flagship hardware from Wi-Fi 6E volume plays from legacy 802.11ac clearance inventory. Cost compression in the standard tier is intensifying because gallium arsenide foundry concentration in Taiwan exposes vendors to single-source pricing power. Residential mesh adopters exhibit lowest price sensitivity; rural Indian single-band purchasers exhibit highest.
Supply Chain Analysis
Certification queue bottlenecks at Wi-Fi Alliance and FCC testing facilities gate downstream assembly ramp rates, forcing vendors to pre-position inventory ahead of seasonal retail windows. Manufacturing concentrates in China, Taiwan, and Vietnam, with Shenzhen anchoring radio front-end module fabrication and PCB assembly. Supply chains draw from gallium arsenide semiconductors, epoxy resin laminates, and passive RF components. Single-source vulnerability in Taiwan-based foundries threatens tri-band chipset availability. Distribution runs through wholesale ISP procurement, online retail algorithms, and big-box electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FCC certification timelines in the United States lag MIIT approval velocities in China by eight to twelve weeks, creating launch-window advantages for Shenzhen-based vendors with dual-jurisdiction testing protocols.
For Market Incumbents: Cement manufacturing scale advantages through captive gallium arsenide sourcing partnerships that insulate against Taiwan foundry concentration risk. Deepen backward integration into PCB laminate production to offset epoxy resin feedstock volatility. Prioritize Wi-Fi 7 certification investment ahead of retail seasonal windows to defend against cloud-native networking startups threatening subscription revenue attachment.
For New Entrants and Emerging Players: Enter via municipal Wi-Fi backhaul contracts under India's Digital India program, where residential-grade extender specifications face limited incumbent saturation. Target underserved rural United States counties prioritized by BEAD infrastructure grants, leveraging cloud-managed platforms to bypass hardware margin competition. Pursue white-label ISP procurement relationships as the most penetrable channel.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated fabricators possessing captive semiconductor sourcing and established SaaS revenue stacks. Long-term viability over the next decade favors vendors with dual Wi-Fi 6E and Wi-Fi 7 roadmap execution capability. Acquisition targets should demonstrate harmonized FCC-CE-MIIT certification templates. Monitor Wi-Fi Alliance 6E queue compression as the signal indicating margin recovery inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Wi-Fi 7 Chipset Sampling Acceleration | Qualcomm and MediaTek early releases force vendor roadmap bifurcation between premium and volume tiers. |
| Cloud-Native Management Platform Launch | Subscription revenue attachment shifts channel partner preference toward SaaS-capable vendors. |
| Dual-Jurisdiction Certification Investment | Harmonized FCC-Ofcom testing protocols reduce duplicate engineering spend for transatlantic launches. |
| AI-Driven RF Optimization Integration | Machine learning channel selection algorithms enable recurring revenue models beyond hardware margins. |
| Rural Broadband CPE Supply Agreement | BEAD grant prioritization in underserved United States counties creates multi-year procurement pull-through. |
Study Parameters
Multiple input streams — structured interviews with networking hardware procurement managers, primary fieldwork with ISP technical integration teams, and secondary validation through FCC equipment authorization databases and Wi-Fi Alliance certification disclosures — were reconciled to construct segment-level demand estimates. Industry stakeholders included router OEM product managers, retail category buyers, semiconductor foundry planning officers, and municipal broadband procurement directors. Secondary sources encompassed customs trade data, ETSI harmonized standards filings, and hyperscaler capex disclosures. Bottom-up unit shipment modeling and top-down service provider CPE procurement triangulation anchored value projections.
Historical shipment trajectories were cross-referenced against panel input from distribution channel partners to calibrate adoption curve assumptions across the projection horizon. Segmentation dimensions modeled included radio frequency architecture, deployment environment, and procurement pathway. CAGRs were derived from slope analysis of replacement cycle compression rates and spectrum liberalization timing. Industry-specific forecast inputs incorporated Wi-Fi 6E certification queue durations and gallium arsenide foundry utilization rates.
Inputs from Wi-Fi Alliance certification databases and ISP procurement contract registries were available through the study window; gaps in real-time foundry capacity utilization data introduce uncertainty bands around chipset availability assumptions. Forecasts reflect documented assumptions regarding regulatory sequencing and replacement cycle elasticity. A model refresh is warranted upon material change in FCC or ETSI spectrum allocation rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
RTP Market
Network Technology
DNS DHCP and IPAM Market
Network Technology
UK B2B Fixed Connectivity Market
Network Technology
Global Deep Packet Inspection and Processing Market
Network Technology
Gigabit Passive Optical Network (GPON) Market
Network Technology
Network Telemetry Market
Network Technology
Structured Cabling Market
Network Technology
Global Network Switches Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Virtual Router Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
Router and Switch Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Gigabit Ethernet Market