
 Neonatal Intensive Care Market | 2026-2036
Neonatal Intensive Care Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal Intensive Care Market Intelligence
The mix of end-use settings is hardening toward pediatric hospitals and dedicated neonatal units as specialty clinics face reimbursement compression. Drägerwerk AG anchors its position through manufacturing scale in incubators and ventilator platforms. Masimo Corporation differentiates via pulse oximetry and noninvasive monitoring technology leadership. Philips Healthcare extends its footprint through integrated NICU workflow systems that span monitoring, diagnostics, and informatics.
Neonatal intensive care encompasses specialized medical interventions, equipment, and monitoring systems designed to sustain premature and critically ill newborns requiring controlled thermal environments, respiratory assistance, and continuous physiological surveillance; these systems typically operate within temperature ranges of 36.0°C to 37.5°C and integrate multi-parameter monitoring for heart rate, oxygen saturation, and blood pressure. The primary purpose centers on reducing neonatal mortality and long-term morbidity through early stabilization and organ-supportive therapy. Ventilators and monitoring devices command the deepest margin pools as hospitals prioritize noninvasive respiratory modalities and continuous data integration. Incubators and infant warmers represent mature categories with replacement-driven demand cycles. Cloud-based deployment models within NICU informatics are gaining traction as health systems seek centralized telemetry across distributed birth centers.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for manufacturers seeking market access in the United States and Europe. ISO 13485 quality management standards and IEC 60601-1 electrical safety specifications further constrain design choices and supplier qualification processes. Stakeholders must monitor how CMS reimbursement adjustments for neonatal critical care and emerging state-level maternal health initiatives redirect capital allocation across facility types and equipment categories.
Market Dynamics
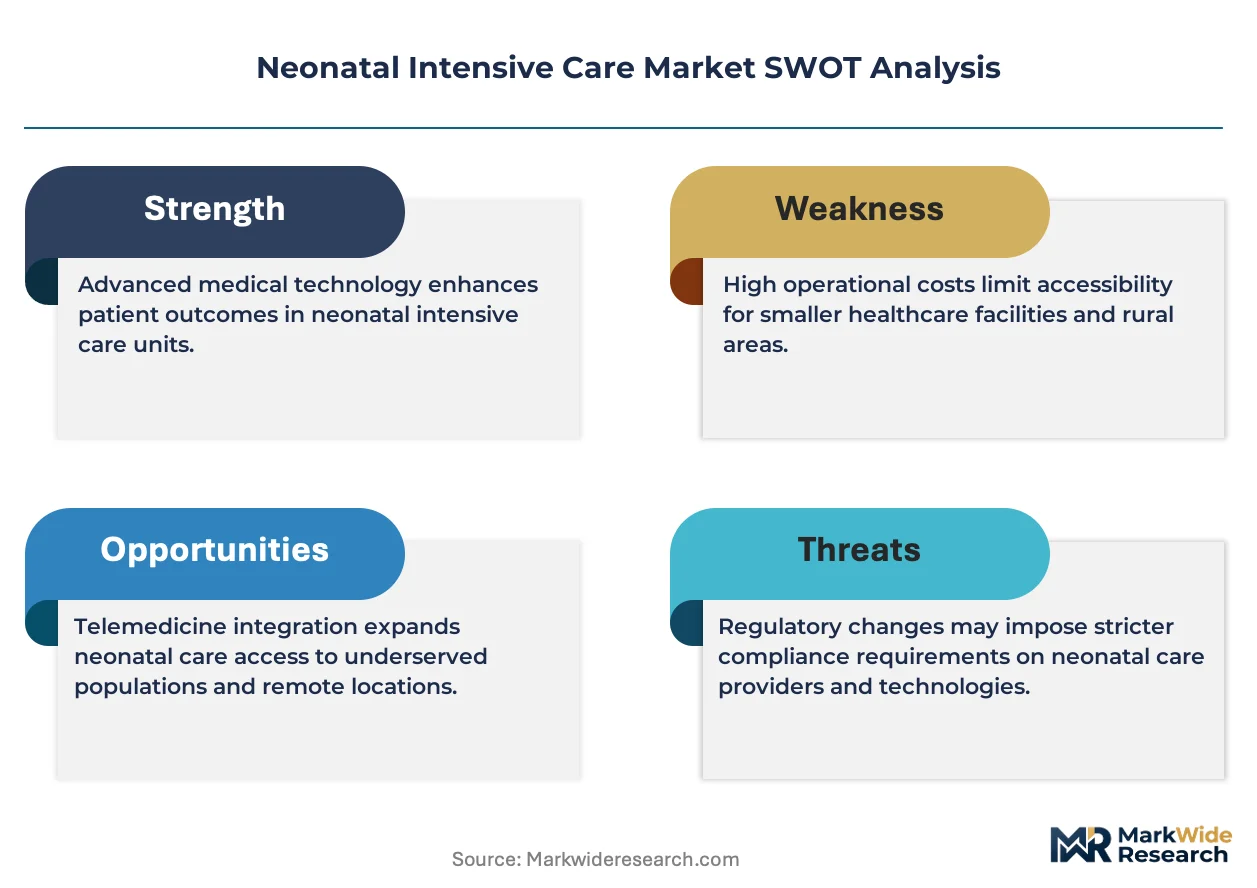
Consolidation of neonatal services into regional centers of excellence is compressing equipment procurement cycles and favoring vendors with integrated platform capabilities over point-product suppliers.
Growth Catalysts
- CMS reimbursement adjustments:Federal payment incentives for Level IV NICU designation are accelerating capital investment in high-acuity infrastructure across US tertiary care networks.
- Noninvasive respiratory modalities:Clinical preference for nasal CPAP and high-flow nasal cannula is expanding the addressable market for hybrid ventilator platforms in pediatric hospitals.
- Cloud-based telemetry:Centralized monitoring architectures are enabling multi-site NICU networks to pool specialist resources across distributed birth centers.
Market Restraints
- EU Medical Device Regulation compliance costs:Clinical evidence requirements for Class III respiratory devices are extending time-to-market by 18-24 months for European submissions.
- Semiconductor supply concentration:Dependency on East Asian foundries for pulse oximetry sensors and ventilator control modules creates procurement vulnerability.
- Specialized neonatal workforce scarcity:Limited availability of neonatologists and NICU-trained respiratory therapists constrains bed expansion regardless of equipment availability.
Strategic Opportunities
- AI-integrated alarm management:Machine learning algorithms that reduce false-positive alarms are creating differentiation in monitoring platforms for sleep-deprived clinical staff.
- Modular incubator architectures:Upgradeable thermal platforms allow mid-tier hospitals to phase advanced capabilities without full replacement cycles.
- State maternal health initiatives:California and Illinois programs targeting infant mortality reduction are directing dedicated funding streams toward NICU infrastructure modernization.
Industry Challenges
- IEC 60601-1 third edition testing:Electrical safety certification for networked devices requires extensive electromagnetic compatibility validation that delays product launches.
- Legacy EMR integration:Proprietary data formats from incumbent monitoring vendors create interoperability friction with emerging cloud-native informatics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal Intensive Care Market |
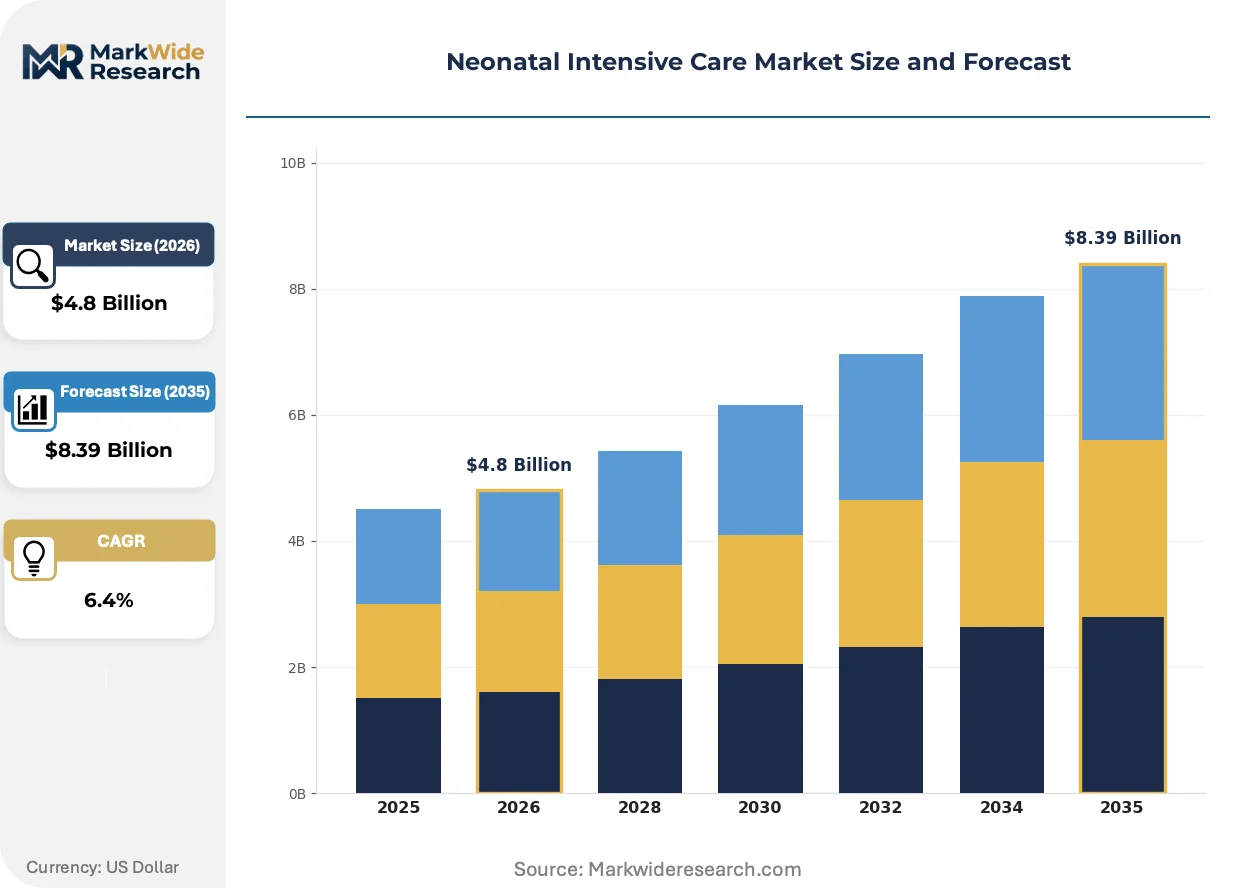
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incubators, Ventilators, Phototherapy Equipment, Infant Warmers, Monitoring Devices Therapy Area: Respiratory Support, Thermal Regulation, Infection Control, Neurodevelopmental Care End User: Specialty Clinics, Neonatal Units, Pediatric Hospitals, Skilled Nursing Facilities Deployment Model: On-Premises, Managed Services, Cloud-Based Systems, Mobile Solutions |
| Companies Covered | Drägerwerk AG, Masimo Corporation, Medtronic, Becton Dickinson and Company, Fisher & Paykel Healthcare, GE Healthcare, Siemens Healthineers, ICU Medical, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal Intensive Care Market Strategic Shifts & Innovations
Neonatal intensive care equipment is undergoing platform unification as hospitals seek to reduce vendor fragmentation and standardize clinical workflows across monitoring, respiratory, and thermal support domains.
Noninvasive respiratory support technology is consolidating multiple ventilation modes into single-platform architectures. Pediatric hospitals are replacing standalone CPAP devices with hybrid systems capable of escalating from nasal cannula to invasive ventilation without patient transfer. This capability compression is eliminating intermediate equipment tiers and concentrating procurement decisions on vendors with full-spectrum respiratory platforms.
EU Medical Device Regulation post-market surveillance requirements are mandating systematic clinical follow-up for implantable and life-supporting devices. Manufacturers must now maintain active registries for ventilator and incubator performance data across European installations. German and French notified bodies are enforcing this through unannounced factory audits, with respiratory support device manufacturers experiencing the most intensive documentation scrutiny.
Hospital procurement committees are consolidating vendor relationships through enterprise-wide equipment standardization contracts. Multi-hospital health systems are negotiating sole-source agreements for NICU platforms that bundle monitoring, ventilation, and informatics under unified service terms. This concentration pattern is most pronounced in the United States, where Catholic health systems and academic medical centers are leveraging scale to extract performance guarantees and dedicated clinical engineering support.
Neonatal Intensive Care Market Segmentation
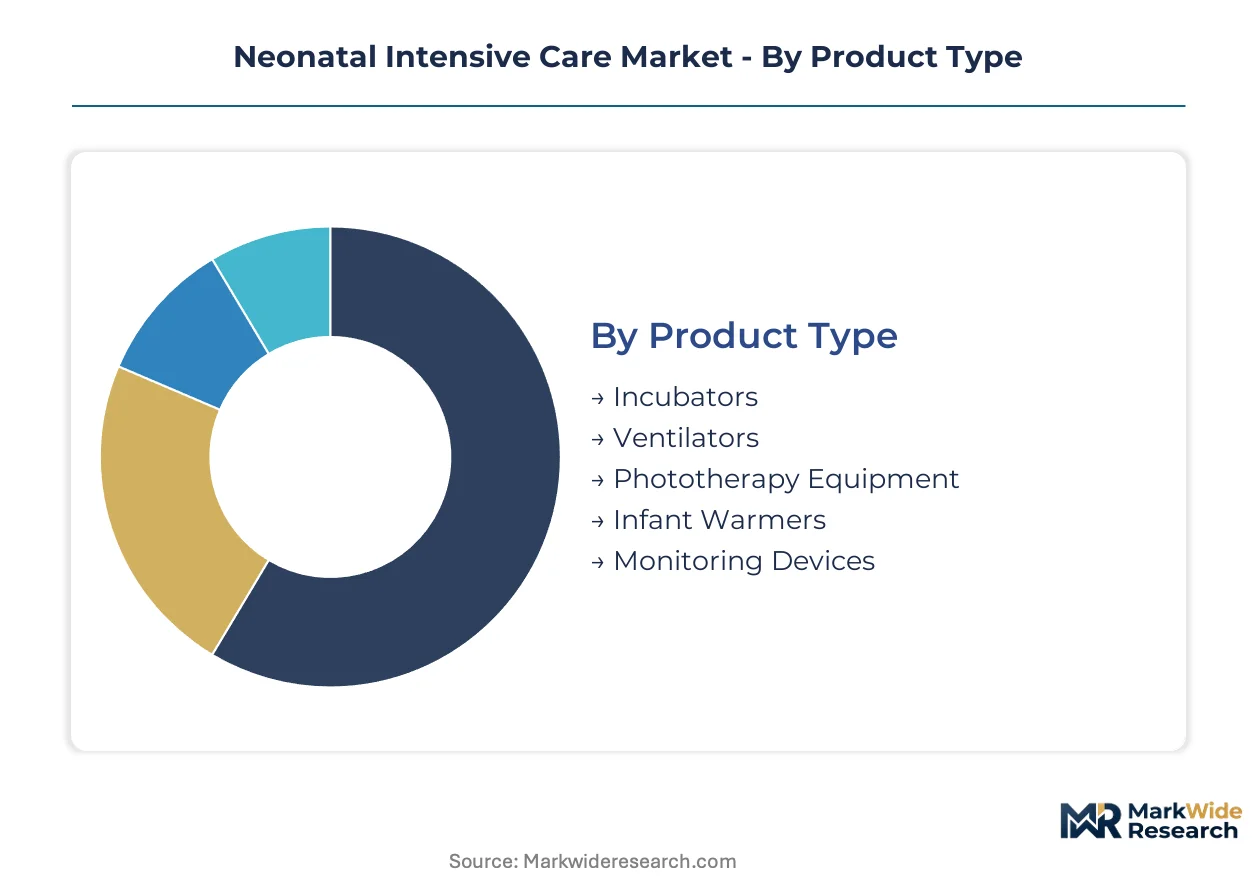
Equipment procurement patterns in neonatal intensive care diverge sharply by care setting acuity and reimbursement tier. Understanding these segment boundaries clarifies why vendor consolidation strategies succeed or fail across different hospital types.
Product Type:
Ventilator and monitoring device manufacturing concentrates among German and US suppliers with integrated respiratory platforms, while incubator production fragments across mid-tier Asian and European specialists lacking full NICU portfolios.
- Ventilators:Hybrid platforms now integrate nasal CPAP, high-flow cannula, and invasive ventilation modes within single hardware architectures. Demand clusters in US academic medical centers pursuing Level IV NICU designation where CMS reimbursement premiums justify capital-intensive equipment upgrades. FDA 510(k) clearance timelines and EU MDR clinical evidence requirements favor incumbent manufacturers with established regulatory infrastructure over emerging competitors.
- Monitoring Devices:Multi-parameter systems track heart rate, oxygen saturation, blood pressure, and respiratory rate through centralized telemetry architectures. Pediatric hospitals in tertiary care networks prioritize platforms with cloud-native data integration and AI-integrated alarm management to address specialist workforce scarcity across distributed birth centers.
- Incubators:Thermal regulation platforms with servo-controlled humidity and oxygen delivery represent mature replacement-driven demand.
- Infant Warmers:Radiant heat devices for delivery room stabilization and intermediate care settings serve lower-acuity neonatal units.
- Phototherapy Equipment:LED-based bilirubin reduction systems address jaundice management in newborn populations.
Today's leader: Ventilators. Tomorrow's challenger: Monitoring Devices.
Therapy Area:
Cost tier stratification separates high-margin respiratory interventions from commoditized thermal support, with infection control and neurodevelopmental care occupying intermediate positions where clinical evidence requirements determine pricing power.
- Respiratory Support:Noninvasive ventilation modalities dominate clinical practice, with nasal CPAP and high-flow nasal cannula reducing intubation rates in premature infants. US tertiary care networks and European pediatric hospitals drive procurement concentration as regional centers of excellence consolidate high-acuity cases.
- Thermal Regulation:Incubator and warmer technologies maintain core body temperature in premature neonates with limited brown adipose tissue reserves.
- Infection Control:Hand hygiene systems, isolation protocols, and antimicrobial surface technologies address nosocomial transmission risks in NICU environments.
- Neurodevelopmental Care:Light reduction, noise control, and positioning interventions support brain development in extremely preterm infants.
Respiratory Support commands premium pricing through technology differentiation. Thermal Regulation faces margin compression from replacement-cycle commoditization.
End User:
Customer type determines procurement sophistication, with pediatric hospitals leveraging enterprise-scale standardization contracts while specialty clinics confront reimbursement constraints limiting capital access.
- Pediatric Hospitals:Tertiary and quaternary care institutions with dedicated NICU infrastructure pursue integrated platform standardization across monitoring, respiratory, and thermal domains. US Catholic health systems and academic medical centers negotiate sole-source agreements bundling equipment, service, and clinical engineering support under multi-year contracts.
- Neonatal Units:Hospital-based specialized departments within general acute care facilities manage moderate-acuity cases.
- Specialty Clinics:Independent outpatient facilities face reimbursement compression from CMS and private payers limiting equipment investment capacity.
- Skilled Nursing Facilities:Post-acute settings provide transitional care for technology-dependent infants awaiting home discharge.
Pediatric Hospitals extract maximum vendor concessions through scale. Neonatal Units represent the volume expansion opportunity as regional consolidation proceeds.
Deployment Model:
Technology maturity separates established on-premises installations from emerging cloud architectures, with managed services occupying a transitional position where hospitals outsource infrastructure complexity without surrendering clinical control.
- Cloud-Based Systems:Centralized telemetry platforms enable multi-site NICU networks to pool specialist monitoring resources across distributed birth centers. US health systems in California and Illinois deploy these architectures to support state maternal health initiatives targeting infant mortality reduction through remote specialist access.
- On-Premises:Traditional localized equipment installations maintain data sovereignty within hospital firewall boundaries.
- Managed Services:Outsourced equipment maintenance and clinical engineering support reduce internal technical staffing requirements.
- Mobile Solutions:Transport incubators and portable monitoring devices enable intrahospital and interfacility patient movement.
Cloud-Based Systems are climbing the fastest as health systems prioritize centralized resource pooling. On-Premises retains dominance in security-sensitive installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston medical technology corridor anchors neonatal intensive care equipment development, with Massachusetts General Brigham and Boston Children's Hospital driving clinical validation protocols for respiratory platforms and integrated monitoring systems.
United States
CMS reimbursement premiums for Level IV NICU designation accelerate capital investment across tertiary care networks. FDA 510(k) clearance pathways and premarket notification requirements shape product development timelines for respiratory support devices. The Texas Medical Center in Houston consolidates high-acuity neonatal services, creating procurement concentration for hybrid ventilator platforms.
Germany
EU Medical Device Regulation compliance costs extend time-to-market for Class III respiratory devices by 18-24 months. German notified bodies enforce post-market surveillance requirements through unannounced factory audits. The Baden-Württemberg industrial cluster around Tübingen and Stuttgart hosts incubator manufacturing operations with established regulatory infrastructure.
United Kingdom
NHS England's maternal health initiatives direct funding toward regional neonatal networks and centralized telemetry architectures. MHRA alignment with EU MDR standards maintains stringent clinical evidence requirements for life-supporting devices. London's academic medical centers pursue enterprise-wide equipment standardization contracts bundling monitoring and respiratory platforms.
Japan
PMDA approval processes for medical devices emphasize electrical safety certification under IEC 60601-1 standards. METI industrial policy supports domestic manufacturing of pulse oximetry sensors and ventilator control modules. The Kansai region around Osaka maintains specialized production capacity for thermal regulation equipment.
India
CDSCO medical device regulations are tightening product standards for imported respiratory support equipment while expanding domestic manufacturing incentives. State-level maternal health programs in Maharashtra and Karnataka target infant mortality reduction through NICU infrastructure modernization. The Delhi-NCR corridor attracts investment in cost-optimized monitoring device assembly.
Neonatal Intensive Care Market Key Industry Players
Enterprise-wide equipment standardization dominates the current landscape as multi-hospital health systems negotiate sole-source agreements. The vendor base concentrates among integrated platform suppliers with full-spectrum respiratory, monitoring, and thermal portfolios. Two strategic archetypes define competitive positioning: German and US manufacturers with established regulatory infrastructure, and diversified health technology conglomerates with informatics integration capabilities. Portfolio diversification and strategic partnerships represent the dominant competitive moves as point-product suppliers face procurement exclusion.
Within the integrated platform tier, Drägerwerk AG and Masimo Corporation exemplify contrasting specialization models. Drägerwerk AG anchors German manufacturing scale in respiratory and thermal support domains. Masimo Corporation occupies a position defined by pulse oximetry and noninvasive monitoring technology leadership. Philips Healthcare sits within the diversified health technology archetype, extending competitive presence through workflow system integration across the NICU environment.
| Leading Market Players |
|---|
| Drägerwerk AG |
| Masimo Corporation |
| Medtronic |
| Becton Dickinson and Company |
| Fisher & Paykel Healthcare |
| GE Healthcare |
| Siemens Healthineers |
| ICU Medical |
| Philips Healthcare |
| Others |
Cost & Logistics Intelligence
Pulse oximetry sensors sourced from East Asian foundries feed through distributor markups of 15-25% before reaching US pediatric hospitals, with FDA-cleared Class III respiratory devices commanding premium positioning against CE-marked alternatives in European procurement cycles.
Pricing Analysis
Distributor margins on ventilator platforms compress 3-5 percentage points when manufacturers sell direct to multi-hospital health systems under enterprise standardization contracts. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform vendors from point-product specialists, with AI-integrated alarm management modules attracting 20-30% uplifts over basic telemetry configurations. Cost compression in incubator categories intensifies because Asian manufacturers compete on replacement-cycle pricing against established German suppliers. Specialty clinics exhibit highest price sensitivity due to CMS reimbursement compression, while Level IV NICU designation seekers absorb premium equipment costs through federal payment incentives.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Catholic health systems and academic medical centers negotiating sole-source agreements. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan for pulse oximetry sensors and ventilator control modules. Control systems draw from German industrial automation clusters and US medical electronics specialists. Single-source vulnerability in East Asian foundry capacity creates procurement exposure for manufacturers dependent on just-in-time component delivery. Distribution runs through authorized medical device distributors with clinical engineering service capabilities in major metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Neonatal Intensive Care Market functions as a stable compounder anchored by irreversible clinical demand for respiratory and thermal support in premature infant populations.
For Market Incumbents: To counter point-product supplier exclusion from enterprise standardization contracts, Drägerwerk AG and Philips Healthcare should deepen backward integration into pulse oximetry sensor production to reduce East Asian foundry dependency. Capacity addition in Baden-Württemberg manufacturing clusters would shorten EU MDR compliance timelines for Class III respiratory devices. Certification investment in IEC 60601-1 third edition testing infrastructure accelerates product launch velocity against regulatory bottlenecks. For New Entrants and Emerging Players: Enter via modular incubator architectures targeting mid-tier US hospitals phasing advanced capabilities without full replacement cycles. State maternal health initiatives in California and Illinois present the most penetrable funding streams for cloud-based telemetry platforms. Hospital system partnership with GPO contracts managers unlocks procurement committee access faster than direct clinical selling. For Investors and Strategic Acquirers: Consolidation pressure builds where vendor fragmentation across monitoring, respiratory, and thermal domains frustrates health system procurement committees seeking platform unification. Long-term viability favors diversified health technology conglomerates with informatics integration capabilities over pure-play equipment manufacturers. Acquisition target archetype: pulse oximetry specialists with FDA 510(k) clearance infrastructure and cloud-native data architectures. Signal to watch: unannounced factory audits by German and French notified bodies indicating EU MDR enforcement intensity against respiratory support device manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market access for hybrid ventilator platforms in US tertiary care networks. |
| EU MDR Compliance Investment | Extends time-to-market for Class III devices but creates regulatory moats against emerging competitors. |
| Hospital System Partnership | Locks in multi-year sole-source agreements bundling equipment, service, and clinical engineering support. |
| Cloud-Native Telemetry Development | Enables centralized specialist resource pooling across distributed birth centers in California and Illinois. |
| AI-Integrated Alarm Management | Reduces false-positive rates for sleep-deprived NICU staff, creating platform differentiation. |
Research Approach
Bottom-up pediatric hospital procurement modeling reconciled against top-down respiratory device manufacturing tracking forms the analytical core. Primary interviews with neonatologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EU MDR submission databases, CMS Medicare reimbursement data, and hospital procurement registries. Triangulation between demand-side capital expenditure patterns and supply-side production capacity estimates validates volume assumptions.
Input-output matrices map equipment procurement by acuity tier, deployment model, and regional regulatory cluster across the projection horizon. Segmentation dimensions include product type, therapy area, end-user setting, and deployment architecture. CAGRs derive from weighted average of historical replacement cycles, CMS reimbursement trajectory, and state maternal health initiative funding flows. Industry-specific forecast inputs incorporate neonatologist workforce scarcity constraints and EU MDR post-market surveillance compliance timelines.
The model holds under stable CMS reimbursement premiums for Level IV NICU designation; deviation in federal payment policy or EU MDR enforcement intensity would shift capital allocation timing across equipment categories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Neonatal and Infant Care Equipment Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Treatment Market
Neonatal Care
Perinatal Software Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Infant Care Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Preterm Birth Prevention and Management Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Umbilical Market