
 Perinatal Software Market | 2026-2036
Perinatal Software Market Size, Share, and Industry Trends Forecast 2026-2036
Perinatal Software Market Intelligence
A shift in purchasing power from individual obstetrician practices toward large, consolidated maternity clinics is reorganizing the competitive landscape for perinatal software. GE HealthCare leverages its extensive installed base in hospitals to cross-sell software suites. PeriGen, Inc. differentiates through its specialization in AI-driven clinical decision support for labor and delivery. Koninklijke Philips N.V. competes with integrated fetal and maternal monitoring hardware and software platforms.
Perinatal software encompasses IT systems for managing clinical data and workflows throughout the pregnancy and postpartum periods. These platforms integrate real-time fetal monitoring data, such as heart rate variability, and must support EHR interoperability via standards like HL7. Cloud-based deployment models are displacing on-premises installations due to superior scalability. Within applications, modules for high-risk pregnancy risk assessment represent a significant value pool.
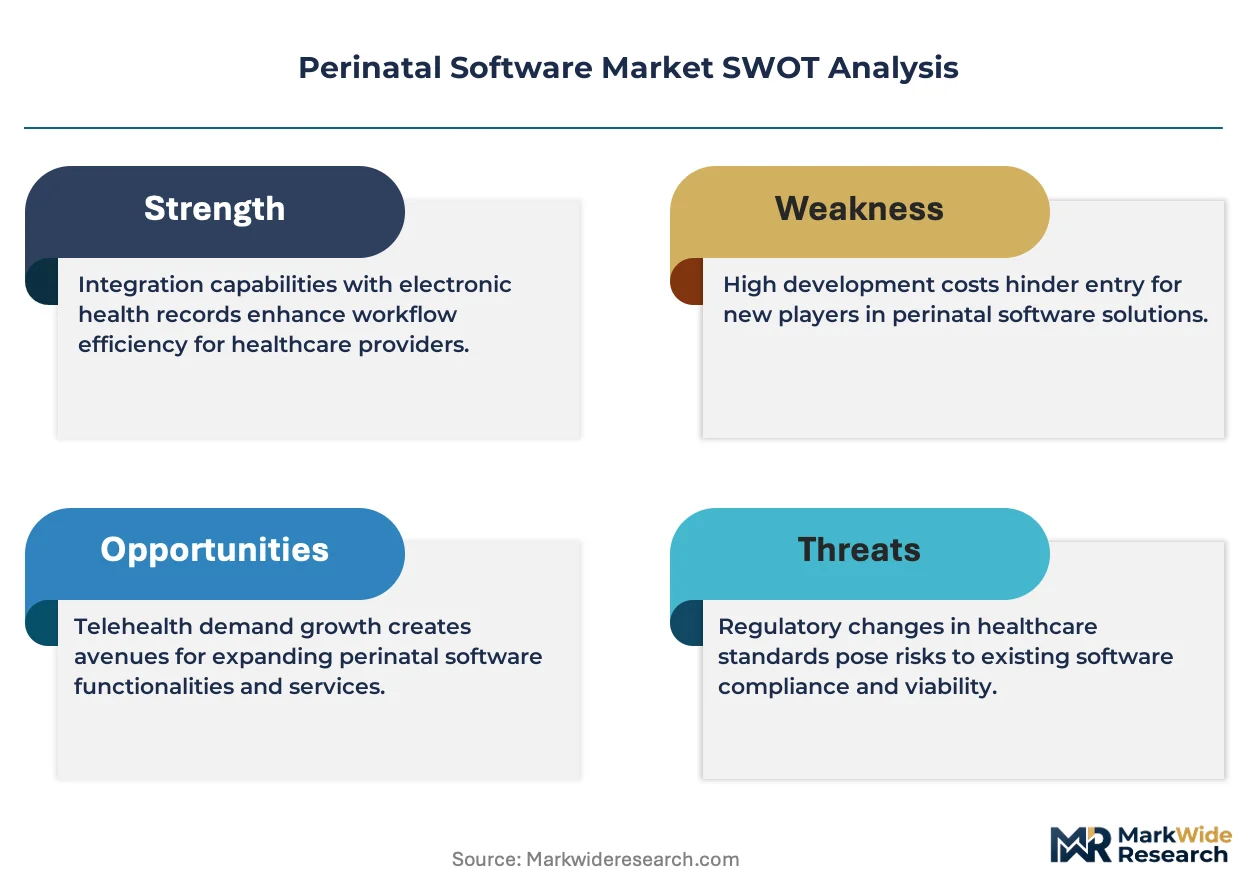
Data security and patient privacy mandates, including HIPAA in the United States and GDPR in Europe, govern software design and data handling protocols. Software classified as a medical device also requires adherence to frameworks like the EU's MDR or FDA clearance in the US. Vendors face a strategic choice between developing advanced, standalone clinical decision support tools or building broader, more integrated EHR-compatible platforms.
Market Dynamics
The consolidation of healthcare providers into large, integrated maternity clinic networks is the central structural force shaping the perinatal software market. This shift moves purchasing power away from individual practices, favoring vendors who can deliver scalable, interoperable enterprise-level solutions.
Growth Catalysts
- Value-Based Care Initiatives:Government and private payer programs rewarding improved maternal-fetal outcomes are driving investment in software for high-risk pregnancy identification and management, particularly in the United States healthcare system.
- AI in Clinical Decision Support:The integration of artificial intelligence and machine learning into software for analyzing real-time fetal heart rate patterns enables earlier detection of distress, creating significant clinical value for labor and delivery units.
- Workflow Efficiency Demand:Large-scale maternity clinics require integrated software suites to standardize care protocols, automate documentation, and manage high patient volumes efficiently, reducing administrative burden on clinical staff.
Market Restraints
- High Total Cost of Ownership:The significant upfront investment for software licenses, coupled with costs for implementation, staff training, and ongoing maintenance, presents a substantial barrier for smaller, independent obstetrics practices and clinics.
- Legacy System Interoperability:Achieving seamless data exchange between new perinatal software and existing, often fragmented, hospital electronic health record (EHR) systems remains a major technical and financial hurdle despite standards like HL7.
- Stringent Regulatory Clearance:Software classified as a medical device, especially clinical decision support tools, must undergo lengthy and expensive approval processes with bodies like the FDA or secure CE marking under the EU's MDR.
Strategic Opportunities
- Postpartum Care Modules:Expanding software capabilities to include postpartum mental health screening, remote lactation consulting, and infant monitoring addresses a critical, underserved phase of the perinatal care continuum.
- Wearable Device Integration:Converging perinatal platforms with consumer and medical-grade wearables for remote monitoring of maternal vital signs and fetal movement offers a new frontier for proactive, continuous care outside the clinic. *Emerging Market Upgrades: Healthcare systems in certain Asia-Pacific and Latin American countries are modernizing their clinical IT infrastructure, creating white-space opportunities for vendors offering cloud-based, scalable perinatal solutions.
Industry Challenges
- Cybersecurity and Data Privacy:Ensuring robust protection of sensitive patient data against sophisticated cyber threats requires continuous investment in security infrastructure and strict adherence to evolving regulations like GDPR and HIPAA.
- Complex System Integration:Implementing and integrating comprehensive perinatal software into a hospital's diverse IT environment is a complex project that demands specialized expertise and significant resource allocation from the provider.
- Clinical Informatics Talent Gap:A shortage of professionals with dual expertise in obstetrics and health information technology creates bottlenecks during software implementation, customization, and user training phases within healthcare organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perinatal Software Market |
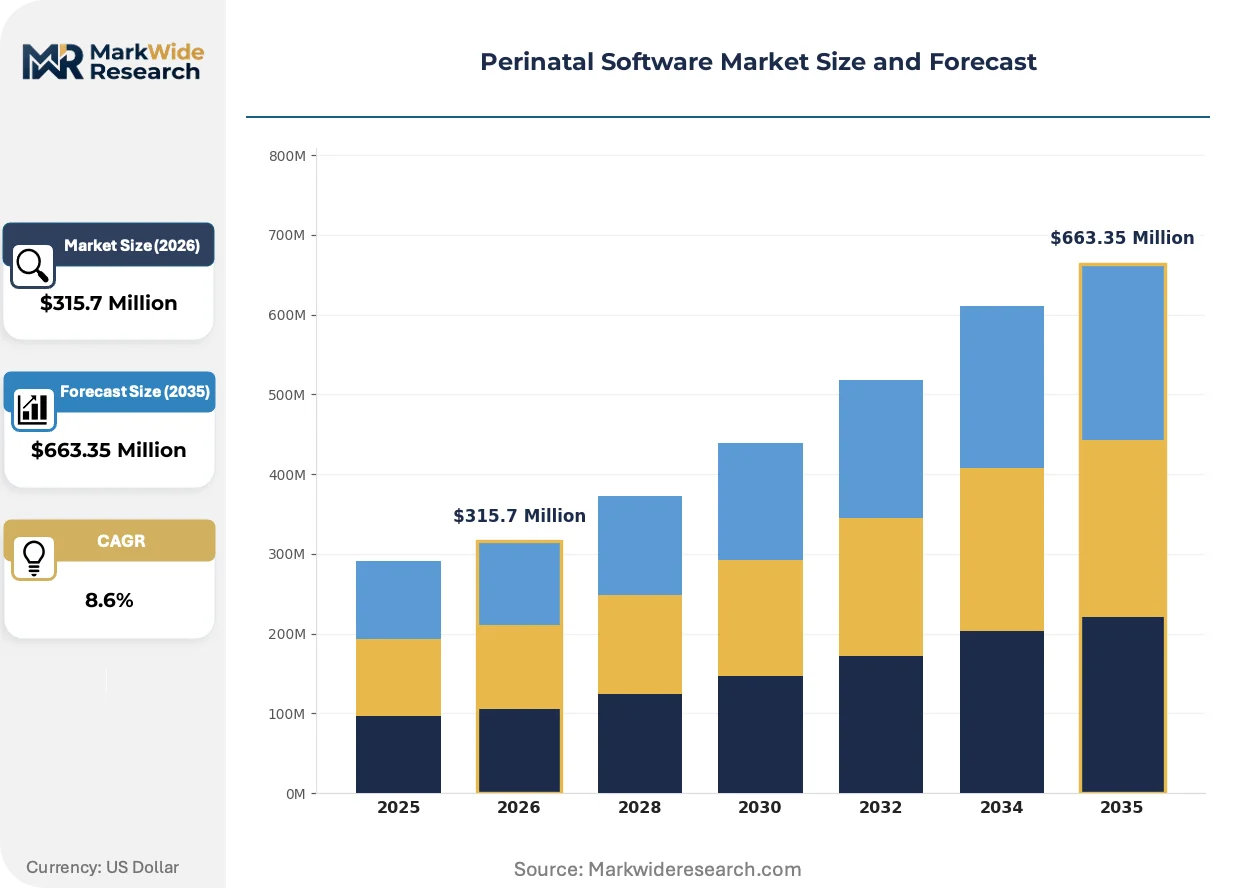
| Market Size in 2026 | $315.7 Million |
| Market Size in 2035 | $663.35 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Decision Support, Patient Monitoring, Data Management, Electronic Health Records Application: Risk Assessment, Prenatal Care Planning, Postnatal Follow-up, Birth Outcome Analysis End User: Maternity Clinics, Obstetricians, Midwifery Practices, Neonatal Units Deployment: Cloud-Based, On-Premises, Hybrid, Web-Based |
| Companies Covered | PeriGen, Inc., Koninklijke Philips N.V., GE HealthCare, Clinical Computer Systems, Inc., Trium Analysis Online GmbH, EDAN Instruments, Inc., K2 Medical Systems Ltd., Huntleigh Healthcare Limited, Cerner Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perinatal Software Market Strategic Shifts & Innovations
The evolution of perinatal software centers on a fundamental transition from isolated data repositories to interconnected, intelligent clinical ecosystems. This change is driven by the need for holistic patient views, predictive analytics, and seamless care coordination across the entire pregnancy journey.
Cloud-based platforms provide superior scalability, remote accessibility, and simplified maintenance for managing perinatal data. Large hospital networks and consolidated maternity clinics are the principal adopters, seeking to reduce their reliance on on-premise hardware. This adoption of SaaS models is displacing traditional, capital-intensive on-premises software installations, lowering IT infrastructure costs for providers.
The European Union's Medical Device Regulation (MDR) has intensified scrutiny on software that provides clinical decision support. This framework mandates more rigorous clinical evidence and continuous post-market surveillance for vendors to obtain and maintain CE marking. Developers of AI-powered risk assessment modules are most affected, now required to make substantial investments in validation studies.
Purchasing authority is migrating from individual obstetrics departments to centralized hospital IT committees that prioritize enterprise-wide compatibility. This transition disadvantages vendors of niche, standalone applications in favor of those offering broader platforms that integrate smoothly with a hospital's primary EHR system. This dynamic is especially visible in the consolidated healthcare markets of Germany and Canada.
Perinatal Software Market Segmentation
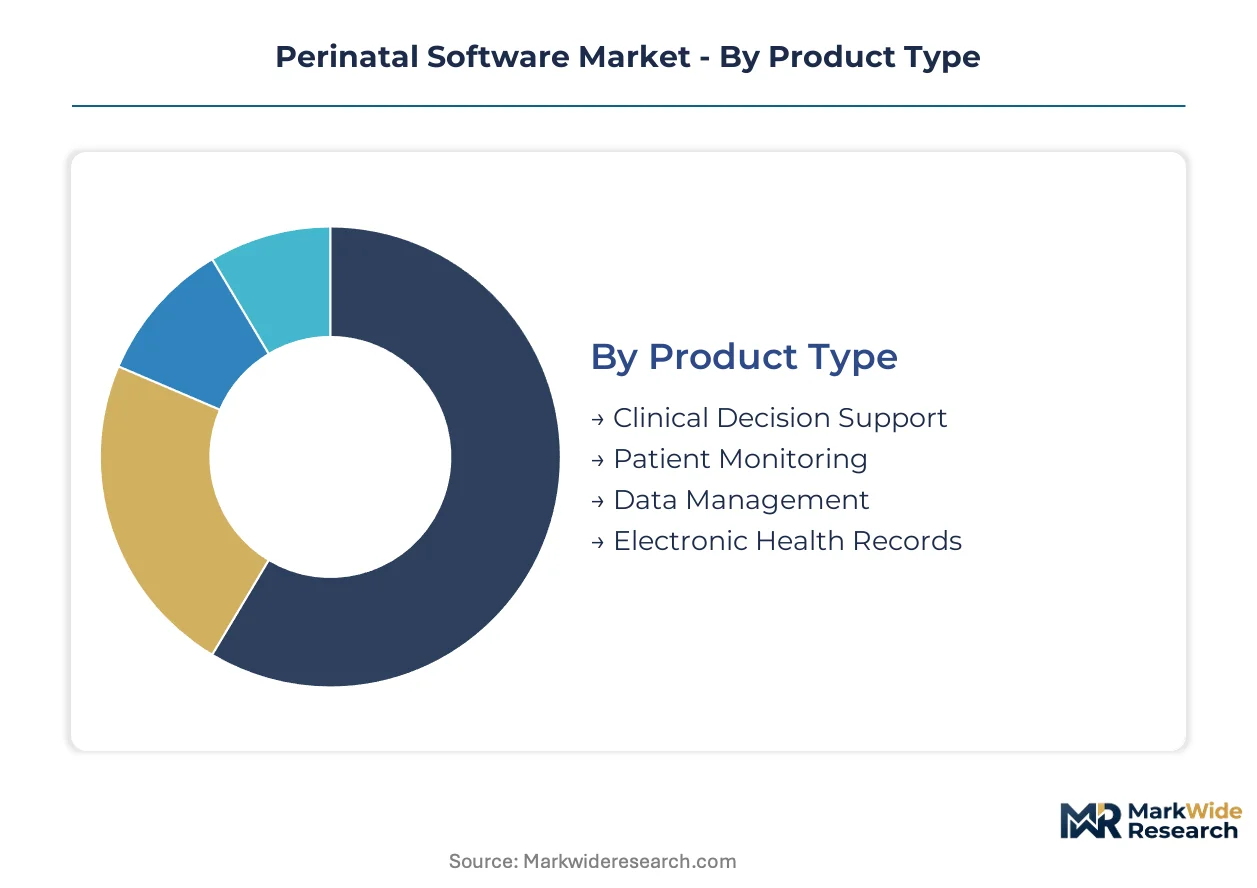
Understanding the market's segmentation reveals how perinatal software addresses diverse clinical needs and operational models across healthcare systems. This analysis dissects the market by product type, application, end user, and deployment, highlighting where innovation and demand converge. Each segment reflects specific technological capabilities and user requirements within the comprehensive perinatal care continuum.
Product Type:
The market for perinatal software product types shows a divergence in adoption patterns, with some solutions primarily serving domestic healthcare needs while others are gaining traction in export-driven modernization efforts.
- Clinical Decision Support:These advanced tools integrate AI and machine learning algorithms to analyze real-time fetal monitoring data, identifying potential distress or high-risk conditions during labor and delivery. Demand is particularly strong in developed healthcare systems like Germany and Canada, where value-based care initiatives reward improved maternal-fetal outcomes.
- Patient Monitoring:This segment encompasses software designed to collect, display, and analyze physiological data from both mother and fetus, often integrating with specialized hardware like fetal heart rate monitors. Large-scale maternity clinics prioritize these solutions for standardizing care protocols and managing high patient volumes efficiently.
- Data Management:These platforms focus on organizing and storing vast amounts of patient data, ensuring accessibility and integrity across various clinical workflows.
- Electronic Health Records:EHR-compatible modules facilitate seamless data exchange and interoperability with existing hospital IT infrastructure, a critical requirement for consolidated healthcare providers.
Electronic Health Records commands the established base due to its foundational role. The steepest expansion runs through Clinical Decision Support.
Application:
Perinatal software applications are diversifying, with some modules focusing on early intervention and others on long-term follow-up, each addressing distinct stages of maternal and infant health.
- Risk Assessment:Software in this category identifies high-risk pregnancies through predictive analytics, enabling early intervention and personalized care plans. Value-based care initiatives in the United States healthcare system are driving investment in these modules.
- Prenatal Care Planning:These applications assist healthcare providers in scheduling appointments, managing patient education, and tracking the progress of routine prenatal visits. They help standardize care protocols across large maternity clinic networks.
- Postnatal Follow-up:This application area includes modules for monitoring maternal recovery, infant health, and postpartum mental well-being, addressing a critical yet historically underserved phase.
- Birth Outcome Analysis:Tools for analyzing delivery data, identifying trends, and supporting quality improvement initiatives within labor and delivery units fall into this segment.
Prenatal Care Planning serves as a core application. The market experiences rapid development in Risk Assessment capabilities.
End User:
The end-user landscape for perinatal software is transforming, with a pronounced shift in purchasing power and specific requirements from different types of healthcare providers.
- Maternity Clinics:Large, consolidated maternity clinic networks represent a significant purchasing force, demanding scalable, interoperable enterprise-level solutions that integrate with existing EHR systems. These clinics prioritize workflow efficiency and standardized care.
- Obstetricians:Individual obstetrician practices often seek specialized tools that enhance clinical decision-making and patient engagement, though their purchasing power is diminishing relative to larger entities. They value ease of use and specific clinical functionalities.
- Midwifery Practices:These practices require flexible software solutions supporting their unique care models, often emphasizing remote monitoring and patient education.
- Neonatal Units:Specialized software for neonatal care focuses on intensive monitoring, data integration from various medical devices, and detailed outcome tracking for newborns.
Obstetricians traditionally formed the primary user base. However, Maternity Clinics are now dictating the market's trajectory.
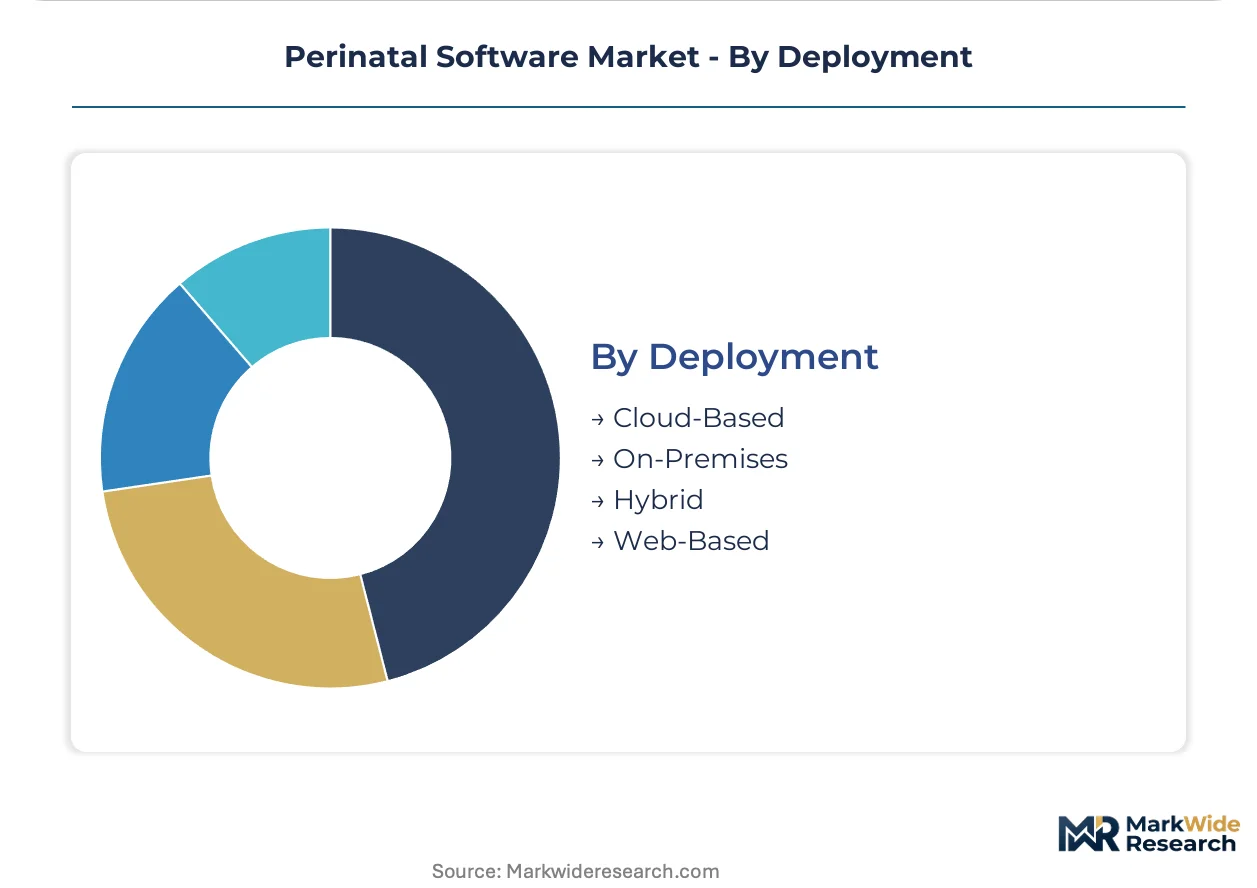
Deployment:
The deployment models for perinatal software are evolving, with cloud-based solutions gaining prominence over traditional on-premises installations due to their inherent advantages.
- Cloud-Based:These platforms offer superior scalability, remote accessibility, and reduced IT infrastructure costs, making them highly attractive to large hospital networks and consolidated maternity clinics. Cloud solutions also simplify maintenance and updates.
- On-Premises:Traditional on-premises installations provide healthcare providers with complete control over data and systems, often preferred by institutions with stringent security requirements or legacy IT infrastructure. These deployments require significant upfront investment.
- Hybrid:This model combines elements of both cloud and on-premises deployment, offering flexibility for organizations transitioning their IT systems or managing sensitive data locally.
- Web-Based:Solutions accessible via a web browser, often a subset of cloud-based offerings, provide broad accessibility and ease of use without requiring extensive local software installation.
On-Premises represents the historical foundation. Cloud-Based deployments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large, consolidated maternity clinics represent the primary buying power for perinatal software across developed economies. These enterprise-level buyers prioritize scalable, interoperable solutions for managing high patient volumes. Germany and Canada lead this shift, demanding integrated platforms for standardized care.
United States
Investment in high-risk pregnancy identification software is significant in the United States, propelled by value-based care initiatives. HIPAA mandates strict data privacy and security protocols, directly impacting software design and data handling. Major healthcare networks in metropolitan areas such as New York and San Francisco increasingly adopt integrated perinatal platforms.
Germany
Consolidated maternity clinics in Germany demand advanced clinical decision support tools. The EU's MDR framework requires rigorous validation for software classified as medical devices. Healthcare clusters in Bavaria and North Rhine-Westphalia are early adopters of AI-driven fetal monitoring solutions.
Canada
Health Canada's regulations promote interoperability within the country's publicly funded healthcare system. Consolidated provincial health authorities prioritize enterprise-level perinatal software for standardized care delivery. Major urban centers like Toronto and Vancouver are central to the deployment of integrated EHR-compatible platforms.
Japan
Modernization efforts in Japan's healthcare system are driving demand for advanced clinical IT infrastructure. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees software as a medical device. Tokyo and Osaka's large hospital groups are exploring cloud-based perinatal solutions for scalability and efficiency.
Australia
Australia's healthcare system focuses on improving maternal-fetal outcomes through digital health initiatives. The Therapeutic Goods Administration (TGA) regulates medical device software, including perinatal tools. Major hospital networks in Sydney and Melbourne are integrating remote monitoring capabilities into their perinatal care.
Perinatal Software Market Key Industry Players
Player mix skews toward established healthcare technology conglomerates alongside specialized clinical decision support innovators. The market exhibits a tiered structure, with large diversified players leveraging extensive installed bases in hospitals. Strategic archetypes include integrated hardware-software providers, focused AI-driven solution developers, and EHR-compatible platform specialists. Portfolio diversification and strategic partnerships are dominant competitive moves among vendors seeking broader market penetration.
Specialists in AI-driven clinical decision support, such as PeriGen, Inc., differentiate through advanced analytical capabilities for labor and delivery. Koninklijke Philips N.V. occupies a position as an integrated hardware and software platform provider, combining monitoring devices with data management. GE HealthCare, a US-based entity, represents a diversified healthcare technology conglomerate leveraging its extensive installed base within hospitals to cross-sell software suites. These entities exemplify the varying approaches to market penetration and value proposition within the perinatal software sector.
| Leading Market Players |
|---|
| PeriGen, Inc. |
| Koninklijke Philips N.V. |
| GE HealthCare |
| Clinical Computer Systems, Inc. |
| Trium Analysis Online GmbH |
| EDAN Instruments, Inc. |
| K2 Medical Systems Ltd. |
| Huntleigh Healthcare Limited |
| Cerner Corporation |
| Others |
Cost & Logistics Intelligence
Scalability in cloud infrastructure development strongly influences both supply concentration among platform providers and the price floors for feature-rich software suites. This dynamic favors vendors with established R&D budgets.
Pricing Analysis
Subscription-based SaaS models with tiered feature sets dominate perinatal software pricing, reflecting ongoing service and update requirements. Price differentiation stems from the level of AI-driven clinical decision support sophistication and the breadth of EHR integration capabilities. Pricing pressure stems from the competitive need to offer integrated suites to large maternity clinics, while smaller, independent obstetric practices exhibit the highest price sensitivity.
Supply Chain Analysis
The United States and Germany anchor the development of specialized clinical decision support algorithms and advanced software engineering for perinatal applications. Key component dependencies include high-performance cloud computing services and specialized medical device data integration APIs. Single-source vulnerability for specific AI model training datasets poses a structural risk. Distribution runs through direct sales teams targeting large hospital networks and strategic partnerships with established EHR vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The perinatal software market is undergoing a significant buyer-power shift, driven by the consolidation of individual obstetrician practices into large, integrated maternity clinic networks. This structural change reshapes vendor strategies.
For Market Incumbents:Consolidate existing hospital relationships by cross-selling advanced perinatal software modules into their extensive installed base of medical devices. This defends against emerging AI-specialist entrants by leveraging a comprehensive platform approach and investing in FHIR-compliant interoperability. Focus R&D on developing integrated hardware-software solutions that seamlessly capture and analyze real-time fetal monitoring data.
For New Entrants and Emerging Players:Anchor in underserved segments by developing specialized postpartum care modules or remote monitoring solutions for midwifery practices. The most penetrable segment for new entrants involves cloud-based, scalable solutions for modernizing clinical IT infrastructure in emerging Asia-Pacific and Latin American markets. A go-to-market angle involves partnering with local healthcare IT integrators for faster market access and customization.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among vendors offering comprehensive, integrated perinatal software suites with strong EHR interoperability. Long-term viability depends on acquiring firms with proven clinical efficacy and robust data security frameworks, particularly those specializing in AI-driven risk assessment. A signal to watch is the successful clearance of novel AI-powered diagnostic support tools by regulatory bodies like the FDA or CE marking under MDR.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidating disparate systems reduces administrative burden for large maternity clinics. |
| AI Clinical Decision Support Development | Enhances early detection of fetal distress, improving maternal-fetal outcomes for providers. |
| Cloud-Based SaaS Transition | Reduces IT infrastructure costs and provides superior scalability for hospital networks. |
| Postpartum Module Expansion | Addresses a critical, underserved phase of the perinatal care continuum, expanding market reach. |
| Regulatory Clearance Investment | Ensures adherence to stringent frameworks like EU MDR, enabling market access for advanced tools. |
Research Approach
Cross-validation between primary interviews with clinical informatics specialists and secondary validation from regulatory filings anchors the qualitative findings. This involved discussions with obstetricians, hospital IT managers, clinical decision support developers, and maternal-fetal medicine specialists. Secondary data sources included public health reports, medical device databases from FDA and EMA, and academic research on perinatal outcomes. Bottom-up and top-down triangulation ensured data consistency.
Sensitivity analysis informed the forecast framework, assessing market dynamics and potential shifts across the analysis window. Segmentation dimensions modeled included product type, application area, end-user archetype, deployment model, and regional healthcare system maturity. Compound Annual Growth Rates were derived from historical trends, projected technology adoption curves, and expected regulatory impacts. Key industry-specific forecast inputs included maternity clinic consolidation rates and investment in value-based care initiatives.
Material uncertainties — including unforeseen shifts in healthcare policy or major technological disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding current market structures and the pace of digital health transformation. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
United States Neonatal and Prenatal Devices Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Neonatal Critical Care Equipment Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market