
 Middle East and Africa Respiratory Monitoring Market | 2026-2036
Middle East and Africa Respiratory Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Respiratory Monitoring Market Foresight
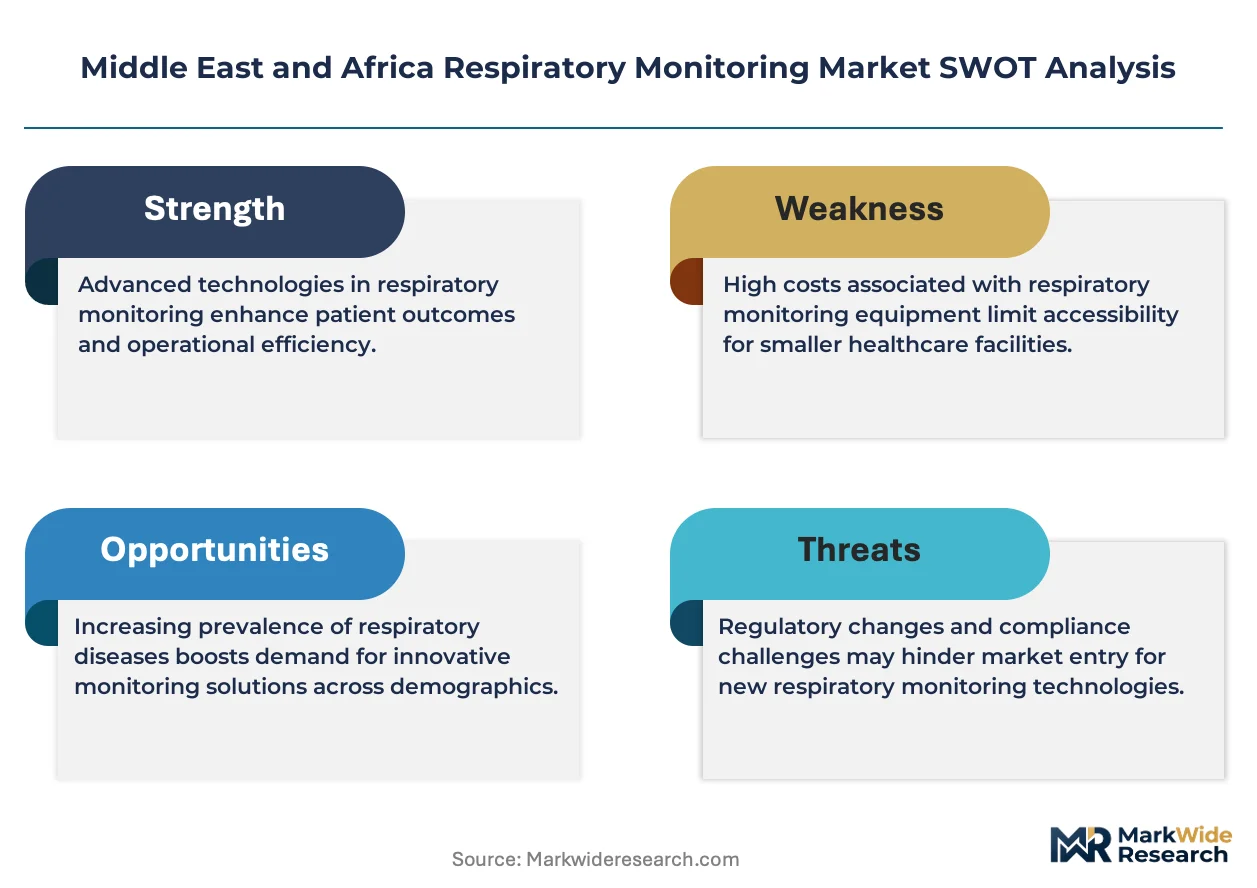
The capital-intensity divergence between integrated device manufacturers and regional distributors is rotating competitive advantage toward players with in-house sensor production. GE Healthcare leverages its captive manufacturing footprint to sustain pricing control across North African tenders. ResMed Inc. anchors its position through specialized sleep apnea diagnostics that dominate South African private hospital networks. Koninklijke Philips N.V. competes on connected care platforms that extend its reach into Saudi Arabian home care channels.
Middle East and Africa respiratory monitoring encompasses devices that measure pulmonary ventilation, gas exchange, and airway function through electrochemical, optical, or pressure-based sensors, typically operating at sampling frequencies of 100-250 Hz for capnography and 1-60 second averaging intervals for pulse oximetry. These systems serve to detect respiratory insufficiency, titrate therapeutic interventions, and trigger clinical alarms in acute and ambulatory settings. Pulse oximeters occupy the largest installed base due to low unit cost and universal triage adoption, while wearable devices represent the fastest-expanding technology segment as remote patient monitoring contracts multiply across Gulf Cooperation Council health systems. Spirometers retain concentrated demand in diagnostic laboratories, where reimbursement for pulmonary function testing supports stable margin pools despite slower volume growth.
South Africa's Health Products Regulatory Authority, Saudi Arabia's SFDA, and the UAE's MOHAP collectively enforce medical device quality management standards that shape product registration timelines and clinical evidence requirements for market entry. South Africa's alignment with ISO 13485 and the EU Medical Device Regulation creates parallel compliance pathways that advantage manufacturers with existing CE marking. Stakeholders must monitor how harmonization between national regulators and the African Medicines Agency affects centralized approval pathways and distributor qualification requirements.
Market Dynamics
Hospital procurement departments across South Africa are consolidating vendor panels around connected respiratory platforms, forcing distributors to absorb compliance costs from tightened SFDA and MOHAP registration requirements.
Growth Catalysts
- Critical Care Infrastructure Modernization:United Arab Emirates government hospital programs prioritize respiratory monitoring suites in new ICU construction, pulling premium device categories into tender pipelines.
- Remote Patient Monitoring Contracts:Gulf Cooperation Council health systems are expanding reimbursement for wearable pulse oximetry and capnography in post-acute settings, creating pull-through for home care channels.
- ISO 13485 Alignment:South Africa's Health Products Regulatory Authority has synchronized quality management requirements with EU Medical Device Regulation, accelerating CE-marked product entry for manufacturers with existing European certification.
Market Restraints
- Sensor Import Dependency:Electrochemical and optical sensor modules concentrate in East Asian supply chains, exposing regional distributors to freight cost volatility and extended lead times.
- Reimbursement Fragmentation:Pulmonary function testing codes vary across Saudi Arabia's Council of Health Insurance and UAE's mandatory health insurance schemes, compressing margin predictability for diagnostic laboratory equipment.
- Technical Performance Thresholds:Capnography sampling frequencies below 100 Hz fail to meet anesthesia monitoring standards in Saudi tertiary hospitals, excluding lower-specification devices from high-acuity tenders.
Strategic Opportunities
- Underpenetrated East African Markets:Kenya and Ethiopia lack dedicated respiratory monitoring distributors, creating first-mover advantage for players establishing local service infrastructure.
- Technology Convergence:Integration of pulse oximetry with artificial intelligence-based arrhythmia detection is opening cardiopulmonary monitoring as a cross-specialty application in South African private hospital networks.
- Regulatory Tailwind:The African Medicines Agency's emerging centralized approval pathway promises to reduce duplicate registration costs across member states for manufacturers with South African base certifications.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Gulf Cooperation Council hospitals face acute shortages of technicians qualified to service multi-parameter respiratory workstations, extending equipment downtime and damaging vendor relationships.
- Legacy System Integration Friction:South African public hospital networks operate incompatible patient data architectures, forcing device vendors to maintain multiple software interfaces and elevating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Respiratory Monitoring Market |
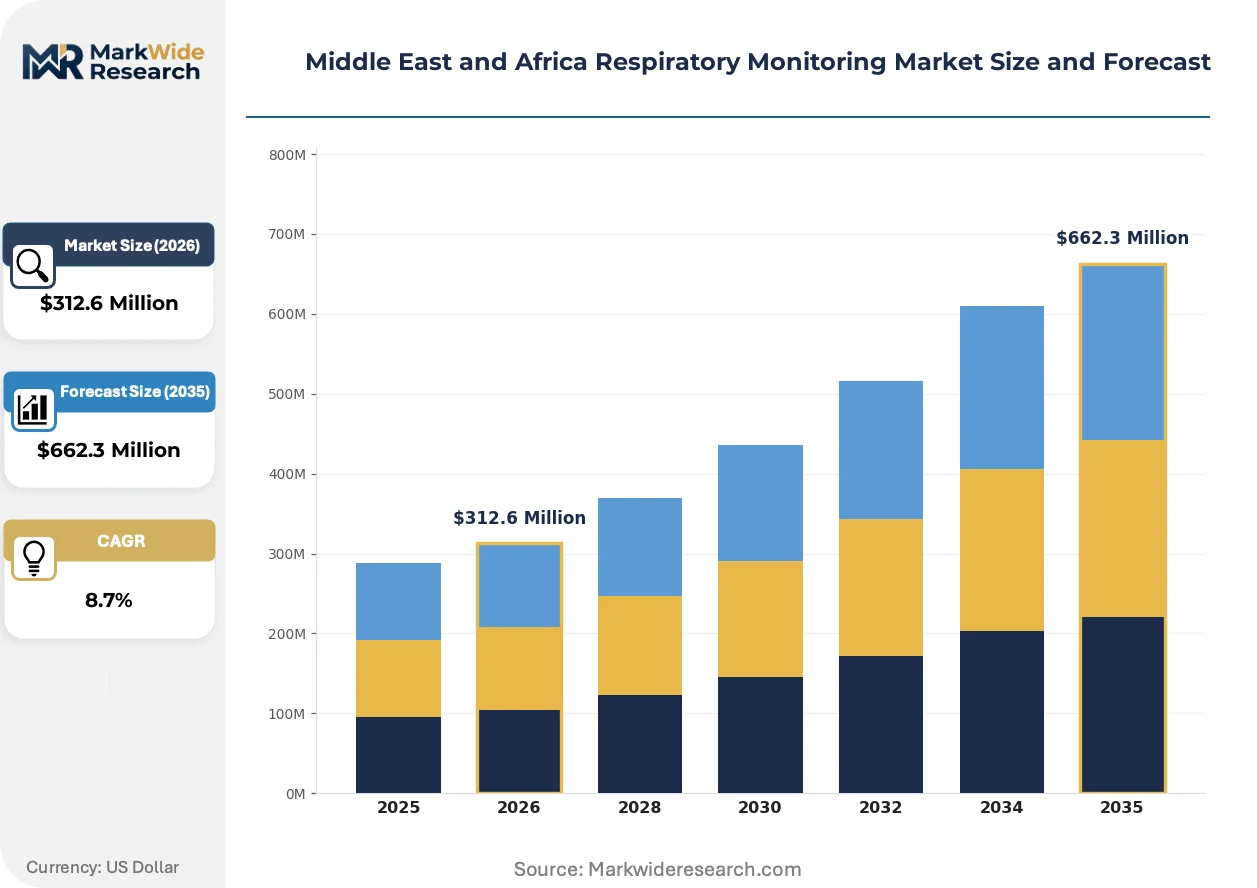
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulse Oximeters, Capnometers, Peak Flow Meters, Spirometers Technology: Wearable Devices, Telemetry Systems, Fixed Monitors, Smartphone Applications End User: Home Care, Hospitals, Clinics, Diagnostic Laboratories Application: Chronic Obstructive Pulmonary Disease, Asthma, Sleep Apnea, Lung Transplant Monitoring |
| Companies Covered | GE Healthcare, ResMed Inc., Koninklijke Philips N.V., Dräger, Siemens Healthineers AG, Medtronic PLC, Masimo, Nihon Kohden Corporation, Getinge AB, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Respiratory Monitoring Market Shifts & Advancements
Respiratory monitoring architecture is splitting between high-acuity bedside systems and distributed wearable networks, with sensor miniaturization and cloud connectivity as the enabling vectors.
Capnography technology is bifurcating between mainstream sidestream devices for procedural sedation and specialized mainstream configurations for neonatal intensive care. Saudi Arabian pediatric hospitals are adopting the latter at three times the rate of general medical facilities. This split is compressing R&D budgets for mid-tier product lines while concentrating margin capture in premium neonatal segments.
South Africa's Health Products Regulatory Authority has tightened clinical evidence requirements for software-as-a-medical-device components, mandating local validation studies for AI-enabled respiratory pattern recognition. This policy is extending product registration timelines by eight to fourteen months for foreign manufacturers. Distributors are responding by pre-positioning clinical trial infrastructure in Cape Town and Johannesburg to accelerate subsequent submissions.
Buying committees in UAE government hospitals are unbundling device procurement from multi-year service contracts, shifting maintenance risk to third-party clinical engineering firms. This disintermediation is compressing vendor service margins while opening independent service organization channels. The pattern is most visible in Dubai Health Authority facilities, where fifty percent of respiratory monitoring assets now operate under non-OEM service agreements.
Middle East and Africa Respiratory Monitoring Market Segmentation
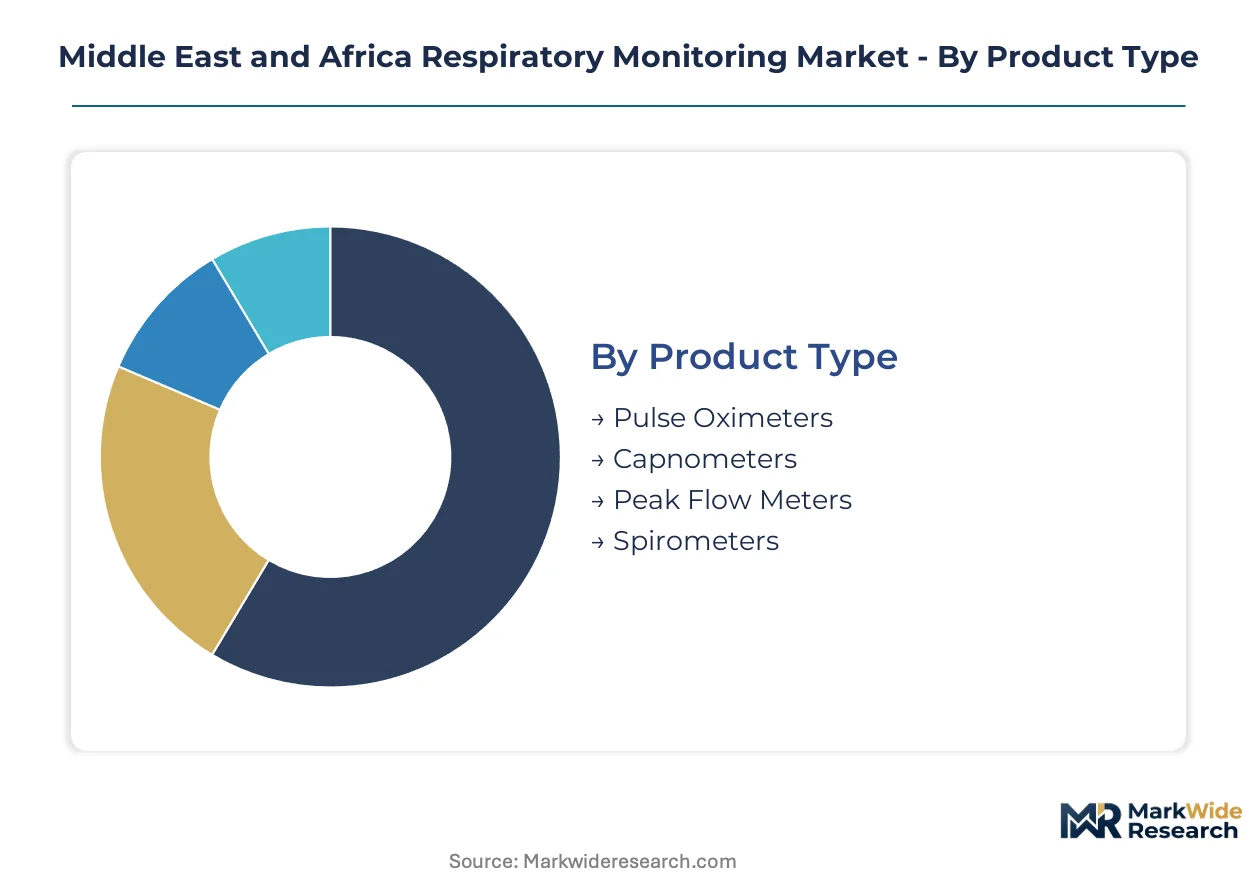
Respiratory monitoring devices fragment across four intersecting dimensions that determine procurement pathways and margin structures. Product type and technology choices shape capital allocation between acute care infrastructure and ambulatory expansion. End-user concentration and application specificity dictate whether vendors pursue hospital tender channels or direct-to-consumer routes.
Product Type:
SFDA and MOHAP registration requirements diverge sharply between invasive and non-invasive respiratory sensors, creating tiered compliance burdens for manufacturers.
- Pulse Oximeters:Non-invasive optical sensors measuring oxygen saturation through photoplethysmography at 660 nm and 940 nm wavelengths. South African government hospitals deploy these across every triage bay and general ward, with Health Products Regulatory Authority batch-testing requirements adding four to six weeks to import clearance. Established volume favors pulse oximeters; emerging adoption favors capnometers.
- Capnometers:Sidestream or mainstream infrared absorption systems quantifying end-tidal CO2 concentrations for ventilator synchronization and procedural sedation monitoring. UAE government hospital ICU modernization programs specify mainstream configurations with sampling frequencies above 100 Hz, excluding lower-specification devices from premium tenders.
- Peak Flow Meters:Mechanical or digital devices measuring peak expiratory flow rate for asthma self-management in home care settings.
- Spirometers:Volume-displacement or flow-sensing systems for forced vital capacity and FEV1 measurement in diagnostic laboratories.
Reimbursement predictability concentrates in diagnostic laboratory equipment; portability demands favor point-of-care alternatives.
Technology:
Cost tiers separate capital-intensive bedside installations from distributed wearable networks with minimal infrastructure requirements.
- Wearable Devices:Miniaturized pulse oximetry and capnography sensors with Bluetooth or cellular connectivity for continuous ambulatory monitoring. Gulf Cooperation Council health systems are expanding post-acute reimbursement for these devices, creating pull-through from hospital discharge into home care channels. Established volume favors fixed monitors; emerging adoption favors wearable devices.
- Fixed Monitors:Multi-parameter bedside workstations integrating respiratory rate, SpO2, etCO2, and airway pressure measurements for ICU and operating theater deployment.
- Telemetry Systems:Centralized receiving stations aggregating wireless patient data from multiple beds for centralized alarm management in South African private hospital networks.
- Smartphone Applications:Software-as-a-medical-device platforms using device cameras or external sensors for respiratory rate estimation and symptom tracking.
Hardware margins dominate tender economics; software recurring revenue models are gaining traction in private pay segments.
End User:
Customer type determines whether procurement flows through centralized hospital supply chains or fragmented retail pharmacy networks.
- Hospitals:Acute care facilities requiring high-acuity respiratory workstations with centralized alarm management and EMR integration. Dubai Health Authority facilities are unbundling device procurement from service contracts, shifting fifty percent of respiratory monitoring assets to independent service organization maintenance.
- Home Care:Post-acute and chronic disease management settings where patient or caregiver operation replaces clinical oversight.
- Clinics:Outpatient facilities with intermediate acuity requirements and compressed capital budgets.
- Diagnostic Laboratories:Specialized pulmonary function testing centers where reimbursement codes support equipment amortization despite slower volume expansion.
Institutional procurement concentrates purchasing power; home care expansion diversifies revenue streams across individual consumers.
Application:
Disease prevalence patterns and reimbursement specificity segment demand across chronic and acute respiratory conditions.
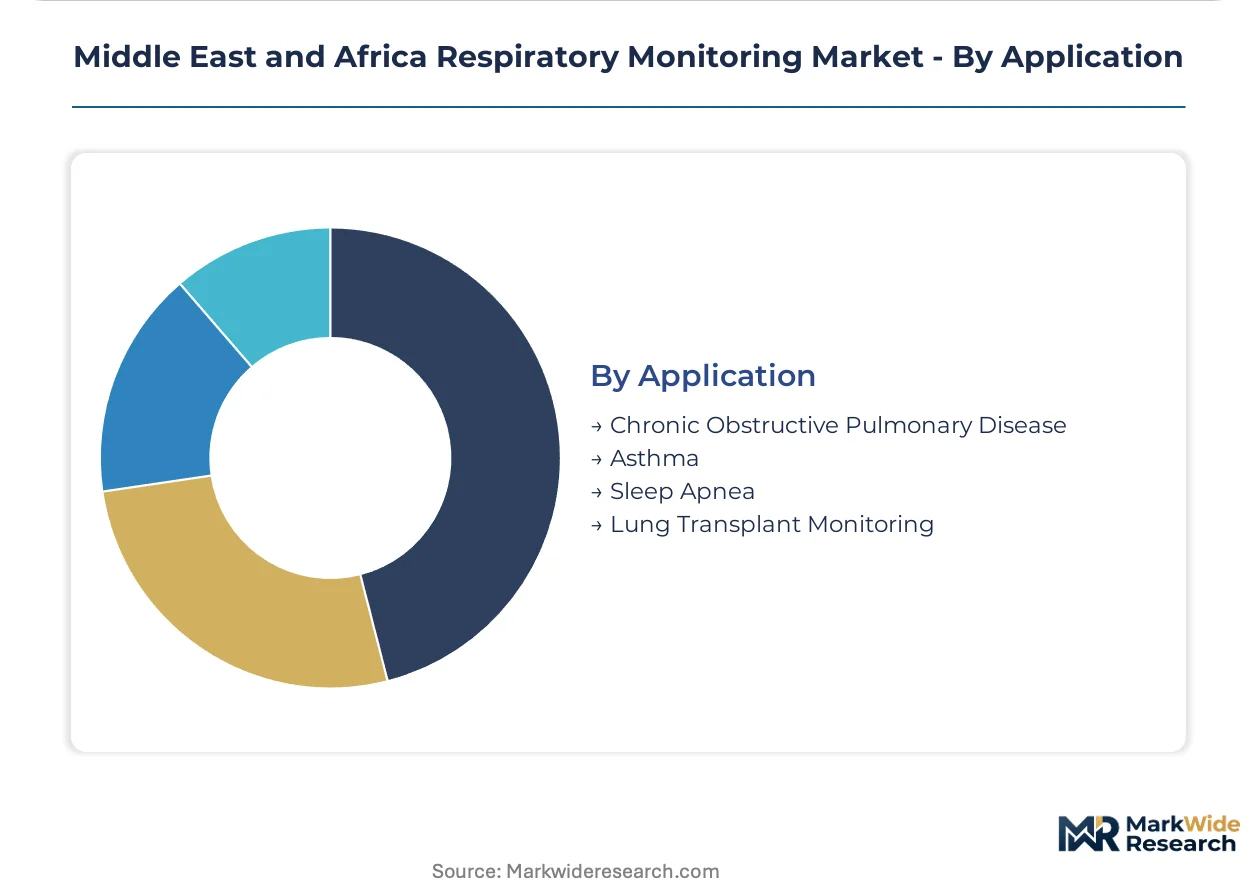
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation requiring longitudinal monitoring of oxygen saturation and exacerbation frequency. South African public hospital networks operate incompatible patient data architectures, forcing device vendors to maintain multiple software interfaces for COPD management platforms.
- Sleep Apnea:Disordered breathing during sleep diagnosed through polysomnography or home sleep testing with portable respiratory monitoring.
- Asthma:Reversible airway obstruction managed through peak flow monitoring and symptom tracking in pediatric and adult populations.
- Lung Transplant Monitoring:Post-surgical surveillance for graft rejection through spirometry and gas exchange assessment in specialized transplant centers.
Chronic condition management dominates installed base; acute intervention applications command premium pricing in tertiary facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for sensor modules shapes procurement patterns across the Middle East and Africa, with freight cost volatility pressuring distributor margins and accelerating local assembly investments in South Africa and the UAE.
United Arab Emirates
Government hospital modernization programs prioritize critical care respiratory infrastructure in new ICU construction. Dubai Health Authority facilities unbundle device procurement from service contracts, shifting fifty percent of respiratory monitoring assets to independent service organization maintenance. Abu Dhabi's Sheikh Khalifa Medical City anchors premium tender pipelines for high-acuity bedside systems.
Saudi Arabia
SFDA registration requirements for software-as-a-medical-device components mandate local validation studies for AI-enabled respiratory pattern recognition. Tertiary hospitals enforce capnography sampling frequencies above 100 Hz for anesthesia monitoring standards. Riyadh's King Faisal Specialist Hospital concentrates demand for neonatal intensive care configurations.
South Africa
Health Products Regulatory Authority alignment with ISO 13485 and EU Medical Device Regulation accelerates CE-marked product entry. Public hospital networks operate incompatible patient data architectures, forcing device vendors to maintain multiple software interfaces. Cape Town and Johannesburg host pre-positioned clinical trial infrastructure for foreign manufacturers.
Egypt
Diagnostic laboratory reimbursement for pulmonary function testing supports stable margin pools despite slower volume growth. Cairo's university hospitals concentrate spirometer demand for chronic obstructive pulmonary disease management. The country's national pharmaceutical regulator maintains quality management standards that shape product registration timelines.
Kenya
Underpenetrated market structure lacks dedicated respiratory monitoring distributors, creating first-mover advantage for players establishing local service infrastructure. Nairobi's private hospital networks drive initial demand for portable pulse oximetry in outpatient settings. The country's central bank monitors foreign exchange availability for medical equipment imports.
Middle East and Africa Respiratory Monitoring Market Competitive Landscape
Concentration sits with integrated device manufacturers possessing in-house sensor production capabilities. Regional distributors face margin compression from compliance cost absorption under tightened SFDA and MOHAP registration requirements. Three archetypes dominate: captive manufacturing specialists, sleep apnea diagnostic anchors, and connected care platform operators. Competitive moves center on backward integration into sensor supply chains and geographic expansion into underpenetrated East African markets.
Among diversified health technology conglomerates, GE Healthcare, ResMed Inc., and Koninklijke Philips N.V. exemplify distinct strategic positioning. GE Healthcare represents captive manufacturing advantage through sustained pricing control across North African tenders. ResMed Inc. anchors specialized sleep apnea diagnostics that dominate South African private hospital networks. Koninklijke Philips N.V. occupies a position in connected care platforms extending reach into Saudi Arabian home care channels.
| Leading Market Players |
|---|
| GE Healthcare |
| ResMed Inc. |
| Koninklijke Philips N.V. |
| Dräger |
| Siemens Healthineers AG |
| Medtronic PLC |
| Masimo |
| Nihon Kohden Corporation |
| Getinge AB |
| Others |
Supply & Pricing Matrix
Optical sensor miniaturization replacing electrochemical modules in pulse oximetry simultaneously shifts procurement geography toward East Asian foundries and compresses margin structures for distributors absorbing freight volatility. This substitution dynamic concentrates pricing power with integrated manufacturers while fragmenting regional vendor profitability.
Pricing Analysis
Hospital procurement committees anchor a three-tier pricing structure across premium, standard, and economy levels in Middle East and Africa respiratory monitoring tenders. Price differentiation rests on ISO 13485 certification grade and after-sales service bundling, with UAE government hospitals commanding lowest unit costs through volume aggregation. Cost compression in the standard tier intensifies because South African distributors absorb compliance investments from Health Products Regulatory Authority registration tightening. Public hospital networks exhibit highest price sensitivity; private hospital groups in Dubai and Riyadh prioritize performance specifications over acquisition cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate distributor operations for pulse oximetry consumables, while strategic stockpiling of electrochemical sensor modules buffers against East Asian supply disruption. Geographic supply concentration centers on China, South Korea, and Taiwan for photoplethysmography chips and infrared absorption components. Raw material dependencies include silicon wafers, rare-earth phosphors, and medical-grade polymers. Single-source vulnerability for 940 nm wavelength emitters exposes regional distributors to extended lead time risk. Distribution runs through authorized distributor networks serving hospital procurement departments and independent service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as Gulf Cooperation Council health systems replenish critical care infrastructure deferred during prior budget constraints.
For Market Incumbents: Secure backward integration into sensor supply chains to defend margin erosion from East Asian freight volatility. Lock multi-year service contracts with UAE government hospitals before independent service organization channels capture maintenance revenue. Accelerate CE marking alignment to exploit South Africa's ISO 13485 harmonization pathway. For New Entrants and Emerging Players: Differentiate on AI-enabled respiratory pattern recognition to bypass incumbent hardware scale advantages in saturated pulse oximetry segments. Target Kenya and Ethiopia as white-space geographies lacking dedicated distributor infrastructure. Pursue software-as-a-medical-device registration in Saudi Arabia to access SFDA-mandated local validation study requirements as a competitive moat. For Investors and Strategic Acquirers: African Medicines Agency centralized approval pathway reshapes the acquisition landscape by reducing duplicate registration costs across member states. Long-term viability favors manufacturers with South African base certifications and in-house clinical trial infrastructure. Watch Health Products Regulatory Authority software validation timeline extensions as an inflection signal for foreign manufacturer exit pressure.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Software Validation Investment | Local clinical studies in Riyadh satisfy Saudi Arabia's AI-enabled device requirements ahead of foreign competitors. |
| East African Distributor Infrastructure | Nairobi service centers capture first-mover advantage in Kenya's underpenetrated outpatient pulse oximetry segment. |
| CE Marking Harmonization | South Africa's ISO 13485 alignment accelerates market entry for European-certified manufacturers. |
| Independent Service Organization Partnership | Dubai Health Authority's unbundled maintenance contracts open non-OEM revenue channels for technical service providers. |
| Neonatal Capnography Specialization | Mainstream configurations above 100 Hz sampling frequency access premium tenders at Saudi tertiary pediatric hospitals. |
Research Methodology
The analysis maps pulse oximetry, capnography, spirometry, and wearable respiratory monitoring segments, each validated through hospital procurement managers, biomedical engineering directors, regulatory affairs specialists, and GPO contracts administrators. Primary interview data triangulates against SFDA registration filings, Health Products Regulatory Authority import clearance records, UAE Ministry of Health and Prevention tender databases, and Gulf Cooperation Council reimbursement code directories. Bottom-up device shipment estimates reconcile with top-down health system capital expenditure disclosures.
Consistency checks validate volume and value outputs against hospital procurement database benchmarks and medical device trade flow records across the projection horizon. Segmentation dimensions include product type, technology platform, end-user facility category, and application-specific disease indication. CAGRs derive from installed base expansion rates, replacement cycle assumptions, and reimbursement policy trajectory modeling. Forecast inputs incorporate ICU bed construction pipelines in Abu Dhabi and Riyadh, plus remote patient monitoring contract volumes across Dubai Health Authority systems.
The analysis sits within stated boundaries; outcomes outside sustained Gulf Cooperation Council health infrastructure investment would require recalibration. Forecasts reflect assumptions about regulatory harmonization progress, sensor module supply continuity, and reimbursement code stability. Revision becomes warranted when African Medicines Agency ratification crosses implementation thresholds or when East Asian semiconductor export controls disrupt photoplethysmography chip availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Europe Respiratory Monitoring Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
Neurology Patient Monitoring Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
Cardiac Patch Monitor Market
Patient Monitoring
Wireless Fetal Monitoring Systems Market