
 Neonatal Respiratory Distress Syndrome Treatment Market | 2026-2036
Neonatal Respiratory Distress Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal Respiratory Distress Syndrome Treatment Market Foresight
The EU MDR's tightened clinical evidence requirements for pediatric devices is realigning how manufacturers structure neonatal respiratory trials across European markets. Chiesi Farmaceutici S.p.A. leverages its heritage in surfactant science to sustain leadership in exogenous surfactant supply chains. Pfizer Inc. anchors its position through broad antibiotic portfolios that address secondary infections in ventilated preterm infants.
Neonatal respiratory distress syndrome treatment encompasses pharmacological and mechanical interventions to restore functional residual capacity in preterm lungs deficient in pulmonary surfactant, typically administered via endotracheal instillation or less invasive surfactant administration techniques within the first hours of life. Surfactant replacement therapy dominates value generation due to its established mortality reduction profile and mandatory inclusion in neonatal resuscitation protocols, while bronchodilators occupy a narrower niche addressing reactive airway components in prolonged ventilator dependence. Inhalation delivery commands the largest share of clinical utilization, though intravenous corticosteroid protocols for antenatal maturation continue to shape upstream prevention economics.
FDA oversight of orphan drug designations for surfactant therapies creates accelerated review pathways that compress development timelines for preterm-focused formulations. EMA's pediatric investigation plans and the EU MDR's post-market surveillance requirements collectively elevate clinical evidence burdens for devices used in neonatal ventilation circuits. Stakeholders must monitor how reimbursement authorities in major markets calibrate bundled payment models for extremely low birth weight infant episodes against standalone therapy pricing.
Market Dynamics
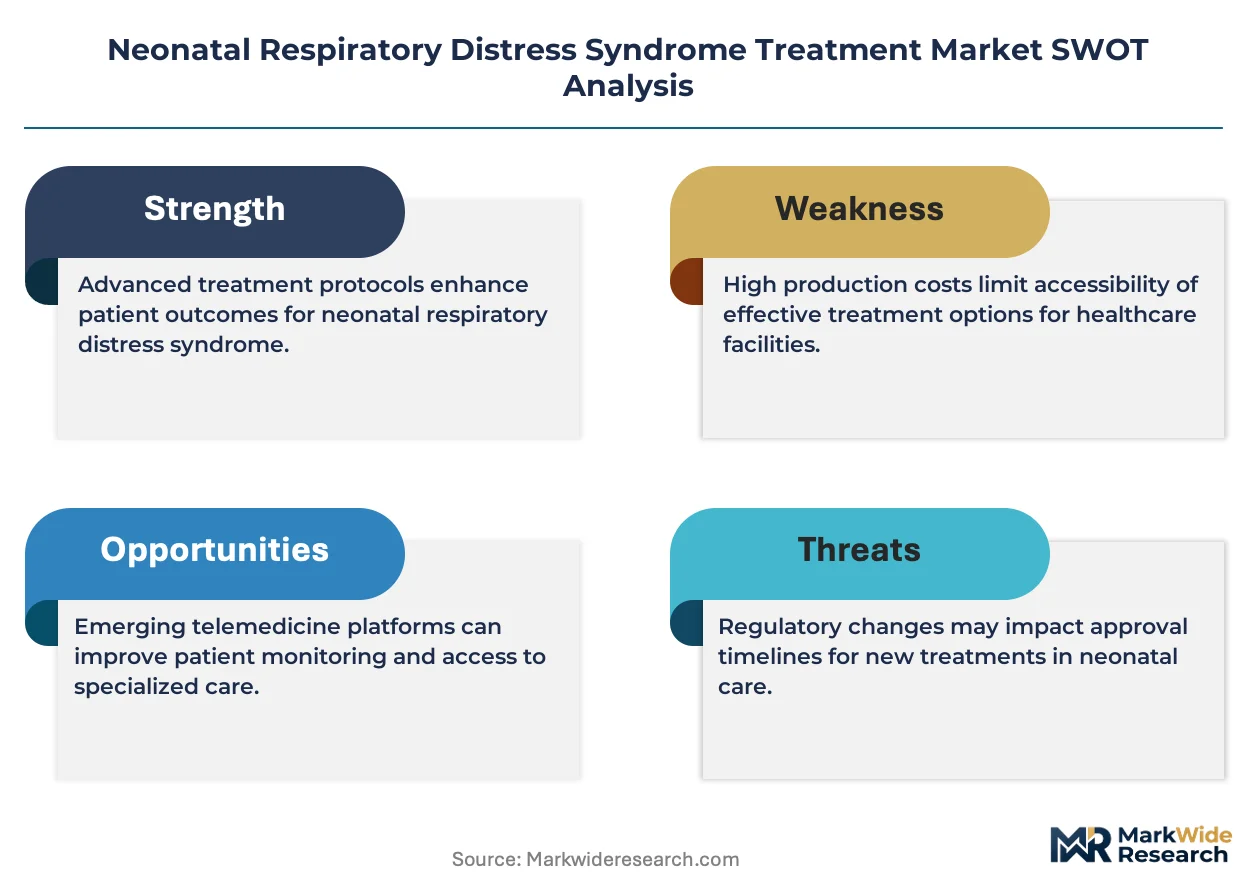
Surfactant therapy supply concentration among three European manufacturers is compressing procurement timelines and elevating tender complexity for neonatal intensive care units worldwide.
Growth Catalysts
- FDA orphan drug exclusivity extensions:The framework accelerates surfactant formulation approvals for preterm indications, shortening development cycles for pediatric-focused therapies.
- Less invasive surfactant administration (LISA):This technique reduces mechanical ventilation exposure in extremely low birth weight infants, expanding addressable patient populations in tertiary care centers.
- Japan's neonatal network consolidation:Prefecture-level perinatal centers are standardizing surfactant protocols, creating concentrated demand pools for specialized formulations.
Market Restraints
- Porcine lung extract supply volatility:Raw material dependence on agricultural biosecurity conditions in Denmark and the Netherlands creates input cost instability.
- Single-source API concentration:Synthetic surfactant peptide manufacturing clusters in Switzerland, exposing buyers to geopolitical transit risks.
- EMA pediatric investigation plan timelines:Extended evidence generation requirements for neonatal devices delay market entry by 18-24 months versus adult pathways.
Strategic Opportunities
- Indian tertiary neonatal unit expansion:Government-funded perinatal centers in Maharashtra and Tamil Nadu are adopting surfactant protocols for the first time, creating new demand formation.
- Antenatal corticosteroid-surfactant combination protocols:Converging maternal-fetal medicine with neonatal therapeutics is opening integrated care pathway contracts.
- US Medicaid bundled payment pilots:Episode-based reimbursement for extreme prematurity is incentivizing protocol standardization across hospital networks.
Industry Challenges
- Neonatal pharmacology trial recruitment:Parental consent complexity and small patient cohorts extend clinical study duration beyond commercial viability thresholds.
- Legacy ventilator-surfactant delivery incompatibility:Device interface standardization gaps between European and North American equipment manufacturers complicate LISA technique rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal Respiratory Distress Syndrome Treatment Market |
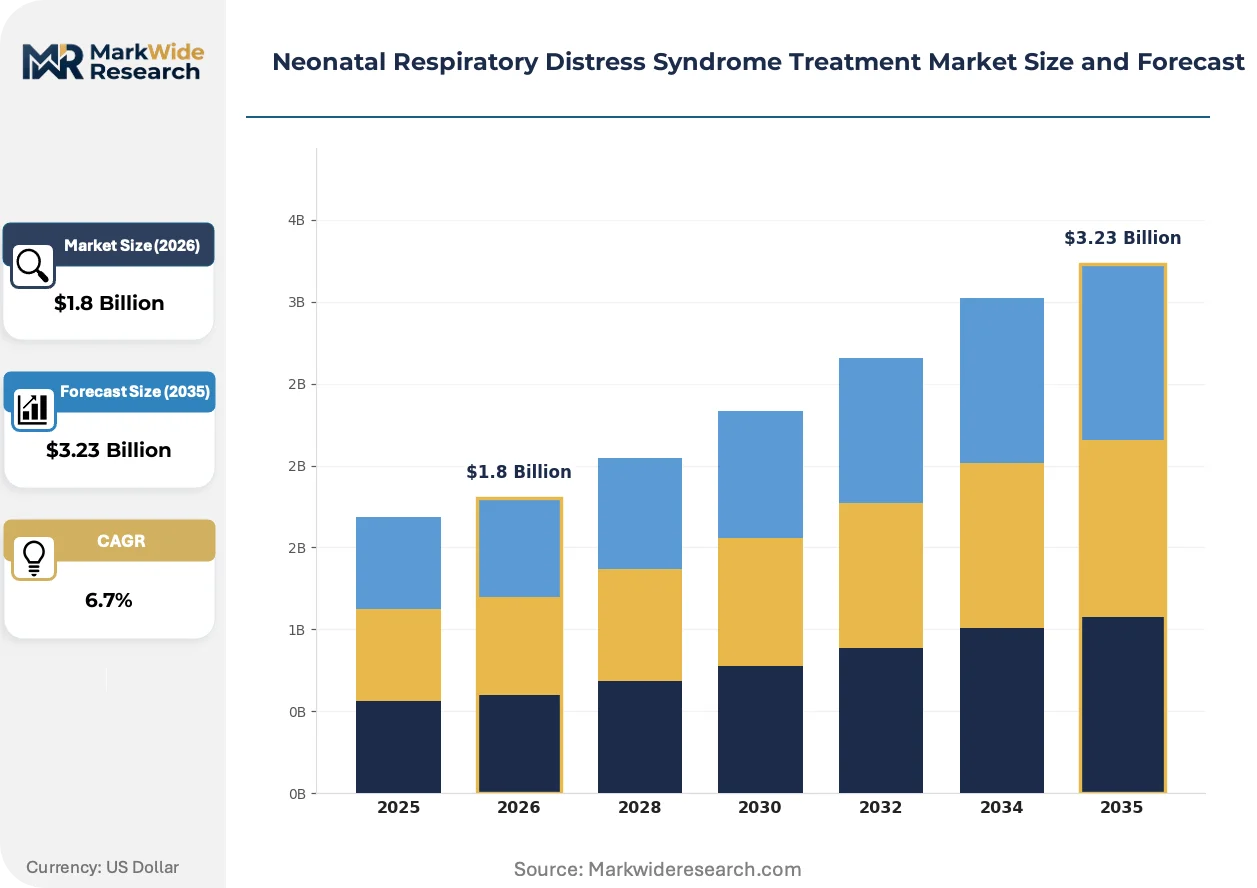
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Bronchodilators, Corticosteroids, Antibiotics Delivery Mode: Inhalation, Intravenous, Oral, Subcutaneous End User: Neonatal Intensive Care Units, Hospitals, Home Care, Clinics Therapy Area: Respiratory Disorders, Prematurity, Genetic Disorders, Infectious Diseases |
| Companies Covered | AbbVie Inc., Chiesi Farmaceutici S.p.A., Pfizer Inc., Merck & Co., Inc., Novartis AG, Sanofi, AstraZeneca, Fresenius Kabi, ONY, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal Respiratory Distress Syndrome Treatment Market Shifts & Advancements
Neonatal respiratory care is converging around minimally invasive delivery modalities and predictive stratification tools that reshape when and how surfactant intervention occurs.
Synthetic peptide surfactant technology is unifying the functional advantages of animal-derived extracts with recombinant manufacturing scalability. Academic medical centers in Germany and the United States are piloting these formulations for infants with congenital surfactant protein deficiencies. The technology is unifying previously separate procurement streams for standard and specialized indications into single-supplier contracts.
EU MDR post-market surveillance requirements for neonatal ventilation circuits are mandating real-world evidence collection that exceeds prior CE-marking thresholds. Device manufacturers must now maintain active safety registries across multiple member states. Neonatal intensive care units in France and Italy are responding by consolidating purchasing around suppliers with established pharmacovigilance infrastructure.
Hospital buying committees are compressing surfactant supplier rosters from multi-source to dual-source arrangements to simplify protocol training and inventory management. This consolidation is displacing fragmented local distributor networks in favor of direct manufacturer agreements. The shift is most visible in US children's hospital networks and Japanese prefectural medical centers with standardized formularies.
Neonatal Respiratory Distress Syndrome Treatment Market Segmentation
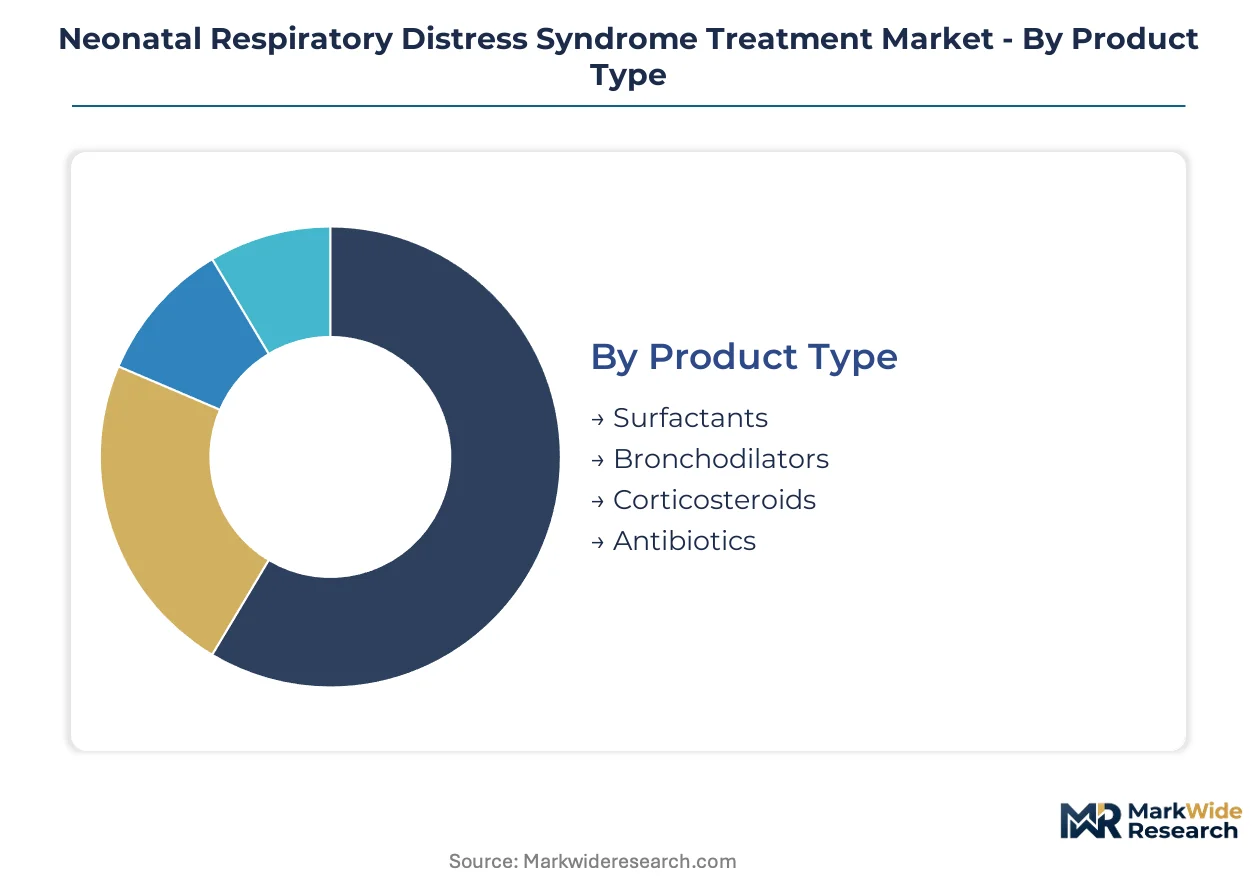
Segmentation in neonatal respiratory care reveals how procurement decisions split between mandatory surfactant protocols and discretionary adjunct therapies. Treatment modality selection hinges on gestational age thresholds, ventilation requirements, and bundled reimbursement structures.
Product Type:
Hospital formulary committees prioritize mortality reduction data and supply security when allocating budget across pharmacological categories.
- Surfactants:Exogenous pulmonary surfactants derived from porcine lung extracts or synthetic peptides restore alveolar surface tension mechanics in preterm infants. Demand concentrates in US and Japanese tertiary perinatal centers where mandatory resuscitation protocols drive volume procurement through sole-source or dual-source contracts.
- Bronchodilators:Beta-agonist and anticholinergic agents address reactive airway components in prolonged ventilator dependence, typically reserved for infants beyond 32 weeks gestation with evolving chronic lung disease. Adoption is accelerating in German neonatal networks standardizing weaning protocols.
- Corticosteroids:Systemic dexamethasone and hydrocortisone protocols modulate inflammatory cascades in ventilator-dependent infants.
- Antibiotics:Empiric and targeted antimicrobial therapy prevents secondary pneumonia in intubated preterm populations.
Volume sits with Surfactants; growth tilts toward Corticosteroids as antenatal-neonatal integrated protocols expand.
Delivery Mode:
Route selection reflects invasiveness trade-offs between efficacy assurance and iatrogenic injury minimization in fragile neonatal physiology.
- Inhalation:Endotracheal instillation and less invasive surfactant administration techniques deliver medication directly to terminal airspaces. Japanese prefectural centers and US children's hospital networks are consolidating around standardized inhalation protocols to reduce mechanical ventilation exposure.
- Intravenous:Systemic corticosteroid and antibiotic administration bypasses pulmonary absorption variability in hemodynamically unstable infants.
- Oral:Enteral formulations support post-extubation transition and chronic medication management.
- Subcutaneous:Depot injections remain niche for specific hormonal or immunomodulatory indications in specialized genetic disorder management.
Procurement volume clusters in Inhalation; protocol innovation is accelerating fastest in Intravenous combination therapies.
End User:
Care setting determines reimbursement pathway complexity and technology infrastructure requirements for therapy administration.
- Neonatal Intensive Care Units:Level III and IV NICUs command sophisticated ventilation-surfactant integration with 24-hour neonatologist coverage. India's government-funded perinatal centers in Maharashtra and Tamil Nadu are adopting surfactant capabilities for the first time, creating infrastructure buildout demand.
- Hospitals:General hospital maternity units with Level II nurseries manage moderate prematurity with selective surfactant transfer protocols.
- Home Care:Post-discharge respiratory support and medication management for chronic lung disease of prematurity.
- Clinics:Outpatient follow-up for surfactant protein deficiency screening and long-term pulmonary monitoring.
Revenue concentrates in Neonatal Intensive Care Units; capacity expansion is climbing fastest in Hospitals upgrading to Level III designation.
Therapy Area:
Indication targeting shapes clinical trial design and regulatory pathway selection for pipeline assets.
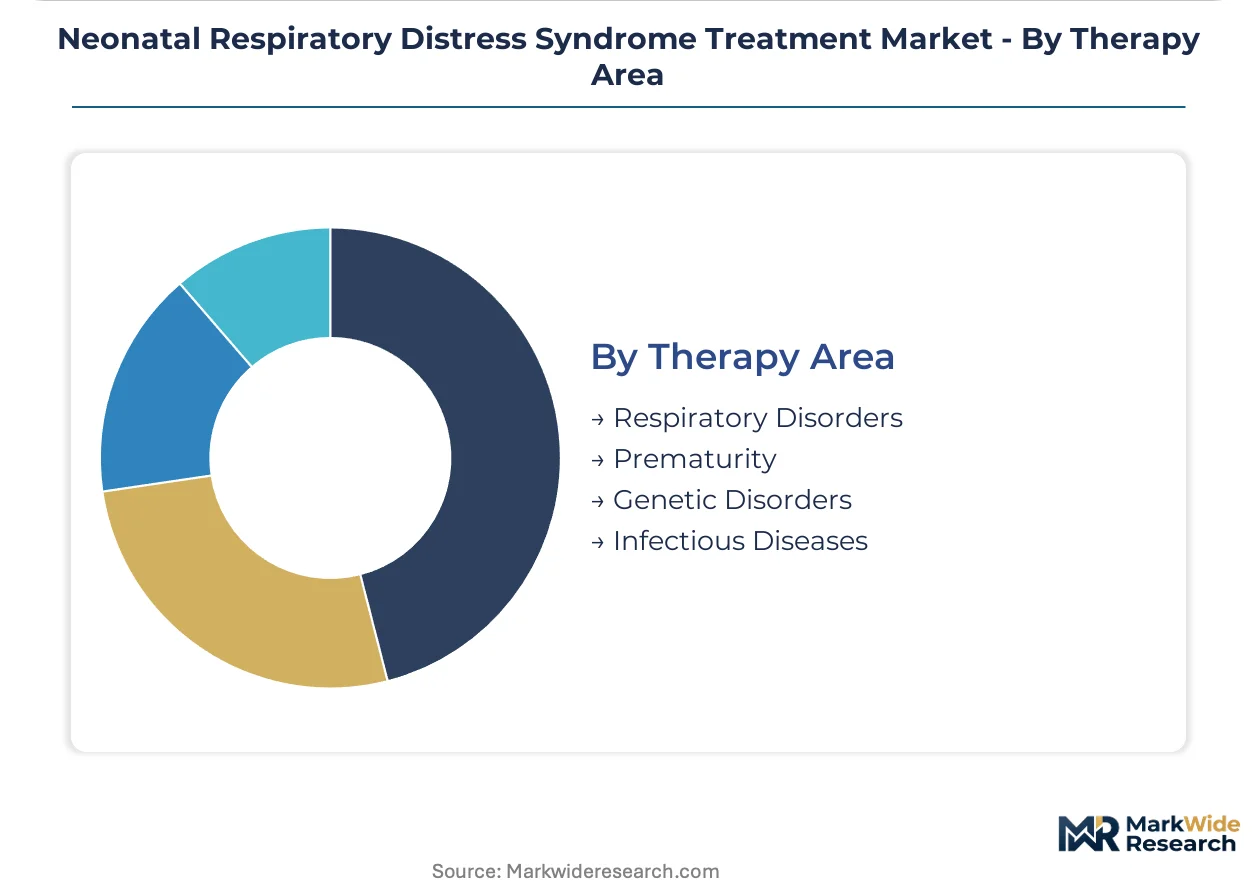
- Respiratory Disorders:Primary surfactant deficiency and acute respiratory distress syndrome in preterm neonates. Academic medical centers in Germany and the United States pilot synthetic peptide formulations for congenital surfactant protein deficiencies, unifying standard and specialized procurement streams.
- Prematurity:Gestational age-driven protocols for infants below 37 weeks encompassing antenatal corticosteroid priming through neonatal surfactant rescue.
- Genetic Disorders:Rare surfactant metabolism dysfunction and alveolar capillary dysplasia requiring individualized therapeutic approaches.
- Infectious Diseases:Pneumonia and sepsis-related respiratory compromise requiring antimicrobial-surfactant combination management.
Patient volume aggregates in Prematurity; pipeline investment is expanding most steeply in Genetic Disorders as synthetic surfactant technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors clinical trial density for synthetic surfactant formulations, while manufacturing supply chains cluster across Swiss pharmaceutical corridors and Danish agricultural processing zones.
United States
Medicaid bundled payment pilots for extreme prematurity episodes are standardizing surfactant protocols across children's hospital networks. FDA orphan drug exclusivity frameworks compress development timelines for preterm-focused formulations. Tertiary perinatal centers in California and Massachusetts concentrate procurement volume through sole-source contracts.
Germany
Academic medical centers in Munich and Heidelberg pilot recombinant peptide surfactants for congenital protein deficiencies. EMA pediatric investigation plans extend evidence generation timelines for neonatal devices by 18-24 months versus adult pathways. Baden-Württemberg's neonatal networks are consolidating purchasing around suppliers with established pharmacovigilance infrastructure.
Japan
Prefecture-level perinatal centers in Tokyo and Osaka are standardizing less invasive surfactant administration techniques. METI-funded neonatal network consolidation creates concentrated demand pools for specialized formulations. Kansai region medical centers are compressing supplier rosters from multi-source to dual-source arrangements.
India
Government-funded perinatal centers in Maharashtra and Tamil Nadu are adopting surfactant protocols for the first time. CDSCO regulatory pathways for imported neonatal therapies shape procurement timelines for tertiary units. Mumbai and Chennai hospital clusters are driving infrastructure buildout demand for Level III NICU designation.
Switzerland
Synthetic surfactant peptide manufacturing clusters in Basel expose buyers to geopolitical transit risks for active pharmaceutical ingredients. Swissmedic oversight of biologics manufacturing maintains quality benchmarks for European supply. The country's pharmaceutical corridor anchors recombinant production scalability for next-generation formulations.
Neonatal Respiratory Distress Syndrome Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory exclusivity and supply security dimensions. Three European manufacturers concentrate animal-derived surfactant supply, compressing procurement timelines for neonatal intensive care units worldwide. Strategic archetypes span heritage surfactant specialists, diversified pharmaceutical portfolios, and synthetic peptide technology developers. Competitive moves center on backward integration into raw material sourcing and direct hospital contracting to displace fragmented distributor networks.
Within the heritage specialist tier, Chiesi Farmaceutici S.p.A. and ONY, Inc. exemplify supply chain anchoring through decades of exogenous surfactant manufacturing experience. Among diversified pharmaceutical conglomerates, AbbVie Inc. and Pfizer Inc. occupy positions where broad antibiotic and critical care portfolios address secondary infection management in ventilated preterm populations. Novartis AG sits within the innovation-driven archetype, representing synthetic peptide technology migration away from animal-derived extracts.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Chiesi Farmaceutici S.p.A. |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Novartis AG |
| Sanofi |
| AstraZeneca |
| Fresenius Kabi |
| ONY, Inc. |
| Others |
Supply & Pricing Matrix
Synthetic peptide surfactant manufacturing migration from animal-derived extracts is compressing cost structures while concentrating API production in Swiss pharmaceutical corridors. This technological shift simultaneously reduces raw material biosecurity exposure and elevates pricing power for recombinant-capable suppliers against legacy extract-dependent competitors.
Pricing Analysis
Mortality-reduction outcomes anchor value-based pricing for surfactant therapies, with tertiary perinatal centers in the United States and Japan contracting through sole-source or dual-source arrangements that bundle delivery with protocol training. Price differentiation separates synthetic peptide formulations from porcine-derived extracts, with certification under FDA orphan drug exclusivity frameworks commanding premium positioning. Pricing pressure stems from Medicaid bundled payment pilots compressing episode-based reimbursement for extreme prematurity. General hospital maternity units with Level II nurseries exhibit highest price sensitivity, while academic medical centers prioritize supply security over unit cost.
Supply Chain Analysis
Regional distribution centers in Basel, Copenhagen, and Amsterdam orchestrate hub-and-spoke patterns for surfactant therapies, with cold-chain integrity requirements dictating inventory positioning near tertiary neonatal intensive care units. Geographic supply concentration clusters in Switzerland for synthetic peptide APIs, Denmark and the Netherlands for porcine lung extract processing, and Italy for finished dose manufacturing. Raw material dependencies encompass agricultural biosecurity conditions for porcine sourcing, recombinant fermentation capacity for peptide production, and specialized packaging for terminal sterilization. Single-source vulnerability in Swiss API manufacturing exposes buyers to geopolitical transit disruption. Distribution runs through direct manufacturer agreements displacing fragmented distributor networks in US children's hospital networks and Japanese prefectural centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR's pediatric investigation plan timelines and post-market surveillance requirements erect a cost-of-compliance barrier that favors established players with pharmacovigilance infrastructure, filtering out undercapitalized entrants.
For Market Incumbents: Cement supply security through backward integration into porcine sourcing or recombinant fermentation capacity, while consolidating direct hospital contracting relationships to displace distributor intermediaries. Synthetic peptide technology substitution threatens heritage extract-dependent portfolios; prioritize R&D investment in recombinant manufacturing scalability to maintain margin structure. For New Entrants and Emerging Players: Government-funded perinatal centers in Maharashtra and Tamil Nadu represent the most penetrable demand formation, with first-time surfactant protocol adoption creating infrastructure partnership opportunities. Target integrated care pathway contracts combining antenatal corticosteroid priming with neonatal surfactant rescue, leveraging India's CDSCO regulatory pathways for imported therapies as market entry mechanism. For Investors and Strategic Acquirers: Exit pathways concentrate in synthetic peptide technology developers with recombinant manufacturing scalability, as animal-derived extract dependence becomes stranded asset risk. Long-term viability over the analysis window favors suppliers with dual-source raw material flexibility and established FDA orphan drug exclusivity positions. Watch for EMA pediatric investigation plan completion timelines as inflection indicator for European market access valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Exclusivity Filing | FDA accelerated review compresses development timelines for preterm-focused surfactant formulations. |
| Synthetic Peptide Manufacturing Scale-Up | Recombinant production in Basel corridors unifies standard and specialized indication procurement streams. |
| Less Invasive Surfactant Administration Training | Protocol standardization across Japanese prefectural centers reduces mechanical ventilation exposure. |
| Direct Hospital System Contracting | US children's hospital networks consolidate supplier rosters from multi-source to dual-source arrangements. |
| EU MDR Pharmacovigilance Infrastructure Investment | Post-market surveillance compliance elevates evidence burdens filtering out undercapitalized device competitors. |
Research Methodology
Multi-period observation of surfactant therapy procurement volumes, neonatal intensive care unit admission rates, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with neonatology department heads, hospital formulary directors, regulatory affairs specialists at pharmaceutical manufacturers, and GPO contracts managers. Secondary validation drew from FDA orphan drug designation filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov protocol registries, and CMS Medicaid bundled payment pilot documentation. Bottom-up patient cohort modeling and top-down pharmaceutical revenue triangulation cross-checked volume and value estimates.
Segment-weighting across product type, delivery mode, end user, and therapy area dimensions structured the analytical framework, with gestational age thresholds and ventilation requirement intensity serving as additional stratification inputs. CAGRs were derived from cohort survival modeling and therapy penetration curve analysis, incorporating antenatal corticosteroid-surfactant protocol convergence and synthetic peptide technology substitution rates as industry-specific forecast inputs across the projection horizon.
Caveats apply where EU MDR evidence generation timeline extensions, porcine lung extract supply disruptions from agricultural biosecurity events, or Medicaid reimbursement pilot expansions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Neonatal Dialysis Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Phototherapy Devices Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Europe Fetal and Neonatal Care Equipment Market
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
Umbilical Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market