
 Preterm Birth Prevention and Management Market | 2026-2036
Preterm Birth Prevention and Management Market Size, Share, and Industry Trends Forecast 2026-2036
Preterm Birth Prevention and Management Market Outlook
Modular service bundling is pivoting how health systems procure preterm birth interventions, shifting from discrete drug purchasing to comprehensive maternal risk-management contracts. Pfizer Inc. leverages its manufacturing scale to supply tocolytic agents across multiple delivery formats. Covis Pharma GmbH specializes in branded hydroxyprogesterone caproate formulations, anchoring its position in the injectable hormonal segment. Sera Prognostics differentiates through biomarker-based risk prediction, extending its reach into early-screening protocols.
Preterm birth prevention and management encompasses pharmacological, mechanical, and diagnostic interventions designed to delay delivery before thirty-seven weeks gestation, with progesterone formulations, cervical pessaries, and fetal fibronectin testing representing core technical modalities. Its primary purpose is to reduce neonatal morbidity, mortality, and associated healthcare costs through early identification and intervention. The medications segment dominates current revenue, driven by hydroxyprogesterone and tocolytic prescriptions, while monitoring tools represent the fastest-expanding category as biomarker platforms gain clinical traction. Hospitals capture the largest end-user share due to their capacity for integrated labor-and-delivery management, though home care providers are gaining ground as remote monitoring technologies mature.
The FDA's obstetric drug development guidance shapes trial endpoints and labeling requirements for preterm interventions, while the EMA's pediatric investigation plans influence European market access timelines for hormonal therapies. Compliance with these frameworks demands substantial clinical investment, filtering out smaller developers and concentrating development among well-capitalized firms. Stakeholders must weigh the trade-off between biomarker-driven personalization and the reimbursement complexity it introduces across fragmented payer systems.
Market Dynamics
Hospital procurement offices are consolidating preterm birth interventions into maternal risk-management contracts that bundle diagnostics, pharmaceuticals, and monitoring services under single vendor relationships.
Growth Catalysts
- Medicaid expansion:State-level program expansions in the United States have widened eligibility for progesterone therapies and cervical cerclage procedures among high-risk pregnancies.
- Biomarker platform maturation:Fetal fibronectin and novel proteomic assays are embedding into first-trimester screening protocols, enabling earlier risk stratification.
- FDA obstetric guidance evolution:The agency's updated trial endpoint requirements for preterm interventions are clarifying pathways for novel tocolytic approvals.
Market Restraints
- Progesterone API concentration:Active pharmaceutical ingredient manufacturing for hydroxyprogesterone caproate concentrates among three contract manufacturers, creating supply vulnerability.
- Reimbursement fragmentation:Medicaid fee schedules vary by state, complicating national pricing strategies for branded hormonal therapies.
- Diagnostic substitution:Transvaginal ultrasound cervical length measurement competes directly with biomarker testing for initial risk assessment.
Strategic Opportunities
- Home-based monitoring:Remote uterine activity sensors and telemedicine protocols are opening channels outside traditional hospital-based labor-and-delivery units.
- EMA pediatric investigation alignment:Harmonized neonatal outcome study requirements are streamlining European market access for developers with US-approved products.
- Integrated perinatal networks:Accountable care organizations in the United States are seeking single-source partners for full-spectrum preterm prevention programs.
Industry Challenges
- Maternal-fetal medicine specialist scarcity:Fellowship-trained physicians capable of interpreting complex risk algorithms remain concentrated in academic medical centers.
- Clinical trial recruitment:Enrollment of high-risk pregnant patients demands extended site networks and enhanced retention protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preterm Birth Prevention and Management Market |
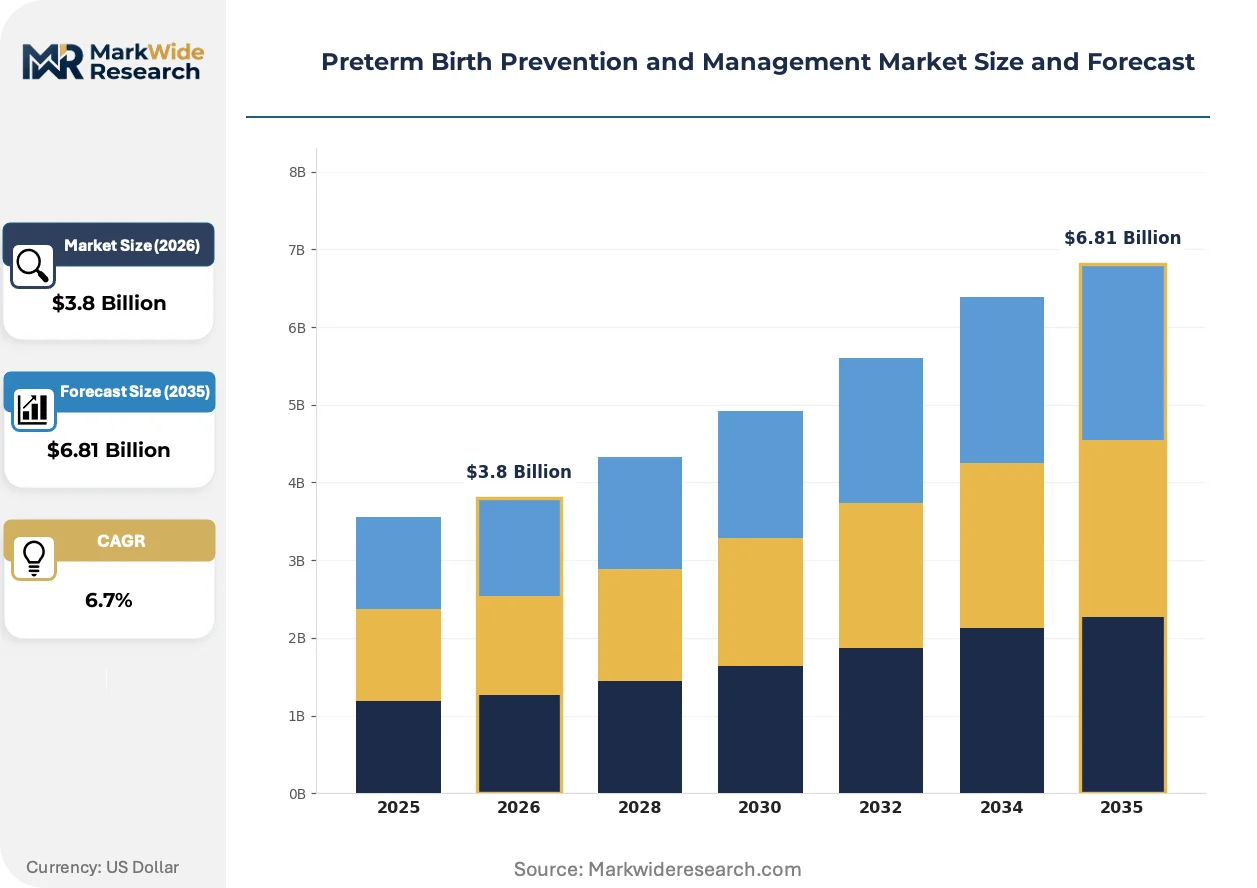
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Devices, Supplements, Monitoring Tools Therapy Area: Hormonal Treatments, Antimicrobial Therapy, Lifestyle Modifications, Nutritional Support Delivery Mode: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Clinics, Community Health Centers, Home Care Providers |
| Companies Covered | Teva Pharmaceuticals USA, Inc., Covis Pharma GmbH, Pfizer Inc., AbbVie Inc., Bayer AG, Novartis AG, Ferring B.V., Sera Prognostics, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preterm Birth Prevention and Management Market Strategic Shifts
Digital biomarker platforms and risk-prediction algorithms are compressing the window between initial screening and therapeutic intervention, reshaping how health systems allocate resources across prenatal care pathways.
Artificial intelligence-driven risk scoring is converging with electronic health record systems to flag high-risk pregnancies at earlier gestational ages. Health systems in California and Texas are piloting these integrations. The technology is converging with traditional obstetric workflows to reduce false-positive referral rates and concentrate specialist resources on validated high-risk cases.
The FDA's 2023 obstetric drug development guidance mandates composite neonatal outcome endpoints rather than gestational age alone. This regulatory shift extends trial duration and increases data collection costs. Sponsors targeting preterm indications are responding by prioritizing drugs with existing safety profiles in other indications.
Service bundling now dominates how integrated delivery networks contract for preterm prevention. Discrete purchasing of tocolytics, pessaries, and diagnostics is giving way to per-patient episode pricing. This shift is most visible in United States Medicaid managed care plans seeking predictable maternal healthcare expenditures.
Preterm Birth Prevention and Management Market Segmentation
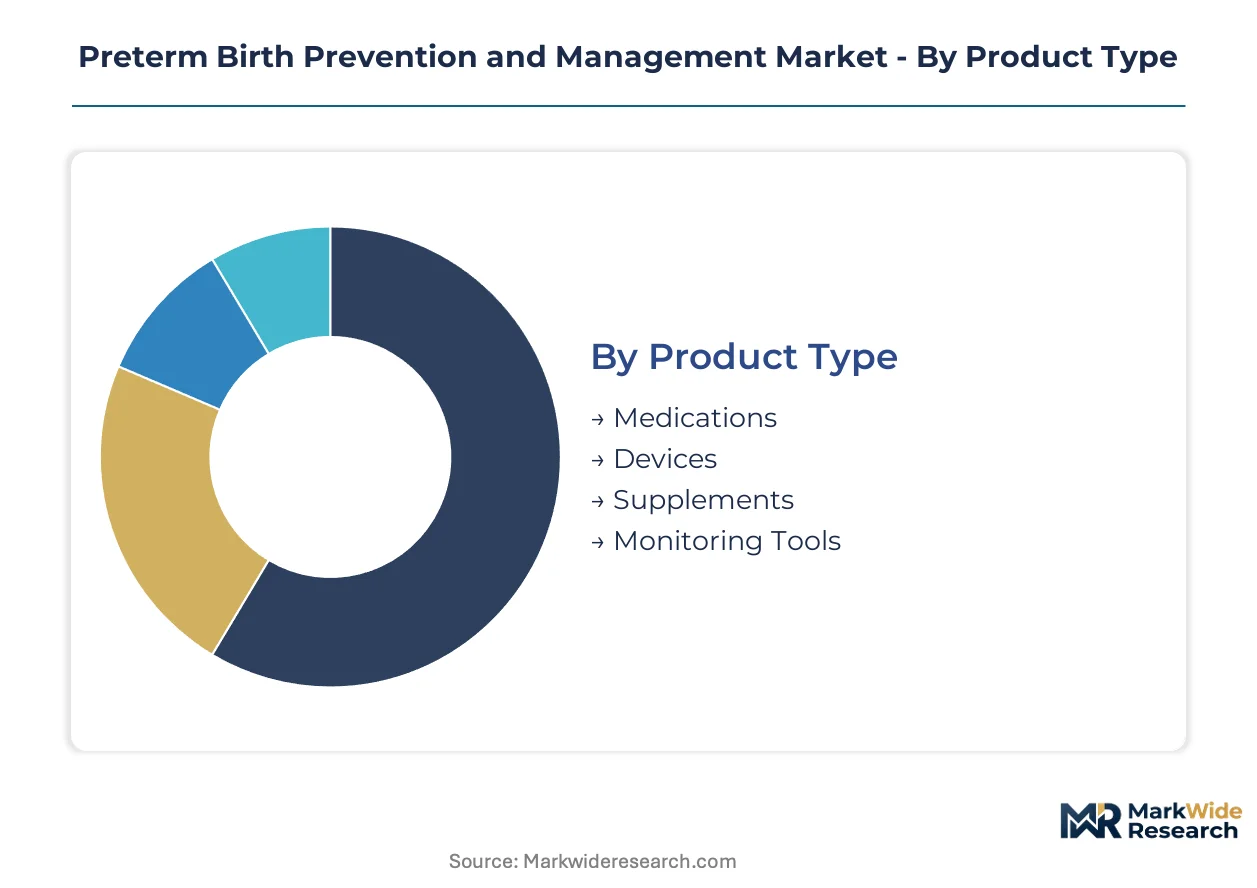
Preterm birth prevention requires precise matching of intervention modality to risk profile and care setting. Segmentation reveals how FDA and EMA approval pathways diverge across hormonal, mechanical, and diagnostic categories, shaping vendor specialization and procurement patterns.
Product Type:
FDA 505(b)(2) pathways dominate medications and devices, while monitoring tools face 510(k) clearance or de novo classification depending on algorithm complexity; supplements occupy a regulatory gray zone with DSHEA compliance rather than premarket approval.
- Medications:Hydroxyprogesterone caproate formulations and tocolytic agents constitute the revenue core. Hospital systems in Texas and California negotiate multi-year supply agreements for these hormonal therapies, though Medicaid reimbursement variance across states complicates national pricing.
- Devices:Cervical pessaries and cerclage systems require PMA or 510(k) clearance depending on material composition and duration of implantation. Academic medical centers drive specification standards, particularly for silicone-based pessary designs with extended wear protocols.
- Supplements:Omega-3 fatty acids and vitamin D formulations fall under dietary supplement regulations with substantiation requirements but no premarket approval burden.
- Monitoring Tools:Fetal fibronectin assays and emerging proteomic platforms embed into early-screening protocols, with CLIA-waived point-of-care versions expanding into community settings.
Leading the category by volume: Medications. Growing fastest: Monitoring Tools.
Therapy Area:
Cost tiers separate branded hormonal injections from generic alternatives and non-pharmacological interventions, with reimbursement intensity directly tracking clinical evidence strength.
- Hormonal Treatments:Intramuscular hydroxyprogesterone caproate remains the standard of care for singleton pregnancies with prior preterm birth. Medicaid expansion states show prescription concentration, particularly where managed care plans bundle maternal risk services.
- Antimicrobial Therapy:Antibiotic prophylaxis targets bacterial vaginosis and urinary tract infections as secondary prevention. Obstetric practices in Florida and Georgia incorporate screening into routine prenatal protocols.
- Lifestyle Modifications:Smoking cessation and activity restriction programs carry minimal direct cost but require behavioral health infrastructure that concentrates in integrated delivery networks.
- Nutritional Support:Prenatal vitamin optimization and specialized dietary counseling occupy the lowest reimbursement tier, with variable coverage across commercial and public payers.
Highest reimbursement intensity: Hormonal Treatments. Steepest expansion trajectory: Antimicrobial Therapy as microbiome research advances.
Delivery Mode:
Patient compliance and pharmacokinetic requirements dictate route selection, with injectable formulations commanding premium pricing despite adherence challenges.
- Injectable:Weekly intramuscular hydroxyprogesterone administration dominates prophylactic protocols. Home health nursing services in Illinois and Ohio have developed specialized programs to support adherence.
- Oral:Nifedipine and other tocolytics offer acute preterm labor management with immediate onset. Emergency departments and labor units stock oral formulations for rapid deployment.
- Intravenous:Magnesium sulfate for neuroprotection and acute tocolysis requires inpatient monitoring, limiting use to hospital settings with maternal-fetal medicine coverage.
- Transdermal:Nitroglycerin patches and emerging hormonal delivery systems remain niche, with patch adhesion challenges in pregnant populations constraining adoption.
Dominant by prescription volume: Injectable. Gaining share fastest: Oral as outpatient management protocols expand.
End User:
Care setting determines intervention complexity and reimbursement mechanism, with risk-stratification algorithms increasingly routing patients across the continuum.
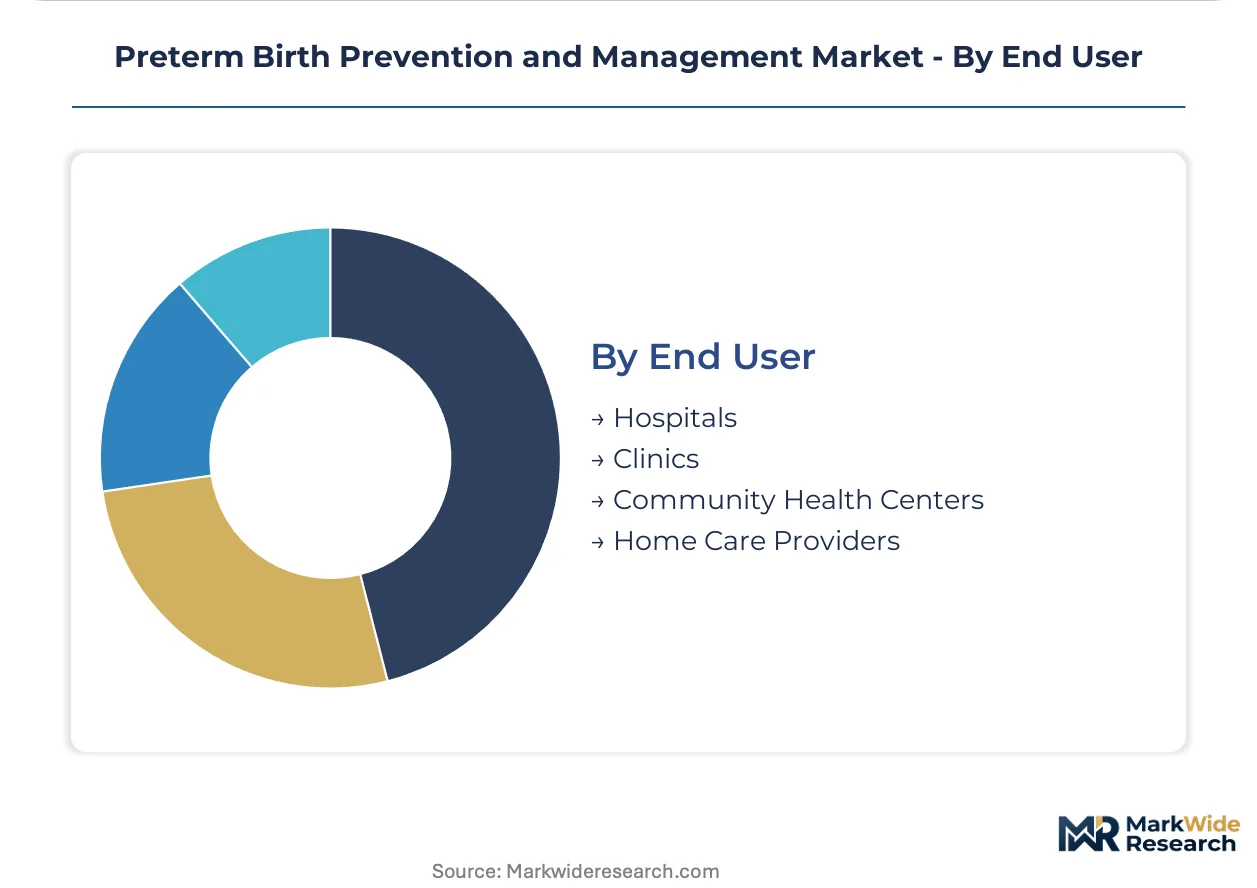
- Hospitals:Integrated labor-and-delivery units manage acute preterm labor, cerclage placement, and high-risk antepartum admissions. Academic centers in Massachusetts and North Carolina anchor referral networks for complex cases.
- Clinics:Obstetric practices handle routine prophylactic prescriptions and cervical length monitoring. Federally qualified health centers in expansion states have scaled progesterone access.
- Community Health Centers:Frontline prenatal care sites with limited specialist backup rely on telemedicine links to maternal-fetal medicine hubs for risk consultation.
- Home Care Providers:Remote uterine activity monitoring and injectable medication administration are emerging channels, with reimbursement frameworks still fragmenting across state Medicaid programs.
Capturing largest patient volume: Hospitals. Expanding most quickly: Home Care Providers as remote monitoring technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicaid expansion zones in the United States have concentrated maternal-fetal medicine infrastructure, while European perinatal networks and Asia-Pacific government health programs shape parallel development corridors for preterm birth interventions.
United States
Integrated perinatal networks in Texas and California drive demand for risk-stratified progesterone protocols. The FDA's evolving obstetric drug development guidance mandates composite neonatal endpoints, extending trial timelines for novel tocolytics. Academic medical centers in North Carolina and Massachusetts anchor referral networks for complex cerclage procedures.
Germany
EMA pediatric investigation plans harmonize neonatal outcome requirements with US trials, accelerating market access for hormonal therapies. The country's statutory health insurance system reimburses cervical length monitoring through standardized maternal care pathways. Berlin and Munich host concentration of perinatal research consortia developing biomarker-based screening algorithms.
United Kingdom
NHS England's maternity transformation program bundles preterm prevention into integrated care systems across London and the Midlands. The Medicines and Healthcare products Regulatory Agency aligns with EMA guidance on obstetric trial design. Manchester and Birmingham health systems pilot digital risk-prediction tools embedded in electronic health records.
Japan
PMDA consultation procedures for obstetric indications emphasize long-term neonatal follow-up data. METI funding supports domestic manufacturing of hydroxyprogesterone active pharmaceutical ingredients. Tokyo and Osaka medical centers concentrate specialist capacity for high-risk antepartum management.
Australia
TGA approval pathways for preterm interventions require Australian-specific neonatal outcome data despite international trial participation. State-based perinatal data collections in New South Wales and Victoria enable population-level risk algorithm validation. Sydney and Melbourne academic hospitals lead multicenter studies on cervical pessary effectiveness.
Preterm Birth Prevention and Management Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the preterm birth prevention landscape. The market structure concentrates revenue among pharmaceutical manufacturers with established hormonal therapy portfolios and diagnostic developers with biomarker platforms. Three archetypes dominate: multinational drug makers with manufacturing scale, specialized reproductive health firms with regulatory expertise in obstetric indications, and precision diagnostics companies with proteomic assay capabilities. Competitive moves center on service bundling contracts with integrated delivery networks and strategic partnerships to combine pharmaceutical and diagnostic offerings.
Among diversified pharmaceutical manufacturers, Pfizer Inc. and Novartis AG occupy positions defined by manufacturing breadth across multiple therapeutic delivery formats. Covis Pharma GmbH exemplifies the specialized reproductive health archetype with concentrated focus on branded hormonal formulations. Sera Prognostics represents the precision diagnostics vector, anchoring biomarker-based risk prediction within early-screening protocols. These three patterns illustrate how competitive positioning separates scale-driven supply from indication-specific regulatory depth and algorithm-driven personalization.
| Leading Market Players |
|---|
| Teva Pharmaceuticals USA, Inc. |
| Covis Pharma GmbH |
| Pfizer Inc. |
| AbbVie Inc. |
| Bayer AG |
| Novartis AG |
| Ferring B.V. |
| Sera Prognostics |
| Sanofi S.A. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up contract manufacturers of hydroxyprogesterone active pharmaceutical ingredients exert outsized influence on both supply allocation and pricing discipline across branded and generic hormonal therapy segments. Their consolidated ownership structures enable coordinated capacity management that buffers margin erosion even as Medicaid reimbursement variance intensifies buyer price sensitivity.
Pricing Analysis
Margin tightening in injectable hormonal therapies reflects Medicaid fee schedule compression across expansion states and the concentration of hydroxyprogesterone API production. Three-tier pricing structure across innovator-branded, authorized-generic, and compounding-pharmacy formulations separates reimbursement tiers. Price differentiation rests on FDA approval status and FDA Risk Evaluation and Mitigation Strategy compliance. Hospital procurement offices demonstrate highest price sensitivity due to bundled contract obligations, while specialty maternal-fetal medicine practices exhibit lowest sensitivity where clinical protocol adherence overrides cost considerations.
Supply Chain Analysis
Dual-sourcing requirements mandated by hospital procurement offices for critical tocolytic agents have reshaped supplier qualification protocols across the industry. API manufacturing concentrates in the United States, Italy, and India for hormonal therapies, while device components source from Germany and China. Raw material dependencies include 17-alpha-hydroxyprogesterone, specialized silicone elastomers for pessary manufacture, and recombinant protein substrates for biomarker assays. Single-source vulnerability in hydroxyprogesterone API creates supply risk given the three-manufacturer concentration. Distribution runs through specialty pharmaceutical wholesalers with cold-chain capabilities for temperature-sensitive biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomarker-driven risk stratification platforms are displacing traditional cervical length ultrasound as the frontline screening modality, compressing the window for therapeutic intervention and rewiring procurement priorities across integrated delivery networks.
For Market Incumbents: Anticipate diagnostic substitution pressure from proteomic assay developers by deepening integration of Sera Prognostics-style algorithms into existing service bundling contracts. Prioritize backward integration into CLIA-waived point-of-care manufacturing to defend channel position against remote monitoring entrants. Secure capacity commitments from the three hydroxyprogesterone API manufacturers through multi-year offtake agreements.
For New Entrants and Emerging Players: Launch via telemedicine-enabled home care channels where state Medicaid programs are piloting remote uterine activity monitoring reimbursement. Target community health centers in Medicaid expansion states as the most penetrable endpoint, given their limited specialist backup and reliance on telemedicine links to maternal-fetal medicine hubs. Position around per-patient episode pricing models that align with accountable care organization expenditure predictability requirements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision diagnostics developers with FDA-cleared proteomic platforms and established CLIA laboratory infrastructure in the United States. Long-term viability in this market hinges on owning the risk-stratification layer that determines therapeutic routing. Monitor FDA guidance evolution on composite neonatal outcome endpoints as the critical inflection signal for tocolytic development economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Platform Integration | Embedding proteomic risk scores into EHR systems at Texas and California health systems compresses screening-to-intervention windows. |
| Service Bundling Contract Expansion | Per-patient episode pricing with Medicaid managed care plans in Illinois and Ohio locks out discrete pharmaceutical competitors. |
| API Manufacturing Security | Captive supply agreements with Italian and Indian contract manufacturers buffer hydroxyprogesterone shortage vulnerability. |
| Remote Monitoring Reimbursement Strategy | State-by-state Medicaid telehealth policy navigation determines home-based monitoring channel viability. |
| EMA Pediatric Investigation Alignment | Harmonized neonatal outcome studies accelerate European market access for US-approved hormonal therapies. |
Study Parameters
Multi-period observation of FDA 505(b)(2) approval pathways, state Medicaid formulary inclusion timelines, and biomarker assay adoption curves anchored the trend analysis, supplemented by interviews with maternal-fetal medicine specialists, hospital pharmacy directors, GPO contracts managers, and reproductive health regulatory consultants. Secondary validation drew from FDA Center for Drug Evaluation and Research guidance documents, CMS Medicare and Medicaid data, ClinicalTrials.gov obstetric trial registries, and EMA pediatric investigation plan submissions. Bottom-up prescription volume modeling and top-down expenditure flow analysis were triangulated against integrated delivery network procurement database extracts.
Segment-weighting approaches applied differential growth coefficients across therapy modalities, with hormonal treatments, antimicrobial prophylaxis, and monitoring tools each assigned distinct trajectory assumptions across the projection horizon. Administration route, care setting, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from fitted adoption curves for biomarker platforms and elasticity-adjusted prescription volumes for established hormonal therapies. Forecast inputs included maternal-fetal medicine specialist workforce projections and state-level Medicaid expansion policy momentum.
Regulatory guidance revision, API supply disruption, and diagnostic substitution acceleration are the dominant revision risks to the outlook. Deviation in FDA obstetric trial endpoint requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
United States Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Perinatal Software Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Neonatal Critical Care Equipment Market