
 Natural Wax Emulsion Market | 2026-2036
Natural Wax Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Wax Emulsion Market Analysis
Indonesia is fragmenting as a production base for natural wax emulsions, with local processors expanding candelilla and soy wax refining to serve ASEAN coating formulators. Evonik Industries AG leverages its surfactant technology leadership to control high-performance dispersion quality for automotive OEM clearcoats. Croda International Plc anchors its position through backward integration into botanical wax sourcing, ensuring supply security for personal care grade emulsions. BASF SE competes on manufacturing scale, operating integrated aqueous wax lines that feed construction and packaging adhesive segments across Europe.
Natural wax emulsion denotes a stable aqueous dispersion of plant or animal-derived wax particles, typically stabilized by non-ionic surfactants at particle sizes below five microns, manufactured through high-pressure homogenization or phase-inversion processes to impart water resistance, gloss, and barrier properties to substrate coatings. Carnauba wax dominates premium coating applications where hardness and high-gloss finish are specified, while soy wax emulsions represent the fastest-growing product type due to cost positioning and abundant North American oilseed supply. The liquid form category captures the majority of volume, though paste formulations command margin pools in cosmetic and specialty adhesive niches where precise viscosity control justifies higher unit economics.
REACH registration requirements and the EU F-Gas Regulation constrain petrochemical solvent alternatives, directly expanding addressable demand for aqueous natural wax systems in European industrial coatings. The US EPA and FDA maintain distinct but overlapping jurisdiction, with EPA VOC rules pushing architectural coating reformulation while FDA food-contact approvals gate wax emulsion use in food packaging applications. Stakeholders must monitor evolving bio-based content certification schemes, as these standards will increasingly determine qualification for public procurement and premium private-label supply contracts.
Market Dynamics
Automotive OEMs and wood coating manufacturers are consolidating procurement around aqueous bio-based systems, compressing solvent-borne wax demand as REACH VOC ceilings harden across European formulation facilities.
Growth Catalysts
- REACH VOC limits:ECHA enforcement of volatile organic compound thresholds in industrial coatings redirects formulation spend toward plant-derived wax dispersions. Coating houses in Germany and the Netherlands accelerate aqueous system qualification.
- North American soy wax supply:Abundant oilseed processing infrastructure enables cost-competitive emulsion feedstock for packaging adhesives and construction sealants. Domestic crushing capacity expansion supports regional formulator security.
- Automotive clearcoat specifications:Premium vehicle finish requirements for hardness and gloss drive carnauba wax emulsion uptake in OEM coating lines. Tier-1 suppliers specify aqueous dispersion compatibility with electrocoat primer systems.
Market Restraints
- Carnauba harvest concentration:Brazilian northeast drought cycles create raw material availability volatility. Northeastern Piauí and Ceará state harvest disruptions propagate through specialty coating supply chains.
- Petrochemical wax price arbitrage:Paraffin and microcrystalline wax derivatives maintain cost advantage in mass-market packaging applications. Price-sensitive adhesive formulators resist bio-premium absorption.
- High-pressure homogenization capex:Sub-five-micron particle size requirements demand capital-intensive processing equipment. Mid-scale emulsion producers face capacity expansion barriers against integrated chemical majors.
Strategic Opportunities
- Indonesian candelilla processing:Local refiners in Java and Sumatra are scaling botanical wax capacity to serve ASEAN coating formulators. Proximity to Singapore and Malaysia distribution hubs reduces landed cost for regional buyers.
- FDA food-contact pathway:Wax emulsion approvals for direct food packaging applications remain underpenetrated relative to coating volumes. Early movers in paperboard barrier coatings capture premium positioning.
- Construction adhesive convergence:Hybrid formulations combining natural wax emulsions with silane-modified polymers address green building certification requirements. LEED and BREEAM point systems reward bio-based content thresholds.
Industry Challenges
- Surfactant stabilization expertise:Non-ionic emulsifier selection and phase-inversion protocol optimization require specialized formulation chemists. Talent scarcity constrains mid-tier producers attempting premium grade qualification.
- Bio-based certification fragmentation:Competing USDA BioPreferred, EU Ecolabel, and ISO 16620 standards create compliance complexity. Multi-market suppliers face redundant testing and documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Wax Emulsion Market |
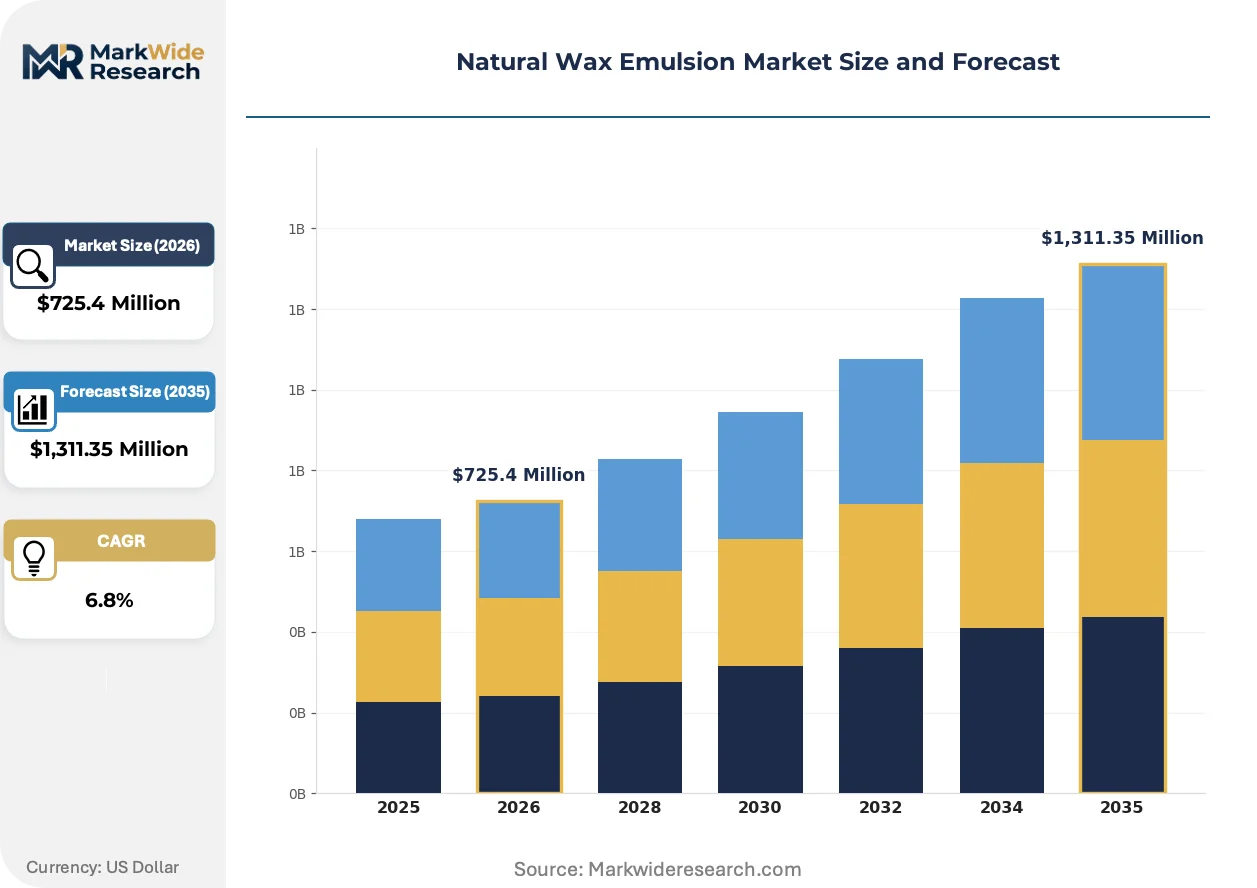
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,311.35 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beeswax, Carnauba Wax, Candelilla Wax, Soy Wax Application: Coatings, Cosmetics, Adhesives, Textiles End User: Personal Care, Automotive, Packaging, Construction Form: Liquid, Paste, Solid, Gel |
| Companies Covered | Evonik Industries AG, ALTANA AG, Croda International Plc, The Lubrizol Corporation, Sasol Limited, BASF SE, Arkema S.A., Henkel AG & Co. KGaA, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Wax Emulsion Market Emerging Trajectories
Formulation chemistry is pivoting toward cold-process emulsification and bio-surfactant stabilization, collapsing energy intensity while expanding feedstock flexibility beyond traditional tropical wax sources.
High-shear homogenization is migrating from batch tank systems to continuous inline processing, enabling real-time particle size distribution control. Coating manufacturers in Germany and the US Midwest are retrofitting existing lines with modular homogenizer skids. This equipment shift compresses capital deployment timelines and reduces batch-to-batch quality variance for automotive clearcoat suppliers.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon blowing agents in insulation foams, indirectly expanding natural wax emulsion demand as water-resistant barrier alternatives in construction membranes. Building envelope specialists in France and the Netherlands specify aqueous wax systems for breathable moisture control layers. The regulatory pressure is accelerating reformulation R&D spend among European adhesive compounders.
Direct mill-base integration is replacing pre-dispersed wax concentrate procurement among large coating houses. Automotive OEMs in Stuttgart and Detroit now specify in-line emulsion addition at the let-down stage, compressing logistics cost and enabling just-in-time viscosity adjustment. This integration pattern concentrates volume with suppliers capable of bulk tanker delivery and technical service co-location.
Natural Wax Emulsion Market Segmentation
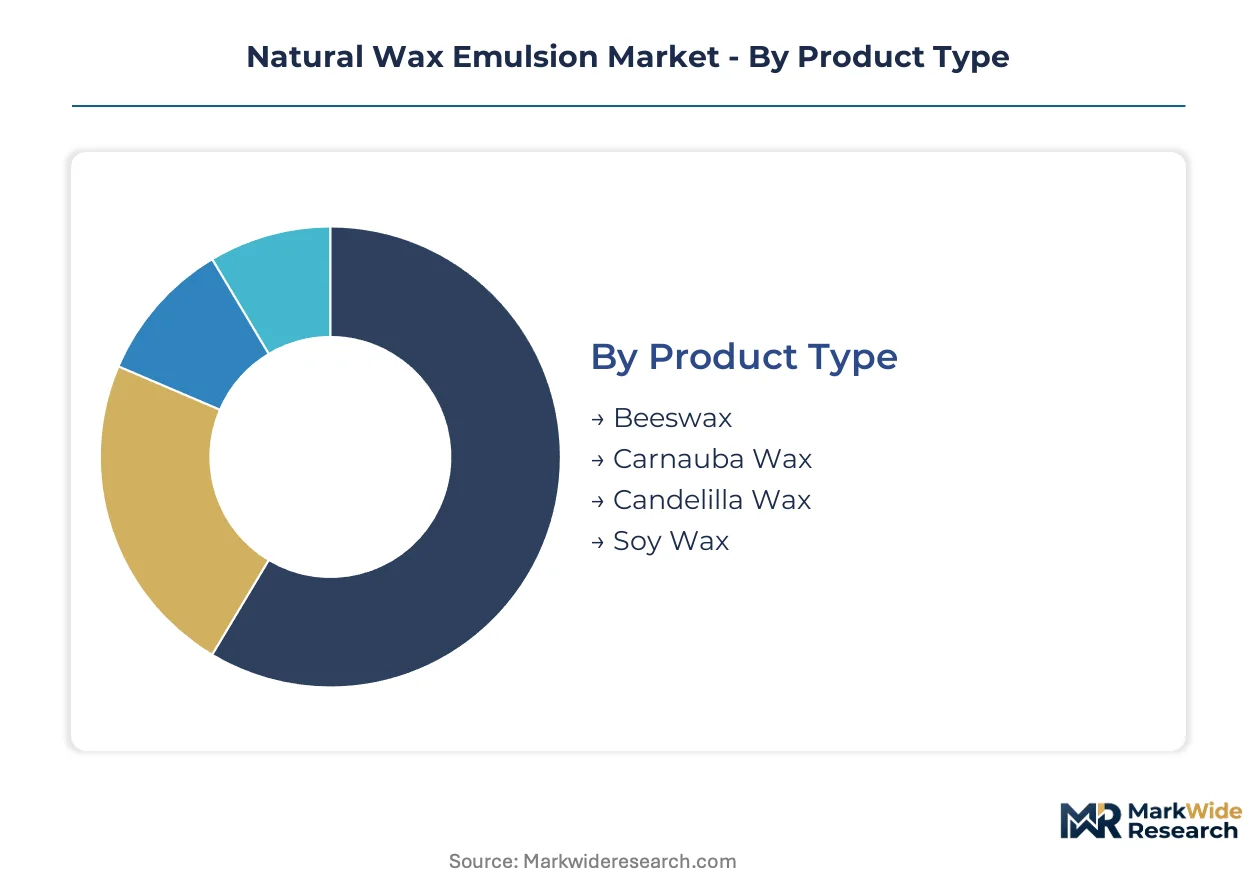
Natural wax emulsion procurement patterns diverge sharply across feedstock chemistry and physical form, with coating formulators prioritizing hardness specifications while cosmetic compounders emphasize sensory properties and regulatory clearance speed.
Product Type:
Carnauba wax commands the longest production cycles due to Brazilian harvest seasonality, while soy wax turns inventory fastest through continuous North American oilseed processing.
- Carnauba Wax:Extracted from Copernicia prunifera palm fronds, this hardest natural wax delivers premium gloss and scratch resistance specifications. German automotive OEM clearcoat lines specify carnauba for electrocoat compatibility, though northeastern Brazilian drought cycles constrain supply security.
- Soy Wax:Hydrogenated soybean oil derivatives offer cost positioning against tropical wax imports. US Midwest crushing capacity expansion supports packaging adhesive formulators seeking bio-based content thresholds without carnauba premium absorption.
- Beeswax:Secreted by Apis mellifera colonies, this animal-derived emulsion provides film-forming plasticity for cosmetic balms and leather conditioners.
- Candelilla Wax:Extracted from Euphorbia antisyphilitica shrubs, this brittle vegetable wax serves furniture polish and chewing gum glaze applications.
Carnauba dominates installed base. Soy wax is where expansion concentrates.
Application:
Coatings generate the highest volume throughput with standardized automotive specifications, whereas cosmetics demand the most fragmented SKU proliferation.
- Coatings:Aqueous wax dispersions provide water resistance and gloss control for wood finishing and automotive clearcoats. REACH VOC ceilings in Germany and the Netherlands accelerate aqueous system qualification against solvent-borne alternatives.
- Cosmetics:Emulsion stability and skin-feel drive formulation chemist selection between carnauba hardness and beeswax plasticity. EU Ecolabel and USDA BioPreferred certification schemes determine premium private-label contract eligibility.
- Adhesives:Natural wax emulsions modify hot-melt viscosity and open time for packaging and construction applications.
- Textiles:Water-repellent finishes on technical fabrics employ paraffin-natural wax blends for breathability balance.
Coatings anchor volume concentration. Cosmetics command the steepest expansion trajectory.
End User:
Automotive procurement operates on multi-year platform contracts with frozen specifications, while personal care brands reformulate seasonally chasing ingredient marketing trends.
- Automotive:OEM clearcoat specifications demand sub-five-micron particle size distribution and electrocoat primer compatibility. Stuttgart and Detroit coating lines specify in-line emulsion addition at let-down stage.
- Personal Care:Skin-feel, stability, and clean-label positioning drive wax emulsion selection for color cosmetics and hair care. Croda International Plc secures botanical wax supply through backward integration.
- Packaging:FDA food-contact approvals gate wax emulsion use in paperboard barrier coatings, with approvals remaining underpenetrated relative to industrial coating volumes.
- Construction:Hybrid formulations combining natural wax emulsions with silane-modified polymers address LEED and BREEAM green building certification requirements.
Automotive locks in long-term supply agreements. Personal care is where SKU proliferation accelerates.
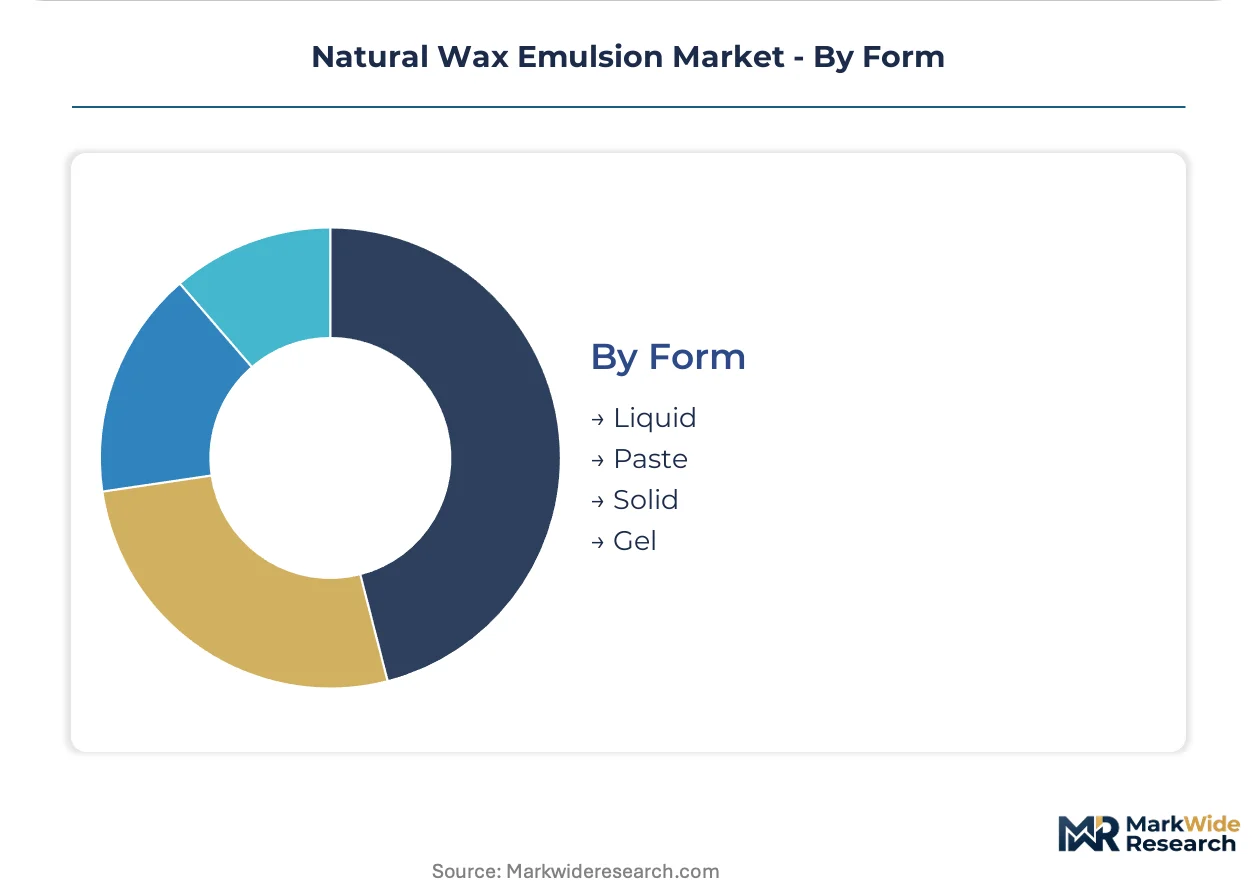
Form:
Liquid emulsions flow through automated dosing equipment fastest, while paste forms require heated storage but enable precise viscosity control.
- Liquid:Stable aqueous dispersions below five microns feed automated coating lines and cosmetic manufacturing. Bulk tanker delivery concentrates volume with suppliers capable of technical service co-location.
- Paste:Higher solids content enables precise viscosity adjustment in cosmetic compounding and specialty adhesive niches. Higher unit economics justify heated storage infrastructure.
- Solid:Flaked or pelletized wax requires downstream emulsification but offers logistics flexibility for regional processors.
- Gel:Thixotropic formulations serve niche pharmaceutical and personal care applications requiring suspension stability.
Liquid captures throughput concentration. Paste commands margin pool expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA enforcement of REACH VOC ceilings anchors European demand redirection toward aqueous natural wax systems. Specialty chemical producers in Germany and the Netherlands are scaling aqueous wax capacity to serve pan-European coating makers.
Germany
Automotive OEM clearcoat specifications and wood finishing applications drive formulation spend toward plant-derived wax dispersions. REACH registration requirements and EU Green Deal mandates harden VOC ceilings across industrial coating facilities. Stuttgart coating lines specify in-line emulsion addition at let-down stage, concentrating volume with suppliers capable of bulk tanker delivery.
United States
Packaging adhesive formulators and construction sealant manufacturers seek cost-competitive emulsion feedstock from abundant North American oilseed supply. EPA VOC rules push architectural coating reformulation while FDA food-contact approvals gate wax emulsion use in food packaging applications. Domestic crushing capacity expansion in the US Midwest supports regional formulator security.
Brazil
Carnauba wax harvest concentration in northeastern Piauí and Ceará states creates raw material availability volatility for premium coating applications. Brazilian northeast drought cycles propagate through specialty coating supply chains. Local processors face supply security challenges as automotive OEMs specify hardness and high-gloss finish requirements.
Indonesia
Local refiners in Java and Sumatra are scaling candelilla and soy wax refining capacity to serve ASEAN coating formulators. Proximity to Singapore and Malaysia distribution hubs reduces landed cost for regional buyers. Indonesian processors are fragmenting as a production base for natural wax emulsions targeting pan-Asian adhesive and coating markets.
France
Building envelope specialists specify aqueous wax systems for breathable moisture control layers in construction membranes. EU F-Gas Regulation phase-down schedules eliminate hydrofluorocarbon blowing agents, indirectly expanding natural wax emulsion demand. French adhesive compounders accelerate reformulation R&D spend to address green building certification requirements.
Natural Wax Emulsion Market Vendor Landscape
Integrated chemical majors and specialty surfactant technology providers split the market between manufacturing scale and formulation expertise. The vendor base concentrates around aqueous dispersion quality control and botanical wax supply security. Three archetypes dominate: surfactant-technology leaders controlling high-performance dispersion quality, backward-integrated botanical wax sourcers ensuring supply security, and scale-driven integrated producers feeding construction and packaging segments. Capacity expansion and strategic partnerships constitute the dominant competitive moves as mid-scale emulsion producers face high-pressure homogenization capex barriers.
Within the surfactant-technology tier, Evonik Industries AG exemplifies high-performance dispersion quality control for automotive OEM clearcoats. Croda International Plc anchors the backward-integrated archetype through captive botanical wax sourcing for personal care grade emulsions. BASF SE occupies the scale-driven position with integrated aqueous wax lines feeding construction and packaging adhesive segments across Europe.
| Leading Market Players |
|---|
| Evonik Industries AG |
| ALTANA AG |
| Croda International Plc |
| The Lubrizol Corporation |
| Sasol Limited |
| BASF SE |
| Arkema S.A. |
| Henkel AG & Co. KGaA |
| Clariant AG |
| Others |
Supply Flow & Price Mechanics
Overcapacity in German aqueous wax processing lines is compressing margin pools for mid-scale emulsion producers while concentrating pricing power with integrated chemical majors capable of bulk tanker delivery and technical service co-location.
Pricing Analysis
Geographic price spreads between Brazilian carnauba-derived emulsions and North American soy wax alternatives run 15-25% at equivalent solids content, with tropical wax premiums reflecting harvest seasonality and northeastern drought risk. Three-tier pricing structure across premium carnauba, standard soy-blend, and economy petroleum-wax-replacement levels stratifies by certification grade and automotive OEM qualification status. Cost compression in mid-tier packaging adhesives is intensifying because petrochemical wax derivatives maintain arbitrage advantage for price-sensitive formulators. Volume buyers in construction sealants exhibit highest price sensitivity, while cosmetic compounders pursuing clean-label positioning absorb premium positioning with least resistance.
Supply Chain Analysis
Upstream feedstock sourcing draws from Brazilian northeast palm frond harvesting, US Midwest oilseed crushing infrastructure, and Indonesian candelilla shrub cultivation. Raw material dependencies center on surfactant stabilization chemistries, high-pressure homogenization equipment, and aqueous dispersion packaging formats. Single-source vulnerability concentrates in northeastern Piauí and Ceará state carnauba harvest zones, where drought cycles propagate availability shocks through premium coating supply chains. Distribution runs through regional chemical distributors in Germany and the Netherlands, with bulk tanker direct delivery consolidating volume at large automotive OEM coating houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural wax emulsion penetration sits at early-cycle expansion, with FDA food-contact pathway approvals remaining underpenetrated relative to industrial coating volumes and creating substantial runway for qualified suppliers.
For Market Incumbents: Entrench aqueous dispersion quality leadership through captive surfactant technology development and bulk tanker delivery infrastructure co-location at Stuttgart and Detroit automotive coating clusters. Backward integration into botanical wax sourcing secures supply security against Brazilian harvest volatility, while ECHA REACH registration maintenance gates competitor qualification timelines.
For New Entrants and Emerging Players: ASEAN coating formulators in Indonesia, Malaysia, and Singapore represent geographic underpenetration with reduced landed cost potential through Java and Sumatra refining proximity. FDA food-contact approvals for paperboard barrier coatings offer the most penetrable application segment, with early movers capturing premium positioning through direct technical service engagement at packaging converters.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-escalation play because REACH VOC ceilings and EU F-Gas Regulation phase-downs structurally expand addressable demand for aqueous bio-based systems regardless of petroleum wax price cycles. Acquisition targets should profile mid-scale emulsion producers with surfactant stabilization expertise and existing automotive OEM qualification. The signal to watch is ECHA enforcement intensity against solvent-borne coating facilities, which would accelerate aqueous system procurement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Wax Sourcing | Croda International Plc secures carnauba supply security for personal care grade emulsions against Brazilian drought cycles. |
| High-Pressure Homogenization Capacity Expansion | Evonik Industries AG controls sub-five-micron particle size distribution for automotive OEM clearcoat specifications. |
| FDA Food-Contact Approval Pathway Investment | Early movers in paperboard barrier coatings capture premium positioning at packaging converters seeking clean-label alternatives. |
| Technical Service Co-Location with Automotive OEMs | BASF SE concentrates volume through bulk tanker delivery and in-line emulsion addition at Stuttgart coating lines. |
| Indonesian Candelilla Processing Scale-Up | Local refiners in Java reduce landed cost for ASEAN coating formulators through proximity to Singapore distribution hubs. |
Methodological Framework
Operator-level perspectives from coating formulators, surfactant technology specialists, automotive OEM procurement teams, and botanical wax processors anchored the qualitative base. Primary interviews with plant managers at German and Dutch aqueous wax facilities, procurement leads at Tier 1 automotive suppliers, and distribution channel partners across Europe and North America combined with secondary validation from ECHA REACH registration databases, US EPA VOC rule filings, and customs trade data for wax emulsion imports. Bottom-up capacity estimates and top-down demand segmentation triangulated volume and value outputs.
Scenario-bracketing framed analytical work across the analysis window, with segmentation dimensions spanning feedstock chemistry, physical form, application vertical, and end-user industry. CAGRs derived from regression analysis against automotive production forecasts, construction spending indices, and cosmetic formulation trend data. Industry-specific inputs included Brazilian agricultural yield projections for carnauba harvest modeling and US soybean crushing capacity expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by integrated chemical majors or accelerated FDA approval timelines by specialty entrants would shift outcomes from base-case projections. Cross-checking against ECHA enforcement action databases and automotive OEM coating line qualification announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Micellar Water Market
Surfactants
MDEA Esterquats Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Wax Emulsion Market
Surfactants
Trisiloxane Market
Surfactants
Chlorooctane Market
Surfactants
Zeolite for Detergents Market
Surfactants
Anionic Surfactants Market
Surfactants
Tetrabutylammonium Bromide Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Benzyl Trimethyl Ammonium Chloride Market
Surfactants
Specialty Surfactants Market
Surfactants
Global Methyl Soyate Market
Surfactants
Sodium Lauroyl Sarcosinate Market
Surfactants
Soy-Based Surfactants Market
Surfactants
Global Fluorosurfactants Market