
 MDEA Esterquats Market | 2026-2036
MDEA Esterquats Market Size, Share, and Industry Trends Forecast 2026-2036
MDEA Esterquats Market Outlook
Personal care formulators is realigning MDEA esterquat procurement toward high-efficacy conditioning polymers. BASF SE leverages its integrated fatty acid supply chain to dominate European personal care grade production. Evonik Industries anchors its position through R&D intensity in esterquat modification chemistry. Stepan Company specializes in surfactant applications for North American household cleaning markets.
MDEA esterquats are quaternary ammonium compounds synthesized from methyldiethanolamine and fatty acid esters, typically containing C16-C18 alkyl chains that confer cationic charge density for surface adsorption. These compounds function primarily as fabric softeners, hair conditioners, and antistatic agents through electrostatic interaction with anionic substrates. The personal care segment leads value generation due to premium conditioning performance requirements, while industrial applications represent the fastest-growing category as metalworking and textile processors adopt low-foam antistatic formulations. Surfactant applications command the largest volume share, though emulsifier demand is accelerating in food-grade lubricant and coating systems.
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act govern antimicrobial esterquat claims in the United States, while REACH registration in Europe mandates full toxicological dossiers for C16-C18 quaternary ammonium substances. FDA oversight applies to incidental food-contact lubricant applications containing MDEA esterquat residues. Stakeholders must monitor evolving state-level restrictions on quaternary ammonium compounds in cleaning products, as California and New York are advancing disclosure and concentration limit frameworks that could reshape formulation strategies across multiple end-use segments.
Market Dynamics
REACH registration mandates for C16-C18 quaternary ammonium substances are restructuring formulation strategies across European personal care and industrial cleaning segments, compressing legacy product lifecycles while accelerating biodegradable esterquat R&D investment.
Growth Catalysts
- Biodegradability mandates:EPA surfactant standards in the United States are tightening discharge limits for quaternary ammonium compounds, pulling demand toward esterquat architectures with superior aquatic toxicity profiles.
- Metalworking fluid reformulation:Industrial processors in Germany are replacing traditional antistatic additives with low-foam MDEA esterquat variants to meet workplace exposure guidelines.
- Hair conditioning polymer advancement:Personal care formulators are expanding esterquat incorporation into rinse-off conditioners to achieve silicone-free detangling performance.
Market Restraints
- Fatty acid feedstock volatility:C16-C18 alkyl chain precursors track palm oil and tallow commodity swings, compressing margin stability for esterquat manufacturers without captive oleochemical supply.
- European supply concentration:Specialty chemical production clusters in Germany and the Netherlands create geographic vulnerability to regional energy cost spikes and logistics disruption.
- Amine-based substitute competition:Proprietary betaine and amidoamine chemistries from integrated surfactant houses are displacing esterquats in mid-tier fabric softener applications.
Strategic Opportunities
- Food-grade lubricant emulsifiers:FDA-regulated incidental food-contact applications represent an underpenetrated outlet for MDEA esterquat residues with compliant toxicological dossiers.
- India personal care expansion:BIS standards harmonization with REACH biodegradability protocols is opening formulation pathways for imported esterquat conditioning agents.
- Textile antistatic convergence:Integration of esterquat chemistry with fluorine-free durable water repellent finishes is creating hybrid functional finishing systems for technical fabrics.
Industry Challenges
- ECHA dossier compilation expertise:REACH registration requires specialized toxicological and ecotoxicological study design capabilities that mid-scale esterquat producers struggle to staff internally.
- Legacy quaternary ammonium decommissioning:Formulators face reformulation complexity when swapping dialkyl dimethyl ammonium chloride softener bases for esterquat alternatives in existing production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MDEA Esterquats Market |
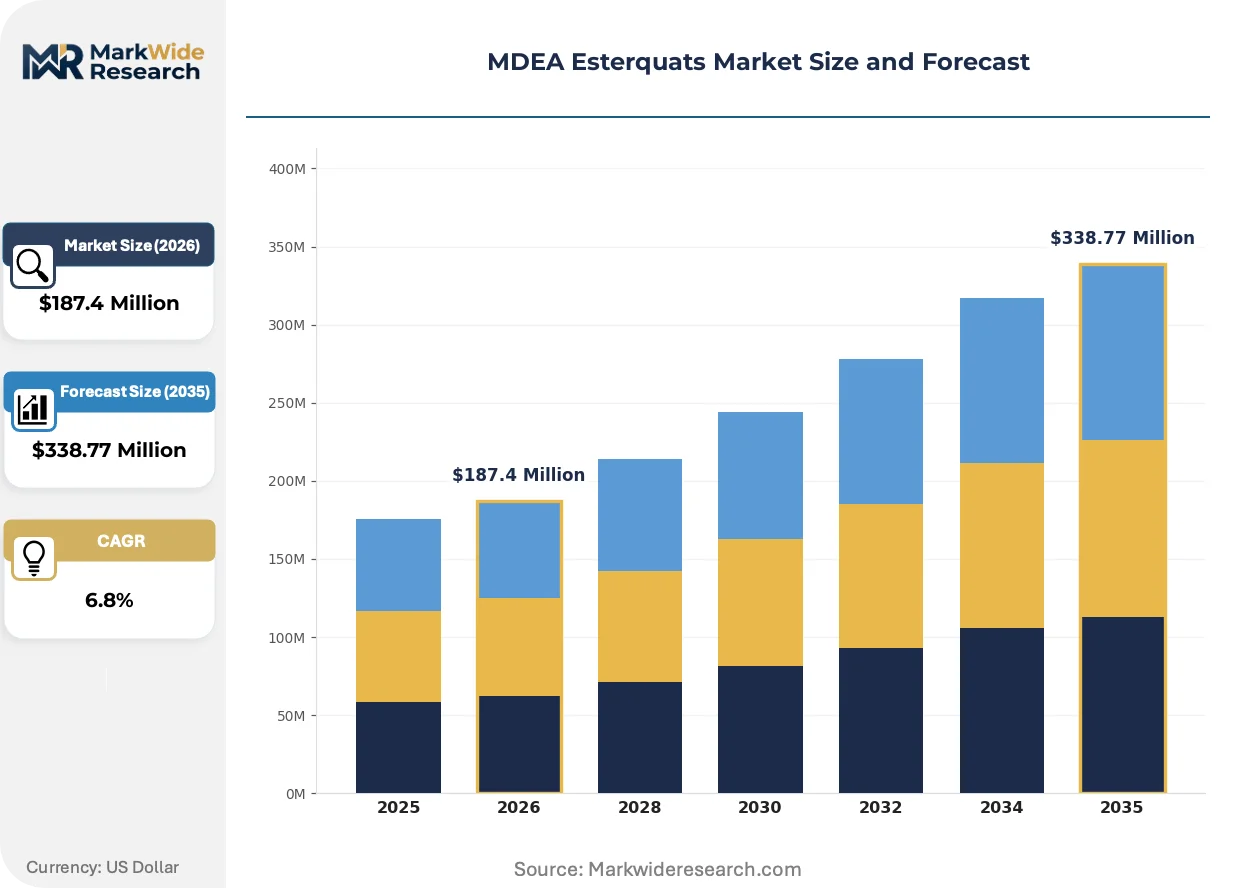
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Care, Household Cleaning, Industrial Applications, Textile Treatment Application: Surfactants, Antistatic Agents, Emulsifiers, Dispersants End User: Cosmetics Manufacturers, Cleaning Product Companies, Textile Industry, Food Processing Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale Suppliers |
| Companies Covered | BASF SE, Evonik Industries, Stepan Company, Kao Corporation, Akzo Nobel, Clariant, ABITEC Corporation, The Lubrizol Corporation, Italmatch Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MDEA Esterquats Market Strategic Shifts
Formulation chemistry is pivoting toward multifunctional esterquat architectures that merge conditioning performance with regulatory compliance, compressing the traditional trade-off between efficacy and biodegradability.
Esterquat variants with enhanced hydrolytic stability are consolidating market position in high-temperature metalworking and textile processing applications. Industrial formulators in Germany and the United States are adopting these grades at accelerating pace to replace conventional quaternary ammonium salts. The technology is consolidating supplier tiers by rewarding producers with integrated fatty acid supply chains and advanced esterification capabilities.
REACH Annex XVII restrictions on persistent organic pollutants are tightening impurity limits in quaternary ammonium compound registrations. ECHA guidance documents are forcing reformulation of legacy esterquat products containing residual dialkylamine precursors. Personal care segment manufacturers in France and Italy are responding by auditing supply chains for precursor contamination and accelerating substitution timelines.
Specification-driven procurement is replacing commodity spot purchasing in North American household cleaning channels. Large format retailers and contract manufacturers are consolidating supplier panels around esterquat producers with verified EPA Safer Choice and USDA BioPreferred certifications. The shift is most visible in California and New York, where state-level disclosure mandates are elevating transparency requirements above federal baselines.
MDEA Esterquats Market Segmentation
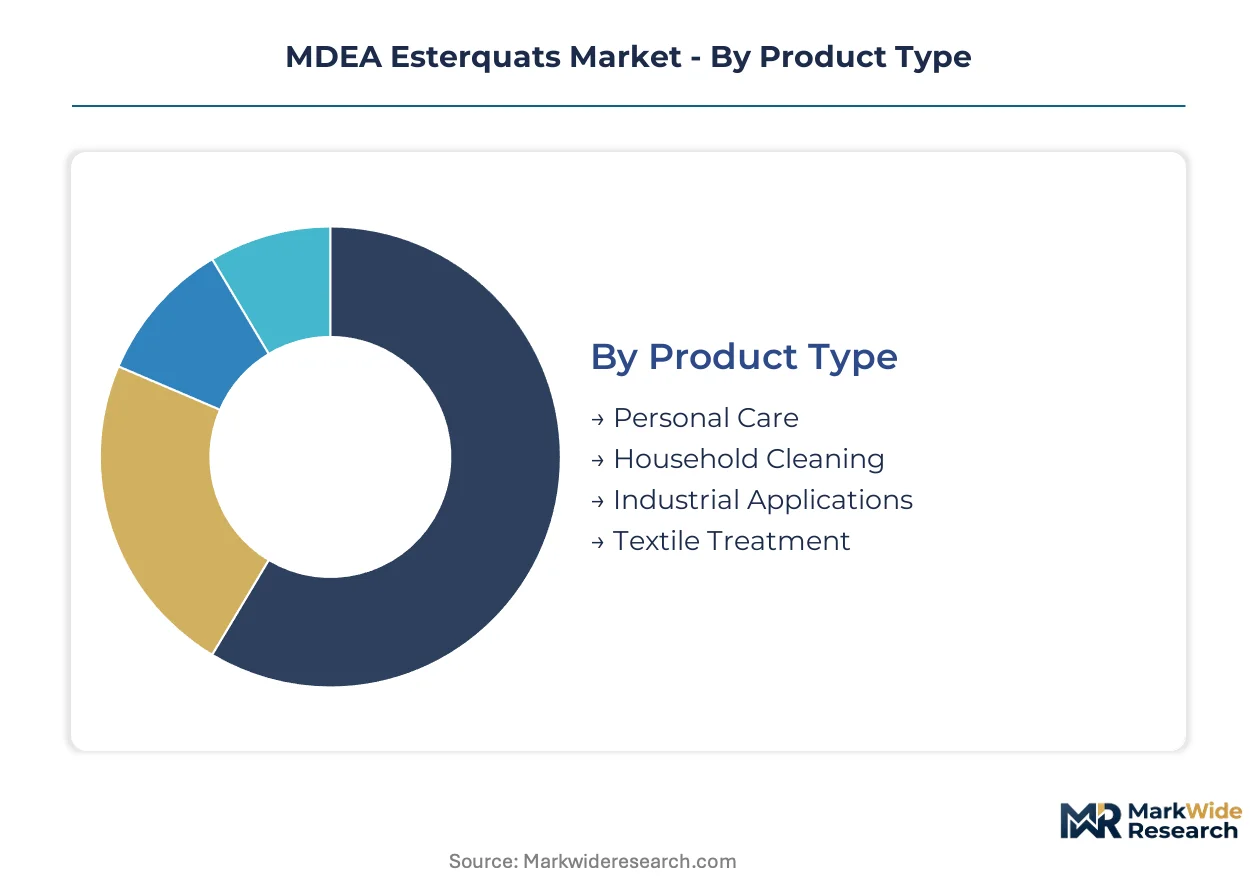
MDEA esterquat procurement patterns diverge sharply across end-use verticals, with personal care formulators prioritizing conditioning efficacy while industrial buyers emphasize hydrolytic stability and regulatory compliance. Understanding these segment-specific value drivers enables suppliers to align product architectures with buyer decision criteria rather than competing on commodity specifications.
Product Type:
Buyers in this market select product categories based on performance tier requirements and regulatory burden tolerance, with premium conditioning applications commanding stricter purity specifications than industrial formulations.
- Personal Care:High-purity esterquat grades with enhanced cationic charge density serve silicone-free hair conditioner formulations. French and Italian cosmetics manufacturers are expanding procurement of these grades to meet REACH Annex XVII impurity limits while maintaining detangling performance benchmarks.
- Industrial Applications:Low-foam MDEA esterquat variants with improved thermal stability replace conventional quaternary ammonium salts in metalworking fluids. German automotive parts processors are driving specification tightening for workplace exposure compliance.
- Household Cleaning:Standard-grade esterquats function as fabric softener bases in liquid and sheet formulations. Large-format retailers in California and New York are consolidating supplier panels around EPA Safer Choice certified producers.
- Textile Treatment:Hybrid esterquat chemistries integrate with fluorine-free durable water repellent systems for technical fabric finishing. Demand concentrates in German technical textile clusters serving automotive and medical end-uses.
Volume sits with Household Cleaning; growth tilts toward Personal Care.
Application:
Application selection tracks functional requirements across surface-active performance, with surfactant dominance giving way to specialized emulsifier demand in food-contact regulated environments.
- Surfactants:Cationic surface-active properties enable fabric softening and hair conditioning through electrostatic substrate interaction. North American household cleaning channels represent the primary volume outlet, though specification-driven procurement is compressing spot-market participation.
- Emulsifiers:Food-grade lubricant applications require MDEA esterquat residues with FDA-compliant toxicological dossiers for incidental food-contact scenarios. This application is expanding most quickly as food processing equipment manufacturers reformulate away from mineral oil-based systems.
- Antistatic Agents:Low-resistance surface modification for synthetic textiles and polymer films. Textile processors in Germany are adopting hydrolytically stable grades for high-temperature finishing lines.
- Dispersants:Particle suspension in aqueous and non-aqueous media for coatings and pigment systems. Niche demand from specialty chemical formulators with proprietary dispersion requirements.
Surfactants dominate current procurement volumes; emulsifiers are climbing the fastest on regulatory tailwinds.
End User:
End-user concentration reflects downstream industry structure, with cosmetics and cleaning product manufacturers exhibiting divergent supplier relationship models—specification partnerships versus volume contracting.
- Cosmetics Manufacturers:Premium personal care brands in France, Italy, and Germany audit supply chains for REACH precursor compliance. These buyers prioritize conditioning performance validation and regulatory documentation over unit cost optimization.
- Cleaning Product Companies:Contract manufacturers and branded houses in North America consolidate supplier panels around certified producers. California disclosure mandates and New York concentration limits are reshaping formulation sourcing strategies.
- Textile Industry:Technical fabric finishers and synthetic fiber producers require antistatic and softening functionality. German automotive textile suppliers are leading adoption of hybrid esterquat-durable water repellent systems.
- Food Processing:Equipment lubricant formulators and food-grade coating manufacturers represent an underpenetrated outlet. FDA oversight of incidental food-contact residues creates barrier-to-entry for non-dossier-compliant producers.
Cleaning Product Companies anchor volume demand; Cosmetics Manufacturers are gaining share fastest on premium conditioning polymer advancement.
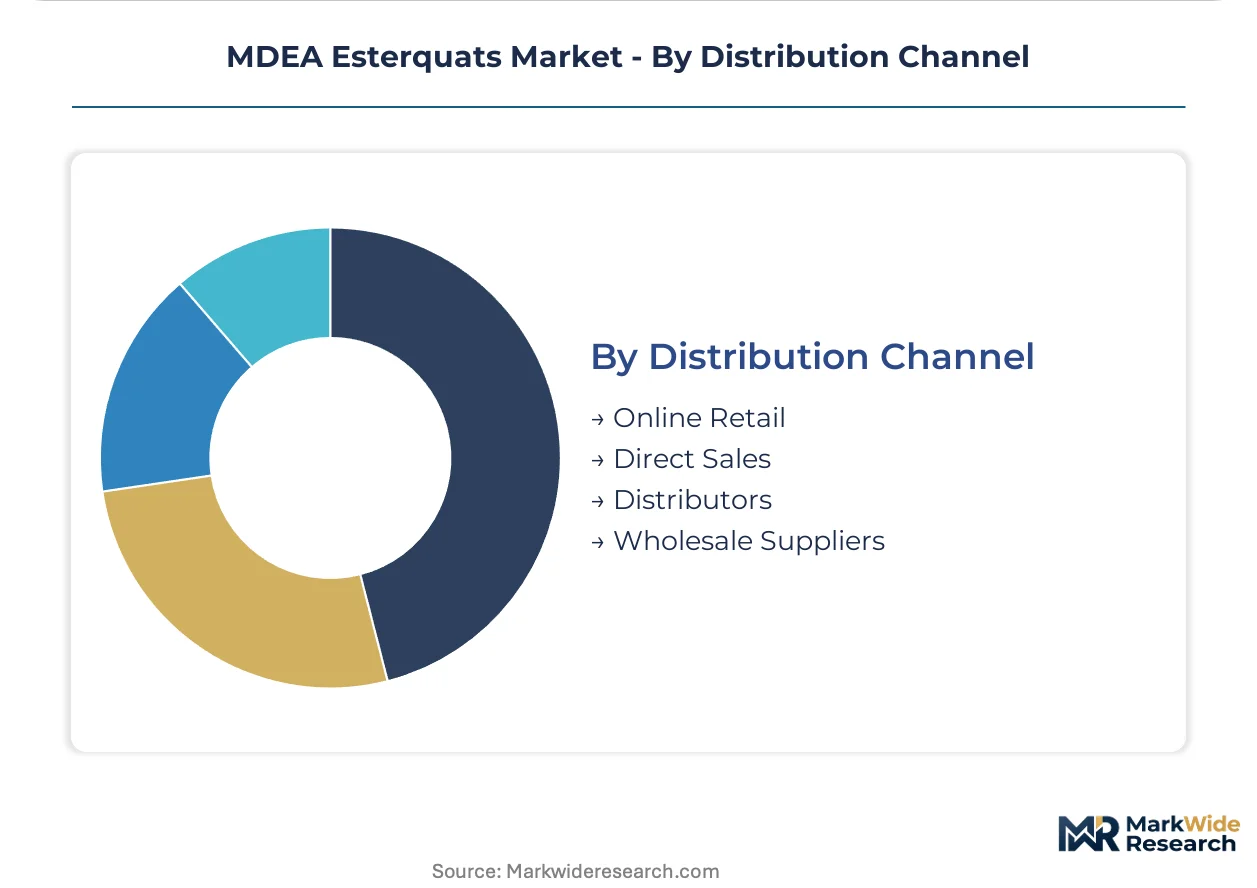
Distribution Channel:
Channel selection correlates with buyer scale and specification complexity, with direct relationships dominating technically demanding applications and distributor networks serving fragmented regional demand.
- Direct Sales:Technical partnership models for personal care and industrial formulators requiring customized esterquat modifications. BASF SE and Evonik Industries leverage integrated supply chains to serve large-scale European cosmetics manufacturers through dedicated account structures.
- Distributors:Regional chemical distributors with formulation technical support capabilities serve mid-tier cleaning product and textile processing accounts. German and Dutch specialty chemical distribution clusters concentrate inventory for just-in-time delivery.
- Wholesale Suppliers:Volume-based procurement for standard-grade fabric softener and household cleaning applications. Price-sensitive buyers in North American mass-market channels favor this route.
- Online Retail:Emerging channel for small-scale formulators and research quantities. Limited current penetration due to hazmat shipping constraints and technical consultation requirements.
Direct Sales commands premium segment value; Distributors are expanding most quickly as mid-tier formulators seek technical support integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical parks in Ludwigshafen and Marl concentrate European MDEA esterquat capacity through tax-advantaged zones that offset energy-intensive esterification costs. Specialty chemical producers leverage these locations to serve REACH-compliant personal care and industrial cleaning demand.
Germany
Personal care formulators in Hamburg and Düsseldorf drive premium-grade procurement for silicone-free hair conditioners. ECHA REACH registration mandates for C16-C18 quaternary ammonium substances compress legacy product lifecycles. The Marl Chemical Park hosts integrated fatty acid esterification operations supplying antistatic additives to automotive textile processors.
United States
Household cleaning contract manufacturers in New Jersey and Illinois consolidate supplier panels around EPA Safer Choice certified producers. California's Cleaning Product Right to Know Act and New York's disclosure mandates elevate transparency requirements above federal baselines. Stepan Company anchors North American surfactant supply from Illinois manufacturing positions.
France
Cosmetics manufacturers in Paris and Lyon audit supply chains for REACH Annex XVII precursor compliance. ANSM oversight of cosmetic ingredient safety reinforces ECHA toxicological dossier requirements. The Lyon chemical cluster supports esterquat modification chemistry for premium conditioning polymer applications.
India
Personal care brands in Mumbai and Ahmedabad expand procurement as BIS standards harmonize with REACH biodegradability protocols. CDSCO cosmetic ingredient guidelines create formulation pathways for imported conditioning agents. Gujarat's specialty chemical corridor attracts esterquat distributors serving mid-tier formulators.
Japan
Textile finishers in Osaka and Nagoya adopt hydrolytically stable grades for high-temperature synthetic fiber processing. METI chemical substance management frameworks align with OECD testing protocols for quaternary ammonium compounds. The Kansai region concentrates antistant agent demand from technical fabric producers serving automotive end-uses.
MDEA Esterquats Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated oleochemical houses commanding premium personal care supply while regional surfactant blenders capture household cleaning volume. The vendor base organizes around three archetypes: captively supplied majors with backward integration into fatty acid feedstocks, R&D-intensive modifiers of esterquat architecture, and formulation-focused surfactant houses serving specification-driven procurement channels. Capacity expansion and certification-driven supplier consolidation represent the dominant competitive moves as buyers consolidate panels around verified EPA and ECHA compliance dossiers.
Among European-based integrated producers, BASF SE and Evonik Industries occupy positions that exemplify the captively supplied and R&D-intensive archetypes respectively. Stepan Company represents the North American formulation-focused surfactant house model. These three anchors illustrate how geographic supply chain integration and regulatory dossier capabilities stratify competitive positioning across premium and standard-grade market tiers.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries |
| Stepan Company |
| Kao Corporation |
| Akzo Nobel |
| Clariant |
| ABITEC Corporation |
| The Lubrizol Corporation |
| Italmatch Chemicals |
| Others |
Value Chain & Pricing Dynamics
Specialized esterquat chemists concentrated in Germany's Marl and Ludwigshafen chemical parks command wage premiums that widen spreads between REACH-certified premium grades and standard household cleaning formulations. Labor-cost differentials between these integrated production clusters and toll-manufacturing alternatives in Eastern Europe feed directly into three-tier pricing stratification across personal care, industrial, and mass-market segments.
Pricing Analysis
Lead-time compression commands premium positioning, with personal care formulators paying elevated rates for just-in-time delivery of high-purity conditioning grades while spot inventory of standard fabric softener bases trades at discounted clearing levels. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and purity specification, with EPA Safer Choice and REACH Annex XVII compliance serving as the primary price differentiation drivers. Cost compression in standard-grade household cleaning channels is intensifying because large-format retailers consolidate supplier panels around volume-contracted certified producers. Cleaning product contract manufacturers exhibit highest price sensitivity, while cosmetics houses in France and Italy prioritize regulatory documentation over unit cost optimization.
Supply Chain Analysis
Direct-to-specialty-chemical-manufacturer channels handle technical-grade demand from personal care and industrial formulators requiring customized esterquat modifications, while distributor networks with technical support capabilities serve fragmented regional cleaning and textile processing accounts. Production gravity centers on Germany, the Netherlands, and the United States, with German chemical parks hosting integrated fatty acid esterification operations that draw from palm oil and tallow feedstocks. Raw material dependencies rest on C16-C18 alkyl chain precursors, methyldiethanolamine, and quaternization reagents. Single-source vulnerability around German energy-intensive production clusters creates exposure to regional electricity cost spikes and logistics disruption. Distribution runs through specialty chemical distributors in German and Dutch clusters for European just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
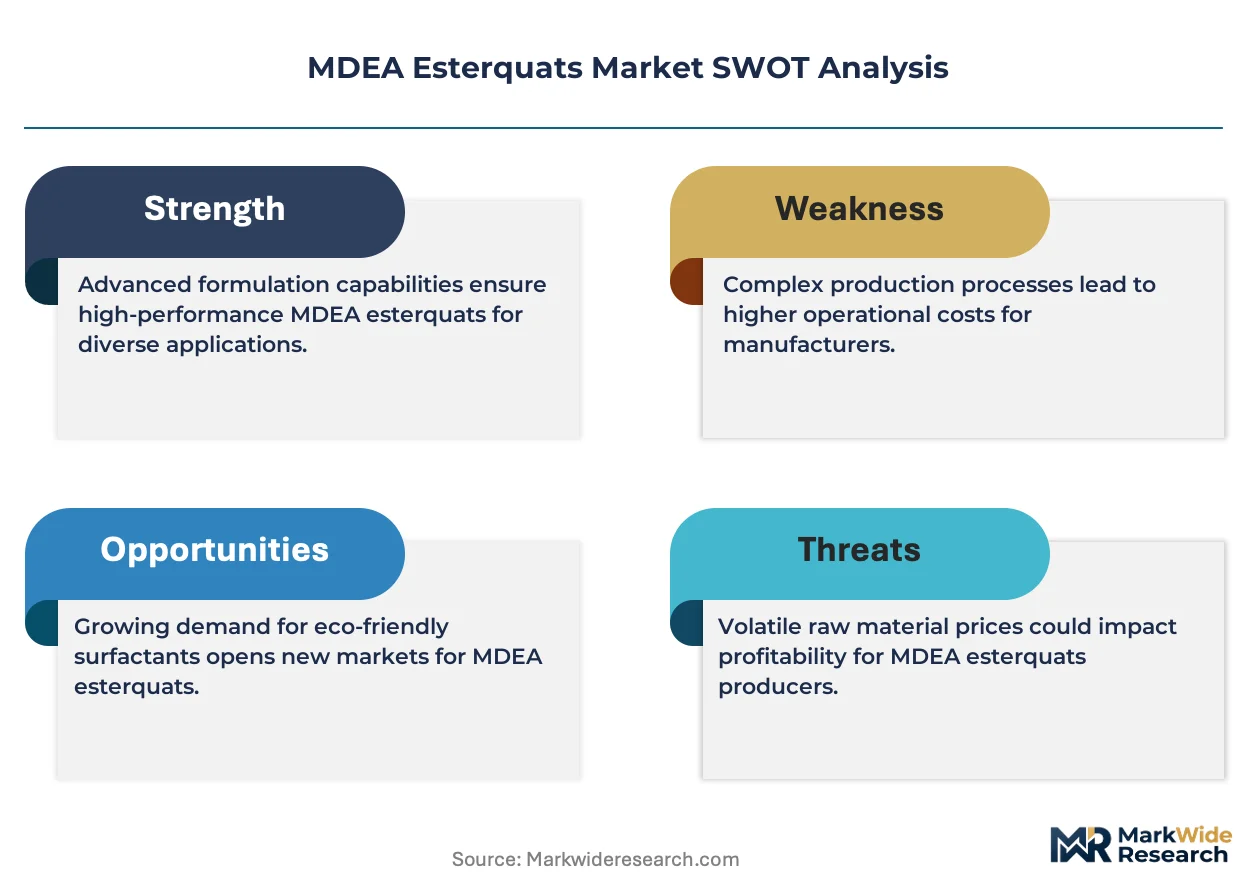
Specialty esterquat capacity expansion lags demand acceleration, with ECHA REACH registration timelines for C16-C18 quaternary ammonium substances creating 18-24 month bottlenecks that prop pricing power for compliant incumbents.
For Market Incumbents: Cement market position by accelerating backward integration into captive fatty acid supply chains and expanding hydrolytically stable grade production at Marl Chemical Park. Amidoamine and betaine substitute technologies from integrated surfactant houses threaten mid-tier fabric softener share. Certification investment in FDA-compliant food-grade lubricant emulsifier dossiers offers defensive channel expansion. For New Entrants and Emerging Players: Biodegradable esterquat architectures with enhanced aquatic toxicity profiles offer entry wedge into EPA-regulated North American household cleaning channels. India personal care expansion represents most penetrable geography given BIS-REACH harmonization. Food-grade lubricant emulsifiers for incidental food-contact applications provide lowest competitive density entry point with technical partnership go-to-market model. For Investors and Strategic Acquirers: Re-rating potential sits with R&D-intensive esterquat modifiers given hair conditioning polymer advancement catalysts and silicone-free formulation tailwinds. Long-term viability favors producers with integrated oleochemical supply chains and verified ECHA compliance dossiers. Signal to watch: California and New York state-level quaternary ammonium disclosure mandate enforcement accelerating supplier panel consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Acid Feedstocks | BASF SE's captive oleochemical supply anchors margin stability against palm oil commodity swings. |
| REACH Annex XVII Precursor Compliance Investment | Evonik Industries' toxicological dossier capabilities accelerate substitution timelines for legacy dialkylamine contaminants. |
| EPA Safer Choice Certification Program | Stepan Company's verified credentials secure specification-driven procurement from California contract manufacturers. |
| Food-Grade Lubricant Emulsifier Development | FDA-compliant toxicological dossiers create barrier-to-entry for non-compliant producers in food processing equipment. |
| Hydrolytically Stable Grade Capacity Expansion | German automotive textile processors drive adoption for high-temperature finishing line compliance. |
Study Parameters
Independent corroboration across primary interviews with specialty chemical plant managers, personal care procurement leads, textile processing technical directors, and distribution channel partners, combined with secondary validation through ECHA registration databases, customs/trade data, SEC 10-K filings, and Cefic sector reports, underwrites the qualitative findings. Bottom-up demand modeling across end-use segments triangulates against top-down supply-side capacity assessments.
Comparable-period anchoring to historical REACH registration waves and EPA surfactant standard evolution frames the projection horizon. Segmentation dimensions span product grade tier, end-use industry, application function, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating fatty acid feedstock price volatility and certification timeline compression. Industry-specific inputs include ECHA dossier approval rates and state-level disclosure mandate adoption trajectories.
Several conditions sit outside the modeled scope, including abrupt feedstock supply disruptions, unilateral regulatory acceleration beyond published ECHA guidance, and substitute technology breakthroughs in amidoamine chemistry. Forecasts reflect assumptions around REACH compliance timeline stability and EPA enforcement continuity. Periodic stress-testing of base assumptions against emerging state-level restriction frameworks is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Bitumen Emulsifier Market
Surfactants
Global Oilfield Surfactants Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Microemulsions Market
Surfactants
Global Sodium Lauryl Sulfate Market
Surfactants
Defoamers Market
Surfactants
Cetanol Market
Surfactants
Glycol Monostearate Market
Surfactants
Tetradecyl Chloride Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Calcium Stearoyl-2 Lactylate Market
Surfactants
Lauramide DEA Market
Surfactants
Amphoteric Emulsifier Market
Surfactants
Detergent Chemicals Market
Surfactants
Sodium Cocoyl Isethionate Market