
 Mosquito Repellent Market | 2026-2036
Mosquito Repellent Market Size, Share, and Industry Trends Forecast 2026-2036
Mosquito Repellent Market Analysis
Plant-based active ingredients are hardening cost positions against synthetic chemistry in mosquito repellent manufacturing. S.C. Johnson & Son, Inc. leverages its household brand portfolio to sustain shelf dominance in North American retail channels. Reckitt Benckiser Group plc anchors its position through concentrated R&D spending on next-generation vaporizer technologies. Godrej Consumer Products Ltd. dominates the Indian subcontinent with region-specific fragrance profiles and pricing tiers calibrated to local purchasing power.
Mosquito repellents are topical or spatial formulations containing active compounds—typically DEET, picaridin, or botanical extracts at concentrations between 10% and 30%—that interfere with arthropod olfactory receptors to prevent bites, serving primarily consumer health protection and outdoor activity enablement. Sprays and lotions occupy the largest revenue share due to portability and immediate efficacy, while coils retain entrenched demand in price-sensitive rural markets across South and Southeast Asia. Online stores represent the fastest-expanding distribution channel as direct-to-consumer subscription models reduce replenishment friction for recurring household purchasers.
EPA registrations govern active ingredient approvals and label claims in the United States, while India's Central Insecticides Board mandates efficacy testing and packaging disclosures under the Insecticides Act. The EU Biocidal Products Regulation imposes stringent data requirements on active substance suppliers, elevating compliance costs that favor larger formulated product manufacturers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving botanical extract safety assessments as these determine whether natural-positioned brands retain premium pricing authority or face reclassification into conventional pesticide frameworks.
Market Dynamics
EPA's updated ingredient safety reviews are compressing reformulation timelines and forcing manufacturers to accelerate botanical extract development cycles ahead of synthetic chemistry phase-outs.
Growth Catalysts
- India's Insecticides Act enforcement:Mandatory efficacy testing and packaging disclosures under the Central Insecticides Board are professionalizing quality standards and consolidating demand toward compliant manufacturers.
- Urban vector-borne disease clusters:Concentrated dengue and malaria incidence in tropical metropolitan zones is sustaining recurring household expenditure on protective formulations.
- Direct-to-consumer subscription models:Online replenishment systems are reducing purchase friction for recurring mosquito repellent users and capturing lifetime value.
Market Restraints
- Pyrethroid supply concentration:Active ingredient sourcing for coils and vaporizers concentrates among Chinese chemical manufacturers, exposing formulators to input volatility.
- EU Biocidal Products Regulation data costs:ECHA's stringent active substance dossier requirements elevate compliance burdens that disadvantage smaller botanical extract suppliers.
- DEET substitution pressure:Consumer preference migration toward picaridin and plant-based alternatives is eroding established synthetic chemistry revenue streams.
Strategic Opportunities
- Indonesia's rural electrification gaps:Non-electric spatial repellent formats retain entrenched demand in off-grid households across the archipelago.
- Wearable device convergence:Integration of repellent-emitting patches with fitness trackers and outdoor apparel opens premium positioning in recreational segments.
- India's PLI scheme for specialty chemicals:Production-linked incentives for domestic active ingredient manufacturing reduce import dependency for local formulators.
Industry Challenges
- Botanical extract standardization:Inconsistent citronella and eucalyptus oil potency across harvest batches complicates label claim verification and batch release protocols.
- Cross-border registration synchronization:Divergent efficacy testing protocols between EPA, ECHA, and India's Central Insecticides Board extend multi-market launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mosquito Repellent Market |
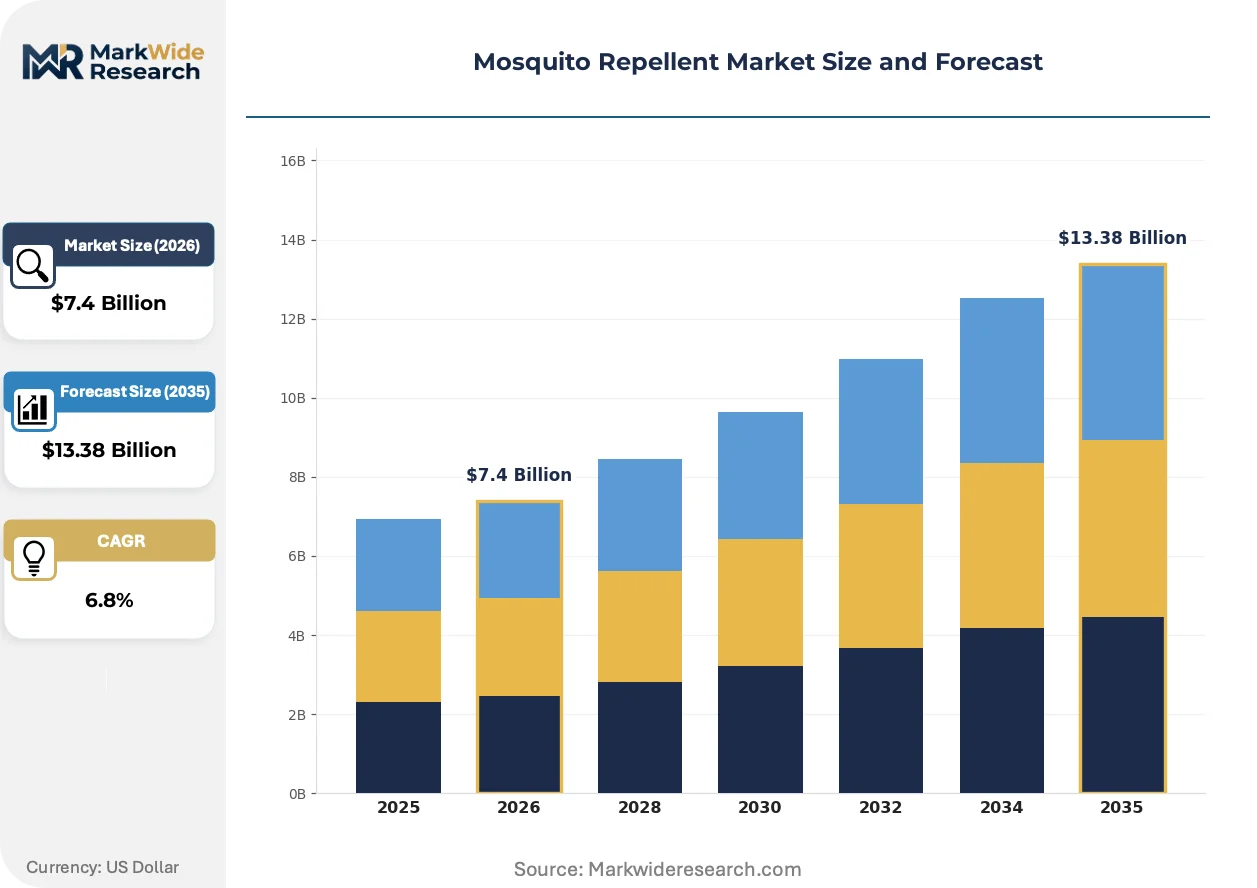
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Lotions, Coils, Candles Active Ingredient: DEET, Picaridin, Oil of Lemon Eucalyptus, IR3535 Distribution Channel: Hypermarkets, Pharmacies, Online Stores, Convenience Stores End User: Households, Travelers, Outdoor Enthusiasts, Camping Sites |
| Companies Covered | S.C. Johnson & Son, Inc., Reckitt Benckiser Group plc, Spectrum Brands Holdings Inc., Godrej Consumer Products Ltd., Dabur India Ltd., 3M Company, Henkel AG & Co. KGaA, BASF SE, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mosquito Repellent Market Emerging Trajectories
Formulation chemistry and delivery mechanisms are undergoing parallel transformation as regulatory pressure and consumer preference shift collide. Three distinct vectors are reshaping competitive positioning.
Encapsulated essential oil microspheres are extending protection duration from botanical actives. Outdoor equipment manufacturers and apparel brands are embedding these reservoirs into wearable formats at accelerating pace. The technology is integrating spatial protection into lifestyle products previously outside the repellent category.
REACH's expanded data requirements for biocidal active substances are filtering supplier bases. ECHA's 2024 dossier updates demand chronic toxicity studies that many botanical extract importers cannot fund. European formulators are responding by consolidating procurement toward vertically integrated raw material producers with captive toxicology capabilities.
Retail pharmacy chains in Brazil are unbundling repellent from seasonal promotional cycles into year-round wellness assortments. This inventory repositioning replaces peak-summer stacking with consistent shelf presence. The shift is most visible in São Paulo and Rio de Janeiro metropolitan pharmacies where dengue vigilance campaigns sustain baseline demand.
Mosquito Repellent Market Segmentation
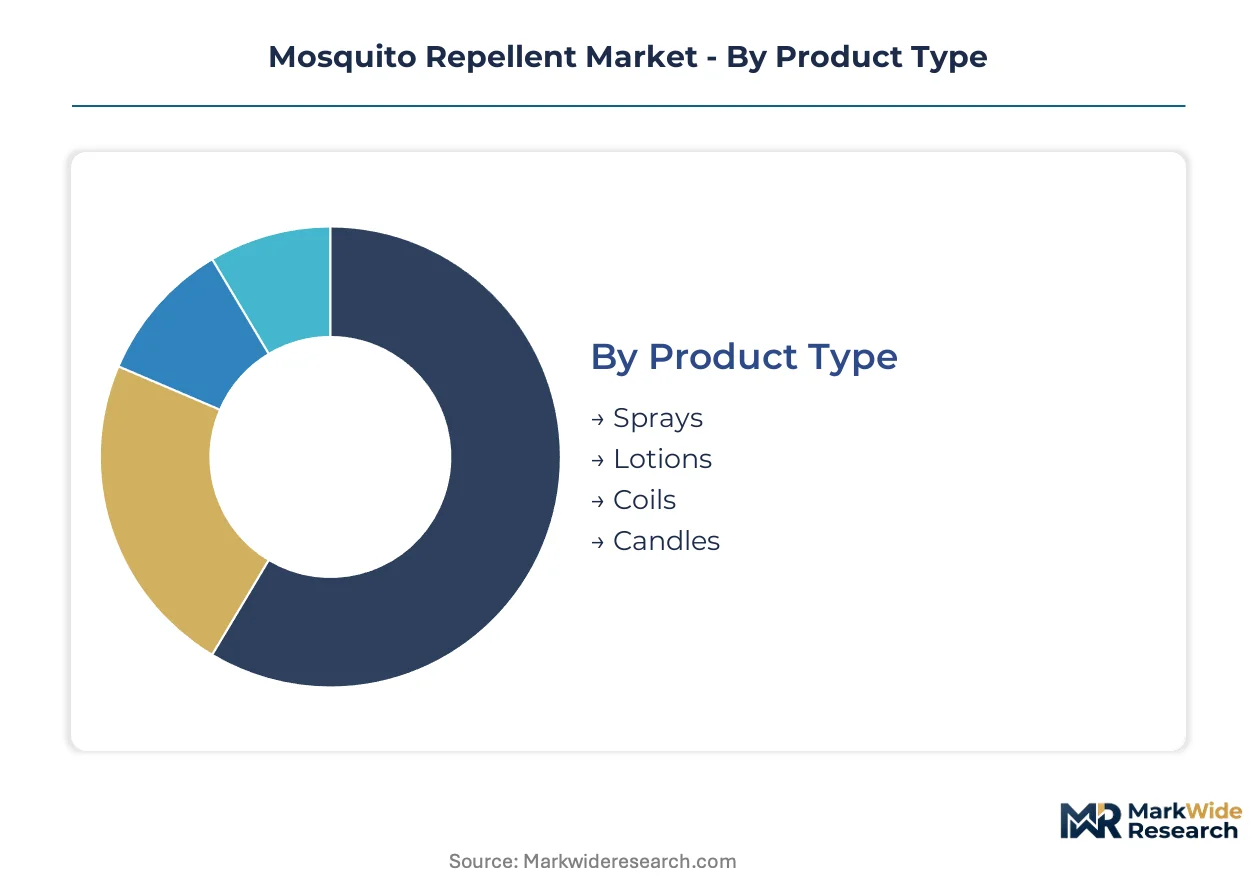
Manufacturers calibrate portfolio depth across four intersecting dimensions. Product format dictates use occasion and replenishment frequency. Active ingredient selection determines regulatory pathway and premium positioning authority.
Product Type:
Portability and immediate efficacy drive household purchase decisions across tropical and temperate zones.
- Sprays:Aerosol and pump formulations deliver rapid surface coverage with adjustable dispersion patterns. Demand concentrates among outdoor enthusiasts in Brazil and India where pre-activity application dominates. EPA registration requirements for pressurized delivery systems elevate compliance costs that favor established manufacturers with dedicated regulatory affairs teams.
- Lotions:Emulsion-based topical applications provide extended skin adherence through controlled-release polymers. Households in Southeast Asian metropolitan zones favor these for child-safe positioning and precise dosage control. Formulators compete on non-greasy sensory profiles to differentiate against generic alternatives.
- Coils:Pyrethroid-impregnated combustible matrices release spatial repellent through slow burning. Rural electrification gaps across Indonesia and India's Bihar state sustain entrenched demand despite particulate emission concerns.
- Candles:Citronella and geraniol oil formulations combine ambient lighting with limited-radius protection. Patio dining and camping occasions in US and Australian recreational markets drive seasonal procurement patterns.
Volume sits with sprays; growth tilts toward lotions.
Active Ingredient:
Regulatory approval status and consumer safety perception partition chemistry choices across price tiers.
- DEET:N,N-diethyl-meta-toluamide remains the reference standard for duration and efficacy across tropical disease vectors. Military and expedition-grade applications in African and Southeast Asian markets sustain demand despite consumer migration toward alternatives. EPA's updated safety reviews are compressing reformulation timelines for legacy formulations.
- Picaridin:Synthetic piperidine derivative delivers comparable protection without plasticizer effects on gear and equipment. European formulators under ECHA's REACH framework favor this chemistry for reduced dermal irritation profiles and favorable toxicology dossiers.
- Oil of Lemon Eucalyptus:Botanical extract containing p-menthane-3,8-diol provides EPA-registered biopesticide positioning. Premium household segments in Germany and France accept shorter protection windows for natural-origin claims.
- IR3535:Ethyl butylacetylaminopropionate offers synthetic efficacy with improved cosmetic elegance. Japanese and South Korean manufacturers integrate this active into daily-wear formulations targeting urban commuters.
DEET commands volume leadership; botanical extracts gain share fastest in premium positioning.
Distribution Channel:
Replenishment urgency and purchase planning horizon determine channel selection for protective formulations.
- Hypermarkets:Mass merchandisers capture planned stock-up purchases through seasonal promotional stacking and multi-unit pricing. India's Reliance Retail and Brazil's Carrefour operations dominate volume throughput in tropical disease corridors.
- Pharmacies:Professional recommendation channels serve anxious parents and immunocompromised travelers seeking clinical validation. ANVISA-registered products in Brazilian pharmacy chains command price premiums through pharmacist endorsement.
- Online Stores:Direct-to-consumer platforms reduce replenishment friction through subscription models and auto-replenishment algorithms. Urban Indian households and US coastal metros show highest digital conversion rates for recurring repellent purchases.
- Convenience Stores:Impulse and emergency procurement for unplanned outdoor exposure. Highway corridors and tourist districts in Thailand and Vietnam sustain 24-hour availability requirements.
Hypermarkets retain volume concentration; online stores expand most quickly through subscription capture.
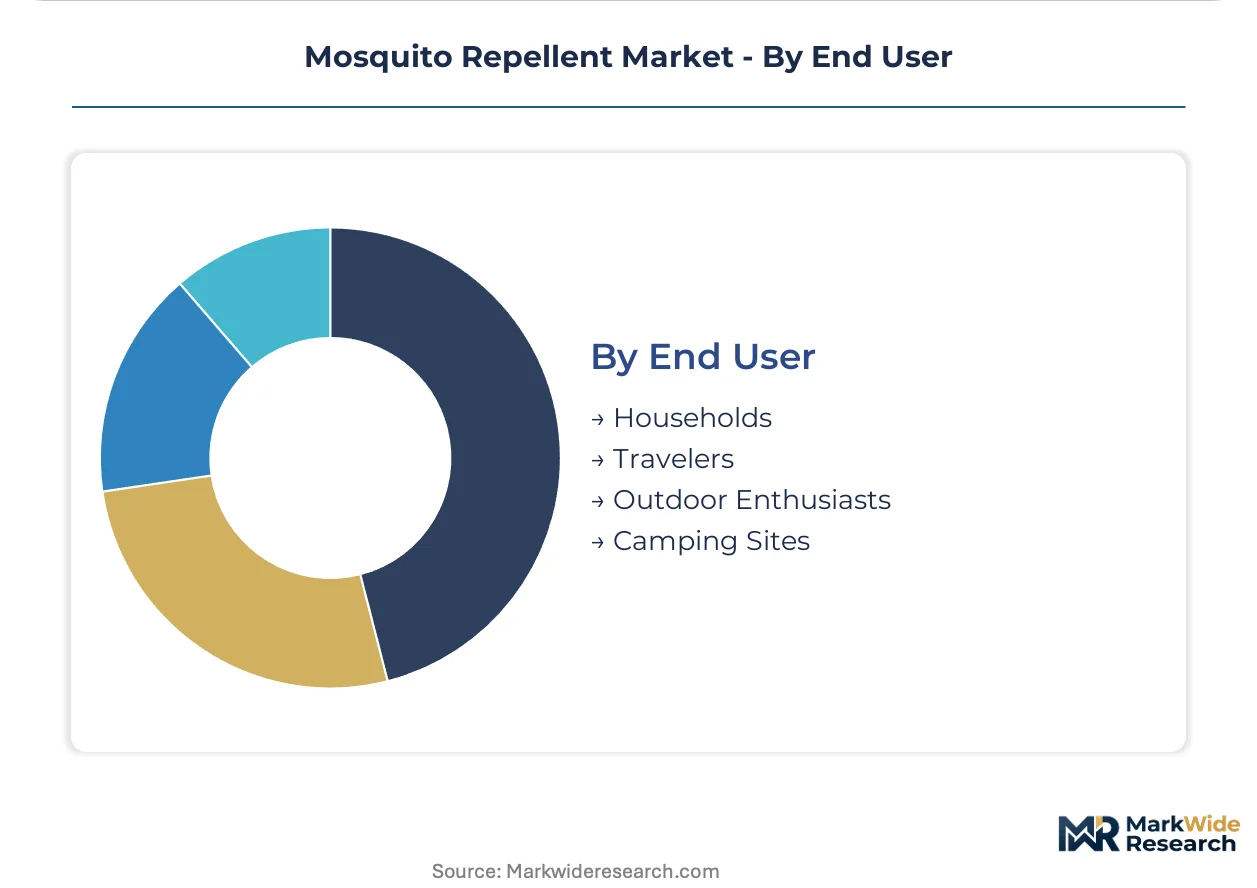
End User:
Risk perception and exposure duration shape formulation requirements across distinct usage contexts.
- Households:Multi-member residential units with children drive demand for skin-safe, odor-acceptable daily protection. India's urban dengue vigilance campaigns sustain baseline category expenditure beyond seasonal peaks.
- Travelers:International tourists and business visitors require compact, airline-compliant formats for tropical destination preparation. Pre-trip pharmacy consultations in European departure cities elevate premium product attachment rates.
- Outdoor Enthusiasts:Hikers, anglers, and hunters prioritize sweat-resistant, gear-compatible formulations for extended field exposure. US national park visitation patterns correlate with concentrated demand spikes.
- Camping Sites:Commercial and recreational campground operators procure spatial repellents for communal area protection. Seasonal bulk purchasing by European and Australian site managers follows reservation booking curves.
Households anchor volume; travelers generate steepest expansion trajectory through pre-trip preparation rituals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates household expenditure on protective formulations as urban vector-borne disease incidence sustains category demand beyond seasonal peaks. Brazil and Indonesia anchor volume through rural electrification gaps and tropical climate exposure. Regulatory divergence across EPA, ECHA, and India's Central Insecticides Board fragments multi-market launch timelines.
United States
Outdoor recreation expenditure and military procurement sustain demand for expedition-grade formulations with extended protection duration. EPA registration requirements for pressurized delivery systems elevate compliance costs that favor established manufacturers with dedicated regulatory affairs capabilities. Atlanta-based formulation specialists serve southeastern metropolitan zones where dengue vigilance campaigns sustain baseline consumption.
India
Urban vector-borne disease clusters in Mumbai, Delhi, and Bengaluru drive consistent household spending on daily-wear protective formulations. The Central Insecticides Board mandates efficacy testing and packaging disclosures under the Insecticides Act, consolidating demand toward compliant domestic manufacturers. Maharashtra and Gujarat host concentrated production capacity for coil and vaporizer formats calibrated to regional purchasing power tiers.
Brazil
Pharmacy chains in São Paulo and Rio de Janeiro unbundle repellent from seasonal promotional cycles into year-round wellness assortments. ANVISA registration requirements command price premiums through pharmacist endorsement channels. The Amazon basin and northeastern agricultural corridors sustain bulk procurement by commercial farming operations for field worker protection.
Indonesia
Rural electrification gaps across Java and Sumatra sustain entrenched demand for non-electric spatial repellent formats in off-grid households. The national health ministry's dengue eradication programs distribute subsidized protective formulations through primary care networks. Jakarta-based distributors coordinate archipelago-wide logistics for coil and mat replenishment to remote island communities.
Germany
Premium household segments accept shorter protection windows from botanical extracts for natural-origin positioning. ECHA's REACH framework and expanded biocidal data requirements filter supplier bases toward vertically integrated raw material producers. Bavarian and Baden-Württemberg retail networks emphasize DEET-free alternatives for child-safe and gear-compatible applications.
Mosquito Repellent Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with household names dominating shelf presence in developed retail channels while regional formulators capture price-sensitive volume. The vendor base concentrates around three strategic archetypes: diversified consumer goods conglomerates with household brand portfolios, domestic champions with calibrated pricing for emerging market purchasing power, and chemical suppliers providing active ingredient intermediates. Competitive moves center on M&A for brand portfolio expansion and captive supply integration for pyrethroid active ingredient security.
Among diversified consumer goods conglomerates, S.C. Johnson & Son, Inc. and Reckitt Benckiser Group plc represent the branded specialist archetype with sustained shelf dominance across North American and European retail channels. Godrej Consumer Products Ltd. anchors the domestic champion position within the Indian subcontinent. These three entities exemplify divergent strategic positioning: the conglomerates leverage cross-category household penetration for repellent placement, while the India-based specialist calibrates fragrance profiles and unit economics to local market structures.
| Leading Market Players |
|---|
| S.C. Johnson & Son, Inc. |
| Reckitt Benckiser Group plc |
| Spectrum Brands Holdings Inc. |
| Godrej Consumer Products Ltd. |
| Dabur India Ltd. |
| 3M Company |
| Henkel AG & Co. KGaA |
| BASF SE |
| Johnson & Johnson Services, Inc. |
| Others |
Supply Flow & Price Mechanics
Indian household procurement through hypermarkets and pharmacy chains concentrates demand toward three-tier pricing structures calibrated to local purchasing power tiers. This buyer archetype concentration anchors pricing models across emerging market formulators while pressuring margin structures in premium botanical segments.
Pricing Analysis
Volume leadership sits with economy-tier pyrethroid coils serving rural electrification gaps, while margin capture concentrates in premium botanical lotions targeting anxious parents in metropolitan pharmacy channels. Price differentiation rests on EPA registration status and fragrance profile sophistication. Cost compression in synthetic chemistry tiers is intensifying because of DEET substitution pressure from picaridin and plant-based alternatives. Rural households across Indonesia and India's Bihar state exhibit highest price sensitivity; travelers through European departure cities show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese chemical manufacturers supplying pyrethroid active ingredients for coils and vaporizers. Manufacturing concentration spans China, India, and Germany for active ingredient synthesis and formulated product finishing. Raw material dependencies include citronella oil from Indonesian harvests, eucalyptus extracts from Australian plantations, and synthetic piperidine precursors from Chinese petrochemical complexes. Tariff exposure on botanical extract imports complicates European formulator procurement strategies. Distribution runs through archipelago-wide logistics networks in Indonesia and consolidated retail pharmacy chains in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over pyrethroid active ingredient supply determines margin defense against synthetic chemistry substitution. Players are pursuing backward integration into specialty chemical manufacturing to secure input cost positions.
For Market Incumbents: Acquire pyrethroid manufacturing capacity in India under the PLI scheme for specialty chemicals to reduce import dependency exposure. Consolidate procurement toward vertically integrated raw material producers with captive toxicology capabilities as ECHA's expanded biocidal data requirements filter supplier bases. Defend against DEET substitution pressure by accelerating encapsulated essential oil microsphere development cycles ahead of regulatory phase-outs. For New Entrants and Emerging Players: EPA's updated ingredient safety reviews in the United States open a window for botanical extract positioning in premium household segments. Target Indonesia's rural electrification gaps with non-electric spatial repellent formats where entrenched demand persists in off-grid households. Pursue direct-to-consumer subscription models through online platforms to capture lifetime value from recurring urban Indian purchasers. For Investors and Strategic Acquirers: The window for entry favors domestic champions with calibrated pricing for emerging market purchasing power and established regulatory compliance capabilities. Long-term viability over the coming decade rests on positioning for botanical extract standardization as inconsistent citronella and eucalyptus oil potency complicates label claim verification. Watch cross-border registration synchronization delays between EPA, ECHA, and India's Central Insecticides Board as the inflection signal for multi-market launch timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrethroid Manufacturing | India's PLI scheme for specialty chemicals reduces import dependency for local formulators facing input volatility. |
| Encapsulated Essential Oil Microsphere Development | Technology integration with outdoor apparel brands extends protection duration and opens premium recreational positioning. |
| Direct-to-Consumer Subscription Launch | Auto-replenishment algorithms reduce purchase friction for recurring household purchasers in urban Indian and US coastal metros. |
| Regulatory Affairs Capability Expansion | Dedicated teams navigate divergent efficacy testing protocols between EPA, ECHA, and India's Central Insecticides Board. |
| Botanical Extract Supplier Consolidation | Procurement shifts toward vertically integrated raw material producers with captive toxicology capabilities under REACH. |
Methodological Framework
Customs records, EPA registration databases, and Central Insecticides Board filings formed the secondary backbone for supply-side mapping and regulatory pathway analysis. Primary interviews with formulation chemists, regulatory affairs directors at multinational consumer goods conglomerates, category buyers at Indian hypermarket chains, and procurement leads at Brazilian pharmacy networks combined with secondary validation through bottom-up and top-down triangulation approaches.
Historical trendline analysis across patent filings, import-export trajectories, and retail audit data established baseline growth patterns without reliance on single-source projections. Segmentation dimensions modeled include product format, active ingredient chemistry, distribution channel, and end-user risk profile across the projection horizon. CAGRs were derived from demand elasticity estimates calibrated to urban vector-borne disease incidence patterns and regulatory reformulation timeline pressures.
Caveats apply where EPA safety review acceleration, ECHA biocidal data requirement expansion, or Indian Insecticides Act enforcement shifts could materially shift the outlook. Forecasts reflect documented assumptions about botanical extract standardization progress and pyrethroid supply concentration persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Multifunctional Cleaner Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
Bleaching Chemicals Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Sanitizing Agents Market
Cleaning Chemicals
Global Dust Suppression and Control Chemicals Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market