
 Zeolite for Detergents Market | 2026-2036
Zeolite for Detergents Market Size, Share, and Industry Trends Forecast 2026-2036
Zeolite for Detergents Market Outlook
A shift from single-source to multi-source zeolite procurement is broadening supply options for detergent compounders. Albemarle Corporation leverages its bromine-specialty chemicals heritage to sustain captive zeolite output in North American supply chains. Tosoh Corporation anchors Asian detergent builder demand through integrated soda ash-to-zeolite production in Japan. BASF SE competes on formulation science, bundling zeolite with polymer dispersants for European powder detergent clients.
Zeolite for detergents refers to synthetic crystalline aluminosilicates with defined pore structures, typically Zeolite A with a SiO₂/Al₂O₃ ratio near 2.0, manufactured via hydrothermal crystallization of sodium aluminate and sodium silicate solutions to sequester water hardness ions during washing. The primary commercial purpose is phosphate-free water softening in laundry and automatic dishwashing formulations. Zeolite A dominates powder detergent applications due to optimal calcium exchange capacity and cost-positioning, while liquid detergent compatibility constraints push formulators toward specialized Zeolite Y grades. Natural zeolite occupies peripheral roles in industrial cleaning where lower purity tolerances match price-sensitive procurement.
REACH restricts phosphorus discharge thresholds in EU cleaning products, compelling formulators toward zeolite builders. EPA Safer Choice standards and state-level phosphate bans in the US reinforce parallel substitution trends. China's GB standards on detergent phosphorus content and MEE enforcement of wastewater discharge limits create comparable compliance pressure. Stakeholders must monitor regulatory divergence between geographies where zeolite builder specifications differ on heavy metal content and particle size distribution.
Market Dynamics
Phosphate replacement mandates across Western Europe are restructuring zeolite procurement patterns as formulators race to comply with tightening discharge thresholds before statutory deadlines.
Growth Catalysts
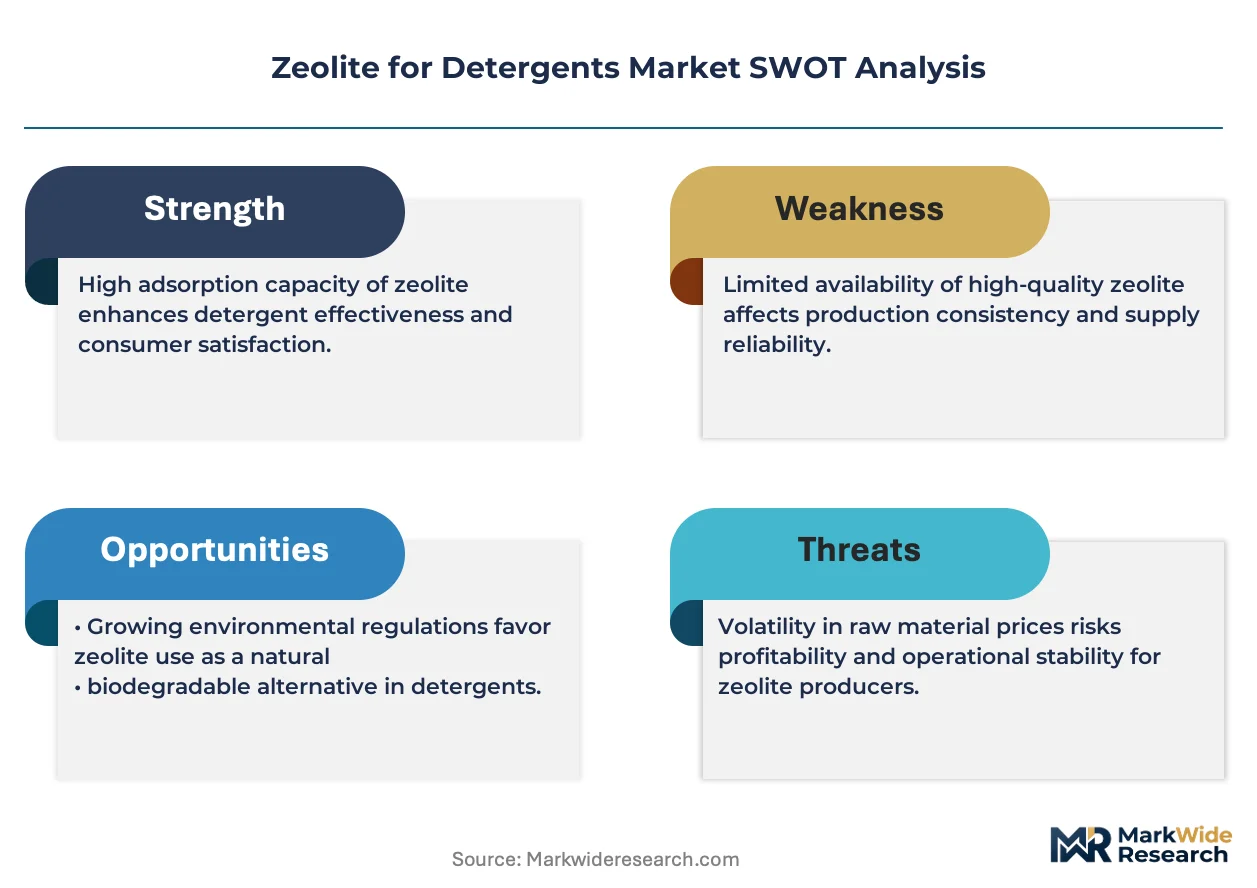
- REACH phosphorus limits:ECHA enforcement of detergent phosphorus caps in EU member states is compelling formulators to switch builders.
- Automatic dishwashing expansion:Rising machine penetration in German and French households is creating dedicated demand for Zeolite A grades optimized for hard water.
- Hydrothermal crystallization advances:Continuous reactor designs are compressing production cycles and improving particle size consistency for powder detergent integration.
Market Restraints
- Soda ash price volatility:Sodium carbonate feedstock fluctuations directly compress zeolite A margins and destabilize contract pricing.
- Liquid detergent incompatibility:Zeolite A precipitation in aqueous formulations limits addressable share of the fastest-growing detergent format.
- Silicate supply concentration:Sodium silicate production clusters in China and the US create geographic vulnerability for European zeolite manufacturers.
Strategic Opportunities
- Zeolite Y for liquids:Higher silica ratio grades compatible with gel and liquid detergents open penetration of the premium concentrated segment.
- India phosphate phase-out:BIS deliberations on phosphorus limits in household cleaners position zeolite builders for regulatory tailwinds.
- Industrial cleaning channels:Natural zeolite adoption in food processing and hospitality sectors offers price-positioned volume outside consumer detergents.
Industry Challenges
- REACH registration timelines:ECHA substance dossier requirements for modified zeolite compositions extend product launch cycles by 18-24 months.
- Particle size standardization:Divergent specifications between German detergent compounders and French automatic dishwasher manufacturers fragment production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zeolite for Detergents Market |
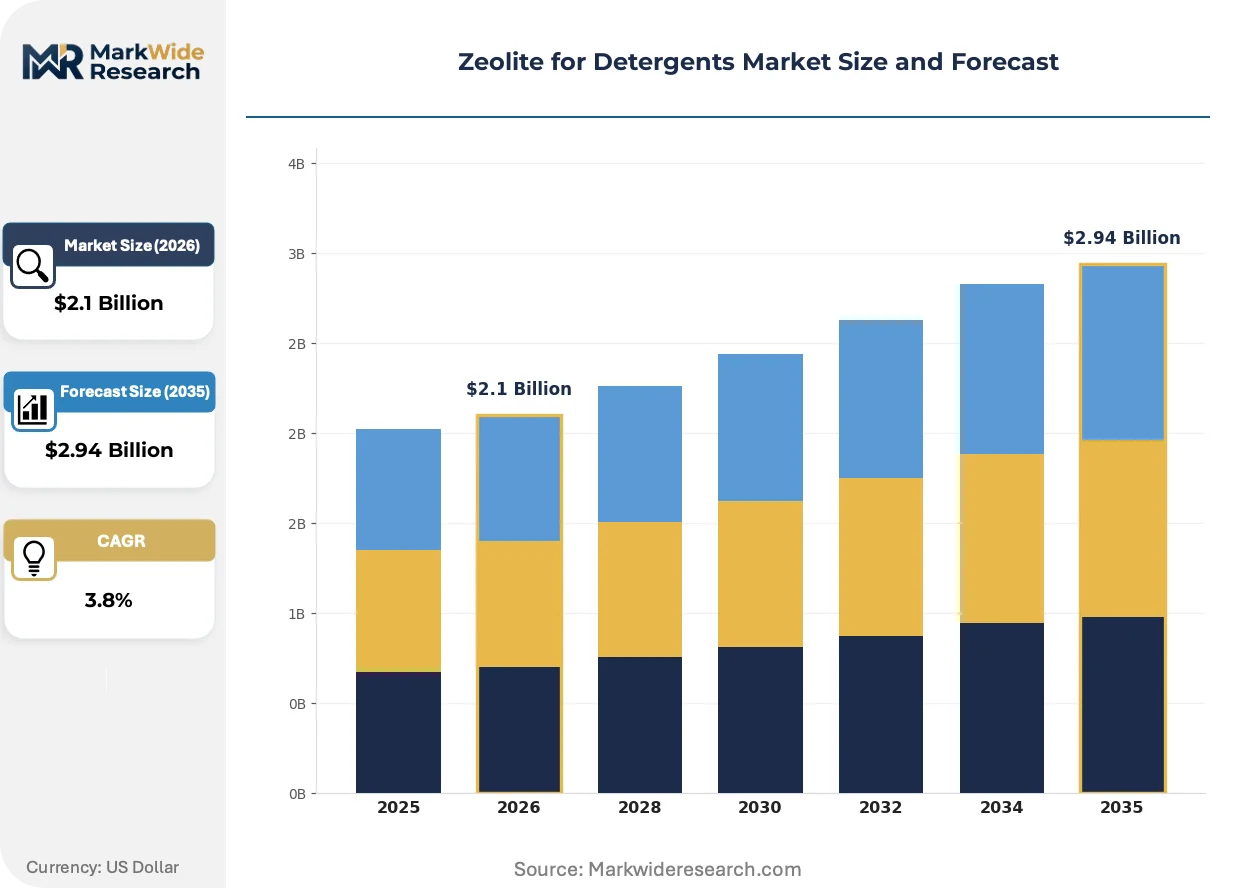
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zeolite A, Zeolite Y, Zeolite X, Natural Zeolite Application: Household Cleaning, Industrial Cleaning, Food Processing, Personal Care End User: Manufacturers, Retailers, Distributors, Consumers Form: Powder, Granules, Tablets, Liquid |
| Companies Covered | Albemarle Corporation, Tosoh Corporation, BASF SE, Arkema Group, PQ Corporation, Honeywell International Inc., W. R. Grace & Co., Zeolyst International, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zeolite for Detergents Market Strategic Shifts
Zeolite builder technology is fragmenting into application-specific grades as formulators abandon universal powders for targeted performance positioning.
Zeolite Y with elevated SiO₂/Al₂O₃ ratios is modularizing liquid detergent formulation architecture. Premium brands in Japan and South Korea are adopting these grades for concentrated gel products. The technology is modularizing supply chain relationships as producers develop dedicated liquid-grade capacity separate from powder-optimized Zeolite A lines.
EPA Safer Choice standards are tightening phosphorus screening criteria for cleaning product certification. Formulators seeking the label must document builder substitution with verified phosphate-free alternatives. Powder detergent manufacturers in California and Washington State are accelerating zeolite qualification to maintain retail placement under state-level green procurement mandates.
Compounders are consolidating supplier relationships around dual-source zeolite strategies with defined volume splits. Large European detergent manufacturers are disintermediating traders to secure direct hydrothermal reactor access. Germany and the Netherlands show the most advanced procurement restructuring, with household brands negotiating three-year offtake agreements tied to REACH compliance verification.
Zeolite for Detergents Market Segmentation
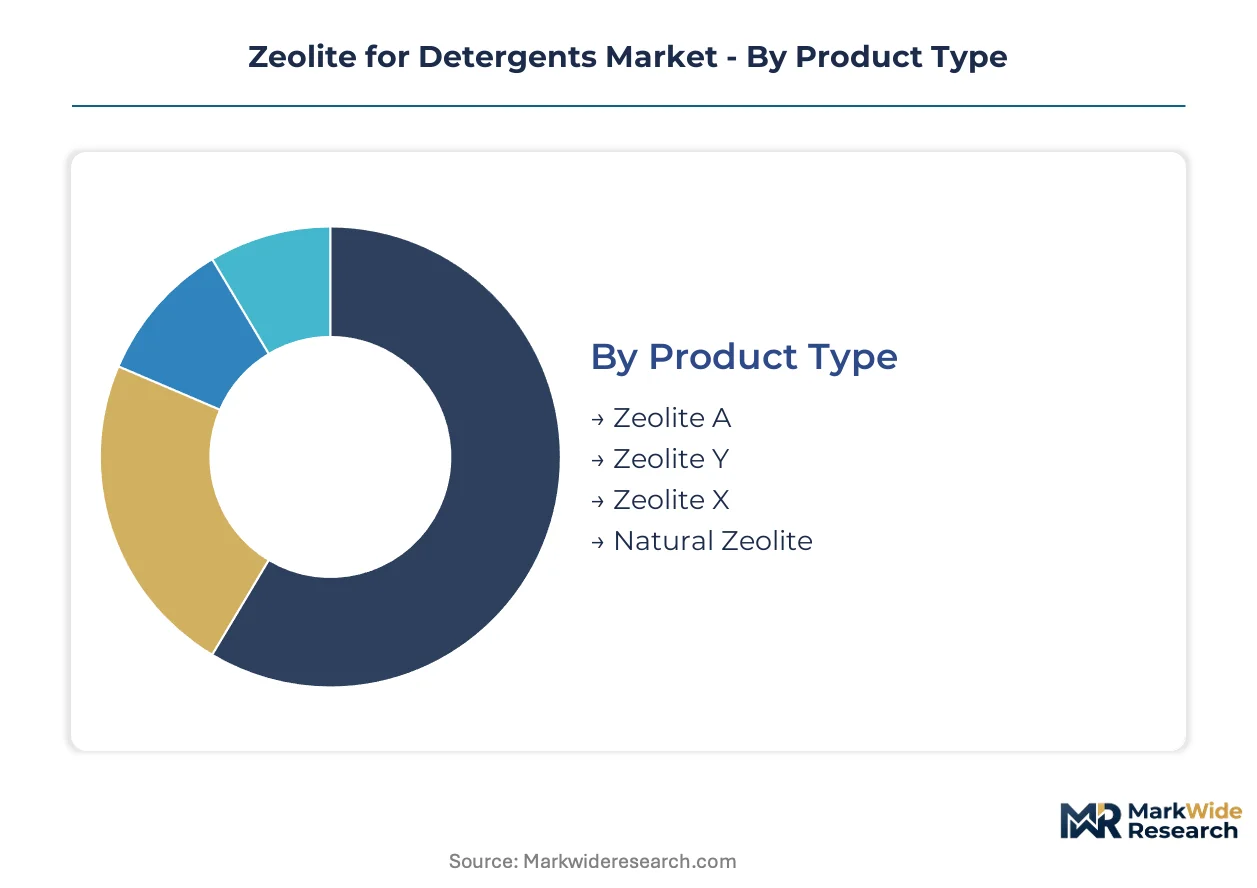
Zeolite builder procurement diverges sharply by product chemistry and detergent format compatibility. Formulators select grades based on ion exchange capacity thresholds, dissolution kinetics, and regulatory phosphorus limits in target markets.
Product Type:
Cost tier separates commodity powder detergents from premium liquid and concentrated formulations requiring specialized silica ratios.
- Zeolite A:Synthetic crystalline aluminosilicate with SiO₂/Al₂O₃ ratio near 2.0 manufactured via hydrothermal crystallization. German and French household cleaning brands concentrate procurement here as REACH phosphorus caps tighten replacement deadlines.
- Zeolite Y:Higher silica ratio grade with enhanced liquid compatibility and gel detergent stability. Japanese and South Korean premium brands drive qualification for concentrated products where precipitation resistance commands price premiums.
- Zeolite X:Larger pore structure variant offering modified calcium exchange kinetics for specialized hard water formulations.
- Natural Zeolite:Lower purity aluminosilicate from volcanic deposits serving price-sensitive industrial cleaning channels in food processing and hospitality sectors.
Zeolite A leads volumes today; Zeolite Y is gaining share fastest.
Application:
Volume scale distinguishes mass-market laundry powders from niche industrial channels with divergent purity tolerances.
- Household Cleaning:Laundry and automatic dishwashing powders represent the primary revenue concentration. German machine penetration rates and French dishwasher adoption create dedicated demand for builder-optimized formulations with defined particle size distribution.
- Industrial Cleaning:Food processing equipment sanitation and hospitality linen washing accept lower purity natural zeolite where cost positioning outweighs optical brightener compatibility.
- Food Processing:Equipment rinse aids and surface cleaners with residue limits specified by national food safety regulators.
- Personal Care:Toothpaste abrasives and cosmetic formulations requiring micronized grades with heavy metal content certification.
Household cleaning commands the largest revenue pool; industrial cleaning offers the steepest expansion trajectory in emerging markets.
End User:
Supply chain position determines whether buyers negotiate direct reactor access or accept trader-mediated spot volumes.
- Manufacturers:Detergent compounders with captive formulation laboratories qualifying zeolite grades against internal performance benchmarks.
- Retailers:Private label brands sourcing pre-formulated builder blends through toll manufacturing arrangements.
- Distributors:Regional chemical traders holding inventory for mid-tier compounders without direct producer contracts.
- Consumers:Small-scale industrial buyers purchasing natural zeolite in bulk for on-site cleaning solution preparation.
Manufacturers dominate procurement value; retailers are expanding fastest as private label share climbs.
Form:
Customer type fragmentation reflects powder-to-liquid format shifts and automatic dishwasher hardware requirements.
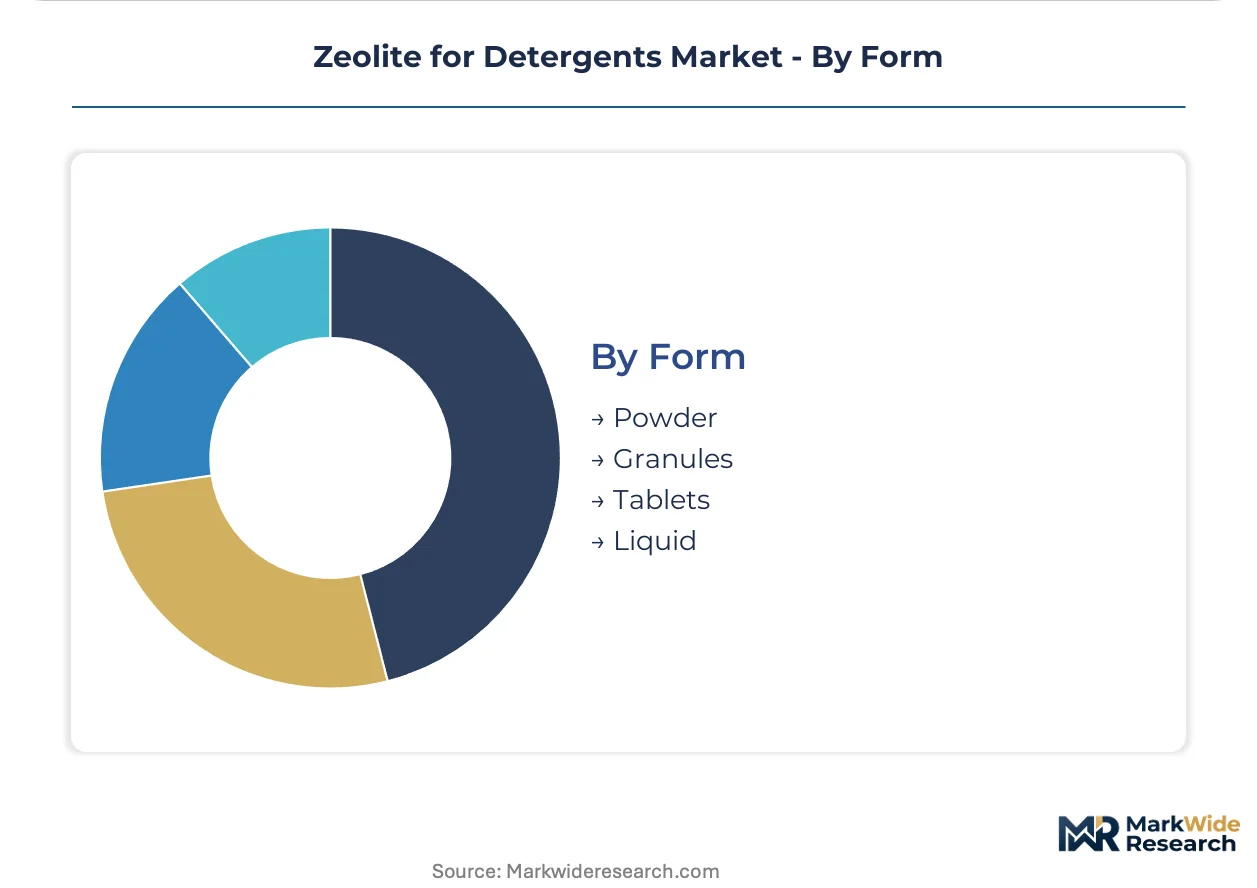
- Powder:Zeolite A integration remains technically straightforward with established dispersant systems and spray-drying compatibility.
- Granules:Agglomerated builder formats for industrial laundry systems with controlled dissolution rate specifications.
- Tablets:Unit-dose automatic dishwasher products requiring compression-stable zeolite grades with defined disintegration kinetics.
- Liquid:Zeolite Y and modified grades for gel concentrates where suspension stability and optical clarity determine formulation acceptance.
Powder leads installed base; liquid formats are climbing the fastest as concentrated detergents displace conventional loads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors zeolite procurement intensity as German detergent compounders accelerate phosphate replacement ahead of regulatory deadlines. REACH enforcement and national phosphorus discharge limits are restructuring builder supply chains across Western Europe. Formulators in France, Italy, and the Netherlands are qualifying alternative aluminosilicate sources to secure compliance certification.
Germany
Machine dishwasher penetration rates in Bavaria and North Rhine-Westphalia drive dedicated Zeolite A demand for hard water formulations. ECHA REACH substance dossier requirements extend product launch cycles for modified zeolite compositions. Düsseldorf-based household cleaning brands negotiate three-year offtake agreements tied to phosphorus cap verification.
France
Automatic dishwashing adoption in the Île-de-France region creates specification-grade demand for compression-stable zeolite tablets. ANSM and environmental agency phosphorus screening criteria tighten under EU Green Deal implementation. Lyon-area formulators qualify particle size distributions optimized for French dishwasher hardware requirements.
United States
California and Washington State green procurement mandates accelerate zeolite qualification for EPA Safer Choice certification. State-level phosphate bans in the Great Lakes region reinforce substitution trends for laundry powder compounders. Chicago and Detroit industrial corridors host toll manufacturers blending builder systems for private label retailers.
Japan
Premium concentrated gel detergents in the Kanto region drive Zeolite Y adoption for liquid-compatible formulations. METI chemical substance management frameworks align with corporate sustainability commitments from major consumer brands. Osaka-Kobe manufacturing clusters integrate soda ash-to-zeolite production for captive detergent builder supply.
China
GB standards on detergent phosphorus content and MEE wastewater discharge enforcement create compliance pressure for domestic formulators. Yangtze River Delta detergent manufacturers source sodium silicate feedstock from regional production clusters. Shandong Province zeolite producers serve both household cleaning compounders and industrial cleaning channels.
Zeolite for Detergents Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue liquid-compatible specialty grades and natural zeolite industrial channels. The vendor base concentrates around integrated chemical conglomerates with captive silicate supply and independent zeolite specialists serving regional detergent compounders. Two strategic archetypes dominate: hydrothermal crystallization specialists with reactor-scale flexibility, and diversified chemical majors bundling builders with polymer dispersants. Capacity expansion in Western Europe and strategic partnerships for Indian market access represent the primary competitive vectors.
Within the integrated chemical major tier, BASF SE and Albemarle Corporation exemplify divergent supply chain architectures. BASF SE anchors European formulation science capabilities through bundled polymer-zeolite systems. Albemarle Corporation represents North American captive production models leveraging bromine-specialty heritage for regional supply security. Tosoh Corporation occupies a distinct position as an Asia-Pacific integrated producer with soda ash-to-zeolite vertical control.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Tosoh Corporation |
| BASF SE |
| Arkema Group |
| PQ Corporation |
| Honeywell International Inc. |
| W. R. Grace & Co. |
| Zeolyst International |
| Clariant AG |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Germany and the Netherlands anchor zeolite supply discipline through multi-generational reactor assets, translating captive sodium silicate access into pricing power over detergent compounders facing REACH compliance deadlines. Their ownership structure insulates production decisions from quarterly earnings pressure, enabling long-term offtake contracting that stabilizes builder input costs for Western European formulators.
Pricing Analysis
Sodium aluminate and sodium silicate feedstock volatility passes through to zeolite A contract pricing with 60-90 day lags, compressing margins when soda ash markets spike. Three-tier pricing structure across premium, standard, and economy levels separates Zeolite Y liquid-grade certification from commodity Zeolite A powder specifications. Pricing pressure stems from liquid detergent incompatibility that caps addressable volume in the fastest-growing format. Private label retailers exhibit highest price sensitivity, while German household brands absorb premiums for REACH-verified supply security.
Supply Chain Analysis
Zeolite production rests on sodium silicate feedstock concentrated in China, the United States, and Germany, with hydrothermal crystallization capacity clustering along the Rhine-Ruhr and Osaka-Kobe industrial corridors. Sodium carbonate, sodium aluminate, and energy inputs constitute 70% of variable production costs. Single-source vulnerability in silicate supply creates geographic exposure for European manufacturers dependent on Asian feedstock. Distribution runs through direct reactor access agreements for large compounders, with regional chemical traders holding inventory for mid-tier buyers lacking producer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH phosphorus caps and parallel GB standards in China create structural demand substitution that outpaces organic volume growth.
For Market Incumbents: To counter soda ash price volatility and margin compression in commodity Zeolite A, secure captive sodium silicate supply through backward integration into regional production clusters. Add dedicated Zeolite Y liquid-grade capacity to capture premium positioning in Japanese and South Korean gel detergent markets. For New Entrants and Emerging Players: Launch via toll manufacturing arrangements serving Indian detergent compounders ahead of anticipated BIS phosphorus limits. Target natural zeolite supply for price-sensitive industrial cleaning channels in food processing and hospitality sectors where purity tolerances permit lower-cost entry. For Investors and Strategic Acquirers: Valuations sit cheapest among hydrothermal crystallization specialists with stranded reactor capacity and underutilized silicate supply agreements. Five-to-ten year viability hinges on regulatory substitution durability rather than organic detergent volume growth. Watch ECHA enforcement intensity and Indian regulatory deliberations as inflection signals for builder demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate | Captive feedstock supply from Shandong Province producers insulates margin volatility for European zeolite manufacturers. |
| Zeolite Y Liquid-Grade Capacity Addition | Dedicated reactor lines in Osaka-Kobe clusters capture premium positioning for Japanese gel detergent formulators. |
| Long-term Supply Agreement | Three-year offtake contracts with Düsseldorf-based household brands tie pricing to REACH phosphorus cap verification. |
| Joint Venture for Indian Market Access | Partnerships with Mumbai detergent compounders pre-position builder supply ahead of BIS regulatory deliberations. |
| Green Manufacturing Transition | Continuous hydrothermal reactor designs reduce energy intensity for EPA Safer Choice certification compliance. |
Study Parameters
Direct dialogue with detergent formulators, zeolite plant managers, sodium silicate procurement leads, and ECHA regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from customs trade data, Cefic chemical industry reports, SEC 10-K filings of listed producers, and REACH substance dossier databases. Bottom-up volume estimates from individual reactor capacities triangulated against top-down detergent formulation demand models.
Top-down demand segmentation across product type, application, and detergent format dimensions integrated with bottom-up supply capacity assessments across the analysis window. CAGRs derived from regression analysis of historical phosphate substitution rates correlated with regulatory enforcement milestones. Forecast inputs incorporated hydrothermal crystallization yield improvements and automatic dishwasher penetration trajectories in Germany and France.
Forecast precision tightens around the base case; tail outcomes carry wider variance under soda ash price spike scenarios or ECHA registration timeline extensions for modified zeolite compositions. Projections reflect assumptions on regulatory substitution durability and liquid detergent format growth. A small set of named triggers—Indian BIS phosphorus limits, EPA Safer Choice criteria tightening, and Zeolite Y suspension stability breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Cyclopentasiloxane Market
Surfactants
Sodium Naphthalene Sulphonate Formaldehyde Market
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
Cocamide Monoethanolamine Market
Surfactants
Wax Emulsion Market
Surfactants
Emulsion Stabilizers Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Specialty Surfactants Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Tetradecyl Chloride Market
Surfactants
Chlorooctane Market
Surfactants
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market
Surfactants
Global Surfactants Market
Surfactants
Asia Pacific Surfactants Market
Surfactants
Global Sodium Cocoyl Glutamate Market
Surfactants
Micellar Water Market