
 Slurry Homogenizer Tank Market | 2026-2036
Slurry Homogenizer Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Slurry Homogenizer Tank Market Insights
Modular tank configurations is decoupling capital expenditure from installation timelines across the slurry homogenizer tank market. GEA Group Aktiengesellschaft leverages its European manufacturing footprint to sustain long-term service contracts with mining operators. Alfa Laval AB anchors its position through specialized high-pressure processing systems for chemical blending applications. SPX Flow, Inc. competes aggressively in the portable tank segment across North American construction material manufacturers.
A slurry homogenizer tank is a pressurized or atmospheric vessel equipped with mechanical agitation, rotor-stator mixing, or ultrasonic homogenization systems designed to achieve particle size uniformity in abrasive or viscous suspensions, typically constructed from stainless steel or rubber-lined carbon steel with jacketed cooling capabilities for temperature-sensitive chemical reactions. Vertical homogenizers dominate cement processing installations due to their gravity-assisted discharge efficiency and lower footprint requirements, while rotor-stator mixing technology leads margin pools in food processing applications where shear sensitivity demands precise control. Custom fabricated tanks represent the fastest-growing configuration as mining companies and chemical producers specify site-specific dimensional and metallurgical requirements for corrosive mineral slurries.
OSHA pressure vessel standards and EPA emissions guidelines shape equipment design requirements for US-based coating manufacturers, while China's SAMR enforces GB standards for industrial mixing equipment safety certification. The EU's F-Gas Regulation indirectly influences cooling jacket specifications for European chemical producers seeking low-global-warming-potential refrigerant compatibility. Stakeholders must monitor evolving carbon steel tariff regimes and their impact on custom fabrication cost structures.
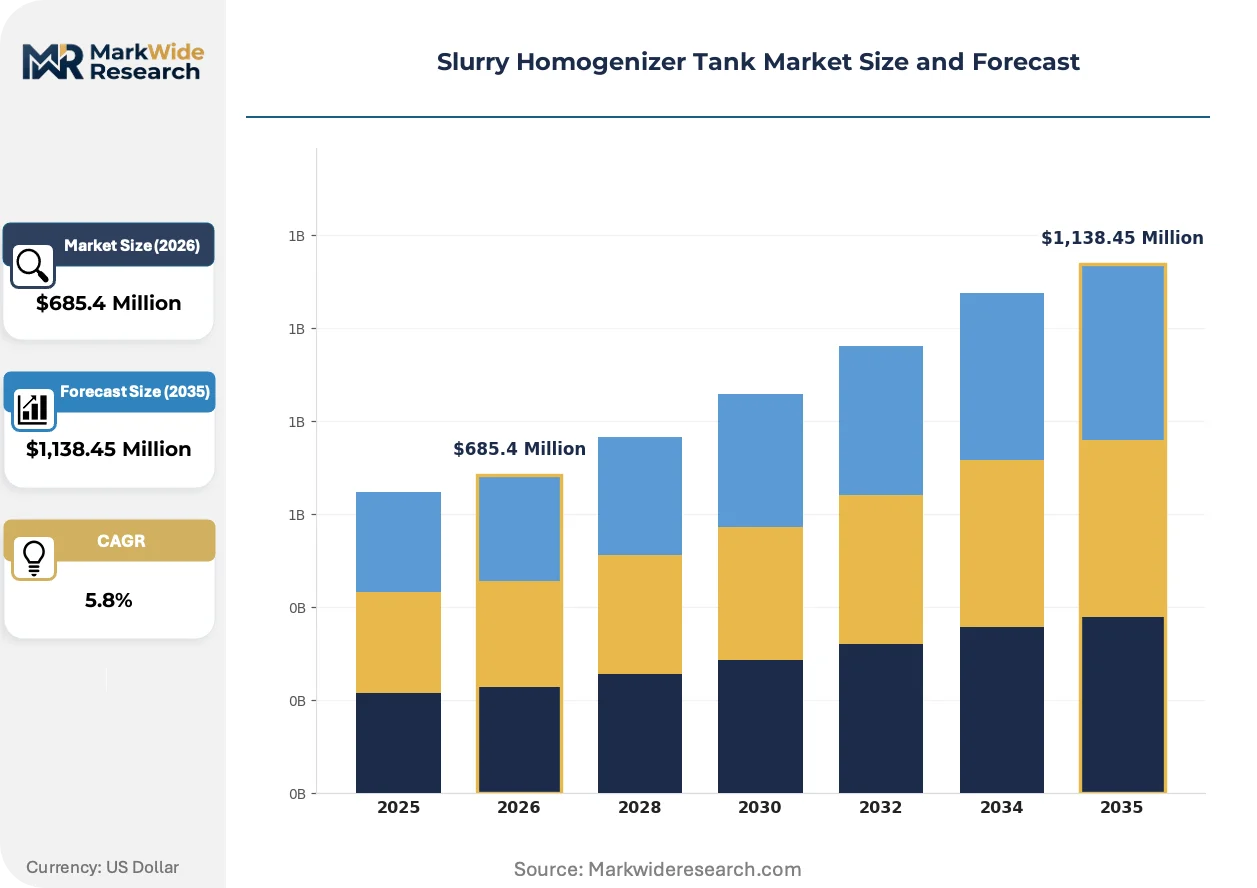
Market Dynamics
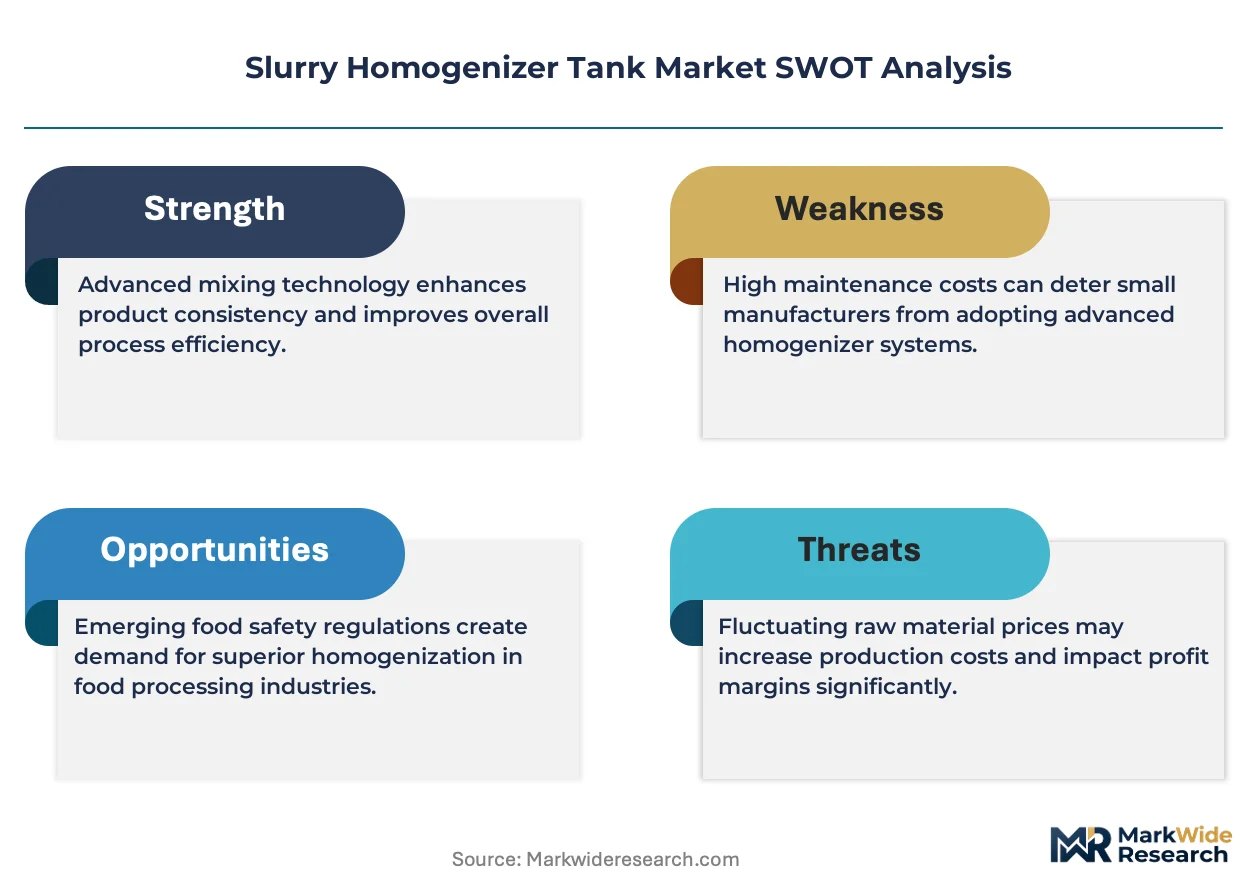
Modular tank configurations are decoupling capital expenditure from installation timelines, allowing mining operators to scale processing capacity without full-site shutdowns. This structural shift compresses project delivery cycles and reshapes supplier-customer contracting terms.
Growth Catalysts
- India's infrastructure investment acceleration:Cement processing facilities are expanding homogenizer tank fleets to meet clinker blending demands from highway and dam construction projects.
- GB standards tightening:China's SAMR certification requirements for imported industrial mixing equipment are forcing foreign manufacturers to upgrade safety interlock systems, raising technical barriers but validating premium equipment suppliers.
- Rotor-stator mixing technology:Food processors are specifying shear-controlled homogenization for plant-based protein suspensions, opening adjacent demand channels beyond traditional mining and chemical applications.
Market Restraints
- Carbon steel tariff volatility:Custom fabrication cost structures fluctuate with trade policy shifts, squeezing margin predictability for tank builders serving North American coating manufacturers.
- High-pressure system certification backlog:Australia's expanding mining adoption faces inspection queue delays from limited TGA-recognized pressure vessel certifiers.
- Ultrasonic homogenization substitution:Laboratory-scale chemical producers are piloting probe-based systems that bypass tank infrastructure entirely for batch volumes below 500 liters.
Strategic Opportunities
- Brazilian mineral processing expansion:Iron ore beneficiation plants lack standardized homogenization infrastructure, creating first-mover positioning for tank suppliers offering ANVISA-compatible material certifications.
- EU F-Gas Regulation compliance:Cooling jacket retrofits for low-global-warming-potential refrigerant compatibility represent recurring revenue streams from European chemical producer installed bases.
- Portable tank rental channels:Construction material manufacturers are testing lease-to-own models for short-duration projects, shifting capital allocation from ownership to operating expenditure.
Industry Challenges
- Welding certification scarcity:ASME Section IX-qualified pressure vessel welders command premium wages, extending delivery timelines for custom-fabricated mining tanks.
- Legacy DCS integration complexity:Brownfield cement plants require protocol translation layers to connect modern homogenizer controls to 1990s-era distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slurry Homogenizer Tank Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Homogenizer, Horizontal Homogenizer, Custom Fabricated Tank, Portable Tank Technology: Mechanical Agitation, Ultrasonic Homogenization, High-Pressure Processing, Rotor-Stator Mixing Application: Cement Processing, Mineral Treatment, Chemical Blending, Food Processing, Paint Manufacturing End User Industry: Construction Material Manufacturers, Mining Companies, Chemical Producers, Food Processing Plants, Coating Manufacturers |
| Companies Covered | Matec Industries, PRODOMIX, Quadro Liquids, Silverson Machines Ltd., Wahal Engineers, GEA Group Aktiengesellschaft, SPX Flow, Inc., Alfa Laval AB, Niro Soavi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slurry Homogenizer Tank Market Trends and Innovations
Equipment intelligence and materials science are converging to redefine performance benchmarks. Suppliers are embedding condition monitoring and advancing metallurgical formulations to extend service intervals in abrasive environments.
Advanced ceramic lining systems are unifying wear resistance with thermal shock tolerance in high-velocity slurry applications. Copper-gold concentrators in Chile's Atacama operations are specifying alumina-zirconia composite coatings to extend tank shell life beyond 80,000 operating hours. This unifying materials approach is compressing replacement cycle frequency and shifting supplier revenue toward lining refurbishment services.
REACH chemical authorization protocols are restricting chromium-based hardfacing alloys in EU-manufactured homogenizer impellers. Equipment producers are qualifying cobalt-free tungsten carbide alternatives through ECHA substance evaluation pathways. German chemical blending facilities are absorbing 12-18 month material requalification timelines to maintain CE-marked equipment access.
Service unbundling is separating mechanical maintenance from process optimization consulting. Mining operators in Western Australia are contracting tank performance guarantees independently from OEM service agreements, opening third-party technical advisory channels. This behavioral shift is most pronounced among mid-tier gold producers with captive engineering teams seeking specialist agitation efficiency audits.
Slurry Homogenizer Tank Market Segmentation
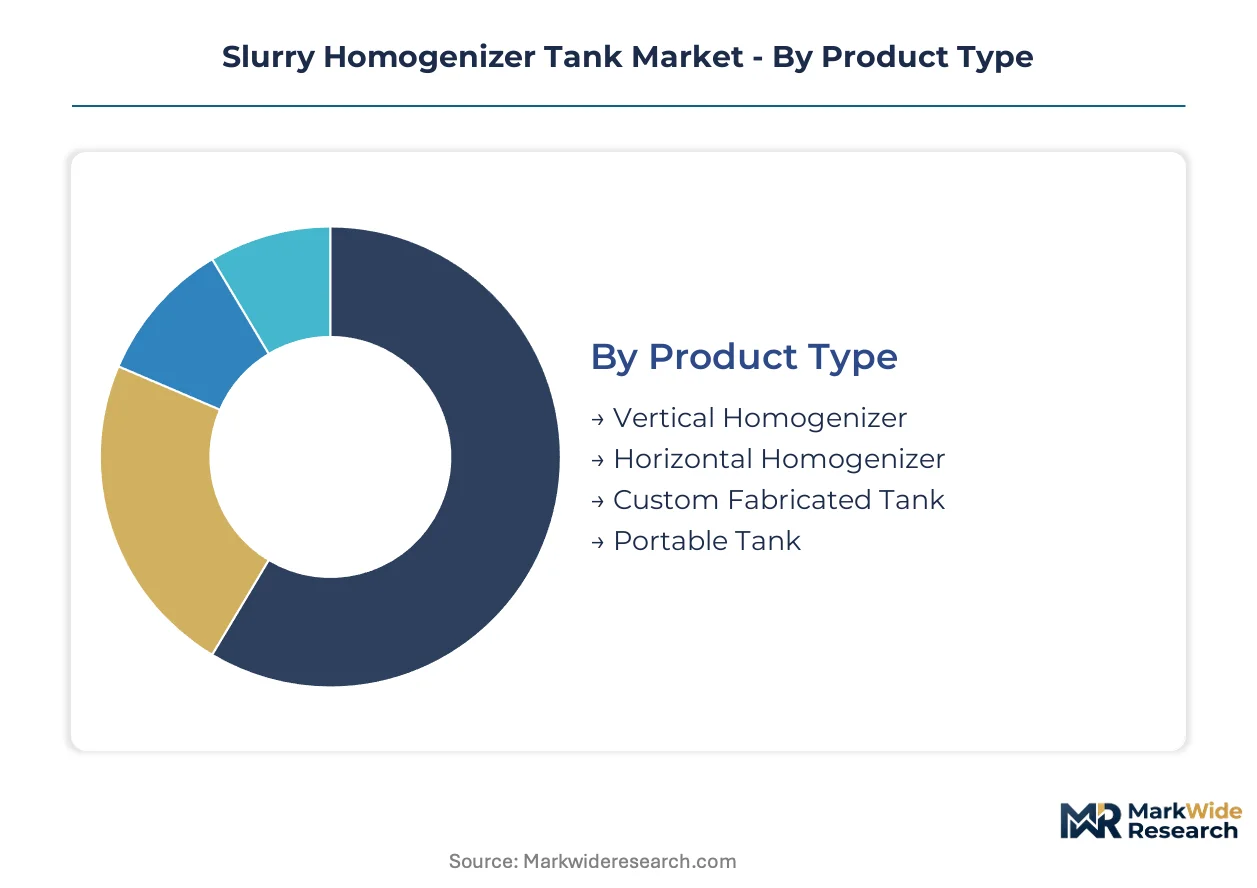
Segmentation in the slurry homogenizer tank market reveals how certification requirements, abrasive duty specifications, and installation constraints fragment procurement decisions across end-use industries. Understanding these divides exposes where technical barriers protect margin pools and where standardization pressures compress pricing.
Product Type:
ASME Section VIII certification dominates vertical and horizontal pressure vessels, while portable tanks navigate OSHA portable equipment guidelines and custom fabricated units require site-specific welding inspections.
- Vertical Homogenizer:Gravity-assisted discharge geometry minimizes floor space demands. Cement processing facilities in India specify vertical configurations for clinker blending operations where footprint constraints intersect with high-volume throughput requirements.
- Custom Fabricated Tank:Site-specific dimensional and metallurgical engineering addresses corrosive mineral slurry chemistries. Mining operators in Western Australia commission rubber-lined carbon steel shells with ceramic tile backing for copper-gold concentrator circuits.
- Horizontal Homogenizer:Low-profile installation suits underground processing plants with height restrictions. Chemical blending facilities specify jacketed horizontal vessels for temperature-sensitive reactions.
- Portable Tank:Skid-mounted configurations enable rapid redeployment across construction material manufacturing sites. North American coating manufacturers test lease-to-own procurement models for project-based capacity.
Vertical homogenizers sit at the top of the volume ranking, with custom fabricated tanks climbing the fastest.
Technology:
Pressure vessel classification splits the technology landscape, with high-pressure processing systems requiring TGA or SAMR certification and ultrasonic homogenization operating below regulatory thresholds.
- Rotor-Stator Mixing:Shear-controlled particle size reduction achieves precise dispersion in viscous suspensions. Food processing plants specify rotor-stator systems for plant-based protein emulsions where texture consistency determines product acceptance.
- High-Pressure Processing:Intensifier pump systems achieve sub-micron particle distribution in abrasive mineral slurries. Mining companies in Australia expand adoption despite inspection queue delays from limited certifier capacity.
- Mechanical Agitation:Impeller-based mixing serves cost-sensitive cement processing installations. Standardized drive trains simplify maintenance protocols for brownfield plant operators.
- Ultrasonic Homogenization:Probe-based systems bypass tank infrastructure for laboratory-scale chemical production. Batch volumes below 500 liters increasingly substitute tank-based processing entirely.
Mechanical agitation maintains the largest installed base, though high-pressure processing gains share fastest in mining applications.
Application:
Material abrasion severity and regulatory exposure vary sharply across applications, with mineral treatment facing MEE discharge scrutiny and food processing navigating FSSAI safety protocols.
- Cement Processing:Clinker blending and raw meal homogenization demand abrasion-resistant lining systems. India's infrastructure investment acceleration drives fleet expansion for highway and dam construction material supply.
- Mineral Treatment:Copper-gold concentrator circuits require alumina-zirconia composite coatings for high-velocity slurry duty. Chilean operations specify 80,000-hour shell life targets to compress replacement cycles.
- Chemical Blending:Jacketed cooling capabilities support temperature-sensitive reactions. European producers retrofit cooling systems for F-Gas Regulation refrigerant compatibility.
- Food Processing:Shear-sensitive formulations require precise agitation control. Plant-based protein suspensions open adjacent demand channels beyond traditional industrial applications.
- Paint Manufacturing:VOC emission controls under EPA guidelines shape equipment specifications. Coating manufacturers prioritize sealed tank designs with vapor recovery integration.
Cement processing commands the greatest unit volume, while mineral treatment shows the steepest expansion trajectory.
End User Industry:
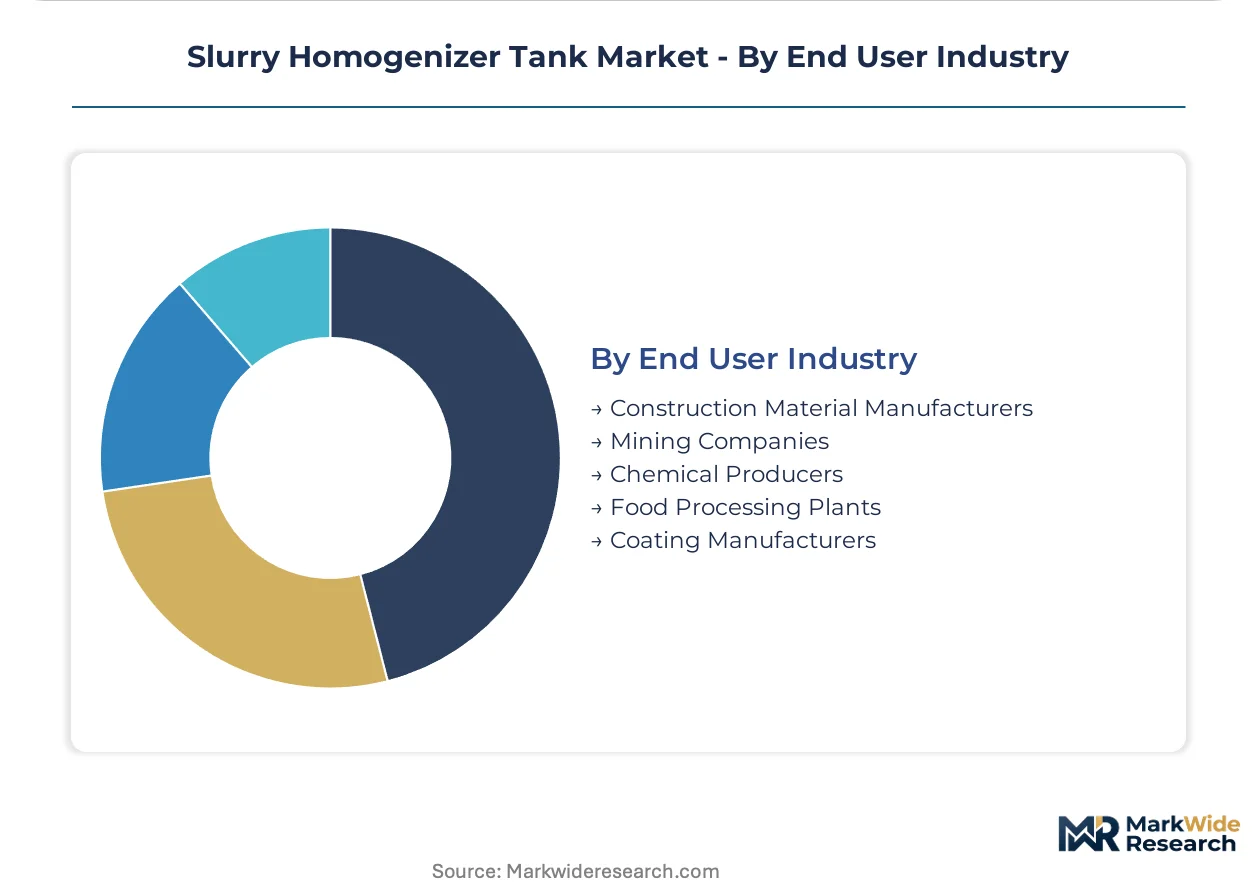
Capital intensity and technical sophistication diverge across end users, with mining companies specifying custom engineered solutions and construction material manufacturers prioritizing standardized procurement.
- Mining Companies:Site-specific metallurgical requirements and abrasive duty specifications drive custom fabrication demand. Australian operators contract performance guarantees independently from OEM service agreements.
- Construction Material Manufacturers:Standardized vertical homogenizers serve clinker and aggregate processing needs. Portable tank rental channels shift capital allocation from ownership to operating expenditure.
- Chemical Producers:REACH authorization protocols restrict chromium-based hardfacing alloys. German facilities absorb extended material requalification timelines to maintain CE-marked equipment access.
- Food Processing Plants:FSSAI safety certification requirements govern equipment selection. Shear-controlled homogenization technology penetrates plant-based protein processing lines.
- Coating Manufacturers:EPA emissions guidelines and OSHA pressure vessel standards shape procurement criteria. Carbon steel tariff volatility squeezes margin predictability for North American tank builders.
Construction material manufacturers represent the largest addressable base, with mining companies expanding most quickly through high-pressure processing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial homogenization technology first achieved commercial scale in German chemical processing facilities during the mid-20th century, establishing design principles that spread through European mining and food sectors before diffusing to resource economies worldwide.
Australia
Iron ore and copper-gold concentrator operators in Western Australia are expanding high-pressure processing system fleets to handle rising throughput demands. TGA pressure vessel certification requirements create inspection queue bottlenecks that extend project timelines for imported equipment. The Pilbara region hosts the densest concentration of slurry homogenizer installations, with mine operators contracting performance guarantees independently from OEM service agreements.
China
Cement processing facilities in Shandong and Jiangsu provinces are retrofitting vertical homogenizers to meet clinker blending demands from high-speed rail and dam construction projects. SAMR enforcement of GB standards for industrial mixing equipment safety is forcing foreign manufacturers to upgrade safety interlock systems on imported tanks. The Yangtze River Delta industrial corridor concentrates domestic tank fabrication capacity, with local producers capturing share from European suppliers.
India
Infrastructure investment acceleration is driving fleet expansion at cement processing plants in Gujarat and Rajasthan to supply highway and dam construction materials. FSSAI safety certification requirements govern equipment selection for emerging food processing applications including plant-based protein suspensions. The Mumbai-Pune industrial belt is emerging as a fabrication hub for rubber-lined carbon steel tanks serving mineral treatment operations.
Chile
Copper-gold concentrators in the Atacama Desert are specifying alumina-zirconia composite coatings to extend tank shell life beyond 80,000 operating hours in high-velocity slurry applications. The national mining regulator enforces pressure vessel inspection protocols that align with ASME standards for imported equipment. Antofagasta and Calama host the most intensive concentration of abrasive-duty homogenizer installations in South America.
Germany
Chemical blending facilities in North Rhine-Westphalia are absorbing extended material requalification timelines to maintain CE-marked equipment access under REACH authorization protocols restricting chromium-based hardfacing alloys. The EU F-Gas Regulation is driving cooling jacket retrofits for low-global-warming-potential refrigerant compatibility. The Ruhr industrial region anchors European demand for specialized high-pressure processing systems.
Slurry Homogenizer Tank Market Competitive Landscape
The competitive structure tilts toward diversified industrial equipment conglomerates with captive process engineering capabilities. Market concentration is moderate, with a handful of European and North American multinationals commanding premium positions in high-pressure and food-grade segments while regional fabricators compete on cost for standard mining applications. Three archetypes dominate: full-line industrial equipment suppliers with integrated service networks, specialized mixing technology houses with proprietary rotor-stator designs, and regional tank fabricators serving site-specific procurement requirements. Capacity expansion and strategic partnerships represent the dominant competitive moves, as established players seek to secure welding certification capacity and local content qualifications in resource-rich jurisdictions.
Among European-based industrial conglomerates, GEA Group Aktiengesellschaft and Alfa Laval AB occupy positions anchored by long-term service contract capabilities and specialized high-pressure processing expertise. SPX Flow, Inc. represents the North American diversified equipment archetype with exposure to portable tank configurations. Wahal Engineers and PRODOMIX exemplify regional specialists serving site-specific metallurgical and dimensional requirements in Asian markets. These named entities serve as reference points for understanding how geographic footprint, certification breadth, and service bundling differentiate competitive positioning across procurement segments.
| Leading Market Players |
|---|
| Matec Industries |
| PRODOMIX |
| Quadro Liquids |
| Silverson Machines Ltd. |
| Wahal Engineers |
| GEA Group Aktiengesellschaft |
| SPX Flow, Inc. |
| Alfa Laval AB |
| Niro Soavi |
| Others |
Pricing and Supply Chain Analysis
Captive welding certification capacity in Western Australia and North Rhine-Westphalia anchors both supply security and pricing power for premium pressure vessel fabricators. This integration pattern insulates ASME-qualified producers from certification queue bottlenecks while supporting sustained margin premiums over regional competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified custom fabrication from modular vertical units and portable skid-mounted configurations. Certification grade and after-sales service bundling drive price differentiation, with TGA-recognized inspection credentials commanding substantial premiums. Cost compression in the standard tier intensifies because Chinese domestic producers exploit GB standards familiarity to undercut European imports. Mining companies exhibit the least price sensitivity due to performance guarantee requirements, while construction material manufacturers prioritize economy-tier procurement.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining operator demand, while distributor networks serve fragmented coating manufacturer procurement. Supply concentrates in Germany, China, and India, with the Yangtze River Delta and Mumbai-Pune belt hosting dense fabrication clusters. Raw material flows draw from Swedish specialty steel mills, Australian alumina-zirconia ceramic suppliers, and domestic carbon steel producers. Tariff exposure on rubber lining imports from Southeast Asia represents the dominant structural risk. Distribution runs through long-term service contracts for premium tiers and spot procurement for portable configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Infrastructure investment acceleration in India and Australia's mining expansion are shifting procurement toward premium specifications with extended service life guarantees.
For Market Incumbents: Acquire TGA-recognized pressure vessel certification capacity to defend against inspection queue bottlenecks. Consolidate backward integration into alumina-zirconia ceramic coating supply to secure abrasive-duty performance differentiation. Expand welding certification training pipelines in Western Australia to capture mining operator performance guarantee contracts independently from OEM service agreements. For New Entrants and Emerging Players: Capture Brazilian iron ore beneficiation plant demand by offering ANVISA-compatible material certifications where standardized homogenization infrastructure remains underdeveloped. Target Chilean copper-gold concentrator retrofits with alumina-zirconia composite coating expertise. Lead with lease-to-own portable tank models to shift construction material manufacturer capital allocation from ownership to operating expenditure. For Investors and Strategic Acquirers: Roll-up economics work for regional tank fabricators with captive welding certification capacity because ASME Section IX-qualified welder scarcity extends delivery timelines and protects incumbent pricing power. Five-to-ten year viability hinges on installed base expansion for cooling jacket retrofit services under EU F-Gas Regulation compliance mandates. Watch for ultrasonic homogenization substitution rates in laboratory-scale chemical production as volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Mining Corridors | Pilbara region demand from Australian iron ore operators justifies localized fabrication footprint. |
| Backward Integration into Ceramic Coatings | Alumina-zirconia composite supply control extends tank shell life beyond 80,000 operating hours. |
| Long-term Service Agreement | Performance guarantee contracts with Western Australian gold producers shift revenue toward recurring streams. |
| Certification Investment | SAMR GB standards compliance opens Yangtze River Delta cement processing retrofit opportunities. |
| Joint Venture | Local content partnerships in Gujarat and Rajasthan accelerate infrastructure project fleet deployment. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and aftermarket service heads, secondary validation through customs trade data and SEC filings, and technical specification analysis — were reconciled to construct market estimates. Conversations with maintenance directors at cement processing facilities, OEM procurement teams specifying metallurgical requirements, and distribution channel partners supplying rubber-lined carbon steel components informed demand-side assumptions. Bottom-up unit economics triangulated against top-down industrial equipment spending patterns to anchor volume projections.
Data-stream reconciliation across product type, technology, application, and end-user industry dimensions shaped the analytical framework across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation rather than single-point extrapolation. Modeled inputs included India's infrastructure investment acceleration, Australia's high-pressure processing system adoption curves, and REACH authorization protocol impacts on German chemical blending facility procurement.
Carbon steel tariff volatility, TGA certification queue extensions, and ultrasonic homogenization substitution in sub-500 liter batch production are the dominant revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Membrane Bioreactor (MBR) Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
Water Purification Systems Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Produced Water Treatment Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Water Free/ Waterless Urinals Market
Water & Sludge Treatment
Europe Boiler Water Treatment Chemicals Market