
 Global Fluorosurfactants Market | 2026-2036
Global Fluorosurfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fluorosurfactants Market Foresight
Multi-source procurement among coatings formulators is consolidating as large consumers seek supply security against fluorochemical feedstock volatility. The Chemours Company leverages its integrated fluoroproducts chain to sustain North American supply leadership. Solvay anchors European demand through specialty perfluoropolyether grades for semiconductor etching applications. Daikin Industries dominates Asian supply with captive fluoropolymer manufacturing and direct channel control into Japanese electronics fabrication.
Fluorosurfactants are surface-active agents containing perfluorinated alkyl chains that reduce surface tension below 20 mN/m, enabling wetting of low-energy substrates such as polyolefins and fluoropolymers through selective fluorophilic-hydrophilic molecular architecture. Perfluoroalkyl carboxylic acids retain the largest volume share in coatings applications where extreme surface tension reduction commands premium formulation value. Semiconductor manufacturing represents the fastest-expanding application segment as advanced node lithography and wet-etch processes demand ultrapure fluorosurfactant chemistries with sub-ppb metal contamination specifications.
EPA regulation of long-chain perfluoroalkyl substances under TSCA Section 5 and EU REACH restrictions on C8-based fluorotelomers are reshaping product registration requirements and reformulation timelines across major supply corridors. ECHA classification of perfluorooctanoic acid as a substance of very high concern has triggered substitution mandates that favor short-chain fluorosurfactants and fluorine-free alternatives in European coatings and textile treatment markets. Stakeholders must monitor regulatory divergence between EPA, ECHA, and China's MEE as compliance complexity becomes a primary determinant of market access and product portfolio viability.
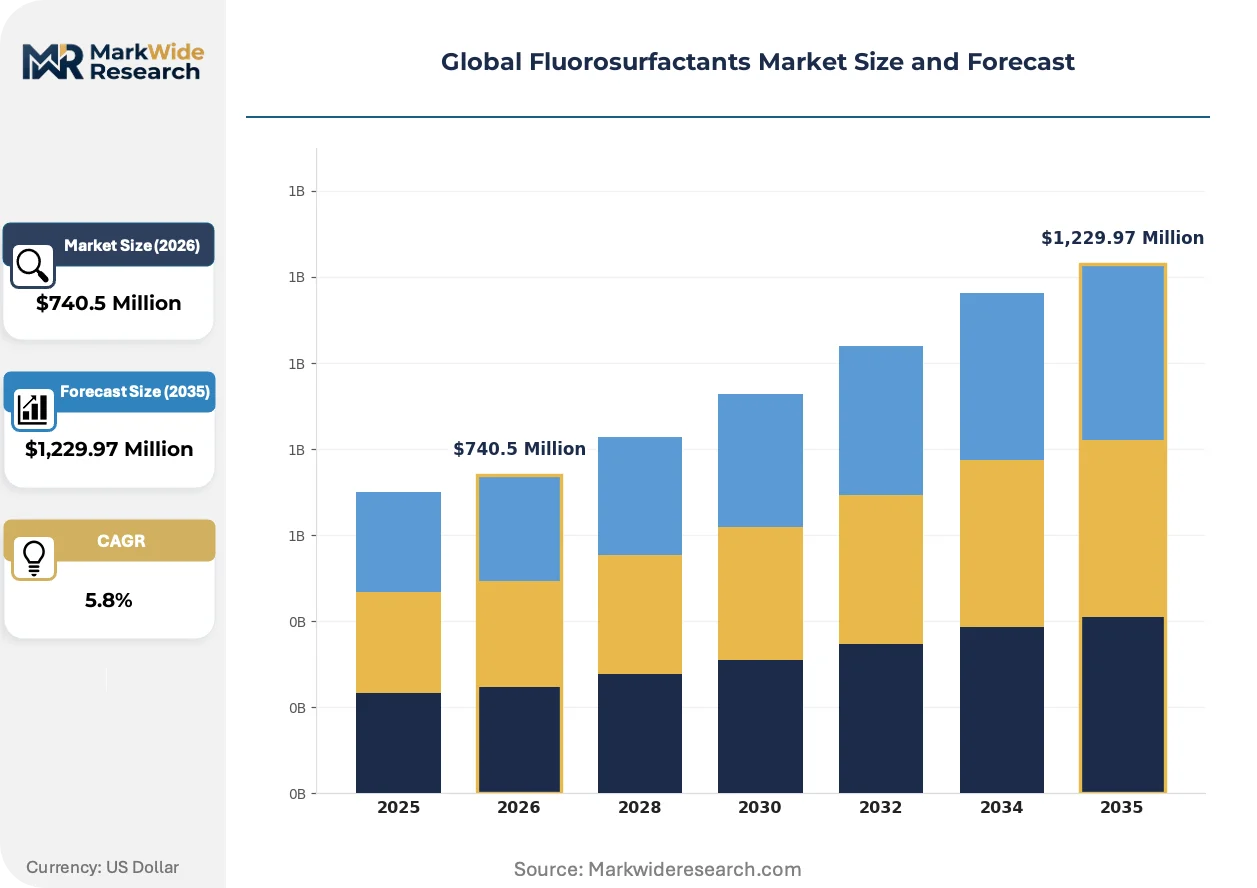
Market Dynamics
REACH restrictions on long-chain perfluorinated compounds are forcing wholesale reformulation across European coatings and textile supply chains, compressing product development timelines while opening substitution windows for short-chain and fluorine-free alternatives.
Growth Catalysts
- Semiconductor node advancement:Sub-7nm lithography and wet-etch processes in Taiwan and South Korea are mandating ultrapure fluorosurfactant chemistries with sub-ppb metal contamination specifications.
- China's MEE enforcement tightening:Stricter environmental compliance in the Yangtze River Delta electronics fabrication corridor is accelerating procurement of specialized surfactant grades from domestic and qualified import sources.
- Automotive coatings performance premium:Electrophoretic and clearcoat systems for electric vehicle platforms in Germany and the United States are specifying fluorosurfactants for superior leveling on complex polypropylene substrates.
Market Restraints
- Fluorochemical feedstock volatility:Hydrofluoric acid and tetrafluoroethylene supply concentration in Chinese and Japanese production clusters exposes formulators to price spikes and allocation risk.
- ECHA SVHC classification cascade:Perfluorooctanoic acid and related C8-based fluorotelomers face mandatory substitution timelines that invalidate existing product registrations and force costly reformulation.
- Fluorine-free surfactant substitution:Silicone and hydrocarbon alternatives from specialty chemical suppliers are capturing share in lower-performance coatings segments where extreme surface tension reduction is not required.
Strategic Opportunities
- India specialty chemicals expansion:PLI scheme incentives and Gujarat-Maharashtra chemical corridor infrastructure are attracting fluorosurfactant toll manufacturing investments serving domestic paint and electronics markets.
- Perfluoropolyether semiconductor etching grades:Advanced node fabrication in Hsinchu and Pyeongtaek is creating demand for ultra-high-purity fluorosurfactant chemistries with dedicated supply chain qualification protocols.
- Short-chain fluorotelomer regulatory tailwind:EPA TSCA Section 5 and REACH alignment on C6-based chemistry acceptance is enabling product portfolio transitions that preserve fluorosurfactant performance advantages while meeting compliance requirements.
Industry Challenges
- Fluoropolymer synthesis expertise scarcity:Talented process chemists and reactor operators capable of managing telomerization and electrochemical fluorination are concentrated at a handful of legacy production sites.
- Multi-jurisdiction registration synchronization:Divergent EPA, ECHA, and MEE data requirements and review timelines force parallel submission strategies that extend product launch windows by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fluorosurfactants Market |
| Market Size in 2026 | $740.5 Million |
| Market Size in 2035 | $1,229.97 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
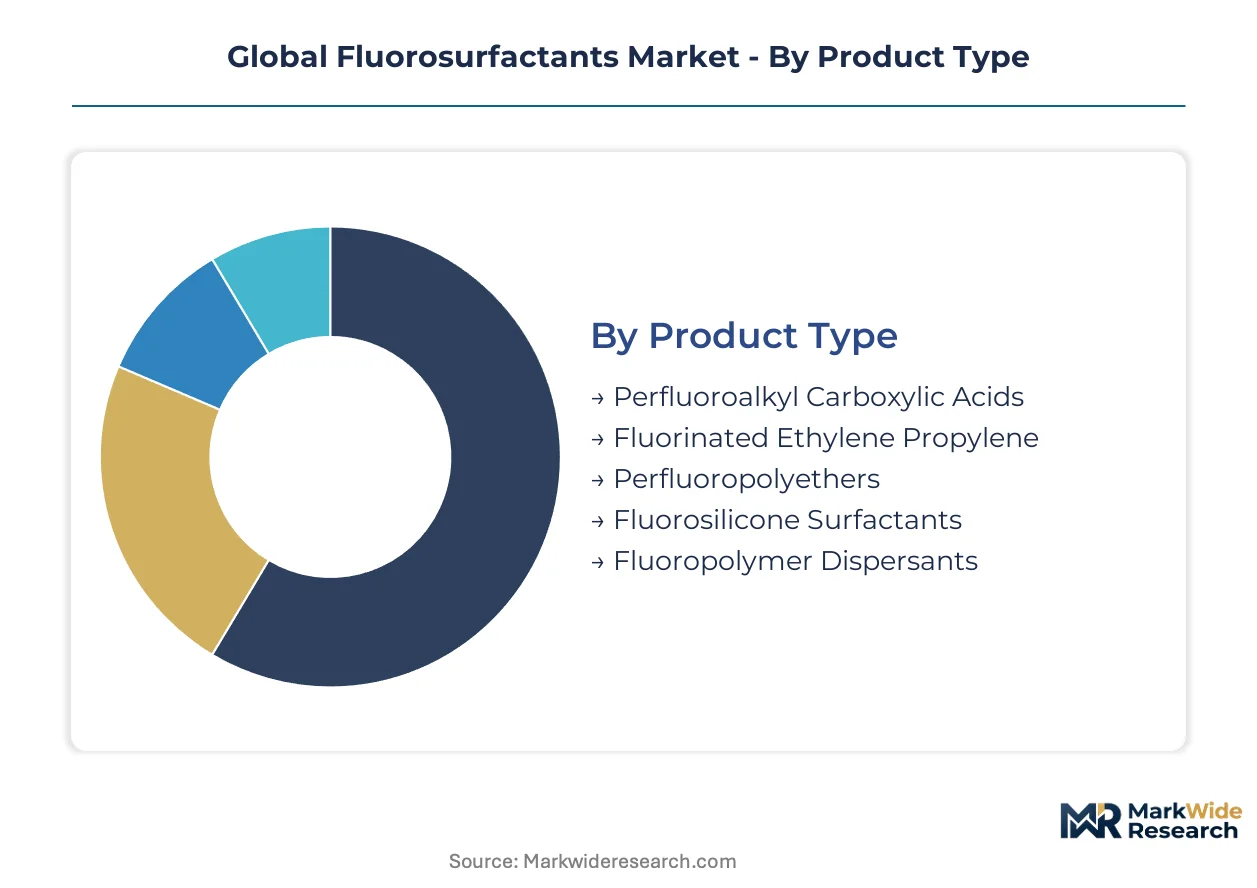
| Segmentation | Product Type: Perfluoroalkyl Carboxylic Acids, Fluorinated Ethylene Propylene, Perfluoropolyethers, Fluorosilicone Surfactants, Fluoropolymer Dispersants Application: Coatings, Firefighting Foams, Oil Recovery, Semiconductor Manufacturing, Textile Treatment End User Industry: Petrochemical Refineries, Electronics Fabrication, Paint Manufacturing, Oilfield Services, Textile Processing Form: Liquid, Powder, Emulsion, Gel, Granules |
| Companies Covered | The Chemours Company, 3M, Solvay, AGC, DIC Corporation, Daikin Industries, Merck KGaA, Arkema, Pilot Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fluorosurfactants Market Shifts & Advancements
Reformulation pressure from regulatory authorities is compressing product development cycles and forcing simultaneous investment in short-chain fluorosurfactant platforms and fluorine-free alternatives across major supply corridors.
Short-chain perfluoroalkyl carboxylic acid technology is absorbing the functional requirements previously served by C8-based chemistries in coatings and textile treatment applications. Automotive OEMs in Stuttgart and Detroit are qualifying these reformulated systems for new platform launches. The technology is absorbing volume from displaced long-chain products while manufacturers rebuild registration dossiers.
EU F-Gas Regulation amendments and ECHA restriction proposals on per- and polyfluoroalkyl substances are tightening acceptable emission thresholds across industrial applications. Coatings formulators face accelerated substance evaluation timelines that compress reformulation windows. German and French industrial paint manufacturers are responding by dual-tracking fluorosurfactant and silicone-hybrid development programs.
Direct technical service engagement is displacing traditional distributor-led specification selling in semiconductor and aerospace end-uses. Specialty chemical suppliers are embedding application engineers at customer R&D facilities in Hsinchu, Dresden, and Austin. This pattern is most pronounced in Taiwan and South Korea where foundry process chemistry decisions centralize at individual fabrication sites.
Global Fluorosurfactants Market Segmentation
Fluorosurfactant specifications diverge sharply across end-use requirements, with semiconductor-grade purity standards, coatings performance thresholds, and firefighting foam environmental compliance creating distinct product architectures. Formulators must match molecular chain length, fluorine content, and counterion selection to substrate chemistry and regulatory jurisdiction.
Product Type:
Technical specifications governing surface tension reduction, thermal stability, and chemical resistance define product selection across industrial applications.
- Perfluoroalkyl Carboxylic Acids:Linear perfluorinated chains with terminal carboxylic acid functionality achieve surface tension below 15 mN/m. Coatings formulators in Stuttgart and Detroit specify these grades for automotive clearcoat leveling on polypropylene substrates. REACH restrictions on C8 chain lengths are forcing reformulation toward C6 homologues with retained performance.
- Perfluoropolyethers:Ether-linked perfluorinated backbones deliver exceptional thermal oxidative stability above 300°C. Semiconductor etching applications in Hsinchu and Pyeongtaek demand sub-ppb metal contamination specifications that only electrochemical fluorination routes can achieve. This segment is expanding most quickly as advanced node fabrication proliferates.
- Fluorinated Ethylene Propylene:Copolymer surfactants derived from tetrafluoroethylene-hexafluoropropylene offer chemical inertness in aggressive media.
- Fluorosilicone Surfactants:Hybrid architectures combining siloxane backbones with perfluorinated side chains enable substrate wetting across polar and non-polar surfaces.
- Fluoropolymer Dispersants:Stabilizing agents for PTFE and PVDF particle suspensions in aqueous and solvent-based systems.
Mature deployment sits with Perfluoroalkyl Carboxylic Acids in industrial coatings. Newer deployment is concentrated in Perfluoropolyethers for semiconductor process chemistry.
Application:
Performance requirements and regulatory exposure vary substantially across application segments, dictating molecular architecture and supply chain qualification intensity.
- Semiconductor Manufacturing:Photoresist developers, etchants, and cleaning formulations require ultrapure fluorosurfactants with particle counts below specification thresholds. Taiwan and South Korean foundries enforce dedicated supply chain qualification protocols that exclude non-qualified sources. EPA and MEE alignment on contamination limits is harmonizing procurement standards across major fabrication corridors.
- Coatings:Architectural, industrial, and automotive formulations exploit extreme surface tension reduction for substrate wetting and defect elimination. German OEMs are dual-tracking fluorosurfactant and silicone-hybrid development programs in response to EU F-Gas Regulation amendments. Performance premiums sustain specification despite substitution pressure.
- Firefighting Foams:Aqueous film-forming foams depend on fluorosurfactant synergy with hydrocarbon surfactants for fuel surface sealing.
- Oil Recovery:Enhanced oil recovery formulations leverage fluorosurfactant partitioning behavior in high-salinity reservoir conditions.
- Textile Treatment:Stain-resistant and oil-repellent fabric finishes utilize C6-based fluorotelomer technologies following ECHA SVHC classification of C8 alternatives.
Established volume concentrates in Coatings. Steepest expansion trajectory belongs to Semiconductor Manufacturing.
End User Industry:
Procurement sophistication and technical service requirements differentiate customer segments, with direct manufacturer engagement displacing distributor channels in qualified applications.
- Electronics Fabrication:Foundry process chemistry decisions centralize at individual fabrication sites in Dresden, Hsinchu, and Austin. Specialty chemical suppliers embed application engineers at customer R&D facilities to secure specification. MEE enforcement tightening in the Yangtze River Delta is accelerating procurement of qualified surfactant grades.
- Paint Manufacturing:Industrial and automotive coatings producers consolidate procurement among qualified suppliers to secure feedstock availability. Multi-source strategies are compressing as large consumers seek supply security against fluorochemical volatility.
- Petrochemical Refineries:Process anti-fouling and separation applications consume fluorosurfactant chemistries in high-temperature hydrocarbon environments.
- Oilfield Services:Drilling fluid and completion chemical formulators specify fluorosurfactants for extreme pressure-temperature stability.
- Textile Processing:Finish applicators in European and East Asian manufacturing clusters reformulate in response to perfluorinated substance restrictions.
Longstanding integration characterizes Paint Manufacturing. Emerging specification intensity defines Electronics Fabrication.
Form:
Physical presentation determines handling logistics, formulation compatibility, and active content delivery economics across customer operations.
- Liquid:Solution and dispersion formats dominate coatings and semiconductor process chemistry applications. Pumpable delivery enables automated dosing in continuous manufacturing environments. Concentrated aqueous and solvent-based variants reduce freight costs for high-volume consumers.
- Emulsion:Aqueous dispersed systems with controlled particle size distribution suit waterborne coatings and textile padding applications. Stability against mechanical shear and electrolyte exposure determines specification fitness.
- Powder:Solid fluorosurfactant preparations enable dry blending in powder coatings and masterbatch compounding.
- Gel:Thixotropic formulations target specialized adhesive and sealant applications requiring controlled flow characteristics.
- Granules:Free-flowing solid presentations facilitate metering in automated polymer processing equipment.
Conventional supply favors Liquid formats. Technical differentiation is migrating toward Emulsion systems for waterborne formulation compatibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hydrofluoric acid and tetrafluoroethylene supply clusters in China and Japan anchor fluorosurfactant production geography. Procurement patterns track electronics fabrication corridors and automotive manufacturing concentrations.
United States
Automotive OEMs in Detroit specify fluorosurfactants for electric vehicle clearcoat systems on polypropylene substrates. EPA TSCA Section 5 regulation of long-chain perfluoroalkyl substances is compressing reformulation timelines for coatings manufacturers. Texas and Louisiana host fluorochemical feedstock processing that supplies domestic surfactant synthesis.
Germany
Stuttgart-based automotive coatings formulators drive demand for extreme surface tension reduction in electrophoretic systems. ECHA SVHC classification of perfluorooctanoic acid triggers mandatory substitution mandates across industrial paint supply chains. The North Rhine-Westphalia chemical corridor concentrates reformulation R&D for short-chain fluorotelomer alternatives.
China
Electronics fabrication clusters in the Yangtze River Delta scale procurement of specialized surfactant chemistries for semiconductor process applications. MEE enforcement tightening accelerates qualification of domestic and import surfactant grades. Domestic fluoropolymer manufacturing in Zhejiang and Jiangsu provinces reduces import dependency for captive surfactant production.
South Korea
Advanced node foundries in Pyeongtaek mandate ultrapure fluorosurfactant chemistries with sub-ppb metal contamination specifications for wet-etch processes. Alignment with EPA contamination limits harmonizes procurement standards for multinational fabrication operations. The Seoul Capital Area centralizes process chemistry decisions at individual fabrication sites with dedicated supply chain qualification protocols.
Japan
Electronics fabrication in Kyushu and Nagoya regions sustains demand for perfluoropolyether grades with thermal oxidative stability above 300°C. METI oversight of fluorochemical emissions shapes acceptable thresholds for industrial surfactant applications. Daikin Industries' captive fluoropolymer manufacturing in Osaka Prefecture anchors direct channel control into domestic fabrication facilities.
Global Fluorosurfactants Market Competitive Landscape
Global majors compete with regional champions across integrated fluoroproducts chains and specialty perfluoropolyether grades. The vendor base stratifies between integrated chemical conglomerates with captive fluoropolymer production and specialty surfactant formulators serving qualified semiconductor applications. Three archetypes dominate: integrated fluoroproducts suppliers with backward control over tetrafluoroethylene feedstock, specialty perfluoropolyether manufacturers serving etching applications, and regional toll manufacturers exploiting local chemical corridor infrastructure. Capacity expansion and portfolio diversification toward short-chain fluorotelomer platforms represent the dominant competitive vectors.
Among integrated fluoroproducts suppliers, The Chemours Company exemplifies the North American archetype with sustained supply leadership through captive manufacturing chains. Solvay occupies a comparable position in European specialty grades, while Daikin Industries anchors Asian supply with direct channel control into Japanese electronics fabrication. These three companies represent distinct geographic anchoring strategies rather than direct product competition, with each exploiting regional feedstock access and customer proximity to defend specification positions in qualified applications.
| Leading Market Players |
|---|
| The Chemours Company |
| 3M |
| Solvay |
| AGC |
| DIC Corporation |
| Daikin Industries |
| Merck KGaA |
| Arkema |
| Pilot Chemical |
| Others |
Supply & Pricing Matrix
Integrated chemical conglomerates with sovereign wealth backing and family-rolled legacy producers anchor fluorosurfactant supply, translating captive tetrafluoroethylene access into pricing discipline that resists spot-market volatility while compressing margins for non-integrated formulators.
Pricing Analysis
Warranty and technical service bundling separates semiconductor-grade fluorosurfactant quotations from unbundled coatings-grade transactions, with foundry qualification protocols commanding premium inclusion of application engineering support. Three-tier pricing structure across semiconductor purity, industrial performance, and textile treatment grades reflects certification intensity and metal contamination thresholds. Cost compression in coatings applications is intensifying because silicone-hybrid alternatives capture specification share where extreme surface tension reduction is dispensable. Paint manufacturers exhibit highest price sensitivity due to reformulation frequency, while semiconductor foundries prioritize supply security over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Taiwan and South Korean foundries force qualification of secondary fluorosurfactant suppliers despite electrochemical fluorination expertise concentrating at legacy Japanese and Belgian production sites. Feedstock supply draws from hydrofluoric acid clusters in China and Japan, with tetrafluoroethylene availability tethered to fluoropolymer manufacturing economics. Single-source vulnerability concentrates in perfluoropolyether electrochemical fluorination routes, where reactor qualification timelines extend procurement risk. Distribution runs through direct technical service channels for semiconductor applications and regional chemical distributors for coatings formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory substitution mandates across EPA, ECHA, and MEE jurisdictions are compressing reformulation timelines and forcing sub-scale fluorosurfactant producers toward exit or acquisition, consolidating viable supply around integrated feedstock owners and qualified specialty manufacturers.
For Market Incumbents: Deepen backward integration into hydrofluoric acid and tetrafluoroethylene feedstock to secure margin position against volatile fluorochemical raw material markets. Expand electrochemical fluorination capacity in Zhejiang or Jiangsu provinces to capture Yangtze River Delta semiconductor procurement growth. Accelerate C6-based fluorotelomer registration dossiers ahead of ECHA substitution deadlines to lock in coatings specification continuity.
For New Entrants and Emerging Players: Toll manufacturing partnerships with Gujarat-Maharashtra chemical corridor infrastructure offer lowest-capital entry into India paint and electronics markets. Target textile treatment applications in European manufacturing clusters where C6 reformulation demand outpaces incumbent capacity response. Embed application engineers at Dresden foundry R&D facilities to secure qualification through direct technical service engagement.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialty surfactant formulators with existing semiconductor customer qualifications in Taiwan or South Korea. Long-term viability hinges on electrochemical fluorination asset ownership and registration dossier completeness across EPA, ECHA, and MEE jurisdictions. Watch for MEE enforcement intensity in the Yangtze River Delta as inflection indicator for domestic Chinese procurement substitution timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorochemical Feedstock | Captive hydrofluoric acid supply insulates Chemours and Daikin from Chinese export volatility. |
| Electrochemical Fluorination Capacity Expansion | Sub-ppb metal purity specifications for Hsinchu foundries require dedicated reactor investment. |
| Short-Chain Fluorotelomer Registration Dossier Investment | ECHA acceptance of C6 chemistry enables portfolio transition ahead of C8 substitution mandates. |
| Direct Technical Service Channel Development | Embedded application engineers at Austin and Dresden secure semiconductor process chemistry specification. |
| Regional Toll Manufacturing Partnership | PLI scheme incentives in Gujarat attract fluorosurfactant production serving domestic Indian demand. |
Research Methodology
Document review covered SEC 10-K filings, ECHA registration dossiers, and customs trade data, complemented by interviews with fluorosurfactant plant managers, coatings procurement leads at Stuttgart and Detroit automotive OEMs, semiconductor process chemistry directors in Hsinchu and Pyeongtaek, and specialty chemical distribution channel partners. Bottom-up volume modeling triangulated against top-down fluoropolymer feedstock consumption analysis validated market sizing across the projection horizon.
Cross-reference between historical fluorosurfactant price series and expert panel input on reformulation timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled included product chain length, end-use application intensity, regional regulatory cluster, and customer qualification tier. CAGRs derived from fluorochemical feedstock capacity expansion schedules and semiconductor node migration patterns.
Caveats apply where ECHA restriction proposal amendments or MEE enforcement intensity shifts could materially shift the outlook for short-chain fluorotelomer acceptance timelines. Deviation in tetrafluoroethylene feedstock availability from Zhejiang production clusters would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Surfactant EOR Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Cyclotetrasiloxane Market
Surfactants
Dodecanol Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Superwetting Surfactants Market
Surfactants
Global Detergent Polymers Market
Surfactants
Isopropyl Myristate Market
Surfactants
Sulfosuccinate Market
Surfactants
Defoamers Market
Surfactants
TEA Esterquats Market
Surfactants
Sodium Naphthalene Sulphonate Formaldehyde Market
Surfactants
Dioctyl Sulfosuccinates Components Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Polysorbate 40 Market
Surfactants
Sulfate Free Body Wash Market