
 Sodium Lauroyl Sarcosinate Market | 2026-2036
Sodium Lauroyl Sarcosinate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Lauroyl Sarcosinate Market Outlook
The capital-intensity divergence between integrated petrochemical giants and specialty surfactant producers is unwinding traditional competitive boundaries in sodium lauroyl sarcosinate supply. BASF SE leverages its backward integration into fatty acid feedstocks to control input costs across cosmetic and pharmaceutical grades. Galaxy Surfactants anchors its position through concentrated manufacturing in India, exporting to formulators in Europe and Southeast Asia. Croda International differentiates via biotechnology-derived routes that appeal to clean-label personal care brands.
Sodium lauroyl sarcosinate is an anionic surfactant synthesized from sarcosine and lauroyl chloride, typically delivered as a 30% aqueous solution with pH 7.5-8.5, valued for its mildness and compatibility with skin and ocular tissue. Cosmetic grade dominates value capture due to premium pricing in sulfate-free personal care formulations, while pharmaceutical grade represents the fastest-expanding margin pool as ophthalmic and topical drug delivery applications multiply. Liquid formulation leads volume shipments for industrial blending efficiency, though powder form is gaining traction in solid detergent tablets and dry shampoo aerosols.
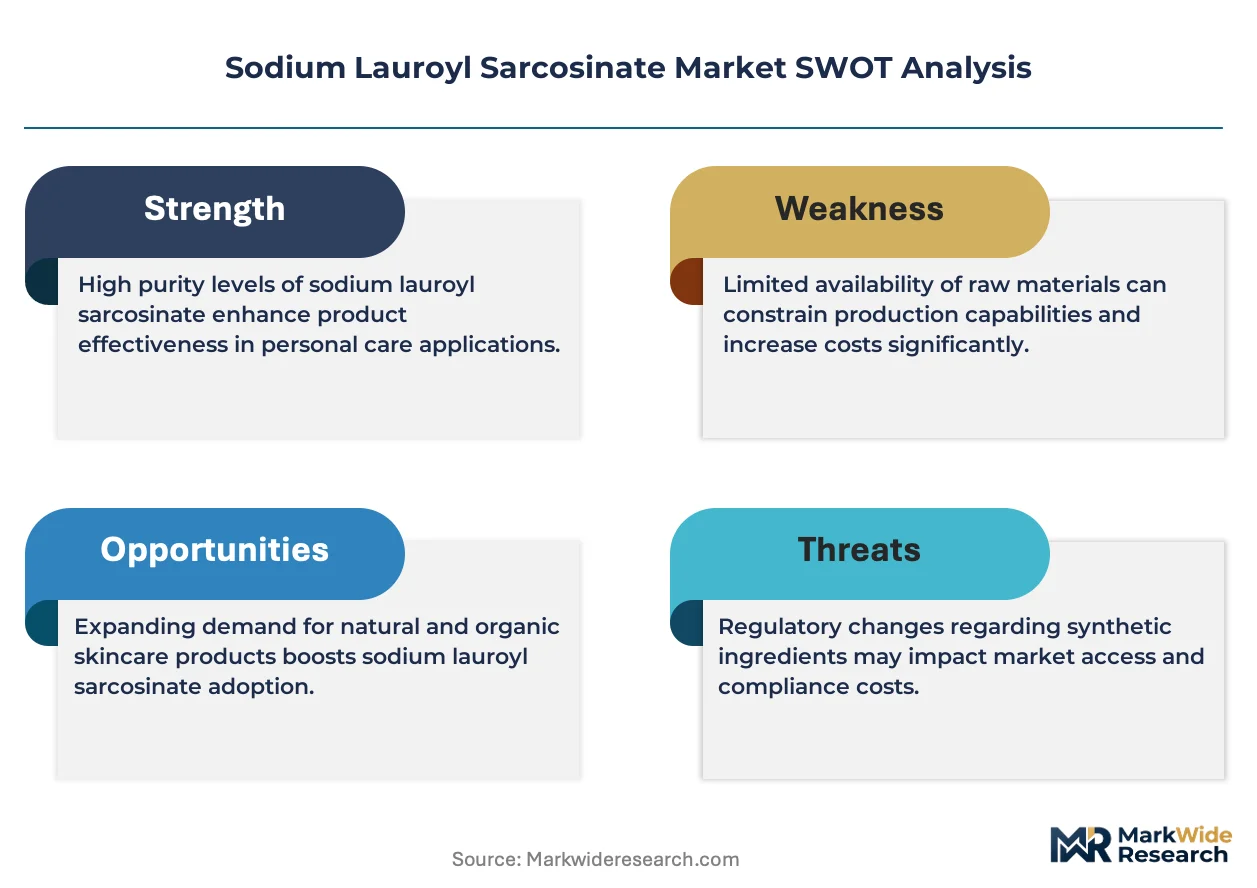
REACH registration requirements and the EU Green Deal's biodegradability mandates are tightening market access for petrochemical-derived surfactants, directly advantaging sarcosinate chemistry. FDA oversight of cosmetic ingredient safety under the Modernization of Cosmetics Regulation Act is elevating documentation burdens for US suppliers, favoring established players with toxicology databases. China's NMPA and GB standards for cosmetic raw materials impose additional testing protocols that filter smaller exporters from the supply base. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration investments with geographic revenue exposure.
Market Dynamics
The sodium lauroyl sarcosinate market is being fundamentally restructured by REACH and EU Green Deal mandates that systematically disadvantage petrochemical-derived surfactants while accelerating procurement of biodegradable amino acid derivatives across personal care formulations.
Growth Catalysts
- REACH Biodegradability Mandates:ECHA registration requirements under REACH Annex VII-VIII are disqualifying conventional alkyl sulfates from cosmetic applications, redirecting formulator procurement toward sarcosinate chemistry that demonstrates rapid aquatic biodegradation.
- Sulfate-Free Personal Care:Premium shampoo and facial cleanser brands in Germany and France are eliminating sodium lauryl sulfate from formulations, creating immediate substitution demand for mild anionic alternatives with comparable foaming profiles.
- Ophthalmic Drug Delivery:Pharmaceutical manufacturers are validating sarcosinate surfactants for ocular tolerance in topical formulations, opening a margin-rich application vertical beyond traditional cosmetic uses.
Market Restraints
- Feedstock Concentration:Lauroyl chloride supply concentrates among integrated petrochemical producers in Germany and the Netherlands, exposing specialty surfactant manufacturers to input cost volatility when fatty acid markets tighten.
- Sarcosine Supply Bottleneck:Pharmaceutical-grade sarcosine production remains limited to three specialized chemical manufacturers globally, constraining capacity expansion for high-purity cosmetic and pharmaceutical grades.
- Preservative System Complexity:Aqueous sarcosinate solutions require carefully balanced preservation against microbial contamination, adding formulation cost and technical risk that simpler surfactants avoid.
Strategic Opportunities
- India Domestic Market Development:Galaxy Surfactants and local competitors are redirecting export-oriented capacity toward India's expanding middle-class personal care market, where sulfate-free positioning commands premium pricing in urban centers.
- Solid Dosage Form Innovation:Powder-grade sarcosinate penetration into dry shampoo aerosols and detergent tablets is creating new formulation categories that bypass liquid handling infrastructure entirely.
- FDA MoCRA Compliance Services:The Modernization of Cosmetics Regulation Act is elevating toxicology documentation requirements, creating a service revenue stream for suppliers with established safety databases to support smaller brand registrations.
Industry Challenges
- Process Analytical Technology Integration:Batch consistency for pharmaceutical-grade sarcosinate requires real-time monitoring of chloride content and pH, demanding capital investment in PAT infrastructure that mid-scale producers lack.
- Cross-Contamination Protocols:Manufacturers serving both cosmetic and pharmaceutical grades must maintain segregated production lines with validated cleaning procedures, extending changeover times and compressing effective capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Lauroyl Sarcosinate Market |
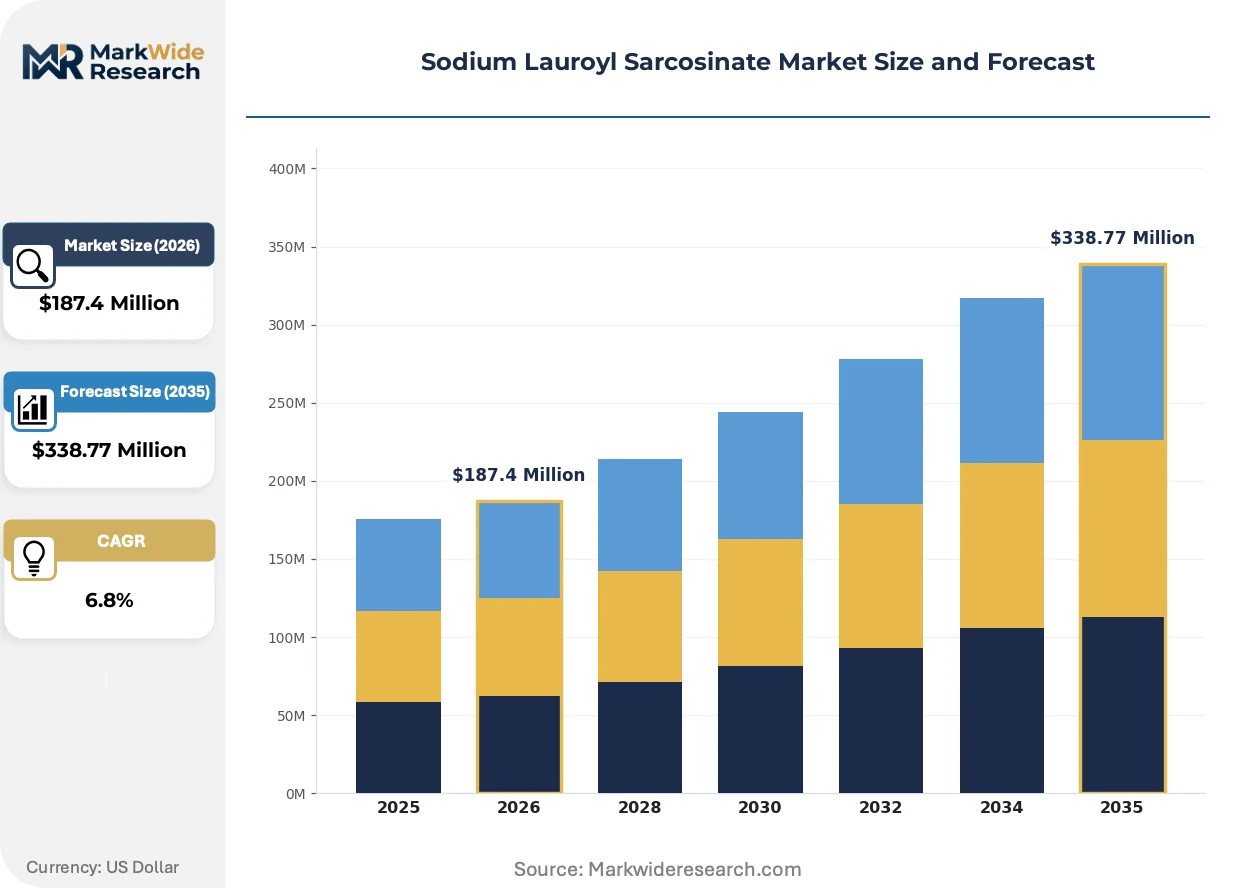
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Industrial Grade, Pharmaceutical Grade, Food Grade Application: Personal Care Products, Household Cleaners, Industrial Cleaners, Food Processing Formulation Type: Liquid Form, Powder Form, Cream Form, Gel Form Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | BASF SE, Croda International, Evonik Industries, Clariant, Innospec, Galaxy Surfactants, Stepan Company, Ashland, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Lauroyl Sarcosinate Market Strategic Shifts
Biotechnology-derived production routes and regulatory compliance automation are actively displacing conventional chemical synthesis and manual documentation processes across the sodium lauroyl sarcosinate value chain.
Enzymatic sarcosine synthesis from renewable feedstocks is bifurcating the supplier base into petrochemical-dependent and biotechnology-enabled camps. Croda International and specialty fermentation houses are scaling enzymatic routes that reduce carbon intensity metrics valued by clean-label cosmetic brands. This technology is bifurcating procurement patterns, with premium personal care brands now requiring biotechnology-derived certification while mass-market formulations tolerate conventional chemical synthesis.
ECHA's 2024 update to REACH Annex XIII biodegradability testing protocols is tightening pass-fail thresholds for surfactant environmental safety. Manufacturers must now demonstrate >60% biodegradation within 28 days using OECD 301B standardized methods, disqualifying several competing anionic surfactant chemistries. German and French formulators are responding by consolidating supplier qualifications around sarcosinate derivatives with pre-validated biodegradation dossiers.
Direct-to-brand ingredient sourcing is compressing traditional distribution layers that previously handled surfactant logistics. Specialty chemical distributors in Western Europe are losing volume to supplier-managed inventory programs where BASF SE and Galaxy Surfactants maintain consignment stock at major personal care manufacturing sites. This channel restructuring is most visible in Germany's Rhine-Ruhr cosmetic production cluster, where just-in-time delivery contracts now specify 48-hour replenishment cycles.
Sodium Lauroyl Sarcosinate Market Segmentation
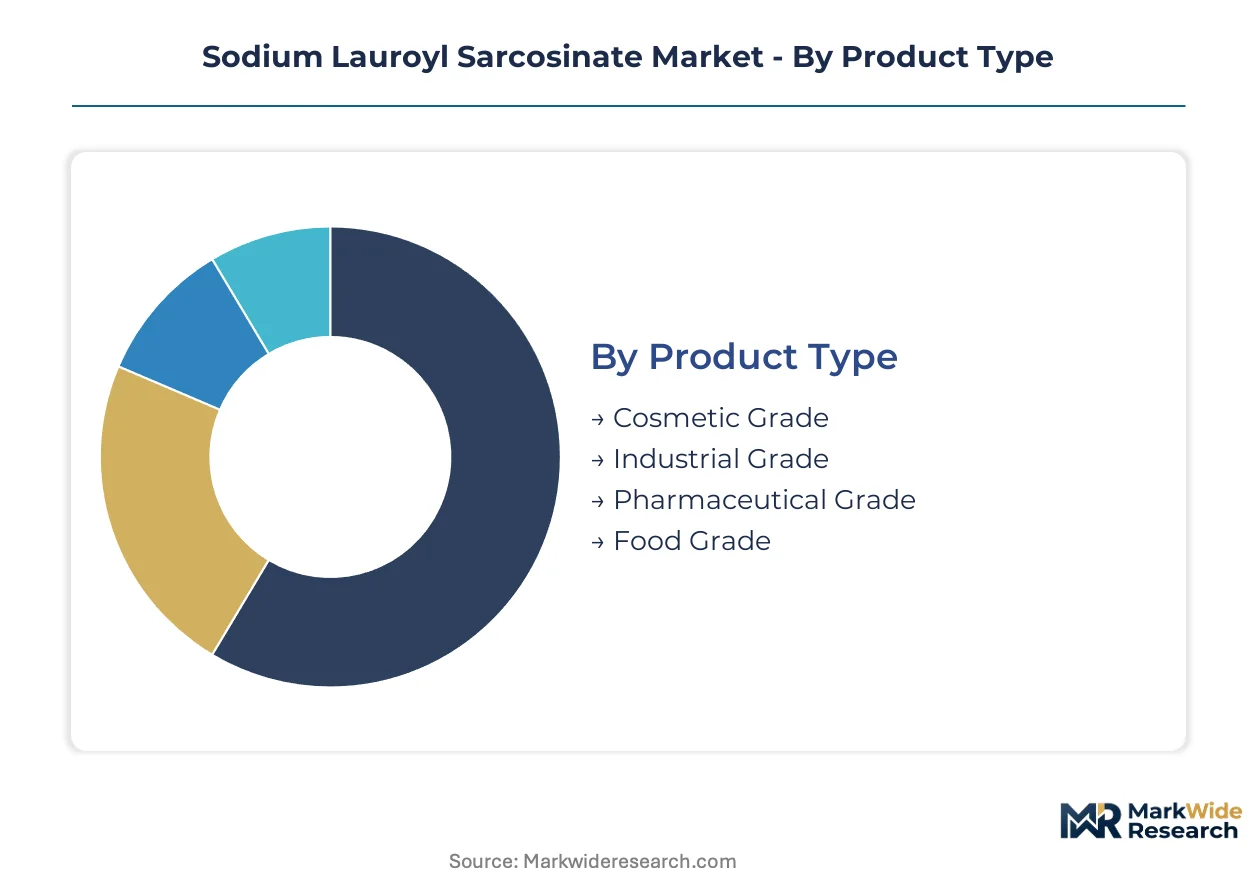
Sodium lauroyl sarcosinate procurement patterns diverge sharply across end-use specifications and formulation requirements. Grade purity thresholds and regulatory documentation burdens create distinct commercial territories that suppliers must navigate separately.
Product Type:
Cosmetic-grade specifications face intensifying substitution pressure from biosurfactants and glucoside chemistry as clean-label brands diversify mild surfactant portfolios. Industrial-grade volumes confront direct displacement by cheaper alkyl sulfates where biodegradability mandates do not apply.
- Cosmetic Grade:This specification demands heavy metal limits below 10 ppm and microbial specifications meeting ISO 16218 standards. German and French formulators in the Rhine-Ruhr cluster specify this grade for sulfate-free shampoos where mildness claims support premium positioning against glucoside alternatives.
- Pharmaceutical Grade:USP-NF compliance with endotoxin testing and validated sterilization protocols distinguishes this tier. Ophthalmic drug manufacturers in Switzerland and the United States are qualifying sarcosinate surfactants for topical formulations, creating documentation-intensive demand that filters out commodity suppliers.
- Industrial Grade:Technical specifications prioritize foaming performance and cost efficiency over purity metrics. Metal degreasing operations in automotive manufacturing clusters tolerate higher chloride residuals in exchange for bulk pricing.
- Food Grade:FSSAI and FDA food contact approvals constrain this segment to a handful of certified producers. Foam control applications in beverage processing and dairy equipment cleaning drive limited but stable offtake.
Cosmetic grade retains volume leadership; pharmaceutical grade holds the steepest expansion curve.
Application:
Cost-tier stratification separates premium personal care formulations from commodity industrial cleaning compounds. Margin structures vary by a factor of three between these application territories.
- Personal Care Products:Facial cleansers, sulfate-free shampoos, and baby care formulations specify sarcosinate for its mildness and ocular tolerance. REACH-compliant European brands pay significant premiums for biodegradable certification that supports green marketing claims.
- Household Cleaners:Dishwashing liquids and laundry detergents incorporate sarcosinate where skin sensitivity positioning differentiates against standard alkyl sulfate formulations. Concentrated liquid refills for subscription delivery models favor this surfactant's stability in aqueous concentrates.
- Industrial Cleaners:Hard surface degreasing and parts washing applications prioritize foaming height and oil emulsification over mildness. Price competition from petroleum sulfonates and phosphate esters constrains sarcosinate penetration to niche food-processing equipment cleaning.
- Food Processing:Conveyor lubricants and CIP (clean-in-place) systems in dairy and beverage plants use food-grade sarcosinate where incidental food contact compliance is mandatory. USDA and 3A Sanitary Standards certification requirements limit supplier qualification.
Personal care products command the highest value per kilogram; household cleaners provide the most stable volume base.
Formulation Type:
Supply chain configuration favors liquid handling infrastructure, though powder investments are accelerating for solid dosage innovation.
- Liquid Form:Aqueous solutions at 30% active concentration dominate industrial blending operations. Tanker truck deliveries to large personal care manufacturing sites minimize handling costs and support just-in-time production scheduling.
- Powder Form:Spray-dried granules with controlled particle size distribution enable dry shampoo aerosols and detergent tablet compression. Solid dosage growth in waterless beauty products is expanding powder specification demand faster than liquid alternatives.
- Cream Form:Pre-thickened concentrates with added rheology modifiers simplify formulation for small-batch cosmetic producers. Contract manufacturers serving indie beauty brands specify this form to reduce processing equipment requirements.
- Gel Form:Transparent aqueous gels with clarity specifications support premium facial cleanser aesthetics. Asian markets particularly value gel viscosity and optical properties for sensory positioning.
Liquid form retains volume leadership; powder form holds the steepest expansion curve.
Distribution Channel:
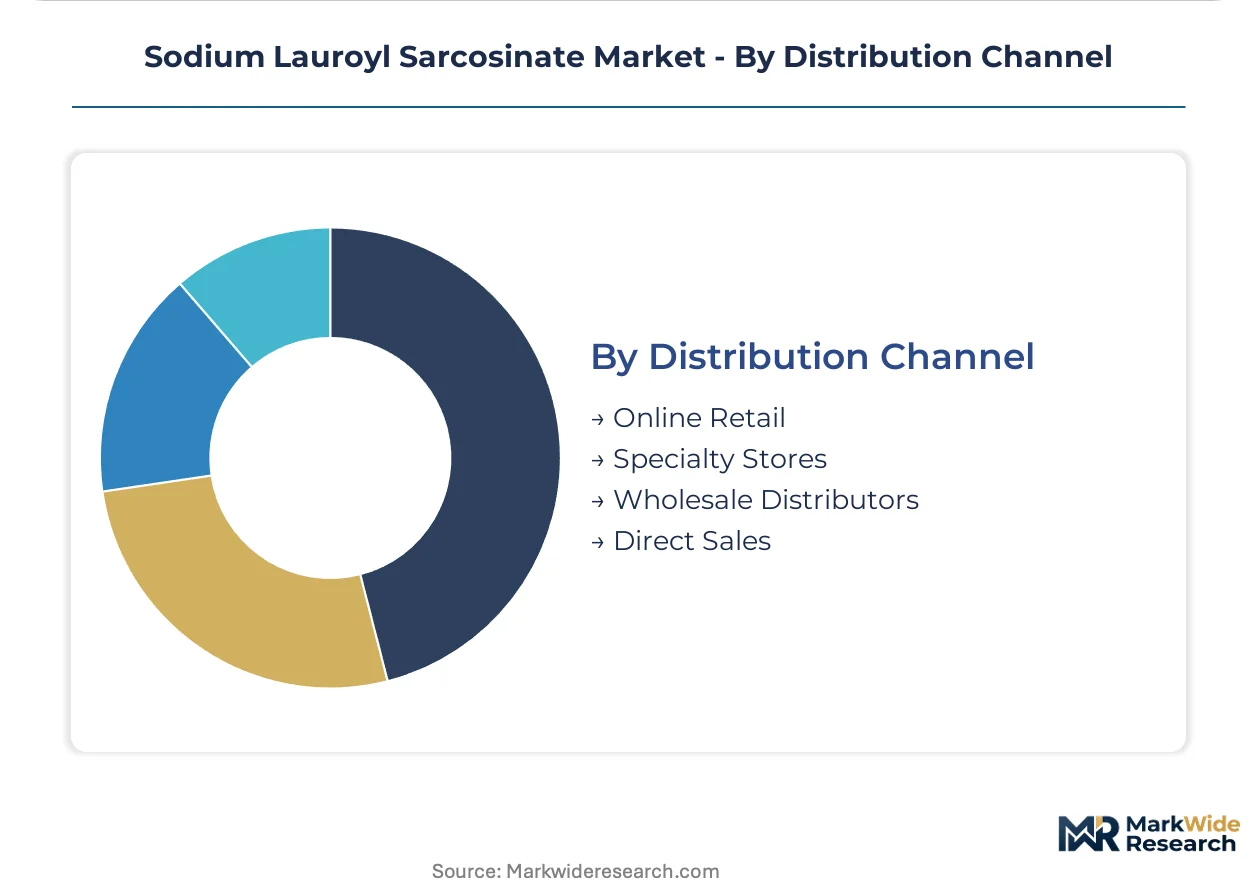
Customer-type stratification separates multinational formulators with direct procurement teams from regional brands dependent on distributor technical support.
- Online Retail:E-commerce platforms serve small cosmetic brands and DIY formulators with kilogram-scale packaging. Alibaba and specialty chemical marketplaces are consolidating this fragmented demand segment.
- Specialty Stores:Regional distributors with technical service capabilities support mid-tier personal care manufacturers. These channels provide formulation guidance and regulatory documentation that commodity traders cannot match.
- Wholesale Distributors:Bulk chemical traders handle standard-grade volumes for industrial cleaning compounders. Inventory pooling across multiple surfactant chemistries reduces working capital requirements for price-sensitive buyers.
- Direct Sales:Supplier-managed inventory programs at major manufacturing sites eliminate distributor margins. BASF SE and Galaxy Surfactants operate consignment stock arrangements with leading personal care brands in Germany and India.
Direct sales capture the highest value contracts; wholesale distributors move the largest aggregate tonnage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes sodium lauroyl sarcosinate predominantly in premium sulfate-free personal care formulations, while India deploys the surfactant across mass-market cleansing products and export-oriented pharmaceutical intermediates. This consumption-mix differential shapes divergent pricing structures and regulatory compliance investments across manufacturing bases.
Germany
Rhine-Ruhr cosmetic manufacturers drive specialty-grade demand for mild anionic surfactants in facial cleansers and baby care products. REACH Annex VII-VIII biodegradability mandates under ECHA oversight disqualify conventional alkyl sulfates from cosmetic applications. Leverkusen and Düsseldorf production clusters host backward-integrated chemical majors supplying premium brands across Western Europe.
United States
Ophthalmic drug delivery applications and clean-label personal care brands propel pharmaceutical-grade consumption in New Jersey and California formulation hubs. FDA Modernization of Cosmetics Regulation Act elevates toxicology documentation burdens, filtering smaller suppliers from the market. Greater Philadelphia's specialty chemical corridor concentrates contract manufacturing for sarcosinate-based topical therapeutics.
India
Galaxy Surfactants anchors export-oriented capacity serving European and Southeast Asian formulators while redirecting volumes toward domestic urban middle-class markets. BIS cosmetic raw material standards and FSSAI food-grade certifications constrain supplier qualification. Maharashtra's chemical manufacturing belt around Mumbai and Pune generates scale economies for both liquid and powder-grade production.
China
NMPA cosmetic ingredient registration and GB standards for surfactant purity filter foreign exporters from pharmaceutical-grade procurement. Yangtze River Delta personal care manufacturers integrate sarcosinate into sulfate-free shampoos targeting domestic premium segments. Shanghai formulation laboratories validate biodegradable surfactant alternatives for brands seeking EU export compliance.
Switzerland
Swissmedic-regulated ophthalmic and dermal drug delivery applications command the steepest purity premiums globally. Basel's pharmaceutical manufacturing cluster qualifies sarcosinate surfactants for sterile topical formulations requiring endotoxin-controlled specifications. Swiss buyers consolidate supplier relationships around pre-validated pharmaceutical documentation dossiers.
Sodium Lauroyl Sarcosinate Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in sodium lauroyl sarcosinate supply. BASF SE and Evonik Industries leverage captive fatty acid feedstock production to control input costs across cosmetic and pharmaceutical grades. Galaxy Surfactants and Stepan Company occupy the specialist tier with concentrated manufacturing in India and North America respectively. Competitive moves center on biotechnology-derived route development and supplier-managed inventory programs at major personal care manufacturing sites.
Among European-integrated chemical majors, BASF SE exemplifies backward integration into lauroyl chloride feedstocks, while Croda International occupies a position within biotechnology-enabled production routes appealing to clean-label cosmetic brands. Galaxy Surfactants represents the export-oriented specialist archetype, anchoring capacity concentration in India for supply to formulators in Germany, France, and Southeast Asia. These three company types illustrate the competitive structure: feedstock-integrated leaders, biotechnology-differentiated players, and scale-focused regional specialists.
| Leading Market Players |
|---|
| BASF SE |
| Croda International |
| Evonik Industries |
| Clariant |
| Innospec |
| Galaxy Surfactants |
| Stepan Company |
| Ashland |
| Dow |
| Others |
Value Chain & Pricing Dynamics
Forty-five-day inventory cycles at Rhine-Ruhr cosmetic manufacturing sites concentrate negotiating leverage among backward-integrated German chemical majors, amplifying their pricing power over specialty-grade sarcosinate procurement. This lead-time compression binds supply chain configuration directly to margin capture across cosmetic and pharmaceutical grade tiers.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical-grade procurement, while spot purchasing persists for industrial-grade volumes where specification tolerance permits supplier switching. Three-tier pricing structure across premium, standard, and economy levels separates USP-NF certified pharmaceutical grades from REACH-compliant cosmetic specifications and technical industrial grades. Price differentiation centers on endotoxin certification and biodegradation dossier completeness. Cost compression in industrial-grade supply is intensifying because petroleum sulfonate substitutes undercut sarcosinate on foaming performance metrics. Mass-market personal care manufacturers exhibit highest price sensitivity; Swiss ophthalmic drug developers demonstrate lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Indian-manufactured sarcosinate entering German formulation hubs. Supply concentrates in Germany, India, and the Netherlands, with lauroyl chloride feedstock anchored in German and Dutch petrochemical complexes. Raw material dependencies rest on pharmaceutical-grade sarcosine from specialized chemical manufacturers and fatty acid derivatives from integrated oleochemical operations. Single-source vulnerability in sarcosine supply creates bottleneck exposure for high-purity grade expansion. Distribution runs through supplier-managed inventory programs at major personal care manufacturing sites, displacing traditional specialty chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biotechnology-derived production routes and REACH biodegradability mandates are reshaping competitive positioning in sodium lauroyl sarcosinate supply, creating asymmetric opportunity windows across incumbent defense and new entrant attack vectors.
For Market Incumbents: Fortify backward integration into lauroyl chloride feedstocks to neutralize input cost volatility when fatty acid markets tighten. Expand pharmaceutical-grade capacity in Switzerland and Germany ahead of ophthalmic drug delivery qualification waves. Lock in long-term offtake agreements with Rhine-Ruhr cosmetic manufacturers to preempt glucoside substitution in sulfate-free formulations. For New Entrants and Emerging Players: Lead with enzymatic sarcosine synthesis certification to capture clean-label brand procurement that commands biotechnology-derived premiums. Target India's domestic urban middle-class personal care market where sulfate-free positioning supports price premiums and local manufacturing avoids import logistics burdens. Deploy direct-to-brand ingredient sourcing models that compress distributor margins and accelerate customer acquisition. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated chemical majors divesting non-core surfactant operations under portfolio rationalization pressures. Mid-scale fermentation houses with validated enzymatic routes present acquisition appeal for biotechnology capability gaps. The sector exhibits durable 5-10 year demand visibility anchored in regulatory displacement of petrochemical surfactants. Monitor ECHA Annex XIII biodegradability protocol amendments as inflection signals for accelerated conventional surfactant disqualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lauroyl Chloride | Captive fatty acid supply from German petrochemical complexes neutralizes input cost volatility for cosmetic grades. |
| Enzymatic Sarcosine Synthesis Scale-Up | Fermentation-derived routes reduce carbon intensity metrics valued by REACH-compliant clean-label cosmetic brands. |
| Pharmaceutical Grade Capacity Addition | USP-NF compliant production in Switzerland captures ophthalmic drug delivery margins above cosmetic tier pricing. |
| Supplier-Managed Inventory Programs | Consignment stock arrangements at Rhine-Ruhr sites displace distributor layers and lock in just-in-time contracts. |
| Biodegradation Dossier Pre-Validation | OECD 301B documentation ahead of ECHA Annex XIII updates accelerates supplier qualification for EU formulators. |
Study Parameters
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings in this study. Plant managers at Indian and German surfactant manufacturing facilities, procurement leads at Western European personal care OEMs, distribution channel partners handling specialty chemical logistics, and technical R&D directors developing enzymatic synthesis routes provided operational perspective. Secondary validation drew from ECHA REACH registration databases, customs and trade flow records, SEC 10-K filings from listed chemical majors, and Cefic surfactant market reports. Bottom-up capacity and demand modeling triangulated against top-down market sizing from production value chain analysis.
Sensitivity analysis across feedstock price scenarios and regulatory implementation timelines stress-tested projection robustness. The analytical framework segments by grade tier (cosmetic, pharmaceutical, industrial, food), end-use industry (personal care, household cleaners, industrial cleaners, food processing), formulation type (liquid, powder, cream, gel), and regional production hub configuration. CAGRs were derived from segment-level volume trajectories and value-per-kilogram evolution across purity specifications. Forecast inputs incorporated REACH Annex XIII biodegradability threshold compliance costs and FDA MoCRA toxicology documentation burdens.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of petrochemical surfactant restrictions or breakthrough biosurfactant cost parity would require recalibration. Forecasts reflect assumptions regarding ECHA implementation timelines, fatty acid feedstock availability, and pharmaceutical-grade sarcosine capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Detergent Chemicals Market
Surfactants
Global Saponin Market
Surfactants
Alkylamines Market
Surfactants
Detergent Grade Zeolite Market
Surfactants
Isopropyl Myristate Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Sodium Naphthalene Sulphonate Formaldehyde Market
Surfactants
Sodium Lauryl Sulphate Market
Surfactants
Benzyl Trimethyl Ammonium Chloride Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Emulsion Stabilizers Market
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
Linear Alkylbenzene Sulfonate (LAS) Market
Surfactants
Cetyl Chloride Market
Surfactants
Amphoteric Emulsifier Market