
 Global Low Foam Surfactants Market | 2026-2036
Global Low Foam Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Foam Surfactants Market Intelligence
Technical formulation support for specific end-use applications is expanding the value proposition beyond bulk chemical sales. Global chemical giant BASF SE leverages its vast production scale and integrated Verbund system to offer a wide product portfolio. Evonik Industries AG specializes in high-performance additives for industrial and institutional cleaning. Stepan Company sustains its market position through its dedicated focus on core anionic and nonionic surfactant technologies.
Low foam surfactants are surface-active agents engineered to reduce surface tension with minimal foam generation, often achieved by capping alcohol ethoxylates with propylene oxide groups. Their primary function is to provide wetting, detergency, and emulsification in high-agitation environments like automatic dishwashing and industrial spray cleaning. Nonionic surfactants command the largest share of the market due to their formulation flexibility and effectiveness across a wide pH range. Within applications, demand from agrochemical formulations is accelerating due to the need for efficient pesticide delivery systems.
Regulatory frameworks significantly influence product composition and market access. The European Union's Detergent Regulation and similar mandates from the US EPA enforce strict biodegradability standards, pushing formulators away from persistent chemistries. In parallel, China's GB standards for cleaning agents dictate performance and safety criteria for domestic products. Future competitiveness depends on developing surfactants from bio-based feedstocks that meet both performance benchmarks and evolving sustainability goals.
Market Dynamics
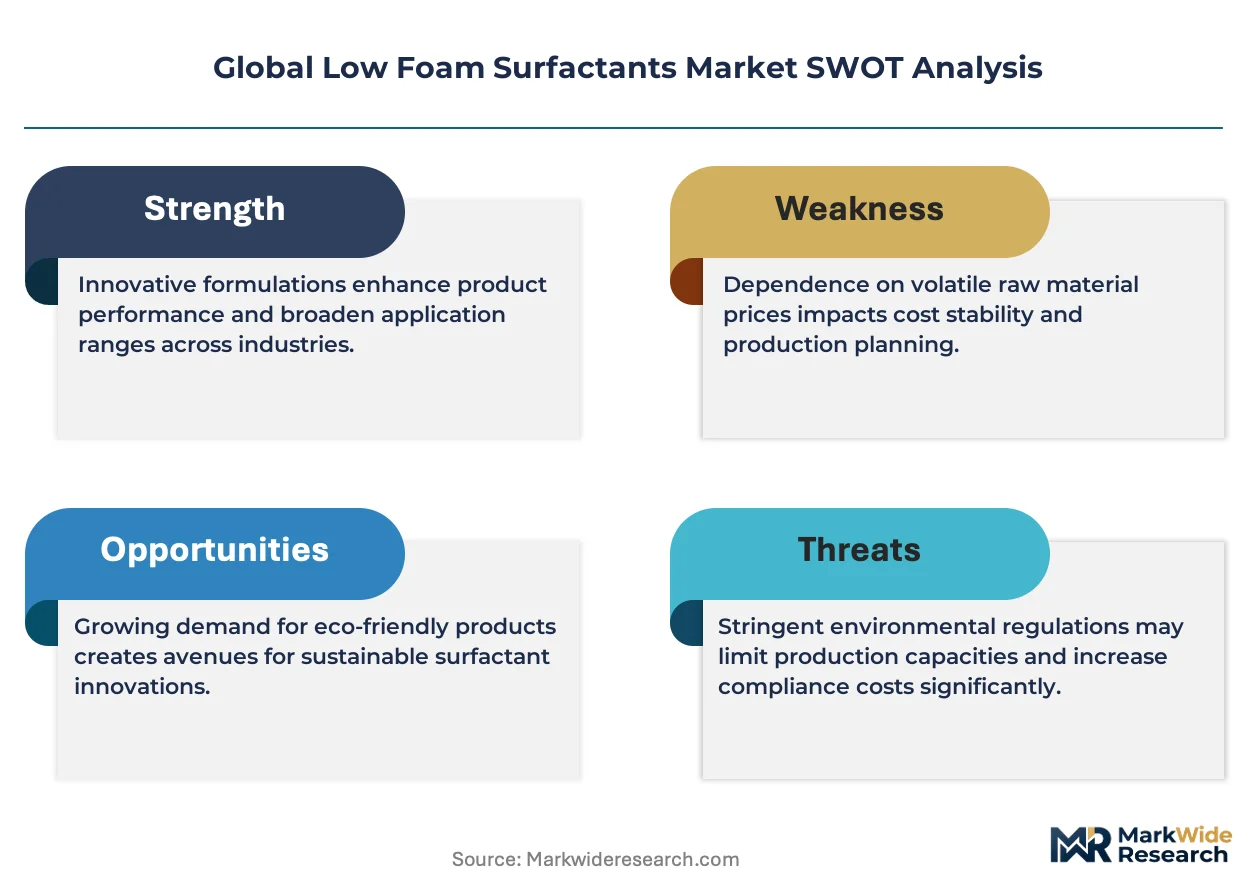
The market's central dynamic is the tension between stringent environmental regulations demanding biodegradable formulations and the industrial sector's need for high-performance surfactants in aggressive operating environments. This forces innovation toward chemistries that satisfy both sustainability mandates and technical efficacy benchmarks.
Growth Catalysts
- Regulatory Mandates:The European Union's Detergent Regulation and similar biodegradability standards from the US EPA compel the adoption of compliant low foam surfactants, particularly in consumer and institutional cleaning products.
- Agrochemical Efficiency:Demand from the agrochemical sector is rising for advanced surfactant systems that improve the wetting and spreading of pesticides, enhancing crop protection efficacy and reducing environmental runoff.
- Industrial Upgrading in China:China's expanding advanced manufacturing base requires sophisticated low foam surfactants for critical processes like metal cleaning, textile processing, and electronics fabrication, driving regional consumption.
Market Restraints
- Feedstock Price Volatility:The cost of key raw materials, such as propylene oxide and specialty alcohols, is subject to fluctuations in petrochemical markets, creating margin pressure for manufacturers.
- Performance Trade-offs:Formulators face inherent technical challenges in balancing low-foam characteristics with other desired properties like detergency, emulsification, and stability across wide temperature and pH ranges.
- Substitution from Alternative Technologies:In certain applications, non-surfactant technologies like enzymatic cleaners or advanced polymer systems present a potential substitution threat, limiting market penetration in specific niches.
Strategic Opportunities
- Bio-Based Feedstocks:Developing and scaling surfactants derived from renewable resources like plant oils and sugars offers a significant opportunity to meet corporate sustainability goals and appeal to environmentally conscious customers.
- High-Purity Electronics Cleaning:Untapped potential exists in formulations for cleaning sensitive electronic components and semiconductors, where ultra-low foam and minimal residue are critical performance requirements.
- Industrialization in Southeast Asia:Markets in countries like Vietnam and Indonesia represent new growth frontiers as their manufacturing and processing industries expand, creating fresh demand for industrial cleaning agents.
Industry Challenges
- Complex Regulatory Compliance:Navigating and ensuring compliance with a fragmented landscape of international chemical regulations, such as the EU's REACH and China's GB standards, requires significant investment and expertise.
- Specialized Formulation Support:The shift toward application-specific solutions demands a highly skilled technical salesforce capable of providing in-depth formulation support, increasing operational costs and creating a talent bottleneck.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Foam Surfactants Market |
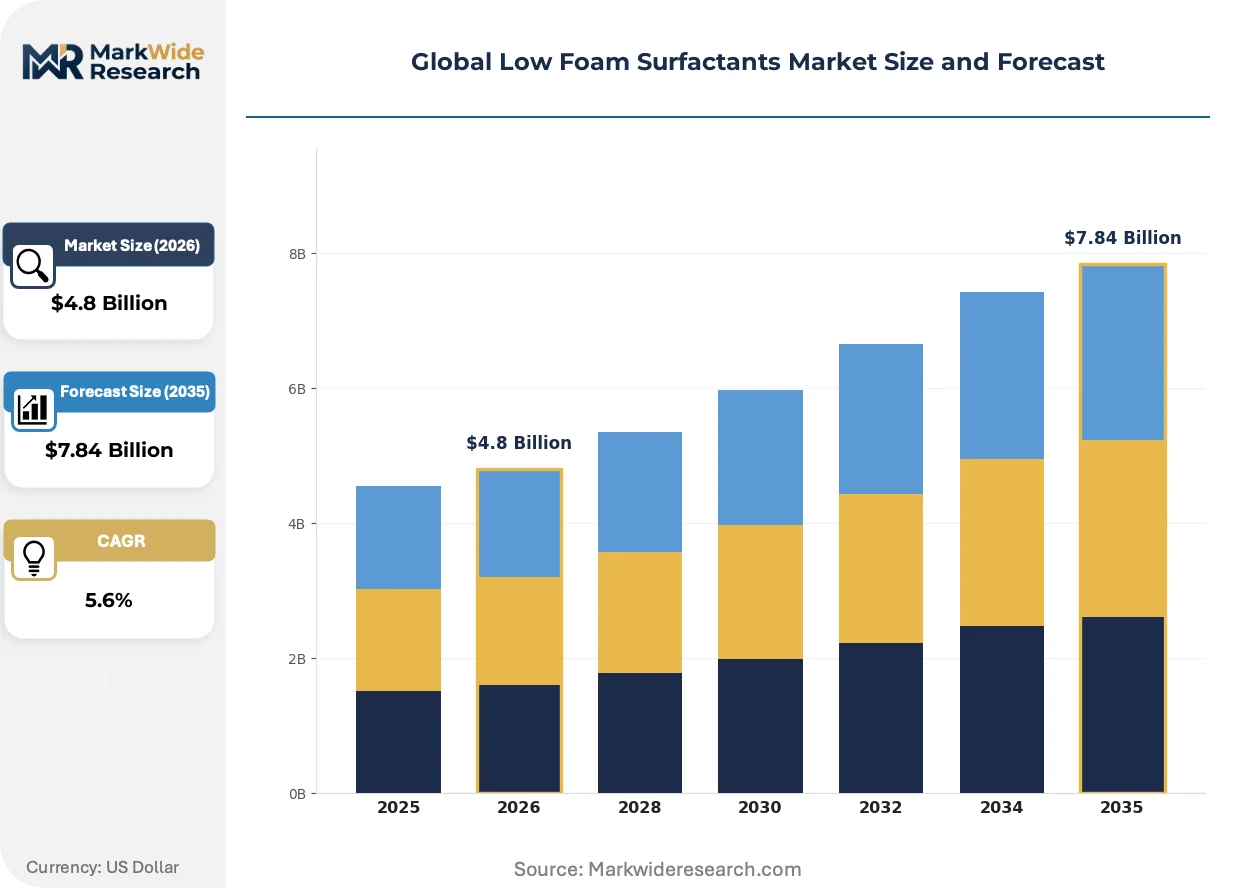
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anionic Surfactants, Nonionic Surfactants, Cationic Surfactants, Amphoteric Surfactants Application: Textile Processing, Agrochemical Formulations, Personal Care, Metal Cleaning End User Industry: Household Products, Agriculture, Personal Hygiene, Industrial Cleaning Formulation: Liquid, Powder, Paste, Emulsion |
| Companies Covered | Stepan Company, Croda International Plc, BASF SE, Huntsman Corporation, Nouryon, Dow Inc., Evonik Industries AG, Lubrizol Corporation, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Foam Surfactants Market Strategic Shifts & Innovations
The evolution of low foam surfactants is defined by a push towards multifunctional molecules that deliver superior performance under extreme conditions while adhering to a tightening global sustainability framework. This convergence is reshaping product development priorities and competitive strategies across the value chain.
Advanced capping chemistries, which modify alcohol ethoxylates with controlled blocks of propylene oxide or butylene oxide, provide precise control over foaming, solubility, and wetting properties. Formulators in the automatic dishwashing and industrial clean-in-place sectors are rapidly adopting these specialized molecules. This innovation is consolidating the market around producers with sophisticated alkoxylation capabilities, creating higher barriers to entry.
The US EPA's Safer Choice program establishes a clear benchmark for ingredients with favorable environmental and human health profiles. This standard directly influences raw material selection, pushing manufacturers to verify and document the toxicological and biodegradability data for their surfactants. The institutional cleaning sector is most impacted, with suppliers actively reformulating product lines to achieve the Safer Choice label for a market advantage.
A distinct behavioral shift is occurring as end-users increasingly specify surfactants based on functional performance outcomes rather than just chemical composition or price. This model bypasses traditional commodity channels and favors suppliers who can provide detailed application data on metrics like dynamic surface tension and foam collapse rates. This demand for proven efficacy is most pronounced within the high-stakes agrochemical and metalworking fluid industries.
Global Low Foam Surfactants Market Segmentation
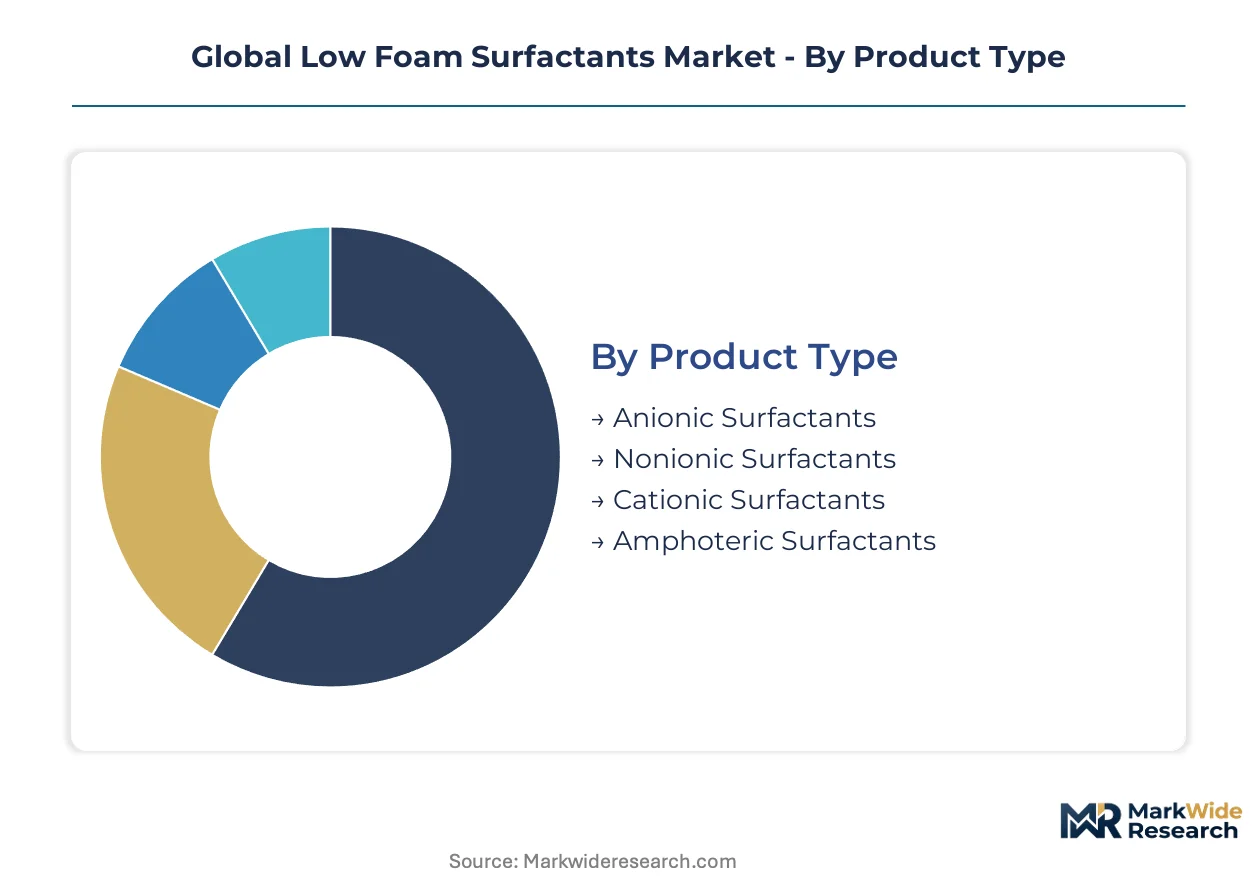
The Global Low Foam Surfactants Market is structured by distinct product chemistries, diverse application areas, specific end-user industries, and varied physical formulations. Understanding these segments reveals the critical performance attributes and regulatory drivers influencing purchasing decisions across the value chain.
Product Type:
Buyers differentiate low foam surfactants based on their specific charge, pH stability, and overall performance characteristics in demanding environments.
- Nonionic Surfactants:These surfactants, characterized by their uncharged hydrophilic head groups, offer broad compatibility and stability across varying pH levels. Demand concentrates in industrial cleaning and automatic dishwashing, driven by their effectiveness in hard water conditions and minimal foaming.
- Anionic Surfactants:Anionic surfactants, bearing a negatively charged head group, provide excellent detergency and emulsification properties at a lower cost point. Consumption is high in general-purpose cleaning and textile processing, where their strong grease-cutting action is critical.
- Cationic Surfactants:Cationic surfactants possess a positively charged head group, offering conditioning and antimicrobial properties, primarily used in specialty applications like fabric softeners.
- Amphoteric Surfactants:Amphoteric surfactants exhibit both positive and negative charges depending on pH, providing mildness and foam control, often utilized in personal care products.
Volume sits with Nonionic Surfactants; growth tilts toward Amphoteric Surfactants.
Application:
Different applications require distinct functional profiles from low foam surfactants, influencing selection based on specific process needs and performance outcomes.
- Agrochemical Formulations:Agrochemical formulations utilize low foam surfactants as adjuvants to improve the spreading and wetting of pesticides on plant surfaces. Demand is accelerating due to the need for efficient delivery systems that minimize runoff and enhance crop protection efficacy in China and Brazil.
- Metal Cleaning:Metal cleaning applications require low foam surfactants to remove oils, greases, and particulates from metal surfaces without excessive foam generation in spray wash systems. The expansion of advanced manufacturing in Germany and Japan drives consumption for precision cleaning processes.
- Textile Processing:Low foam surfactants in textile processing facilitate wetting, scouring, and dyeing operations, preventing foam build-up in high-agitation machinery.
- Personal Care:Personal care products employ low foam surfactants for gentle cleansing and emulsification, balancing mildness with effective performance in shampoos and body washes.
The industrial sector drives significant consumption, while specialized needs in agriculture are expanding most quickly.
End User Industry:
Regulatory frameworks heavily influence surfactant selection across end-user industries, dictating biodegradability, toxicity, and performance standards.
- Industrial Cleaning:Industrial cleaning relies on low foam surfactants for high-efficiency processes like clean-in-place systems and spray washing in manufacturing facilities. The stringent performance requirements for degreasing and sanitization in European food processing plants drive this segment.
- Agriculture:Agriculture utilizes low foam surfactants to enhance the performance of crop protection chemicals, ensuring better coverage and absorption by target plants. The increasing focus on sustainable farming practices in India and the US boosts demand for effective adjuvant systems.
- Household Products:Household products incorporate low foam surfactants for automatic dishwashing detergents and hard surface cleaners, where minimal sudsing is essential for performance.
- Personal Hygiene:Personal hygiene applications, such as hand soaps and body washes, use low foam surfactants that offer mildness and effective cleansing without excessive lather.
Industrial applications consume the largest volumes, and agricultural uses demonstrate substantial growth potential.
Formulation:
The physical form of low foam surfactants dictates handling, storage, and application methods for end-users, affecting logistics and integration into manufacturing processes.
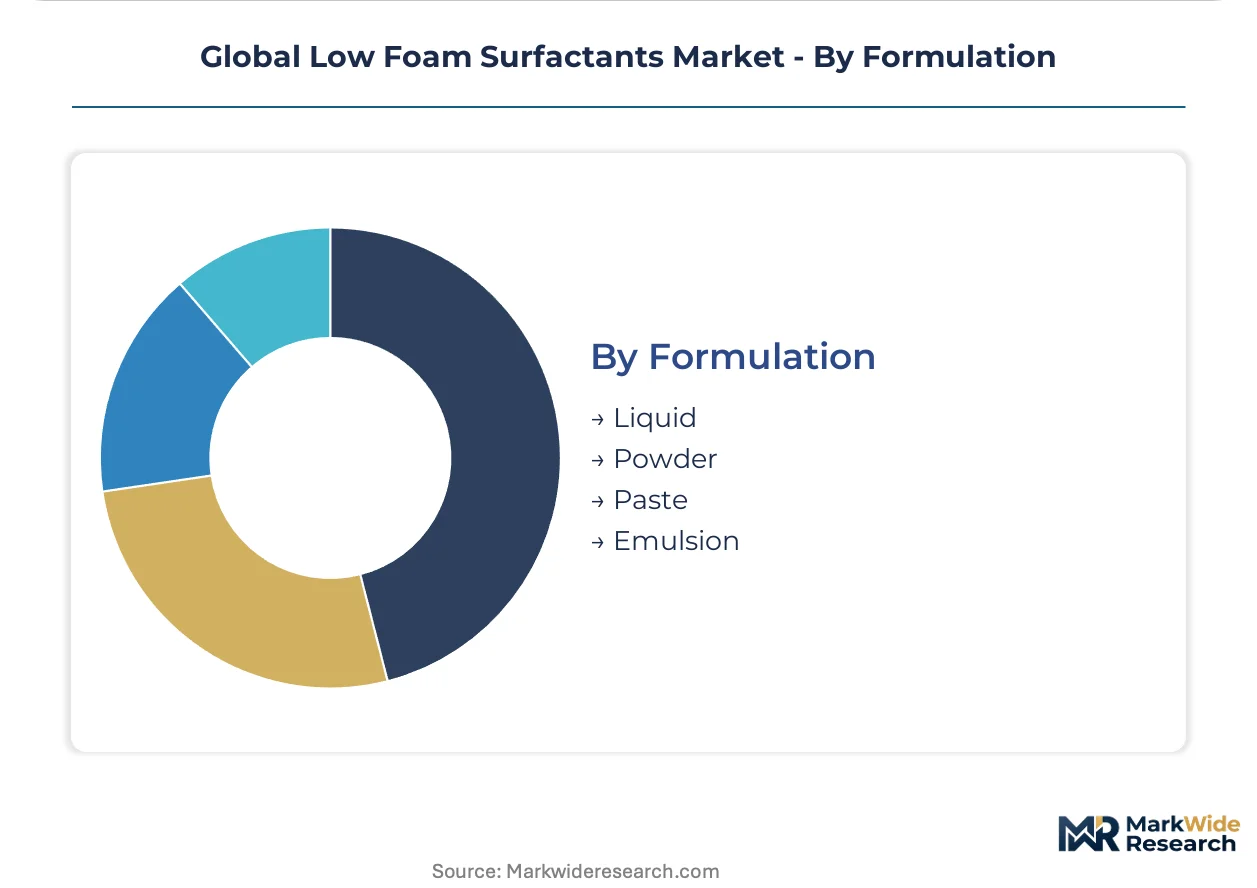
- Liquid:Liquid formulations of low foam surfactants offer ease of handling, precise dosing, and rapid dispersion in aqueous systems. They are widely preferred in industrial cleaning concentrates and household products due to their convenience and stability.
- Powder:Powder formulations provide concentrated surfactant delivery, extended shelf life, and reduced shipping costs, particularly for heavy-duty cleaning and agrochemical applications. Their stability in dry blends makes them suitable for remote agricultural use cases.
- Paste:Paste formulations offer a high concentration of active ingredients, often used in specialized industrial applications requiring viscous or semi-solid delivery.
- Emulsion:Emulsion formulations ensure homogeneous dispersion of water-insoluble surfactants, providing stability and targeted release in complex systems like metalworking fluids.
Liquid formulations dominate the market due to ease of use, while specialized applications increasingly favor emulsions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The production-consumption dynamic for low foam surfactants often shows manufacturing concentration in established chemical hubs, while demand growth increasingly shifts to regions with expanding industrial bases. Local regulatory frameworks and application-specific needs shape market evolution across diverse geographies.
China
China's expanding advanced manufacturing sector drives significant demand for low foam surfactants in metal cleaning and textile processing. The country's GB standards for cleaning agents dictate performance and safety criteria, influencing product formulations. Industrial clusters in the Yangtze River Delta actively consume these specialized chemicals for electronics fabrication and precision cleaning.
Germany
Germany's robust industrial cleaning sector, particularly in food processing and automotive manufacturing, requires high-performance low foam surfactants. European Union regulations, including the Detergent Regulation, enforce strict biodegradability standards for products sold here. Chemical production hubs like Ludwigshafen and Leverkusen continue to innovate in sustainable surfactant chemistries.
United States
The United States market sees strong demand from agrochemical formulations and industrial cleaning applications. The US EPA's Safer Choice program influences raw material selection, promoting environmentally preferable options. Manufacturing centers in Texas and Louisiana produce key petrochemical feedstocks, supporting domestic surfactant production.
India
India's agricultural sector represents substantial growth potential for low foam surfactants, enhancing pesticide delivery systems. The increasing focus on sustainable farming practices boosts demand for effective adjuvant systems across the country. Industrial zones around Mumbai and Gujarat are developing new manufacturing capabilities, increasing local consumption of cleaning agents.
Japan
Japan's precision manufacturing industries, including electronics and automotive, rely on low foam surfactants for critical metal cleaning processes. Japanese Industrial Standards (JIS) influence quality and performance benchmarks for industrial chemicals. Advanced chemical research and production facilities in Tokyo and Osaka contribute to specialized surfactant development.
Global Low Foam Surfactants Market Key Industry Players
Top-tier vendors anchor the global low foam surfactants market, while a fragmented landscape of regional and specialized players addresses niche applications. Large chemical conglomerates and specialized surfactant manufacturers form distinct strategic archetypes. Dominant competitive moves include portfolio diversification to meet varied application needs and strategic partnerships to navigate complex regulatory landscapes.
Within the large-scale chemical production tier, BASF SE leverages its integrated Verbund system to offer a broad product portfolio. Evonik Industries AG exemplifies a specialist in high-performance additives for industrial and institutional cleaning. Stepan Company sustains its market position by focusing on core anionic and nonionic surfactant technologies, catering to a wide range of industrial and consumer applications.
| Leading Market Players |
|---|
| Stepan Company |
| Croda International Plc |
| BASF SE |
| Huntsman Corporation |
| Nouryon |
| Dow Inc. |
| Evonik Industries AG |
| Lubrizol Corporation |
| Clariant AG |
| Others |
Cost & Logistics Intelligence
The performance-critical divergence between commodity low foam surfactants and specialized, application-specific formulations manifests in distinct pricing models and supply chain configurations.
Pricing Analysis
Cost-down pressure on commodity nonionic surfactants accelerates because of petrochemical feedstock price volatility. The dominant pricing model for bulk products remains contract-based long-term offtake, while specialty formulations command value-based pricing. Price differentiation often traces to performance efficacy, such as foam collapse rates, and regulatory compliance like the US EPA's Safer Choice label. Industrial cleaning and agrochemical sectors demonstrate lower price sensitivity for specialized, high-performance formulations compared to general-purpose cleaning applications.
Supply Chain Analysis
Regional distribution centers facilitate the delivery of low foam surfactants to industrial and agricultural end-users. Geographic supply concentration for key feedstocks like propylene oxide and specialty alcohols centers in China, Germany, and the United States. Commodity price volatility for these petrochemical raw materials represents a significant supply chain risk. The distribution model for specialized low foam surfactants often involves direct sales supported by technical service teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low foam surfactants market is consolidating, driven by the complex regulatory compliance landscape forcing smaller, less specialized players to exit.
For Market Incumbents:Anticipate continued pressure from stringent environmental regulations like the EU's REACH and the US EPA's Safer Choice program. Invest heavily in research and development for advanced capping chemistries and bio-based feedstocks to meet evolving sustainability goals. Expand technical formulation support for specific end-use applications, enhancing the value proposition beyond bulk chemical sales. Address the threat of substitution from alternative technologies by demonstrating superior performance and cost-effectiveness.
For New Entrants and Emerging Players:Enter via niche applications requiring ultra-low foam and minimal residue, such as high-purity electronics cleaning. Target the industrialization in Southeast Asia, where manufacturing and processing industries are expanding rapidly. Differentiate offerings through innovative bio-based formulations that meet both performance benchmarks and sustainability criteria. Partner with local distributors to provide specialized technical service and gain regional market access.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized surfactant manufacturers given the increasing demand for bio-based and high-performance formulations. Long-term viability is strong due to sustained demand from performance-critical industrial applications and agrochemicals. Target vertically integrated specialists with proprietary bio-based surfactant technologies or advanced alkoxylation capabilities. Watch for increased adoption rates of bio-based low foam surfactants in industrial sectors as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and aligns with global sustainability mandates like the EU Green Deal. |
| Capacity Expansion for Advanced Chemistries | Addresses the growing demand for specialized low foam surfactants in high-efficiency industrial cleaning. |
| Long-term Supply Agreements for Bio-Based Feedstocks | Secures access to renewable resources, mitigating petrochemical price volatility for manufacturers. |
| Joint Venture for Regional Market Access | Facilitates penetration into expanding industrial markets in Southeast Asia and other developing regions. |
| Product Launch of New Bio-Based Formulation | Captures market share in segments prioritizing environmental profiles and stringent biodegradability standards. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and academic literature underwrites the qualitative findings of this study. Primary interviews with chemical R&D directors, industrial cleaning procurement managers, agrochemical formulators, and environmental compliance officers provided critical insights. Secondary data from EU Detergent Regulation documents, US EPA Safer Choice program guidelines, and China's GB standards validated market dynamics through bottom-up and top-down triangulation.
Historical performance data from comparable periods anchors the quantitative projections across the analysis window. The analytical framework modeled market segmentation by product type, application, end-user industry, and formulation. Compound annual growth rates were derived from historical growth trends and projected market dynamics, incorporating raw material price forecasts and regulatory compliance costs as key inputs over the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme feedstock price volatility or sudden regulatory shifts. Forecasts reflect assumptions regarding technological advancements and evolving environmental mandates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Cetyl Chloride Market
Surfactants
Cetyl Trimethyl Ammonium Chloride Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Sodium Lauryl Sulphate Market
Surfactants
Sodium Cocoyl Isethionate Market
Surfactants
Global Silicone Surfactants Market
Surfactants
Fatty Methyl Ester Sulfonate Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Soy-Based Surfactants Market
Surfactants
Sulfate Free Body Wash Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Oil-in-Water Anionic Emulsifier Market
Surfactants
Polysorbate 40 Market
Surfactants
Wetting Agents Market
Surfactants
Pharmaceutical Surfactants Market
Surfactants
Glycol Monostearate Market