
 Global Methyl Soyate Market | 2026-2036
Global Methyl Soyate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Methyl Soyate Market Intelligence
Enzymatic transesterification at lower temperatures is rewriting process economics for methyl soyate producers, cutting energy inputs and improving yield consistency. Cargill, Incorporated leverages its captive soybean crushing network to secure feedstock cost advantages across North American operations. Stepan Company anchors its position through specialized surfactant-grade methyl soyate formulations. Vertec BioSolvents differentiates via technical-grade purity specifications tailored to precision cleaning markets.
Methyl soyate is a fatty acid methyl ester derived from soybean oil transesterification, typically exhibiting a flash point above 170°C and kinematic viscosity near 4.2 mm²/s at 40°C, functioning primarily as a biodegradable solvent and lubricant base stock. Pure methyl soyate dominates volume shipments for biofuel blending and straight solvent replacement, while blended methyl soyate captures margin pools in paints and coatings where formulators require tailored evaporation profiles. The agricultural grade segment sustains growth through adjuvant demand from agrochemical firms expanding bio-based tank-mix portfolios.
The EPA regulates methyl soyate under the Toxic Substances Control Act and the Renewable Fuel Standard, while REACH in Europe mandates registration and hazard communication for bio-based chemical imports, collectively elevating compliance costs for non-certified suppliers. China's GB standards for industrial solvents and the EU Green Deal's decarbonization targets for chemical manufacturing are tightening specifications on feedstock provenance and lifecycle emissions. Stakeholders must monitor regulatory divergence between jurisdictions to optimize certification investments and avoid market access friction.
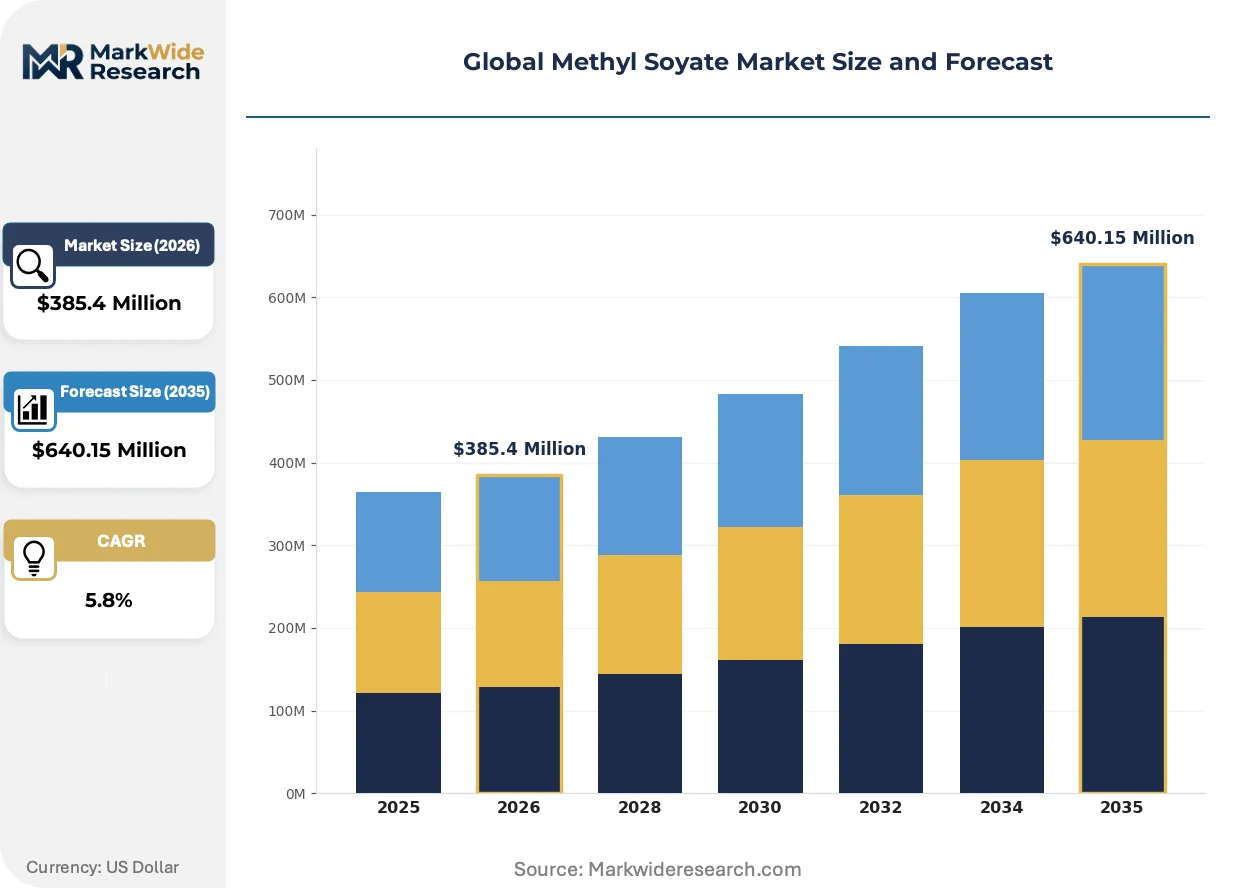
Market Dynamics
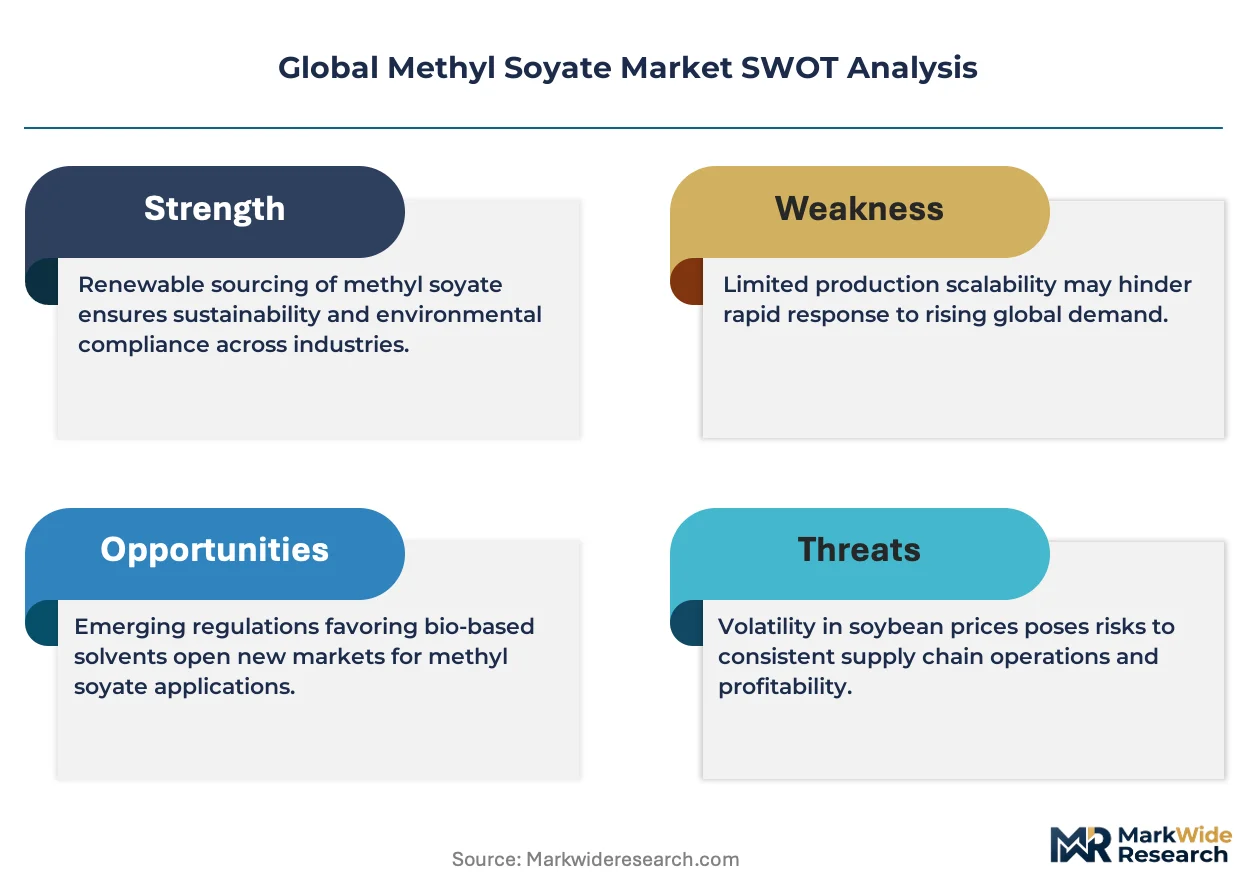
Enzymatic transesterification at lower temperatures is compressing energy costs and tightening yield consistency for methyl soyate producers, while REACH and EPA regulations on petroleum-based solvents accelerate feedstock substitution toward bio-based alternatives.
Growth Catalysts
- REACH solvent restrictions:The European Union's phased limitations on volatile organic compound emissions from petroleum-derived solvents are compelling paint and coating formulators to integrate methyl soyate as a compliant replacement.
- Agrochemical adjuvant demand:Agricultural grade methyl soyate functions as a bio-based tank-mix carrier, with agrochemical firms expanding sustainable portfolio offerings across North American and European crop protection markets.
- Precision cleaning specifications:Technical-grade purity requirements in electronics and aerospace maintenance operations are pulling ultra-pure methyl soyate volumes into specialized solvent applications.
Market Restraints
- Soybean oil price volatility:Feedstock costs fluctuate with commodity crop cycles and weather patterns in Argentina and Brazil, compressing margin predictability for non-integrated producers lacking captive crushing capacity.
- Cetane number limitations:Methyl soyate's lower cetane rating relative to petroleum diesel restricts blending ratios in certain cold-climate biofuel specifications, capping addressable volume in transportation fuel markets.
- Compatibility constraints:Seal and gasket material incompatibility with ester-based solvents in legacy industrial equipment creates retrofit friction and slows replacement adoption in mature manufacturing facilities.
Strategic Opportunities
- India industrial solvent transition:BIS standards evolution and domestic biofuel blending mandates are opening procurement channels for imported methyl soyate in Maharashtra and Gujarat chemical processing clusters.
- Marine lubricant formulations:Vessel operators facing IMO sulfur regulations are testing fatty acid methyl ester base stocks for biodegradable stern tube and hydraulic fluids in coastal shipping routes.
- Carbon accounting integration:EU Green Deal lifecycle emissions verification requirements are rewarding methyl soyate suppliers with certified sustainable feedstock traceability, creating premium positioning against uncertified competitors.
Industry Challenges
- Enzyme catalyst sourcing:Specialized lipase procurement for low-temperature transesterification requires long-lead contracts with biotechnology suppliers, constraining process scale-up timelines.
- Multi-jurisdiction registration:Separate EPA TSCA filings, REACH dossier submissions, and China's GB standard compliance create overlapping certification burdens for suppliers targeting cross-border market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Methyl Soyate Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Methyl Soyate, Blended Methyl Soyate, Industrial Grade, Technical Grade, Agricultural Grade Application: Biofuels, Solvents, Lubricants, Surfactants, Emulsifiers, Paints & Coatings End User: Chemical Manufacturers, Agrochemical Firms, Personal Care Producers, Paint Companies, Lubricant Companies, Bioenergy Firms Packaging Type: Drums, Bulk Containers, Intermediate Bulk Containers, Jerricans, Totes, Pails |
| Companies Covered | Camco Chemical Co. Inc., Vertec BioSolvents, BASF SE, Graham Chemical Corporation, Unicon Fibro Chemicals Pvt. Ltd., Stepan Company, Florida Chemical Company, Kerley Ink, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Methyl Soyate Market Strategic Shifts & Innovations
Process intensification and regulatory chemistry are rewriting competitive economics in methyl soyate production, with technology migration and policy alignment determining which suppliers capture margin expansion.
Continuous-flow enzymatic reactors are migrating from batch alkali-catalyzed systems that dominated legacy transesterification operations. Specialty chemical producers in Germany and the United States are retrofitting plants with immobilized lipase columns to reduce thermal energy inputs and eliminate aqueous waste streams. This technology migration from conventional methods is compressing capital recovery periods and enabling smaller-scale distributed production near soybean crushing facilities.
EPA Renewable Fuel Standard pathway approvals for novel feedstock qualifications are tightening documentation requirements for bio-based content verification. Fuel blenders must now demonstrate chain-of-custody integrity from oilseed origin through esterification, elevating compliance infrastructure costs. The biofuel certification segment is responding by consolidating supplier relationships with vertically integrated crushers who control traceability documentation.
Formulator procurement teams are consolidating solvent vendor panels from multi-source commodity purchasing toward single-source technical partnerships with methyl soyate specialists who provide application-specific evaporation profiling. Paints and coatings manufacturers in China and Germany are embedding supplier technical service capabilities into product development workflows. This concentration pattern is most visible in automotive refinish operations where color-matching consistency demands precise solvent blend reproducibility.
Global Methyl Soyate Market Segmentation
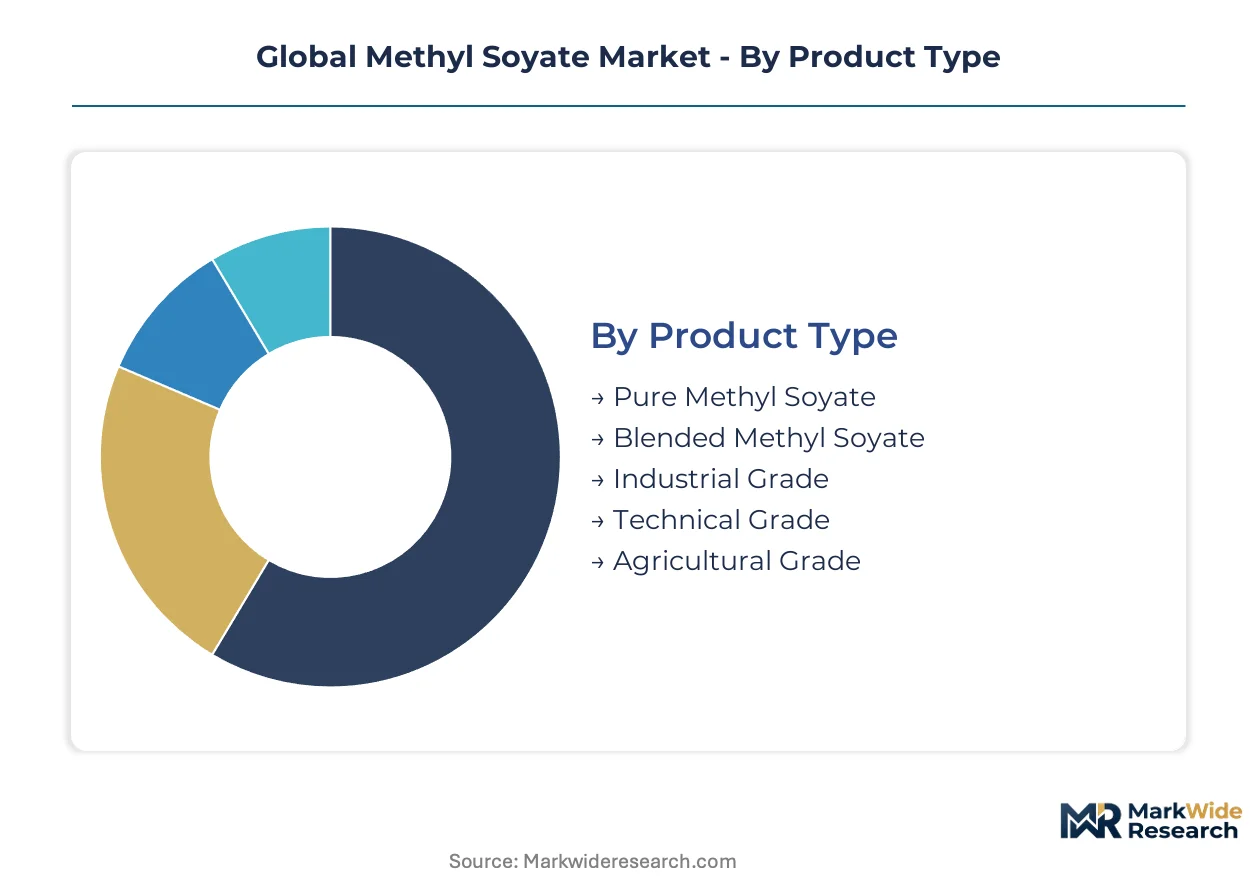
Methyl soyate's commercial trajectory diverges sharply across specification tiers and end-use channels. Understanding where volume concentrates versus where margins expand fastest enables suppliers to calibrate capacity investments and technical service deployment.
Product Type:
Inventory velocity varies dramatically across purity grades, with fuel-grade specifications turning monthly while specialized agricultural formulations sit on quarterly replenishment cycles.
- Pure Methyl Soyate:Unblended fatty acid methyl ester meeting ASTM D6751 and EN 14214 specifications for direct biofuel blending and straight solvent replacement. Demand concentrates in United States biodiesel operations and German chemical manufacturing clusters where high-purity feedstock enables downstream formulation flexibility.
- Blended Methyl Soyate:Custom formulations combining methyl soyate with co-solvents or performance additives to achieve targeted evaporation rates and viscosity profiles. Paint companies in China and automotive refinish operations across Germany drive procurement volumes as formulators seek drop-in replacements for restricted petroleum solvents under REACH and EPA volatile organic compound regulations.
- Industrial Grade:Standard-purity ester serving general-purpose cleaning and degreasing applications where color stability and odor specifications are less stringent.
- Technical Grade:Ultra-low moisture and particulate specifications meeting aerospace and electronics precision cleaning protocols.
- Agricultural Grade:Formulated adjuvant base carrying active ingredients in crop protection tank mixes, with bio-based content credentials satisfying sustainability procurement mandates from major agrochemical distributors.
Pure methyl soyate anchors the volume base while technical grade formulations gain share at the steepest rate.
Application:
Margin structures stratify across use cases, with commodity biofuel applications compressing returns and specialized surfactant formulations sustaining premium positioning.
- Solvents:Direct replacement for mineral spirits and aromatic hydrocarbons in industrial degreasing, parts washing, and resin cleanup operations. German automotive suppliers and United States metal fabrication facilities are converting equipment fleets to accommodate ester-based systems as EPA and REACH enforcement tightens on petroleum-derived alternatives.
- Paints & Coatings:Carrier solvent and coalescing agent in waterborne and high-solids formulations where low vapor pressure reduces workplace exposure limits. Chinese architectural coatings producers and German automotive OEM paint shops specify methyl soyate for VOC compliance without sacrificing film formation properties.
- Biofuels:Biodiesel blending component and heating fuel substitute in residential and commercial boiler applications.
- Lubricants:Base stock for biodegradable hydraulic fluids and metalworking fluids in environmentally sensitive operating environments.
- Surfactants:Hydrophobic tail component in anionic and nonionic surfactant synthesis for household and industrial cleaning products.
- Emulsifiers:Food-grade and industrial emulsion stabilization where regulatory clearance permits bio-based content claims.
Solvent applications dominate current shipment volumes while paints and coatings represent the fastest-climbing application trajectory.
End User:
Procurement sophistication varies across buyer categories, with chemical manufacturers negotiating on specification flexibility and agrochemical firms prioritizing certified sustainable sourcing documentation.
- Chemical Manufacturers:Intermediate buyers integrating methyl soyate into downstream specialty chemical production, with purchasing decisions driven by feedstock cost stability and multi-regulatory compliance coverage for export markets.
- Agrochemical Firms:Formulators of crop protection products seeking tank-mix carriers with favorable toxicological profiles and bio-based content percentages for sustainability marketing.
- Paint Companies:Architectural and industrial coatings producers balancing VOC compliance against drying time and film performance requirements.
- Lubricant Companies:Blenders of biodegradable hydraulic and metalworking fluids targeting marine and forestry equipment operators.
- Personal Care Producers:Cosmetic and personal hygiene product formulators utilizing methyl soyate derivatives for emollient and solvent functions.
- Bioenergy Firms:Renewable fuel producers and distributors managing blending operations under EPA Renewable Fuel Standard and similar national biofuel mandates.
Chemical manufacturers anchor the volume base while agrochemical firms expand procurement most aggressively.
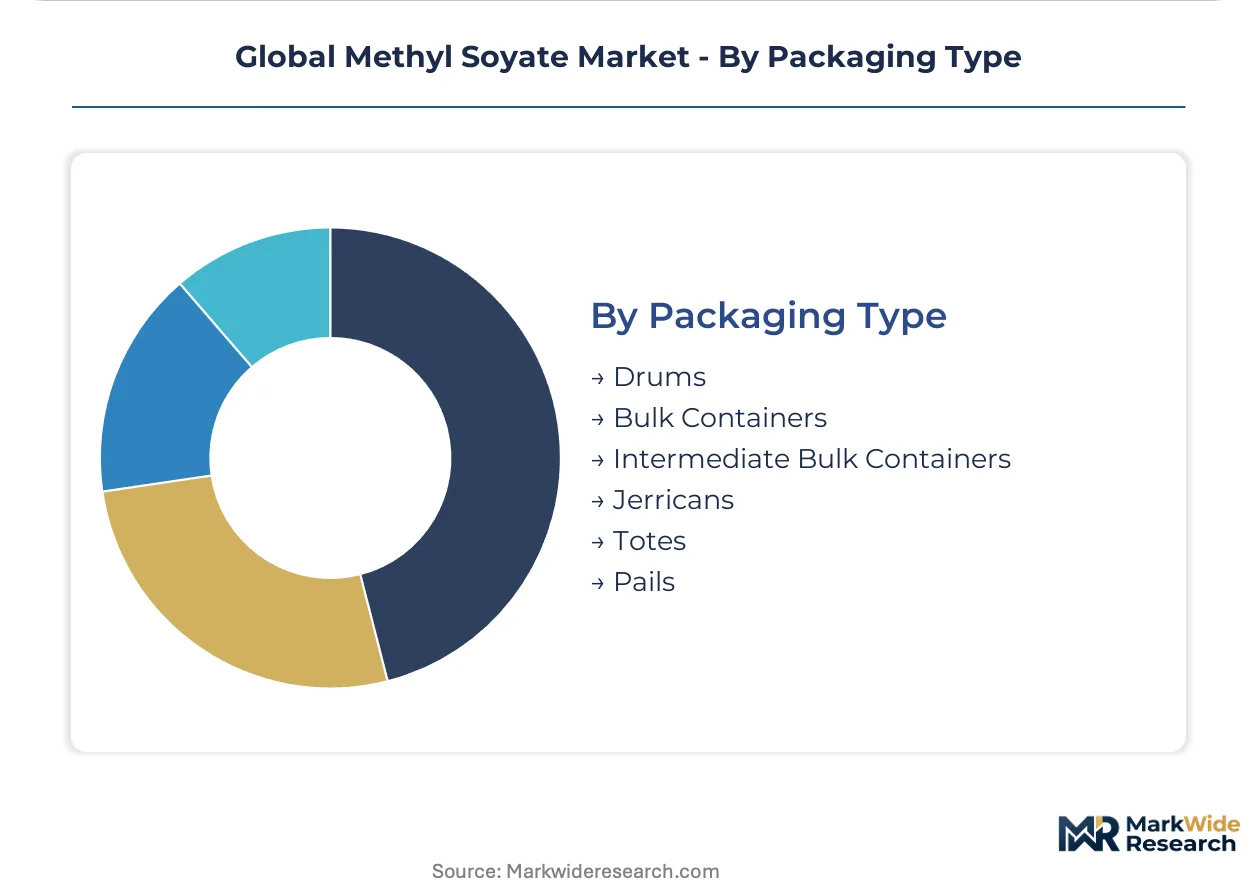
Packaging Type:
Logistics economics favor bulk formats for integrated producers while specialized distributors capture margin through smaller-unit value-added services.
- Bulk Containers:Tank truck and railcar deliveries serving high-volume chemical manufacturers and biofuel blenders with dedicated storage infrastructure.
- Intermediate Bulk Containers:Flexible and rigid IBC formats bridging bulk efficiency with moderate-volume user flexibility.
- Drums:Standard 55-gallon steel and fiber containers for general industrial solvent distribution.
- Totes:Intermediate-volume polyethylene containers with dispensing compatibility for paint and coatings operations.
- Jerricans:Small-format containers for retail and maintenance-shop solvent sales.
- Pails:Five-gallon and smaller containers for specialty lubricant and agricultural adjuvant distribution.
Bulk containers dominate tonnage movements while intermediate bulk containers capture the steepest share gains among mid-scale processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paint formulators and biofuel blenders concentrate procurement in industrial clusters where soybean crushing infrastructure overlaps with solvent formulation expertise. United States buyers dominate volume contracts for fuel-grade specifications. German and Chinese chemical manufacturers drive technical-grade demand for coatings applications.
United States
EPA Renewable Fuel Standard enforcement compels biodiesel blenders to source ASTM D6751-compliant methyl soyate for transportation fuel pools. The Renewable Fuel Standard pathway approvals tighten chain-of-custody documentation from oilseed origin through esterification. Iowa and Illinois soybean crushing corridors anchor methyl soyate production capacity near Cargill's captive feedstock network.
Germany
REACH volatile organic compound restrictions force automotive OEM paint shops to replace petroleum-derived aromatic solvents with bio-based ester alternatives. The EU Green Deal lifecycle emissions verification rewards suppliers with certified sustainable feedstock traceability. Bavarian and North Rhine-Westphalian chemical processing clusters scale enzymatic transesterification capacity for technical-grade solvent output.
China
GB standards evolution for industrial solvents and dual carbon decarbonization targets accelerate bio-based feedstock substitution in architectural coatings. The Ministry of Ecology and Environment tightens specifications on feedstock provenance and lifecycle emissions for chemical manufacturing. Yangtze River Delta paint producers in Jiangsu and Zhejiang provinces integrate methyl soyate for VOC compliance without sacrificing film formation properties.
India
BIS standards migration and domestic biofuel blending mandates open procurement channels for imported methyl soyate in chemical processing applications. The Petroleum Planning and Analysis Cell biofuel roadmap creates blending obligations that pull fatty acid methyl ester volumes into transportation fuel markets. Maharashtra and Gujarat industrial solvent clusters transition from petroleum-based carriers toward bio-based alternatives under state-level clean air initiatives.
Brazil
Agrochemical firms expanding sustainable portfolio offerings drive agricultural-grade methyl soyate demand for bio-based tank-mix carriers. ANVISA toxicological profile requirements favor ester-based adjuvants with favorable environmental fate characteristics. São Paulo state crop protection formulators integrate methyl soyate into sustainability-marketed product lines for export to North American and European markets.
Global Methyl Soyate Market Key Industry Players
Channel-controlling players compete with product-specialist players across specification tiers. Vertically integrated agribusiness operators leverage captive soybean crushing networks to secure feedstock cost advantages. Specialty chemical producers anchor positions through application-specific formulation expertise and multi-regulatory compliance coverage. Competitive moves concentrate on enzymatic process licensing partnerships and geographic expansion into underpenetrated solvent markets.
Among North American-based operators, Cargill, Incorporated and Stepan Company exemplify divergent archetypes. Cargill occupies a position anchored in upstream feedstock control through its soybean crushing infrastructure. Stepan sits within the specialty formulation tier, emphasizing surfactant-grade purity specifications and technical service capabilities. Vertec BioSolvents represents the precision-cleaning specialist archetype, with positioning calibrated to aerospace and electronics maintenance protocols requiring ultra-low moisture specifications.
| Leading Market Players |
|---|
| Camco Chemical Co. Inc. |
| Vertec BioSolvents |
| BASF SE |
| Graham Chemical Corporation |
| Unicon Fibro Chemicals Pvt. Ltd. |
| Stepan Company |
| Florida Chemical Company |
| Kerley Ink |
| Cargill, Incorporated |
| Others |
Cost & Logistics Intelligence
Undercapacity in German enzymatic transesterification facilities is tightening supplier discipline and amplifying pricing leverage for technical-grade methyl soyate producers serving REACH-compliant coatings markets. This utilization squeeze feeds directly into contract structures that index soybean oil futures, compressing margin buffers for non-integrated formulators.
Pricing Analysis
Cost-plus contracts indexed to CBOT soybean oil futures dominate procurement between integrated crushers and downstream blenders, with price differentiation hinging on certification tier and volume scale. Technical-grade specifications carrying EU Green Deal lifecycle verification command substantial premiums over fuel-grade alternatives. Pricing pressure stems from Argentine crop volatility transmitting through feedstock costs. Chemical manufacturers exhibit highest price sensitivity due to thin formulation margins, while aerospace precision-cleaning buyers prioritize specification adherence over cost.
Supply Chain Analysis
Contract-manufacturing concentration sits with Cargill's captive North American crushing network and Stepan's specialty esterification facilities, with geographic supply concentration in the United States, Germany, and China. Raw material dependencies center on soybean oil, immobilized lipase enzymes, and methanol feedstocks. Supply chain risk manifests in single-source vulnerability for specialized lipase procurement from biotechnology suppliers. Distribution runs through bulk tanker networks for integrated producers and intermediate bulk container channels for mid-scale paint formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against rapeseed-derived methyl ester alternatives gaining traction under EU crop diversification mandates. Incumbents must navigate feedstock flexibility threats while locking in certification advantages.
For Market Incumbents: Pre-empt rapeseed methyl ester substitution by securing long-term soybean supply contracts with Iowa and Illinois crushing corridors. Anchor certification advantages through EU Green Deal traceability investments that uncertified competitors cannot replicate. Defend technical-grade positioning by embedding application-specific evaporation profiling services into customer R&D workflows.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial solvent clusters represent the most penetrable entry point as BIS standards migration accelerates bio-based carrier substitution. Marine lubricant formulations for IMO-regulated coastal shipping routes offer second-tier white space with lower incumbent saturation. Pursue toll-manufacturing partnerships with underutilized Brazilian crushing capacity to bypass capital-intensive enzymatic reactor investments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous-flow enzymatic transesterification as process licensing spreads, compressing barriers for mid-scale entrants. Target acquisition candidates with captive soybean sourcing and established EPA TSCA plus REACH dossier coverage. Monitor enzyme catalyst contract renewal rates as the inflection signal for process economics stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soybean Crushing | Cargill's captive Iowa corridor secures feedstock cost advantages against spot-market-dependent competitors. |
| Continuous-Flow Enzymatic Reactor Deployment | German retrofit investments eliminate aqueous waste streams and compress energy inputs for technical-grade output. |
| EU Green Deal Certification Program | Lifecycle emissions verification creates premium positioning against uncertified suppliers in coatings markets. |
| Long-Term Supply Agreement with Agrochemical Distributors | Stepan's surfactant-grade formulations anchor recurring revenue through tank-mix adjuvant portfolios. |
| Joint Venture for India Market Entry | Maharashtra chemical cluster partnerships bypass BIS registration friction and accelerate local blending capacity. |
Research Approach
Initial hypotheses were tested against primary input from plant managers at soybean crushing facilities, procurement leads at paint and coatings OEMs, distribution channel partners in industrial solvents, and technical R&D directors in enzymatic process development, then refined against secondary validation from customs trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed agribusiness operators, and EPA Renewable Fuel Standard pathway documentation. Bottom-up capacity assessments across Iowa, Illinois, Bavaria, and Jiangsu provinces were triangulated with top-down demand modeling from end-use consumption patterns.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning purity grade tier, end-use application channel, packaging format, and regional production hub. CAGRs were derived from installed capacity expansion schedules mapped against regulatory-driven substitution elasticities. Industry-specific forecast inputs incorporated REACH enforcement timelines and EPA biofuel mandate trajectory assumptions.
Macroeconomic conditions sit as an overlay; deviation in soybean commodity cycles, energy input costs, or euro-dollar exchange rates would shift the trajectory for import-dependent European formulators. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and enzyme catalyst cost curves. Quarterly review of CBOT soybean oil futures spreads, EPA pathway approval backlogs, and EU ETS carbon price levels is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Low Foam Surfactants Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Soy-Based Surfactants Market
Surfactants
Global Oilfield Surfactants Market
Surfactants
Bitumen Emulsifier Market
Surfactants
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Anionic Surfactants Market
Surfactants
Specialty Surfactants Market
Surfactants
Global Saponin Market
Surfactants
Cocomonoethanolamide (CMEA) Market
Surfactants
Cocamidopropyl Betaine Market
Surfactants
Micellar Water Market
Surfactants
Soap Salts Market