
 Micellar Water Market | 2026-2036
Micellar Water Market Size, Share, and Industry Trends Forecast 2026-2036
Micellar Water Market Analysis
Travel-size and refillable formats are restructuring how consumers purchase micellar water, shifting volume from standard bottles toward modular and subscription-compatible configurations. L'Oréal leverages its pharmacy channel dominance across Western Europe to anchor premium positioning for sensitive-skin variants. Bioderma sustains formulation credibility through dermatological testing protocols that reinforce clinical trust. Unilever competes on price-accessible liquid formats in mass retail across emerging markets.
Micellar water is a surfactant-based cleansing solution containing micelles—spherical lipid aggregates that trap oil, dirt, and makeup without rinsing—formulated typically at pH 5.0-5.5 to match skin barrier function. Sensitive-skin formulations command the widest pharmacy shelf presence due to dermatological endorsement, while foam and gel textures represent the fastest-expanding formulation segment as consumers seek rinse-free alternatives with sensory differentiation. Pump packaging captures disproportionate margin pools through perceived hygiene and dosage control, though sachet formats gain traction in travel and trial-size channels across Asia-Pacific markets.
REACH in Europe and FDA cosmetic labeling requirements in the United States impose strict surfactant disclosure and preservative limits that elevate R&D costs for new entrants. ECHA substance evaluations and state-level clean-beauty legislation in California push brands toward biodegradable micelle systems and reduced synthetic polymer content. Stakeholders must monitor evolving biodegradability standards and refill infrastructure investments as regulatory and sustainability pressures converge on packaging and formulation decisions.
Market Dynamics
Refillable packaging infrastructure and biodegradable surfactant mandates are compressing legacy single-use formats while elevating R&D spend across formulation chemistry. The transition from petroleum-derived micelle systems to plant-based alternatives is forcing capital reallocation toward biopolymer compatibility testing and pump-dispenser standardization.
Growth Catalysts
- REACH biodegradability thresholds:ECHA substance evaluations in Europe accelerate reformulation toward sugar-based surfactants that meet aquatic toxicity protocols. This creates first-mover advantage for brands with pre-validated ingredient pipelines.
- South Korea multi-step routines:Double-cleansing protocols in Seoul and Busan sustain per-capita consumption volumes that exceed Western markets by factor of three. Local beauty retailers anchor micellar water as the essential first-step product.
- Biopolymer micelle engineering:Advances in fermentation-derived lipid aggregates enable pH-stable formulations without synthetic polymers. Laboratory-scale production is scaling toward commercial viability through university partnerships in France and Germany.
Market Restraints
- Surfactant supply concentration:Coconut-derived glucoside feedstock concentrates in Southeast Asian processing hubs, exposing margins to weather volatility and shipping lane disruptions through the Strait of Malacca.
- Preservative regulatory friction:EU Annex V restrictions on phenoxyethanol and paraben alternatives force reformulation cycles that extend product development timelines by 18-24 months.
- Waterless cleansing substitution:Solid balm and powder-to-foam formats capture trial-oriented consumers seeking plastic-free alternatives, compressing volume in standard liquid segments.
Strategic Opportunities
- India pharmacy channel expansion:Underpenetrated dermocosmetic distribution in tier-two cities creates whitespace for sensitive-skin positioning. CDSCO registration pathways for imported cosmetics are streamlining.
- Refill station infrastructure:Retail partnerships with French supermarket chains demonstrate scalable closed-loop models. Consumers exchange empty vessels for discounted replenishment, locking brand loyalty.
- Silicone-free certification tailwind:Clean-beauty retailers in California and New York are mandating silicone exclusion from shelf placement. Early compliance secures premium positioning before standardization spreads.
Industry Challenges
- Biodegradability testing capacity:OECD 301B protocol validation requires specialized laboratory partnerships that concentrate in Germany and Switzerland. Queue times for certification extend launch schedules.
- Pump mechanism standardization:Refill compatibility demands cross-brand nozzle geometry alignment that conflicts with proprietary design investments. Industry consortium formation remains stalled.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micellar Water Market |
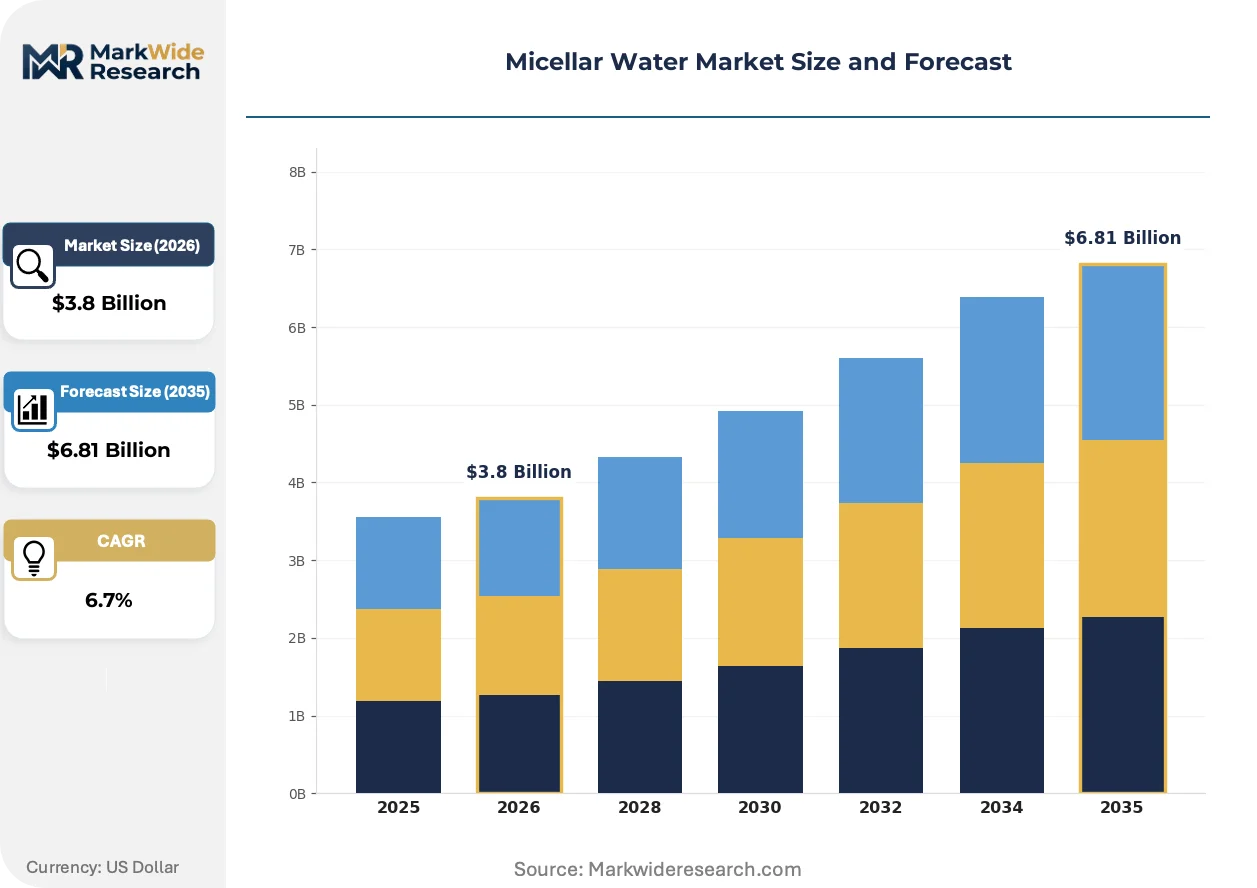
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensitive Skin, Oily Skin, Dry Skin, Combination Skin Formulation: Gel, Liquid, Foam, Wipes Packaging Type: Bottles, Tubs, Sachets, Pumps Distribution Channel: Online Retail, Hypermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Procter & Gamble, Bioderma, L'Oréal, Beiersdorf, Kao Corporation, Shiseido Company, Johnson & Johnson, Clarins, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micellar Water Market Emerging Trajectories
Formulation chemistry and packaging engineering are converging to eliminate rinse-dependent usage occasions while satisfying preservative-free claims. The competitive frontier has shifted from cleansing efficacy to sensory experience and circular material flows.
Hybrid micelle-encapsulation systems are unifying makeup removal and active ingredient delivery in single-application formats. Prestige beauty consumers in Paris and Milan are adopting these dual-function products at triple the rate of standard micellar water. This convergence is compressing the traditional serum-cleanser sequence into one step, threatening adjacent skincare category volumes.
REACH authorization requirements for non-biodegradable surfactants are forcing ingredient disclosure granularity that exceeds previous cosmetic labeling norms. Manufacturers must now document full supply chain surfactant origins back to vegetable oil harvest. Sensitive-skin and pediatric segments face the steepest compliance burden as dermatological endorsement protocols layer atop chemical safety documentation.
Subscription-based replenishment models are displacing impulse pharmacy purchases among urban millennials in London and New York. Direct-to-consumer channels capture recurring revenue through algorithmic usage tracking that anticipates depletion. South Korean beauty platforms pioneered this behavioral shift, with domestic penetration now exceeding forty percent of category volume in Seoul metropolitan retail.
Micellar Water Market Segmentation
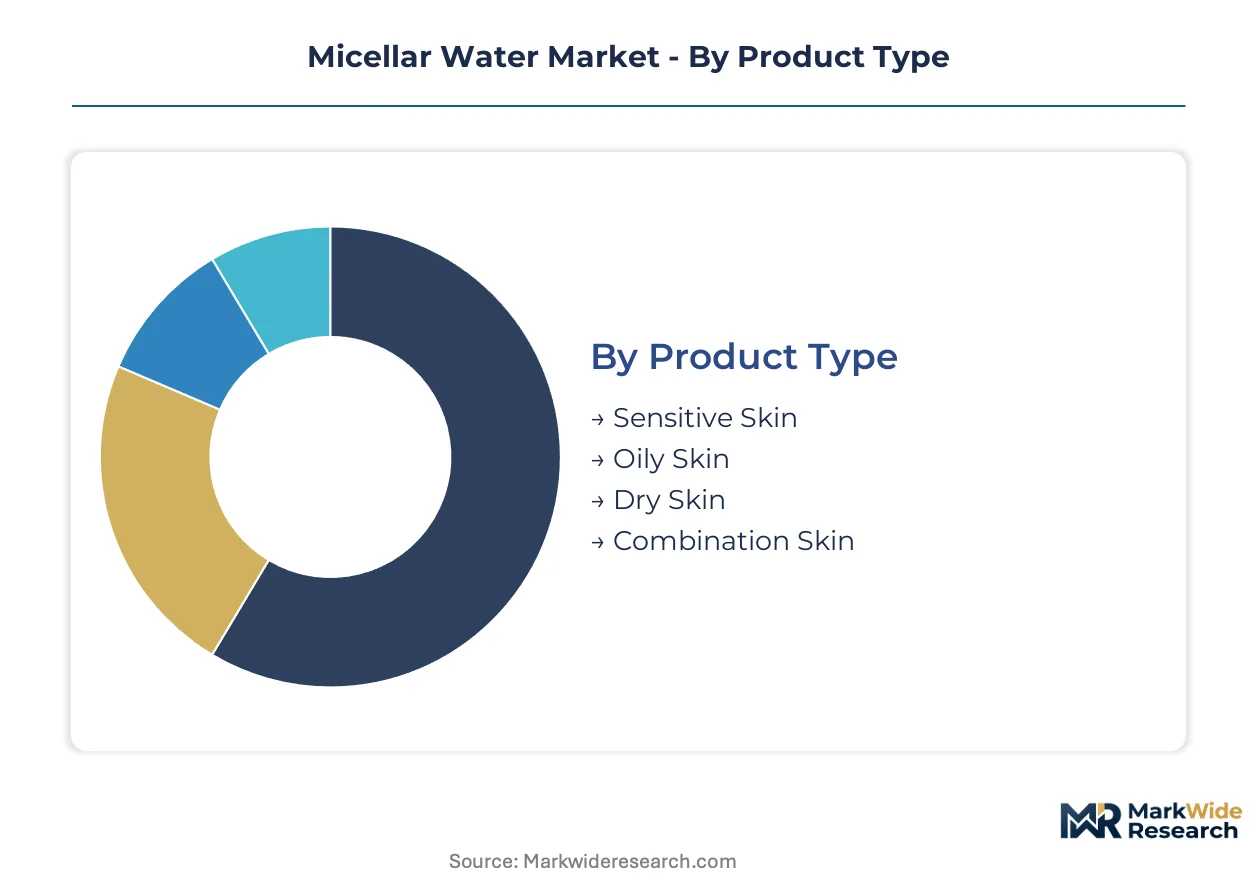
Micellar water segmentation reflects divergent buyer priorities across dermatological need states, sensory preferences, and replenishment occasions. Formulation chemistry and packaging modality choices now determine margin capture more than brand equity alone.
Product Type:
Skin sensitivity profiles drive pharmacy channel placement and pricing power more than any other purchase determinant.
- Sensitive Skin:Formulated at pH 5.0-5.5 with minimal surfactant load and zero fragrance. Dermatological endorsement protocols in France and Germany sustain pharmacy shelf dominance and premium positioning.
- Oily Skin:Higher micelle density with astringent botanical extracts targets sebum control. Demand concentrates in Seoul and Busan where double-cleansing routines prioritize oil-dissolving efficacy as the first step.
- Dry Skin:Glycerin-enriched bases with ceramide additives prevent barrier disruption. Adoption spreads through Nordic markets where hard water conditions amplify post-cleanse tightness concerns.
- Combination Skin:Zone-specific formulation balancing T-zone oil removal with cheek hydration. Traction builds in urban Indian markets where consumers reject binary dry/oily categorization.
Volume sits with Sensitive Skin; growth tilts toward Combination Skin.
Formulation:
Texture innovation is expanding usage occasions beyond traditional cotton-pad application.
- Liquid:Standard micellar suspension requiring mechanical removal with pads or reusable rounds. Established manufacturing infrastructure in Western Europe keeps unit economics lowest across all formats.
- Foam:Pre-activated aerated dispense eliminating friction during application. Expanding most quickly in Japanese convenience retail where time-compressed morning routines favor single-step speed.
- Gel:Thickened rheology enabling targeted application without runoff. Prestige positioning in Milan and Paris leverages sensorial differentiation to command 40% price premiums over liquid equivalents.
- Wipes:Impregnated nonwoven substrates for travel and gym contexts. Regulatory friction from EU Single-Use Plastics Directive compresses volume in European markets while sustaining relevance in Middle Eastern airport retail.
Liquid captures baseline volume; foam and gel together are gaining share fastest through sensory upgrade demand.
Packaging Type:
Refill compatibility and dosage precision now outweigh aesthetic differentiation in purchase decisions.
- Bottles:Conventional PET or rPET vessels across 100ml to 500ml capacities. Volume concentrates in hypermarket channels across Spain and Italy where family-size procurement remains habitual.
- Pumps:Metered-dispense mechanisms reducing product waste and contamination risk. Margin pools disproportionately favor this format through perceived hygiene premium in German pharmacy chains.
- Sachets:Single-use flexible pouches for trial and travel segments. Penetration deepens in Southeast Asian e-commerce where sampling economics outperform miniature bottle production.
- Tubs:Wide-mouth containers for wipe formats and bulk gel storage. Niche relevance persists in professional salon backbar usage across Brazil.
Pump mechanisms anchor premium positioning; sachets show steepest expansion trajectory through digital sampling programs.
Distribution Channel:
Channel selection determines formulation positioning and margin structure more than demographic targeting.
- Pharmacies:Dermocosmetic endorsement with trained staff consultation. Sensitive-skin variants achieve highest conversion rates here through trust transfer from white-coat authority.
- Online Retail:Algorithmic replenishment and subscription bundling. Seoul metropolitan penetration exceeds 40% of category volume through platform-integrated usage tracking.
- Hypermarkets:Mass-market liquid formats with promotional dependency. Price-accessible positioning in Poland and Mexico sustains volume despite margin compression.
- Specialty Stores:Curated clean-beauty assortments with ingredient transparency mandates. Silicone-free certification requirements in California and New York concentrate premium placement here.
Pharmacies hold established volume; online retail is climbing the fastest through subscription lock-in mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France manufactures the majority of premium micellar water formulations while South Korea and the United States absorb disproportionate consumption volumes through distinct channel structures.
France
Pharmacy chains in Paris and Lyon anchor dermocosmetic distribution where trained staff consultation drives sensitive-skin variant conversion. REACH authorization requirements through ECHA force granular surfactant supply chain documentation back to vegetable oil harvest. The Île-de-France cluster concentrates formulation R&D laboratories serving export markets across Western Europe.
South Korea
Double-cleansing protocols in Seoul and Busan sustain per-capita consumption exceeding Western benchmarks through platform-integrated replenishment algorithms. MFDS cosmetic safety assessments mandate preservative disclosure standards that exceed regional norms. Beauty retailers in the Seoul Capital Area anchor micellar water as the essential first-step product in multi-step routines.
United States
Clean-beauty specialty stores in California and New York mandate silicone-free certification for shelf placement, compressing legacy formulation windows. FDA cosmetic labeling requirements impose strict surfactant disclosure thresholds that elevate compliance costs. Direct-to-consumer subscription channels in New York capture recurring revenue through algorithmic usage tracking.
Germany
Pump-dispense mechanisms dominate pharmacy chains in Berlin and Munich through perceived hygiene premiums and dosage precision. ECHA substance evaluations accelerate industry-wide reformulation toward biodegradable sugar-based surfactants. The North Rhine-Westphalia region concentrates biodegradability testing laboratories facing extended OECD 301B protocol queue times.
India
Tier-two cities present underpenetrated dermocosmetic distribution whitespace for sensitive-skin positioning as CDSCO registration pathways streamline. BIS cosmetic standards enforcement tightens ingredient disclosure requirements for imported formulations. Maharashtra and Gujarat anchor domestic manufacturing infrastructure serving pharmacy channel expansion.
Micellar Water Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and channel access vectors. The vendor base stratifies into three tiers: multinational beauty conglomerates with pharmacy network control, regional dermocosmetic specialists with dermatological endorsement protocols, and mass-market consumer goods groups competing on price-accessible liquid formats. Dominant competitive moves include refill infrastructure partnerships with retail chains and biopolymer micelle engineering through university laboratory alliances.
Within the conglomerate tier, L'Oréal and Unilever occupy positions defined by divergent channel strategies. L'Oréal anchors premium positioning through pharmacy network dominance across Western Europe. Unilever exemplifies mass-market scale economics through price-accessible formats in emerging market hypermarkets. Bioderma represents the pure-play dermocosmetic archetype, sustaining formulation credibility through clinical testing protocols that reinforce trust transfer in pharmacy environments.
| Leading Market Players |
|---|
| Procter & Gamble |
| Bioderma |
| L'Oréal |
| Beiersdorf |
| Kao Corporation |
| Shiseido Company |
| Johnson & Johnson |
| Clarins |
| Unilever |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap dermocosmetic specialists in France anchor premium pricing discipline through pharmacy channel control, while their sourcing concentration in Southeast Asian coconut-derived surfactant hubs exposes margins to freight volatility and raw material availability swings.
Pricing Analysis
Cost-down pressure on mass-market liquid tiers accelerates because Unilever and comparable consumer goods groups compete on price-accessible formats in emerging market hypermarkets. Three-tier pricing structure across premium pharmacy-positioned, standard specialty retail, and economy hypermarket levels separates dermatological endorsement tiers. Certification grade—specifically REACH biodegradability compliance and silicone-free clean-beauty mandates—drives price differentiation alongside volume scale procurement. Mass-market buyers in Poland and Mexico exhibit highest price sensitivity, while prestige consumers in Paris and Milan accept forty percent premiums for gel textures with sensorial positioning.
Supply Chain Analysis
Freight cost volatility through the Strait of Malacca compresses margins for brands dependent on Southeast Asian glucoside processing hubs. Coconut-derived surfactant feedstock concentrates in Indonesia, Malaysia, and the Philippines, with formulation chemistry resting on vegetable oil harvest documentation back to plantation level. Single-source vulnerability intensifies as weather disruptions and shipping lane congestion compound procurement uncertainty. Distribution runs through pharmacy chains in Western Europe, direct-to-consumer platforms in Seoul and New York, and hypermarket networks across emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The micellar water category is becoming a vertical-integration race as players pursue captive supply of biodegradable surfactant feedstocks to secure REACH compliance and margin control against raw material volatility.
For Market Incumbents: Extend pharmacy channel dominance through refill infrastructure partnerships with French supermarket chains, locking brand loyalty via closed-loop vessel exchange programs. Deepen backward integration into fermentation-derived lipid aggregate production through university laboratory alliances in France and Germany, insulating formulation pipelines from Southeast Asian supply concentration. Counter waterless cleansing substitution threats by accelerating hybrid micelle-encapsulation systems that unify makeup removal with active delivery. For New Entrants and Emerging Players: Begin with tier-two Indian cities where CDSCO registration streamlines and dermocosmetic distribution remains underpenetrated for sensitive-skin positioning. Target combination-skin segments in urban Indian markets where consumers reject binary dry/oily categorization and local formulation gaps persist. Pursue silicone-free certification early to secure shelf placement in California and New York clean-beauty specialty stores before compliance standardizes. For Investors and Strategic Acquirers: Distressed-cycle entries favor biopolymer micelle engineering specialists with pre-validated OECD 301B biodegradability certification in Germany and Switzerland. Long-term viability over the next decade hinges on refill station infrastructure scalability and regulatory compliance pipeline depth. Watch queue times for ECHA substance evaluation and OECD protocol validation as inflection indicators for first-mover advantage windows.| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Micelle Engineering | Fermentation-derived lipid aggregates enable pH-stable formulations without synthetic polymers through French and German university partnerships. |
| Refill Station Infrastructure | Retail partnerships with French supermarket chains demonstrate scalable closed-loop models that lock consumer loyalty through vessel exchange economics. |
| Silicone-Free Certification | Early compliance with California and New York clean-beauty retailer mandates secures premium shelf placement before standardization spreads. |
| Pharmacy Channel Expansion | Trained staff consultation in Paris and Lyon pharmacy chains drives sensitive-skin variant conversion through dermatological trust transfer. |
| Direct-to-Consumer Platform Launch | Algorithmic usage tracking in Seoul and New York captures recurring revenue through subscription replenishment displacing impulse purchases. |
Methodological Framework
Trade databases, ECHA substance evaluation filings, and MFDS cosmetic safety assessment records formed the secondary backbone for surfactant supply chain mapping and regulatory compliance tracking. Primary interviews with pharmacy chain category managers, dermocosmetic brand development executives, and biodegradability testing laboratory directors in Germany and Switzerland combined with secondary validation. Customs records for coconut-derived glucoside feedstock flows and Nielsen retail audit data for channel volume splits enabled bottom-up and top-down triangulation across formulation chemistry and packaging modality segments.
Historical trendline analysis of pharmacy channel premium positioning versus hypermarket mass-market penetration established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated skin sensitivity profiles, formulation textures, packaging mechanisms, and distribution channel structures. CAGRs derived from algorithmic replenishment penetration rates in Seoul, refill infrastructure scaling curves in France, and regulatory compliance timeline assumptions for REACH biodegradability thresholds. Forecast inputs included university partnership commercialization timelines for biopolymer micelle systems and CDSCO registration pathway streamlining rates for Indian market entry.
Underlying measurement precision varies by segment; online retail subscription data and pharmacy chain sell-through reports carry tighter precision than emerging market hypermarket estimates where informal channel leakage persists. Forecasts reflect documented assumptions about regulatory enforcement timing and surfactant feedstock supply stability. Stakeholders should weight assumptions against their own operating context for supply chain concentration and channel access investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Soy-Based Surfactants Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Emulsion Stabilizers Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
MDEA Esterquats Market
Surfactants
Tetradecyl Chloride Market
Surfactants
Superwetting Surfactants Market
Surfactants
Dioctyl Sulfosuccinates Components Market
Surfactants
Pharmaceutical Surfactants Market
Surfactants
Sodium Lauryl Sulphate Market
Surfactants
Cetyl Trimethyl Ammonium Chloride Market
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
Surfactant EOR Market
Surfactants
Green Surfactants Market
Surfactants
Asia Pacific Biosurfactants Market
Surfactants
North America Surfactants Market