
 Wax Emulsion Market | 2026-2036
Wax Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Wax Emulsion Market Analysis
EU REACH restrictions on volatile organic compound emissions is consolidating demand toward water-based wax emulsion systems across industrial coating supply chains. Sasol Limited leverages its integrated Fischer-Tropsch wax operations to secure feedstock advantage for synthetic emulsion grades. Dow Inc. sustains technology leadership in polymer-stabilized dispersion chemistry for high-performance surface coatings. Clariant AG specializes in micronized and emulsified natural wax portfolios tailored to cosmetics and food-contact applications.
Wax emulsion denotes a stable colloidal dispersion of wax particles in a continuous aqueous or solvent phase, typically manufactured through high-pressure homogenization or phase-inversion processes to achieve particle sizes between 0.1 and 5.0 micrometers for controlled film formation and surface modification. Paraffin wax emulsions retain mature volume positions in paper coating and food packaging where cost efficiency governs procurement decisions. Synthetic wax dispersions represent the fastest-expanding product category as polyolefin and Fischer-Tropsch variants deliver superior thermal stability and abrasion resistance for automotive and industrial surface coatings. Water-based formulations command expanding share across all end-use segments as environmental compliance tightens and solvent recovery costs escalate.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based formulation expansion in US manufacturing facilities, while REACH registration requirements and the EU Green Deal's chemical sustainability targets reshape product development priorities for emulsion suppliers serving European coating formulators. China's MEE enforcement of VOC emission limits in the Yangtze River Delta and Pearl River Delta clusters is redirecting domestic production capacity toward water-based systems. Stakeholders must monitor evolving bio-based content mandates and carbon border adjustment mechanisms to anticipate reformulation investments and regional supply reconfigurations.
Market Dynamics
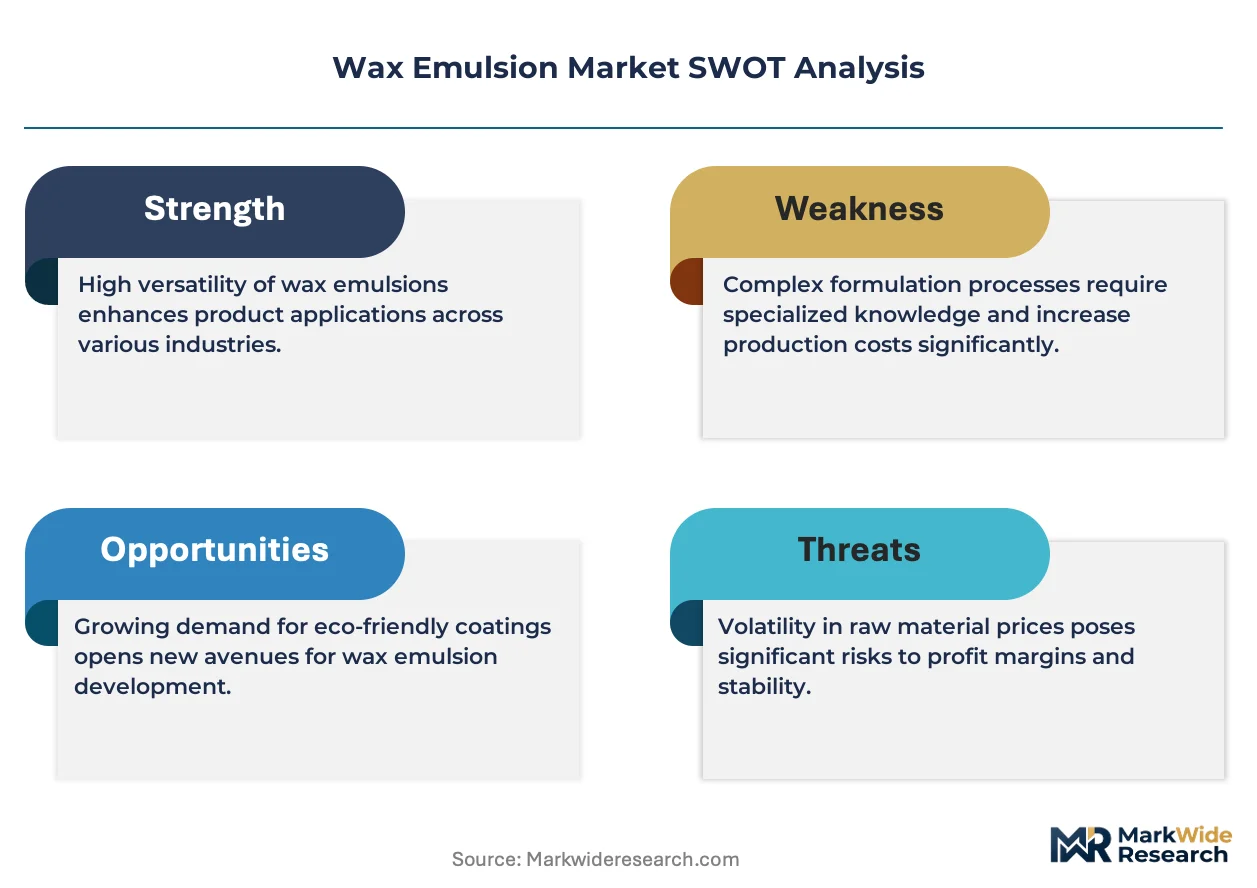
REACH restrictions on volatile organic compounds are forcing coating formulators across Europe to abandon solvent-based systems, consolidating procurement around water-based wax emulsion alternatives with superior film-forming properties.
Growth Catalysts
- Automotive OEM reformulation:German vehicle manufacturers are accelerating water-based coating adoption to meet fleet emission standards and reduce solvent recovery infrastructure costs.
- ECHA registration timelines:Accelerated substance evaluation under REACH is disqualifying legacy solvent-based additives, opening specification windows for compliant emulsion chemistries.
- Fischer-Tropsch wax availability:Synthetic feedstock expansion from gas-to-liquid operations is improving thermal stability benchmarks for high-performance industrial finishes.
Market Restraints
- Crude oil derivative volatility:Paraffin wax feedstock costs fluctuate with naphtha cracking margins, compressing margin predictability for commodity-grade emulsion suppliers.
- Specialty additive concentration:Polymer stabilizer and surfactant supply clusters in the US Gulf Coast and Rotterdam harbor create geographic vulnerability for European formulators.
- Water sensitivity limitations:Aqueous emulsion films exhibit inferior moisture barrier performance versus solvent-cast alternatives in food packaging applications.
Strategic Opportunities
- India industrial coating expansion:BIS adoption of VOC emission limits for decorative paints is creating first-mover advantage for water-based system suppliers in Mumbai and Gujarat manufacturing corridors.
- Cosmetics clean-label positioning:Emulsified carnauba and candelilla wax portfolios command formulation preference as natural origin claims displace petroleum-derived alternatives.
- EU Green Deal carbon border adjustments:Embedded carbon accounting for imported coatings is incentivizing regional emulsion production investment near downstream formulators.
Industry Challenges
- Homogenization equipment scarcity:High-pressure dispersing capacity for sub-micron particle size distribution requires specialized engineering expertise concentrated among legacy equipment suppliers.
- Multi-jurisdiction registration burden:Separate dossier preparation for EPA TSCA, REACH, and China's MEE chemical inventories extends product launch timelines and strains regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wax Emulsion Market |
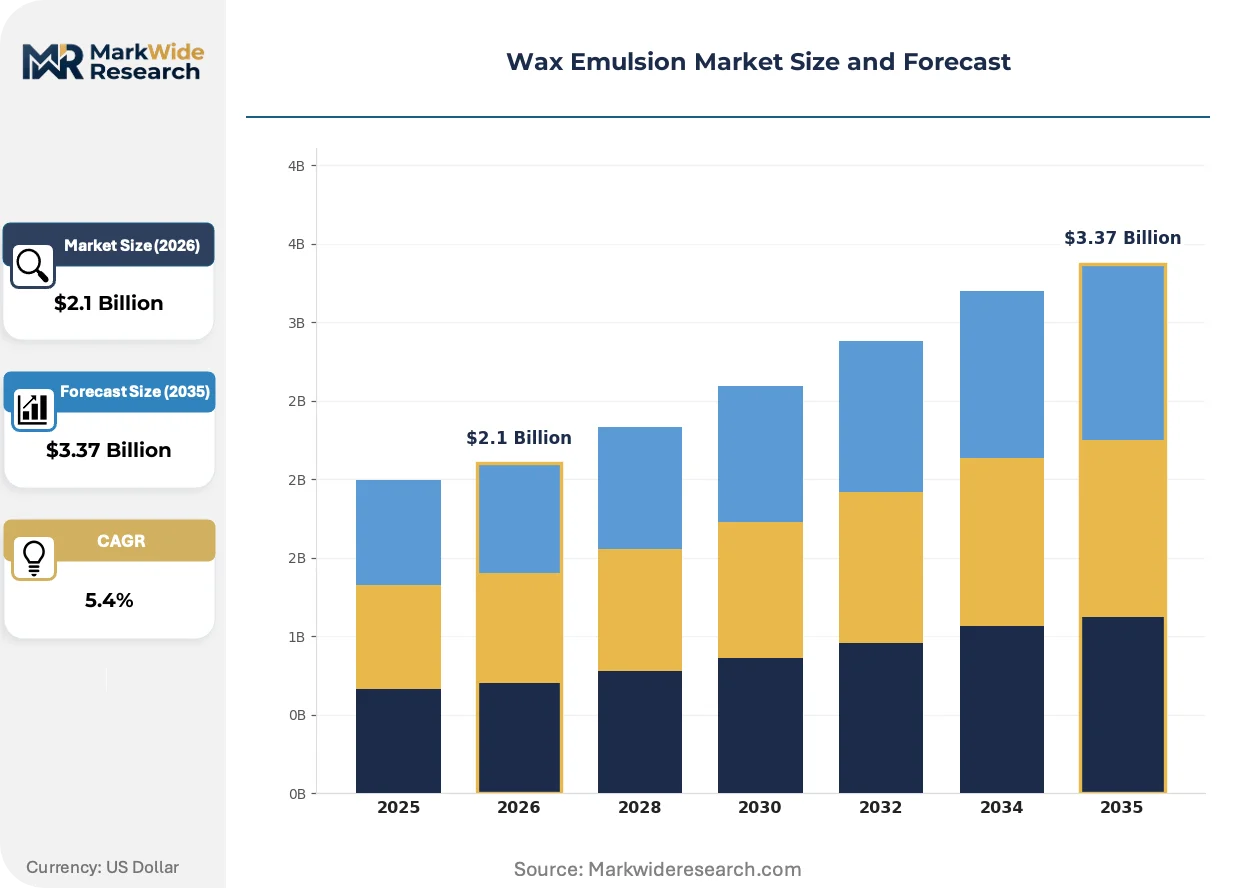
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcrystalline Wax, Paraffin Wax, Synthetic Wax, Natural Wax End Use Industry: Paints & Coatings, Cosmetics, Adhesives, Textiles Application: Surface Coatings, Textile Finishing, Food Packaging, Paper Coating Formulation: Water-Based, Solvent-Based, Emulsion, Others |
| Companies Covered | Sasol Limited, Dow Inc., BASF SE, Evonik Industries AG, Clariant AG, ExxonMobil Corporation, ALTANA AG, Nippon Seiro Co., The Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wax Emulsion Market Emerging Trajectories
Formulation chemistry is converging around bio-based stabilization systems that eliminate petroleum-derived surfactants while maintaining colloidal stability across freeze-thaw cycles.
Hybrid natural-synthetic wax blends are unifying the cost efficiency of paraffin with the thermal performance of Fischer-Tropsch variants. Automotive underbody coating formulators in Stuttgart and Wolfsburg are specifying these intermediates for stone-chip resistance applications. The technology is unifying previously separate procurement streams for commodity and specialty wax grades into single-source supply relationships.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is constraining solvent-based capacity expansion at US manufacturing facilities. Coating producers in Ohio and Michigan are redirecting capital toward aqueous dispersion equipment and wastewater treatment infrastructure. Wood furniture finishing operations are experiencing the most acute compliance pressure, accelerating specification changes for water-based surface treatments.
Specification authority is migrating from formulator technical teams to corporate sustainability officers with mandate over Scope 3 emission reduction targets. Tier-1 automotive suppliers now require wax emulsion vendors to provide product carbon footprint data and mass balance certifications for bio-based content claims. This behavioral shift is most pronounced in German and Austrian industrial coating supply chains where OEM sustainability scorecards determine qualified supplier status.
Wax Emulsion Market Segmentation
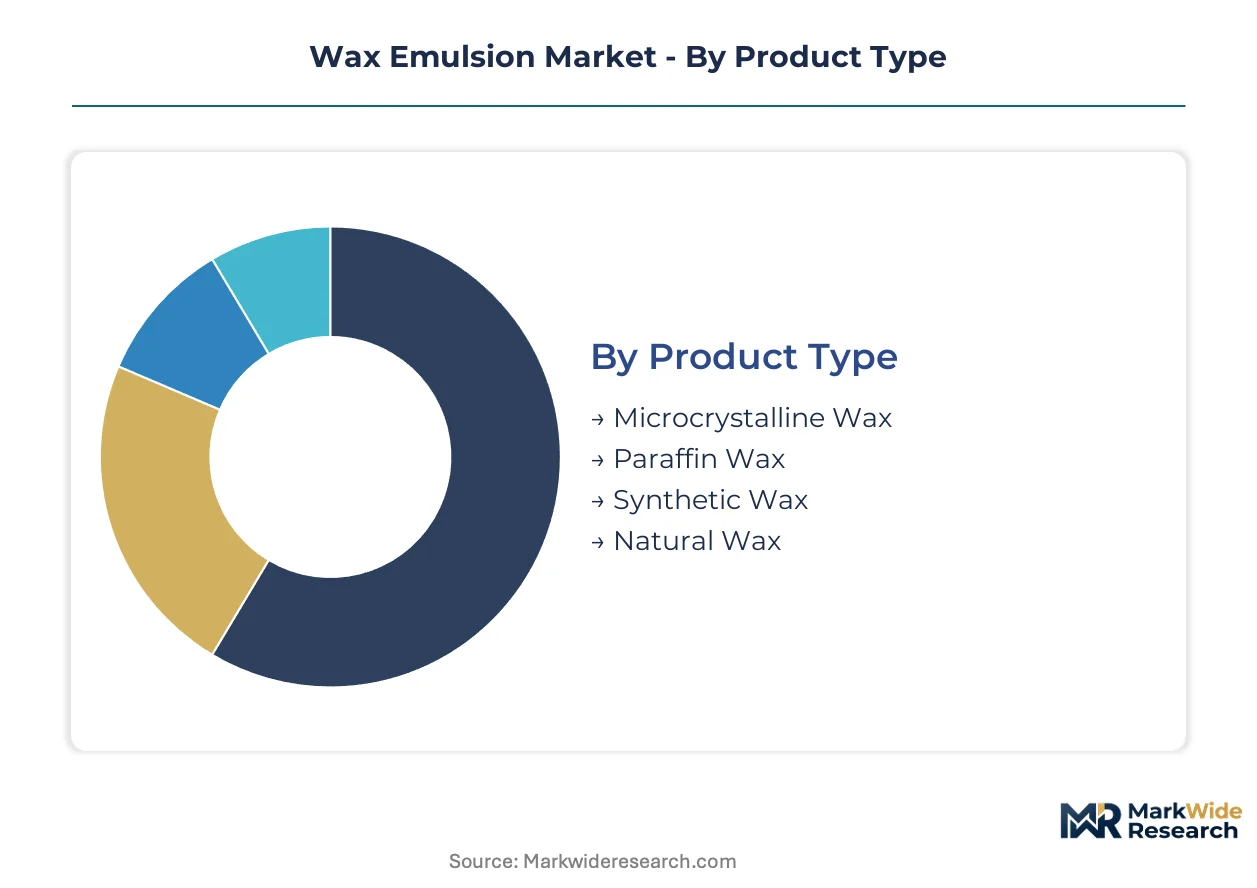
Wax emulsion segmentation reflects divergent technical requirements across industrial coating, consumer goods, and packaging applications. Procurement patterns vary sharply between commodity paraffin grades for high-volume paper coating and specialty synthetic dispersions demanding precise particle size distribution for automotive finishes.
Product Type:
The customization-vs-standardization spectrum runs from specification-tolerant paraffin commodities to engineered synthetic grades requiring tight thermal stability benchmarks for OEM qualification.
- Paraffin Wax:Refined petroleum distillates with crystalline structure dominate paper coating and corrugated board applications where cost efficiency governs procurement. Demand concentrates in German packaging converters reformulating for EU Green Deal compliance, though margin pressure from naphtha feedstock volatility constrains supplier pricing power.
- Synthetic Wax:Fischer-Tropsch and polyolefin variants deliver superior abrasion resistance and thermal stability for automotive underbody coatings and industrial metal finishes. German OEMs in Stuttgart and Wolfsburg specify these grades for stone-chip resistance applications, consolidating procurement around integrated gas-to-liquid feedstock suppliers.
- Microcrystalline Wax:Amorphous petroleum-derived grades with higher oil content provide flexibility in adhesives and rust-preventive coatings where low-temperature performance matters.
- Natural Wax:Carnauba and candelilla emulsions serve cosmetics and food-contact applications requiring bio-based origin claims and clean-label positioning.
Leading the category by volume: Paraffin Wax. Growing fastest: Synthetic Wax.
End Use Industry:
Margin structure varies from thin commodity coatings to premium personal care formulations where certification costs amortize across smaller batch sizes.
- Paints & Coatings:Architectural, automotive, and industrial surface treatments represent the dominant demand pool. REACH-driven solvent restrictions across Europe are redirecting specification authority toward water-based emulsion systems with controlled film-forming properties.
- Cosmetics:Emulsified natural waxes command formulation preference for lipsticks, creams, and hair care products where petroleum-derived alternatives face clean-label displacement.
- Adhesives:Hot-melt and pressure-sensitive applications utilize microcrystalline and paraffin emulsions for tack modification and open-time control.
- Textiles:Fabric finishing and nonwoven binders employ wax emulsions for water repellency and hand modification in technical apparel applications.
Volume leadership sits with Paints & Coatings. Cosmetics exhibits the steepest expansion trajectory as natural origin claims displace synthetic alternatives.
Application:
Technical performance requirements span moisture barrier specifications in food contact to abrasion resistance in automotive underbody protection.
- Surface Coatings:Architectural and industrial protective finishes utilize synthetic wax dispersions for gloss control and mechanical durability. German automotive OEMs specify sub-micron particle distributions for Class A surface quality.
- Food Packaging:Paraffin and microcrystalline emulsions provide moisture barrier properties in paperboard and corrugated applications, though aqueous films exhibit inferior performance versus solvent-cast alternatives.
- Textile Finishing:Water-repellent treatments for technical fabrics and outdoor apparel employ emulsified waxes as durable water-repellent alternatives to fluorinated chemistries.
- Paper Coating:High-volume applications in printing and packaging papers utilize commodity paraffin emulsions for surface sizing and gloss enhancement.
Surface Coatings leads by value contribution. Food Packaging expands most quickly as bio-based barrier coatings gain regulatory preference.
Formulation:
Environmental compliance timelines are restructuring capacity investment toward aqueous systems despite residual solvent demand in moisture-critical applications.
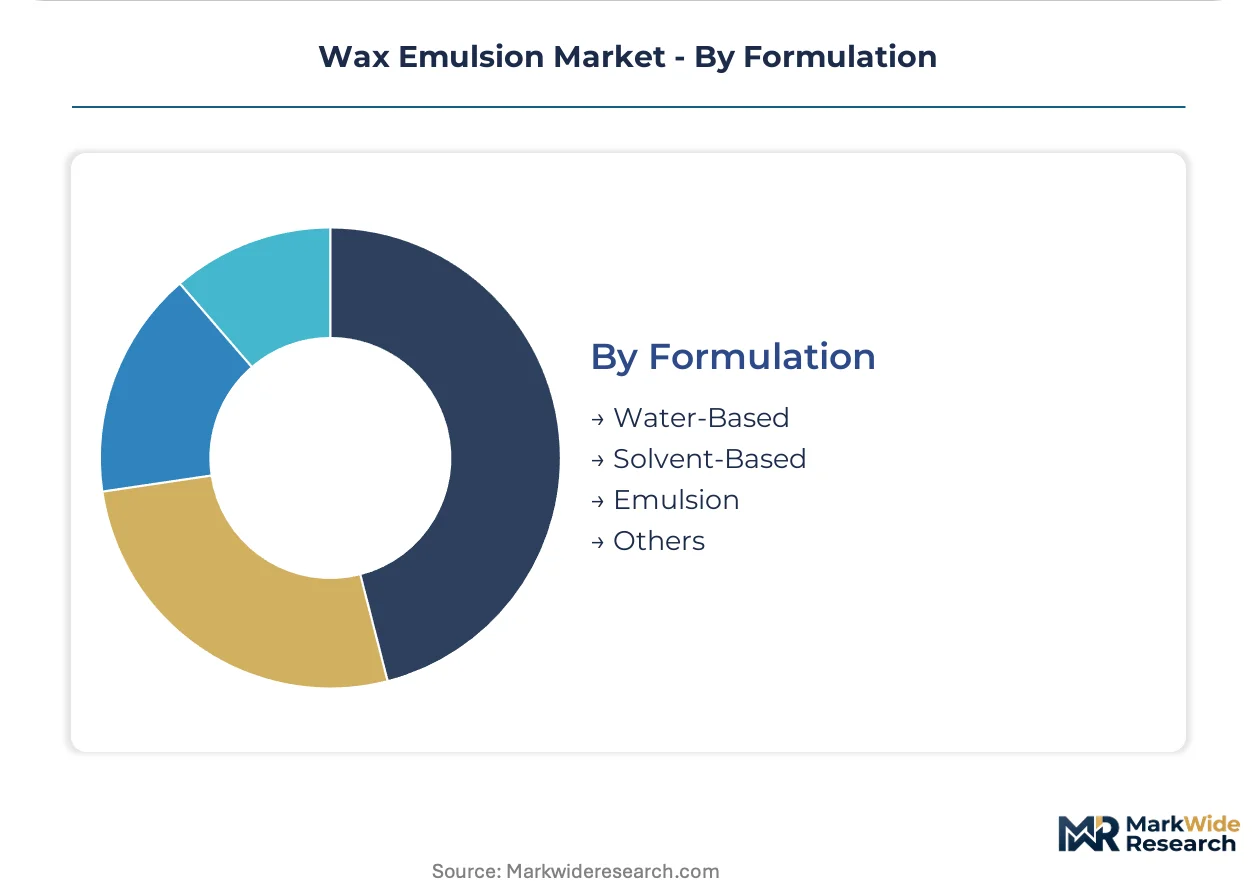
- Water-Based:Aqueous dispersions stabilized with surfactant and polymer systems command expanding share across all end-use segments. EPA NESHAP constraints in Ohio and Michigan manufacturing facilities are accelerating capital redirection toward aqueous dispersion equipment.
- Solvent-Based:Hydrocarbon and oxygenated solvent systems retain niche positions in food packaging and specialty coatings where moisture barrier performance is paramount.
- Emulsion:Colloidal wax-in-water systems manufactured through high-pressure homogenization represent the standard commercial format for industrial applications.
- Others:Hot-melt dispersions and powder wax preparations serve specialized applications incompatible with liquid delivery systems.
Water-Based formulations dominate current volume. Solvent-Based systems are contracting fastest under multi-jurisdiction VOC enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European wax emulsion demand as German automotive OEMs reformulate coating systems for EU Green Deal compliance. Water-based dispersion capacity is expanding across the Stuttgart-Wolfsburg corridor to serve stone-chip resistance specifications.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive specification authority for synthetic wax emulsions in underbody coatings. REACH registration timelines under ECHA are disqualifying legacy solvent-based additives from qualified supplier lists. The Stuttgart manufacturing corridor is consolidating procurement around Fischer-Tropsch feedstock suppliers with integrated gas-to-liquid operations.
United States
Wood furniture finishers in Ohio and Michigan face acute EPA NESHAP compliance pressure for surface treatment applications. The National Emission Standards for Hazardous Air Pollutants are constraining solvent-based capacity expansion across Great Lakes manufacturing facilities. Coating producers are redirecting capital toward aqueous dispersion equipment and wastewater treatment infrastructure in these states.
China
Industrial coating formulators in the Yangtze River Delta and Pearl River Delta are redirecting production capacity toward water-based systems. MEE enforcement of VOC emission limits is tightening across eastern coastal manufacturing clusters. Domestic emulsion suppliers are scaling high-pressure homogenization capacity to serve architectural and automotive coating demand in Shanghai and Jiangsu province.
India
Decorative paint manufacturers in Mumbai and Gujarat manufacturing corridors are preparing for BIS adoption of VOC emission limits. The Bureau of Indian Standards is aligning technical regulations with European REACH frameworks for industrial coatings. Water-based system suppliers are establishing formulation laboratories in Maharashtra to capture first-mover advantage in compliance-driven procurement.
Japan
Cosmetics formulators in the Kanto region specify emulsified carnauba and candelilla waxes for clean-label positioning. METI guidance on chemical substance management is elevating bio-based content requirements for personal care applications. Tokyo-area compounders are certifying natural wax portfolios to displace petroleum-derived alternatives in premium skincare formulations.
Wax Emulsion Market Vendor Landscape
The competitive structure tilts toward integrated petrochemical operators with captive Fischer-Tropsch feedstock positions. Specialty chemical houses with polymer stabilization expertise occupy the technology-intensive tier, while regional emulsion compounders serve packaging and construction applications with commodity paraffin grades. Three archetypes dominate: integrated synthetic wax producers, polymer dispersion specialists, and natural wax portfolio managers. Capacity expansion and strategic partnerships constitute the primary competitive moves as suppliers position near downstream formulators facing carbon border adjustment exposure.
Among integrated petrochemical operators, Sasol Limited and ExxonMobil Corporation anchor the synthetic wax supply tier with backward integration into gas-to-liquid and petroleum refining operations respectively. Dow Inc. exemplifies the polymer stabilization specialist archetype, while Clariant AG occupies a position within the natural and micronized wax segment serving cosmetics and food-contact applications.
| Leading Market Players |
|---|
| Sasol Limited |
| Dow Inc. |
| BASF SE |
| Evonik Industries AG |
| Clariant AG |
| ExxonMobil Corporation |
| ALTANA AG |
| Nippon Seiro Co. |
| The Lubrizol Corporation |
| Others |
Supply Flow & Price Mechanics
Automotive OEM reformulation mandates in Germany are forcing coating suppliers to absorb certification and equipment conversion costs, compressing margins for commodity-grade paraffin emulsion producers while synthetic Fischer-Tropsch suppliers capture value through thermal performance premiums.
Pricing Analysis
Performance-based pricing anchors synthetic wax emulsion contracts to stone-chip resistance outcomes in automotive underbody applications. Three-tier pricing structure across premium Fischer-Tropsch, standard polyolefin, and economy paraffin grades reflects certification complexity and thermal stability benchmarks. Pricing pressure stems from naphtha feedstock volatility compressing paraffin supplier margins. Commodity paper coating buyers exhibit highest price sensitivity, while automotive OEM technical teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Emulsion returns and off-specification batches feed back into reprocessing circuits at German compounding facilities, reducing raw material waste in high-pressure homogenization operations. Feedstock supply concentrates in South Africa, Qatar, and Germany through integrated gas-to-liquid operations and petroleum refining complexes. Manufacturing draws from Fischer-Tropsch wax, polymer stabilizers, and surfactant inputs. Single-source vulnerability exists for high-pressure dispersing equipment engineered by specialized German and Italian machinery suppliers. Distribution runs through regional blending terminals serving Stuttgart-Wolfsburg automotive corridors and Rotterdam chemical hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where REACH registration timelines and ECHA substance evaluations erect regulatory moats favoring incumbents with established dossier capabilities and qualified supplier status.
For Market Incumbents: Extend qualified supplier relationships with German automotive OEMs by investing in product carbon footprint certification and mass balance documentation for bio-based content claims. Defend against specialty chemical entrants by securing captive Fischer-Tropsch feedstock through long-term offtake agreements with gas-to-liquid operators. Capacity addition in the Stuttgart manufacturing corridor reinforces proximity advantages for just-in-time coating supply. For New Entrants and Emerging Players: BIS adoption of VOC emission limits in India opens a window for water-based system suppliers to establish formulation laboratories in Maharashtra before domestic incumbents complete compliance transitions. Target decorative paint manufacturers in Mumbai and Gujarat corridors with technical service models emphasizing reformulation support. Natural wax emulsion portfolios for cosmetics applications in Japan's Kanto region offer penetrable white-space with clean-label positioning against petroleum-derived alternatives. For Investors and Strategic Acquirers: The window for entry favors integrated petrochemical operators with backward control over synthetic wax feedstock and established ECHA registration portfolios. Long-term viability hinges on carbon border adjustment resilience and regional production positioning near downstream formulators. Monitor EU Green Deal embedded carbon accounting implementation as inflection signal for supply chain reconfiguration investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fischer-Tropsch Feedstock | Captive wax supply from Sasol's gas-to-liquid operations secures thermal stability specification control for automotive OEMs. |
| Water-Based Capacity Expansion | Aqueous dispersion equipment investment in Ohio and Michigan addresses EPA NESHAP constraints on solvent-based coating production. |
| Natural Wax Portfolio Certification | Emulsified carnauba and candelilla certification to METI bio-content standards unlocks premium cosmetics positioning in Japan. |
| Regional Blending Terminal Network | Proximity production near Stuttgart and Wolfsburg automotive clusters minimizes carbon border exposure under EU Green Deal mechanisms. |
| High-Pressure Homogenization Technology Licensing | Sub-micron particle distribution expertise transfers to Yangtze River Delta suppliers scaling water-based architectural coating capacity. |
Methodological Framework
Multi-period observation of ECHA registration timelines, EPA enforcement patterns, and MEE VOC compliance trajectories anchored the trend analysis, supplemented by interviews with coating formulators, automotive OEM procurement specialists, and specialty chemical regulatory affairs directors. Primary fieldwork across German automotive corridors, US Great Lakes manufacturing facilities, and Chinese Yangtze River Delta clusters combined with secondary validation from customs trade data, SEC chemical segment disclosures, and national chemical inventory filings. Bottom-up emulsion demand modeling triangulated against top-down coatings market value estimates.
Segment-weighting approaches distributed volume and value across paraffin, synthetic, microcrystalline, and natural wax grades, further disaggregated by water-based versus solvent-based formulation chemistry, end-use industry concentration, and regional regulatory cluster intensity. CAGRs derived from fitted growth curves reflecting compliance-driven substitution elasticities, feedstock cost trajectories, and capacity expansion announcements throughout the projection horizon. Industry-specific forecast inputs incorporated REACH substance evaluation schedules and BIS technical regulation adoption timelines.
Caveats apply where accelerated ECHA substance restrictions, abrupt naphtha feedstock price dislocations, or carbon border adjustment mechanism implementation delays could materially shift the outlook. Practitioners should monitor EU Green Deal embedded carbon accounting rulemaking and MEE enforcement intensity in Pearl River Delta clusters for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
Emulsifying Wax Market
Surfactants
Global Demulsifiers Market
Surfactants
Global Detergents Market
Surfactants
Amphoteric Emulsifier Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Global Silicone Surfactants Market
Surfactants
MDEA Esterquats Market
Surfactants
Anionic Surfactants Market
Surfactants
Alcohol Ether Sulfates Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Global Biosurfactant Market
Surfactants
Sodium Lauroyl Sarcosinate Market
Surfactants
Wetting Agents Market
Surfactants
Sodium Lauryl Sulphate Market