
 Soy-Based Surfactants Market | 2026-2036
Soy-Based Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Soy-Based Surfactants Market Analytics
Specialized oleochemistry expertise is redrawing competitive boundaries in soy-based surfactants as traditional petrochemical formulators retrain technical staff for triglyceride processing. Archer Daniels Midland Company leverages its upstream crushing infrastructure to secure consistent lecithin and fatty acid streams for surfactant precursors. Stepan Company anchors North American production with alkoxylation capabilities tuned to soy-derived alcohols. Evonik Industries AG differentiates through amphoteric technologies that exploit soy betaine structures for mild personal care applications.
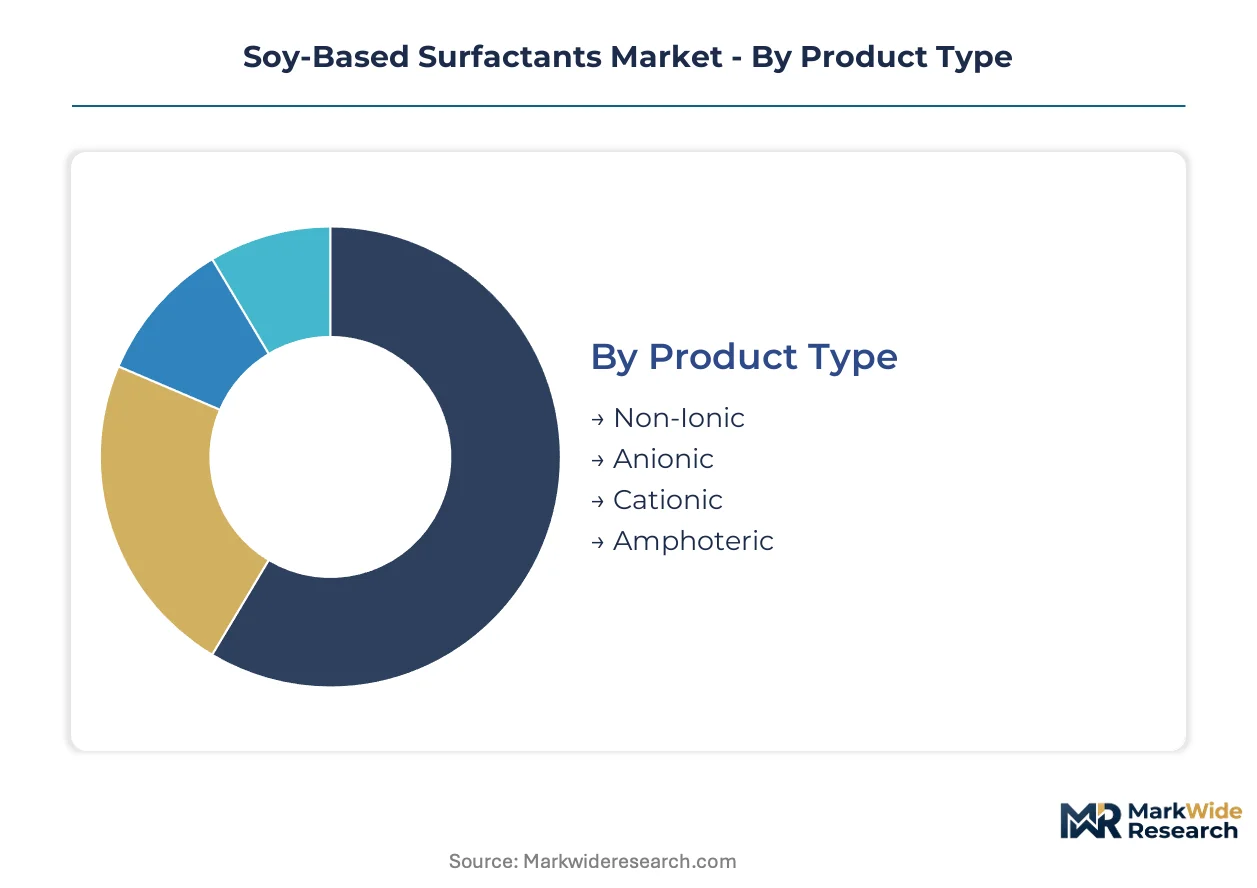
Soy-based surfactants are surface-active agents synthesized from soybean oil triglycerides through hydrolysis, ethoxylation, or sulfonation, typically exhibiting HLB values between 8 and 16 for emulsification and detergency functions in aqueous systems. Non-ionic variants dominate volume due to their compatibility across hard water conditions and mildness profiles prized by personal care brands. Liquid forms lead industrial cleaning adoption because of easier dosing integration in automated dilution systems, while powder grades sustain growth in concentrated laundry formulations where shipping economics favor reduced water content. The emulsifiers segment captures premium positioning as cosmetic manufacturers reformulate water-oil systems away from synthetic ethoxylates.
EPA Safer Choice labeling and REACH Annex XVII restrictions on nonylphenol ethoxylates are redirecting procurement budgets toward bio-based alternatives that soy surfactants satisfy. BIS certification requirements in India and China's GB standards for biodegradable detergents are expanding addressable markets for exporters with compliant manufacturing. The EU F-Gas Regulation indirectly supports soy surfactant penetration in cleaning applications where fluorinated surfactants face phase-down timelines. Stakeholders must monitor feedstock price volatility against fossil-derived alternatives while building formulation partnerships with end-users ahead of tightening chemical inventory disclosures.
Market Dynamics
REACH Annex XVII restrictions on nonylphenol ethoxylates and EPA Safer Choice labeling requirements are structurally redirecting procurement budgets toward bio-based surfactant feedstocks, compressing the addressable market for petrochemical alternatives while elevating soy-derived chemistry in formulation pipelines.
Growth Catalysts
- EU Green Deal decarbonization mandates:Industrial cleaning manufacturers in Germany are retrofitting formulations to meet binding emissions targets, creating pull-through demand for plant-derived surfactants with verified carbon footprints.
- India's BIS certification expansion:Biodegradable detergent standards under compulsory certification schemes are opening export channels for compliant soy surfactant producers seeking new volume outlets.
- Personal care brand reformulation:Water-oil emulsifier systems are transitioning away from synthetic ethoxylates as cosmetic manufacturers respond to ingredient disclosure pressures from EU and US retailers.
Market Restraints
- Soybean oil price volatility:Agricultural commodity swings create margin compression versus stable-priced fossil-derived surfactant alternatives, complicating long-term contract pricing.
- Specialized oleochemistry talent scarcity:Triglyceride processing expertise concentrates among legacy edible oil processors, limiting formulation service capacity for new market entrants.
- Fluorinated surfactant phase-down timelines:EU F-Gas Regulation restrictions on perfluorinated chemistry create substitution pressure, but performance gaps in high-heat cleaning applications slow complete displacement.
Strategic Opportunities
- China's GB standards compliance gap:Domestic biodegradable detergent certification lags behind export requirements, creating first-mover advantage for foreign producers with pre-certified manufacturing.
- Alkoxylation technology convergence:Integration of continuous processing with soy-derived alcohol feedstocks enables custom HLB tuning for specialty personal care applications.
- Concentrated laundry powder formats:Reduced water content shipping economics favor soy surfactant powders in e-commerce direct-to-consumer channels bypassing traditional distributor networks.
Industry Challenges
- Triglyceride hydrolysis scale-up complexity:Batch-to-batch fatty acid profile variation requires real-time quality adjustment systems that strain legacy surfactant plant infrastructure.
- REACH full substance registration timelines:New soy-derived surfactant chemistries face multi-year dossier preparation periods that delay market entry against established petrochemical registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy-Based Surfactants Market |
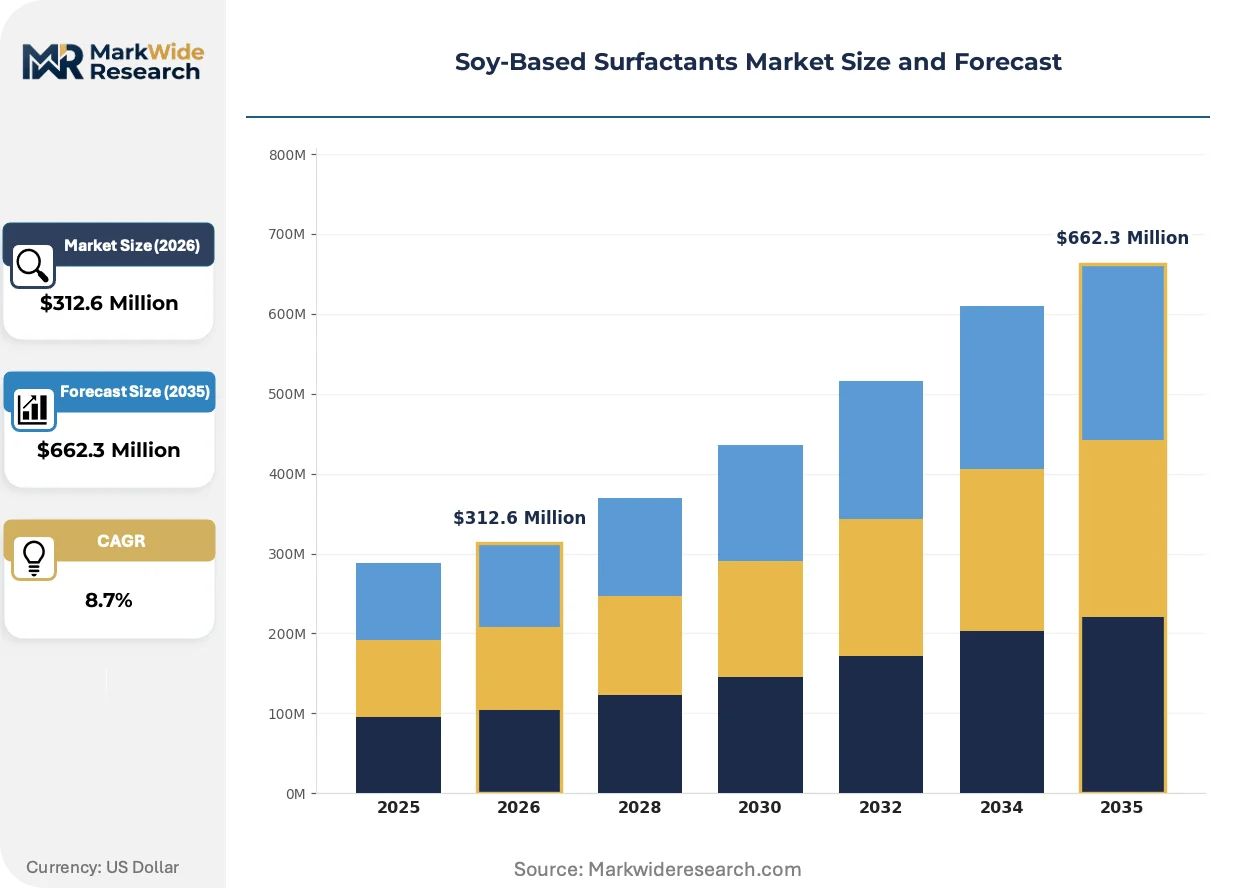
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Ionic, Anionic, Cationic, Amphoteric End User: Personal Care, Household Products, Industrial Cleaning, Agriculture Application: Detergents, Emulsifiers, Dispersants, Foaming Agents Form: Liquid, Powder, Paste, Granules |
| Companies Covered | Archer Daniels Midland Company, DuPont, The Scoular Company, FUJI OIL ASIA, Stepan Company, Evonik Industries AG, Clariant AG, BASF SE, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy-Based Surfactants Market Evolving Landscape
Enzymatic interesterification processes are reshaping how soy surfactant precursors achieve consistent fatty acid distributions, enabling tighter HLB control for cosmetic formulators.
Enzymatic transesterification is supplanting traditional chemical hydrolysis in premium surfactant precursor production. Personal care compounders in France and Switzerland are adopting enzymatically processed soy betaines for mild baby care formulations. The technology is compressing capital requirements for mid-scale producers while raising quality consistency barriers for commodity manufacturers.
EPA Safer Choice program expansion into industrial cleaning categories is tightening chemical disclosure thresholds for contract manufacturers serving federal procurement. Facility certification audits now require full supply chain feedstock documentation back to crushing origin. Cleaning chemical blenders in Ohio and Texas are restructuring supplier qualification protocols to maintain eligibility for institutional contracts.
Direct raw material purchasing from crushing cooperatives is fragmenting traditional surfactant distributor relationships. Large personal care brands in California are negotiating toll manufacturing arrangements that bypass standard chemical distribution markups. This channel compression is most advanced in North American markets where identity-preserved soybean traceability commands formulation premiums.
Soy-Based Surfactants Market Segmentation
Soy-based surfactant suppliers configure production lines around specific molecular architectures and physical forms that dictate channel economics. Formulators select segments based on solubility requirements, processing temperatures, and end-use certification standards that vary sharply across personal care, industrial, and agricultural applications.
Product Type:
Non-ionic and anionic variants flow through bulk chemical distributors serving industrial cleaning compounders, while amphoteric grades reach personal care formulators through specialized cosmetic ingredient channels.
- Non-Ionic:Ethoxylated soy alcohols deliver HLB values between 8 and 16, enabling stable emulsification across hard water conditions without complexing agents. Demand concentrates in German industrial cleaning manufacturers retrofitting formulations for EU Green Deal compliance, where compatibility with existing dosing equipment accelerates adoption timelines.
- Anionic:Sulfonated soy fatty acid derivatives provide high foaming capacity and soil suspension in aqueous systems. Personal care brands in France and Switzerland source these for sulfate-free shampoo reformulations, responding to retailer ingredient disclosure mandates that disqualify petroleum-derived alkyl sulfates.
- Cationic:Quaternized soy amines serve conditioning applications in hair care and fabric softeners.
- Amphoteric:Soy betaine structures from enzymatic processing command premium positioning in mild baby care formulations.
Non-ionic surfactants dominate installed base. Amphoteric variants are where expansion concentrates.
End User:
Cost tier stratification separates premium personal care applications from commodity industrial cleaning volumes, with household products occupying a mid-tier position on formulation complexity.
- Personal Care:Cosmetic manufacturers demand certified identity-preserved soy feedstocks with full supply chain documentation to satisfy retailer chemical disclosure protocols. California-based brands negotiate direct toll manufacturing arrangements that bypass standard distributor markups, compressing channel costs for high-margin emulsifier systems.
- Household Products:Concentrated laundry powder formats favor soy surfactant powders where reduced water content improves e-commerce shipping economics. Chinese domestic manufacturers face compliance gaps against export-grade GB standards, creating first-mover openings for pre-certified foreign suppliers.
- Industrial Cleaning:Automated dilution systems in Ohio and Texas facilities specify liquid soy surfactants for precise dosing control.
- Agriculture:Pesticide adjuvant applications require surfactants compatible with complex tank-mix chemistries.
Industrial cleaning commands volume leadership. Personal care delivers margin expansion.
Application:
Application selection tracks directly to processing temperature requirements and interface stabilization demands in target formulations.
- Detergents:Alkoxylation-tuned soy alcohols enable custom HLB matching for specific soil types and water hardness profiles. India's BIS certification expansion for biodegradable detergents opens export channels for compliant producers seeking volume outlets beyond saturated European markets.
- Emulsifiers:Water-oil system stabilization commands premium positioning as cosmetic manufacturers phase out synthetic ethoxylates restricted under REACH Annex XVII. Batch-to-batch fatty acid profile variation necessitates real-time quality adjustment systems that strain legacy surfactant plant infrastructure.
- Dispersants:Pigment and active ingredient suspension applications favor soy-derived chemistry for agricultural and coating formulations.
- Foaming Agents:Controlled foam generation serves fire suppression and food processing applications with strict residue requirements.
Detergents anchor production scale. Emulsifiers are climbing the fastest.
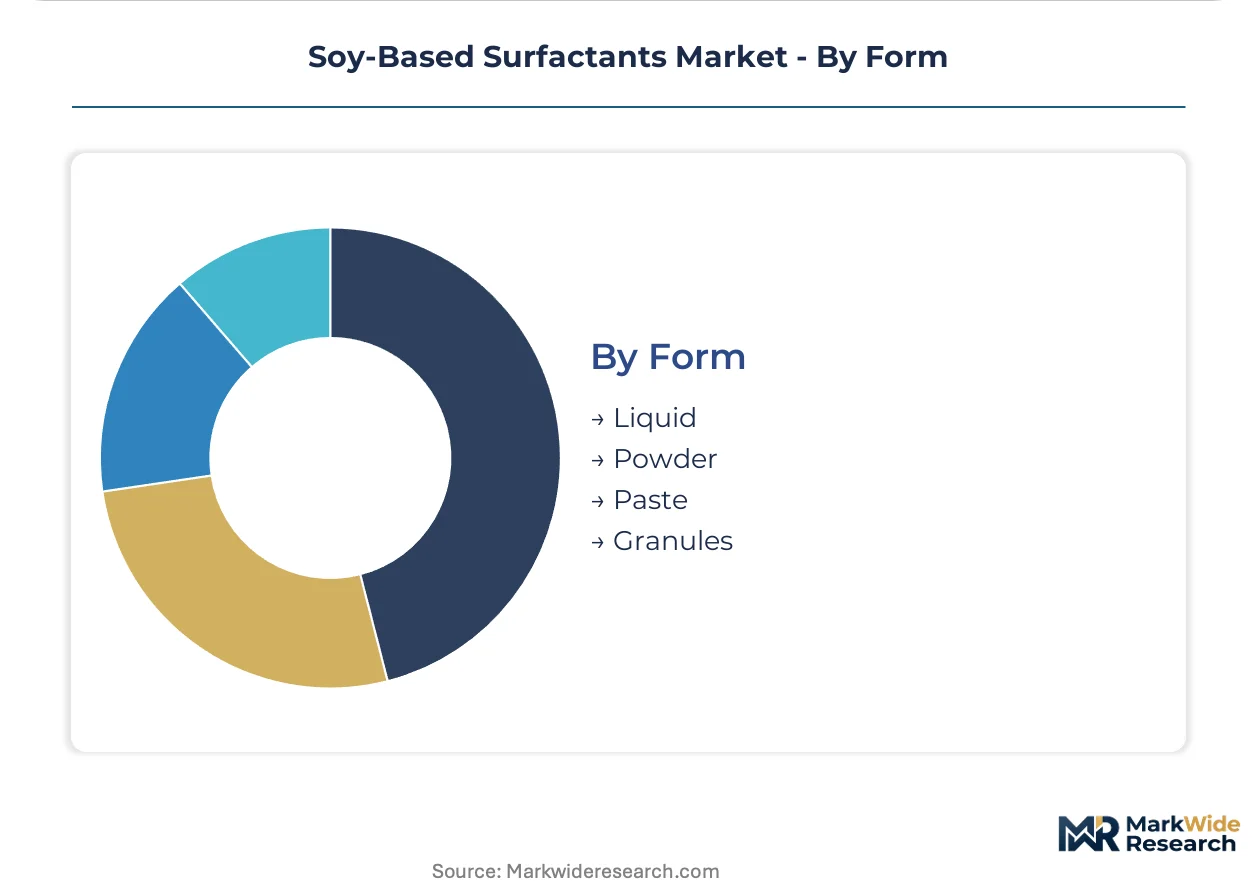
Form:
Physical form selection balances shipping economics against dissolution kinetics and handling safety in target end-use environments.
- Liquid:Easier dosing integration dominates industrial cleaning adoption where automated dilution systems require pumpable feedstocks. EPA Safer Choice program expansion into institutional cleaning categories tightens chemical disclosure thresholds for Ohio and Texas contract manufacturers serving federal procurement.
- Powder:Reduced water content enables concentrated laundry formulations where direct-to-consumer e-commerce channels bypass traditional distributor networks. Shipping cost advantages compound for cross-border transactions where weight-based freight tariffs apply.
- Paste:Intermediate water content serves specialty personal care compounders requiring controlled viscosity during processing.
- Granules:Dust-free handling properties suit agricultural adjuvant applications with outdoor mixing requirements.
Liquid forms lead installed capacity. Powder formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH Annex XVII restrictions on petrochemical surfactants anchor European demand, while EPA Safer Choice program expansion drives procurement shifts in North American institutional cleaning. Regulatory divergence across major economies is fragmenting compliance pathways and creating geographic arbitrage opportunities for certified producers.
United States
California-based personal care brands negotiate direct toll manufacturing arrangements that bypass standard distributor markups for identity-preserved soy feedstocks. EPA Safer Choice program expansion into industrial cleaning categories tightens chemical disclosure thresholds for contract manufacturers serving federal procurement. Ohio and Texas cleaning chemical blenders restructure supplier qualification protocols to maintain eligibility for institutional contracts.
Germany
Industrial cleaning manufacturers retrofit formulations to meet binding EU Green Deal decarbonization mandates, creating pull-through demand for plant-derived surfactants with verified carbon footprints. REACH Annex XVII restrictions on nonylphenol ethoxylates compress the addressable market for petrochemical alternatives. The Rhineland industrial cluster hosts concentrated alkoxylation capacity tuned to soy-derived alcohol feedstocks.
China
Domestic biodegradable detergent certification under GB standards lags behind export requirements, creating first-mover advantage for foreign producers with pre-certified manufacturing. The country's national environmental regulator enforces dual carbon goals that indirectly favor bio-based feedstocks in cleaning applications. Yangtze River Delta surfactant compounders face margin pressure from agricultural commodity swings versus stable-priced fossil alternatives.
India
BIS certification expansion for biodegradable detergents opens export channels for compliant soy surfactant producers seeking volume outlets beyond saturated European markets. The Bureau of Indian Standards mandates compulsory certification schemes that redirect procurement budgets toward bio-based alternatives. Maharashtra and Gujarat household product manufacturers retrofit lines to meet emerging compliance deadlines.
Switzerland
Swissmedic and federal chemical safety frameworks enforce ingredient disclosure standards that exceed baseline EU requirements, elevating premium positioning for enzymatically processed soy betaines. Personal care compounders adopt mild baby care formulations that exploit soy-derived amphoteric structures. Basel-area cosmetic ingredient channels concentrate demand for certified identity-preserved feedstocks with full supply chain documentation.
Soy-Based Surfactants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in soy-based surfactants, with upstream oilseed processors leveraging crushing infrastructure to secure consistent precursor streams. The middle tier comprises alkoxylation specialists and amphoteric technology developers that differentiate through HLB tuning capabilities and mildness profiles. Two strategic archetypes dominate: vertically integrated agricultural processors with captive fatty acid supplies, and specialty chemical houses with formulation partnership depth. Competitive moves concentrate on backward integration into identity-preserved soybean sourcing and continuous processing technology licensing.
Within the integrated processor tier, Archer Daniels Midland Company exemplifies upstream control over lecithin and fatty acid streams, while Stepan Company anchors North American production capabilities. Evonik Industries AG occupies a position among amphoteric technology specialists exploiting soy betaine structures. These three represent distinct competitive vectors: agricultural supply security, regional production scale, and premium personal care positioning.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| DuPont |
| The Scoular Company |
| FUJI OIL ASIA |
| Stepan Company |
| Evonik Industries AG |
| Clariant AG |
| BASF SE |
| Solvay |
| Others |
Value Network & Pricing Analysis
Alkoxylation capacity utilization in the Rhineland industrial cluster anchors price floors for soy-derived surfactants, compressing margins for smaller batch producers while rewarding continuous-process operators with scale economies in precursor sourcing and energy integration.
Pricing Analysis
Price spreads between German industrial cleaning compounders and California personal care brands reflect certification-tier differentiation, with identity-preserved soy feedstocks commanding substantial premiums over commodity-grade alternatives. Pricing stratifies across premium enzymatically-processed amphoteric grades, standard ethoxylated non-ionic intermediates, and economy sulfonated anionics for bulk detergent applications. Cost compression in the economy tier is intensifying because agricultural commodity volatility erodes contract stability against fossil-derived surfactant benchmarks. Household product manufacturers in India exhibit the highest price sensitivity due to thin formulation margins, while Swiss cosmetic compounders demonstrate minimal sensitivity given retailer-mandated ingredient disclosure requirements.
Supply Chain Analysis
The United States and Germany anchor soy surfactant production through integrated crushing and alkoxylation infrastructure, with China and India emerging as formulation hubs for regional detergent and personal care markets. Raw material flows draw from identity-preserved soybean crushing cooperatives, refined lecithin streams, and fatty acid distillates from edible oil processing. Single-source vulnerability concentrates in enzymatic transesterification catalyst supply, where specialized biocatalyst producers serve multiple surfactant manufacturers. Distribution runs through bulk chemical distributors for industrial volumes, while direct toll manufacturing arrangements bypass traditional markups for premium personal care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large personal care brands negotiating direct manufacturing arrangements, fragmenting traditional distributor relationships and compressing channel economics for mid-tier suppliers.
For Market Incumbents: Compound formulation partnership depth by embedding technical service teams with end-user R&D departments, particularly in Swiss and California cosmetic laboratories where enzymatic processing expertise commands premium positioning. Secure backward integration into identity-preserved soybean crushing through cooperative supply agreements that lock in traceability documentation for EPA Safer Choice and REACH compliance. Capacity addition in the Rhineland cluster reinforces alkoxylation scale advantages against emerging Asian competitors. For New Entrants and Emerging Players: Technical formulation support for mid-scale Indian household product manufacturers represents a service-layer gap where incumbents under-serve, creating white-space for BIS certification consulting bundled with surfactant supply. China's domestic biodegradable detergent compliance gap offers the most penetrable geography for pre-certified foreign producers with established GB-standard manufacturing. A toll-manufacturing partnership model with Maharashtra and Gujarat compounders provides the lowest-friction go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among amphoteric technology specialists with enzymatic processing capabilities and locked-in personal care formulation partnerships. Long-term viability across the analysis window favors targets with captive fatty acid supply and continuous alkoxylation technology rather than batch-dependent commodity producers. The signal to watch is REACH full substance registration completion timelines, which differentiate investable assets from stranded chemistries facing multi-year market entry delays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing | Identity-preserved soybean sourcing secures traceability premiums for EPA and REACH compliance. |
| Continuous Alkoxylation Technology Licensing | Custom HLB tuning capabilities capture specialty personal care formulation partnerships. |
| Enzymatic Processing Scale-Up | Mildness profiles from soy betaine structures command premium positioning in baby care. |
| Long-term Supply Agreement | Federal procurement eligibility under EPA Safer Choice locks in institutional cleaning volumes. |
| Joint Venture in India | BIS certification compliance opens export channels beyond saturated European markets. |
Research Methodology
The analysis maps non-ionic, anionic, cationic, and amphoteric surfactant sub-sectors, each validated through plant managers at alkoxylation facilities, procurement leads at industrial cleaning compounders, technical R&D directors in cosmetic formulation, and distribution channel partners in bulk chemical supply. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, SEC 10-K filings of integrated oilseed processors, Cefic surfactant industry reports, and EPA Safer Choice certified product listings. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs against regional production capacity disclosures.
Consistency checks validated volume and value outputs against external benchmarks including regional surfactant consumption surveys and import-export flow analysis across the projection horizon. The analytical framework modeled segmentation across product type, end-use industry, physical form, and regional regulatory cluster throughout the forecast period. CAGRs derived from curve-fitting historical volume trajectories against policy-driven substitution timelines for petrochemical alternatives, with soybean oil price volatility and REACH registration completion rates serving as key forecast sensitivity inputs.
Underlying assumptions cover sustained EU Green Deal enforcement, EPA Safer Choice program expansion, and BIS certification implementation timelines, with deviation risk concentrated in agricultural commodity price swings and enzymatic catalyst supply disruptions. Forecasts reflect these assumptions with explicit scenario weighting for regulatory acceleration or delay. Recalibration cycles align with material shifts in REACH Annex XVII amendments, EPA procurement rule changes, and major feedstock price discontinuities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Cocamide Monoethanolamine Market
Surfactants
Defoamers Market
Surfactants
Sodium Naphthalene Sulphonate Formaldehyde Market
Surfactants
Naphthalene Sulfonate Market
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Detergent Chemicals Market
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Powder Defoamers Market
Surfactants
Lauramide DEA Market
Surfactants
Global Detergents Market
Surfactants
Global Surfactants Market
Surfactants
Green Surfactants Market
Surfactants
Cetanol Market
Surfactants
Emulsion Stabilizers Market