
 Microcrystalline Wax Market | 2026-2036
Microcrystalline Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Microcrystalline Wax Market Analysis
Cosmetics is realigning microcrystalline wax procurement priorities as stick formulations and color cosmetics demand higher oil-binding grades. ExxonMobil leverages integrated petroleum refining to secure feedstock consistency across specialty wax grades. Sasol sustains synthetic wax capabilities that compete with petroleum-derived alternatives in premium personal care segments. Koster Keunen specializes in natural-origin wax blends that differentiate positioning among clean-label formulators.
Microcrystalline wax consists of saturated hydrocarbons with branched and cyclic structures, featuring finer crystal sizes than paraffin wax and melting points typically ranging from 60°C to 90°C depending on grade and oil content. Manufacturers refine heavy lubricating oil distillates through solvent dewaxing or hydrocracking to produce these amorphous waxes for applications requiring flexibility, adhesion, and moisture resistance. Hard wax grades anchor margin pools in coatings and pharmaceutical coatings where thermal stability commands premium positioning. Soft wax segments occupy growing volume in personal care emulsions as formulators seek spreadability without petrolatum alternatives. Petroleum-derived sources dominate current supply structures, though synthetic and natural categories are gaining traction among sustainability-focused buyers.
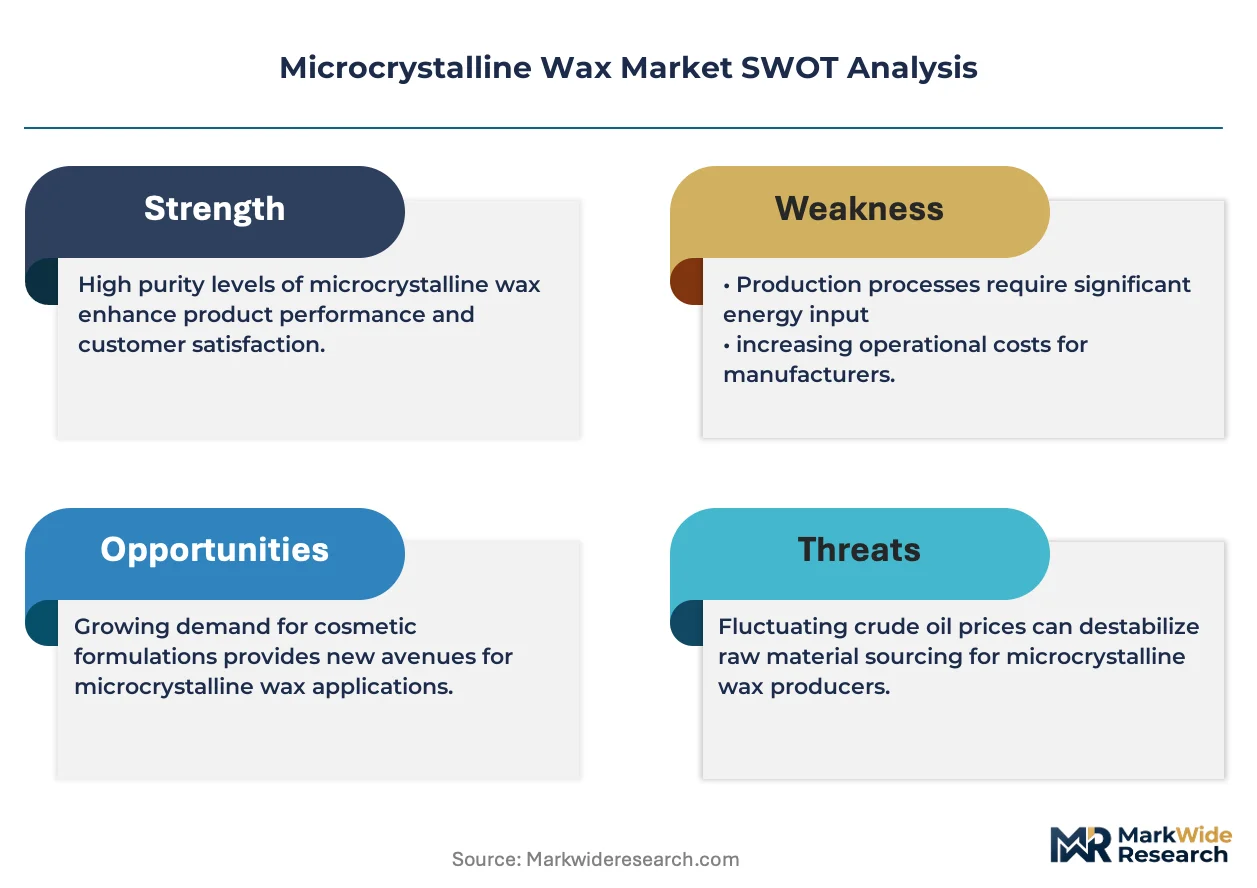
EPA regulations govern petroleum refinery emissions that affect wax production economics, while FDA 21 CFR standards define food-contact and pharmaceutical-grade specifications that constrain supplier eligibility. REACH registration requirements in Europe impose substance documentation burdens that favor established producers with dedicated compliance infrastructure. Stakeholders must monitor feedstock volatility from crude oil markets and evolving bio-based certification schemes that could redraw competitive boundaries between petroleum, synthetic, and natural source categories.
Market Dynamics
Cosmetics formulators are intensifying procurement of high oil-binding microcrystalline wax grades as stick formulations and color cosmetics displace traditional emulsion formats. This demand pivot is compressing supplier qualification timelines and elevating purity specifications beyond legacy petroleum wax standards.
Growth Catalysts
- REACH substance registration:European ECHA documentation requirements favor established producers with dedicated compliance infrastructure, consolidating qualified supplier pools for pharmaceutical and food-contact grades.
- China personal care manufacturing:Domestic brands scaling production are sourcing microcrystalline wax locally, redirecting volume from import-dependent procurement models.
- Hydrocracking refinement:Advanced hydrocracking processes yield consistent amorphous wax structures with controlled oil content, enabling tighter specification matching for coatings and adhesive applications.
Market Restraints
- Crude oil feedstock volatility:Petroleum-derived microcrystalline wax production economics track heavy lubricating oil distillate availability, exposing margin stability to upstream commodity swings.
- Supplier concentration in Gulf Coast refining:US EPA refinery emissions regulations constrain domestic wax production capacity expansion, limiting geographic diversification of supply origins.
- Natural wax substitution:Clean-label formulators are blending plant-derived wax alternatives into stick formulations, compressing addressable volume in premium personal care segments.
Strategic Opportunities
- India personal care market penetration:BIS standards alignment and CDSCO cosmetic ingredient registration create first-mover positioning for compliant petroleum wax suppliers.
- Synthetic wax technology convergence:Fischer-Tropsch synthetic processes combined with bio-based feedstock certification schemes enable premium positioning outside petroleum value chains.
- Direct-to-formulator digital channels:Specialty chemical platforms are disintermediating traditional distributor networks, compressing lead times for small-batch cosmetic wax procurement.
Industry Challenges
- REACH dossier maintenance burden:Substance data compilation and SIEF coordination require dedicated regulatory affairs staffing that mid-scale refiners struggle to resource.
- Multi-grade certification timeline compression:Simultaneous FDA food-contact, pharmaceutical USP, and cosmetic INCI approvals extend qualification cycles beyond typical procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microcrystalline Wax Market |
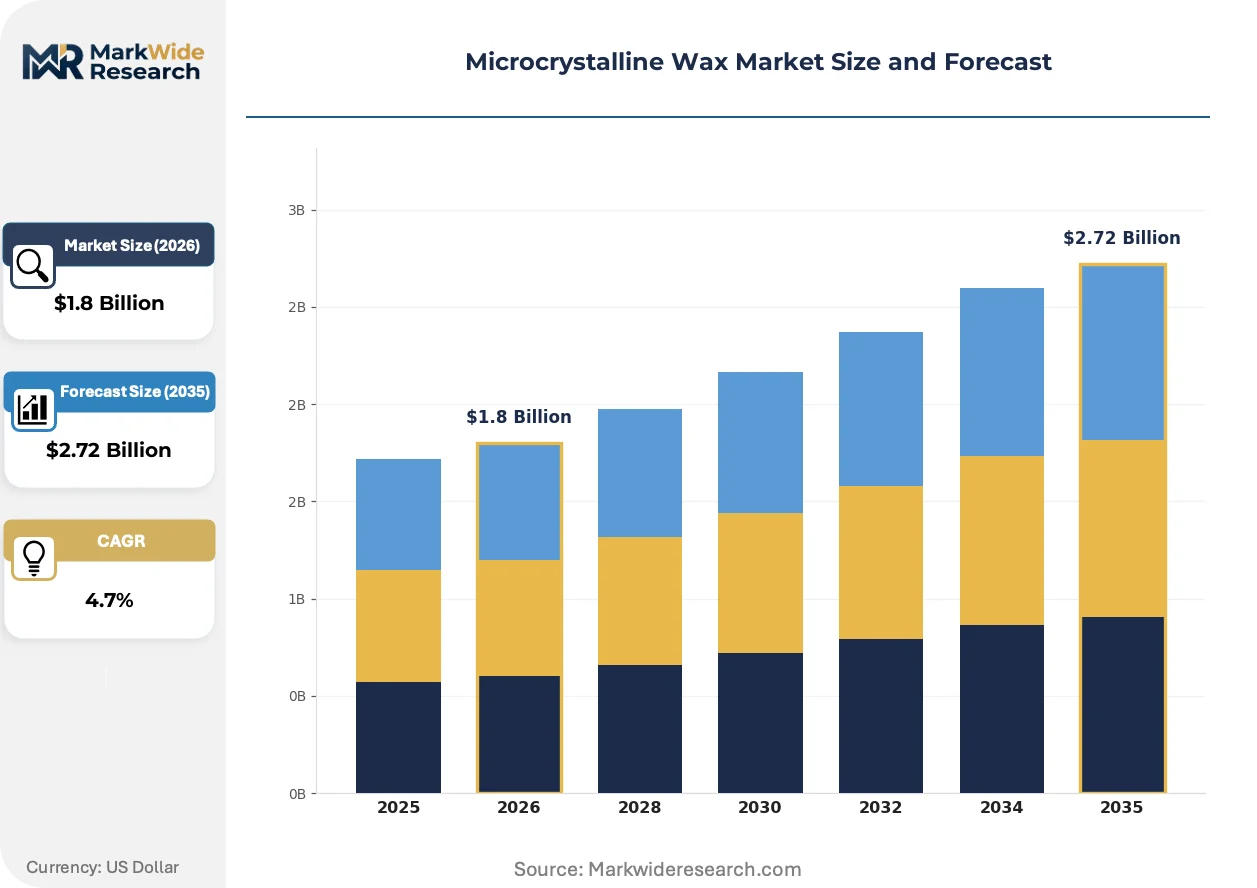
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Wax, Soft Wax, Specialty Wax, Blended Wax Application: Cosmetics, Coatings, Food, Pharmaceuticals End User: Personal Care, Packaging, Adhesives, Textiles Source: Petroleum, Synthetic, Natural, Others |
| Companies Covered | ExxonMobil, Sasol, Sinopec, Shell, Koster Keunen, Paramelt, Nippon Seiro, The International Group, Sonneborn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microcrystalline Wax Market Emerging Trajectories
Hydrorefined microcrystalline wax grades are displacing conventional solvent-dewaxed products as thermal stability specifications tighten across coatings and pharmaceutical applications. This technology pivot is elevating capital intensity requirements while compressing the viable supplier base.
Advanced hydrocracking catalyst systems are integrating real-time oil-content monitoring into continuous wax production lines. Coatings manufacturers in Germany and Japan are adopting these grades for high-temperature powder coating formulations. The technology is integrating predictive quality control that reduces batch rejection rates and shortens customer qualification protocols.
EU F-Gas Regulation phase-down schedules are indirectly pressuring petroleum refinery energy profiles, altering wax production cost structures for EU-sited manufacturers. German and Dutch refiners are investing in hydrogen co-generation to maintain operating permits. Hard wax grades for industrial coatings face margin compression as energy transition compliance costs accumulate.
Cosmetic compounders are consolidating supplier relationships around integrated wax-petrolatum-ointment base portfolios. Traditional single-product distributors are losing share to full-line specialty chemical houses in France and South Korea. This concentration is visible in procurement team restructuring at mid-scale personal care brands, where technical service integration outweighs price-only sourcing.
Microcrystalline Wax Market Segmentation
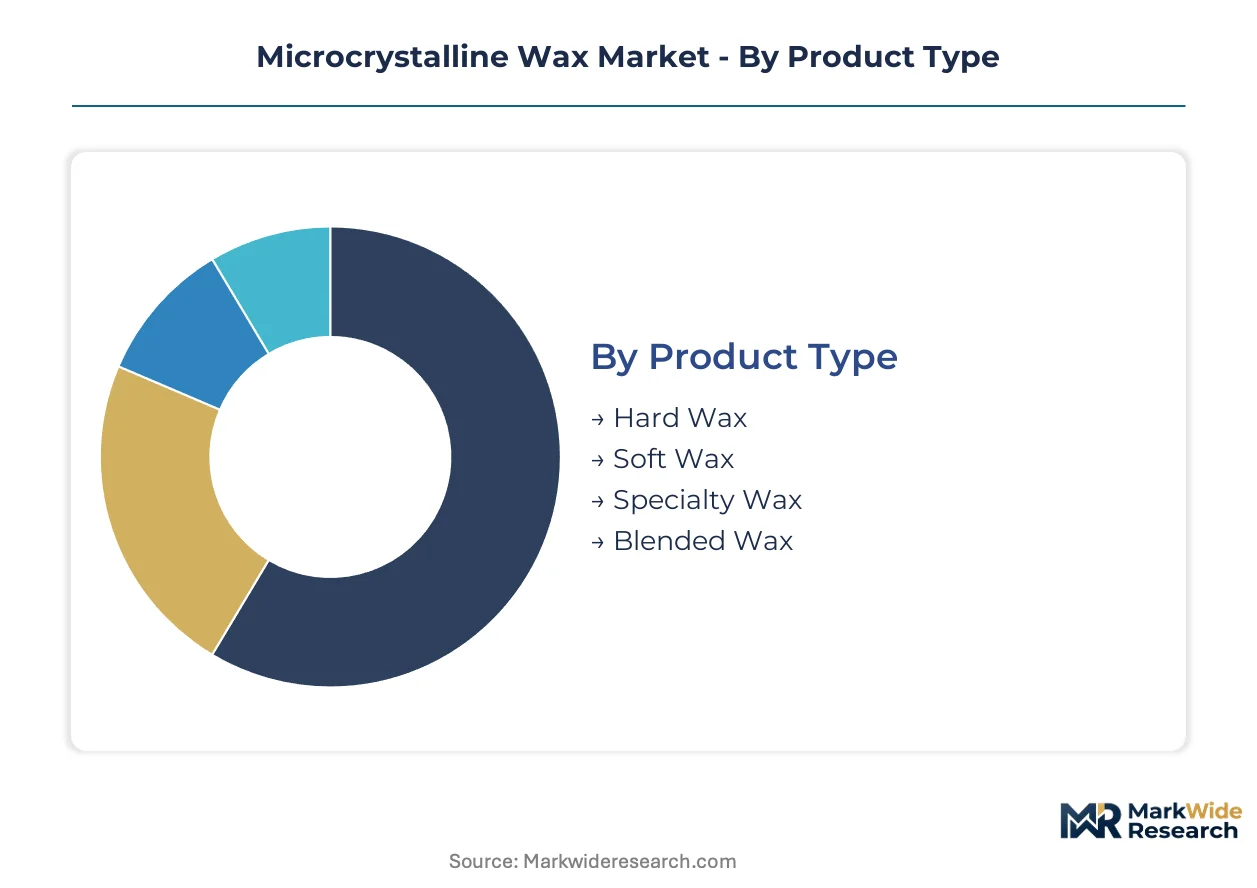
Microcrystalline wax procurement decisions hinge on crystalline structure, oil content, and thermal behavior specifications that vary sharply across end-use requirements. Formulators in cosmetics and coatings select grades based on adhesion, flexibility, and regulatory compliance thresholds rather than commodity pricing alone.
Product Type:
Refinement technology and oil-content control differentiate product tiers, with hydrocracking advancement reshaping grade availability.
- Hard Wax:High melting-point grades with dense crystalline structures anchor industrial coatings and pharmaceutical tablet coatings where thermal stability commands specification priority. Demand concentrates in German and Japanese powder coating manufacturers adopting hydrorefined grades for high-temperature process lines.
- Soft Wax:Elevated oil-content variants deliver spreadability and emulsion stability without petrolatum alternatives. Personal care formulators in South Korea and France are consolidating procurement around soft wax for stick foundations and lip products, compressing traditional paraffin substitution rates.
- Specialty Wax:Customized viscosity and penetration specifications serve niche adhesive and textile applications.
- Blended Wax:Pre-formulated combinations with natural waxes address clean-label positioning requirements.
Hard wax leads on scale; soft wax leads on momentum.
Application:
End-use specifications create divergent purity and certification requirements that fragment supplier qualification pathways.
- Cosmetics:INCI-compliant grades with controlled polycyclic aromatic hydrocarbon levels serve color cosmetics and skincare stick formulations. Domestic brands in China are scaling local procurement, redirecting volume from import-dependent supply chains.
- Pharmaceuticals:USP-grade specifications for ointment bases and tablet coatings require dedicated batch documentation. FDA 21 CFR compliance constraints limit qualified supplier pools, consolidating procurement around established refiners with dedicated regulatory infrastructure.
- Coatings:Thermal stability specifications tighten as powder coating process temperatures rise.
- Food:FDA food-contact and EFSA migration limits constrain additive migration profiles.
Cosmetics commands volume concentration; pharmaceuticals maintains the steepest expansion trajectory.
End User:
Customer technical service requirements are reshaping distribution channel structures across buyer categories.
- Personal Care:Stick formulation and emulsion stability demands drive high oil-binding grade procurement. Compounders in France and South Korea are consolidating relationships around integrated wax-petrolatum-ointment base portfolios, displacing single-product distributors.
- Adhesives:Tack and flexibility specifications in hot-melt formulations favor consistent amorphous structures.
- Packaging:Barrier coating applications for corrugated and flexible materials require moisture resistance without odor transfer.
- Textiles:Yarn lubrication and fabric finishing applications demand specific penetration and melting behavior.
Personal care dominates revenue concentration; adhesives gains share fastest.
Source:
Feedstock origin is becoming a competitive positioning axis as sustainability certification schemes mature.
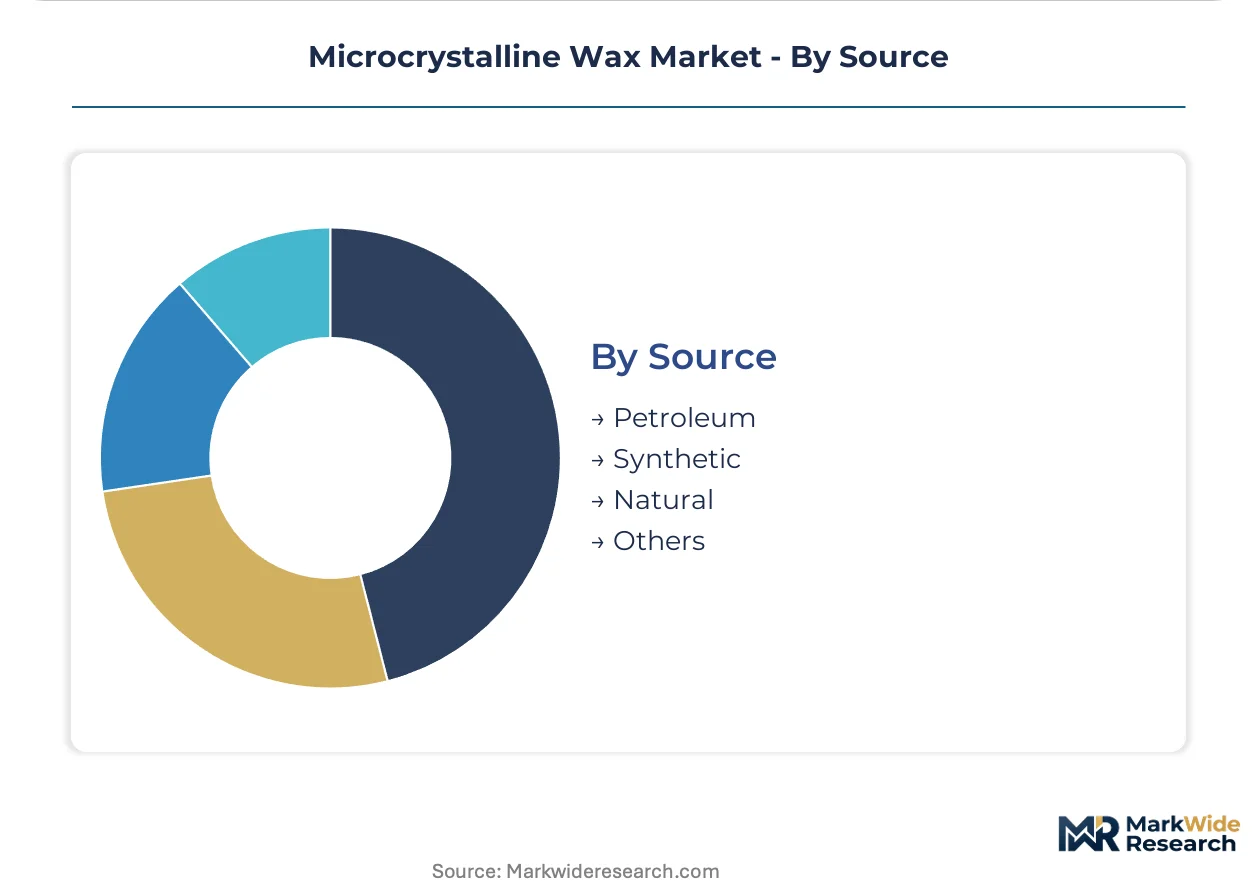
- Petroleum:Refined heavy lubricating oil distillates supply consistent amorphous structures through solvent dewaxing or hydrocracking. Gulf Coast refinery concentration and EPA emissions regulations constrain geographic diversification of petroleum-derived supply.
- Synthetic:Fischer-Tropsch processes yield controlled molecular weight distributions independent of crude oil volatility. Bio-based feedstock certification schemes enable premium positioning outside petroleum value chains.
- Natural:Plant-derived alternatives serve clean-label formulators blending stick formulations.
- Others:Emerging bio-synthetic hybrid processes remain at pilot scale.
Petroleum leads on scale; synthetic leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping microcrystalline wax production geography as compliance costs diverge across jurisdictions. European REACH dossier maintenance burdens push specialty volumes toward integrated refiners with dedicated regulatory infrastructure. Asian manufacturing scale advantages attract capacity investment from formulators seeking supply security.
United States
Gulf Coast refiners dominate petroleum-derived wax supply, serving pharmaceutical and food-contact grade demand. EPA refinery emissions regulations constrain capacity expansion, tightening qualified supplier pools. Houston-area petrochemical complexes anchor domestic production, with specialty wax output concentrated among integrated majors.
Germany
Powder coating manufacturers in the Ruhr industrial belt drive hard wax grade consumption for high-temperature process lines. EU F-Gas Regulation phase-down pressures refinery energy profiles, elevating compliance costs for Dutch and German producers. Ludwigshafen and Rotterdam-Antwerp chemical clusters sustain specialized wax refining capabilities.
China
Domestic personal care brands scaling manufacturing are redirecting microcrystalline wax procurement from import-dependent models toward local supply. NMPA cosmetic ingredient registration requirements and GB standards alignment favor established domestic refiners. Yangtze River Delta chemical parks concentrate specialty wax production capacity serving regional formulators.
India
Personal care market expansion creates first-mover positioning for compliant petroleum wax suppliers. BIS standards alignment and CDSCO cosmetic ingredient registration requirements filter market entry. Gujarat and Maharashtra industrial corridors attract specialty chemical investment targeting domestic compounding demand.
Japan
Precision coatings and electronics applications sustain demand for high-specification wax grades with controlled thermal behavior. METI industrial standards and JIS certification requirements maintain quality barriers for imported material. Chubu region chemical manufacturers specialize in ultra-pure grades for pharmaceutical and cosmetic applications.
Microcrystalline Wax Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated petroleum refiners dominating commodity-grade supply while niche formulators capture premium personal care volumes. The supplier base concentrates around Gulf Coast and Rotterdam-Antwerp refining complexes, constraining geographic diversification. Three archetypes define competitive positioning: integrated petrochemical majors with captive feedstock security, synthetic wax specialists with Fischer-Tropsch capabilities, and natural-origin blenders targeting clean-label formulators. Capacity expansion and portfolio diversification toward integrated wax-petrolatum-ointment bases represent the dominant competitive moves.
Among integrated petroleum refiners, ExxonMobil and Shell exemplify feedstock-backward positioning, leveraging heavy lubricating oil distillate access to secure specialty wax grade consistency. Sasol occupies a synthetic technology tier, with Fischer-Tropsch processes enabling molecular architecture control independent of crude oil volatility. Koster Keunen represents the natural-origin specialist archetype, serving formulators seeking plant-derived alternatives in premium personal care segments.
| Leading Market Players |
|---|
| ExxonMobil |
| Sasol |
| Sinopec |
| Shell |
| Koster Keunen |
| Paramelt |
| Nippon Seiro |
| The International Group |
| Sonneborn |
| Others |
Supply Flow & Price Mechanics
Cosmetics formulators consolidating procurement around integrated wax-petrolatum-ointment base portfolios are compressing distributor margins and forcing supply chain restructuring toward direct technical service relationships. This buyer-side concentration elevates pricing power for integrated refiners with captive feedstock security while squeezing single-product distributors out of premium personal care segments.
Pricing Analysis
Distributor margin compression runs through specialty chemical channels as direct-to-formulator digital platforms disintermediate traditional networks. Three-tier pricing structure across pharmaceutical USP, food-contact FDA, and cosmetic INCI certification levels creates steep differentiation based on batch documentation burden. Pricing pressure stems from natural wax substitution in clean-label stick formulations, with premium personal care segments least price-sensitive due to specification rigidity and qualification timeline costs.
Supply Chain Analysis
China's NMPA cosmetic ingredient registration requirements and GB standards alignment are redirecting procurement toward domestic refiners in the Yangtze River Delta. Feedstock draws from Gulf Coast heavy lubricating oil distillates, German Ruhr industrial cluster hydrocracking operations, and synthetic Fischer-Tropsch streams in South Africa. Single-source vulnerability concentrates in petroleum-derived grades tethered to crude oil volatility, with distribution running through integrated specialty chemical houses in France and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microcrystalline wax market functions as a stable compounder anchored by regulatory certification barriers that extend supplier qualification cycles and entrench incumbent positions.
For Market Incumbents: Lock in feedstock security through backward integration into heavy lubricating oil distillate access or long-term offtake agreements with Gulf Coast refiners. Deepen regulatory affairs infrastructure to manage simultaneous FDA, USP, and REACH dossier maintenance, defending against mid-scale refiners unable to resource dedicated compliance staffing. Prioritize capacity addition in China to capture domestic personal care brand procurement shifts away from import-dependent models. For New Entrants and Emerging Players: Capture white-space positioning in synthetic wax segments where Fischer-Tropsch processes enable bio-based feedstock certification outside petroleum value chains. Target India's personal care compounding demand where BIS standards alignment and CDSCO cosmetic ingredient registration create first-mover windows for compliant suppliers. Lead with digital direct-to-formulator channels that compress lead times for small-batch cosmetic wax procurement, bypassing entrenched distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with synthetic wax specialists possessing Fischer-Tropsch capabilities and bio-based certification pathways that decouple from crude oil volatility. Long-term viability favors producers with integrated regulatory infrastructure spanning pharmaceutical, food-contact, and cosmetic grade portfolios. Watch for REACH dossier maintenance burden consolidation signals as mid-scale European refiners exit or seek strategic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heavy Distillate Supply | Captive feedstock security insulates margin stability from crude oil volatility swings. |
| REACH Dossier Infrastructure Investment | Dedicated regulatory affairs staffing consolidates qualified supplier pools in Europe. |
| Synthetic Wax Capacity Buildout | Fischer-Tropsch processes enable premium positioning outside petroleum value chains. |
| Direct-to-Formulator Digital Platform Launch | Specialty chemical platforms disintermediate traditional distributor networks in cosmetics. |
| India Market Regulatory Compliance | BIS alignment and CDSCO registration create first-mover positioning for compliant entrants. |
Methodological Framework
Multiple input streams — primary interviews with refinery operations managers, cosmetics procurement leads, and coatings technical directors; secondary validation against customs trade data, SEC petroleum refiner filings, and ECHA REACH registration databases; plus specialty chemical distributor channel assessments — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates and supply-side capacity mapping.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to model growth across product type, application, and source segmentation dimensions. CAGRs were derived from trend extrapolation moderated by regulatory timeline constraints and feedstock cost sensitivity analysis, with forecast inputs incorporating hydrocracking technology adoption curves and China domestic procurement shift velocity.
Crude oil price volatility, REACH registration burden escalation, and natural wax substitution acceleration are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about regulatory compliance timeline stability and certification standard harmonization across jurisdictions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Tetrabromobisphenol a (TBBPA) Market
Specialty Chemicals
1,2 Hexanediol Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Homosalate Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market
Specialty Chemicals
Demethylase Inhibitor Market
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
Technical Aerosol Market
Specialty Chemicals
Zinc Eugenol Market