
 Tetrabutylammonium Bromide Market | 2026-2036
Tetrabutylammonium Bromide Market Size, Share, and Industry Trends Forecast 2026-2036
Tetrabutylammonium Bromide Market Analytics
Pharmaceutical sector procurement is reorganizing share away from commodity chemical buyers as peptide synthesis and active pharmaceutical intermediate workflows expand. Tokyo Chemical Industry Co., Ltd. anchors supply continuity through its Japan-based specialty chemical distribution network. Tatva Chintan Pharma Chem Ltd. dominates Indian phase-transfer catalyst manufacturing with backward-integrated bromine sourcing. Merck KGaA leverages its life sciences channel control to secure long-term research institution contracts.
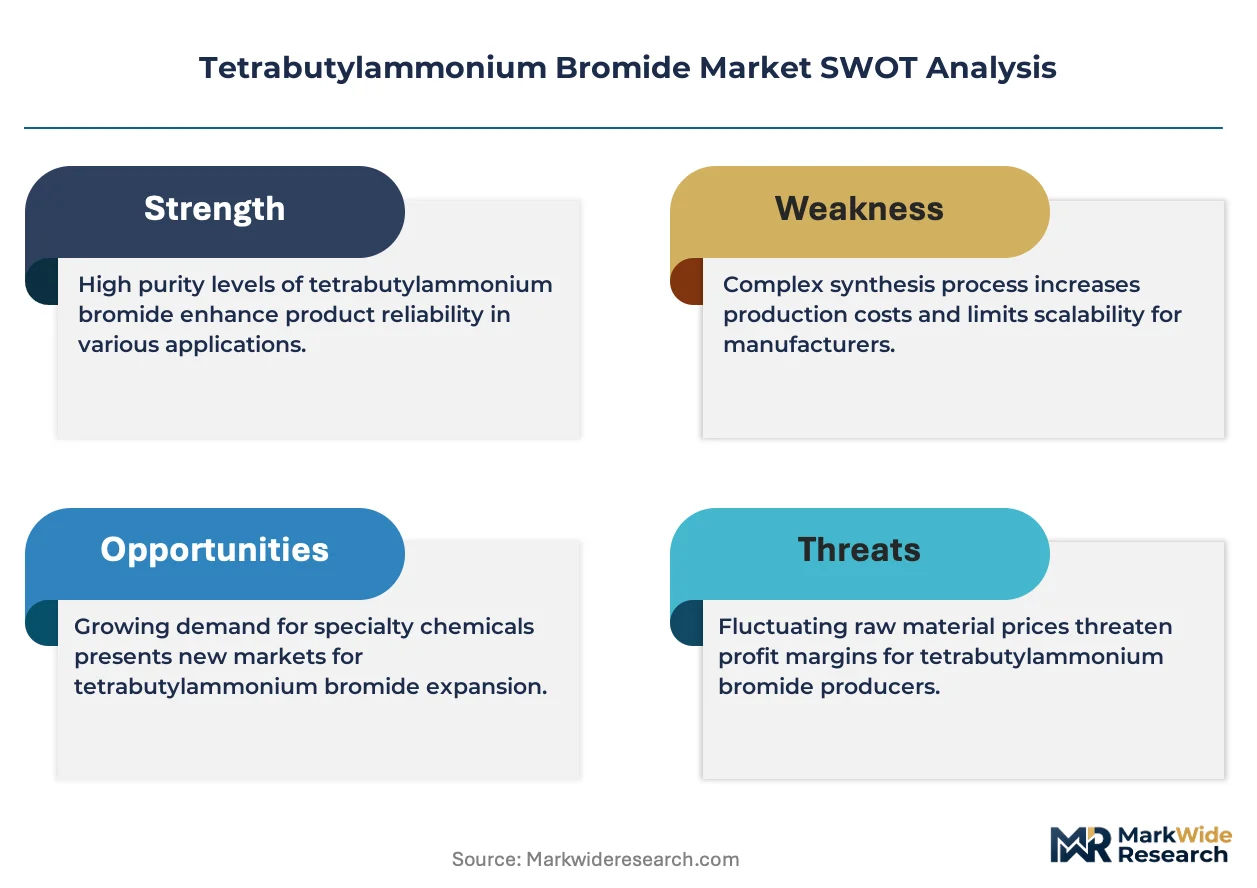
Tetrabutylammonium bromide functions as a quaternary ammonium salt with the molecular formula C16H36BrN, typically supplied at 99% purity for phase-transfer catalysis in aqueous-organic biphasic reaction systems. The powder and crystalline grades command premium positioning due to stringent moisture content specifications below 0.5% required for moisture-sensitive organic synthesis. Application demand within catalysis and organic reactions leads volume absorption, while extraction represents a narrower but higher-margin niche tied to rare earth separation protocols. Purity grade stratification concentrates margin pools at the 99% segment, where pharmaceutical sector qualification requirements sustain pricing power against technical grade alternatives.
EPA oversight under the Toxic Substances Control Act shapes import and manufacturing compliance thresholds for quaternary ammonium salts in the United States, while REACH registration requirements in Europe restrict non-compliant suppliers from accessing downstream chemical formulation markets. China's SAMR enforces GB standards for industrial chemical purity disclosure, affecting export competitiveness of domestic producers. Stakeholders must monitor evolving pharmaceutical-grade certification requirements across multiple jurisdictions to sustain market access as buyer qualification protocols tighten.
Market Dynamics
Pharmaceutical-grade phase-transfer catalysis is tightening purity specifications across the supply base, forcing specialty chemical manufacturers to requalify production lines for sub-0.5% moisture content thresholds.
Growth Catalysts
- Peptide synthesis expansion:Contract development and manufacturing organizations are scaling solid-phase peptide workflows that require quaternary ammonium salts for N-terminal protection chemistry.
- REACH registration completion:European downstream formulators now exclude non-registered suppliers from approved vendor lists, consolidating volume toward compliant producers.
- Rare earth extraction protocols:Hydrometallurgical separation facilities in China are standardizing tetrabutylammonium bromide for lanthanide group partitioning.
Market Restraints
- Bromine supply concentration:Dead Sea and Arkansas brine operations control over 70% of elemental bromine, exposing catalyst manufacturers to input price volatility.
- Substitution by phosphonium salts:Triphenylmethylphosphonium bromide offers superior thermal stability in high-temperature organic synthesis above 150°C.
- EPA TSCA Section 5 notification:New chemical entity reviews delay introduction of modified quaternary ammonium structures by 12-18 months.
Strategic Opportunities
- India CDMO penetration:Domestic pharmaceutical intermediates manufacturing under PLI scheme incentives is creating captive catalyst demand.
- Continuous flow chemistry:Microreactor systems enable real-time phase-transfer catalysis with 40% solvent reduction versus batch processing.
- GB standard harmonization:China's SAMR is aligning industrial chemical disclosure requirements with REACH technical dossiers, easing export qualification.
Industry Challenges
- Analytical chemist scarcity:ICP-MS and Karl Fischer titration expertise for sub-ppm impurity detection commands 35% salary premiums.
- Multi-jurisdiction certification timelines:Simultaneous USP, EP, and ChP qualification requires 18-24 month stability studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetrabutylammonium Bromide Market |
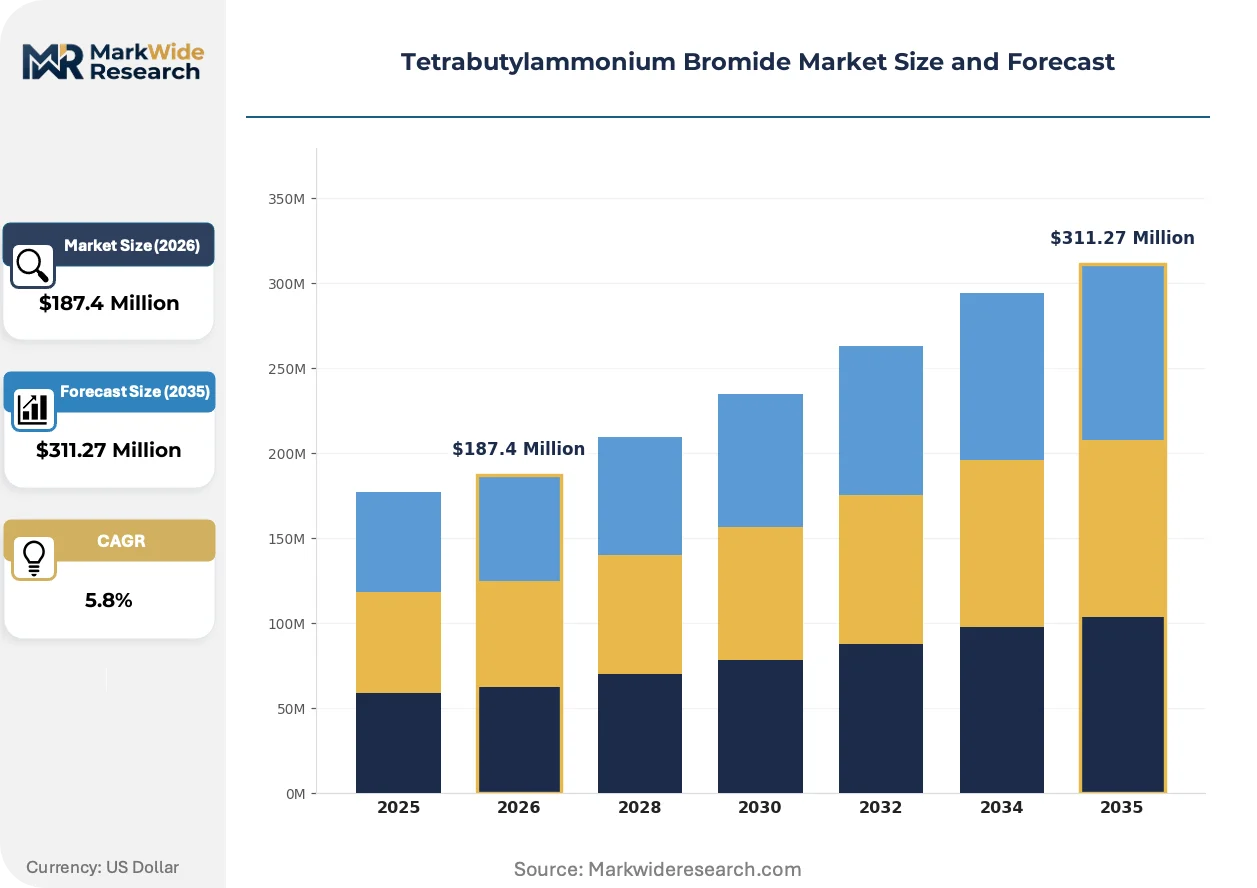
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Solution Application: Synthesis, Organic Reactions, Catalysis, Extraction End User: Chemical Industry, Pharmaceutical Sector, Research Institutions, Academic Labs Purity Grade: 99%, 98%, 97%, Technical Grade |
| Companies Covered | Tokyo Chemical Industry Co., Ltd., Tatva Chintan Pharma Chem Ltd., Merck KGaA, QuZhou Mingfeng Chemical, Shandong Tongcheng Medicine, Thermo Fisher Scientific, Alfa Aesar, Rudong Yongtai Chemical, SACHEM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetrabutylammonium Bromide Market Evolving Landscape
Continuous processing technologies and regulatory data harmonization are compressing the traditional batch-manufacturing model while elevating analytical precision requirements.
Membrane-based phase-transfer systems are displacing conventional mechanical stirring in biphasic reaction environments. Fine chemical manufacturers in Germany and Switzerland are retrofitting existing stirred-tank reactors with hollow-fiber membrane modules. This hardware shift is displacing volume demand for excess catalyst loading by enabling precise interfacial contact control.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are redirecting fluorination chemistry toward quaternary ammonium-mediated halogen exchange. European agrochemical formulators must reformulate existing active ingredient synthesis routes by 2026. The phase-transfer catalyst segment is absorbing this regulatory displacement as specialty manufacturers expand technical service teams for route redesign.
Research institutions are consolidating chemical procurement through centralized e-procurement platforms with embedded purity certification verification. University buying consortia in the United States now require lot-specific COA upload before purchase order release. This channel transformation concentrates volume toward distributors with integrated quality documentation systems.
Tetrabutylammonium Bromide Market Segmentation
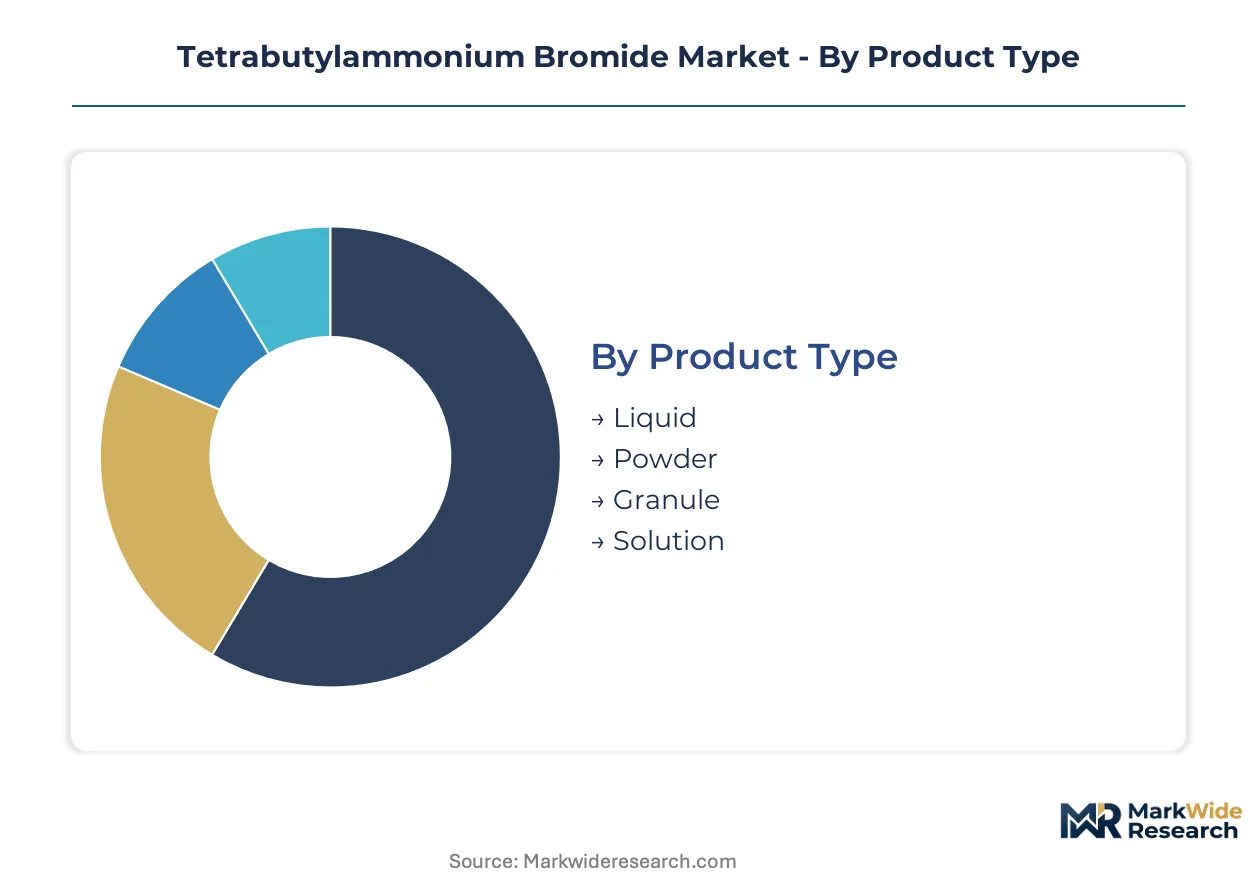
Purity grade stratification concentrates margin pools at the premium tier, while product form selection dictates handling protocols across pharmaceutical and industrial workflows. Application-driven demand patterns reveal divergent growth trajectories between commodity chemical buyers and specialized synthesis contractors.
Product Type:
Substitution pressure from membrane-based phase-transfer systems weighs most heavily on liquid and solution formats, where precise dosing control becomes less critical than in solid-phase workflows requiring exact stoichiometry.
- Powder:Crystalline solid with typical particle size distribution of 100-200 mesh enables precise gravimetric dosing in solid-phase peptide synthesis. Pharmaceutical CDMOs in India and Switzerland specify powder grades for moisture-sensitive N-terminal protection chemistry where sub-0.5% water content prevents hydrolytic degradation.
- Crystalline:Recrystallized material meeting ACS reagent specifications commands premium positioning for analytical reference standards and GMP-validated production. German fine chemical manufacturers anchor procurement of crystalline grades for continuous flow microreactor installations requiring dissolution kinetics control.
- Liquid:Aqueous or solvent-based preparations simplify handling in high-throughput screening operations where manual weighing creates throughput bottlenecks. Academic labs in the United States favor liquid formats for undergraduate organic chemistry instruction.
- Granule:Agglomerated form reduces dust generation during bulk handling in hydrometallurgical extraction facilities. Chinese rare earth separation plants specify granule grades for lanthanide group partitioning protocols.
- Solution:Pre-dissolved formulations in polar aprotic solvents eliminate dissolution steps in automated synthesis platforms. Research institutions deploying robotic liquid handlers prefer solution formats for library generation workflows.
Powder anchors the volume base while crystalline gains share at the steepest rate.
Application:
Cost tier stratification separates commodity chemical buyers pursuing yield optimization from premium-priced extraction protocols where catalyst loss tolerances approach zero.
- Catalysis:Phase-transfer catalysis in biphasic aqueous-organic systems enables nucleophilic substitution reactions with inorganic salts in non-polar solvents. Peptide synthesis contractors scaling solid-phase workflows drive concentration of catalysis demand in India and Switzerland.
- Extraction:Hydrometallurgical separation of lanthanide groups leverages tetrabutylammonium bromide for selective rare earth partitioning. Chinese separation facilities standardizing extraction protocols create captive demand for technical grade material with relaxed organic impurity specifications.
- Synthesis:N-alkylation and ether formation reactions in active pharmaceutical intermediate production consume catalyst at stoichiometric ratios. European agrochemical formulators redirecting fluorination chemistry from PFAS-mediated routes expand synthesis application volume.
- Organic Reactions:General-purpose substitution and elimination chemistry in academic and industrial R&D settings. Research institutions consolidating procurement through e-procurement platforms concentrate organic reactions demand toward distributors with integrated quality documentation.
Catalysis commands the dominant revenue share while extraction climbs the fastest.
End User:
Customer type differentiation separates price-sensitive commodity buyers from qualification-intensive pharmaceutical sector procurement with multi-jurisdiction certification requirements.
- Pharmaceutical Sector:GMP-validated active pharmaceutical intermediate manufacturers require USP, EP, and ChP qualification with 18-24 month stability studies. Contract development organizations scaling peptide therapeutics production anchor pharmaceutical sector volume concentration.
- Chemical Industry:Commodity chemical manufacturers and agrochemical formulators prioritize yield optimization over analytical certification depth. European agrochemical producers reformulating PFAS-dependent synthesis routes expand chemical industry demand.
- Research Institutions:University consortia and national laboratories require lot-specific certificates of analysis with sub-ppm impurity disclosure. United States university buying consortia now mandate COA upload before purchase order release.
- Academic Labs:Individual research groups with lower volume requirements and reduced qualification stringency. Liquid and solution formats dominate academic lab procurement due to handling convenience in teaching environments.
Pharmaceutical Sector anchors the volume base while Research Institutions gain share at the steepest rate.
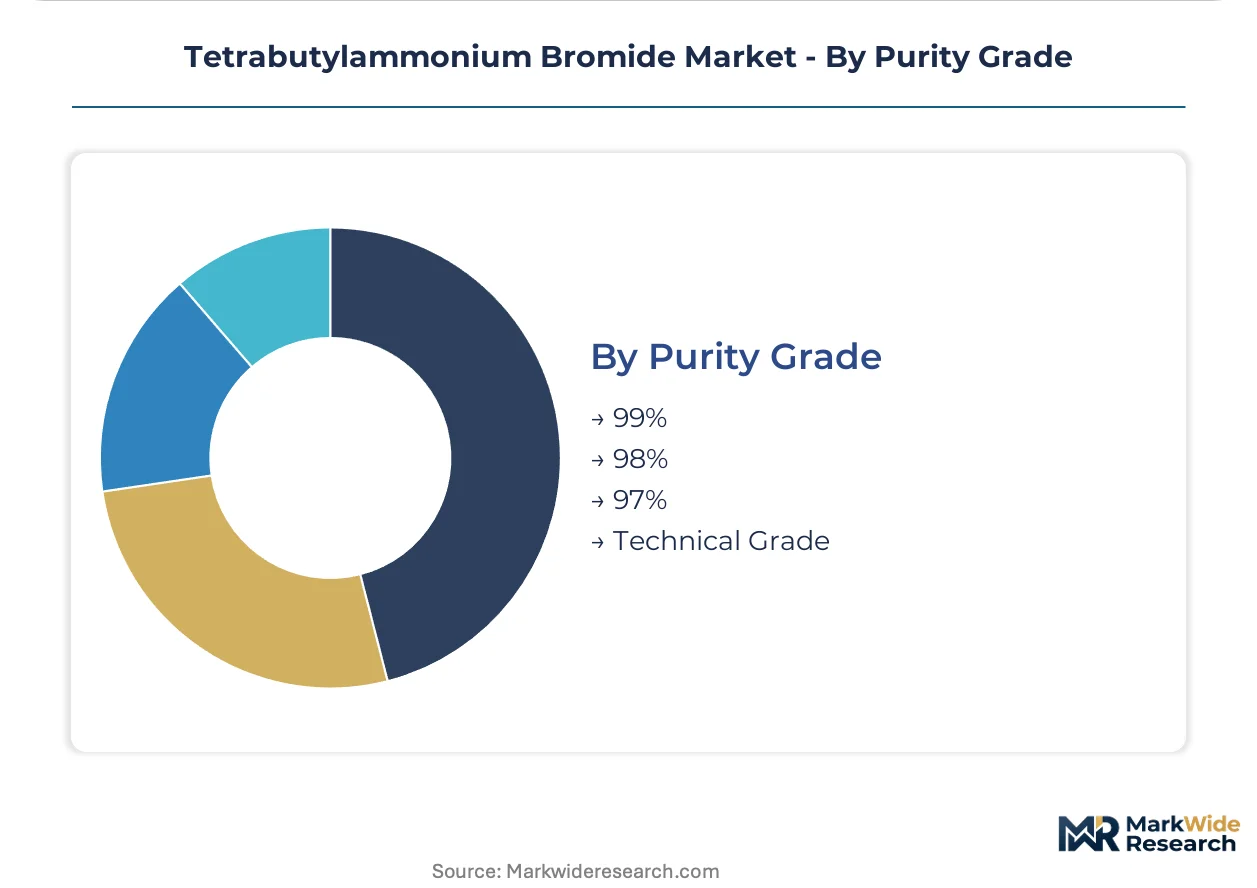
Purity Grade:
Margin concentration stratifies sharply at the 99% tier, where pharmaceutical qualification requirements sustain pricing power against technical grade alternatives serving commodity extraction applications.
- 99%:Pharmaceutical-grade material with comprehensive impurity profiling including residual solvents, heavy metals, and organic byproducts. GMP-validated manufacturers in India and Switzerland specify 99% purity for regulatory submission batches.
- 98%:Technical grade with controlled major impurities for industrial synthesis where trace contaminants do not compromise reaction selectivity. Agrochemical intermediate producers in China and Germany standardize on 98% grades for cost optimization.
- 97%:Standard industrial grade for high-volume applications with relaxed analytical requirements. Rare earth extraction facilities in China absorb 97% material for hydrometallurgical separation where catalyst loss to aqueous raffinate streams is process-inherent.
- Technical Grade:Unspecified purity range for non-critical applications including waste treatment and general laboratory reagent use. Academic teaching labs and preliminary screening operations represent primary technical grade consumption.
99% purity anchors the volume base while 98% gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian manufacturers export tetrabutylammonium bromide to European pharmaceutical formulators under tightening REACH registration requirements. This trade corridor concentrates value capture in compliant producers while excluding non-registered competitors from approved vendor lists.
China
Rare earth extraction facilities in Jiangxi and Inner Mongolia standardize tetrabutylammonium bromide for lanthanide group partitioning. SAMR enforces GB standards for industrial chemical purity disclosure, affecting export competitiveness of domestic producers. The Yangtze River Delta anchors specialty chemical manufacturing clusters serving both domestic pharmaceutical intermediate production and hydrometallurgical separation demand.
India
Contract development and manufacturing organizations scaling peptide therapeutics drive catalyst consumption in Gujarat and Maharashtra. The PLI scheme incentivizes domestic pharmaceutical intermediates manufacturing, creating captive demand for phase-transfer catalysts. Tatva Chintan Pharma Chem Ltd. leverages backward-integrated bromine sourcing from Gujarat salt works to serve this expanding customer base.
Germany
Fine chemical manufacturers in Bavaria and North Rhine-Westphalia retrofit stirred-tank reactors with hollow-fiber membrane modules for continuous flow applications. ECHA REACH registration requirements exclude non-compliant suppliers from downstream chemical formulation markets. The Frankfurt-Rhine-Main cluster concentrates demand from agrochemical formulators reformulating PFAS-dependent synthesis routes.
United States
Research institutions consolidating procurement through university buying consortia now mandate lot-specific COA upload before purchase order release. EPA oversight under the Toxic Substances Control Act shapes import and manufacturing compliance thresholds for quaternary ammonium salts. The Boston-Cambridge biotech corridor anchors pharmaceutical sector demand for GMP-validated material.
Switzerland
Continuous flow microreactor installations in Basel and Zurich require crystalline grades with controlled dissolution kinetics. Swissmedic pharmaceutical-grade certification requirements sustain pricing power against technical grade alternatives. The Lake Geneva region concentrates peptide synthesis contractors scaling solid-phase workflows for N-terminal protection chemistry.
Tetrabutylammonium Bromide Market Competitive Landscape
Listed leaders compete with private specialists across regulatory qualification depth, with public companies leveraging capital market access for multi-jurisdiction certification timelines while private operators capture niche volume through regional distribution control. The vendor base stratifies into three tiers: diversified life sciences conglomerates with channel control, integrated specialty manufacturers with captive raw material sourcing, and regional distributors with quality documentation systems. Strategic moves concentrate on REACH registration completion for European market access and backward integration into bromine supply chains to defend margin positions against input price volatility.
Among Japan-based specialty chemical distributors, Tokyo Chemical Industry Co., Ltd. anchors supply continuity through its domestic distribution network. German diversified life sciences conglomerates exemplify channel control strategies, with Merck KGaA securing long-term research institution contracts through integrated quality documentation systems. Indian integrated manufacturers occupy positions defined by backward-integrated bromine sourcing, with Tatva Chintan Pharma Chem Ltd. representing this archetype in phase-transfer catalyst production.
| Leading Market Players |
|---|
| Tokyo Chemical Industry Co., Ltd. |
| Tatva Chintan Pharma Chem Ltd. |
| Merck KGaA |
| QuZhou Mingfeng Chemical |
| Shandong Tongcheng Medicine |
| Thermo Fisher Scientific |
| Alfa Aesar |
| Rudong Yongtai Chemical |
| SACHEM |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles at European pharmaceutical formulators concentrate purchasing power toward REACH-registered suppliers while compressing margin capture for non-compliant producers. This lead-time discipline ties directly to bromine sourcing economics and certificate-of-analysis verification burdens.
Pricing Analysis
Batch-processing versus continuous-flow technology-generation pricing gaps separate crystalline grades commanding dissolution-kinetics premiums from powder grades serving commodity peptide synthesis. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade levels anchors the market, with USP/EP/ChP certification depth and moisture-content thresholds as primary differentiation drivers. Pricing pressure stems from membrane-based phase-transfer systems displacing excess catalyst loading in German and Swiss retrofit installations. Academic labs exhibit highest price sensitivity due to liquid-format convenience preferences, while GMP-validated CDMOs absorb premium positioning for 99% purity with sub-0.5% moisture specifications.
Supply Chain Analysis
Dead Sea and Arkansas brine chokepoints tether elemental bromine availability to Israeli and American extraction economics, exposing catalyst manufacturers to input price volatility. Manufacturing concentrates in China, India, and Germany, with Jiangxi rare earth separation facilities and Gujarat pharmaceutical intermediate clusters drawing from concentrated bromine feedstock. Raw material dependencies center on elemental bromine, quaternary ammonium precursors, and polar aprotic solvents. Single-source vulnerability from Dead Sea Works and Albemarle Corporation operations constitutes primary structural risk. Distribution runs through specialty chemical distributors with integrated quality documentation systems serving research institution consortia and CDMO procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peptide synthesis workflow expansion represents an early-cycle adoption tailwind, with solid-phase manufacturing scaling across Indian and Swiss contract development organizations driving phase-transfer catalyst penetration ahead of historical baselines.
For Market Incumbents: Compound backward integration into bromine supply chains to defend margin positions against Dead Sea and Arkansas concentration risk. Prioritize REACH registration completion and USP/EP/ChP stability study investment to exclude non-compliant competitors from European pharmaceutical formulator approved vendor lists. Phosphonium salt substitution in high-temperature synthesis above 150°C threatens quaternary ammonium positioning. For New Entrants and Emerging Players: Technical service gaps in PFAS-mediated route redesign for European agrochemical formulators create white-space opportunity. Target membrane retrofit consulting and continuous-flow microreactor catalyst optimization as under-served service layers. Penetrable entry points concentrate in Indian CDMO catalyst supply under PLI scheme incentives, with analytical certification bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life sciences conglomerates with non-core phase-transfer catalyst portfolios. Long-term viability frames around 5-10 year peptide therapeutics manufacturing expansion and rare earth extraction protocol standardization. Acquisition archetypes include regional distributors with integrated COA verification systems. Watch membrane-based phase-transfer system adoption rates as inflection indicator for traditional catalyst volume displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Sourcing | Gujarat salt works and Dead Sea brine operations anchor input cost control for Indian and Israeli manufacturers. |
| REACH Registration Completion | ECHA compliance excludes non-registered suppliers from European downstream chemical formulation markets. |
| Continuous Flow Microreactor Installation | German and Swiss fine chemical manufacturers retrofit stirred-tank reactors with hollow-fiber membrane modules. |
| Multi-Jurisdiction Certification Investment | USP, EP, and ChP qualification with 18-24 month stability studies secures pharmaceutical sector access. |
| Technical Service Team Expansion | European agrochemical formulators require route redesign support for PFAS-dependent synthesis reformulation. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with specialty chemical plant managers, pharmaceutical procurement leads at CDMOs, distribution channel partners, and technical R&D directors; and secondary validation through customs/trade data, ECHA REACH registration databases, SEC 10-K filings, and GB standard disclosure records. Bottom-up and top-down triangulation cross-validated volume estimates against bromine consumption patterns and catalyst loading ratios in peptide synthesis workflows.
Across the analysis window, the forecasting framework modeled segmentation dimensions including purity grade tier, end-use application, product form specification, and regional production hub concentration. CAGRs derived from trajectory analysis of pharmaceutical intermediate manufacturing scaling and rare earth extraction facility standardization. Industry-specific inputs incorporated PLI scheme incentive disbursement patterns and membrane-based phase-transfer system retrofit adoption curves.
Forecasts assume regulatory continuity in REACH, EPA TSCA, and SAMR GB standard regimes; material policy shifts would require re-modeling. Specific risk factors include bromine supply disruption from Dead Sea or Arkansas operations, phosphonium salt substitution acceleration, and analytical chemist scarcity impacting sub-ppm impurity detection capacity. Revision becomes warranted when membrane-based system adoption crosses threshold penetration in German and Swiss fine chemical manufacturing clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Naphthalene Sulfonate Market
Surfactants
Anionic Surfactants Market
Surfactants
Cocomonoethanolamide (CMEA) Market
Surfactants
Sodium Lauryl Sulphate Market
Surfactants
Detergent Grade Zeolite Market
Surfactants
Amphoteric Emulsifier Market
Surfactants
Dispersant Market
Surfactants
Global Rhamnolipid Market
Surfactants
Acrylamide Tertiary-Butyl Sulfonic Acid (ATBS) Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Polyoxyethylene Sorbitan Tristearate Market
Surfactants
Benzyl Trimethyl Ammonium Chloride Market
Surfactants
Specialty Surfactants Market
Surfactants
Sulfate Free Body Wash Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Cationic Surfactants Market