
 Chlorooctane Market | 2026-2036
Chlorooctane Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorooctane Market Analysis
China's Jiangsu province is narrowing the cost gap with European chlorooctane output through integrated chlor-alkali infrastructure. CABB Group GmbH leverages backward integration into chlorine feedstock to sustain margin stability across specialty chlorinated solvents. TCI (Shanghai) Development Co. Ltd. anchors regional distribution networks for laboratory-grade chlorooctane in East Asia. Neogen Chemical Limited differentiates through custom synthesis capabilities for pharmaceutical intermediates requiring halogenation precision.
Chlorooctane is a C8 chlorinated alkane with molecular formula C8H17Cl, typically produced via free-radical chlorination of n-octane or hydrochlorination of octene, yielding a colorless liquid with boiling point near 180°C that serves as a reactive intermediate in nucleophilic substitution reactions for surfactant and agrochemical synthesis. Specialty Chemicals occupies the dominant value share as pharmaceutical and agrochemical manufacturers specify high-purity grades for active ingredient synthesis, while Intermediates represents the fastest-expanding category as contract manufacturers in India and China scale halogenation capacity for export markets. Drum packaging controls the pharmaceutical channel where batch traceability requirements favor unitized handling, though Bulk Containers is displacing smaller formats among agrochemical formulators seeking freight optimization.
EPA hazardous air pollutant standards under the Clean Air Act constrain chlorination facility emissions in the United States, while REACH registration requirements in Europe mandate toxicological dossiers for chloroalkane imports above one tonne annually. China's MEE enforces volatile organic compound emission limits that favor closed-loop chlorination systems in Shandong and Jiangsu production zones. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could redirect fluorination demand toward chlorinated alternatives in electronics cleaning applications.
Market Dynamics
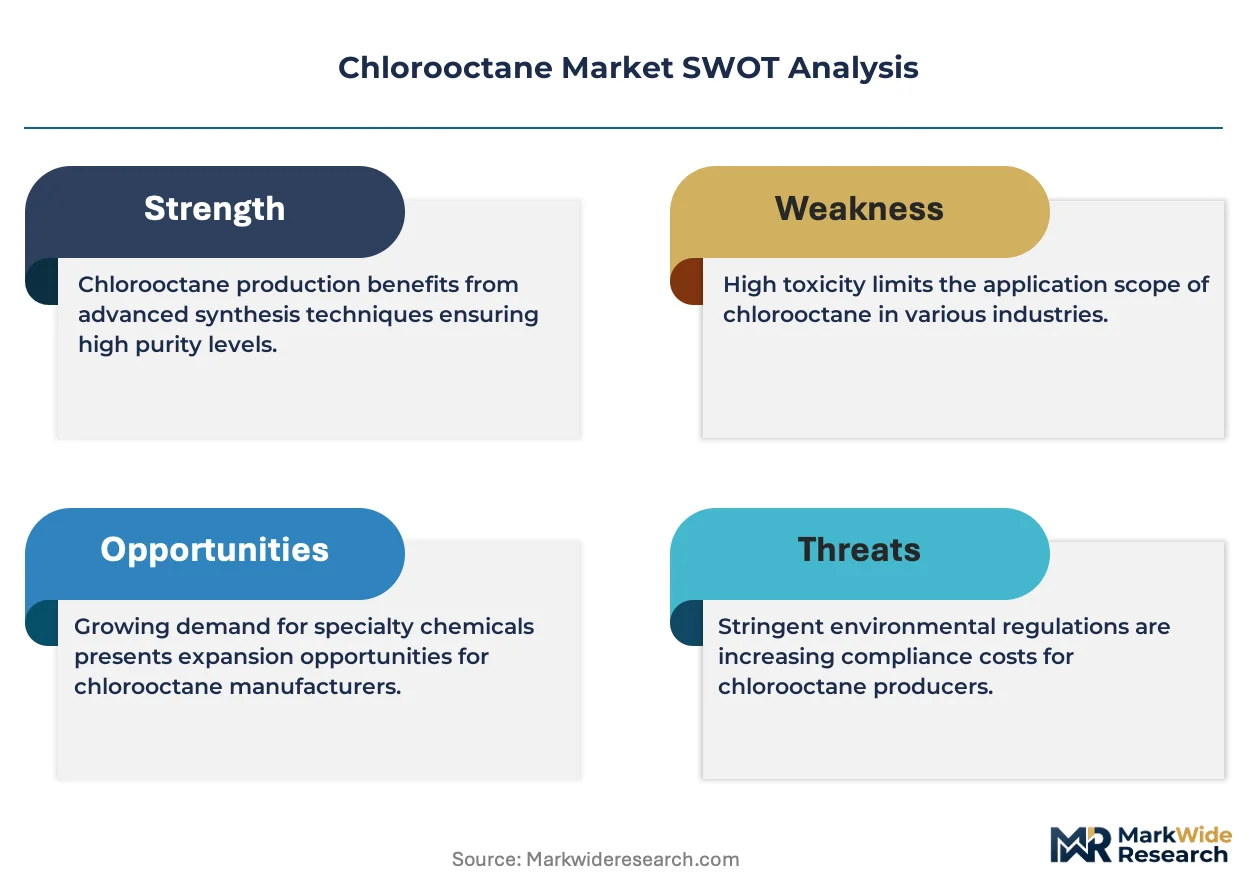
REACH registration dossiers and EPA hazardous air pollutant standards are forcing specialty chemical manufacturers to reengineer chlorination process chemistry, compressing the viable supplier base while elevating capital requirements for compliant production.
Growth Catalysts
- Pharmaceutical intermediate specification:Agrochemical and drug manufacturers in India and China are scaling halogenation capacity to serve export demand for nucleophilic substitution precursors.
- REACH compliance acceleration:European formulators are consolidating supplier relationships around registered chloroalkane sources, favoring established specialty chemical producers with completed toxicological dossiers.
- Closed-loop chlorination systems:China's MEE volatile organic compound emission limits are retrofitting Shandong and Jiangsu production zones with recovery infrastructure that reduces feedstock waste.
Market Restraints
- Chlorine feedstock volatility:Electrolytic caustic soda co-production economics create input cost instability that compresses margin predictability for non-integrated chlorooctane manufacturers.
- Jiangsu production concentration:Overreliance on Yangtze River Delta chemical clusters exposes supply continuity to regional environmental enforcement actions and seasonal river transport restrictions.
- Fluorinated solvent substitution:Per- and polyfluoroalkyl substance restrictions in electronics cleaning applications are redirecting some demand toward hydrofluoroether alternatives rather than chlorinated alkane chemistry.
Strategic Opportunities
- Custom synthesis services:Pharmaceutical contract manufacturers in India are expanding halogenation precision capabilities to capture high-margin active ingredient intermediate production from Western innovators.
- Bulk container freight optimization:Agrochemical formulators in Brazil and Australia are displacing drum packaging with ISO tank configurations that reduce per-unit logistics costs for high-volume surfactant precursors.
- Dual carbon alignment:China's national carbon neutrality mandates are creating preferential permitting pathways for chlor-alkali integrated facilities with carbon capture retrofits.
Industry Challenges
- Halogenation process engineering expertise:Free-radical chlorination and hydrochlorination optimization requires specialized reaction control knowledge that is concentrated among aging technical workforces in Germany and Japan.
- Batch traceability system integration:Pharmaceutical channel drum packaging demands unit-level serialization that conflicts with legacy inventory management infrastructure at mid-scale specialty chemical distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorooctane Market |
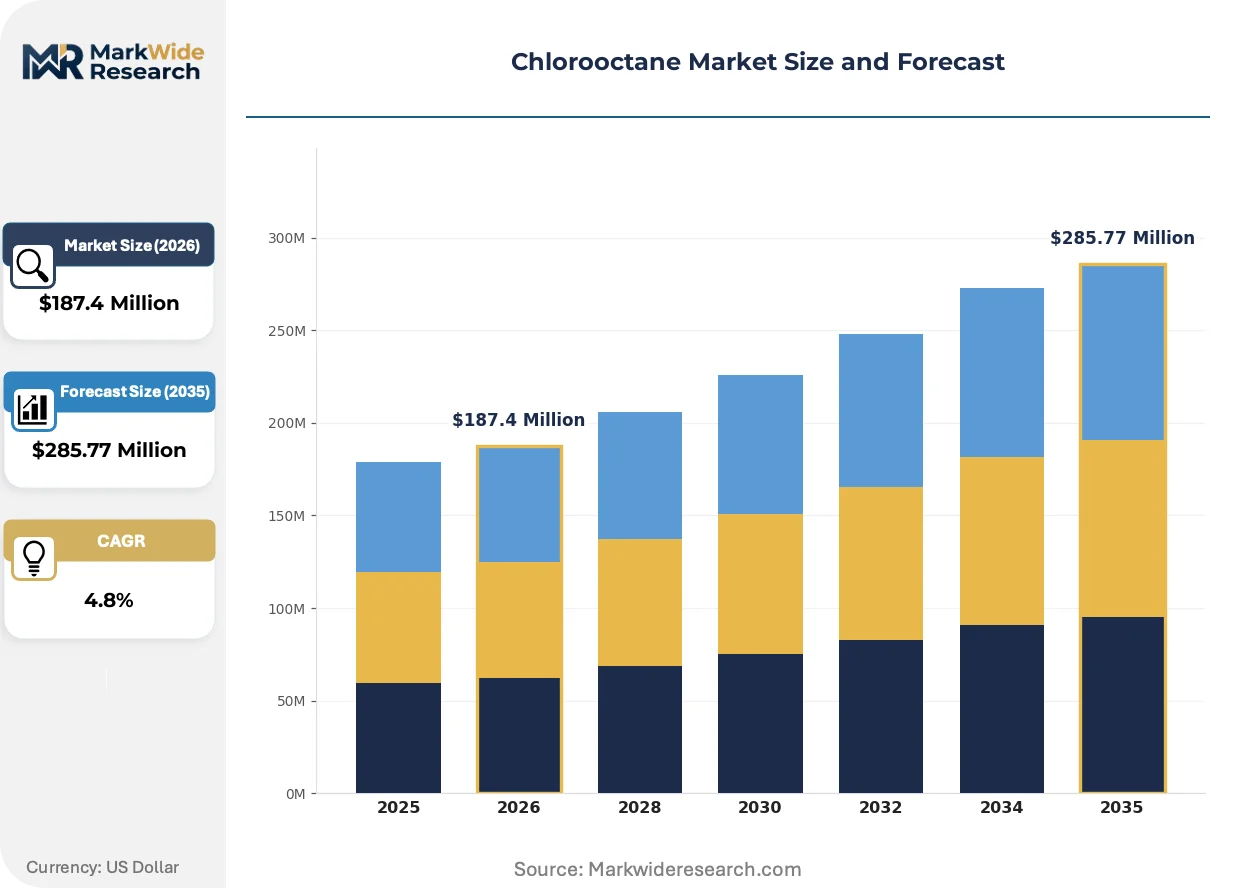
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorinated Solvents, Specialty Chemicals, Surfactants, Intermediates End Use Industry: Pharmaceuticals, Agrochemicals, Paints, Electronics Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers Packaging Type: Drums, Bulk Containers, Bottles, IBCs |
| Companies Covered | CABB Group GmbH, MOLBASE, TCI (Shanghai) Development Co. Ltd., Restek Corporation, NINGBO INNO PHARMCHEM CO. LTD, HiMedia Laboratories, Neogen Chemical Limited, Jinan Finer Chemical Co. Ltd, Jingmen Meifeng Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorooctane Market Emerging Trajectories
Process analytical technology and closed-loop emission recovery are compressing the technical gap between laboratory-grade and industrial-scale chlorooctane production, while regulatory data requirements are reshaping supplier qualification protocols.
Inline Raman spectroscopy is digitizing real-time chlorine conversion monitoring in continuous chlorination reactors. Specialty chemical manufacturers in Germany are deploying these systems to reduce off-specification batches and compress quality assurance cycle times. The technology is digitizing process control documentation for REACH registration compliance, enabling automated batch record generation that reduces regulatory preparation labor.
EPA hazardous air pollutant standards under the Clean Air Act are mandating maximum achievable control technology for chlorination facility emissions. United States producers must retrofit thermal oxidizers and carbon adsorption systems to meet residual chlorine and chlorinated organics limits. The pharmaceutical intermediate segment is responding by consolidating purchases around domestic suppliers with demonstrated compliance histories, displacing import reliance.
Specification-driven procurement is compressing supplier qualification timelines for agrochemical formulators seeking dual-source security. Large surfactant manufacturers are displacing spot market purchasing with framework agreements that embed annual volume commitments and technical audit rights. This pattern is most visible in China's Yangtze River Delta, where integrated chlor-alkali producers are capturing preferred supplier status through captive feedstock cost transparency.
Chlorooctane Market Segmentation
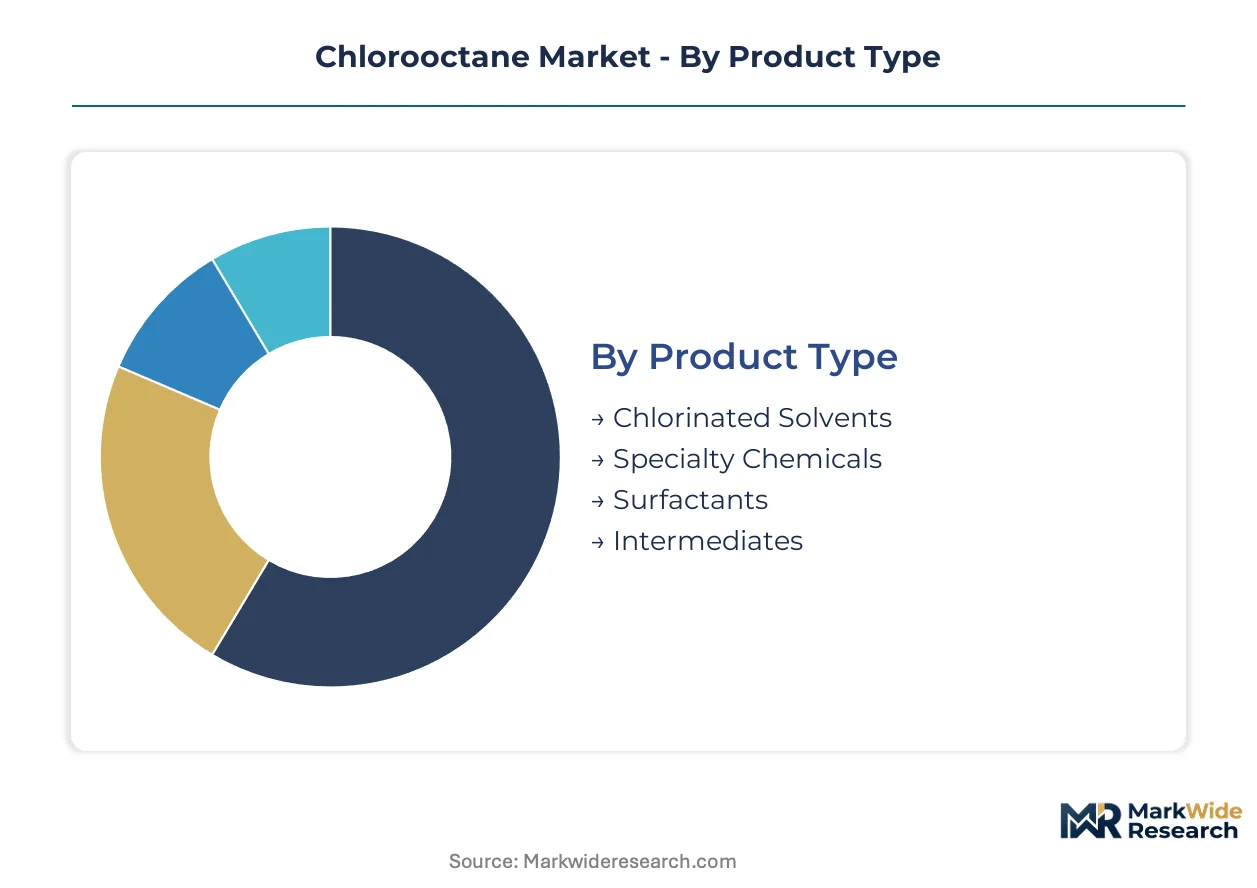
Chlorooctane market segmentation reveals how specification requirements diverge across pharmaceutical synthesis, agrochemical formulation, and electronics cleaning applications. Understanding these dimensional splits enables suppliers to align purification investments with margin capture opportunities.
Product Type:
Product grade differentiation spans laboratory purity through industrial bulk, with each tier commanding distinct qualification protocols and customer relationships.
- Specialty Chemicals:High-purity grades meeting pharmaceutical intermediate specifications require sub-ppm impurity thresholds and full REACH registration dossiers. Agrochemical and drug manufacturers in Germany and China specify these grades for active ingredient synthesis, consolidating purchases around registered suppliers with demonstrated compliance histories.
- Intermediates:Contract manufacturers in India and China are scaling hydrochlorination capacity to serve export demand for nucleophilic substitution precursors. This segment is climbing the fastest as Western innovators outsource halogenation steps to reduce capital intensity.
- Chlorinated Solvents:Technical-grade material serves surfactant and cleaning compound formulations where purity requirements permit broader impurity bands.
- Surfactants:Precursor supply for cationic and amphoteric surfactant manufacturing, with demand tied to agrochemical dispersant and textile softener markets.
The dominant share belongs to Specialty Chemicals, while Intermediates is closing the gap fastest.
End Use Industry:
End-use concentration determines regulatory exposure and pricing power, with pharmaceutical channels demanding batch traceability that agrochemical formulators rarely require.
- Pharmaceuticals:Active ingredient manufacturers specify chlorooctane for nucleophilic substitution reactions in antihistamine and anticholinergic synthesis. FDA and EMA inspection histories now filter supplier qualification, favoring domestic producers with validated quality systems.
- Agrochemicals:Herbicide and fungicide formulators in Brazil and Australia consume drum and bulk volumes for surfactant precursor synthesis. Procurement is shifting toward framework agreements with annual volume commitments and technical audit rights.
- Paints:Solvent and additive applications for industrial coating systems, with demand tracking construction activity in China's Yangtze River Delta.
- Electronics:Precision cleaning applications face substitution pressure from hydrofluoroether alternatives as per- and polyfluoroalkyl substance restrictions reshape solvent selection.
Pharmaceuticals commands the value concentration, though Agrochemicals is expanding most quickly through contract manufacturing outsourcing.
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with large formulators bypassing intermediaries while small laboratories rely on distributor inventory.
- Distributors:Regional chemical distributors maintain drum inventory for mid-scale pharmaceutical and agrochemical customers requiring just-in-time delivery and technical support.
- Direct Sales:Integrated chlor-alkali producers in Jiangsu province sell bulk volumes directly to surfactant manufacturers, leveraging captive feedstock cost transparency.
- Online Retail:Laboratory-grade packaging for research institutions and small-scale synthesis operations, with TCI (Shanghai) Development anchoring East Asian digital channels.
- Wholesalers:Volume aggregation for industrial accounts with standardized specification requirements and price-sensitive procurement.
Distributors retains the volume leadership, while Direct Sales is gaining share fastest through integrated producer expansion.
Packaging Type:
Packaging configuration aligns with freight economics and traceability mandates, creating divergence between pharmaceutical batch control and agrochemical cost optimization.
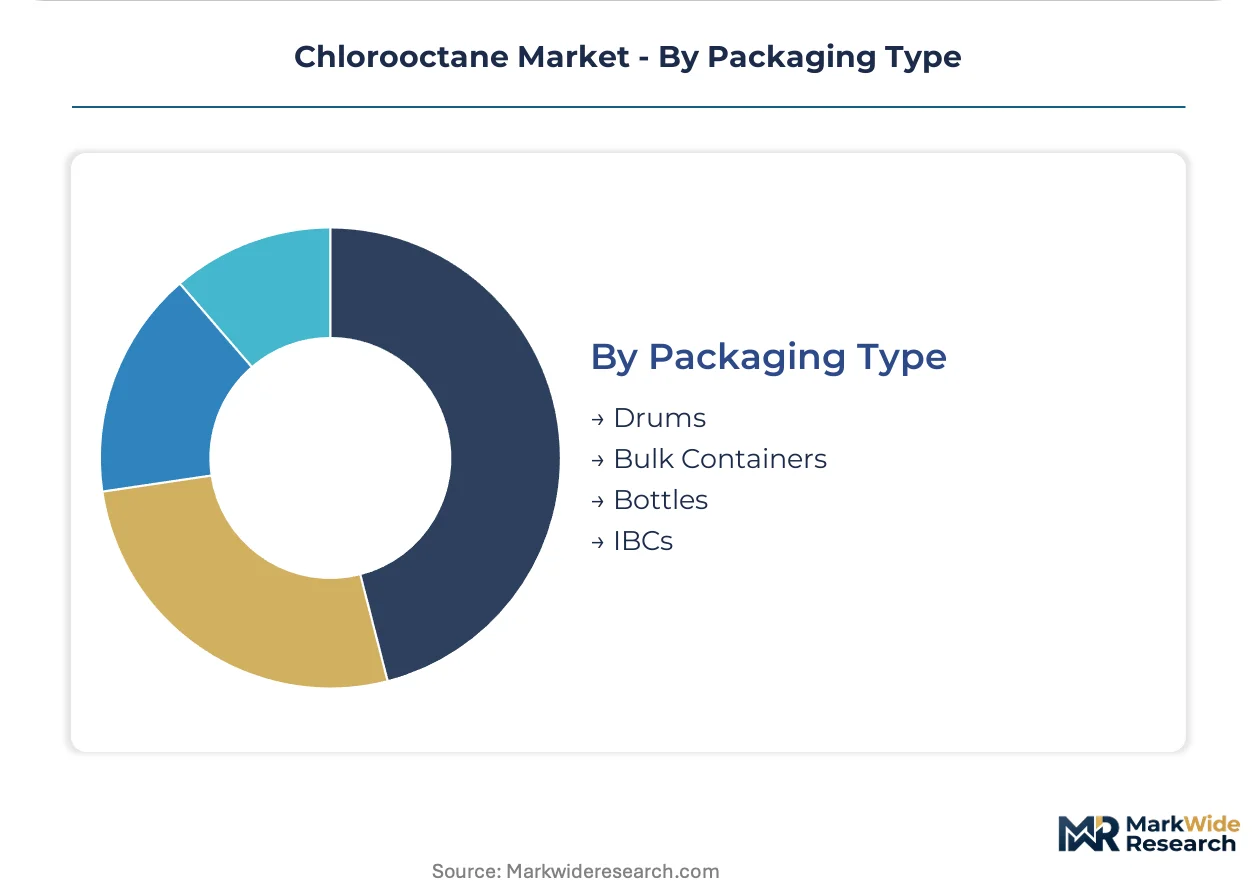
- Drums:Unitized handling dominates pharmaceutical channels where batch traceability requirements favor serialized inventory management and quality documentation.
- Bulk Containers:ISO tank configurations reduce per-unit logistics costs for high-volume surfactant precursors, with agrochemical formulators in Brazil and Australia displacing drum formats.
- IBCs:Intermediate bulk containers serve mid-scale agrochemical operations seeking handling efficiency without full tanker commitment.
- Bottles:Laboratory-scale packaging for analytical and research applications with high purity requirements and low volume consumption.
Drums holds the established position, while Bulk Containers is climbing fastest through agrochemical freight optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes chlorooctane predominantly for pharmaceutical intermediate synthesis, while China deploys it across agrochemical and electronics cleaning applications, creating divergent specification requirements and supplier qualification protocols.
United States
Pharmaceutical manufacturers in New Jersey and North Carolina specify chlorooctane for antihistamine active ingredient synthesis. EPA hazardous air pollutant standards under the Clean Air Act mandate maximum achievable control technology for chlorination emissions. Gulf Coast petrochemical corridors in Texas host specialty chemical producers retrofitting thermal oxidizers to meet residual chlorine limits.
Germany
CABB Group GmbH leverages backward integration into chlorine feedstock to supply pharmaceutical-grade chlorooctane for nucleophilic substitution reactions. REACH registration dossiers require toxicological data for chloroalkane imports exceeding one tonne annually. The Rhine-Ruhr chemical cluster concentrates halogenation expertise among aging technical workforces with free-radical chlorination process control knowledge.
China
Agrochemical formulators in Jiangsu province scale hydrochlorination capacity to serve export demand for surfactant precursors. MEE volatile organic compound emission limits favor closed-loop chlorination systems with recovery infrastructure. The Yangtze River Delta chemical cluster integrates chlor-alkali production with downstream electronics cleaning and agrochemical sectors.
India
Contract manufacturers in Gujarat and Maharashtra expand halogenation precision capabilities for pharmaceutical intermediate outsourcing from Western innovators. CDSCO inspection histories now filter supplier qualification for active ingredient manufacturers. Mumbai-Pune industrial corridors attract investment in custom synthesis services requiring batch traceability systems.
Brazil
Agrochemical formulators in São Paulo state displace drum packaging with ISO tank configurations for surfactant precursor freight optimization. ANVISA registration requirements govern imported chlorinated solvent specifications for herbicide formulation. The Campinas-Sorocaba chemical belt concentrates demand from soybean fungicide and dispersant manufacturers.
Chlorooctane Market Vendor Landscape
Capability concentration sits with integrated chlor-alkali producers possessing REACH registration dossiers; scale advantage sits with Jiangsu-based contract manufacturers serving export agrochemical demand. The supplier base compresses around two tiers: established European specialty chemical houses with toxicological compliance histories, and Chinese integrated producers with captive feedstock cost transparency. Dominant archetypes include backward-integrated chlorine producers, custom synthesis specialists, and regional distribution anchors. Competitive moves center on framework agreements embedding annual volume commitments and technical audit rights, plus carbon capture retrofits securing preferential permitting under dual carbon mandates.
Among Germany-based integrated producers, CABB Group GmbH exemplifies the backward-integrated archetype with captive chlorine feedstock control. TCI (Shanghai) Development Co. Ltd. occupies a position within the East Asian distribution tier, anchoring laboratory-grade supply networks. Neogen Chemical Limited represents the Indian custom synthesis specialist archetype, serving pharmaceutical intermediate demand requiring halogenation precision. These three company types collectively illustrate how geographic specialization and integration depth determine competitive positioning across specification tiers.
| Leading Market Players |
|---|
| CABB Group GmbH |
| MOLBASE |
| TCI (Shanghai) Development Co. Ltd. |
| Restek Corporation |
| NINGBO INNO PHARMCHEM CO. LTD |
| HiMedia Laboratories |
| Neogen Chemical Limited |
| Jinan Finer Chemical Co. Ltd |
| Jingmen Meifeng Chemical |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta barge freight corridors transmit feedstock cost volatility directly into chlorooctane pricing tiers, amplifying margin compression for non-integrated manufacturers while rewarding Jiangsu-based chlor-alkali producers with captive chlorine supply. This logistics-cost differential stratifies the market into three distinct procurement tiers that downstream formulators navigate through contract-structure choices.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical intermediate procurement, with annual volume commitments and technical audit rights displacing spot purchasing as FDA and EMA inspection histories filter supplier qualification. Price differentiation rests on REACH registration status and halogenation precision certification, with laboratory-grade material commanding substantial premiums over technical bulk. Cost compression in agrochemical channels is intensifying because Brazilian and Australian formulators optimize freight through ISO tank configurations. Small-scale research laboratories exhibit the highest price sensitivity, while active ingredient manufacturers prioritize compliance history over unit cost.
Supply Chain Analysis
Electrolytic chlorine and n-octane feedstock availability centers on Germany, China, and India, with caustic soda co-production economics creating input cost instability that propagates through specialty chemical value chains. Chlorooctane manufacturing draws from chlor-alkali infrastructure, hydrochlorination catalyst supply, and precision distillation equipment. Single-source vulnerability concentrates in Jiangsu province environmental enforcement exposure, where MEE emission limits can trigger sudden production halts. Distribution runs through integrated producers selling direct to surfactant manufacturers and regional distributors maintaining drum inventory for mid-scale pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Custom synthesis services for pharmaceutical intermediates represent a service-attach layer expanding faster than commodity chlorooctane production, as Western innovators outsource halogenation precision to capture margin without capital intensity. This recurring-revenue dynamic restructures competitive economics around technical capability rather than feedstock scale alone.
For Market Incumbents: Pre-empt fluorinated solvent substitution threats in electronics cleaning by accelerating carbon capture retrofit investments that secure preferential permitting under China's dual carbon mandates. Consolidate supplier relationships around framework agreements embedding technical audit rights, while defending REACH registration dossiers against emerging Indian custom synthesis specialists. Backward integration into chlorine feedstock remains the critical margin stability lever. For New Entrants and Emerging Players: Mid-scale agrochemical formulators in Brazil and Australia represent the most penetrable entry point, as these accounts displace drum packaging with bulk container configurations and seek dual-source security beyond established Jiangsu suppliers. Pharmaceutical contract manufacturing in Gujarat and Maharashtra offers a second white-space target, where CDSCO inspection histories are still being established. A go-to-market angle anchored on batch traceability system integration and unit-level serialization capabilities bypasses legacy distributor infrastructure limitations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors custom synthesis specialists with halogenation precision capabilities and demonstrated regulatory compliance histories over commodity chlor-alkai scale players. Long-term viability across the analysis window hinges on REACH registration asset value and carbon-neutral production credentials. The signal to watch is MEE enforcement intensity in Jiangsu province, where sudden environmental actions could abruptly revalue supply security premiums. Cross-checking against ECHA registration database trends is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorine Feedstock | CABB Group GmbH's captive supply model sustains margin stability against electrolytic caustic soda volatility. |
| Carbon Capture Retrofit Investment | Preferential MEE permitting pathways under China's dual carbon mandates reward early compliance infrastructure. |
| Custom Synthesis Capability Expansion | Neogen Chemical Limited's pharmaceutical intermediate precision captures outsourcing demand from Western innovators. |
| Framework Agreement Structuring | Annual volume commitments with technical audit rights displace spot purchasing among agrochemical formulators. |
| Batch Traceability System Integration | Unit-level serialization meets pharmaceutical channel requirements that conflict with legacy distributor infrastructure. |
Methodological Framework
Desk research of customs and trade flow databases, ECHA registration filings, and SEC chemical sector disclosures preceded structured interviews with plant managers at chlor-alkai facilities, procurement leads at pharmaceutical and agrochemical formulators, distribution channel partners in East Asian chemical trading networks, and technical R&D directors specializing in halogenation process engineering. Primary fieldwork combined with secondary validation through ACC and Cefic industry reports enabled bottom-up production capacity modeling and top-down demand segmentation triangulation.
Assumptions around REACH compliance timelines, MEE enforcement intensity, and chlorine feedstock cost trajectories were held fixed across baseline scenarios while carbon pricing implementation schedules and fluorinated solvent substitution rates were varied in sensitivity analysis. The analytical framework modeled chlorooctane demand across grade tier, end-use industry concentration, packaging format, and regional production hub across the projection horizon. CAGRs were derived from production capacity expansion announcements, import-export flow analysis, and downstream formulation growth proxies rather than extrapolated historical trends.
Practitioners should monitor ECHA registration renewal deadlines, Jiangsu province environmental enforcement calendars, and hydrofluoroether substitution acceleration in electronics cleaning for early signals requiring forecast revision. Cross-checking against IHS Markit chemical production data and UN Comtrade chloroalkane flow statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Microemulsions Market
Surfactants
Amphoteric Emulsifier Market
Surfactants
Wax Emulsion Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
North America Surfactants Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Cetyl Trimethyl Ammonium Chloride Market
Surfactants
Sodium Lauryl Sulphate Market
Surfactants
Sulfosuccinate Market
Surfactants
Green Surfactants Market
Surfactants
Cocomonoethanolamide (CMEA) Market
Surfactants
Cationic Surfactants Market
Surfactants
Non-Ionic Surfactants Market