
 Global Thioglycolic Acid Market | 2026-2036
Global Thioglycolic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thioglycolic Acid Market Foresight
Buyer concentration among personal care manufacturers is hardening as multinational cosmetics houses consolidate supplier rosters toward fewer qualified thioglycolic acid vendors. Arkema leverages its integrated sulfur chemistry platform to secure feedstock cost advantages across European and Asian operations. Bruno Bock Chemische Fabrik GmbH & Co. KG anchors its position through specialized mercaptan expertise and pharmaceutical-grade certification. Daicel Corporation competes by dominating Asia-Pacific supply chains for high-purity aqueous solutions.
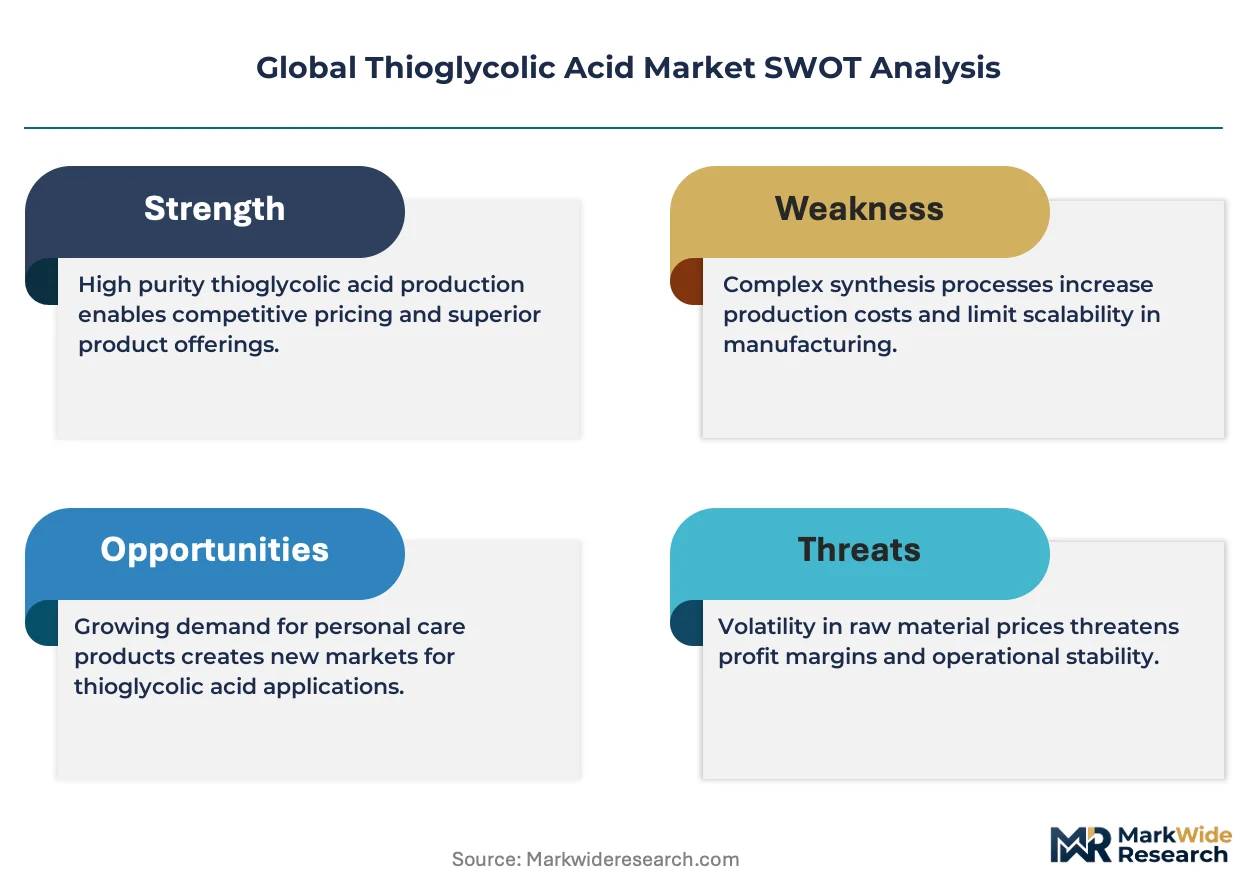
Thioglycolic acid is an organosulfur compound with the formula HSCH₂COOH, typically manufactured through chloroacetic acid reaction with sodium hydrosulfide or thiourea hydrolysis, yielding a clear liquid with strong reducing properties valued for breaking disulfide bonds in keratin and metal oxide surfaces. Aqueous solution grades command the largest volume share due to safer handling profiles and direct formulation compatibility in hair care and metal cleaning applications. Potassium thioglycolate represents the fastest-expanding product category as depilatory brands shift toward lower-odor, skin-neutral formulations. Hair care applications sit at the center of value pools, while metal cleaning segments offer steadier but thinner margins.
REACH registration requirements in Europe and EPA toxic substance reporting in the United States shape product purity thresholds and documentation burdens for cross-border shipments. China's MEE enforces wastewater discharge limits that push tanneries and textile processors toward controlled-dosage thioglycolic acid systems. ISO standards for chemical handling and occupational exposure limits influence packaging specifications and drum labeling protocols worldwide. Stakeholders must monitor evolving mercaptan classification debates under ECHA and national poison control frameworks to anticipate formulation reformulation cycles and regional supply reallocations.
Market Dynamics
Consolidation among personal care multinationals is hardening supplier rosters, forcing thioglycolic acid producers to secure pharmaceutical-grade certifications and aqueous solution capabilities to maintain qualified vendor status.
Growth Catalysts
- REACH and RoHS compliance mandates:European chemical frameworks push producers toward purer grades and aqueous solutions, creating premium pricing tiers for certified suppliers.
- Textile processing clusters:Expanding leather tanning and textile operations in China concentrate demand for controlled-dosage thioglycolic acid systems.
- Potassium thioglycolate substitution:Depilatory brands accelerate formulation shifts toward lower-odor, skin-neutral variants to capture sensitive-skin consumer segments.
Market Restraints
- Sulfur feedstock volatility:Chloroacetic acid and sodium hydrosulfide input costs fluctuate with energy markets, compressing margin stability for non-integrated producers.
- Supplier concentration in Asia-Pacific:High-purity aqueous solution supply chains concentrate in East Asian manufacturing hubs, exposing buyers to single-source geographic risk.
- EPA toxic substance reporting:Cross-border documentation burdens and purity thresholds create friction for shipments entering United States territory.
Strategic Opportunities
- India personal care penetration:Underdeveloped depilatory markets in tier-two Indian cities offer expansion vectors for potassium thioglycolate formulations.
- Metal cleaning diversification:Precision electronics manufacturing in Vietnam and Mexico generates demand for thioglycolic acid in oxide removal applications.
- EU Green Deal chemistry incentives:Sustainable process certifications open preferential procurement channels for European cosmetic houses.
Industry Challenges
- Mercaptan handling certification:ISO occupational exposure protocols and ECHA classification debates force continuous staff retraining and drum relabeling cycles.
- Legacy wastewater infrastructure:China's MEE discharge limits require tanneries to retrofit controlled-dosage systems, extending sales cycles and technical service burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thioglycolic Acid Market |
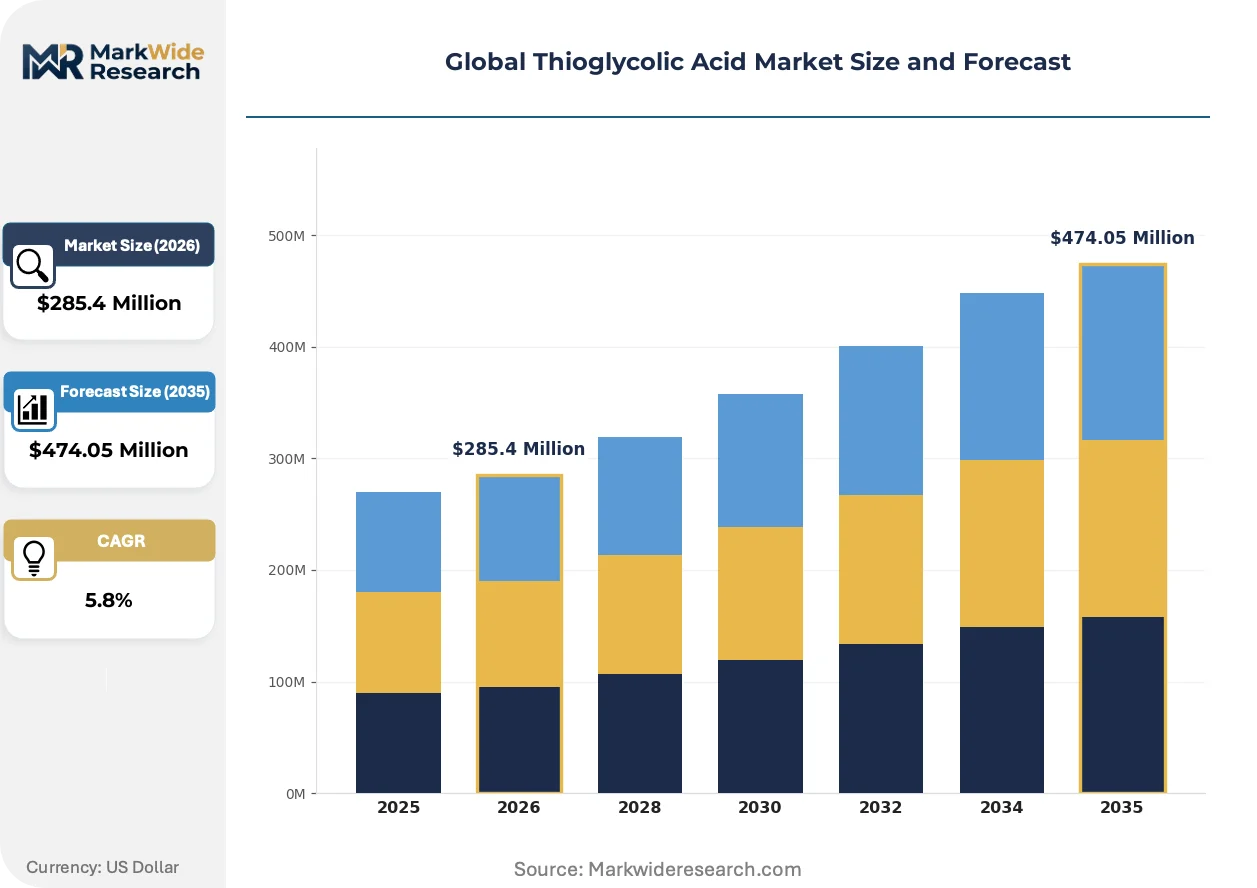
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Thioglycolic Acid, Aqueous Solution, Potassium Thioglycolate, Sodium Thioglycolate, Calcium Thioglycolate Application: Hair Care, Textile Processing, Leather Tanning, Photographic Chemicals, Metal Cleaning End User Industry: Personal Care Manufacturers, Textile Mills, Tanneries, Photographic Labs, Metal Fabricators Packaging Type: Drums, Barrels, Intermediate Bulk Containers, Tankers, Glass Bottles |
| Companies Covered | Arkema, Bruno Bock Chemische Fabrik GmbH & Co. KG, Daicel Corporation, Ever Flourish Chemical, HiMedia Laboratories, Merck Millipore, Qingdao LNT Chemical Co., Ltd., Ruchang Mining, Sasaki Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thioglycolic Acid Market Shifts & Advancements
Formulation chemistry and regulatory classification are actively reshaping competitive positioning in thioglycolic acid markets, with purity grades and delivery formats becoming primary differentiation vectors.
Microencapsulation technology for controlled-release thioglycolate is absorbing formulation complexity in premium depilatory products. Personal care laboratories in France and Germany are adopting encapsulated variants to extend shelf stability and reduce odor profiles. This absorption of technical risk by ingredient suppliers is compressing in-house R&D requirements for mid-tier cosmetic brands.
REACH registration dossier updates under ECHA's ongoing mercaptan substance evaluation are forcing purity threshold elevations across European supply chains. Manufacturers must now document sub-ppm impurity profiles for cosmetic-grade shipments. Hair care applications face the steepest compliance costs, with several formulators reformulating toward potassium salts to sidestep classification uncertainty.
Direct raw material contracting is displacing distributor intermediation among large personal care houses. Multinational cosmetics groups in the United States and Western Europe now negotiate annual sulfur chemistry supply agreements with integrated producers. This channel consolidation is most visible in North American procurement, where qualified vendor lists have narrowed to four certified suppliers.
Global Thioglycolic Acid Market Segmentation
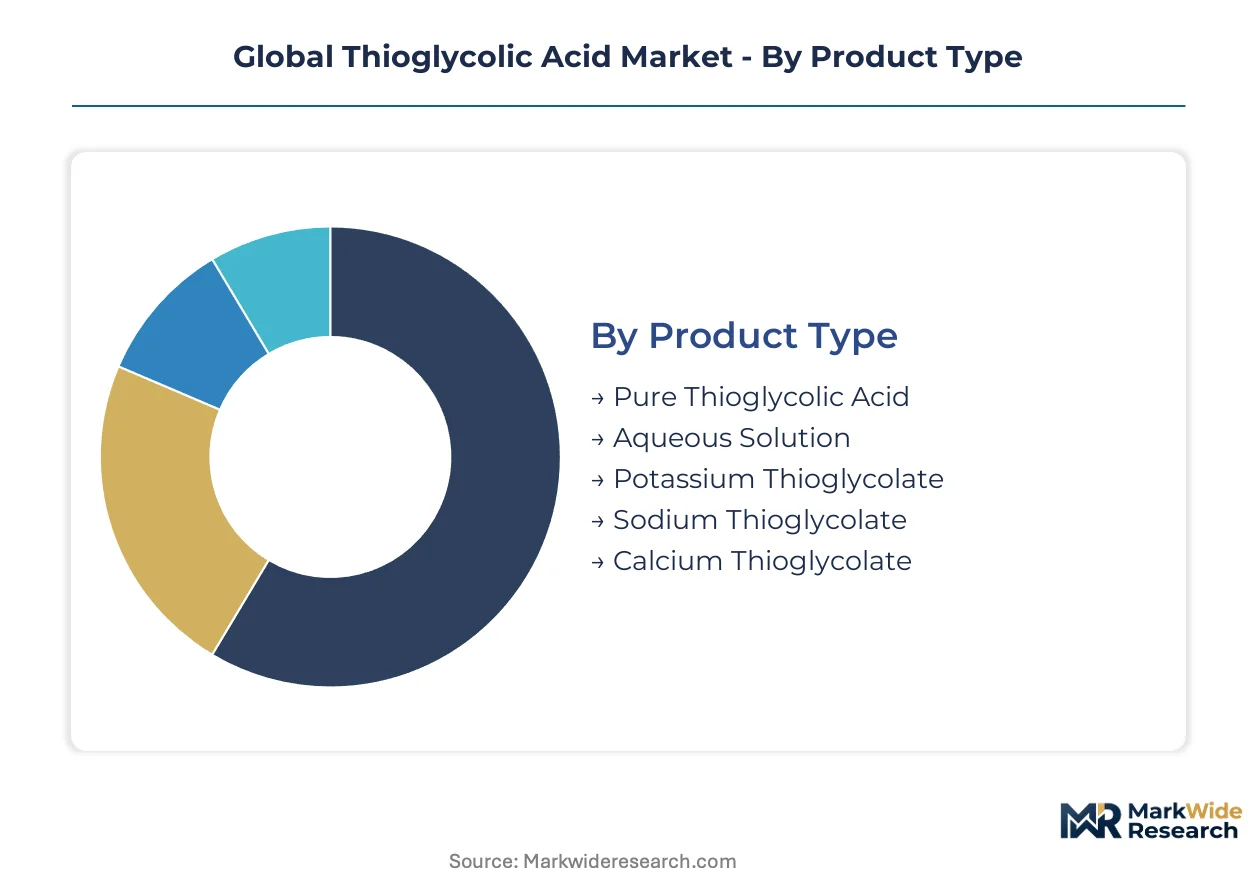
Thioglycolic acid segmentation reveals how capital intensity, regulatory thresholds, and formulation chemistry create tiered profit pools across the value chain. Product grade and delivery format decisions lock in customer switching costs and determine qualification barriers for supplier entry.
Product Type:
Capital intensity varies sharply across product categories, with aqueous solution infrastructure demanding stainless-steel dilution systems and pharmaceutical-grade filtration that pure acid synthesis does not require.
- Pure Thioglycolic Acid:Concentrated organosulfur liquid produced through chloroacetic acid reaction with sodium hydrosulfide. Demand concentrates in Germany and Switzerland for industrial metal cleaning applications where transport economics favor maximum active ingredient density. REACH registration dossiers impose sub-ppm impurity documentation burdens that favor integrated sulfur chemistry producers.
- Aqueous Solution:Diluted formulations typically at 70-80% concentration in deionized water. Hair care manufacturers in France and the United States specify this grade for direct formulation compatibility, absorbing the technical risk of dilution and stabilizer addition from their suppliers. Safer handling profiles reduce drum relabeling cycles under ISO occupational exposure protocols.
- Potassium Thioglycolate:Salt variant with neutral pH and reduced odor profile. Depilatory brands specify this grade for sensitive-skin market positioning.
- Sodium Thioglycolate:Alkaline salt used in permanent wave formulations where pH control drives curl formation kinetics.
- Calcium Thioglycolate:Specialized salt with slower release characteristics, specified in select depilatory cream formulations for extended contact time.
Most installed capacity flows through Aqueous Solution. Expansion is steepest in Potassium Thioglycolate.
Application:
Margin structure across applications follows regulatory exposure and customer concentration, with hair care commanding premium pricing for pharmaceutical-grade certification while metal cleaning trades volume for thinner returns.
- Hair Care:Permanent waves and depilatory products rely on thioglycolic acid's disulfide bond cleavage mechanism. Personal care multinationals in the United States and Western Europe consolidate supplier rosters toward fewer qualified vendors, hardening buyer concentration and elevating documentation requirements.
- Metal Cleaning:Oxide removal and surface preparation applications in precision electronics manufacturing. Vietnam and Mexico generate demand as semiconductor and component assembly clusters expand, though specifications remain less stringent than cosmetic grades.
- Textile Processing:Mercerization and finishing treatments in cotton and synthetic fiber production. China's expanding textile clusters concentrate demand, with MEE wastewater discharge limits pushing processors toward controlled-dosage systems.
- Leather Tanning:Hair removal and beamhouse operations. Tanneries in China's Hebei and Zhejiang provinces face retrofit requirements for effluent control.
- Photographic Chemicals:Developer and fixer formulations in traditional silver-halide processing. Declining volume segment as digital imaging displaces film.
Hair Care absorbs the highest compliance investment per ton. Metal Cleaning offers the steadiest volume off-take with lowest qualification friction.
End User Industry:
Customer type determines packaging format, technical service intensity, and contract structure, with personal care houses driving channel consolidation toward direct raw material contracting.
- Personal Care Manufacturers:Multinational cosmetics groups in France, Germany, and the United States negotiate annual sulfur chemistry supply agreements. These buyers specify pharmaceutical-grade certification and aqueous solution capabilities as table stakes for qualified vendor status.
- Textile Mills:Cotton and synthetic fiber processors in China and India purchase controlled-dosage systems to meet discharge limits. Technical service burdens extend sales cycles.
- Tanneries:Leather processors in China, Italy, and Brazil use thioglycolic acid for unhairing operations. Legacy wastewater infrastructure requires retrofit investment.
- Photographic Labs:Declining customer base with specialized small-volume requirements.
- Metal Fabricators:Electronics and precision component manufacturers in Vietnam and Mexico. Specifications focus on oxide removal performance rather than cosmetic-grade purity.
Personal Care Manufacturers concentrate the highest value per liter. Textile Mills generate the largest absolute volume movement.
Packaging Type:
Format selection traces customer scale and handling infrastructure, with drum and IBC specifications shaped by REACH and EPA documentation requirements for cross-border movement.
- Drums:Standard 200-liter steel containers for mid-volume shipments. Labeling protocols under ECHA mercaptan classification debates force continuous revision cycles.
- Intermediate Bulk Containers:1,000-liter flexible or rigid totes for textile mill and tannery customers with bulk handling infrastructure.
- Barrels:Smaller format for photographic chemical and laboratory supply channels.
- Tankers:Dedicated stainless-steel road tankers for large personal care manufacturers with direct feedstock integration.
- Glass Bottles:Analytical and reagent-grade packaging for laboratory and quality control applications.
Drum shipments dominate cross-border trade. IBC adoption is climbing fastest among integrated textile processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's textile processing clusters generate larger absolute thioglycolic acid volumes than Germany's precision chemical sector, yet European REACH compliance mandates command steeper purity premiums per ton traded.
China
Expanding leather tanning operations in Hebei and Zhejiang provinces drive concentrated demand for controlled-dosage thioglycolic acid systems. The Ministry of Ecology and Environment enforces wastewater discharge limits that force tanneries toward retrofit investments. Textile processing clusters in Jiangsu province absorb the largest regional volume for mercerization treatments.
Germany
Industrial metal cleaning applications in the Ruhr region and pharmaceutical-grade chemical synthesis anchor steady consumption. ECHA's ongoing mercaptan substance evaluation under REACH pushes producers toward sub-ppm impurity documentation. Bruno Bock Chemische Fabrik GmbH & Co. KG maintains specialized mercaptan production capabilities in the northern industrial belt.
United States
Personal care multinationals consolidate supplier rosters toward fewer qualified vendors for depilatory and hair-perming formulations. EPA toxic substance reporting requirements create documentation friction for cross-border shipments entering domestic territory. Direct raw material contracting now displaces distributor intermediation among large cosmetics houses in New Jersey and California.
France
Premium depilatory brands in the Île-de-France cosmetics corridor accelerate formulation shifts toward potassium thioglycolate variants. ANSM monitors cosmetic ingredient classifications alongside ECHA deliberations. Microencapsulation technology adoption concentrates in Paris and Lyon personal care laboratories seeking extended shelf stability.
India
Underdeveloped depilatory markets in tier-two cities offer expansion vectors for potassium thioglycolate formulations targeting sensitive-skin segments. BIS standards for chemical purity create qualification thresholds for imported grades. Textile mills in Gujarat and Tamil Nadu generate growing demand for controlled-dosage systems in cotton finishing operations.
Global Thioglycolic Acid Market Competitive Landscape
European producers anchor one tier through integrated sulfur chemistry platforms and REACH-certified purity capabilities; East Asian specialists hold volume positions in aqueous solution supply chains. The vendor base stratifies across three tiers: multinational chemical conglomerates with backward integration into feedstocks, mid-cap mercaptan specialists with pharmaceutical-grade certifications, and regional solution blenders serving textile and leather clusters. Dominant competitive moves include direct annual contracting with personal care multinationals and capacity expansion in high-purity aqueous solution infrastructure.
Within the integrated sulfur chemistry tier, Arkema exemplifies feedstock cost control across European and Asian operations. Among specialized mercaptan producers, Bruno Bock Chemische Fabrik GmbH & Co. KG occupies a position anchored by pharmaceutical-grade certification and concentrated European production. Daicel Corporation represents the Asia-Pacific high-purity aqueous solution archetype, with supply chain positioning aligned to regional textile and personal care manufacturing gravity.
| Leading Market Players |
|---|
| Arkema |
| Bruno Bock Chemische Fabrik GmbH & Co. KG |
| Daicel Corporation |
| Ever Flourish Chemical |
| HiMedia Laboratories |
| Merck Millipore |
| Qingdao LNT Chemical Co., Ltd. |
| Ruchang Mining |
| Sasaki Chemical |
| Others |
Supply & Pricing Matrix
China's MEE wastewater discharge mandates gate qualified supply access and premium-tier pricing for thioglycolic acid producers serving compliant tanneries and textile processors. These environmental thresholds concentrate vendor certification burdens, allowing certified suppliers to command sustained price premiums over uncertified competitors while forcing buyers to absorb higher unit costs for documented purity grades.
Pricing Analysis
Capacity additions in Jiangsu province are reshaping price floors for aqueous solution grades as new stainless-steel dilution systems come online. Pricing stratifies across pharmaceutical-grade, cosmetic-grade, and industrial-grade tiers, with REACH documentation burdens and sub-ppm impurity testing driving differentiation. Cost compression in standard grades is intensifying because sulfur feedstock volatility from energy market swings squeezes non-integrated producers. Small textile mills in India exhibit the highest price sensitivity, while personal care multinationals in France and Germany prioritize certification over unit cost.
Supply Chain Analysis
Freight cost differentials between drum shipments and dedicated tanker deliveries shape procurement economics for large personal care manufacturers with direct feedstock integration. Supply concentrates in China, Germany, and Japan, with high-purity aqueous solution capacity anchored in East Asian manufacturing hubs. Raw material flows draw from chloroacetic acid, sodium hydrosulfide, and thiourea hydrolysis inputs. Single-source geographic vulnerability in Asia-Pacific exposes buyers to disruption risk. Distribution runs through direct annual contracting with multinational cosmetics houses, displacing traditional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through potassium thioglycolate substitution cycles, as depilatory brands absorb premium pricing for lower-odor, skin-neutral formulations that reduce their own R&D burdens.
For Market Incumbents: Deploy pharmaceutical-grade certification investments to harden qualified vendor status against emerging mercaptan specialists. Arkema's integrated sulfur chemistry platform demonstrates how backward integration into feedstock production defends margin stability amid chloroacetic acid cost swings. Incumbents should accelerate aqueous solution capacity in Jiangsu province to capture textile cluster demand under MEE compliance deadlines.
For New Entrants and Emerging Players: The price-point gap between REACH-certified European grades and standard Asian industrial grades creates entry space for mid-tier mercaptan producers with pharmaceutical-grade filtration capabilities. Tier-two Indian cities offer the most penetrable geography for potassium thioglycolate formulations targeting sensitive-skin depilatory segments. A technical service-heavy go-to-market approach can extend sales cycles into textile mill retrofit opportunities.
For Investors and Strategic Acquirers: Roll-up economics work for specialized mercaptan producers with pharmaceutical-grade certifications because buyer concentration among personal care multinationals is hardening supplier rosters toward fewer qualified vendors. The five-to-ten-year viability window favors mid-cap specialists with aqueous solution infrastructure and existing REACH dossiers. Watch ECHA's ongoing mercaptan substance evaluation as the inflection signal for purity threshold elevations that would trigger reformulation cycles and regional supply reallocations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Feedstocks | Captive supply of sodium hydrosulfide insulates margin stability from energy market volatility. |
| Pharmaceutical-Grade Certification Investment | REACH dossier updates under ECHA evaluation harden qualified vendor status for cosmetics procurement. |
| Aqueous Solution Capacity Expansion | Stainless-steel dilution systems in Jiangsu province capture textile cluster demand under MEE limits. |
| Potassium Thioglycolate Formulation Shift | Salt variant production captures depilatory brand demand for sensitive-skin market positioning. |
| Direct Annual Supply Contracting | Channel consolidation with multinational cosmetics houses displaces distributor intermediation in North America. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at thioglycolic acid production facilities, procurement leads at personal care multinationals, distribution channel partners serving textile clusters, and technical R&D directors at mercaptan specialists. Secondary validation drew from customs and trade data, Cefic chemical industry reports, SEC 10-K filings for integrated sulfur chemistry producers, and ECHA REACH registration dossiers. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Segment-weighting approaches distributed growth contributions across product grade tiers, end-use industry concentrations, packaging format preferences, and regional production hub dynamics throughout the projection horizon. CAGRs were derived from elasticity-adjusted demand curves and input cost trajectory modeling. Forecast inputs incorporated MEE wastewater discharge limit enforcement timelines, ECHA mercaptan classification deliberation schedules, and potassium thioglycolate substitution rates in depilatory formulation pipelines.
Caveats apply where ECHA regulatory decisions, sulfur feedstock cost spikes, or personal care multinational supplier consolidation moves could materially shift the outlook. Forecasts reflect assumptions about certification timeline adherence and cluster expansion rates in Chinese textile processing hubs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Amino Acid Surfactants Market
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
Tetradecyl Chloride Market
Surfactants
Dispersant Market
Surfactants
Fatty Methyl Ester Sulfonate Market
Surfactants
Sodium Cumenesulfonate Market
Surfactants
Green Surfactants Market
Surfactants
MDEA Esterquats Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Lauramide DEA Market
Surfactants
Bitumen Emulsifier Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Calcium Stearoyl-2 Lactylate Market
Surfactants
Cocamide Monoethanolamine Market
Surfactants
Emulsifying Wax Market
Surfactants
TEA Esterquats Market