
 Trisiloxane Market | 2026-2036
Trisiloxane Market Size, Share, and Industry Trends Forecast 2026-2036
Trisiloxane Market Analytics
REACH is restructuring the cost-of-entry calculus for European trisiloxane suppliers by mandating extensive substance registration and toxicity documentation. Dow Inc. leverages its integrated silicone feedstock position to absorb these compliance costs without sacrificing margin. Momentive Performance Materials anchors its competitive stance through deep specialization in agricultural adjuvant grades. Wacker Chemie AG sustains European manufacturing presence while navigating the same regulatory density with captive chlorosilane supply.
Trisiloxane denotes a three-silicon siloxane oligomer with the linear structure MDM, where M represents trimethylsilyl end groups and D represents a dimethylsiloxane unit, prized for its exceptionally low surface tension and rapid spreading coefficient. The compound serves primarily as a superwetting agent in agricultural formulations, personal care emulsions, and industrial coatings where substrate coverage uniformity determines performance. Silicone emulsions dominate current value generation due to their direct deployability in tank-mix adjuvant systems, while modified silicones represent the fastest-expanding category as formulators seek hydrolytically stable variants for aqueous pesticide concentrates. Trisiloxane compounds in powder form occupy a narrower but higher-margin niche serving solid-dose pharmaceutical and cosmetic applications where liquid carriers introduce compatibility risk.
EPA regulates trisiloxane agricultural adjuvants through pesticide registration requirements under FIFRA, while China's MEE enforces emission standards on silicone monomer production that constrain upstream supply elasticity. ECHA's REACH restrictions on cyclic siloxanes D4, D5, and D6 indirectly pressure trisiloxane purity specifications by limiting precursor contamination thresholds. Stakeholders must monitor evolving biocidal product regulations in Europe and pending EPA reassessments of inert ingredient tolerances, as these determinations will dictate which molecular weights and functional modifications retain market access.
Market Dynamics
Agricultural adjuvant demand is restructuring the trisiloxane market as precision farming and reduced-volume pesticide application protocols drive superwetting agent consumption. REACH compliance costs and cyclic siloxane purity mandates are simultaneously compressing supplier margins while favoring integrated chlorosilane producers capable of captive feedstock control.
Growth Catalysts
- Agricultural adjuvant protocols:Farmers in Brazil and the United States deploy trisiloxane-enhanced tank mixes to achieve pesticide coverage at sub-1% application rates, cutting chemical input volumes while maintaining efficacy against resistant pest populations.
- REACH substance registration:The European Union's extended toxicity documentation requirements favor established registrants with existing dossiers, creating competitive moats that deter commodity importers and consolidate share among compliant formulators.
- Dimethylsiloxane unit optimization:Process advances in hydrosilylation catalysis are lowering polydispersity indices in MDM oligomer production, enabling tighter surface tension specifications for aqueous concentrate compatibility.
Market Restraints
- Methyl chloride volatility:Trisiloxane production depends on methyl chloride as a silicon functionalization feedstock, and natural gas price swings transmit directly into dimethylchlorosilane cost structures without hedging mechanisms for specialty silicone producers.
- Qinghai-Xinjiang supply concentration:Metallurgical-grade silicon metal concentrates in western Chinese smelter complexes, exposing downstream trisiloxane manufacturers to power rationing risks during regional grid stress events.
- Cyclic siloxane contamination thresholds:ECHA restrictions on D4, D5, and D6 residues force costly purification retrofits on legacy distillation trains, particularly burdening European producers with aged fixed-asset bases.
Strategic Opportunities
- India crop protection expansion:The country's central pesticide regulator is accelerating registration timelines for adjuvant co-formulations, opening access to a market where average farm size fragmentation creates premium penetration for spreading-enhancing agents.
- Personal care emulsion upgrading:Korean and Japanese cosmetic formulators seek hydrolytically stable trisiloxane variants for water-based sun care, replacing volatile cyclic silicones under pressure from clean beauty certification schemes.
- MEE emission standard alignment:China's Ministry of Ecology and Environment is tightening silicone monomer plant effluent rules, creating first-mover advantage for trisiloxane producers with integrated environmental compliance systems already operational.
Industry Challenges
- Organosilicon synthesis expertise scarcity:The specialized knowledge required for Grignard-based chlorosilane handling and platinum-catalyzed equilibration chemistry concentrates among retiring cohorts at legacy German and Japanese chemical complexes.
- ISO 17025 analytical certification timelines:Third-party validation of trisiloxane purity and cyclic contaminant levels requires 12-18 month queue times at accredited laboratories, delaying product launches and locking working capital in inventory.
- Legacy tank-mix compatibility testing:Agricultural adjuvant suppliers must maintain extensive pesticide formulation libraries for physical compatibility verification, creating fixed cost burdens that scale poorly for niche volume producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trisiloxane Market |
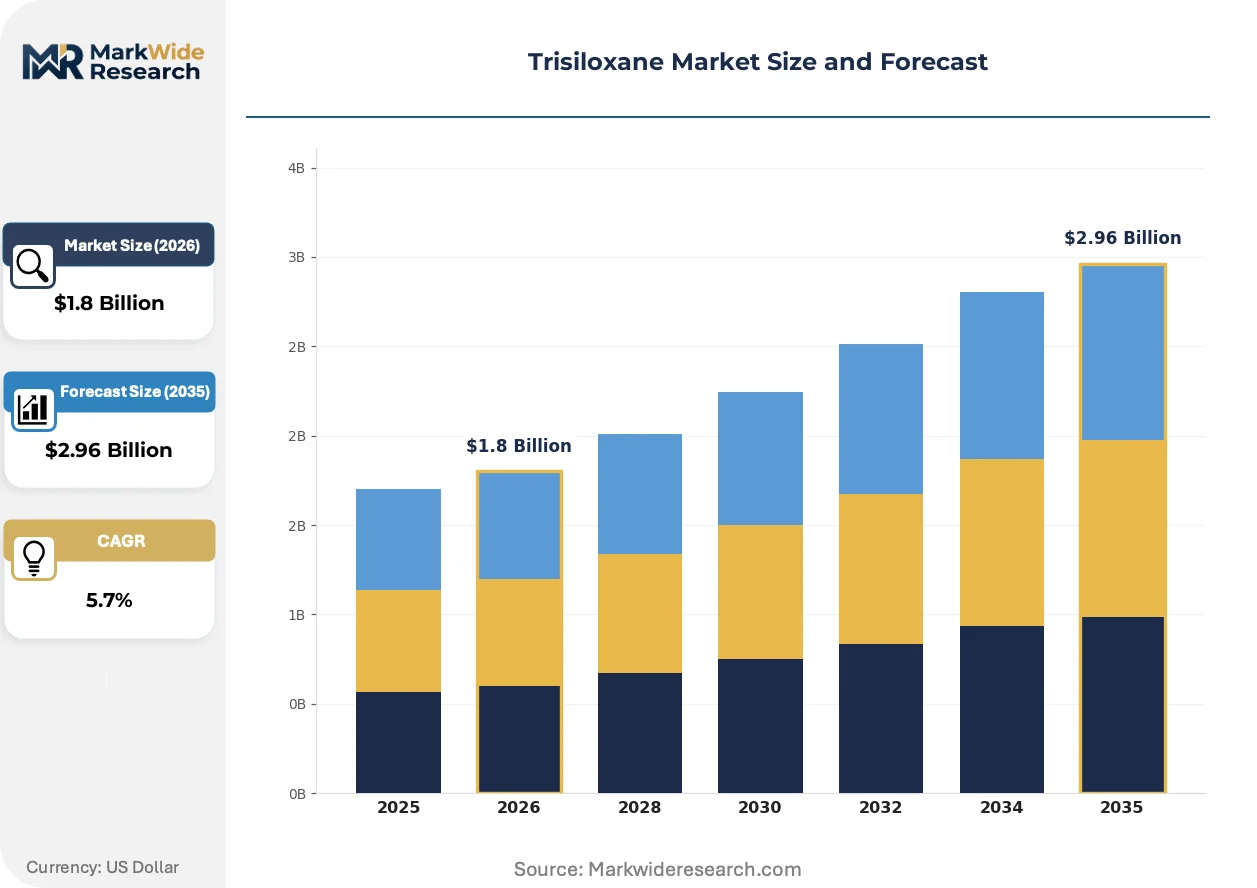
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Emulsions, Siloxane Resins, Modified Silicones, Trisiloxane Compounds Application: Coatings, Personal Care, Agriculture, Textiles End User: Consumer Goods, Industrial, Pharmaceuticals, Automotive Form: Liquid, Gel, Powder, Solid |
| Companies Covered | Dow Inc., Momentive Performance Materials, Wacker Chemie AG, Evonik Industries AG, Shin-Etsu Chemical Co., Ltd., Jiangxi Hito Chemical, Wuhan Kemi-Works Chemical, Zhejiang Runhe Chemical New Material, Elkem ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trisiloxane Market Evolving Landscape
Formulation chemistry is pivoting toward hydrolytic stability as aqueous concentrate pesticide systems displace emulsifiable concentrate formats. Molecular engineering of trisiloxane backbones now prioritizes pH tolerance and tank-mix longevity over spreading coefficient maximization alone.
Alkoxysilane-modified trisiloxane surfactants are converging with aqueous suspension concentrate formulations in North American row-crop applications. Bayer CropScience and Corteva Agriscience procurement teams specify these variants for glyphosate-tolerant soybean programs where tank-mix stability extends beyond 24 hours. The technology is converging with precision application equipment requirements, compressing demand for conventional silicone emulsions that separate under high-shear nozzle conditions.
EPA's pending reassessment of inert ingredient tolerances under FIFRA Section 3 is forcing reformulation of legacy agricultural adjuvant registrations. The agency's 2024 guidance on organosilicone surfactant ecotoxicity endpoints requires chronic aquatic toxicity data not previously mandated, affecting trisiloxane molecular weight distributions above 600 daltons. Midwestern formulators with existing EPA product registrations face 18-24 month data generation timelines to maintain market access.
Certification-driven procurement is reshaping European personal care silicone sourcing as the EU Green Deal's chemical sustainability criteria propagate through retailer scorecards. German and French cosmetic brands now require trisiloxane suppliers to demonstrate renewable feedstock fractions and cradle-to-gate carbon footprints, displacing conventional spot-market purchasing. This pattern concentrates contract volumes with integrated producers possessing lifecycle assessment documentation capabilities.
Trisiloxane Market Segmentation
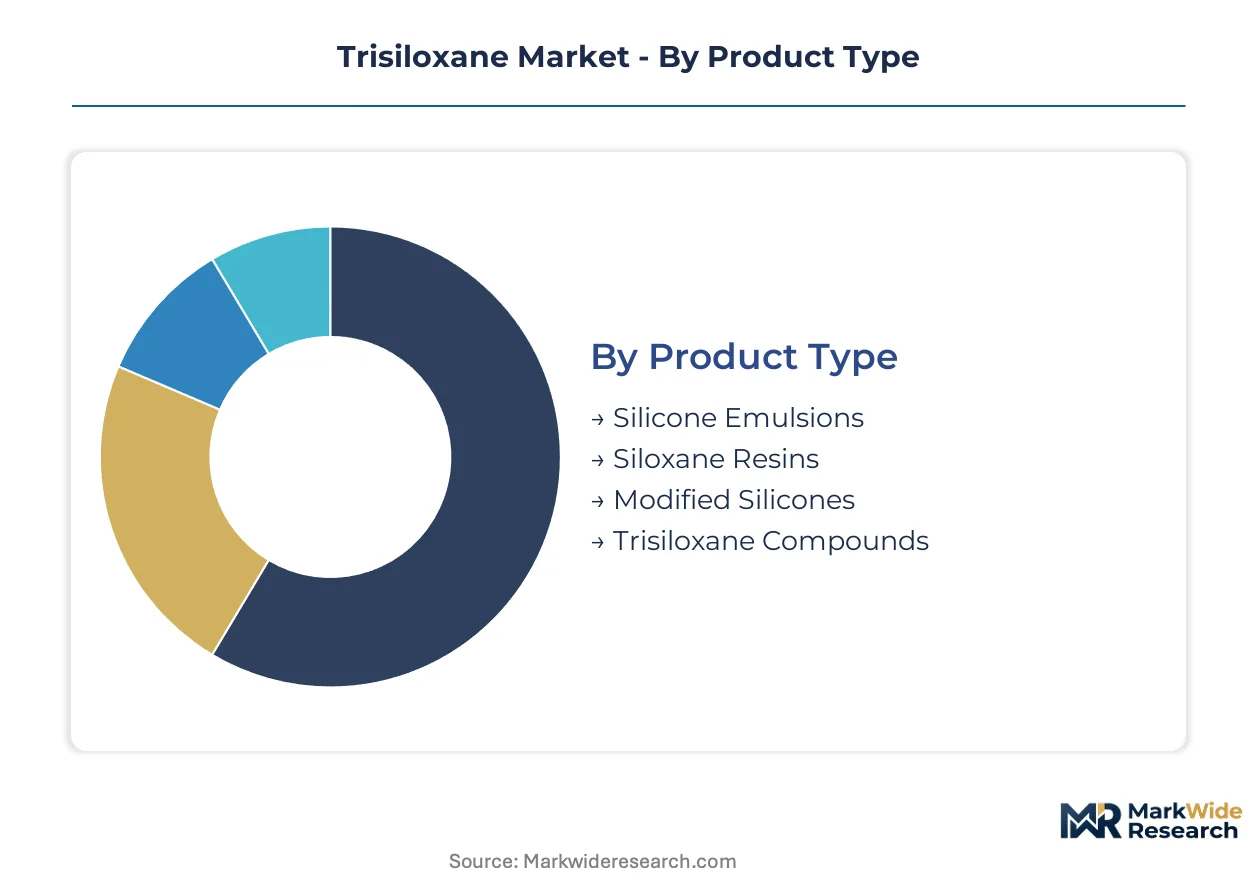
Trisiloxane market segmentation reveals distinct capital requirements across product categories. Silicone emulsion production demands continuous emulsification infrastructure, while modified silicone development requires dedicated R&D investment in hydrolytic stability chemistry.
Product Type:
Silicone emulsions absorb the heaviest upfront capital due to high-shear processing equipment and sterile packaging lines for agricultural tank-mix compatibility.
- Silicone Emulsions:Aqueous dispersions of trisiloxane surfactants stabilized with nonionic emulsifiers, typically 50-80% active content. Brazilian soybean growers and US corn belt operators specify these for glyphosate-tolerant crop programs where coverage uniformity determines yield protection. EPA FIFRA registration requirements lock formulators into 18-24 month validation cycles.
- Modified Silicones:Alkoxysilane-functionalized or polyether-capped variants engineered for pH stability in aqueous pesticide concentrates. Korean and Japanese cosmetic formulators source these for water-based sun care replacing cyclic siloxanes under EU Green Deal retailer scorecards. Hydrolytic stability testing extends development timelines.
- Siloxane Resins:Crosslinked polysiloxane networks requiring thermal curing infrastructure. Industrial coating applications in automotive clearcoats drive specification.
- Trisiloxane Compounds:Pure MDM oligomers supplied neat for downstream formulation. Pharmaceutical solid-dose applications command premium positioning.
Most installed capacity flows through Silicone Emulsions. Expansion is steepest in Modified Silicones.
Application:
Agricultural adjuvant applications concentrate volume throughput, while personal care commands margin premiums through certification-driven procurement.
- Agriculture:Superwetting agents in pesticide tank mixes enabling sub-1% application rates. Brazilian and US farmers deploy these for resistant pest management. REACH compliance in Europe restricts import competition.
- Personal Care:Emollient and spreading agents in skin care, sun care, and color cosmetics. German and French brands now mandate renewable feedstock fractions and cradle-to-gate carbon documentation.
- Coatings:Flow and leveling additives in industrial and automotive finishes. Surface tension reduction properties enable thin-film application.
- Textiles:Softening agents and water repellents in fabric finishing. Performance specifications vary by fiber substrate.
Agriculture anchors volume throughput. Personal care generates the steepest margin expansion.
End User:
Industrial procurement emphasizes tank-mix compatibility libraries, while pharmaceutical qualification demands ISO 17025 analytical certification.
- Industrial:Agricultural chemical formulators and coating manufacturers purchasing bulk silicone emulsions. Dow Inc. and Momentive Performance Materials maintain extensive pesticide formulation compatibility databases.
- Consumer Goods:Cosmetic and personal care brands specifying hydrolytically stable variants. Clean beauty certification schemes displace conventional spot-market purchasing.
- Pharmaceuticals:Solid-dose and topical formulation manufacturers requiring powder-grade trisiloxane with documented purity. Cyclic siloxane contamination thresholds from ECHA restrict supplier qualification.
- Automotive:OEM coating operations and aftermarket refinishing suppliers. Surface quality specifications drive technical service requirements.
Industrial channels absorb the majority of silicone emulsion output. Pharmaceutical qualification timelines create the steepest entry barriers.
Form:
Liquid formulations dominate capital deployment through continuous processing infrastructure, while powder production requires spray-drying or micronization assets.
- Liquid:Neat oils, aqueous emulsions, and solvent-based solutions. Agricultural tank-mix adjuvants and personal care emulsions flow through this form. High-shear processing and sterile filtration equipment lock in capital intensity.
- Gel:Thickened silicone preparations for controlled-release applications. Personal care anhydrous formulations utilize gelled trisiloxane carriers.
- Powder:Spray-dried or mechanically micronized solid grades. Pharmaceutical tablet lubrication and powder cosmetic applications require documented particle size distribution.
- Solid:Pelletized or flaked silicone preparations for polymer compounding. Masterbatch production for textile fiber modification.
Liquid form commands the majority of installed capacity. Powder grades generate the steepest per-kilogram pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized organosilicon synthesis expertise concentrates in legacy German and Japanese chemical clusters, creating regional capability asymmetries that shape competitive positioning across major production zones.
United States
Brazilian and domestic soybean growers drive agricultural adjuvant consumption through glyphosate-tolerant crop programs. EPA FIFRA registration requirements enforce 18-24 month validation cycles for tank-mix formulations. Midwestern formulators in Illinois and Iowa maintain extensive pesticide compatibility libraries for physical stability verification.
Germany
REACH substance registration mandates favor established registrants with existing toxicity dossiers, creating competitive moats against commodity importers. ECHA restrictions on cyclic siloxane residues force costly purification retrofits on legacy distillation infrastructure. Bavarian chemical complexes anchor European chlorosilane production with captive feedstock integration.
China
Domestic silicone production capacity expansion and crop protection chemical output growth concentrate demand in eastern manufacturing zones. MEE emission standards on silicone monomer plants constrain upstream supply elasticity during environmental compliance inspections. Qinghai-Xinjiang metallurgical-grade silicon smelter complexes expose downstream producers to regional power rationing risks.
Brazil
Farmers deploy trisiloxane-enhanced tank mixes to achieve pesticide coverage at sub-1% application rates against resistant pest populations. ANVISA pesticide registration timelines for adjuvant co-formulations create regulatory navigation requirements for imported silicone emulsions. São Paulo state agricultural chemical distributors specify superwetting agents for precision farming protocols.
Japan
Cosmetic formulators seek hydrolytically stable trisiloxane variants for water-based sun care replacing volatile cyclic silicones under clean beauty certification pressure. METI industrial standards govern silicone surfactant purity specifications for personal care applications. Osaka-Kobe chemical industry clusters specialize in pharmaceutical-grade siloxane production for solid-dose applications.
Trisiloxane Market Competitive Landscape
The competitive structure tilts toward integrated chlorosilane producers capable of absorbing regulatory compliance costs without margin compression. Market participation fragments between multinational silicone majors with captive feedstock positions and regional Chinese manufacturers leveraging domestic metallurgical silicon access. Three archetypes dominate: integrated petrochemical-silicone conglomerates, agricultural adjuvant specialists, and Asia-Pacific cost-optimized producers. Capacity expansion and REACH dossier consolidation represent the dominant competitive moves as registration barriers rise.
Within the integrated multinational tier, Dow Inc., Momentive Performance Materials, and Wacker Chemie AG exemplify positioning through upstream chemical infrastructure control. These entities anchor their competitive stance through captive chlorosilane supply and existing regulatory compliance documentation. Chinese manufacturers including Jiangxi Hito Chemical and Zhejiang Runhe Chemical New Material occupy a distinct cost-optimized tier, leveraging proximity to Qinghai-Xinjiang silicon metal production and domestic crop protection chemical growth. Shin-Etsu Chemical Co., Ltd. represents Japanese specialization in high-purity grades for personal care and pharmaceutical qualification requirements.
| Leading Market Players |
|---|
| Dow Inc. |
| Momentive Performance Materials |
| Wacker Chemie AG |
| Evonik Industries AG |
| Shin-Etsu Chemical Co., Ltd. |
| Jiangxi Hito Chemical |
| Wuhan Kemi-Works Chemical |
| Zhejiang Runhe Chemical New Material |
| Elkem ASA |
| Others |
Value Network & Pricing Analysis
Methyl chloride feedstock costs transmit directly from natural gas pricing into dimethylchlorosilane cost structures, cascading through chlorosilane producers to trisiloxane formulators and ultimately separating agricultural adjuvant buyers into premium-certified and spot-market tiers.
Pricing Analysis
Bundled technical service and tank-mix compatibility testing commands premium positioning over unbundled commodity silicone emulsion supply. Price differentiation hinges on REACH dossier completeness and ISO 17025 analytical certification status. Pricing pressure stems from Chinese domestic capacity expansion eroding spot-market realizations. Agricultural formulators in Brazil and the United States exhibit highest price sensitivity, while pharmaceutical qualification buyers accept steep premiums for documented cyclic siloxane purity.
Supply Chain Analysis
Dual-sourcing requirements from Bayer CropScience and Corteva Agriscience procurement teams mandate multi-supplier qualification for agricultural adjuvant grades. Supply concentrates in China, Germany, and the United States, with captive chlorosilane integration at Dow Inc. and Wacker Chemie AG anchoring European and North American positions. Raw material dependencies encompass metallurgical-grade silicon metal from Qinghai-Xinjiang smelters, methyl chloride from chlor-alkali operations, and platinum catalysts for hydrosilylation. Tariff exposure on Chinese silicone emulsion imports into Brazil creates supply chain risk. Distribution runs through agricultural chemical distributors in São Paulo state and Midwestern US formulator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in hydrolytically stable modified silicone grades, where clean beauty certification requirements and EPA FIFRA registration barriers sustain premium capture against commodity emulsion alternatives.
For Market Incumbents: Cement defensive positioning through captive chlorosilane supply integration and REACH dossier consolidation. Dow Inc. and Momentive Performance Materials absorb compliance cost burdens that crush commodity importer margins. Prioritize backward integration into Qinghai-Xinjiang silicon metal sourcing to offset power rationing risk.
For New Entrants and Emerging Players: Enter via India's accelerating adjuvant registration timelines, where fragmented farm sizes create premium penetration for spreading-enhancing agents. Target personal care emulsion upgrading in Korea and Japan as cyclic silicone displacement accelerates. Pursue toll manufacturing partnerships with established EPA registrants to bypass 18-24 month validation cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and cyclic siloxane purification retrofits burden aged European fixed-asset bases. Long-term viability favors integrated producers with lifecycle assessment documentation capabilities. Target acquisition archetype: mid-cap German or Japanese formulators with existing ECHA dossiers and retiring organosilicon synthesis expertise. Signal to watch: EPA FIFRA Section 3 reassessment outcomes on organosilicone surfactant ecotoxicity endpoints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Supply | Dow Inc. and Wacker Chemie AG absorb REACH compliance costs without margin compression. |
| Modified Silicone R&D Investment | Hydrolytic stability chemistry unlocks Korean and Japanese personal care premium positioning. |
| India Market Entry Partnership | Central pesticide regulator acceleration opens access to fragmented farm size premium demand. |
| ISO 17025 Analytical Certification | Third-party validation queues create 12-18 month competitive moats for qualified suppliers. |
| Long-term Supply Agreement with Qinghai-Xinjiang Smelters | Captive metallurgical silicon sourcing mitigates regional power rationing exposure. |
Research Methodology
Direct dialogue with agricultural chemical formulators, cosmetic R&D directors, chlorosilane plant managers, and EPA registration consultants grounded qualitative assessment. Secondary validation drew from ECHA REACH dossier databases, SEC 10-K silicone segment disclosures, China customs export statistics, and ANVISA pesticide registration filings. Bottom-up triangulation across product-grade volume estimates and top-down cross-check against end-use consumption patterns ensured analytical coherence.
Segmentation outputs across silicone emulsion, modified silicone, and trisiloxane compound grades were modeled over the projection horizon. Application-level splits for agriculture, personal care, coatings, and textiles incorporated end-use growth differentials. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact assessment. Key inputs encompassed methyl chloride cost pass-through elasticity, REACH registration status by supplier, and EPA FIFRA reassessment timeline assumptions.
Inputs from ECHA registration databases and China MEE emission compliance records were available through the study window; gaps in real-time Qinghai-Xinjiang power rationing frequency introduce uncertainty bands around Chinese supply elasticity assumptions. Deviation in EPA organosilicone surfactant ecotoxicity endpoint determinations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Detergent Polymers Market
Surfactants
Sodium Lauryl Sulphate Market
Surfactants
Global Oilfield Surfactants Market
Surfactants
TEA Esterquats Market
Surfactants
Acrylamide Tertiary-Butyl Sulfonic Acid (ATBS) Market
Surfactants
Global Demulsifiers Market
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Global Methyl Soyate Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Detergent Grade Zeolite Market
Surfactants
Soy-Based Surfactants Market
Surfactants
Disodium Laureth Sulfosuccinate Market
Surfactants
Sulfate Free Body Wash Market
Surfactants
Dioctyl Sulfosuccinates Components Market
Surfactants
Global Sodium Lauryl Sulfate Market