
 Specialty Surfactants Market | 2026-2036
Specialty Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Surfactants Market Intelligence
Formulation support and regulatory compliance services are realigning how specialty surfactants are sold, moving transactions beyond pure product sales to integrated customer partnerships. This shift favors large, diversified chemical producers. For instance, BASF SE leverages its extensive research and development capabilities to offer custom solutions for complex applications. Stepan Company specializes in a broad portfolio of anionic surfactants for the detergent and cleaning industries. Meanwhile, Evonik Industries AG differentiates with its high-performance silicone-based and amphoteric surfactants for personal care and industrial coatings.
Specialty surfactants are a class of surface-active agents engineered for specific, high-value functions not achievable with commodity surfactants. These molecules possess complex structures, such as polymeric or silicone-based backbones, which provide unique properties like superior emulsification, low-foaming characteristics, or extreme pH stability. Their primary purpose is to modify surface or interfacial tension in formulations for industries from personal care to oilfield chemicals. Demand for nonionic and amphoteric product types is strong, particularly for use in mild personal care formulations. The agrochemicals application segment requires advanced surfactants to improve the efficacy and bioavailability of active ingredients.
The market operates under stringent regulatory oversight from bodies like the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA). Regulations such as REACH in Europe and the Toxic Substances Control Act (TSCA) in the United States dictate chemical registration, evaluation, and authorization, directly impacting product development and market access. Future competitive advantage will hinge on a manufacturer's ability to innovate sustainable, bio-based alternatives that comply with evolving environmental and safety standards across key global markets.
Market Dynamics
The market's central dynamic is the tension between performance requirements and escalating regulatory pressure for sustainable, non-toxic chemical solutions. This force compels manufacturers to innovate beyond traditional petrochemical feedstocks, driving investment in bio-based and biodegradable surfactant chemistries to maintain market access.
Growth Catalysts
- Bio-based Formulations:Consumer demand for milder products in the personal care sector, reinforced by regulations like the EU's REACH, accelerates the shift toward surfactants derived from renewable resources like plant oils and sugars.
- Agrochemical Efficacy:The agrochemicals industry requires advanced surfactant systems to enhance the spreading, wetting, and absorption of pesticide and herbicide active ingredients, improving crop yields and reducing environmental runoff.
- Industrialization in Asia:China's massive industrial base, particularly in textiles, cleaning products, and general manufacturing, creates concentrated and large-scale demand for a wide array of functional specialty surfactants.
Market Restraints
- Feedstock Price Volatility:The costs of key raw materials, including vegetable oils and petrochemical derivatives like ethylene oxide, are subject to significant price fluctuations, impacting manufacturer margins and pricing stability.
- Stringent Regulatory Hurdles:Gaining approval for new chemical entities under frameworks like the US EPA's Toxic Substances Control Act (TSCA) involves lengthy and costly toxicological testing, slowing the pace of innovation.
- Threat of Substitution:In less demanding applications, there is a persistent threat from lower-cost commodity surfactants or blends that can be optimized to approximate the performance of more expensive specialty products.
Strategic Opportunities
- Enhanced Oil Recovery (EOR):Development of robust, high-performance biosurfactants for EOR applications presents a significant opportunity, as these can improve oil extraction efficiency in mature fields while meeting environmental standards.
- Personal Care in Southeast Asia:The expanding middle class and growing manufacturing base in countries like Indonesia and Vietnam offer an underpenetrated market for specialty surfactants in cosmetics and home care products.
- Digital R&D Platforms:Leveraging AI and high-throughput screening allows for the rapid design and testing of novel surfactant molecules, enabling the creation of custom solutions for niche industrial problems in electronics or coatings.
Industry Challenges
- Global Regulatory Divergence:Manufacturers face significant complexity and cost in developing formulations that comply with disparate and evolving environmental and safety standards across Europe, North America, and Asia.
- High Capital Expenditure:The transition to bio-based production requires substantial investment in new manufacturing infrastructure, such as fermentation capacity and downstream processing, which presents a barrier for many firms.
- Formulation Expertise Scarcity:A shortage of experienced formulation chemists who can effectively integrate novel bio-surfactants into complex end-products while meeting performance and stability targets limits adoption rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Surfactants Market |
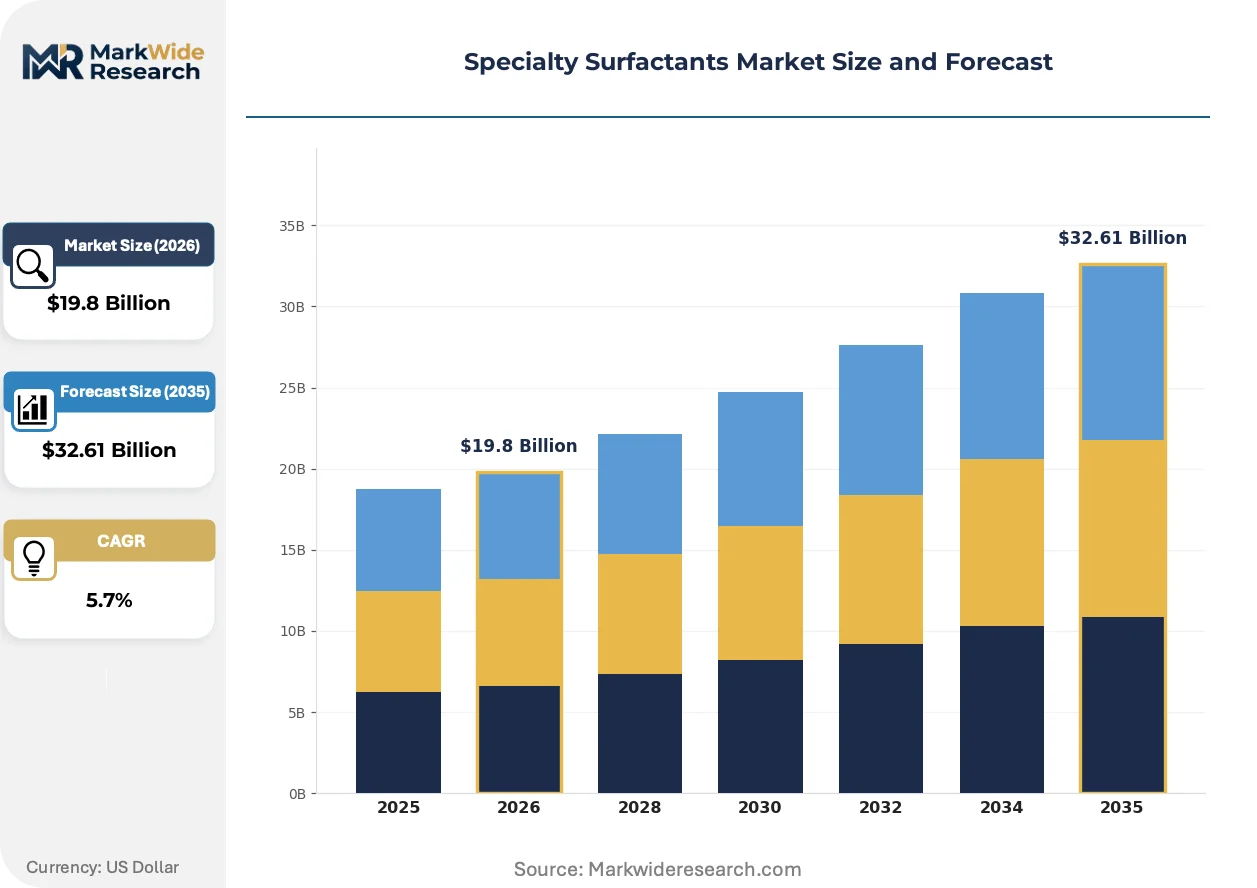
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $32.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anionic, Cationic, Nonionic, Amphoteric, Silicone-based, Polymer-based Application: Personal Care, Agrochemicals, Paints & Coatings, Textile Processing, Oilfield Chemicals, Detergents End User: Manufacturers, Formulators, Industrial Cleaners, Chemical Distributors, Research Laboratories Packaging Type: Drums, Bulk Containers, Bags, Totes, Carboys, Intermediate Bulk Containers |
| Companies Covered | BASF SE, Dow, 3M, Stepan Company, Kao Corporation, Evonik Industries AG, Clariant, Croda International Plc, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Surfactants Market Strategic Shifts & Innovations
The market is defined by a fundamental re-evaluation of the surfactant life cycle, from feedstock sourcing to end-of-life biodegradability. This sustainability-driven imperative is pushing innovation toward novel molecular structures and integrated service models that deliver both performance and compliance.
High-throughput screening (HTS) combined with computational modeling allows for the rapid design of novel surfactant molecules. R&D teams at major chemical producers are the primary adopters, targeting high-value uses in pharmaceuticals and industrial coatings where precise functionality is critical. This data-driven discovery process is consolidating the innovation advantage with larger firms, creating a significant barrier to entry for smaller competitors focused on traditional chemistry.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a key regulatory driver with far-reaching effects. It mandates extensive disclosure on the environmental impact of supply chains, directly impacting chemical suppliers. This affects producers selling into the EU market most acutely, forcing them to provide verifiable life-cycle assessment data and prioritize surfactants with lower carbon footprints and improved circularity.
A definitive shift from transactional product sales to integrated "formulation-as-a-service" models is altering customer relationships. This change disrupts the traditional distributor channel, replacing it with direct, collaborative partnerships where suppliers provide ongoing technical and regulatory support. This trend is most visible in the complex personal care and agrochemical industries, where final product efficacy hinges on sophisticated surfactant system interactions.
Specialty Surfactants Market Segmentation
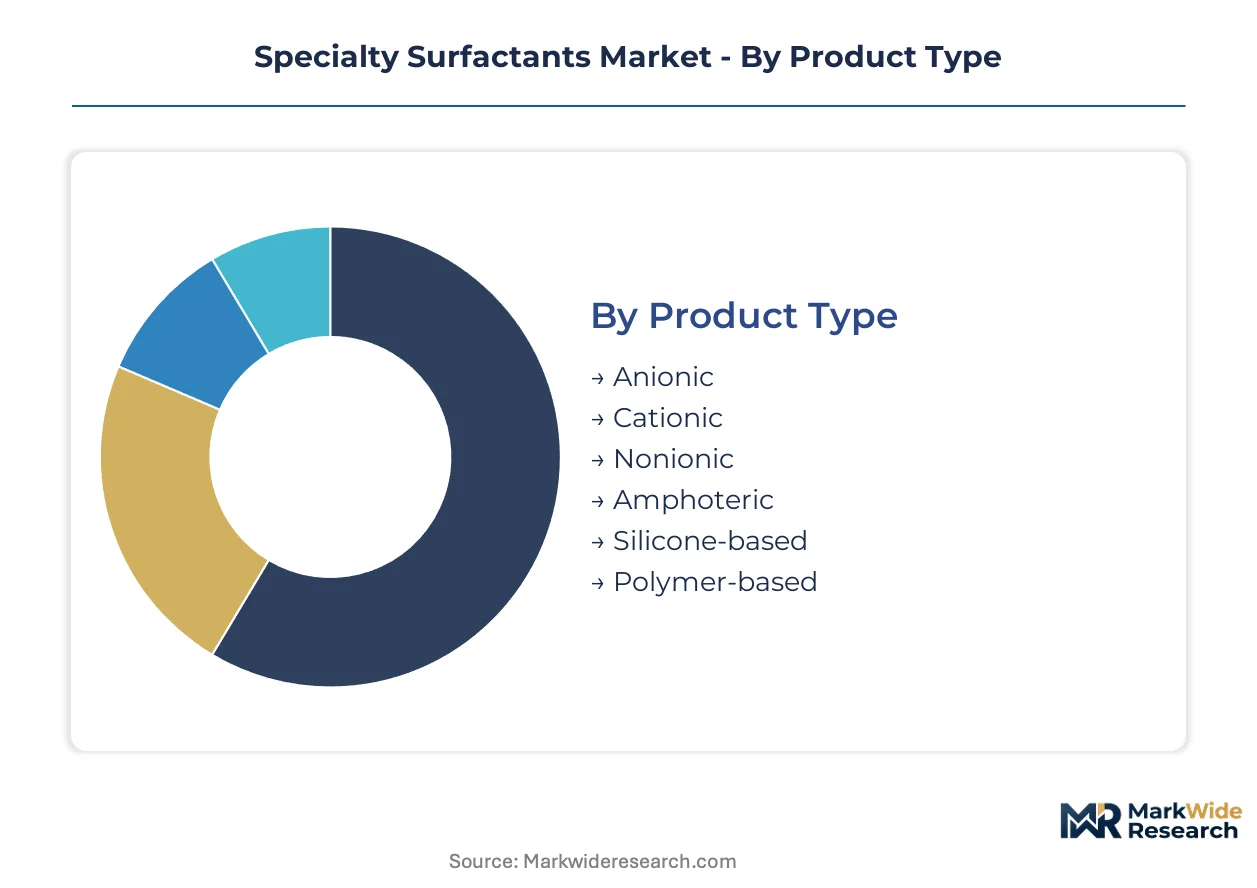
The specialty surfactants market categorizes products and applications based on their unique chemical properties and intended industrial functions. Understanding these distinct segments is crucial for manufacturers to tailor solutions effectively and for end-users to optimize formulation performance. This granular segmentation highlights specific demand pockets and technological advancements across diverse industries.
Product Type:
Buyers prioritize specific product types based on the required surface-active properties for their formulations, driving distinct demand patterns across the market.
- Nonionic:These surfactants do not ionize in solution, offering excellent compatibility with other surfactant types and stability across a wide pH range. Demand concentrates in personal care and industrial cleaning for mildness and emulsifying properties.
- Amphoteric:Amphoteric surfactants possess both positive and negative charges, making them pH-sensitive and exceptionally mild, often used as co-surfactants to reduce irritation. Personal care products, particularly shampoos and body washes, drive their consumption due to consumer preference for gentle formulations.
- Anionic:Anionic surfactants carry a negative charge, providing strong foaming and cleaning capabilities, widely utilized in detergents and household cleaners.
- Cationic:Cationic surfactants have a positive charge, offering conditioning, antistatic, and antimicrobial properties, essential for fabric softeners and hair conditioners.
- Silicone-based:These surfactants incorporate silicone backbones, delivering unique surface modification, defoaming, and spreading characteristics for coatings and personal care.
- Polymer-based:Polymer-based surfactants are macromolecules with surface-active properties, providing superior stabilization and rheology modification in complex formulations.
Volume sits with Anionic surfactants; growth tilts toward Amphoteric products.
Application:
Market demand for specialty surfactants is heavily influenced by the specific functional needs of various industrial applications.
- Personal Care:This segment encompasses cosmetics, toiletries, and dermatological products, where specialty surfactants deliver mild cleansing, emulsification, and foam stabilization. Consumer preference for bio-based and gentle formulations significantly shapes product development within this category.
- Agrochemicals:Surfactants in this sector improve the efficacy of pesticides, herbicides, and fertilizers by enhancing wetting, spreading, and penetration of active ingredients. Advanced formulations are critical for optimizing crop yield and minimizing environmental impact.
- Paints & Coatings:Specialty surfactants function as wetting agents, dispersants, and emulsifiers, ensuring pigment stability, surface leveling, and film formation in various coating systems.
- Textile Processing:These agents are crucial for scouring, dyeing, and finishing operations in the textile industry, improving fabric wettability and dye uptake.
- Oilfield Chemicals:Surfactants enhance oil recovery processes, drilling fluid performance, and corrosion inhibition in the exploration and production of oil and gas.
- Detergents:Specialty surfactants provide targeted cleaning, degreasing, and foaming control for household, industrial, and institutional cleaning formulations.
Personal Care applications command the largest share, while Agrochemicals are expanding most quickly.
End User:
The type of end-user dictates the purchasing criteria and technical support requirements for specialty surfactants.
- Manufacturers:These entities integrate specialty surfactants directly into their final products, such as consumer goods, industrial chemicals, or pharmaceuticals. Their purchasing decisions are driven by performance specifications, cost-efficiency, and regulatory compliance.
- Formulators:Formulators specialize in creating custom blends and solutions, often requiring a diverse range of specialty surfactants to achieve specific functional attributes. They seek technical expertise and a broad product portfolio from suppliers.
- Industrial Cleaners:This segment uses specialty surfactants in large volumes for heavy-duty cleaning and maintenance applications across various industrial settings.
- Chemical Distributors:Distributors act as intermediaries, supplying specialty surfactants to smaller manufacturers and formulators who may not purchase directly from producers.
- Research Laboratories:Laboratories utilize specialty surfactants for R&D, product testing, and analytical purposes, often requiring small quantities of highly specialized or novel chemistries.
Manufacturers represent the largest consumer base; Formulators are gaining share for custom solutions.
Packaging Type:
The scale and logistics of procurement influence the preferred packaging format for specialty surfactants.
- Bulk Containers:These large-capacity containers, such as tank trucks or rail cars, are used for high-volume industrial clients requiring continuous supply. They offer cost efficiencies for transportation and handling of liquid surfactants.
- Intermediate Bulk Containers:IBCs are reusable, multi-trip containers designed for transporting and storing bulk liquids or powders, bridging the gap between drums and full bulk shipments. Their stackability and ease of handling make them suitable for mid-to-large scale users.
- Drums:Drums are standard cylindrical containers, typically 55-gallon, used for shipping liquid specialty surfactants to mid-sized industrial users or for smaller batch productions.
- Bags:Bags are primarily used for powdered or granular specialty surfactants, offering convenient storage and handling for dry formulations.
- Totes:Totes are smaller, often rigid plastic containers, suitable for smaller volumes or specialized liquid products where drums are too large.
- Carboys:Carboys are rigid plastic or glass containers, typically 5 to 15 gallons, used for transporting smaller quantities of highly specialized or hazardous liquid surfactants.
Bulk Containers dominate large-scale industrial procurement, with Intermediate Bulk Containers seeing increased adoption for efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global specialty surfactants market exhibits a clear divide between major production centers and burgeoning consumption hubs. While established chemical industries in Europe and North America drive innovation, demand concentration within China's expansive industrial base significantly influences regional market dynamics. This creates a complex interplay of supply chain optimization and localized formulation development.
China
China's extensive industrial chemical and consumer goods manufacturing base drives immense demand for specialty surfactants. The country's dual carbon goals push manufacturers toward greener chemistries, impacting product development. Industrial clusters like the Yangtze River Delta actively integrate advanced surfactants into textiles, cleaning products, and personal care formulations.
Germany
Germany remains a key innovation hub for specialty surfactants, particularly for high-performance applications in personal care and industrial coatings. The EU's REACH regulation heavily influences product development, emphasizing safer and more sustainable alternatives. Major chemical producers in the Rhine-Main area, such as BASF SE, consistently introduce novel bio-based and silicone-based solutions.
United States
The United States market demonstrates robust demand across personal care, agrochemicals, and oilfield chemicals due to its diverse industrial landscape. The US Environmental Protection Agency (EPA) and the Toxic Substances Control Act (TSCA) dictate stringent approval processes for new chemical entities. The Gulf Coast region, with its petrochemical infrastructure, continues to be a significant production and consumption center for various specialty surfactants.
India
India's expanding middle class and growing manufacturing sector fuel demand for specialty surfactants in personal care, detergents, and agrochemicals. BIS standards guide product quality and safety, encouraging local production of compliant materials. Chemical manufacturing hubs like Gujarat are witnessing increased investment in surfactant production facilities to cater to domestic and regional needs.
Brazil
Brazil's large agricultural sector and a growing personal care market create substantial demand for specialty surfactants. Regulations from ANVISA for cosmetics and health products influence formulation choices, favoring milder ingredients. The industrial heartland of São Paulo state serves as a primary hub for chemical production and formulation, supporting both agricultural and consumer goods industries.
Specialty Surfactants Market Key Industry Players
Capital-heavy producers compete with asset-light formulators in the specialty surfactants market, creating a diversified competitive structure. Large, integrated chemical companies dominate the upstream production of complex molecules. Niche specialists differentiate through proprietary technologies and customized solutions for specific high-value applications. Strategic partnerships and continuous R&D investment in sustainable chemistry represent dominant competitive moves.
Large, diversified chemical producers like BASF SE leverage extensive research and development capabilities to offer custom solutions for complex applications. Stepan Company occupies a strong position within the broad portfolio of anionic surfactants for the detergent and cleaning industries. Evonik Industries AG exemplifies a focus on high-performance silicone-based and amphoteric surfactants for personal care and industrial coatings, representing a specialization-driven archetype.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| 3M |
| Stepan Company |
| Kao Corporation |
| Evonik Industries AG |
| Clariant |
| Croda International Plc |
| Akzo Nobel N.V. |
| Others |
Cost & Logistics Intelligence
Large, integrated chemical companies leverage scale and R&D, influencing specialty surfactant supply behavior and maintaining pricing discipline. This structure impacts market access and innovation investment across various end-use sectors.
Pricing Analysis
Margin tightening in commodity-adjacent specialty surfactants reflects persistent feedstock price volatility. Pricing in this market often combines value-based models for custom solutions with contract-based agreements for high-volume products. Differentiation stems from customization level, superior performance tier, and comprehensive after-sales formulation support. Formulators exhibit lower price sensitivity for highly specialized molecules, while large manufacturers prioritize cost-efficiency for basic specialty grades.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke model characterize specialty surfactant distribution, balancing global production with localized delivery. Supply concentration originates from chemical manufacturing hubs in China, the United States, and Germany. The industry sources key raw materials from vegetable oils and petrochemical derivatives like ethylene oxide, with commodity price volatility presenting a significant structural risk. Distribution often runs through direct manufacturer sales for large accounts, supplemented by chemical distributors for smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty surfactants market is poised for consolidation, driven by stringent regulatory hurdles and high capital expenditure for bio-based production. This pressure forces smaller, less diversified players to exit or seek acquisition.
For Market Incumbents: To counter global regulatory divergence and feedstock price volatility, incumbents must deepen investment in digital R&D platforms. This allows for rapid design of novel bio-based surfactant molecules, ensuring compliance and performance. Securing long-term supply agreements for renewable raw materials also strengthens their competitive position. Strategic acquisitions of specialist firms with proprietary sustainable chemistries will further reinforce market leadership.
For New Entrants and Emerging Players: Capture underpenetrated segments by focusing on high-performance biosurfactants for Enhanced Oil Recovery (EOR) applications. The expanding middle-class personal care market in Southeast Asia also offers significant white-space opportunities. A strong go-to-market angle involves offering custom formulation-as-a-service, leveraging sustainability credentials and technical expertise. This approach allows new players to differentiate beyond traditional product sales.
For Investors and Strategic Acquirers: Distressed-cycle entries favor agile, technology-driven specialists in Europe and North America, especially those with strong bio-based IP. The long-term viability of this market rests on the sustainability imperative, ensuring consistent demand for compliant solutions over the next decade. Investors should target niche bio-based surfactant producers or firms excelling in digital R&D platforms. A key signal to watch is the accelerating pace of M&A activity within the sustainable chemistry sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint for producers and aids compliance with EU CSRD regulations for customers. |
| Long-term Bio-based Feedstock Agreements | Stabilizes raw material costs and ensures supply for sustainable personal care formulations. |
| Joint Ventures in Digital R&D | Accelerates novel surfactant molecule discovery for complex agrochemical applications. |
| Capacity Expansion for Amphoteric Surfactants | Meets rising consumer demand for mild personal care products in emerging Asian markets. |
| Acquisition of Niche Biosurfactant Producer | Integrates specialized technology for Enhanced Oil Recovery (EOR) into a broader product portfolio. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market insights. Primary interviews engaged R&D directors, procurement leads, formulation chemists, and regulatory affairs specialists across the value chain. This approach combined top-down market sizing with bottom-up validation of segment-specific demand. Corporate financial reports and scientific literature further corroborated market trends.
Market volume and value were modeled at a granular level across product type, application, end-user, and packaging format. Regional production hubs also informed the analysis over the projection horizon. Compound Annual Growth Rates (CAGRs) were derived from historical data and projected market drivers, including bio-based feedstock availability and regulatory approval timelines. This framework ensures robust and consistent market projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts and unforeseen feedstock supply disruptions. These forecasts reflect documented assumptions regarding market dynamics and technological advancements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Rhamnolipid Market
Surfactants
Alkylamines Market
Surfactants
Global Amphoteric Surfactants Market
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
TEA Esterquats Market
Surfactants
Selenium Sulphide Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Polymer Surfactants Market
Surfactants
Detergent Grade Zeolite Market
Surfactants
Global Biosurfactant Market
Surfactants
Micellar Water Market
Surfactants
Isopropyl Myristate Market
Surfactants
Wetting Agents Market
Surfactants
Cetyl Trimethyl Ammonium Chloride Market
Surfactants
Sodium Methyl Cocoyl Taurate Market