
 Nanoscale Chemicals and Materials Market | 2026-2036
Nanoscale Chemicals and Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoscale Chemicals and Materials Market Intelligence
A shift from single-source procurement toward multi-source partnerships for specialized nanomaterials is repositioning buyer-supplier relationships. Arkema leverages its extensive chemical portfolio to offer a broad range of functionalized nanomaterials. OCSiAl specializes in the mass production of single-wall carbon nanotubes, enabling large-scale industrial applications. Sumitomo Metal Mining focuses on high-purity metal-based nanoparticles for the electronics sector.
Nanoscale chemicals and materials encompass substances with at least one dimension between 1 and 100 nanometers, exhibiting unique quantum and surface area effects. These materials are engineered to enhance properties like conductivity, strength, and reactivity in commercial products. Nanoparticles command the largest market share due to their established use in various applications. Carbon nanotubes, particularly from the product type segment, represent a high-growth area driven by electronics and composites.
Regulatory oversight from bodies like the US EPA and the EU's ECHA under its REACH framework imposes strict data requirements for nanomaterial safety and registration. In China, the Ministry of Ecology and Environment (MEE) sets standards for material handling and disposal. These regulations directly influence market access and R&D costs. Stakeholder success will depend on navigating this complex and evolving international compliance landscape.
Market Dynamics
The market's central dynamic is the tension between rapid innovation in high-value sectors like electronics and the stringent, evolving regulatory frameworks governing nanomaterial safety. This friction shapes R&D investment, market access, and supply chain qualification processes globally.
Growth Catalysts
- Advanced Displays:The integration of quantum dots into next-generation televisions and mobile device screens by consumer electronics manufacturers enhances color accuracy and energy efficiency, pulling demand for specific nanoparticle types.
- Semiconductor Manufacturing:South Korea's and Taiwan's semiconductor industries require a steady supply of high-purity metal-based nanoparticles for advanced lithography and interconnect processes, creating a concentrated demand hub.
- Composite Materials:The aerospace and automotive sectors are incorporating carbon nanotubes and graphene into polymer composites to achieve significant weight reduction while improving mechanical strength and thermal conductivity.
Market Restraints
- Regulatory Compliance Costs:The European Union's REACH regulation imposes extensive and costly data generation requirements for nanomaterial registration, acting as a significant barrier to market entry for smaller producers.
- Dispersion and Stability Issues:Achieving uniform dispersion of nanoparticles within a host matrix remains a key technical hurdle, which can lead to inconsistent product performance and limit the full realization of material benefits.
- High Production Costs:The synthesis of high-purity materials, such as single-wall carbon nanotubes, involves complex, energy-intensive processes, restricting their use to applications where performance justifies the premium price.
Strategic Opportunities
- Next-Generation Energy Storage:The development of nanomaterials for use in electric vehicle batteries, such as silicon-based anodes or solid-state electrolytes, presents a significant opportunity to improve energy density and charging speeds.
- Biomedical Applications:Functionalized nanoparticles offer new pathways for targeted drug delivery and advanced medical imaging, with potential for streamlined regulatory review under frameworks from bodies like the US FDA.
- Sustainable Materials Development:There is a growing opportunity for nanocatalysts in green chemistry applications, including more efficient industrial processes and the breakdown of environmental pollutants, aligning with global sustainability goals.
Industry Challenges
- Standardization Gaps:A lack of globally harmonized metrology and characterization standards for nanomaterials complicates international trade and creates uncertainty for both producers and end-users regarding material specifications and safety.
- Scaling Production:Transitioning novel nanomaterial synthesis from laboratory-scale batches to consistent, high-volume industrial production requires substantial capital investment in specialized equipment and process controls.
- Workforce Expertise:A shortage of toxicologists, materials scientists, and process engineers with specific expertise in nanoscale science and safety assessment creates a bottleneck for R&D and regulatory compliance efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoscale Chemicals and Materials Market |
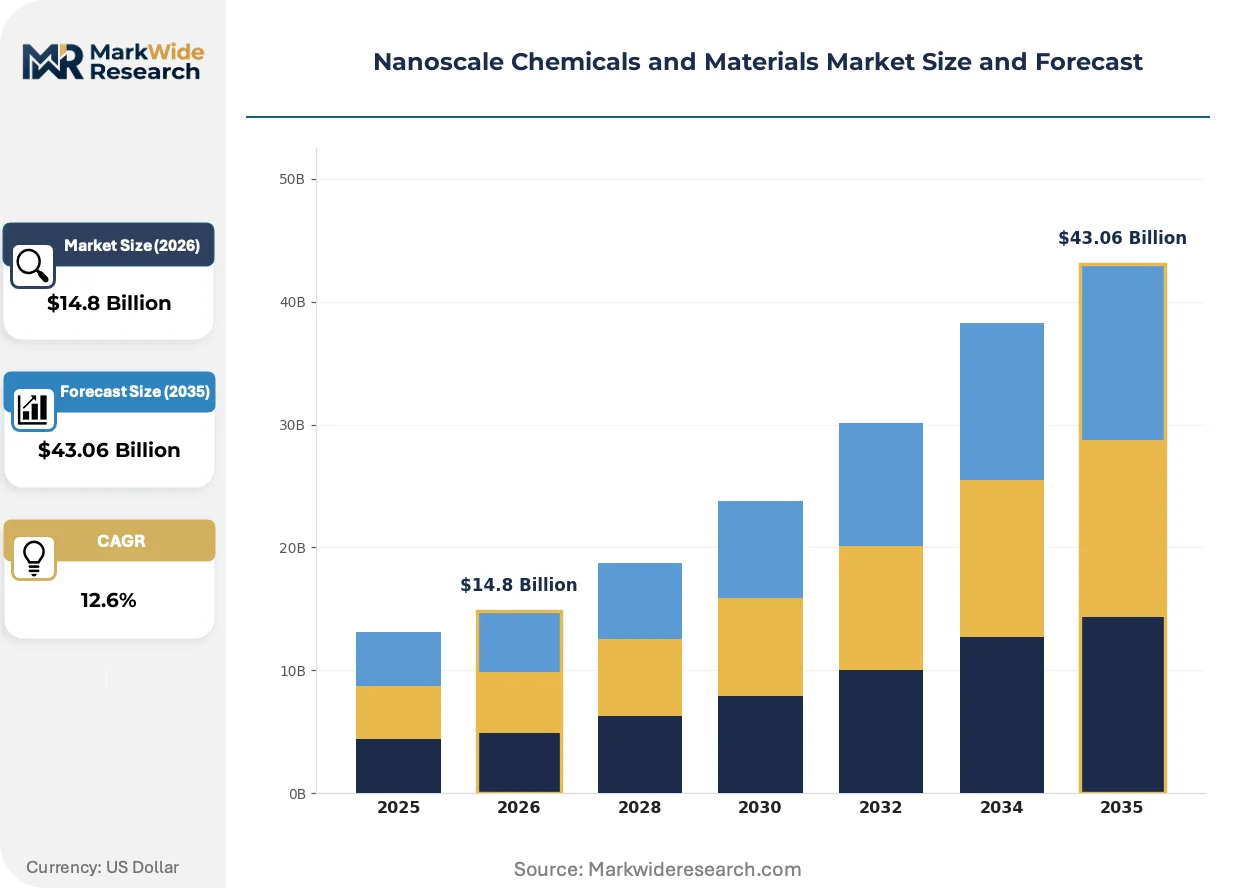
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $43.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanoparticles, Nanotubes, Quantum Dots, Nanowires, Fullerenes Grade: Technical, Electronic, Pharmaceutical, Catalytic, Cosmetic End Use Industry: Electronics Manufacturing, Renewable Energy, Pharmaceuticals, Cosmetics Production, Chemical Processing Packaging Type: Bulk Containers, Bottles, Sealed Pouches, Vials, Capsules |
| Companies Covered | Showa Denko, Zeon Nano Technology, Arkema, nanoComposix, Raymor Industries, Nanocyl, OCSiAl, Sumitomo Metal Mining, Cnano, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoscale Chemicals and Materials Market Strategic Shifts & Innovations
The industrialization of nanoscale materials defines the market's current trajectory. A shift is underway from laboratory novelties to qualified, mass-produced industrial inputs. This transition is governed by an intricate web of international safety, environmental, and end-use performance standards.
Mass-produced single-wall carbon nanotubes offer superior electrical conductivity and mechanical reinforcement compared to traditional additives. The electronics and automotive composites sectors are adopting these materials to create lighter, stronger, and more conductive components. Scalable production of these advanced nanotubes is overtaking the use of lower-performing, batch-produced specialty additives in high-volume industrial applications.
Regulations from China's Ministry of Ecology and Environment (MEE) mandate a rigorous registration process for new chemical substances, including all nanomaterials. This framework requires extensive data on toxicology and environmental fate before a product can be introduced to the Chinese market. Consequently, material developers are embedding safety-by-design principles into early-stage R&D to facilitate market access in this critical region.
A clear trend toward multi-supplier qualification for critical nanomaterials is evident among large end-users. This strategy mitigates supply chain risk associated with reliance on a single-source vendor, though it increases the complexity of quality assurance and supplier management. This pattern is most pronounced within the display and semiconductor industries in South Korea, where supply chain resilience is a primary operational focus.
Nanoscale Chemicals and Materials Market Segmentation
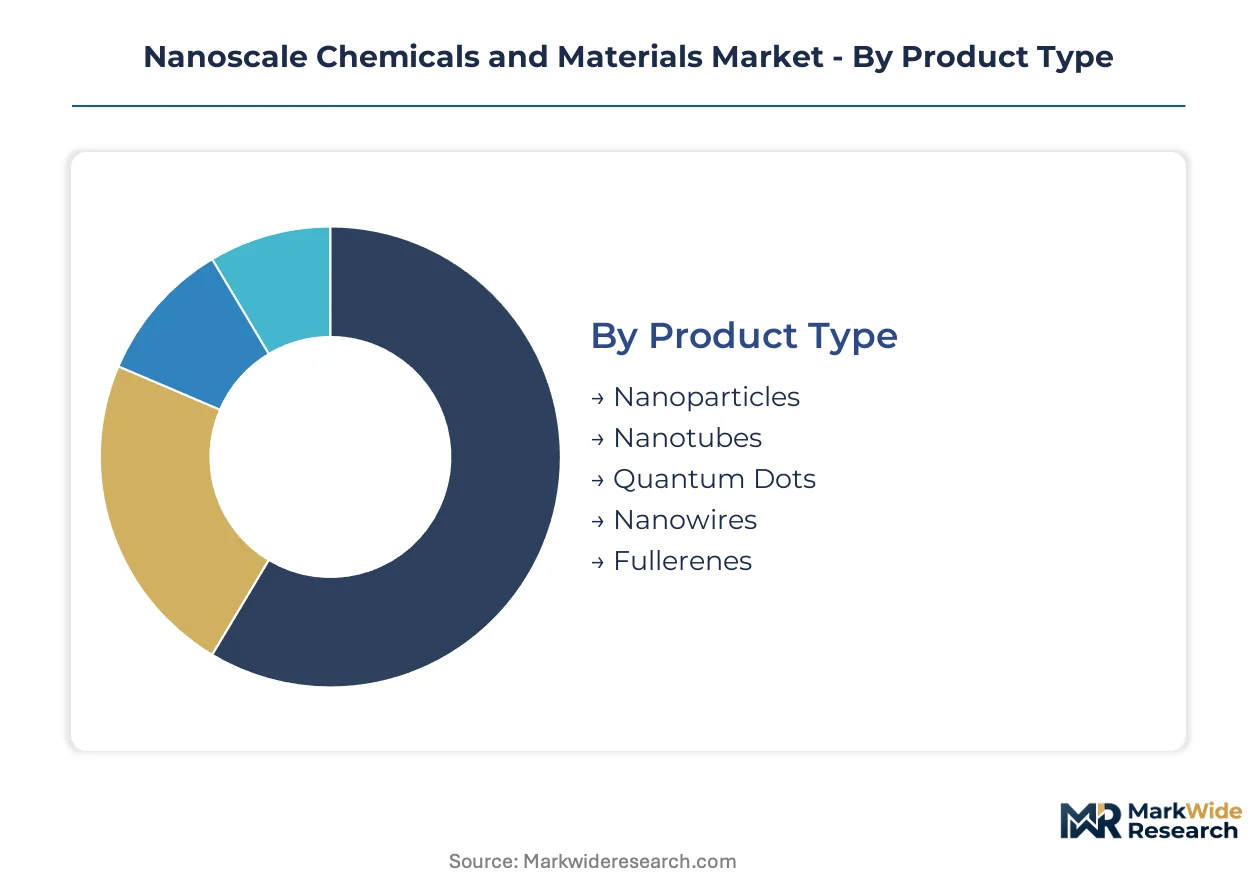
The segmentation of nanoscale chemicals and materials highlights the diverse applications and specific performance requirements across various industries. Understanding these distinct segments is crucial for manufacturers to tailor product development, navigate regulatory pathways, and optimize supply chain strategies for specialized inputs.
Product Type:
The certification burden for nanoscale materials varies significantly by product type, with regulatory bodies like the EU's ECHA and the US EPA scrutinizing different material classes based on their unique physiochemical properties and potential environmental interactions.
- Nanoparticles:Substances with at least one dimension between 1 and 100 nanometers, exhibiting enhanced surface area and quantum effects. Demand concentrates in electronics manufacturing, where they are integral for advanced components and display technologies.
- Nanotubes:Cylindrical carbon molecules with exceptional strength, electrical conductivity, and thermal stability. The automotive and aerospace sectors drive demand for their integration into lightweight, high-performance composite materials.
- Quantum Dots:Semiconductor nanocrystals that emit light at specific wavelengths when excited. Consumer electronics manufacturers utilize quantum dots for enhanced color reproduction in next-generation displays.
- Nanowires:Nanostructures with diameters on the order of a nanometer and unconstrained length, offering high aspect ratios. Research focuses on their use in advanced sensors and miniaturized electronic circuits.
- Fullerenes:Spherical carbon molecules, such as buckyballs, known for their unique cage-like structures. Applications are explored in drug delivery systems and specialized lubricants.
Leading the category by volume: Nanoparticles. Growing fastest: Nanotubes.
Grade:
The grade of nanoscale chemicals directly influences their production costs and market pricing, reflecting the purity requirements and specialized processing for each application.
- Electronic:Characterized by ultra-high purity and precise dimensional control, essential for semiconductor and display fabrication. South Korea's semiconductor foundries demand this grade for advanced lithography and interconnects.
- Pharmaceutical:Requires stringent biocompatibility testing and sterility, often for targeted drug delivery systems and medical diagnostics. The US FDA's regulatory pathways are critical for market entry in biomedical applications.
- Technical:Designed for industrial applications where performance enhancements are prioritized over ultra-high purity. This grade finds use in structural composites and protective coatings.
- Catalytic:Engineered for specific surface reactivity to accelerate chemical reactions in industrial processes. These materials are critical for green chemistry initiatives and emissions control.
- Cosmetic:Formulated for safe topical application, often enhancing UV protection or active ingredient delivery in personal care products.
The electronic grade commands premium pricing due to its stringent specifications, while pharmaceutical grade materials offer significant long-term value.
End Use Industry:
Applications for nanoscale chemicals span diverse industries, each leveraging unique material properties to achieve specific performance improvements or cost efficiencies.
- Electronics Manufacturing:Integrates nanomaterials into advanced displays, semiconductors, and flexible electronics for improved performance and miniaturization. Taiwan's semiconductor industry is a concentrated demand hub for these specialized inputs.
- Pharmaceuticals:Utilizes functionalized nanoparticles for targeted drug delivery, advanced diagnostics, and vaccine development. Regulatory scrutiny by bodies like the European Medicines Agency (EMA) influences product development.
- Renewable Energy:Employs nanomaterials in solar cells, fuel cells, and energy storage devices to enhance efficiency and capacity.
- Cosmetics Production:Incorporates nanoparticles for UV filtration, anti-aging formulations, and improved ingredient stability in personal care products.
- Chemical Processing:Leverages nanocatalysts to improve reaction kinetics, reduce energy consumption, and enhance selectivity in industrial chemical synthesis.
Electronics manufacturing remains the largest consumer segment, with pharmaceuticals offering significant growth potential due to high-value applications.
Packaging Type:
The packaging type for nanoscale chemicals reflects both the volume of material handled and the specific safety and purity requirements of the end-use application.
- Bulk Containers:Large-volume packaging for industrial-scale delivery of nanomaterials, primarily for composite manufacturing and large-scale chemical processing. These containers streamline logistics for high-tonnage requirements in the automotive sector.
- Vials:Small, sterile containers typically used for high-purity or pharmaceutical-grade nanomaterials, ensuring precise dosing and contamination control. Biomedical research facilities and drug manufacturers rely on this packaging for sensitive materials.
- Bottles:Common for laboratory reagents and smaller industrial quantities, providing protection from environmental factors.
- Sealed Pouches:Offer a flexible and lightweight option for various nanomaterials, often used for intermediate volumes or specialty applications.
- Capsules:Specialized packaging for highly sensitive or reactive nanomaterials, providing a protective barrier and controlled release mechanisms.
Bulk containers facilitate large-scale industrial use, while vials cater to the stringent requirements of high-value, sensitive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive chemical manufacturing base provides a significant feedstock source for nanoscale materials production. Its national policies promote advanced materials development, integrating these substances into various industrial sectors. This strategic focus positions China as a critical hub for both supply and demand in the global market.
China
Demand for advanced displays and electric vehicle batteries drives nanomaterial innovation across the country. The Ministry of Ecology and Environment (MEE) mandates rigorous registration for new chemical substances, including all nanomaterials. Industrial parks in the Yangtze River Delta actively develop production capabilities for carbon nanotubes and quantum dots, supporting domestic electronics and automotive industries.
South Korea
Major display and semiconductor producers require high-purity nanoparticles for advanced electronics manufacturing. The Ministry of Food and Drug Safety (MFDS) oversees safety assessments for nanomaterials in consumer products and medical devices. Pyeongtaek and Cheonan are key semiconductor and display manufacturing hubs utilizing specialized nanoscale inputs for next-generation devices.
United States
Biomedical applications and next-generation energy storage solutions create significant demand for functionalized nanoparticles. The Environmental Protection Agency (EPA) regulates nanomaterial safety and environmental impact under the Toxic Substances Control Act. Research clusters in California and Massachusetts drive innovation in nanomedicine and advanced materials science, fostering new product development.
Germany
The automotive and aerospace sectors integrate carbon nanotubes into lightweight composite materials for performance enhancement. The European Union's REACH regulation dictates stringent safety and registration protocols for nanomaterials entering the market. Chemical industrial complexes in North Rhine-Westphalia focus on scalable production of technical-grade nanomaterials for industrial applications.
Japan
Electronics manufacturing and advanced materials research fuel demand for high-performance nanowires and fullerenes. The Ministry of Economy, Trade and Industry (METI) supports research and development initiatives for sustainable nanomaterial applications. Science parks in Tsukuba and the Kansai region concentrate efforts on developing miniaturized electronic circuits and advanced sensors.
Nanoscale Chemicals and Materials Market Key Industry Players
Global majors compete with regional champions across specialized material types and application segments. The market structure exhibits a tiered consolidation, with large chemical conglomerates and specialized nanotechnology firms. Strategic archetypes include diversified chemical giants, niche material specialists, and emerging startups focusing on specific nanomaterial synthesis. Portfolio diversification and strategic partnerships are dominant competitive moves.
Specialists in advanced material synthesis include Arkema, which leverages its extensive chemical portfolio to offer a broad range of functionalized nanomaterials. OCSiAl exemplifies a firm focused on mass production, specializing in single-wall carbon nanotubes for large-scale industrial applications. Sumitomo Metal Mining occupies a position as a provider of high-purity metal-based nanoparticles, primarily for the demanding electronics sector. These entities represent distinct approaches to market penetration, from broad portfolio offerings to highly specialized, high-volume production, shaping the competitive dynamics across various end-use segments.
| Leading Market Players |
|---|
| Showa Denko |
| Zeon Nano Technology |
| Arkema |
| nanoComposix |
| Raymor Industries |
| Nanocyl |
| OCSiAl |
| Sumitomo Metal Mining |
| Cnano |
| Others |
Cost & Logistics Intelligence
High-purity raw material costs for electronic-grade nanoparticles significantly influence the premium pricing observed in semiconductor and display manufacturing, cascading through specialized suppliers to end-product integrators. This dynamic highlights the tight coupling between input material quality and final product value across the nanoscale chemicals market.
Pricing Analysis
Warranty and after-sales service bundling often differentiate offerings for complex nanomaterials, with technical support critical for successful integration. Contract-based long-term offtake agreements dominate for electronic and pharmaceutical grades, ensuring stable supply and pricing. Price differentiation stems from certification level, particularly for EU REACH compliance, and the volume scale of purchases. Pricing softness stems from increasing competition in technical-grade carbon nanotubes. Pharmaceutical manufacturers exhibit lower price sensitivity due to stringent performance and regulatory requirements, unlike technical-grade buyers focused on cost-performance ratios.
Supply Chain Analysis
Regional distribution centers facilitate the timely delivery of specialized nanomaterials to manufacturing hubs in South Korea and Taiwan. Supply concentrations center on China for feedstock chemicals and specialized processing capabilities, while Japan contributes high-performance nanowires and fullerenes. The supply chain relies heavily on specific high-purity metal precursors and carbon sources. Single-source vulnerability for highly specialized nanoparticles represents a key structural risk. Distribution primarily occurs direct-to-OEM for high-value electronic and pharmaceutical applications, with industrial distributors handling technical and catalytic grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanoscale chemicals market is a cost-of-compliance story, where stringent regulations like the EU's REACH framework create a significant barrier to entry, favoring established players with robust safety data.
For Market Incumbents:Lock in long-term supply agreements with major electronics and automotive manufacturers to secure demand. Invest proactively in safety-by-design principles during R&D to navigate evolving regulations from China's MEE and the US EPA. This strategy mitigates the threat of new market entrants with unproven compliance profiles. Deepen vertical integration into specialized precursor materials to control quality and reduce cost volatility, especially for high-purity electronic grades.
For New Entrants and Emerging Players:Capture white-space opportunities in biomedical applications like targeted drug delivery, leveraging streamlined regulatory pathways from the US FDA. Focus on developing cost-effective synthesis methods for technical-grade nanomaterials to penetrate the automotive and aerospace composite sectors. A go-to-market angle emphasizing superior performance-to-cost ratios for specific industrial processes can overcome incumbent inertia. Target regions with less stringent initial regulatory hurdles to establish a foothold.
For Investors and Strategic Acquirers:Commercial validation of silicon-based anodes in electric vehicle batteries is the leading indicator that nanomaterials are moving from niche to mainstream energy storage. The market offers significant long-term growth potential over the next 5-10 years, driven by electronics and energy transition. Target acquisitions of specialists in scalable single-wall carbon nanotube production or functionalized nanoparticles for biomedical applications. Watch for regulatory harmonization efforts as a signal for broader market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Nanotubes | Increases supply to meet growing demand from automotive and aerospace composites sectors. |
| Regulatory Certification Investment | Ensures market access and compliance with stringent frameworks like EU REACH and China MEE. |
| Strategic Partnership with Electronics OEM | Secures demand for high-purity nanoparticles in advanced display and semiconductor manufacturing. |
| Green Manufacturing Process Development | Aligns with global sustainability goals and reduces environmental impact of nanomaterial production. |
| Product Portfolio Diversification into Biomedical | Opens new high-value revenue streams through targeted drug delivery and medical imaging applications. |
Research Approach
Document review covered EU ECHA filings, US EPA databases, China MEE guidelines, and patent databases, complemented by interviews with materials scientists, R&D directors, regulatory affairs specialists, and procurement managers at electronics OEMs. This blended approach ensured comprehensive data collection and validation. Bottom-up market sizing from production capacities was cross-referenced with top-down validation from end-use industry consumption data.
Historical market data cross-referenced with expert panel input shaped the forecast model across the analysis window. The analytical framework segmented the market by product type, grade, end-use industry, packaging type, and regional regulatory compliance status. Compound annual growth rates were projected from demand growth in key end-use sectors like advanced displays and electric vehicle batteries. Semiconductor industry capital expenditure trends and quantum dot adoption rates in consumer electronics served as primary forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory shifts, rapid technological obsolescence, or global supply chain disruptions. Forecasts reflect assumptions regarding material performance and market adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Nanomaterials Market
Nanomaterials
Global Nanocrystalline Cellulose Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
Graphene Aerogel Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Global Nano Calcium Carbonate Market
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Mesoporous Carbons Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Nano Composite Zirconia Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Americas Gold Nanoparticles Market
Nanomaterials
Global Nanoemulsion Market