
 Copper Nano Powder Market | 2026-2036
Copper Nano Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Nano Powder Market Analysis
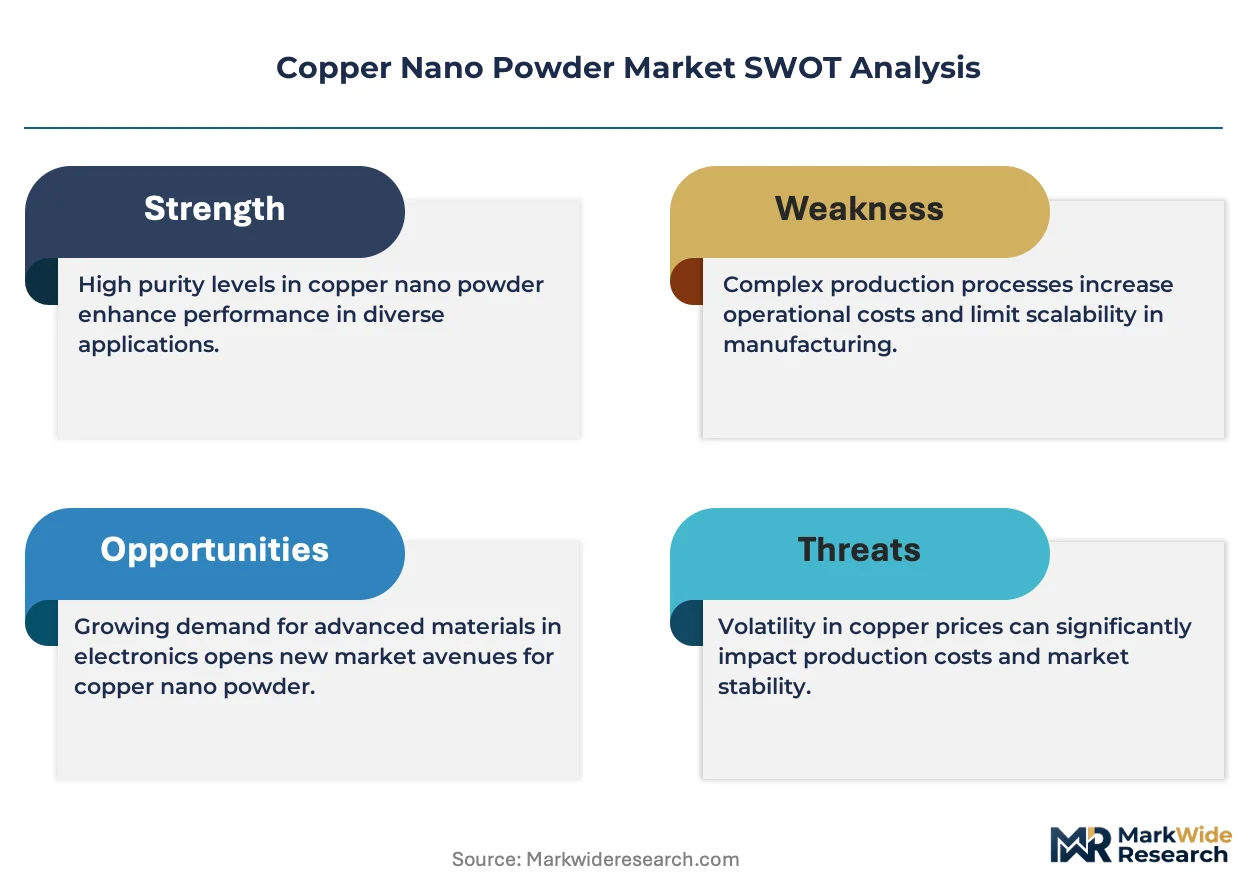
EU REACH chemical registration is consolidating downstream specifications for nano-copper purity and ecotoxicity documentation. American Elements leverages vertical integration across rare and advanced materials to sustain supply security for high-specification buyers. Nanoshel LLC specializes in customized particle size distributions for electronics coating applications. SkySpring Nanomaterials anchors North American supply through ISO-certified production protocols and direct technical service channels.
Copper nano powder denotes metallic copper reduced to particle sizes typically below 100 nanometers, produced via chemical reduction, electrochemical synthesis, or vapor-phase methods, valued for electrical conductivity exceeding 5.8 × 10⁷ S/m and antimicrobial surface activity. The material serves primarily as a conductive filler in printed electronics, antimicrobial additive in medical devices, and catalyst precursor in energy conversion systems. High-purity copper commands premium positioning in semiconductor interconnects where oxygen content below 100 ppm prevents electromigration failure. Energy Storage applications represent the fastest-expanding demand pool as solid-state battery developers specify nano-copper for lithium-metal anode architectures. Electronics Manufacturers as an end-user category concentrate procurement volumes through long-term direct contracts rather than spot distributor purchases.
FDA regulates nano-copper in biomedical coatings through device-specific 510(k) pathways requiring biocompatibility data at the nanoscale. EPA oversees TSCA Section 5 premanufacture notifications for new nano-copper entities entering US commerce. China's SAMR enforces GB standards for nano-material classification and labeling that shape export eligibility. Stakeholders must monitor evolving nano-specific regulatory thresholds across these jurisdictions to preempt compliance-driven supply disruptions and qualification delays.
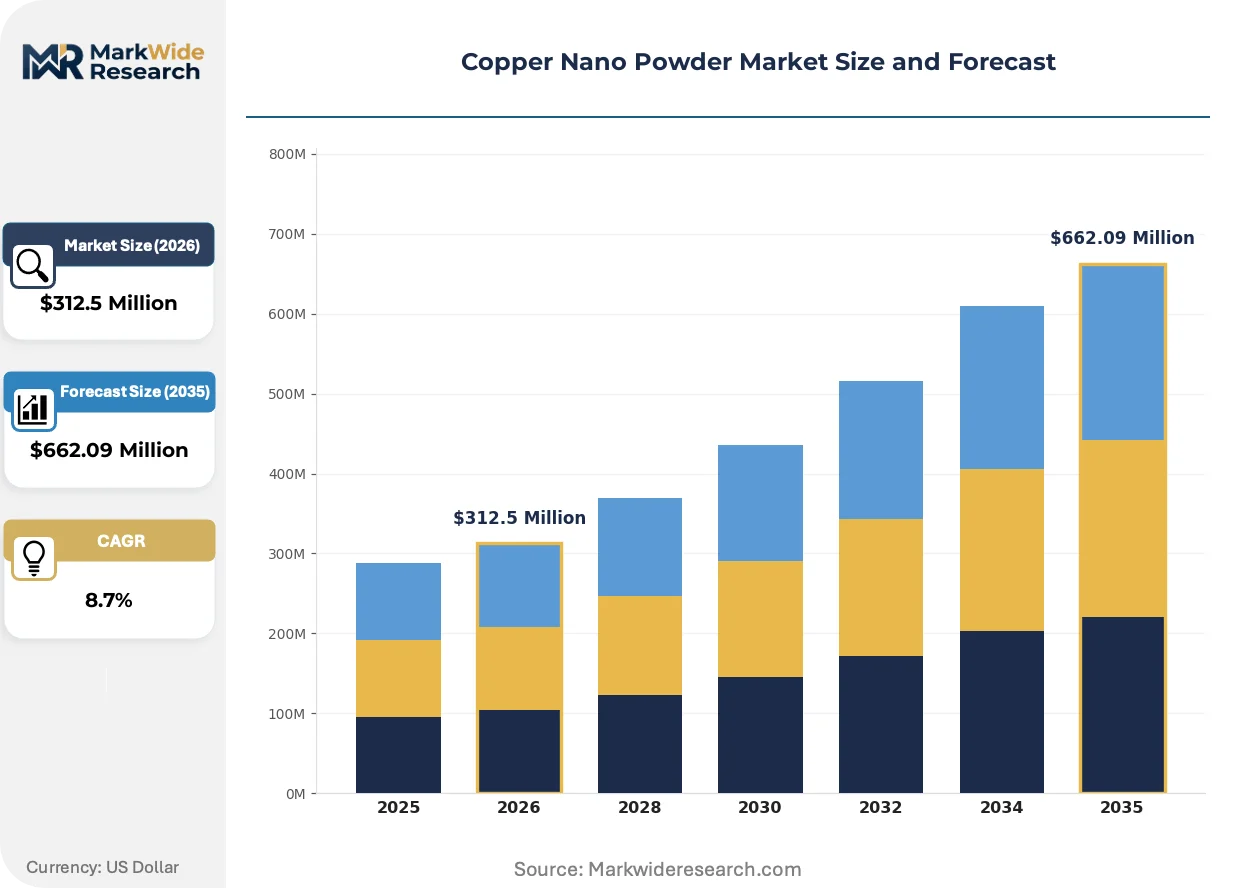
Market Dynamics
Semiconductor interconnect scaling below 7nm nodes is absorbing nano-copper volumes previously reserved for silver-filled alternatives, tightening purity specifications across the supply base. Battery developers in East Asia are locking multi-year procurement contracts ahead of solid-state commercialization timelines.
Growth Catalysts
- Solid-state battery anode architectures:Lithium-metal cell developers specify nano-copper current collectors to suppress dendrite formation. Korean and Chinese battery makers are qualifying suppliers for 2026-2027 production ramps.
- EU REACH nano-specific registration:ECHA's tightened ecotoxicity documentation requirements are filtering out sub-scale producers. Compliant suppliers gain preferential access to German and French electronics manufacturers.
- Printed electronics conductive ink substitution:Nano-copper inks are displacing silver formulations in RFID antenna and flexible circuit applications. Cost-sensitive consumer electronics brands in Vietnam and Mexico are driving formulation switches.
Market Restraints
- Argentum price volatility spillover:Silver market fluctuations distort nano-copper pricing benchmarks. Buyers hesitate to commit to long-term contracts when substitute metal spreads oscillate unpredictably.
- High-purity feedstock concentration:Electrolytic copper cathode supply for nano-reduction concentrates in Chilean and Zambian mining corridors. Geopolitical disruptions to concentrate flows cascade into nano-powder production delays.
- Oxide sensitivity in ambient handling:Surface oxidation above 50nm penetration depth degrades conductivity below semiconductor interconnect thresholds. Specialized inert-atmosphere packaging adds 15-20% to delivered cost.
Strategic Opportunities
- Indian PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives are creating first-mover positioning for nano-copper suppliers establishing local reduction facilities. Tamil Nadu and Gujarat industrial corridors offer land and power subsidies.
- Antimicrobial medical device coatings:FDA 510(k) pathways for nano-copper surface treatments in catheter and implant applications remain underpenetrated. Orthopedic device makers in Warsaw and Minneapolis are initiating biocompatibility studies.
- AI-driven particle size optimization:Machine learning models trained on electrochemical synthesis parameters are compressing R&D cycles for custom distributions. Japanese materials informatics startups are licensing platforms to European producers.
Industry Challenges
- Electrochemical synthesis technician scarcity:Operating pulsed electrodeposition reactors requires rare combinations of nanomaterials chemistry and process engineering expertise. German and Swiss technical universities are launching specialized certification programs.
- Multi-jurisdiction nano-registration synchronization:Divergent classification thresholds between EPA TSCA, EU REACH, and China's GB standards force parallel documentation efforts. Registration timelines extend 18-24 months for new particle size variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Nano Powder Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-purity Copper, Copper Oxide, Composite Copper, Others Application: Electronics, Coatings, Biomedical, Energy Storage End User: Aerospace, Automotive OEMs, Electronics Manufacturers, Research Institutes Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | American Elements, Nanoshel LLC, SkySpring Nanomaterials, Inc., GGP Metalpowder AG, Hongwu International Group Ltd, Nanografi Nano Technology, Nanostructured & Amorphous Materials, Inc., MKNano, Reinste Nano Ventures Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Nano Powder Market Emerging Trajectories
Electrochemical synthesis methods are displacing legacy chemical reduction as the dominant production pathway. Patent filings for continuous-flow reactor designs have tripled since 2022. Regulatory frameworks are hardening around nano-specific hazard classification.
Continuous-flow electrochemical reactors are absorbing capital allocation previously directed toward batch chemical reduction systems. Solid-state battery manufacturers in South Korea and Japan are specifying sub-50nm particle distributions with oxygen content below 50 ppm. This technology compression is enabling direct metallization of polymer substrates without intermediate seed layers.
EU REACH Annex VI amendments are mandating nano-specific substance identification and ecotoxicity data sets for copper particles below 100nm. Formulators importing into Rotterdam and Hamburg must submit extended safety data sheets with dissolution rate testing. Medical device coatings face the steepest compliance cost escalation, pushing some antimicrobial applications toward copper oxide alternatives.
Long-term direct contracting is displacing spot distributor purchases among top-decile electronics manufacturers. Semiconductor foundries in Hsinchu and Dresden are negotiating five-year supply agreements with fixed-volume escalators. This preference compression is most visible in thermal interface material procurement, where qualification timelines exceed 18 months and supplier switching costs have risen sharply.
Copper Nano Powder Market Segmentation
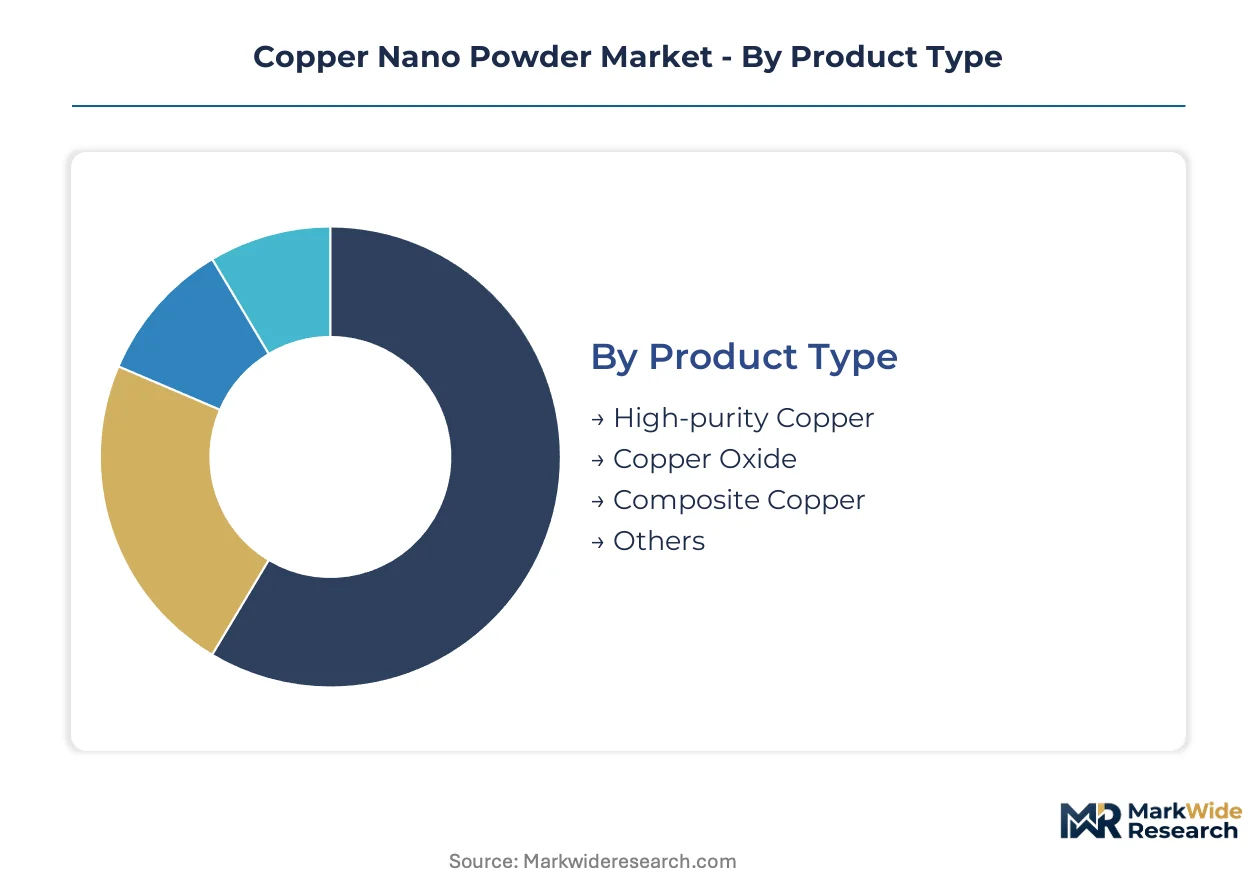
Segmentation in the copper nano powder market reveals distinct purity-performance tradeoffs and procurement pattern differences. Each dimension carries implications for pricing, regulatory burden, and supplier qualification timelines.
Product Type:
Volume concentrates in standard-purity grades for cost-sensitive coating applications. Premium positioning attaches to ultra-high-purity variants serving semiconductor interconnect requirements.
- High-purity Copper:Metallic copper with oxygen content below 100 ppm and particle sizes typically 20-80 nanometers. Semiconductor foundries in Hsinchu and Dresden absorb volumes through five-year direct contracts with fixed-volume escalators, driven by electromigration resistance requirements at sub-7nm nodes.
- Copper Oxide:CuO and Cu₂O variants with controlled stoichiometry for catalytic and antimicrobial applications. Biomedical device makers in Warsaw and Minneapolis are initiating biocompatibility studies for catheter coatings, though FDA 510(k) pathways impose extended documentation timelines.
- Composite Copper:Hybrid formulations incorporating carbon nanotubes or graphene for enhanced thermal conductivity.
- Others:Specialty alloys and surface-functionalized variants for niche research applications.
Mature deployment sits with High-purity Copper. Newer deployment is concentrated in Copper Oxide biomedical coatings.
Application:
Application segmentation tracks the divergence between electronics-driven conductivity requirements and emerging energy storage specifications.
- Electronics:Conductive inks for printed circuit boards, RFID antennas, and flexible circuits. Vietnamese and Mexican consumer electronics brands are driving formulation switches from silver-filled alternatives, compressing material costs for high-volume antenna production.
- Energy Storage:Current collectors and anode architectures for solid-state lithium-metal batteries. Korean and Chinese battery makers are locking multi-year procurement contracts ahead of production ramps, climbing the fastest among application categories.
- Coatings:Antimicrobial surface treatments and corrosion-resistant layers for industrial equipment.
- Biomedical:Implantable device coatings and wound care formulations requiring ISO 10993 biocompatibility certification.
Electronics maintains the largest procurement volumes. Energy Storage shows the steepest expansion trajectory as solid-state commercialization accelerates.
End User:
End-user segmentation reflects procurement sophistication differences between long-term contract manufacturers and spot-market purchasers.
- Electronics Manufacturers:Printed circuit board fabricators and semiconductor packaging houses specifying sub-50nm distributions. These buyers concentrate procurement through direct technical relationships rather than distributor channels, driven by 18-month qualification timelines and steep supplier switching costs.
- Automotive OEMs:Battery pack integrators and thermal management system suppliers. Solid-state battery roadmaps are forcing early supplier lock-ins to secure capacity for 2026-2027 vehicle program launches.
- Aerospace:Satellite and avionics manufacturers requiring traceable supply chains and ITAR-compliant documentation.
- Research Institutes:Academic and national laboratory purchasers with small-batch, high-specification requirements.
Electronics Manufacturers anchor procurement volume. Automotive OEMs are compressing supplier selection timelines most aggressively.
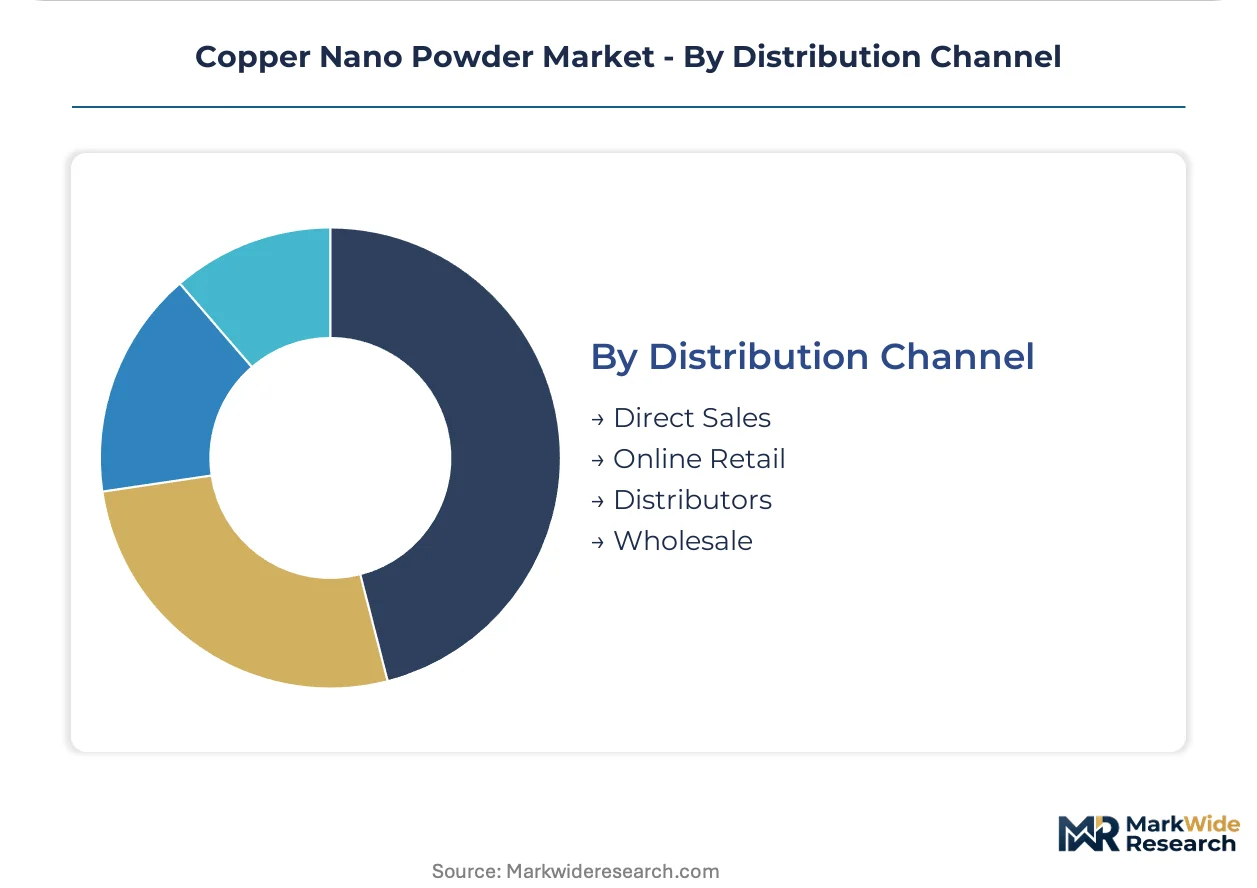
Distribution Channel:
Channel segmentation tracks the shift from transactional purchasing toward technical partnership models.
- Direct Sales:Long-term supply agreements with technical service support and joint R&D programs. Semiconductor foundries and battery developers favor this channel for custom particle size distribution development.
- Distributors:Regional stocking points for qualified buyers with predictable consumption patterns.
- Online Retail:Small-volume procurement for research and pilot-scale applications.
- Wholesale:Bulk transactions for standard-grade material in coating and catalyst applications.
Direct Sales commands the premium tier. Distributors retain relevance for mid-volume electronics coating formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors semiconductor-grade nano-copper procurement, with foundries there locking five-year direct contracts. Dresden and Hsinchu together concentrate sub-50nm specification demand. Battery developers in East Asia are compressing supplier qualification timelines ahead of solid-state commercialization ramps.
China
Domestic battery and semiconductor fabs are expanding nano-copper procurement volumes. SAMR enforces GB standards for nano-material classification and labeling that shape export eligibility. The Yangtze River Delta industrial corridor hosts reduction facilities serving Korean battery maker qualification programs.
South Korea
Lithium-metal cell developers specify nano-copper current collectors to suppress dendrite formation. MFDS maintains medical device coating regulations that parallel FDA biocompatibility frameworks. Battery makers in the Busan-Ulsan corridor are locking multi-year procurement contracts for 2026-2027 production ramps.
United States
Semiconductor packaging houses specify sub-50nm distributions through direct technical relationships. EPA oversees TSCA Section 5 premanufacture notifications for new nano-copper entities entering commerce. The Pacific Northwest hosts research institutes piloting AI-driven particle size optimization platforms.
Germany
Electronics manufacturers drive formulation switches from silver-filled alternatives in RFID antenna applications. ECHA's tightened REACH ecotoxicity documentation requirements filter out sub-scale producers. The Dresden industrial cluster absorbs volumes through fixed-volume escalator contracts with qualified suppliers.
India
Domestic battery manufacturing incentives create first-mover positioning for suppliers establishing local reduction facilities. The PLI scheme for advanced chemistry cells offers land and power subsidies in Tamil Nadu and Gujarat. Mumbai-Pune industrial corridor formulators are initiating biocompatibility studies for catheter coating applications.
Copper Nano Powder Market Vendor Landscape
Premium-margin players sit above commodity-margin players across purity-grade stratification. High-purity variants command positioning above standard grades for coating applications. Three archetypes populate the vendor base: vertically integrated rare materials specialists, customized particle size distributors, and ISO-certified regional producers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as buyers compress qualification timelines.
Among North American material suppliers, American Elements exemplifies the vertically integrated archetype across rare and advanced materials. Nanoshel LLC occupies a position within the customization tier for electronics coating applications. SkySpring Nanomaterials, Inc. anchors the ISO-certified production segment with direct technical service channels. These three represent distinct positioning vectors rather than overlapping competitive territory.
| Leading Market Players |
|---|
| American Elements |
| Nanoshel LLC |
| SkySpring Nanomaterials, Inc. |
| GGP Metalpowder AG |
| Hongwu International Group Ltd |
| Nanografi Nano Technology |
| Nanostructured & Amorphous Materials, Inc. |
| MKNano |
| Reinste Nano Ventures Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
EU REACH nano-specific registration gates qualified supply and premium-tier pricing access, filtering out sub-scale producers while compliant suppliers capture preferential contracts with German and French electronics manufacturers. This regulatory filter concentrates pricing power among certified producers serving semiconductor and battery applications.
Pricing Analysis
Yield-based pricing anchors semiconductor-grade nano-copper contracts, with sub-50nm distributions commanding premiums tied to interconnect reliability outcomes. Three-tier pricing structure across premium, standard, and economy levels separates oxygen-below-50-ppm semiconductor grades from standard coating grades and research-lot material. Cost compression in standard grades intensifies because Vietnamese and Mexican consumer electronics brands drive silver-to-copper formulation switches. Battery developers show least price sensitivity due to 18-month qualification timelines and dendrite-suppression performance requirements.
Supply Chain Analysis
Electrochemical synthesis technician scarcity in German and Swiss manufacturing corridors constrains qualified production capacity expansion. Feedstock draws from Chilean and Zambian electrolytic copper cathode corridors, with reduction facilities clustering in China's Yangtze River Delta and South Korea's Busan-Ulsan belt. Single-source vulnerability concentrates in high-purity feedstock channels, where geopolitical disruptions cascade into nano-powder production delays. Distribution runs through direct technical relationships for semiconductor foundries, with regional distributors serving mid-volume coating formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical synthesis capacity scarcity props pricing across qualified supply tiers, creating defendable margin structures for certified producers. This bottleneck intensifies as solid-state battery roadmaps compress supplier qualification timelines.
For Market Incumbents: Anticipate Korean and Chinese battery makers locking multi-year procurement contracts ahead of production ramps by expanding electrochemical synthesis capacity in certified facilities. Backward integration into high-purity electrolytic copper feedstock secures supply continuity against Chilean concentrate flow disruptions. Prioritize GB standards compliance for Chinese SAMR export eligibility to maintain Yangtze River Delta facility access.
For New Entrants and Emerging Players: Capture first-mover positioning in India's Tamil Nadu and Gujarat industrial corridors by establishing local reduction facilities under PLI scheme incentives for advanced chemistry cells. The antimicrobial medical device coating segment remains underpenetrated, with Warsaw and Minneapolis orthopedic device makers initiating biocompatibility studies. Lead with FDA 510(k) pathway expertise and ISO 10993 certification support to differentiate from commodity suppliers.
For Investors and Strategic Acquirers: Solid-state battery anode architecture qualification announcements from Korean cell developers are the leading indicator that nano-copper demand inflection is materializing. Five-to-ten year viability rests on electrochemical synthesis platform control rather than legacy chemical reduction assets. Target acquisition profiles center on ISO-certified regional producers with direct technical service channels and existing semiconductor foundry relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrochemical Synthesis Capacity Expansion | Continuous-flow reactor deployment displaces batch chemical reduction in certified facilities serving Hsinchu and Dresden foundries. |
| Backward Integration into Feedstock | Captive supply of electrolytic copper cathode insulates against Chilean concentrate corridor geopolitical disruptions. |
| Multi-Jurisdiction Registration Investment | Parallel EPA TSCA, EU REACH, and SAMR GB documentation compresses 18-24 month timelines for new particle size variants. |
| AI-Driven Particle Size Optimization | Machine learning platforms licensed from Japanese materials informatics startups compress R&D cycles for custom distributions. |
| Long-Term Direct Contracting | Five-year supply agreements with fixed-volume escalators lock in semiconductor and battery maker procurement volumes. |
Methodological Framework
Document review covered ECHA registration filings, SAMR GB standard publications, and EPA TSCA premanufacture notifications, complemented by interviews with electrochemical synthesis plant managers, nano-copper procurement leads at Korean battery makers, semiconductor packaging technical directors, and medical device coating formulators. Secondary validation drew from customs trade data, SEC 10-K materials disclosures, and IEA energy storage technology roadmaps. Bottom-up capacity estimates and top-down demand segmentation were triangulated to anchor volume projections.
Historical capacity utilization patterns were cross-referenced against panel input from qualified producers to build the analytical framework across the analysis window. Segmentation dimensions modeled include purity grade tier, application end-use, particle size distribution band, and regional regulatory cluster. CAGRs were derived from supply-demand balance modeling incorporating solid-state battery commercialization timelines and semiconductor node migration patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrochemical synthesis technician pipeline development and REACH Annex VI amendment implementation timing. Forecasts reflect assumptions around Korean battery maker qualification schedules and Chinese domestic fab expansion rates. Material deviation in solid-state battery commercialization timelines or EU nano-specific hazard classification enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Americas Gold Nanoparticles Market
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Nanoscale Chemicals and Materials Market
Nanomaterials
Global Carbon Nanomaterials Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Graphene Aerogel Market
Nanomaterials
Global Nanocrystalline Cellulose Market
Nanomaterials
Nanoparticle Analysis Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Nanocomposites Market