
 Americas Gold Nanoparticles Market | 2026-2036
Americas Gold Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Gold Nanoparticles Market Outlook
Diagnostic laboratory procurement is expanding across the Americas as health systems consolidate testing volumes and seek higher-sensitivity reagents. Cytodiagnostics Inc leverages its specialized colloidal gold portfolios to anchor supply relationships with regional hospital networks. Fortis Life Sciences, LLC competes through backward integration into bioconjugation chemistry that reduces lot-to-lot variability for assay manufacturers. Nanopartz, Inc differentiates by controlling proprietary seed-mediated synthesis protocols that yield narrow size distributions for surface-enhanced Raman spectroscopy applications.
Gold nanoparticles are colloidal suspensions of metallic gold with dimensions typically between 1 and 100 nanometers, synthesized through citrate reduction or seed-mediated growth methods that tune plasmon resonance peaks for specific optical detection tasks. Their primary commercial purpose centers on biosensing, targeted drug delivery, and contrast enhancement in imaging modalities where surface functionalization enables molecular specificity. Colloidal gold dominates current revenue flows due to established supply chains in lateral flow diagnostics, while gold nanorods represent the fastest-expanding category as photothermal therapy protocols advance through clinical validation. The biomedical application segment captures the deepest margin pools because pharmaceutical sponsors fund premium pricing for GMP-compliant nanomaterial batches.
FDA oversees premarket notification and investigational new drug pathways for nanotechnology products, while EPA monitors environmental release thresholds under the Toxic Substances Control Act. Health Canada and ANVISA maintain parallel review frameworks that shape cross-border product registration strategies for vendors operating throughout the hemisphere. Stakeholders must monitor evolving characterization standards from ISO and ASTM that define batch consistency metrics, since compliance with these specifications determines eligibility for federal procurement contracts and reimbursement codes across public health systems.
Market Dynamics
Diagnostic laboratory consolidation across the United States is concentrating procurement volumes into fewer purchasing organizations, forcing gold nanoparticle suppliers to demonstrate batch-to-batch optical consistency at scale to retain hospital network contracts.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:The agency's nanotechnology guidance documents are reducing premarket review timelines for colloidal gold diagnostics, accelerating commercial entry for assay developers in the United States.
- Photothermal Therapy Protocols:Gold nanorods are displacing organic dyes in oncology applications as near-infrared absorption profiles enable precise tumor ablation with reduced collateral tissue damage.
- Boston-Cambridge Research Corridor:Dense concentration of NIH-funded laboratories in Massachusetts is generating sustained demand for surface-functionalized nanoparticles in proteomics and genomics workflows.
Market Restraints
- Chloroauric Acid Price Volatility:Precursor chemical costs fluctuate with spot gold markets, compressing margins for manufacturers lacking long-term commodity hedging instruments.
- Single-Source Synthesis Equipment:Seed-mediated growth reactors are concentrated among three German and Japanese equipment vendors, creating supply chain vulnerability for North American producers.
- Batch Reproducibility Limits:Citrate reduction methods yield broader size distributions than clinical applications demand, requiring costly post-synthesis fractionation.
Strategic Opportunities
- Brazilian Diagnostic Manufacturing:ANVISA's accelerated review pathway for imported reference materials creates entry points for US-based nanoparticle suppliers serving Latin American assay producers.
- CRISPR-Gold Conjugates:Integration of guide RNA-functionalized nanoparticles with gene editing workflows opens therapeutic delivery applications beyond current biosensing dominance.
- Canada's Biomanufacturing Strategy:Federal procurement incentives for domestic nanomaterial production are attracting contract manufacturing investments in Ontario and Quebec.
Industry Challenges
- GMP Analytical Chemist Scarcity:FDA's Phase I IND requirements for nanotherapeutics demand specialized characterization expertise that academic training programs have not scaled to meet.
- ISO/TS 19337 Implementation Lag:Delayed adoption of standardized measurement protocols for particle size distribution is fragmenting contract laboratory capabilities across the Americas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Gold Nanoparticles Market |
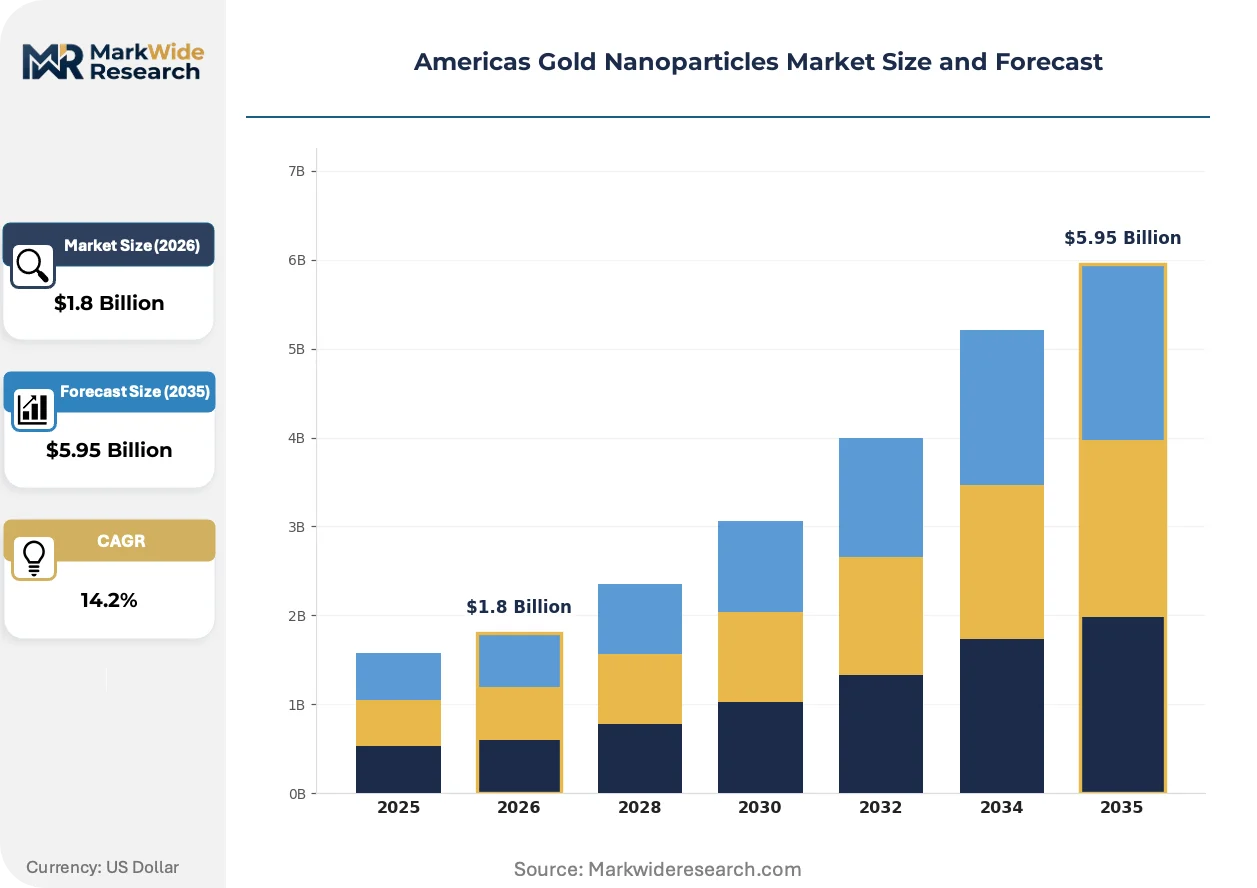
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colloidal Gold, Gold Nanorods, Gold Nanostars, Gold Nanospheres Application: Biomedical, Diagnostics, Drug Delivery, Imaging End User: Pharmaceutical Companies, Research Institutions, Diagnostic Laboratories, Academic Institutions Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Cytodiagnostics Inc, Fortis Life Sciences, LLC, Meliorum Technologies, Inc, Nanopartz, Inc, NanoHybrids Inc, CD Bioparticles, Nanocs Inc, American Elements, Goldsol Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Gold Nanoparticles Market Strategic Shifts
Surface plasmon resonance engineering is advancing faster than assay validation protocols can accommodate, creating capability gaps between nanoparticle synthesis sophistication and regulatory submission readiness.
Seed-mediated growth with silver underplating is integrating into manufacturing workflows for gold nanorods, enabling tunable aspect ratios that match specific near-infrared therapeutic windows. Massachusetts General Hospital's radiology department has adopted these materials for pilot photothermal ablation studies. The structural consequence is compressing development timelines for oncology device sponsors who previously relied on empirical size screening.
FDA's 2023 Nanotechnology Guidance Update is clarifying characterization expectations for combination products incorporating metallic nanoparticles, reducing submission resubmission rates for diagnostic developers. The industrial consequence is reallocating quality assurance resources toward analytical method validation rather than regulatory negotiation. In vitro diagnostic manufacturers in California's Bay Area are responding by embedding FDA pre-submission meetings into product development milestones.
Hospital procurement departments are consolidating reagent purchasing through group purchasing organizations, displacing direct manufacturer relationships that previously governed gold nanoparticle supply contracts. The disrupted channel is independent distributor networks; replacing it are sole-source agreements with specified optical performance guarantees. This concentration is most visible in Texas and Florida health systems where HCA and Tenet operations dominate regional testing volumes.
Americas Gold Nanoparticles Market Segmentation
Gold nanoparticle suppliers must navigate divergent technical specifications across biomedical and diagnostic applications, where plasmon resonance tuning and surface functionalization requirements reshape product development priorities. Segmentation reveals how synthesis methods and end-use validation protocols fragment addressable markets.
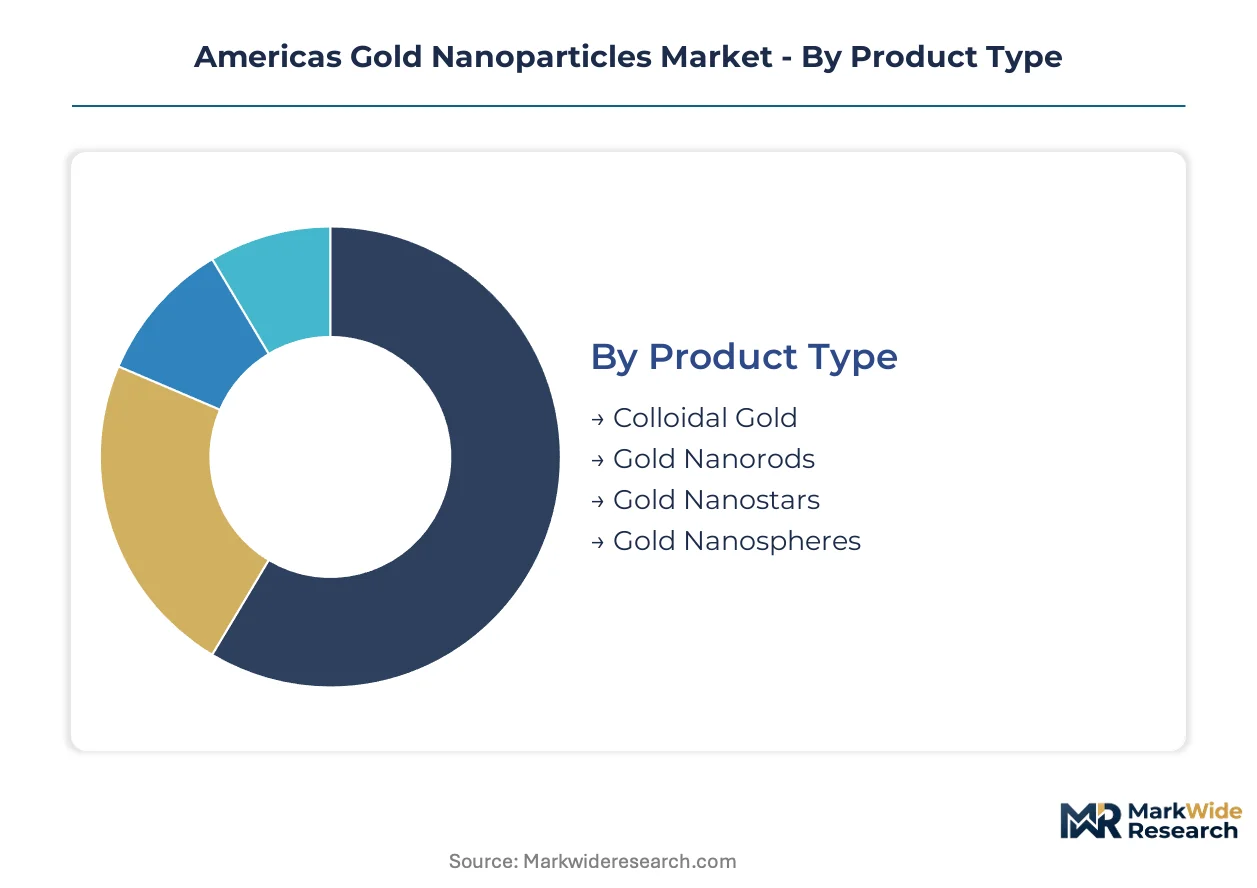
Product Type:
Colloidal gold dominates current procurement volumes through established lateral flow diagnostic supply chains, while nanorods command premium pricing for photothermal therapeutic applications.
- Colloidal Gold:Spherical particles synthesized via citrate reduction with diameters between 2 and 150 nanometers, exhibiting localized surface plasmon resonance peaks tunable between 520 and 580 nanometers. Demand concentrates in California's diagnostic manufacturing belt where FDA-cleared lateral flow assays require consistent optical density specifications. Scale economies from decades of production history compress margins for new entrants lacking backward integration into precursor chemicals.
- Gold Nanorods:Anisotropic structures with aspect ratios between 2 and 20, enabling longitudinal plasmon resonance shifts into the near-infrared therapeutic window. Massachusetts General Hospital's radiology department sources these materials for pilot tumor ablation protocols, driving demand for narrow size distributions that seed-mediated synthesis achieves. Photothermal therapy protocols are displacing organic dyes in oncology device pipelines.
- Gold Nanostars:Branched morphologies with sharp tips generating enhanced electromagnetic field confinement for surface-enhanced Raman spectroscopy substrates.
- Gold Nanospheres:Monodisperse coreshell architectures used as calibration standards and scattering contrast agents in microscopy workflows.
Today's leader: Colloidal Gold. Tomorrow's challenger: Gold Nanorods.
Application:
Biomedical applications capture the deepest margin pools through GMP-compliant batch requirements, while diagnostics generates the highest absolute volumes.
- Biomedical:Targeted drug delivery and therapeutic platforms requiring endotoxin-free synthesis environments and validated sterilization protocols. FDA's Phase I IND requirements for nanotherapeutics demand specialized characterization expertise that pharmaceutical sponsors fund at premium pricing.
- Diagnostics:Biosensing substrates and lateral flow reagents where optical consistency determines assay performance. Hospital procurement consolidation across Texas and Florida health systems is concentrating volumes into group purchasing organizations with stringent batch-to-batch specifications.
- Drug Delivery:CRISPR-gold conjugates and nucleic acid vectors where surface functionalization enables cellular uptake control.
- Imaging:Contrast enhancement agents for computed tomography and photoacoustic modalities, competing with iodinated and gadolinium-based alternatives.
Diagnostics commands present volume leadership. Biomedical holds the steepest expansion trajectory.
End User:
Research institutions drive specification innovation, while pharmaceutical companies anchor revenue stability through multi-year supply agreements.
- Pharmaceutical Companies:GMP nanomaterial procurement for IND-enabling toxicology studies and clinical trial material production. FDA pre-submission meetings are embedding into product development milestones for combination products.
- Research Institutions:Small-batch orders for proteomics and genomics workflows in Boston-Cambridge's NIH-funded corridor. Surface plasmon resonance engineering advances faster than assay validation protocols can accommodate.
- Diagnostic Laboratories:High-throughput reagent consumption as health systems consolidate testing volumes into fewer purchasing organizations.
- Academic Institutions:Grant-funded exploratory synthesis with limited commercial scale requirements.
Diagnostic Laboratories anchor current procurement scale. Pharmaceutical Companies are climbing the fastest.
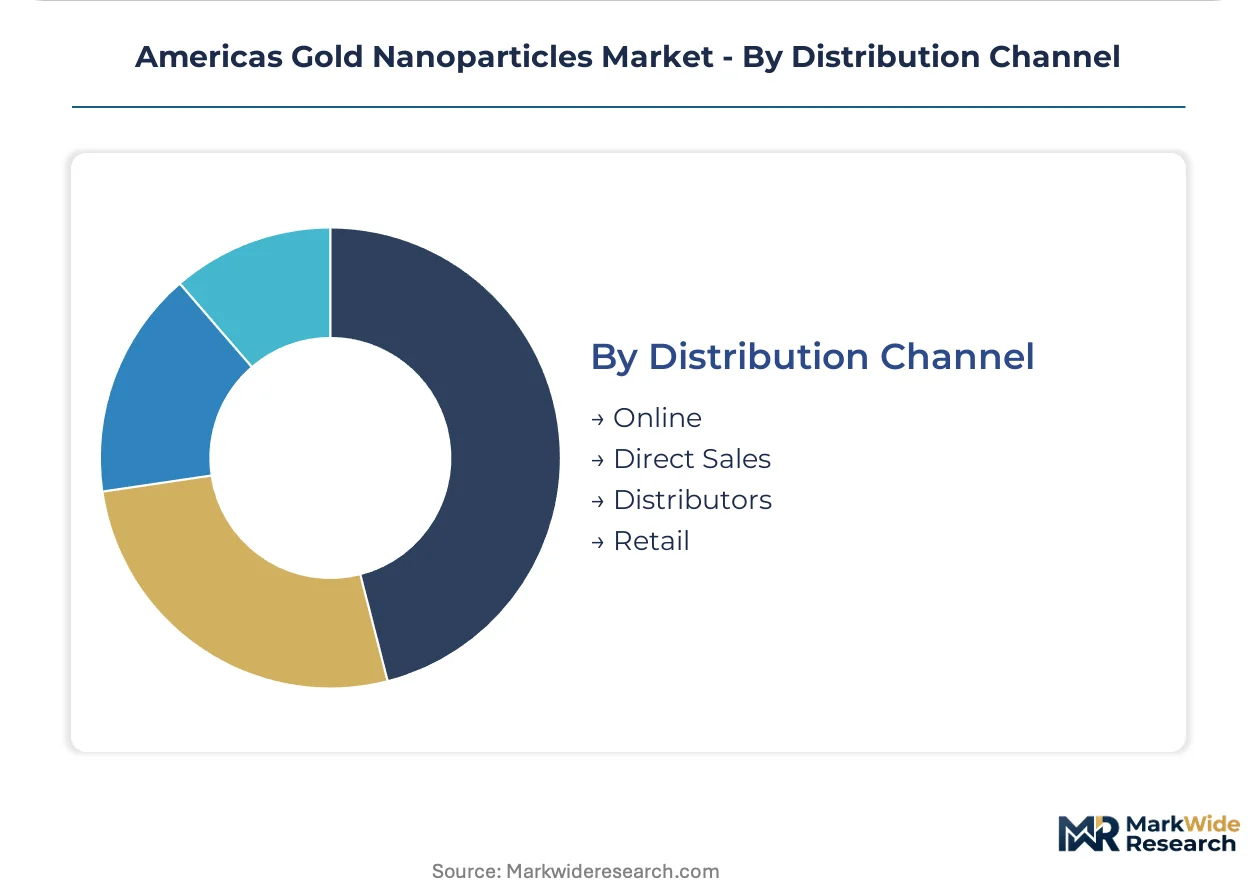
Distribution Channel:
Direct sales relationships are displacing independent distributor networks as sole-source agreements with optical performance guarantees consolidate supply chains.
- Direct Sales:Manufacturer relationships with specified batch consistency metrics for hospital network contracts. Texas and Florida health systems where HCA and Tenet operations dominate regional testing volumes favor this channel.
- Distributors:Independent networks facing displacement as group purchasing organizations consolidate reagent purchasing.
- Online:Small-volume catalog sales for research-grade materials with standardized specifications.
- Retail:Minimal presence limited to educational microscopy supplies and calibration standards.
Direct Sales captures procurement concentration. Distributors face structural compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's diagnostic manufacturing investments lag the United States by scale but exceed Mexico's therapeutic development capacity, creating a tiered procurement landscape across the hemisphere.
United States
FDA's 2023 nanotechnology guidance update accelerates premarket review timelines for colloidal gold diagnostics. Massachusetts General Hospital pilots photothermal ablation protocols with gold nanorods sourced from Boston-Cambridge corridor suppliers. Texas and Florida health systems consolidate reagent purchasing through HCA and Tenet group purchasing organizations.
Canada
Federal procurement incentives under the Biomanufacturing Strategy attract contract manufacturing investments in Ontario and Quebec. Health Canada maintains parallel review frameworks to FDA that shape cross-border product registration strategies. Toronto's biomedical research cluster generates sustained demand for surface-functionalized nanoparticles in proteomics workflows.
Brazil
ANVISA's accelerated review pathway for imported reference materials creates entry points for US-based suppliers serving Latin American assay producers. São Paulo's diagnostic manufacturing belt concentrates regional production capacity for lateral flow devices. Domestic pharmaceutical sponsors fund premium pricing for GMP-compliant nanomaterial batches.
Mexico
Maquiladora networks near the US border assemble diagnostic devices using imported gold nanoparticle reagents. The national pharmaceutical regulator monitors environmental release thresholds for nanomaterial processing facilities. Baja California's medical device corridor houses contract manufacturers serving California's Bay Area diagnostic developers.
Argentina
Research institutions in Buenos Aires drive specification innovation for surface-enhanced Raman spectroscopy applications. The central bank's foreign exchange controls complicate import procurement for chloroauric acid precursors. Local assay developers source catalog-grade materials through distributor networks rather than direct manufacturer relationships.
Americas Gold Nanoparticles Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct value capture tiers. The vendor base organizes around synthesis method mastery, with citrate reduction commoditizing at scale while seed-mediated growth retains premium positioning. Three archetypes dominate: backward-integrated chemical suppliers, specialized bioconjugation service providers, and equipment-dependent synthesis technology licensors. Consolidation pressures intensify as hospital procurement concentration demands batch-to-batch optical consistency guarantees that smaller producers cannot underwrite.
Among North American specialists, Cytodiagnostics Inc exemplifies the colloidal gold portfolio anchor position through supply relationships with regional hospital networks. Fortis Life Sciences, LLC occupies the bioconjugation chemistry tier where in-house production of functionalized reagents reduces lot-to-lot variability for assay manufacturers. Nanopartz, Inc represents the synthesis protocol control archetype, with proprietary methods yielding narrow size distributions for surface-enhanced Raman spectroscopy applications.
| Leading Market Players |
|---|
| Cytodiagnostics Inc |
| Fortis Life Sciences, LLC |
| Meliorum Technologies, Inc |
| Nanopartz, Inc |
| NanoHybrids Inc |
| CD Bioparticles |
| Nanocs Inc |
| American Elements |
| Goldsol Inc |
| Others |
Value Chain & Pricing Dynamics
Chloroauric acid spot prices transmit volatility through three downstream pricing tiers, with GMP-certified nanomaterial batches commanding premiums that citrate-reduction commodity grades cannot approach. Boston-Cambridge corridor suppliers leverage seed-mediated synthesis mastery to defend margin pools against California diagnostic manufacturers facing procurement consolidation pressure.
Pricing Analysis
Capacity additions in Ontario and Quebec contract manufacturing facilities are reshaping price floors for GMP-compliant nanomaterial batches. Three-tier pricing structure across premium, standard, and economy levels separates FDA-IND-enabled therapeutic grades from lateral flow diagnostic specifications and research-catalog materials. Price differentiation hinges on endotoxin certification and validated sterilization protocols. Margins are tightening for citrate-reduction producers lacking backward integration into precursor chemicals. Pharmaceutical sponsors exhibit lowest price sensitivity; hospital group purchasing organizations in Texas and Florida health systems drive hardest bargain.
Supply Chain Analysis
ISO/TS 19337 certification gates fragment contract laboratory capabilities across the Americas, forcing assay manufacturers to qualify multiple suppliers against batch consistency metrics. Manufacturing concentrates in the United States, Canada, and Brazil. Synthesis draws from chloroauric acid precursors, specialized seed-mediated growth reactors, and silver underplating chemistries. Single-source vulnerability concentrates among German and Japanese equipment vendors supplying seed-mediated growth reactors. Distribution runs through direct manufacturer relationships displacing independent distributor networks as sole-source agreements consolidate procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in therapeutic-grade nanomaterial production where pharmaceutical sponsors fund premium pricing, while cost compression in diagnostic tiers forces operational discipline on lateral flow suppliers.
For Market Incumbents: Extend optical consistency guarantees to hospital group purchasing organizations to defend contract renewals against emerging bioconjugation specialists. Deepen captive supply of chloroauric acid precursors through long-term commodity hedging instruments that buffer spot gold volatility. Fortify seed-mediated synthesis equipment relationships with German and Japanese vendors to mitigate single-source vulnerability. For New Entrants and Emerging Players: Mid-tier diagnostic laboratories in São Paulo's manufacturing belt present accessible entry points where ANVISA's accelerated review pathway reduces regulatory friction. CRISPR-gold conjugate development workflows offer specification innovation openings ahead of validated assay protocols. Lead with direct technical sales relationships rather than distributor networks to capture procurement consolidation momentum. For Investors and Strategic Acquirers: Consolidation pressure builds where batch reproducibility limits exceed smaller producers' analytical chemistry capabilities. Five-to-ten year viability favors synthesis-technology licensors with proprietary seed-mediated protocols over citrate-reduction commoditizers. Watch FDA pre-submission meeting volumes as inflection indicator for therapeutic pipeline maturation.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Ontario and Quebec contract manufacturing investments capture Canada's Biomanufacturing Strategy procurement incentives. |
| Seed-Mediated Synthesis Licensing | Proprietary protocols yielding narrow size distributions command premium positioning in photothermal therapy device pipelines. |
| Bioconjugation Chemistry Backward Integration | In-house functionalized reagent production reduces lot-to-lot variability for lateral flow assay manufacturers. |
| ANVISA Registration Pathway Investment | Accelerated review for imported reference materials opens Latin American diagnostic manufacturing supply relationships. |
| ISO/TS 19337 Analytical Method Validation | Standardized particle size distribution measurement determines eligibility for federal procurement contracts. |
Study Parameters
Direct dialogue with GMP analytical chemists, diagnostic laboratory procurement managers, pharmaceutical regulatory affairs leads, and nanomaterial synthesis R&D directors grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) clearance databases, ANVISA registration filings, Health Canada guidance documents, and ISO/ASTM characterization standards. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-level outputs across product type, application, end user, and distribution channel dimensions were generated through structured modeling. CAGRs were derived from slope analysis of historical procurement volumes and projected therapeutic pipeline maturation. Forecast inputs incorporated chloroauric acid price trajectory assumptions and hospital consolidation patterns across Texas, Florida, and California health systems.
Inputs from FDA pre-submission meeting records and GPO contract award databases were available through the study window; gaps in real-time seed-mediated growth reactor capacity utilization introduce uncertainty bands around near-term supply forecasts. A model refresh is warranted upon material change in FDA nanotechnology guidance or ANVISA import reference material regulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Global Carbon Nanomaterials Market
Nanomaterials
Nanomaterial Supercapacitors Market
Nanomaterials
Silver Nanoparticles Market
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Global Nanocrystalline Cellulose Market
Nanomaterials
Global Nanoclay Reinforcement Market
Nanomaterials
Molybdenum Trioxide Nanopowder Market