
 Global Electronic Materials and Chemicals Market | 2026-2036
Global Electronic Materials and Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Materials and Chemicals Market Foresight
Asset-light leasing models for specialty gas delivery systems are reshaping capital deployment among mid-tier semiconductor chemical suppliers. Shin-Etsu Chemical anchors its position through captive polysilicon and organosilicon production that extends across wafer and packaging material lines. BASF SE leverages its Ludwigshafen integrated site to sustain cost advantages in high-purity etchant formulation. Air Liquide dominates on-site gas generation contracts at leading memory foundries, locking in decade-long revenue visibility.
Electronic materials and chemicals encompass high-purity gases, photoresists, wet chemicals, CMP slurries, and thin-film precursors formulated to parts-per-billion contamination thresholds for semiconductor and display manufacturing. Photolithography-grade photoresists require controlled molecular weight distributions and photosensitive compound loadings tuned to specific exposure wavelengths. Semiconductors and photoresists command the deepest margin pools due to qualification barriers and foundry dependency on single-source suppliers. Chemical vapor deposition precursors represent the fastest-growing technology segment as atomic layer deposition transitions from memory to logic device architectures.
REACH in Europe, China's GB standards administered by SAMR, and the EPA's TSCA framework in the United States impose divergent substance notification and purity documentation requirements that fragment supplier compliance costs. The EU F-Gas Regulation restricts fluorinated greenhouse gases used in plasma etching and chamber cleaning, forcing reformulation of process chemistries across memory and logic fabs. Stakeholders must monitor regulatory divergence between major semiconductor geographies when siting new purification and blending capacity.
Market Dynamics
Atomic layer deposition is displacing conventional CVD in logic fabs, forcing reformulation of precursor chemistries and consolidation of supplier qualification lists around organometallic synthesis capabilities.
Growth Catalysts
- 3nm Logic Ramp:Taiwan Semiconductor Manufacturing and Samsung Foundry are qualifying new metal-organic precursors for gate-all-around transistors, expanding addressable chemical spend per wafer.
- EU F-Gas Regulation:Restrictions on NF3 and SF6 are accelerating adoption of F2-based chamber cleaning chemistries with lower global warming potential.
- India Semiconductor Mission:Incentives for domestic fab construction are creating demand for localized high-purity chemical blending and packaging infrastructure.
Market Restraints
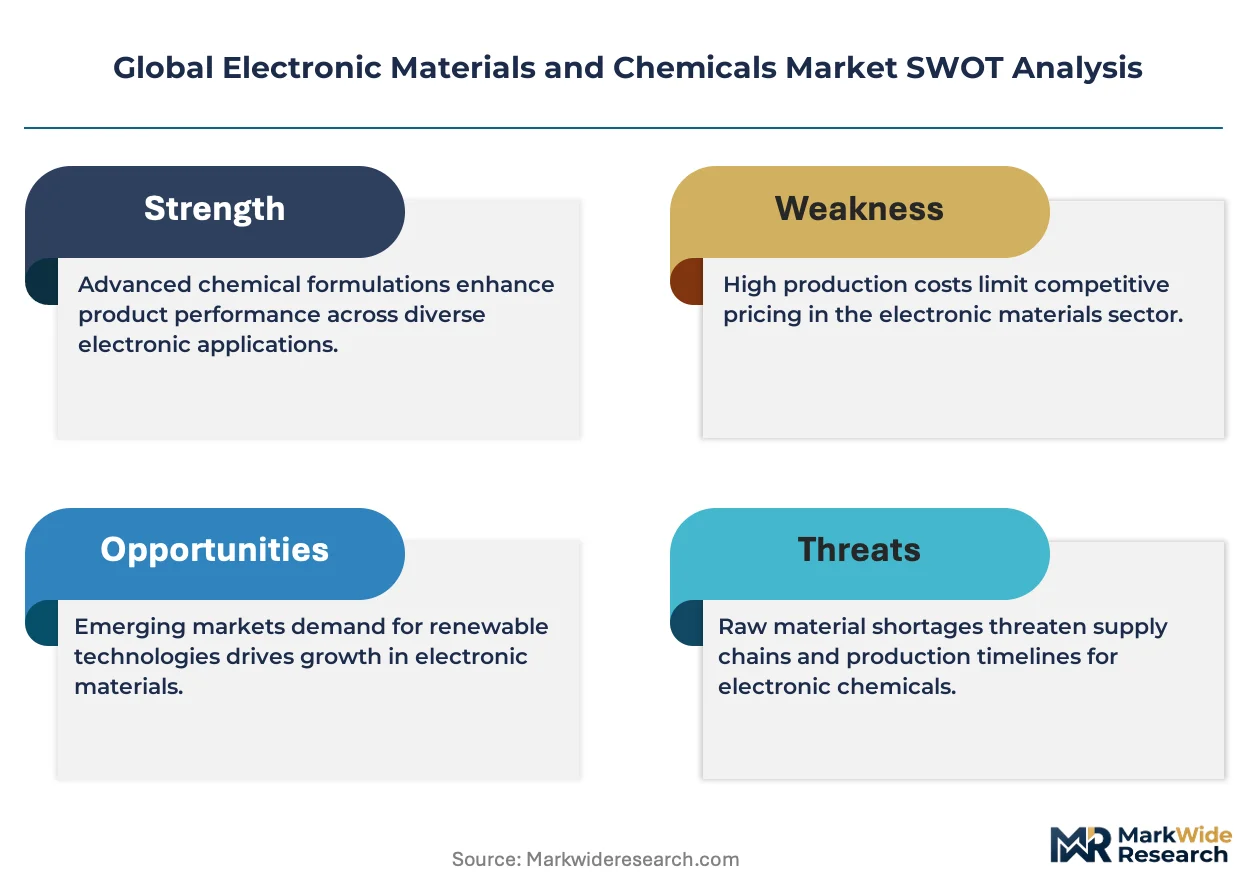
- Fluorspar Concentration:China controls roughly two-thirds of acid-grade fluorspar mining, creating input cost volatility for HF-based etchants.
- Single-Source Photoresist Risk:Japan-based suppliers dominate ArF and EUV resist formulations, leaving foundries exposed to supply interruption.
- Purification Bottleneck:Parts-per-trillion metal impurity removal requires specialized distillation and ion-exchange capacity with 18-24 month construction timelines.
Strategic Opportunities
- Vietnam Assembly Migration:Backend packaging relocation from China is driving demand for localized die-attach adhesives and underfill materials.
- On-Site Gas Generation:Air separation unit deployment at memory fabs eliminates cylinder logistics and reduces carbon intensity per wafer.
- Silicon Carbide Power Devices:Automotive inverter demand is expanding the market for high-temperature dielectric precursors and CMP slurries for SiC wafers.
Industry Challenges
- Organometallic Chemist Shortage:Synthesis of ALD precursors requires PhD-level expertise in air-sensitive compound handling that outstrips university pipeline output.
- Fab-to-Fab Qualification Variance:Each foundry maintains proprietary cleanliness protocols, forcing suppliers to duplicate analytical testing and documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Materials and Chemicals Market |
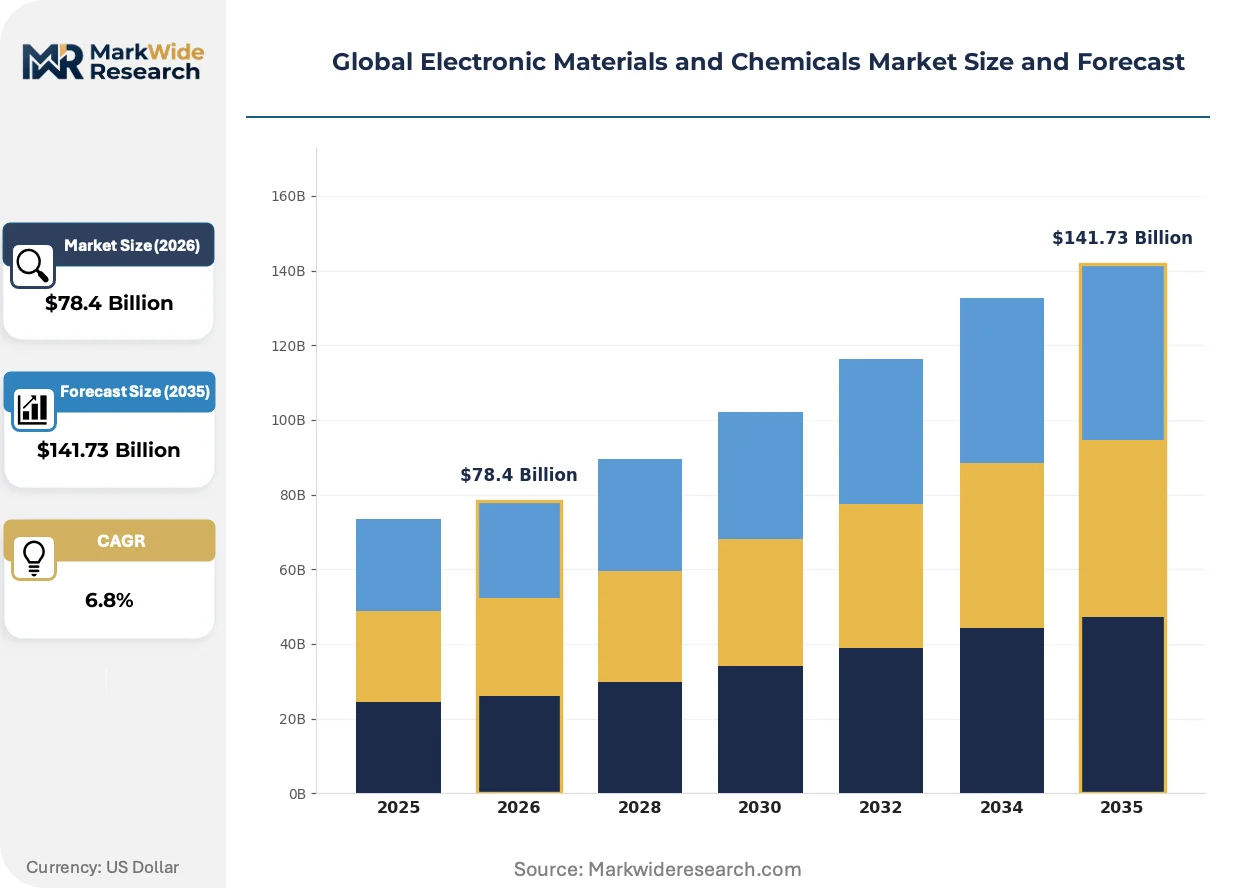
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semiconductors, Photoresists, Conductive Polymers, Dielectrics, Solder Materials, Insulating Coatings Technology: Photolithography, Chemical Vapor Deposition, Etching, Thin Film Deposition, Spin Coating, Plasma Treatment Application: Consumer Electronics, Renewable Energy Devices, Telecommunications, Aerospace Systems, Wearable Electronics, Lighting End User: OEM Manufacturers, Electronic Contract Manufacturers, Printed Circuit Board Producers, Device Integrators |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Linde plc, Fujifilm Corporation, Resonac Holding Corporation, Air Liquide, BASF SE, Merck KGaA, Air Products and Chemicals, Inc., Cabot Microelectronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Materials and Chemicals Market Shifts & Advancements
Process chemistry is fragmenting into application-specific formulations as device architectures diverge between memory and logic, between planar and vertical, between silicon and wide-bandgap.
Directed self-assembly of block copolymers is hybridizing traditional photolithography by enabling sub-7nm patterning without EUV double-patterning. Samsung and Intel are piloting DSA flows for contact hole layers. This convergence is compressing the addressable market for advanced photoresists while expanding demand for tailored polymer synthesis.
China's GB standards administered by SAMR are tightening documentation requirements for imported electronic-grade chemicals, forcing foreign suppliers to establish domestic analytical laboratories. The regulation mandates batch-level impurity certificates that exceed REACH Annex XVII thresholds. European and US suppliers are responding by partnering with Chinese blending facilities to avoid cross-border certification delays.
Memory foundries are unbundling chemical supply contracts from equipment service agreements, creating standalone procurement categories for precursors and slurries. This separation is enabling direct supplier-foundry negotiations previously mediated by tool OEMs. The shift is most pronounced in South Korea's Pyeongtaek cluster where SK Hynix and Samsung have established independent chemical sourcing teams.
Global Electronic Materials and Chemicals Market Segmentation
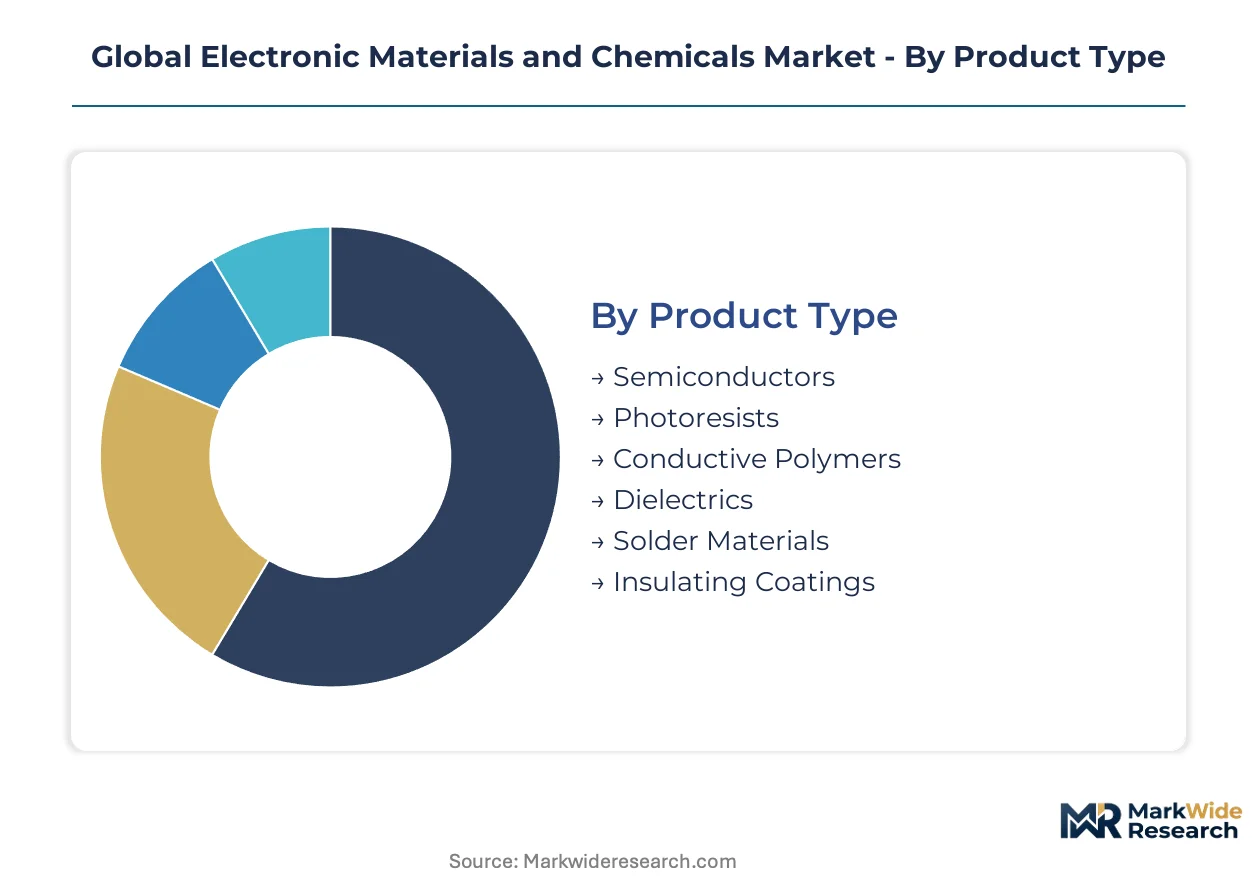
Electronic materials and chemicals fragment along multiple axes that determine qualification barriers, margin structures, and supplier relationships. Understanding these divisions reveals where capital deployment concentrates and where new entrants face the steepest technical hurdles.
Product Type:
Mature commodity chemistries coexist with emerging formulations engineered for angstrom-scale precision, creating divergent margin profiles across the product spectrum.
- Semiconductors:High-purity silicon wafers, epitaxial layers, and doped substrates form the foundational substrate for integrated circuit fabrication. Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek cluster absorb the majority of merchant supply, driven by TSMC and Samsung Foundry capacity expansions for gate-all-around transistor architectures.
- Photoresists:Photosensitive polymer formulations with controlled molecular weight distributions enable pattern transfer at specific exposure wavelengths. Japan-based suppliers dominate ArF and EUV resist production, leaving foundries exposed to single-source risk amid REACH and EPA TSCA purity documentation requirements.
- Conductive Polymers:Organic semiconducting materials for flexible display backplanes and printed electronics.
- Dielectrics:Low-k and high-k insulating films for interlayer isolation and gate stacks.
- Solder Materials:Lead-free alloys and flux systems for board-level assembly.
- Insulating Coatings:Passivation and encapsulation layers protecting active device regions.
Semiconductors retain volume leadership; photoresists hold the steepest expansion curve.
Technology:
Process technology selection determines chemical formulation complexity and supplier qualification intensity, with atomic-scale deposition methods commanding premium pricing.
- Photolithography:Optical patterning using chemically amplified resists and antireflective coatings. Taiwan and South Korea foundries drive demand for 193nm immersion and EUV-compatible chemistries as they ramp 3nm logic production.
- Chemical Vapor Deposition:Gas-phase precursor delivery for conformal film growth. Organometallic synthesis capabilities concentrate among suppliers qualified for memory and logic ALD transitions, with China's SAMR tightening batch-level impurity documentation for imported precursors.
- Etching:Wet and plasma-assisted material removal using fluorinated chemistries.
- Thin Film Deposition:Physical and chemical methods for metal and dielectric layer formation.
- Spin Coating:Rotational application of photoresists and dielectric polymers.
- Plasma Treatment:Surface activation and cleaning using ionized gas species.
Chemical Vapor Deposition commands the highest formulation premiums; photolithography maintains the broadest installed base.
Application:
End-use diversification spreads demand across device categories with varying reliability requirements and chemical consumption intensities.
- Consumer Electronics:Smartphones, tablets, and computing devices driving high-volume wafer starts. Assembly migration to Vietnam is expanding localized demand for die-attach adhesives and underfill materials as backend packaging relocates from China.
- Renewable Energy Devices:Solar cells and power conversion systems requiring specialized metallization pastes and encapsulants. India's Semiconductor Mission incentives are creating demand for domestic high-purity chemical blending infrastructure to support local fab construction.
- Telecommunications:Base station and optical networking equipment with extended reliability specifications.
- Aerospace Systems:Radiation-hardened and high-reliability components with extended qualification cycles.
- Wearable Electronics:Flexible substrates and miniaturized packaging with biocompatibility constraints.
- Lighting:LED epitaxy and phosphor conversion materials.
Consumer Electronics retains volume leadership; Renewable Energy Devices holds the steepest expansion curve.
End User:
Customer type determines procurement sophistication, contract structure, and technical service requirements across the value chain.
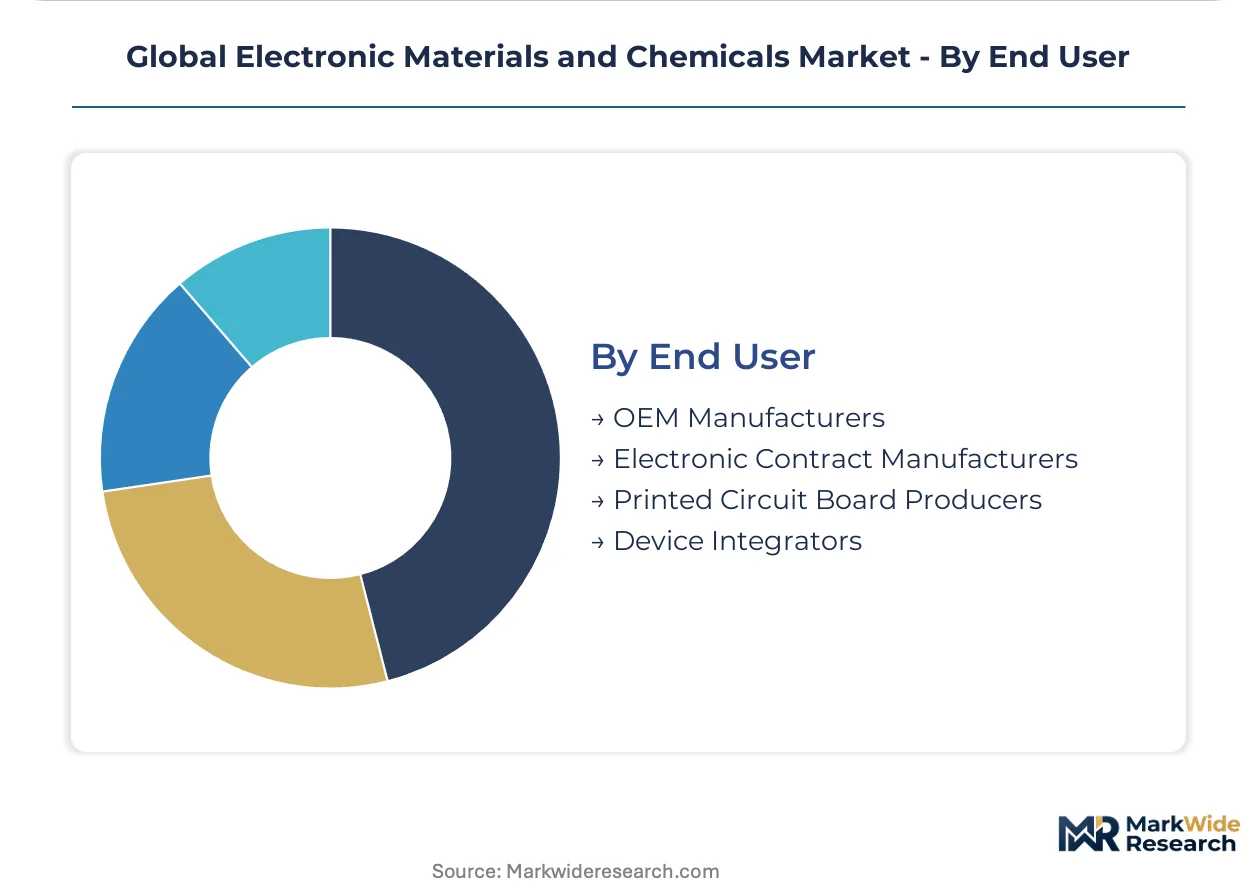
- OEM Manufacturers:Integrated device manufacturers and brand owners with captive fabrication. Memory foundries in South Korea's Pyeongtaek cluster are unbundling chemical supply from equipment service agreements, enabling direct supplier negotiations previously mediated by tool OEMs.
- Electronic Contract Manufacturers:Assembly and test providers with high-volume, price-sensitive procurement.
- Printed Circuit Board Producers:Laminate fabricators and board shops consuming etchants and plating chemistries.
- Device Integrators:System-level assemblers sourcing packaged components.
OEM Manufacturers retain volume leadership; Electronic Contract Manufacturers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands superior pricing leverage for HF-based etchants through fluorspar dominance, while Germany's Saxony corridor extracts premiums from REACH-compliant high-purity formulations. This asymmetry shapes supplier investment priorities across fabrication geographies.
China
Domestic foundry construction under the dual carbon goals is accelerating demand for localized precursor blending capacity. SAMR's GB standards mandate batch-level impurity certificates that exceed import thresholds. Yangtze River Delta clusters in Shanghai and Wuxi house the majority of new high-purity chemical purification facilities.
United States
CHIPS Act subsidies are reshoring advanced logic fabrication, expanding addressable chemical spend per wafer. EPA's TSCA framework imposes substance notification requirements that fragment compliance documentation. Arizona's Phoenix metro and Texas's Austin-San Antonio corridor concentrate new fab announcements from TSMC and Samsung.
South Korea
Memory and logic foundries are unbundling chemical procurement from equipment service agreements. The national emissions trading scheme tightens carbon intensity thresholds for supplier qualification. Pyeongtaek's semiconductor cluster hosts independent chemical sourcing teams at SK Hynix and Samsung.
Germany
EU F-Gas Regulation restrictions on NF3 and SF6 are forcing reformulation of chamber cleaning chemistries. REACH compliance documentation requirements sustain cost premiums for high-purity etchants. Saxony's Dresden-Leipzig corridor anchors European silicon carbide device manufacturing and dielectric precursor demand.
Taiwan
3nm logic ramp at TSMC is qualifying new metal-organic precursors for gate-all-around transistors. The island's environmental regulations tighten wastewater discharge standards for chemical suppliers. Hsinchu Science Park absorbs the majority of merchant photoresist supply for leading-edge node production.
Global Electronic Materials and Chemicals Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in precursor synthesis and high-purity formulation. The market structure concentrates around integrated chemical conglomerates with captive raw material positions and specialized gas suppliers with on-site generation capabilities. Three archetypes dominate: diversified materials platforms with backward integration into polysilicon and organosilicon, industrial gas specialists with fab-embedded service contracts, and photoresist formulators with lithography-wavelength-specific expertise. Competitive moves center on decade-long on-site gas generation contracts and regional purification capacity expansion to satisfy divergent REACH, TSCA, and GB compliance requirements.
Among Japanese chemical conglomerates, Shin-Etsu Chemical Co., Ltd. exemplifies the diversified materials platform archetype through its captive polysilicon and organosilicon production. German industrial giant BASF SE occupies a position within the high-purity formulation tier, leveraging its Ludwigshafen integrated site for etchant cost advantages. French industrial gas specialist Air Liquide represents the on-site generation model, anchoring long-term revenue visibility through memory foundry contracts. These three sit within distinct competitive vectors that resist direct substitution.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Linde plc |
| Fujifilm Corporation |
| Resonac Holding Corporation |
| Air Liquide |
| BASF SE |
| Merck KGaA |
| Air Products and Chemicals, Inc. |
| Cabot Microelectronics Corporation |
| Others |
Supply & Pricing Matrix
Yangtze River Delta clusters in Shanghai and Wuxi anchor global high-purity chemical purification capacity, with their expansion timelines directly constraining downstream foundry procurement leverage. SAMR's GB standards mandate batch-level impurity certificates that exceed import thresholds, forcing foreign suppliers to absorb domestic analytical laboratory costs or cede pricing power to local blenders.
Pricing Analysis
Configured-to-order pricing for metal-organic precursors and photoresists commands spreads exceeding standard-grade wet chemicals due to foundry-specific qualification requirements. Three-tier pricing structure across premium, standard, and economy levels separates EUV-grade photoresists from ArF immersion resists and g-line/i-line commodity formulations. Cost compression in standard-grade HF-based etchants intensifies because China's fluorspar dominance enables domestic suppliers to undercut import parity. Memory foundries exhibit highest price sensitivity due to unbundled procurement contracts, while logic fabs at 3nm nodes accept premium pricing for single-source metal-organic precursors.
Supply Chain Analysis
Export-control regimes restricting organometallic synthesis equipment and precursor formulations limit technology transfer to emerging fabrication geographies. Supply concentrates in Japan for ArF and EUV photoresists, Germany for REACH-compliant high-purity etchants, and South Korea for memory-focused ALD precursors. Critical inputs include acid-grade fluorspar for HF production, high-purity silicon feedstock for polysilicon, and rare earth elements for CMP slurry abrasives. Single-source vulnerability pervades photoresist formulations where JSR, Shin-Etsu, and Tokyo Ohka Kogyo control qualified supply. Distribution runs through fab-embedded on-site gas generation contracts for industrial gases and direct supplier-foundry negotiations for formulated chemicals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where decade-long on-site gas generation contracts and foundry-specific qualification protocols create switching costs that entrench incumbent positions.
For Market Incumbents: Build regulatory entrenchment by establishing domestic analytical laboratories in China to preempt SAMR certification delays, while expanding captive organometallic synthesis capacity to defend against emerging Korean precursor suppliers. The threat of foundries unbundling chemical procurement from equipment service agreements demands accelerated direct technical service investment in South Korea's Pyeongtaek cluster.
For New Entrants and Emerging Players: India's Semiconductor Mission incentives for domestic fab construction represent underpenetrated demand for localized high-purity chemical blending infrastructure, bypassing entrenched supplier qualification lists in Taiwan and South Korea. Target Vietnam's backend packaging migration with die-attach adhesives and underfill materials, leveraging lower regulatory barriers than front-end chemical qualification.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because organometallic synthesis capabilities and foundry qualification relationships concentrate among a narrowing supplier base. Acquisition targets include mid-tier gas suppliers with on-site generation deployment expertise and regional blenders with SAMR-compliant analytical infrastructure. The signal to watch is foundry announcements of second-source qualification programs for EUV photoresists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organometallic Synthesis | Captive precursor production locks in margin pools as ALD displaces conventional CVD at TSMC and Samsung. |
| Domestic Analytical Laboratory Establishment | SAMR-compliant batch certification facilities in China eliminate cross-border documentation delays for European suppliers. |
| On-Site Gas Generation Deployment | Air separation units at SK Hynix and Samsung fabs secure decade-long revenue visibility and eliminate cylinder logistics. |
| Second-Source Photoresist Qualification | Foundry diversification programs reduce single-source risk from JSR and Shin-Etsu amid geopolitical supply concerns. |
| Silicon Carbide Precursor Development | Automotive inverter demand expands addressable market for high-temperature dielectric precursors beyond silicon logic. |
Research Methodology
Desk research of customs and trade flow databases, SEC 10-K filings, and ECHA REACH registration dossiers preceded structured interviews with semiconductor fab procurement directors, specialty chemical plant managers, and organometallic synthesis R&D leads. Primary fieldwork across Taiwan's Hsinchu Science Park, South Korea's Pyeongtaek cluster, and Germany's Saxony corridor validated capacity expansion timelines and qualification protocol divergence. Secondary sources included foundry capex disclosures, SAMR GB standard drafts, and industrial gas contract announcement tracking. Bottom-up wafer-start modeling and top-down chemical spend-per-wafer estimates were triangulated against supplier revenue disclosures.
Analytical assumptions held 3nm logic ramp schedules and memory capital expenditure cycles within announced foundry guidance ranges across the analysis window. Segmentation modeling incorporated product type, technology node, application end-use, and regional regulatory cluster dimensions. CAGRs were derived from wafer-start forecasts and chemical intensity coefficients by device architecture, with atomic layer deposition precursor growth rates benchmarked against equipment OEM shipment disclosures and foundry technology transition timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed chemical suppliers or accelerated second-source qualification programs at TSMC and Samsung would shift outcomes. Material shifts in EU F-Gas Regulation enforcement timelines, China's fluorspar export restrictions, or breakthroughs in directed self-assembly patterning would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Chemicals
Global Imaging Chemicals Market
Electronic Chemicals
Global Circuit Materials Market
Electronic Chemicals
Global 5G EMI Materials Market
Electronic Chemicals
Electronic Wet Chemicals Market
Electronic Chemicals
Silver Paste Market
Electronic Chemicals
Printed Electronic Materials Market
Electronic Chemicals
Liquid Soldering Flux Market
Electronic Chemicals
Electronic Chemicals Market