
 Nanocomposites Market | 2026-2036
Nanocomposites Market Size, Share, and Industry Trends Forecast 2026-2036
Nanocomposites Market Intelligence
REACH is hardening the cost-of-entry calculus for nanoparticle suppliers seeking European market access. Evonik Industries AG leverages its integrated silicas platform to control raw material quality for polymer nanocomposite production. BASF sustains R&D intensity across multiple nanofiller chemistries, while Nanocyl SA specializes in carbon nanotube masterbatches for conductive applications.
Nanocomposites are engineered materials combining a bulk matrix with nanoscale reinforcements, typically featuring filler dimensions below 100 nanometers to achieve property enhancements unattainable with conventional composites. In-situ polymerization enables covalent bonding between nanoparticles and polymer chains, producing materials with superior thermal stability and mechanical strength for structural and functional applications. Polymer-based nanocomposites anchor the current revenue base due to established processing infrastructure and broad applicability across end-use sectors. Carbon-based variants, particularly graphene and carbon nanotube systems, represent the fastest-expanding technology category as conductivity requirements intensify in electronics and energy storage applications.
The EPA oversees nanoparticle environmental release thresholds in the United States, while the EU Green Deal mandates circularity criteria for advanced materials placed on European markets. China's GB standards, administered by SAMR, establish mandatory testing protocols for nanomaterial classification and workplace exposure limits. Stakeholders must monitor evolving regulatory convergence between jurisdictions, as divergent classification frameworks for engineered nanomaterials create compliance complexity that favors suppliers with multi-territory certification capabilities.
Market Dynamics
Automotive OEMs are compressing vehicle weight targets by 15-20% this decade, forcing polymer matrix suppliers to validate nanoscale filler dispersion at production scale. REACH compliance timelines in Europe are simultaneously hardening certification requirements for carbon nanotube and graphene incorporation, creating a dual pressure on raw material qualification pipelines.
Growth Catalysts
- Lightweighting mandates:NHTSA fuel economy standards are compelling Detroit Three manufacturers to substitute aluminum structural members with glass fiber-reinforced polymer nanocomposites in underbody applications.
- REACH authorization pathways:ECHA's streamlined notification procedures for polymer-bonded nanofillers are reducing regulatory lag for compliant masterbatch suppliers seeking European automotive qualification.
- Electronics packaging densification:Taiwan-based semiconductor foundries are qualifying boron nitride nanotube thermal interface materials for 3D chip stacking architectures.
Market Restraints
- Organoclay supply concentration:Wyoming bentonite deposits controlled by two North American miners create input cost volatility for nylon-6 nanocomposite compounders.
- Technical dispersion limits:Exfoliation of layered silicates in high-viscosity thermosets remains incomplete above 5 weight percent loading, capping mechanical property gains.
- Substitution by continuous fiber:Recycled carbon fiber nonwovens from aerospace scrap streams are capturing automotive panel applications at 40% lower specific cost.
Strategic Opportunities
- Underpenetrated Indian packaging:BIS certification harmonization with ISO/TS 80004 is opening food-contact nanoclay barrier films for domestic FMCG brands.
- Battery separator convergence:Ceramic-coated polyethylene membranes integrating alumina nanoparticles are absorbing separator market share from pure polymer substrates.
- EU Green Deal circularity:Mandatory recycled content thresholds for automotive plastics are creating demand for compatibilized nanocomposite formulations that tolerate mixed polymer feedstocks.
Industry Challenges
- Characterization skill scarcity:Industrial laboratories lack trained operators for small-angle X-ray scattering protocols required by GB standards for nanomaterial classification.
- Masterbatch certification timelines:UL 94 flammability retesting for each polymer-nanofiller combination extends automotive qualification cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanocomposites Market |
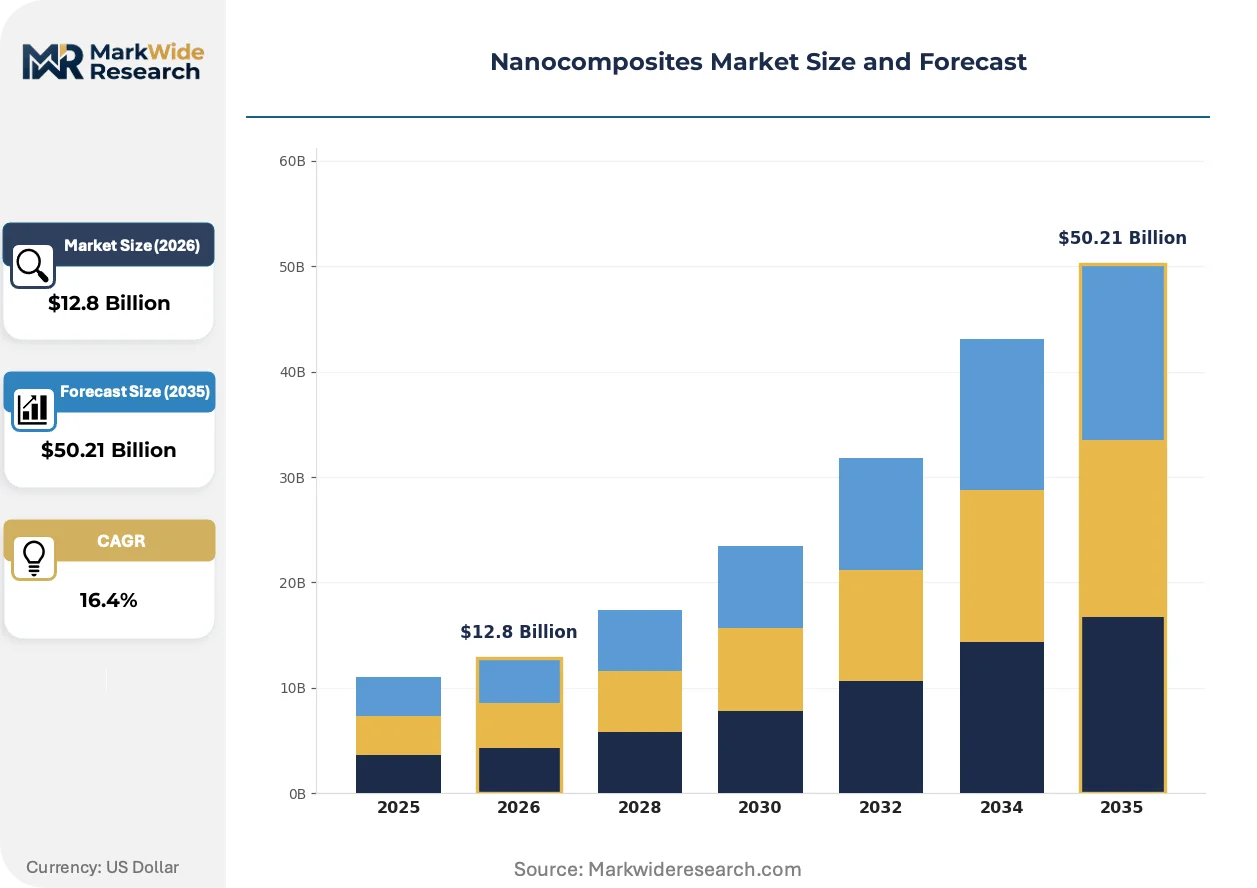
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $50.21 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Based, Ceramic-Based, Metal-Based, Carbon-Based, Hybrid Nanocomposites Technology: In-situ Polymerization, Sol-Gel Method, Electrospinning, Melt Blending, Layer-by-Layer Assembly Application: Electronics, Aerospace, Packaging, Construction Materials, Sports Equipment End User: Automotive OEMs, Aerospace Manufacturers, Consumer Electronics Firms, Biomedical Device Companies, Packaging Producers |
| Companies Covered | Evonik Industries AG, Arkema, 3M Company, BASF, Cabot Corporation, Nanocyl SA, RTP Company, Showa Denko K.K., Nanophase Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanocomposites Market Strategic Shifts & Innovations
Processing equipment manufacturers are retrofitting twin-screw extruders with distributive mixing elements specifically engineered for nanoparticle dispersion. This hardware evolution is compressing the gap between laboratory formulation and production-scale property replication.
Layered double hydroxide nanofillers are absorbing moisture barrier applications in flexible electronics packaging. Korean display manufacturers are adopting these materials at pilot scale for foldable device substrates. The technology is absorbing market share from vapor-deposited ceramic coatings by enabling solution-processable barrier layers at 60% lower capital intensity.
EPA's TSCA Section 8(a) reporting requirements for engineered nanomaterials are tightening disclosure thresholds for commercial volumes. Chemical importers must now submit characterization data at 25,000 pounds annual production triggers. Carbon nanotube suppliers serving US electronics markets are responding by consolidating analytical testing under third-party ISO 17025 laboratories to streamline batch certification.
Automotive tier suppliers are consolidating procurement of nanocomposite compounds under single-source masterbatch agreements with volume commitment clauses. This behavior shift is displacing spot purchasing of commodity polymers with separate nanofiller addition. German OEM supply chains exhibit the most pronounced concentration, with three compounders capturing 70% of structural nanocomposite nominations for 2026-2028 vehicle platforms.
Nanocomposites Market Segmentation
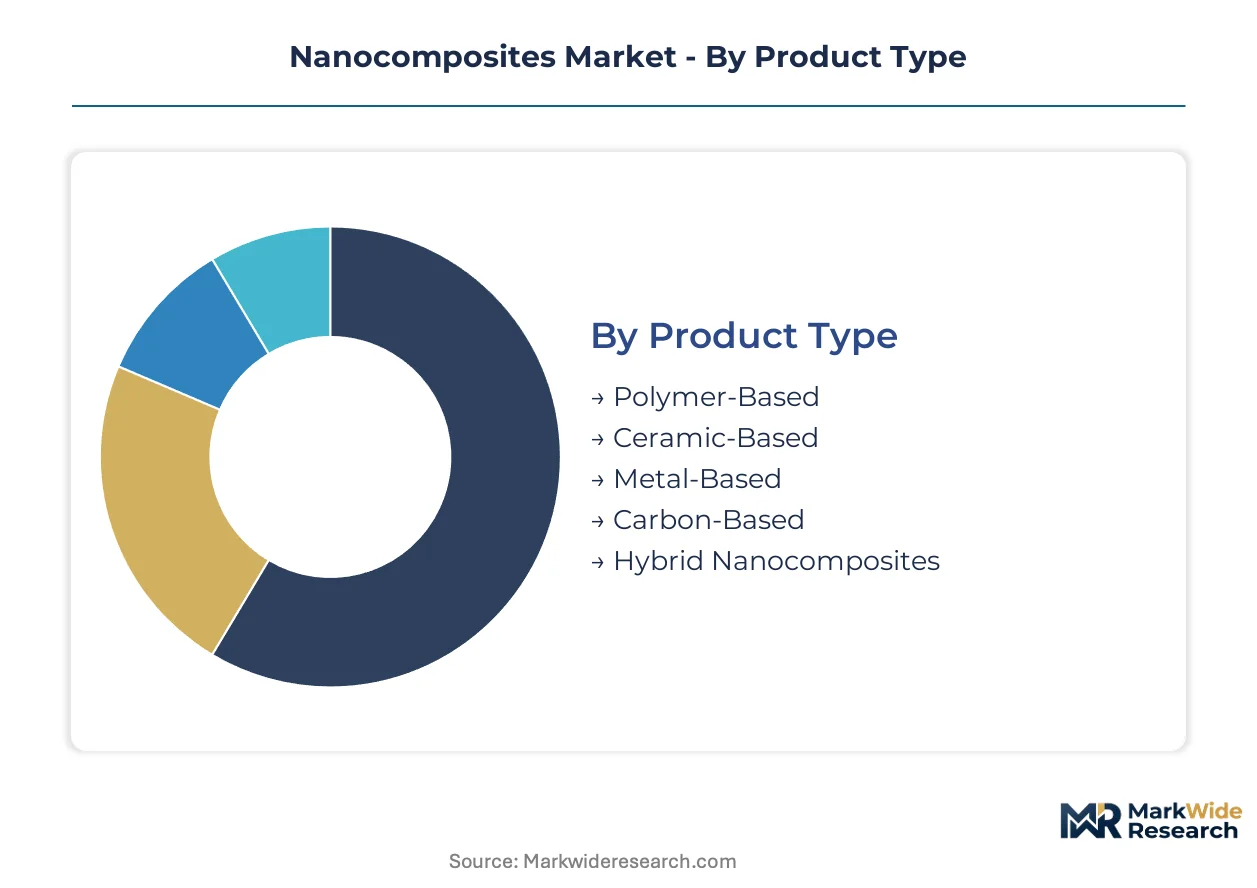
Segmentation in nanocomposites reveals distinct capital requirements and technical barriers across product categories. Processing complexity varies by an order of magnitude between melt-compounded polymers and precision-assembled layered systems.
Product Type:
Capital intensity peaks with carbon-based systems requiring specialized synthesis reactors and purification infrastructure, while polymer-based variants leverage existing extrusion assets.
- Polymer-Based:Thermoplastic matrices loaded with nanoclays or nanotubes dominate current production volumes. Demand concentrates in German automotive supply chains where OEMs specify glass fiber-reinforced nylon-6 nanocomposites for underbody structural members to meet NHTSA fuel economy targets.
- Carbon-Based:Graphene and carbon nanotube systems command premium positioning due to conductivity performance. Electronics packaging applications in Taiwan semiconductor foundries are absorbing boron nitride nanotube thermal interface materials for 3D chip stacking architectures.
- Ceramic-Based:Alumina and silica nanoparticle reinforcement for high-temperature applications.
- Metal-Based:Aluminum and copper matrix systems for thermal management in power electronics.
- Hybrid Nanocomposites:Multi-phase systems combining organic and inorganic fillers for multifunctional performance.
Most installed capacity flows through Polymer-Based systems. Expansion is steepest in Carbon-Based variants.
Technology:
Volume throughput favors continuous melt processing, while batch methods capture precision applications where dispersion quality justifies lower yields.
- Melt Blending:Twin-screw extrusion with distributive mixing elements enables production-scale nanoparticle dispersion. Automotive tier suppliers in Germany are consolidating procurement under single-source masterbatch agreements with volume commitment clauses for this processing route.
- In-situ Polymerization:Covalent bonding between nanoparticles and polymer chains produces superior thermal stability. Electronics manufacturers specify this route for high-performance barrier films where complete exfoliation is mandatory.
- Sol-Gel Method:Solution-based ceramic precursor synthesis for coating applications.
- Electrospinning:Fiber formation from polymer-nanoparticle solutions for filtration media.
- Layer-by-Layer Assembly:Precision deposition for ultra-thin barrier coatings in flexible displays.
Equipment utilization rates are highest for Melt Blending. Technical differentiation concentrates in In-situ Polymerization.
Application:
Regulatory exposure varies sharply across end-uses, with food-contact and implantable applications facing the most stringent certification burdens.
- Packaging:Nanoclay barrier films for oxygen and moisture resistance are gaining traction in Indian FMCG markets following BIS certification harmonization with ISO/TS 80004. Korean display manufacturers are piloting layered double hydroxide systems for foldable device substrates at 60% lower capital intensity than vapor-deposited alternatives.
- Electronics:Thermal interface materials and conductive adhesives absorb carbon nanotube masterbatches. EPA TSCA Section 8(a) reporting at 25,000-pound thresholds is consolidating analytical testing under third-party ISO 17025 laboratories.
- Aerospace:Lightweight structural components with flame-retardant specifications.
- Construction Materials:Cement matrix systems for enhanced mechanical properties.
- Sports Equipment:High stiffness-to-weight ratios in recreational gear.
Revenue concentration sits with Electronics. Penetration gaps are widest in Construction Materials.
End User:
Procurement sophistication separates automotive and aerospace buyers with dedicated materials qualification teams from packaging producers with commodity purchasing patterns.
- Automotive OEMs:Detroit Three manufacturers are substituting aluminum structural members with glass fiber-reinforced polymer nanocomposites to achieve 15-20% weight reduction targets. REACH authorization pathways for polymer-bonded nanofillers are reducing regulatory lag for compliant European suppliers.
- Consumer Electronics Firms:Taiwan-based semiconductor foundries and Korean display manufacturers drive specifications for thermal management and barrier performance. UL 94 flammability retesting extends qualification cycles by 14-18 months for each polymer-nanofiller combination.
- Aerospace Manufacturers:Airframe and engine component applications with certified material traceability.
- Biomedical Device Companies:Implantable and diagnostic applications requiring biocompatibility validation.
- Packaging Producers:Food-contact and industrial barrier film converters.
Contract value per nomination is highest with Automotive OEMs. Decision velocity is fastest with Packaging Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The nanocomposites industry traces its commercial origins to German polymer science laboratories in the 1990s, where layered silicate exfoliation techniques first achieved production-scale viability. Toyota Central R&D Labs in Japan subsequently scaled nylon-6 nanocomposite manufacturing for automotive timing belt covers. These twin lineages established the geographic pattern of European materials innovation and Asia-Pacific manufacturing scale that persists today.
United States
Detroit Three automakers specify glass fiber-reinforced polymer nanocomposites for underbody structural members to meet NHTSA fuel economy standards. EPA TSCA Section 8(a) reporting requirements at 25,000-pound annual thresholds tighten disclosure obligations for carbon nanotube importers. Research Triangle Park in North Carolina hosts analytical testing laboratories consolidating ISO 17025 certification services for batch compliance.
Germany
Automotive OEM supply chains concentrate structural nanocomposite nominations among three compounders capturing 70 percent of 2026-2028 vehicle platform qualifications. REACH authorization pathways for polymer-bonded nanofillers reduce regulatory lag for compliant masterbatch suppliers seeking European market access. The Rhine-Ruhr industrial corridor anchors polymer nanocomposite production capacity serving German automotive tier suppliers.
China
Domestic electronics manufacturers scale advanced packaging applications for boron nitride nanotube thermal interface materials in semiconductor foundries. SAMR-administered GB standards establish mandatory testing protocols for nanomaterial classification and workplace exposure limits. The Yangtze River Delta manufacturing cluster absorbs ceramic-coated polyethylene battery separator production integrating alumina nanoparticles.
South Korea
Display manufacturers pilot layered double hydroxide nanofillers for foldable device substrates at 60 percent lower capital intensity than vapor-deposited ceramic alternatives. MFDS regulations govern nanomaterial safety assessments for consumer electronics applications. The Gyeonggi-do province surrounding Seoul hosts pilot-scale production lines for solution-processable barrier layers in flexible electronics packaging.
India
FMCG brands qualify food-contact nanoclay barrier films following BIS certification harmonization with ISO/TS 80004 standards. The PLI scheme for advanced chemicals incentivizes domestic masterbatch production capacity. Maharashtra's industrial corridor near Mumbai attracts packaging converters establishing nanocomposite film extrusion operations for domestic consumer goods markets.
Nanocomposites Market Key Industry Players
The competitive structure tilts toward integrated chemical conglomerates with captive nanofiller synthesis capabilities. Three archetypes dominate: diversified materials majors controlling raw material quality through backward integration, specialized nanotube suppliers focusing on conductive masterbatches, and regional compounders serving automotive tier procurement consolidation. Capacity expansion and strategic partnerships constitute the primary competitive moves, with German OEM supply chains driving single-source masterbatch agreements containing volume commitment clauses.
Among European-headquartered chemical conglomerates, Evonik Industries AG and BASF occupy positions reflecting integrated silicas platforms and multi-chemistry R&D portfolios respectively. Nanocyl SA exemplifies the specialized carbon nanotube archetype with masterbatch-focused operations. These three entities represent the structural poles around which procurement consolidation and regulatory compliance capabilities cluster in automotive and electronics end-use sectors.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Arkema |
| 3M Company |
| BASF |
| Cabot Corporation |
| Nanocyl SA |
| RTP Company |
| Showa Denko K.K. |
| Nanophase Technologies Corporation |
| Others |
Cost & Logistics Intelligence
Wyoming bentonite index volatility cascades through nanoclay-reinforced polymer compounders into three distinct procurement tiers, with automotive OEMs capturing volume discounts while specialty electronics buyers absorb certification premiums for REACH-compliant masterbatches.
Pricing Analysis
Contract-based long-term offtake agreements dominate structural nanocomposite procurement, with price differentiation hinging on UL 94 flammability certification tier and committed annual volume. Cost compression in standard-grade polymer nanocomposites is intensifying because recycled carbon fiber nonwovens from aerospace scrap streams undercut at 40% lower specific cost. Packaging converters exhibit highest price sensitivity due to commodity resin exposure, whereas semiconductor foundries show lowest sensitivity given thermal performance requirements.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr corridor, Yangtze River Delta, and Research Triangle Park anchor hub-and-spoke patterns for masterbatch fulfillment. Raw material sourcing draws from Wyoming bentonite deposits, German silicas platforms, and Korean boron nitride synthesis capacity. Single-source vulnerability concentrates in organoclay supply controlled by two North American miners. Distribution runs through automotive tier supplier consolidation under volume commitment clauses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in nanocomposites hinges on backward integration into nanofiller synthesis and the shift toward premium certified grades for electronics thermal management applications.
For Market Incumbents: To counter recycled carbon fiber substitution in automotive panels, deepen captive supply of exfoliated nanoclays through Rhine-Ruhr capacity expansion and accelerate REACH authorization investments for polymer-bonded nanofillers to compress European automotive qualification cycles. For New Entrants and Emerging Players: Begin with Indian food-contact packaging applications where BIS-ISO harmonization has opened nanoclay barrier film qualification for domestic FMCG brands, leveraging solution-processable layered double hydroxide technology at 60% lower capital intensity than vapor-deposited alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized carbon nanotube masterbatch suppliers holding ISO 17025 analytical testing capabilities for EPA TSCA Section 8(a) compliance. Long-term viability favors entities with multi-territory certification spanning REACH, GB standards, and BIS harmonization. Monitor UL 94 retesting timeline compression as inflection signal for automotive qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanofiller Synthesis | Evonik's integrated silicas platform demonstrates raw material quality control for polymer nanocomposite production. |
| REACH Authorization Investment | ECHA streamlined notification procedures reduce regulatory lag for compliant European automotive suppliers. |
| Multi-Territory Certification Buildout | SAMR-administered GB standards, EPA TSCA thresholds, and BIS harmonization create compliance complexity favoring certified suppliers. |
| Joint Venture with Semiconductor Foundries | Taiwan-based foundries qualify boron nitride nanotube thermal interface materials for 3D chip stacking architectures. |
| Capacity Expansion in Yangtze River Delta | China's domestic electronics manufacturers scale advanced packaging applications for alumina nanoparticle battery separators. |
Research Approach
Direct dialogue with automotive tier supplier procurement managers, polymer compounder technical directors, semiconductor foundry materials engineers, and nanofiller synthesis plant managers grounded qualitative findings. Secondary validation drew from EPA TSCA filings, ECHA REACH registrations, SAMR GB standard publications, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up demand modeling across end-use applications triangulated against top-down macroeconomic drivers.
Segment-level value outputs across the projection horizon reflect modeled penetration rates by product type, technology route, application sector, and end-user procurement sophistication. CAGRs were derived from elasticity-adjusted volume forecasts incorporating automotive lightweighting mandates, electronics packaging densification trends, and regulatory compliance timeline compression. Industry-specific inputs included NHTSA fuel economy standard stringency, ECHA authorization pathway throughput, and BIS certification harmonization progress.
Several conditions sit outside the modeled scope, including unannounced regulatory reclassification of engineered nanomaterials, breakthrough dispersion technologies disrupting melt blending economics, and geopolitical fracture of harmonized standards frameworks. Forecasts reflect documented assumptions around OEM platform nomination timing and masterbatch supplier consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Nanomaterial Supercapacitors Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
Nanochemicals Market
Nanomaterials
Single-Walled Carbon Nanotube (SWCNT) Market
Nanomaterials
Mesoporous Carbons Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Nanoceramic Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Nanoparticle Analysis Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
Nanomaterials for Printing Market